
 Glass Ionomer Cement Market | 2026-2036
Glass Ionomer Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Ionomer Cement Market Analysis
Dental distributor networks across Europe and North America is reconfiguring around consolidated procurement platforms that favor manufacturers with direct-to-clinic logistics capabilities. GC Corporation leverages its integrated supply chain to sustain shelf presence in Japanese and Southeast Asian dental clinics. Dentsply Sirona competes through digital workflow bundling that anchors glass ionomer products within broader restorative systems. Ivoclar Vivadent differentiates via specialized aesthetic formulations that occupy premium positioning in Swiss and German markets.
Glass ionomer cement consists of a basic glass powder—typically fluoroaluminosilicate—reacted with an aqueous polyacrylic acid to form a polysalt matrix that releases fluoride ions and chemically bonds to tooth structure, primarily serving permanent restorative and luting applications in dentistry. Resin-modified variants command the dominant share due to their dual-cure capability and superior fracture resistance in load-bearing restorations. Conventional formulations retain stable demand in pediatric dentistry and public health programs where moisture tolerance and fluoride release outweigh mechanical limitations. High-strength glass ionomers are gaining fastest in core build-up procedures as practitioners seek single-visit alternatives to composite resins.
The FDA regulates glass ionomer cements as Class II medical devices under 510(k) premarket notification pathways, while the EU MDR imposes stricter clinical evidence requirements for permanent implant materials including dental luting agents. Japan's PMDA maintains distinct biocompatibility testing protocols that create additional compliance layers for imported formulations. Stakeholders must monitor evolving harmonization between ISO 9917 standards and national pharmacopeial methods, as divergence in setting-time and solubility testing directly shapes market access timelines and reformulation costs.
Market Dynamics
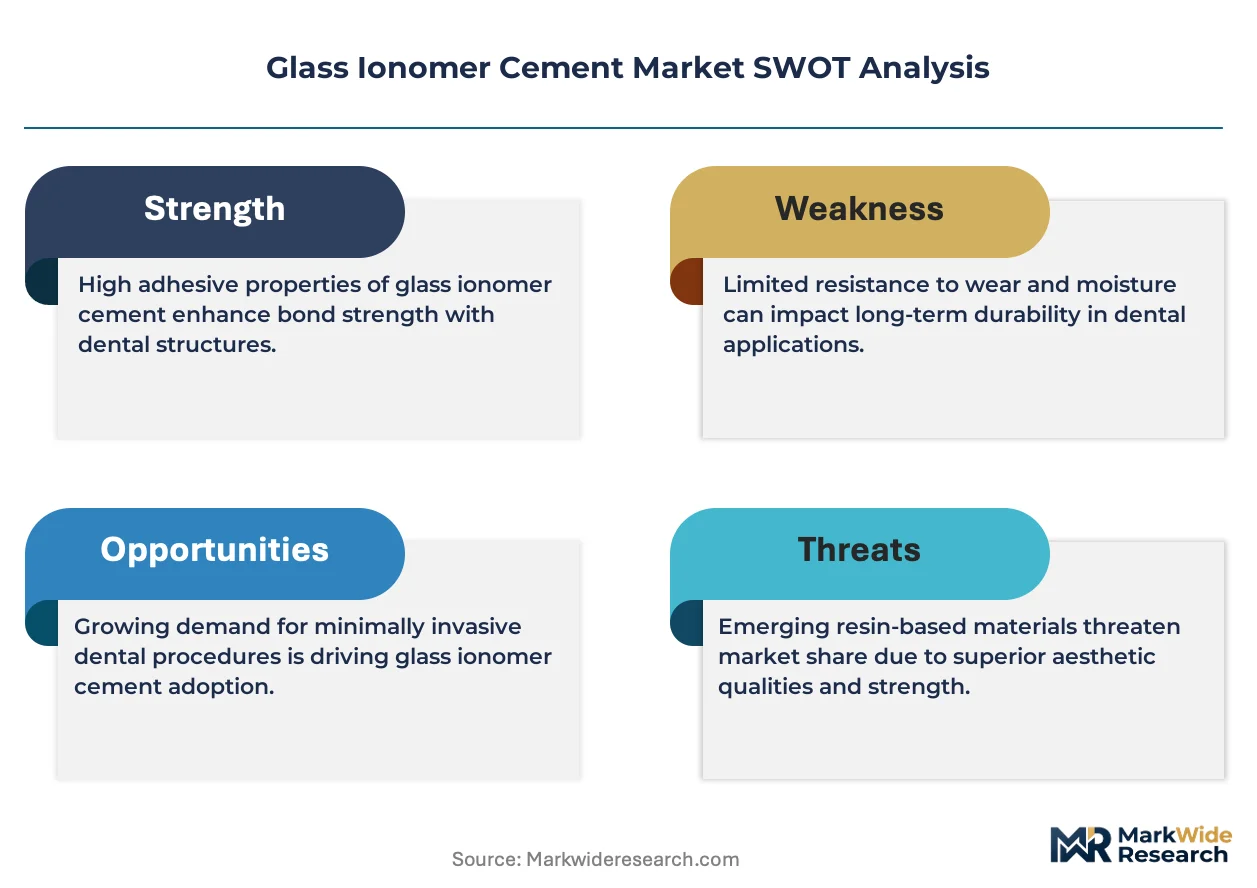
The glass ionomer cement market is being fundamentally restructured by the EU Medical Device Regulation's escalating clinical evidence requirements, which force manufacturers to rebuild biocompatibility documentation pipelines for permanent luting agents and drive consolidation among smaller formulation houses.
Growth Catalysts
- Fluoride-release protocols:Pediatric dentistry programs across India, Thailand, and Vietnam prioritize moisture-tolerant materials that chemically bond to deciduous tooth structure without etching protocols.
- ISO 9917 harmonization:Convergence of setting-time and solubility testing standards between Japan's PMDA and European notified bodies accelerates multi-market registration timelines for reformulated products.
- Single-visit dentistry:Core build-up applications in general practice settings favor high-strength glass ionomers over composite resins for immediate load-bearing restorations.
Market Restraints
- Aluminosilicate glass supply concentration:Specialty glass precursor manufacturing clusters in Germany and Japan create input vulnerability for formulators lacking backward integration into raw material production.
- EU MDR clinical evidence thresholds:Permanent implant material classifications now require prospective clinical data that smaller manufacturers cannot generate without consortium partnerships.
- Resin composite substitution:Nanohybrid and bulk-fill composites capture aesthetic anterior restorations where color stability and polishability outweigh fluoride release benefits.
Strategic Opportunities
- Tier-2 Indian municipal procurement:Government dental health schemes in Nagpur, Jaipur, and Kochi expand subsidized restorative access, creating volume anchors for economy-formulation suppliers.
- Digital workflow bundling:Chairside CAD/CAM systems create attachment points for proprietary glass ionomer blocks and cements within integrated restorative ecosystems.
- Bioactive glass convergence:Hybrid formulations combining fluoroaluminosilicate with antibacterial silver-doped glasses address caries-active patient segments in public health programs.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity and sensitization studies face bottlenecks at accredited laboratories, extending product launch timelines by 8-14 months.
- Legacy clinic inventory systems:Small dental practices in Southeast Asia maintain par levels based on historical brand loyalty, resisting formulary switches despite superior clinical data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Ionomer Cement Market |
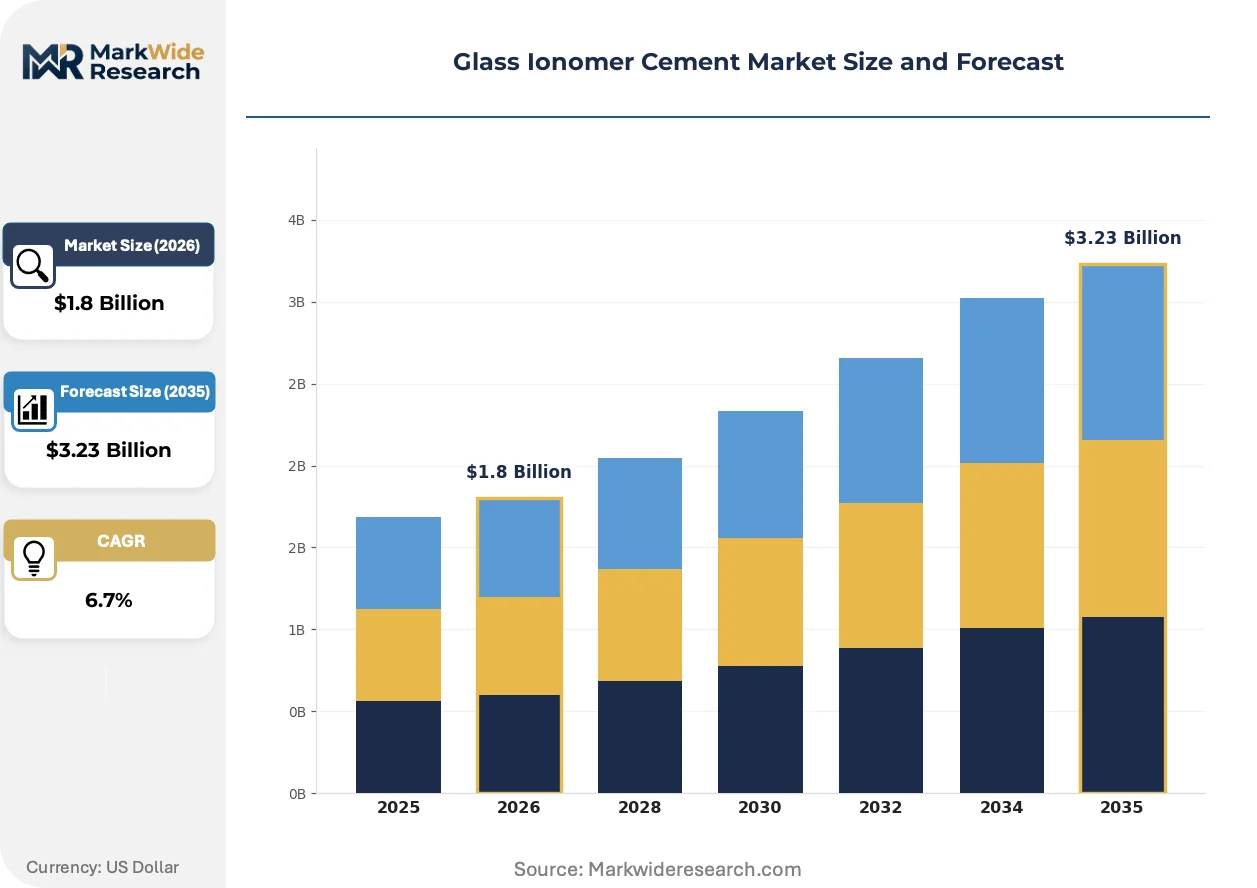
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resin-Modified, Conventional, High-Strength, Aesthetic Application: Restorative Dentistry, Orthodontics, Pediatric Dentistry, Core Build-Up End User: Dentists, Dental Clinics, Hospitals, Research Institutions Distribution Channel: Direct Sales, Online Retail, Dental Distributors, Medical Supply Stores |
| Companies Covered | 3M, Dentsply Sirona, GC Corporation, Ivoclar Vivadent, SHOFU Dental, VOCO GmbH, Kerr Corporation, SDI Limited, Prime Dental Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Ionomer Cement Market Emerging Trajectories
Material science advances and regulatory recalibration are compressing traditional competitive advantages while opening new positioning vectors for formulation houses with integrated evidence-generation capabilities.
High-viscosity bulk-fill glass ionomer formulations are collapsing the procedural step count for posterior Class II restorations by combining packable handling with self-adhesive chemical bonding to enamel and dentin. General practitioners in Australian and Canadian provincial health systems adopt these materials for throughput-sensitive environments where isolation control is inconsistent. The technology is collapsing the historical trade-off between fluoride release and fracture resistance that segmented conventional and resin-modified categories.
The EU MDR's 2021 recast of Annex VIII classification rules reclassifies certain permanent luting cements as Class III implantable devices, triggering notified body involvement and clinical evaluation report requirements that did not exist under the Medical Device Directive. German and Swiss manufacturers with established quality management systems absorb these costs more readily than Mediterranean formulators. High-strength base/liner products face the steepest compliance gradient, as their intended duration of contact with pulp tissue triggers the most stringent biological safety documentation.
Consolidated procurement platforms across Scandinavian and Benelux dental distributor networks disintermediate traditional wholesale relationships, favoring manufacturers with direct-to-clinic logistics infrastructure and real-time inventory visibility. Clinic chains in Denmark and the Netherlands negotiate formulary exclusivity in exchange for volume commitments and compliance data sharing. The shift is most visible in pediatric and public health segments where tender-based purchasing dominates and price transparency requirements expose historical markup structures.
Glass Ionomer Cement Market Segmentation
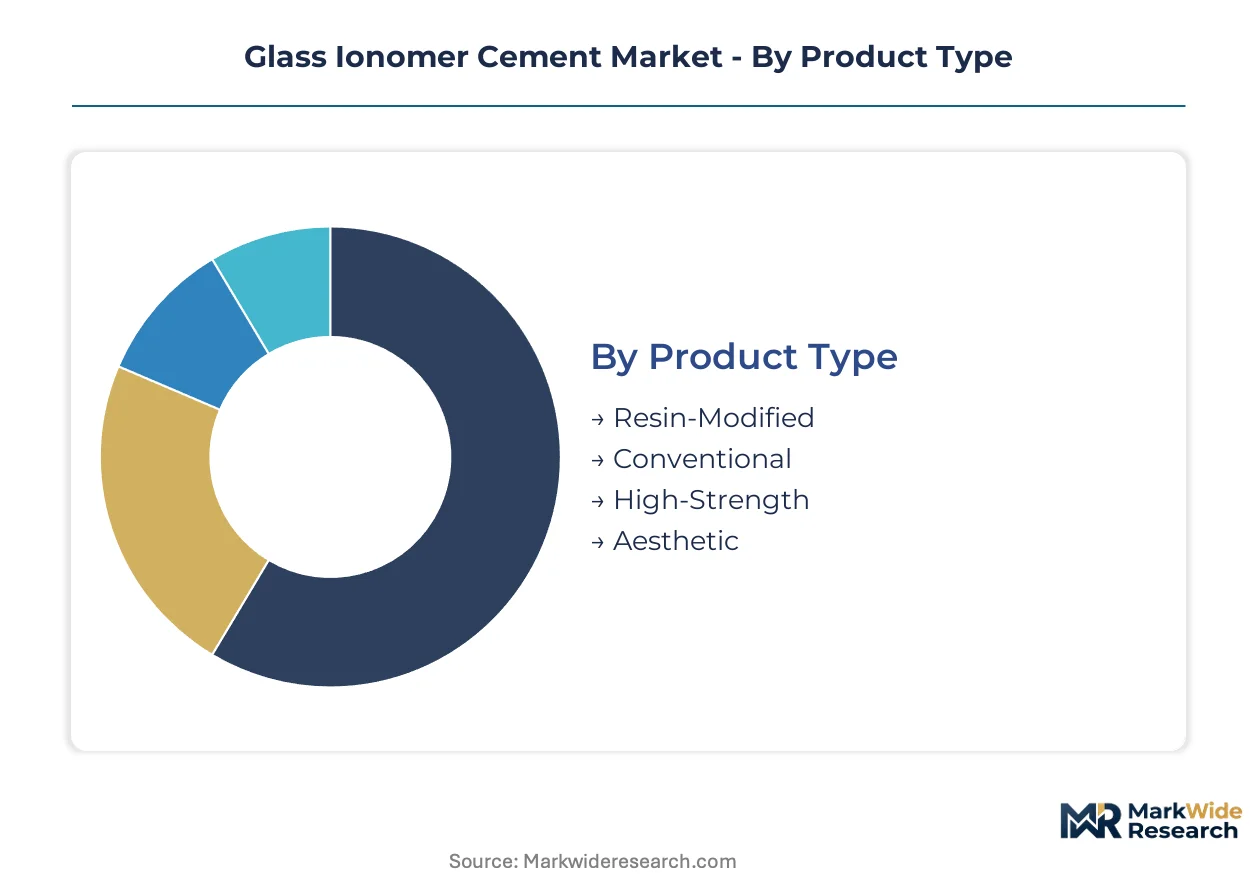
Segmentation in glass ionomer cement markets reflects divergent performance requirements across clinical settings, from moisture-tolerant pediatric formulations to load-bearing core build-up materials. Understanding these divisions clarifies why resin-modified variants dominate private practice while conventional types anchor public health procurement.
Product Type:
Resin-modified formulations span the functional spectrum from fluoride-releasing liners to permanent restorations, with each variant optimized for specific mechanical and handling properties.
- Resin-Modified:Combines polyacrylic acid glass reaction with hydrophilic resin monomers to enable light-cure acceleration and dual-cure reliability in deep cavities. Demand concentrates in German and Japanese private practices where practitioners prioritize fracture resistance in posterior load-bearing applications and chairside efficiency.
- Conventional:Relies solely on acid-base reaction between fluoroaluminosilicate glass and aqueous polyacrylic acid without resin content, maximizing fluoride release and chemical adhesion to moist tooth structure. Adoption clusters in Indian and Vietnamese public health programs where moisture tolerance outweighs mechanical limitations and cost sensitivity dominates procurement decisions.
- High-Strength:Enhanced glass formulation with improved powder-liquid ratio and modified particle size distribution for core build-up and provisional restoration applications requiring immediate load bearing.
- Aesthetic:Translucent glass composition with refined particle morphology and color-matched shade systems for anterior restorations where optical properties rival resin composites.
Established volume favors resin-modified formulations; emerging adoption favors high-strength variants as single-visit dentistry expands.
Application:
Clinical use cases segment by procedural complexity, from routine preventive interventions to technically demanding foundation restorations.
- Restorative Dentistry:Permanent and temporary fillings, cavity liners, and base applications under indirect restorations, serving the broadest practitioner base across general dental practices.
- Orthodontics:Band cementation and bracket bonding applications leveraging chemical adhesion to enamel without etching protocols, particularly valued in moisture-compromised field conditions.
- Pediatric Dentistry:Deciduous tooth restorations and preventive resin restorations where minimal intervention philosophy and fluoride release align with treatment goals. Government dental health schemes in Nagpur, Jaipur, and Kochi drive volume procurement of conventional formulations for school-based programs.
- Core Build-Up:Foundation restorations for endodontically treated teeth requiring high compressive strength and dimensional stability under crown preparation. Australian provincial health systems and Canadian general practices adopt these materials for throughput-sensitive environments where immediate load bearing reduces appointment counts.
Core build-up applications are climbing the fastest as practitioners seek alternatives to composite resin foundations; restorative dentistry maintains the largest installed base.
End User:
Customer types diverge by procurement sophistication, from individual practitioner preference to institutional tender processes.
- Dentists:Individual practitioners selecting materials based on clinical training, brand familiarity, and local distributor relationships, particularly in Southeast Asian markets where historical loyalty resists formulary switches.
- Dental Clinics:Multi-chair group practices and franchise networks negotiating consolidated procurement with direct-to-clinic logistics requirements, prominent in Danish and Dutch clinic chains.
- Hospitals:Academic medical centers and public hospital dental departments with centralized purchasing committees and biocompatibility documentation requirements under EU MDR and FDA pathways.
- Research Institutions:University dental schools and materials science laboratories evaluating novel formulations, generating clinical evidence that shapes subsequent regulatory submissions.
Individual dentists generate the highest transaction frequency; dental clinics are gaining procurement leverage fastest through consolidation.
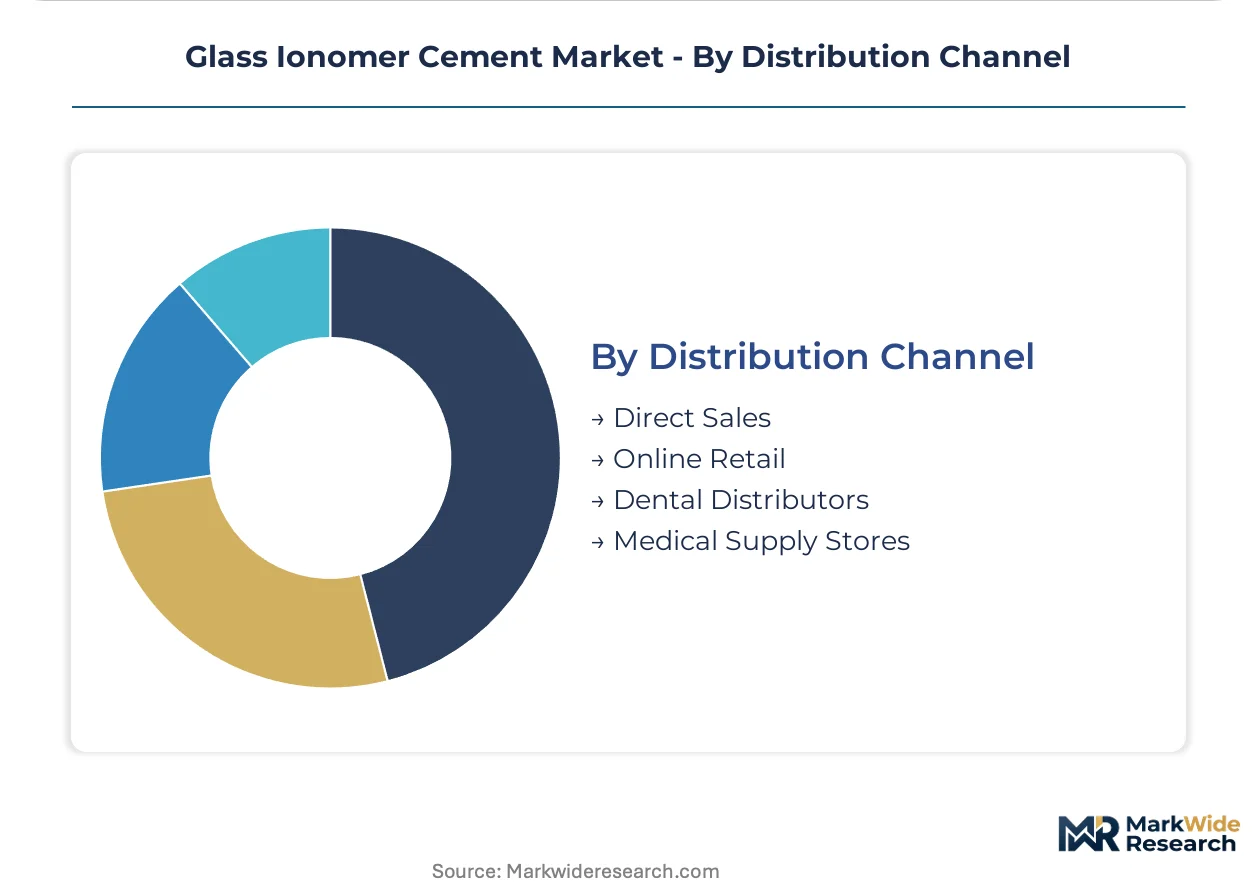
Distribution Channel:
Route-to-market structures reflect geographic density, regulatory complexity, and customer scale preferences.
- Direct Sales:Manufacturer-employed representatives serving high-volume clinic chains and hospital systems with technical support and inventory management, expanding in Scandinavian consolidated procurement environments.
- Online Retail:E-commerce platforms enabling small practice ordering with transparent pricing, growing fastest in North American and Western European markets where digital procurement maturity is highest.
- Dental Distributors:Traditional wholesale networks with field sales forces and local inventory stocking, remaining dominant in Japanese and Southeast Asian markets where relationship-based selling persists.
- Medical Supply Stores:General healthcare distributors serving remote and rural practices with limited product specialization, capturing residual volume in tier-2 Indian cities and secondary Australian markets.
Dental distributors retain the deepest geographic penetration; online retail is expanding most quickly in digitally mature markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU MDR's reclassification of permanent luting cements as Class III implantable devices has concentrated compliance investment in Germany, while pediatric demand expansion reshapes procurement patterns across South and Southeast Asia.
Germany
German dental manufacturers absorb escalating EU MDR clinical evidence costs through established quality management systems, while notified bodies in Berlin and Munich process biological safety documentation for high-strength base products. The country's specialty glass precursor clusters in Bavaria and North Rhine-Westphalia supply fluoroaluminosilicate formulations to domestic formulators and export markets.
India
Government dental health schemes in Nagpur, Jaipur, and Kochi drive volume procurement of conventional glass ionomer cements for school-based pediatric programs. The country's Central Drugs Standard Control Organization maintains distinct biocompatibility filing pathways that extend registration timelines for imported resin-modified variants. Tier-2 municipal tenders increasingly specify moisture-tolerant materials for deciduous tooth restorations.
Japan
Japan's Pharmaceuticals and Medical Devices Agency enforces ISO 9917 convergence with national pharmacopeial methods, creating additional compliance layers for foreign formulation houses. GC Corporation leverages integrated supply chains to sustain shelf presence in Tokyo and Osaka dental clinics. The Kanto region anchors domestic glass powder manufacturing for regional export.
United States
The FDA's 510(k) premarket notification pathway for Class II dental devices maintains faster market access than EU counterparts, though cytotoxicity testing bottlenecks at accredited laboratories extend launch timelines. Chairside CAD/CAM adoption in California and Texas dental practices creates demand for proprietary glass ionomer blocks within digital workflows.
Australia
Australian provincial health systems adopt high-viscosity bulk-fill formulations for throughput-sensitive environments where isolation control proves inconsistent. The Therapeutic Goods Administration aligns biocompatibility requirements with ISO 10993 standards, streamlining multi-market registration for reformulated products. Sydney and Melbourne clinic chains negotiate consolidated procurement with direct-to-clinic logistics requirements.
Glass Ionomer Cement Market Vendor Landscape
Vertically integrated multinationals and specialized regional formulators split the market between compliance-heavy premium tiers and price-sensitive public health segments. The vendor base concentrates around three strategic archetypes: integrated dental conglomerates with digital workflow bundling capabilities, mid-size European formulators with EU MDR-ready quality systems, and Asia-Pacific manufacturers serving government tender markets. Dominant competitive moves include backward integration into fluoroaluminosilicate glass production and strategic partnerships with CAD/CAM system developers.
Among integrated dental conglomerates, 3M and Dentsply Sirona exemplify the digital workflow bundling archetype, anchoring glass ionomer products within broader restorative ecosystems. GC Corporation occupies a distinct position as a Japan-based formulator with captive supply chain infrastructure across Southeast Asian markets. These three entities represent the primary competitive anchors against which mid-size specialists and regional tender suppliers position their offerings.
| Leading Market Players |
|---|
| 3M |
| Dentsply Sirona |
| GC Corporation |
| Ivoclar Vivadent |
| SHOFU Dental |
| VOCO GmbH |
| Kerr Corporation |
| SDI Limited |
| Prime Dental Manufacturing |
| Others |
Supply Flow & Price Mechanics
Bavarian and North Rhine-Westphalian fluoroaluminosilicate glass precursor clusters concentrate manufacturing capacity for specialty aluminosilicate powders, granting domestic German formulators downstream pricing leverage over Mediterranean competitors facing raw material import premiums.
Pricing Analysis
Geographic price spreads between German-manufactured resin-modified formulations and Indian-sourced conventional cements reach threefold multiples, driven by EU MDR compliance costs and certification-grade differentiation. Pricing stratifies across premium aesthetic formulations for Swiss private practices, standard resin-modified tiers for Japanese clinic chains, and economy conventional grades for Indian municipal tenders. Cost compression in the economy tier intensifies as Vietnamese and Thai suppliers enter government procurement markets. Pediatric dentistry programs in Nagpur and Jaipur exhibit the highest price sensitivity, while German and Swiss aesthetic specialists accept substantial premiums for color-matched shade systems.
Supply Chain Analysis
Tariff exposure between Chinese raw material suppliers and European formulators dominates supply chain risk calculus for imported glass powder dependencies. Manufacturing concentrates in Germany, Japan, and India, with specialty fluoroaluminosilicate production anchored in Bavarian chemical clusters and Kanto-region glassworks. Formulation draws from aluminosilicate glass precursors, aqueous polyacrylic acid polymers, and hydrophilic resin monomers. Single-source vulnerability persists for silver-doped bioactive glass additives. Distribution runs through consolidated procurement platforms in Scandinavian markets and traditional dental distributor networks across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass ionomer cement incumbents face sustained substitution pressure from nanohybrid and bulk-fill resin composites in aesthetic anterior applications, requiring defensive repositioning around fluoride-release protocols and moisture-tolerant chemical adhesion.
For Market Incumbents: Insulate core pediatric and public health segments through backward integration into fluoroaluminosilicate glass production, securing captive supply against aluminosilicate precursor volatility. Accelerate ISO 10993 biocompatibility documentation pipelines to absorb EU MDR clinical evidence thresholds that threaten smaller formulation houses. Defend market position by bundling high-viscosity bulk-fill formulations with chairside CAD/CAM system partnerships, creating workflow attachment points that resin composite substitutes cannot easily replicate. For New Entrants and Emerging Players: Tier-2 Indian municipal procurement in Kochi, Nagpur, and Jaipur offers the most penetrable white-space, where government dental health schemes expand subsidized restorative access and incumbent relationships remain thin. Target economy-formulation supply to Vietnamese and Thai public health programs prioritizing moisture-tolerant deciduous tooth restorations. Establish direct-to-clinic logistics capabilities to bypass traditional distributor markups in consolidating Scandinavian and Benelux procurement environments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors EU MDR-ready mid-size formulators with established quality management systems and backward-integrated glass precursor supply. Long-term viability hinges on convergence between glass ionomer and bioactive glass material platforms over the next decade. Acquisition targets should demonstrate notified body relationships for Class III implantable device classifications and captive fluoroaluminosilicate production capacity. Monitor ISO 9917 harmonization progress between Japan's PMDA and European notified bodies as the critical inflection signal for multi-market registration timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Quality System Investment | Notified body relationships for Class III luting cement classifications accelerate market access versus Mediterranean competitors. |
| Backward Integration into Glass Precursors | Captive fluoroaluminosilicate production insulates against German and Japanese supply concentration vulnerabilities. |
| CAD/CAM Workflow Bundling | Proprietary glass ionomer block integration within chairside digital ecosystems creates substitute-resistant attachment points. |
| Bioactive Glass Hybrid Development | Silver-doped antibacterial formulations address caries-active segments in Indian and Vietnamese public health programs. |
| Direct-to-Clinic Logistics Buildout | Real-time inventory visibility satisfies Danish and Dutch clinic chain formulary exclusivity requirements. |
Methodological Framework
Initial hypotheses were tested against primary input from dental materials procurement managers, pediatric dentistry program directors, biomedical regulatory affairs specialists, and glass precursor manufacturing executives and refined through secondary validation against FDA 510(k) filings, EU MDR notified body guidance documents, Japanese PMDA pharmacopeial standards, and ISO 9917 testing protocol harmonization records. Bottom-up demand modeling across product type, application, and end-user segments was triangulated with top-down market sizing from trade flow analysis and distributor revenue disclosures.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning resin-modified, conventional, high-strength, and aesthetic product types; restorative, orthodontic, pediatric, and core build-up applications; and dentist, dental clinic, hospital, and research institution end users. CAGRs were derived from installed base erosion rates, procedure volume elasticities, and substitution dynamics between glass ionomer and resin composite materials. Forecast inputs incorporated EU MDR compliance cost absorption curves and Indian municipal tender expansion trajectories.
Macroeconomic conditions sit as an overlay; deviation in dental reimbursement policy, raw material energy costs, or clinical evidence generation timelines would shift the trajectory. Forecasts reflect documented assumptions regarding ISO 10993 testing capacity expansion and PMDA-EU harmonization progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Special Graphite Market
Specialty Materials
Nanocapsules Market
Specialty Materials
Global Graphic Film Market
Specialty Materials
Silicone Solutions for Leather and Textile Market
Specialty Materials
Alginate Films Market
Specialty Materials
Asia-Pacific Green Sic Market
Specialty Materials
Solar Backsheet Films Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Engineered Quartz Surface Market
Specialty Materials
Middle East and Africa Anti-Friction Coatings Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Microwave Absorbing Materials Market
Specialty Materials
Compostable Cotton Swab Market
Specialty Materials
Global Supplementary Cementitious Materials Market
Specialty Materials
Battery Separator Films Market