
 India Epoxy Resins Market | 2026-2036
India Epoxy Resins Market Size, Share, and Industry Trends Forecast 2026-2036
India Epoxy Resins Market Foresight
BIS certification for construction-grade epoxy systems is hardening the cost-of-entry calculus for smaller compounders. Aditya Birla Chemicals Limited leverages its integrated phenolic chain to sustain margin resilience against raw material volatility. Huntsman Advanced Materials India Private Limited anchors its position through specialized electrical encapsulation grades serving the domestic electronics assembly sector. Atul Ltd differentiates via backward integration into epichlorohydrin, a critical precursor most competitors import.
Epoxy resins are thermosetting polymers formed by reacting epichlorohydrin with bisphenol-A or bisphenol-F, yielding materials with exceptional adhesion, chemical resistance, and mechanical strength above 150°C glass transition temperatures in cured states. Liquid epoxy dominates volume flows into coatings and adhesive formulations across Indian automotive and construction value chains. Solid epoxy grades command premium positioning in powder coating applications for electrical enclosures and appliance finishes. Modified epoxy variants incorporating reactive diluents or flexibilizers represent the fastest-expanding technology tier, driven by wind turbine blade fabrication demands in Gujarat and Tamil Nadu.
BIS standards, CDSCO medical device rules for implantable coatings, and state-level pollution control mandates collectively shape product specifications and plant licensing timelines across Indian manufacturing zones. The Central Electricity Authority's grid infrastructure expansion roadmap directly amplifies demand for electrical encapsulation grades meeting stringent dielectric standards. Stakeholders must monitor BIS harmonization with REACH-aligned chemical safety protocols, as this convergence will determine which formulation portfolios retain market access without costly retooling.
Market Dynamics
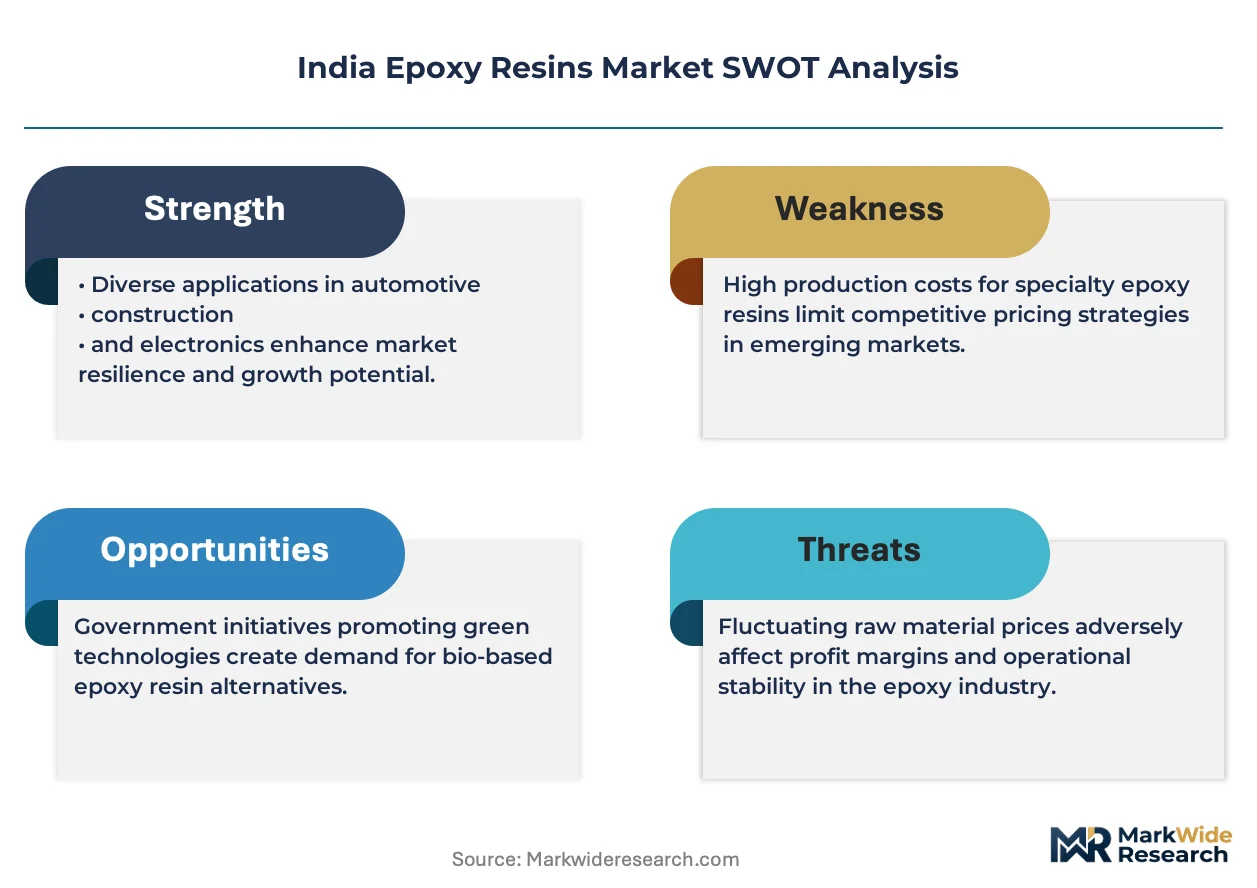
Wind turbine blade fabrication is converging with modified epoxy chemistry to create the fastest-expanding demand tier in India's specialty chemicals landscape. BIS certification mandates for construction-grade materials are simultaneously hardening entry barriers and compressing formulation flexibility for smaller compounders. The Central Electricity Authority's grid infrastructure roadmap is amplifying electrical encapsulation requirements across Maharashtra's manufacturing belt.
Growth Catalysts
- CEA grid expansion mandates:Central Electricity Authority transmission infrastructure targets are accelerating consumption of high-dielectric encapsulation grades across switchgear and transformer manufacturing corridors.
- Tamil Nadu blade fabrication cluster:Wind energy OEMs are absorbing disproportionate volumes of flexibilized epoxy systems for 80-meter-plus rotor blade production.
- PLI scheme for specialty chemicals:Production-linked incentives for advanced materials are attracting capacity investments into Gujarat's petrochemical downstream zones.
Market Restraints
- Epichlorohydrin import dependence:Domestic supply covers under one-third of precursor demand, exposing compounders to freight volatility and currency fluctuation risks.
- BIS harmonization delays:REACH-aligned chemical safety protocol convergence is extending product registration timelines and retooling costs for mid-tier formulators.
- Acrylic polyurethane substitution:Automotive refinish and protective coating segments are migrating toward faster-curing alternatives in temperature-sensitive applications.
Strategic Opportunities
- CDSCO medical device coatings:Implantable device regulation is opening specification-grade opportunities for biocompatible epoxy formulations in cardiovascular and orthopedic segments.
- Kerala-Karnataka electronics corridor:Underpenetrated southern PCB and semiconductor packaging demand offers white space for electrical-grade epoxy distributors.
- DGFT export promotion schemes:Advance authorization and duty drawback mechanisms are enabling cost-competitive positioning in Bangladesh and Sri Lanka markets.
Industry Challenges
- Formulation chemist scarcity:India's technical institutes produce insufficient polymer science graduates with thermoset curing kinetics expertise.
- Multi-certification stacking:Simultaneous BIS, CDSCO, and state pollution control approvals extend product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Epoxy Resins Market |
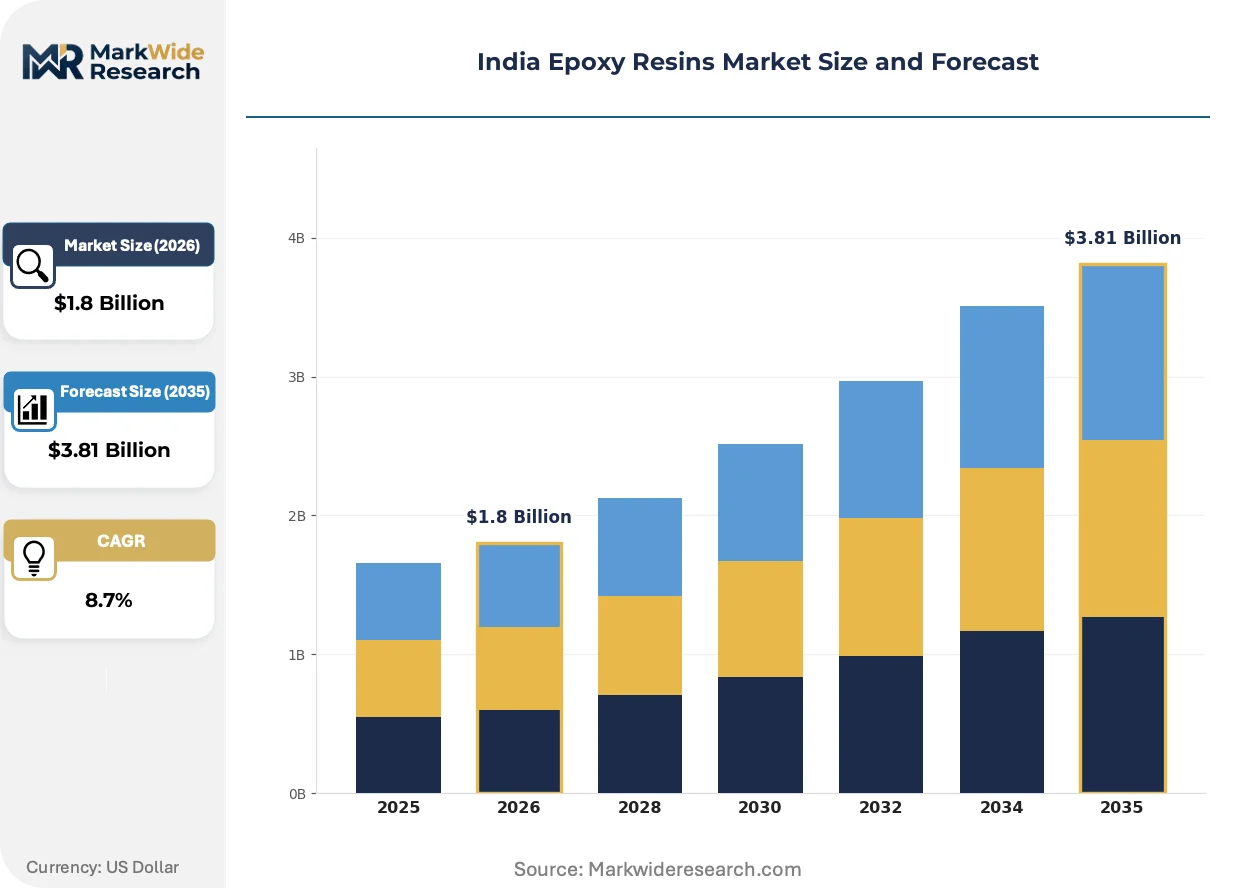
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Epoxy, Solid Epoxy, Modified Epoxy, Waterborne Epoxy Technology: Thermoset, Thermoplastic, Bio-based, Hybrid End User: Automotive, Electronics, Construction, Aerospace Applications: Coatings, Adhesives, Composites, Electrical Encapsulation |
| Companies Covered | KUKDO Chemical Co. Ltd., ARK Epoxy, Aditya Birla Chemicals Limited, Jyoti Innovision Pvt. Ltd., K2P Chemicals, Huntsman Advanced Materials India Private Limited, Atul Ltd, Hexion Chemicals India Pvt. Ltd., Dow Chemicals India Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Epoxy Resins Market Shifts & Advancements
Reactive diluent technology is actively compressing viscosity-performance tradeoffs that previously limited epoxy penetration in large-structure fabrication. Formulation houses are racing to commercialize systems that cure at ambient temperatures without sacrificing glass transition thresholds.
Bio-based epichlorohydrin from glycerin feedstock is converging with conventional bisphenol-A chemistry to reduce petrochemical intensity in wind blade laminates. Suzlon and Vestas suppliers in Gujarat are piloting these hybrid systems at 40-meter mold stations. The technology is converging with cost-parity targets to enable mass adoption without green premiums by 2027.
BIS notification of harmonized standards with REACH chemical safety protocols is forcing reformulation of legacy hardener systems across construction adhesives. CDSCO's impending medical device coating rules are accelerating biocompatibility testing investments. Electrical encapsulation grades face the steepest compliance burden as dielectric standards tighten simultaneously.
Direct procurement from formulation houses is displacing distributor intermediaries among Maharashtra's tier-1 automotive OEMs. Long-term supply agreements with volume commitments and technical service bundling are replacing spot purchasing. Tamil Nadu wind energy developers pioneered this shift; Pune-Nashik automotive clusters are replicating the model.
India Epoxy Resins Market Segmentation
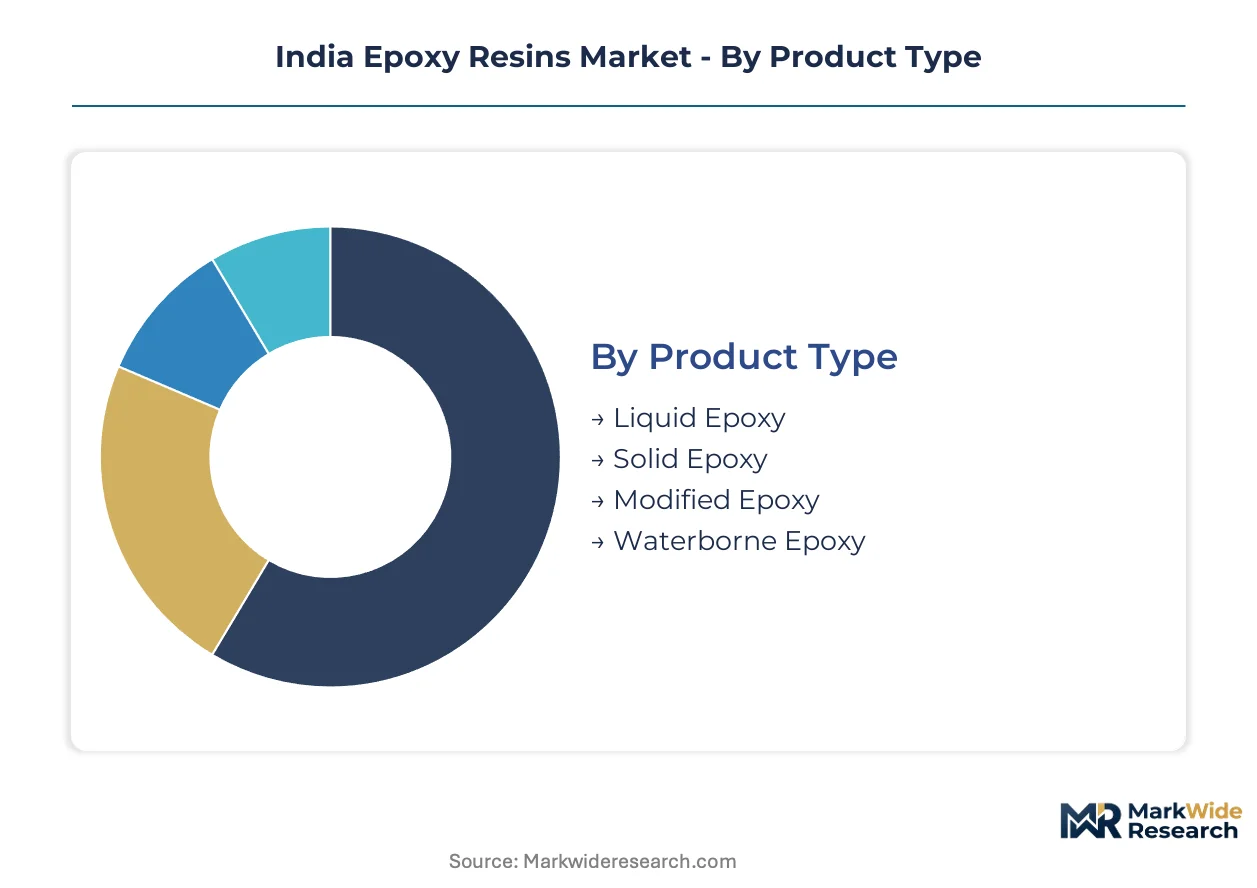
Epoxy resin formulation chemistry determines performance ceilings across India's industrial value chains. Specification-grade differentiation separates construction commodity flows from wind blade laminates and electrical encapsulation systems serving CEA-mandated infrastructure buildouts.
Product Type:
Specification hierarchy separates commodity liquid grades from engineered solid and modified variants commanding formulation premiums.
- Liquid Epoxy:Low-viscosity bisphenol-A or bisphenol-F based systems dominate volume throughput into protective coatings and structural adhesives. Maharashtra automotive OEMs and Gujarat construction chemical compounders absorb the majority of standard-grade flows, with price sensitivity limiting margin expansion.
- Modified Epoxy:Reactive diluent and flexibilizer incorporation enables large-structure fabrication without viscosity-performance tradeoffs. Tamil Nadu wind blade manufacturers specify these systems for 80-meter-plus rotor production, creating the steepest expansion trajectory among product tiers.
- Solid Epoxy:Higher molecular weight grades serve powder coating applications for electrical enclosures and appliance finishes through controlled melt viscosity.
- Waterborne Epoxy:Emulsion-based systems address state pollution control mandates in surface coatings where solvent emissions face tightening scrutiny.
Mature deployment sits with liquid epoxy. Newer deployment is concentrated in modified epoxy.
Technology:
Process chemistry and feedstock origin create tiered positioning across sustainability and performance axes.
- Thermoset:Irreversible crosslinking chemistry delivers glass transition temperatures exceeding 150°C in cured states. Crosslink density engineering separates commodity construction adhesives from high-dielectric electrical encapsulation grades serving CEA grid infrastructure targets.
- Bio-based:Glycerin-derived epichlorohydrin feedstock reduces petrochemical intensity in wind blade laminates. Suzlon and Vestas suppliers in Gujarat pilot hybrid systems at 40-meter mold stations, with cost-parity targets enabling mass adoption without green premiums.
- Thermoplastic:Reversible processing characteristics suit repairable coating systems and recyclable composite intermediates.
- Hybrid:Dual-cure or dual-network architectures combine processing advantages from distinct polymer classes.
Established capacity centers on thermoset platforms. Emerging investment flows into bio-based technology.
End User:
Application performance requirements segment demand by certification burden and specification stringency.
- Electronics:Electrical encapsulation grades meeting stringent dielectric standards serve PCB manufacturing and semiconductor packaging across Maharashtra's Mumbai-Pune belt. BIS harmonization with REACH-aligned protocols is forcing reformulation of legacy hardener systems.
- Construction:BIS certification mandates for structural adhesives and protective coatings harden entry barriers while compressing formulation flexibility for smaller compounders.
- Automotive:Pune-Nashik clusters specify high-performance coatings and structural bonding systems with long-term supply agreements replacing spot purchasing.
- Aerospace:Specification-grade prepregs and tooling compounds serve maintenance and limited domestic manufacturing.
Volume concentration rests with construction. Specification intensity peaks in electronics.
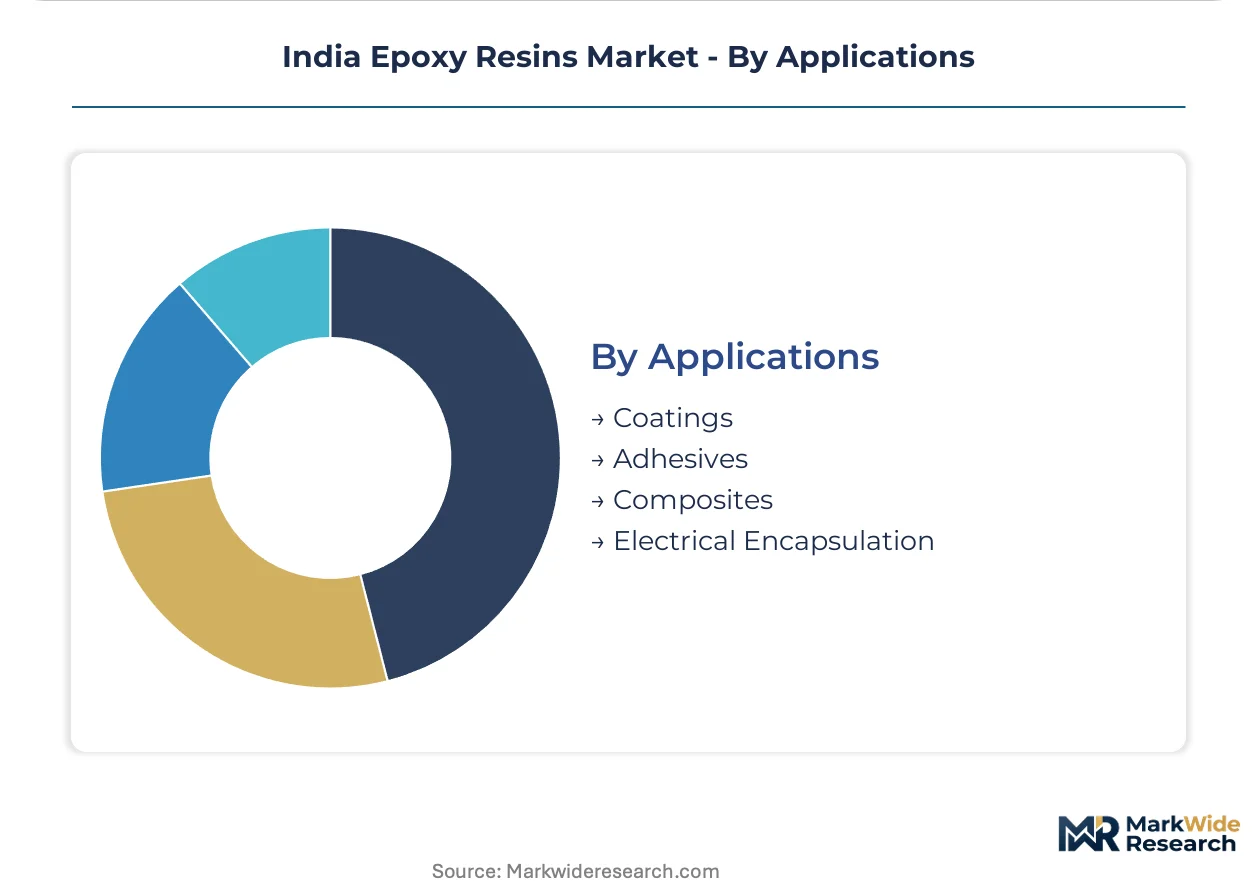
Applications:
Functional end-use separates commodity surface protection from structural and electrical performance systems.
- Composites:Fiber-reinforced laminates for wind turbine blades represent the fastest-expanding application tier. Modified epoxy chemistry enables 80-meter-plus rotor fabrication across Gujarat and Tamil Nadu manufacturing corridors.
- Electrical Encapsulation:High-dielectric grades insulate switchgear and transformers under CEA grid expansion mandates. This application faces the steepest compliance burden as dielectric standards tighten simultaneously with BIS-REACH convergence.
- Coatings:Protective and decorative surface films span automotive refinish, industrial maintenance, and marine protection.
- Adhesives:Structural bonding systems serve construction, automotive, and general industrial assembly.
Traditional volume resides in coatings. Accelerating growth concentrates in composites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum, Chemicals and Petrochemicals Investment Regions (PCPIRs) in Gujarat and Andhra Pradesh concentrate epoxy resin consumption through integrated downstream clusters. State-level industrial policies amplify this concentration.
Maharashtra
Mumbai-Pune specialty chemicals corridor absorbs disproportionate volumes of high-performance electrical encapsulation grades. CEA grid infrastructure mandates drive switchgear and transformer manufacturing demand. Nashik-Pune automotive clusters specify structural bonding systems through direct procurement agreements.
Gujarat
Dahej PCPIR anchors wind turbine blade fabrication with modified epoxy systems for 80-meter-plus rotors. PLI scheme incentives attract capacity investments into petrochemical downstream zones. Suzlon and Vestas suppliers pilot bio-based epichlorohydrin hybrid systems at 40-meter mold stations.
Tamil Nadu
Wind energy OEMs specify flexibilized epoxy chemistry for large-structure blade production. State pollution control mandates tighten emissions scrutiny on solvent-based coating operations. Coimbatore-Salem manufacturing belt concentrates composite fabrication capacity.
Karnataka
Bengaluru electronics corridor generates underpenetrated demand for PCB and semiconductor packaging grades. CDSCO medical device rules open specification opportunities for biocompatible coating formulations. Mysuru-Belagavi industrial nodes absorb construction-grade adhesive volumes.
Kerala
Cochin petrochemical complex feeds downstream formulation activities with precursor availability constraints. State-level coastal regulation zone notifications affect plant licensing timelines for marine coating compounders. Kochi-Thiruvananthapuram corridor develops specialty chemicals skill pools.
India Epoxy Resins Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. The vendor base separates into three layers: integrated chemical majors with captive epichlorohydrin supply, mid-scale compounders serving regional industrial clusters, and niche distributors bridging specification-grade gaps. Strategic archetypes include backward-integrated precursors producers, formulation houses with BIS certification depth, and technology licensors from multinational parents. Capacity expansion and direct procurement contracting dominate competitive moves as spot purchasing fades.
Within the integrated majors tier, Aditya Birla Chemicals Limited and Atul Ltd exemplify divergent supply chain strategies. Aditya Birla leverages phenolic chain integration for margin resilience. Atul anchors positioning through captive epichlorohydrin production that competitors import. Huntsman Advanced Materials India Private Limited occupies a technology-licensing position serving electrical encapsulation specification requirements. KUKDO Chemical Co. Ltd. represents Korean-origin capital deployment into Indian downstream markets.
| Leading Market Players |
|---|
| KUKDO Chemical Co. Ltd. |
| ARK Epoxy |
| Aditya Birla Chemicals Limited |
| Jyoti Innovision Pvt. Ltd. |
| K2P Chemicals |
| Huntsman Advanced Materials India Private Limited |
| Atul Ltd |
| Hexion Chemicals India Pvt. Ltd. |
| Dow Chemicals India Private Limited |
| Others |
Supply & Pricing Matrix
Formulation chemist scarcity across the Mumbai-Pune corridor widens labor-cost differentials between BIS-certified compounders and uncertified regional players, compressing pricing-tier spreads for commodity-grade liquid epoxy while preserving premiums for modified systems serving Tamil Nadu wind blade fabricators.
Pricing Analysis
Short lead-time premiums distinguish contract-based long-term offtake agreements from spot inventory discounts in Maharashtra's electrical encapsulation segment. Three-tier pricing structure across BIS-certified premium, standard industrial, and economy construction grades separates Huntsman-grade dielectric formulations from commodity adhesive flows. Pricing pressure stems from acrylic polyurethane substitution in automotive refinish applications, with Gujarat construction chemical compounders exhibiting highest price sensitivity versus CEA-mandated grid infrastructure buyers.
Supply Chain Analysis
Regional distribution centers in Dahej, Mundra, and Chennai form a hub-and-spoke pattern feeding formulation houses across western and southern manufacturing belts. Supply concentrates in China, South Korea, and Thailand for epichlorohydrin precursor flows, while domestic captive production at Atul Ltd's Gujarat complex covers under one-third of national demand. Single-source vulnerability from epichlorohydrin import dependence exposes compounders to freight volatility, with distribution running through direct procurement channels displacing traditional distributor intermediaries among tier-1 automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS harmonization with REACH-aligned chemical safety protocols erects a formidable cost-of-compliance barrier, creating sustainable moats for compounders with pre-certified formulation portfolios while forcing retooling investments that smaller regional players cannot absorb.
For Market Incumbents: Deepen backward integration into epichlorohydrin precursors or phenolic chain feedstocks to defend margin resilience against raw material volatility and currency fluctuation risks. Prioritize certification investment in CDSCO medical device coating specifications before rule finalization locks out late entrants, while locking long-term supply agreements with Tamil Nadu wind energy developers to secure volume commitments against emerging Korean-capital competitors.
For New Entrants and Emerging Players: Begin with underpenetrated demand in the Kerala-Karnataka electronics corridor for PCB and semiconductor packaging grades, where established distributors retain channel control gaps. Target biocompatible epoxy formulations for cardiovascular and orthopedic implantable devices as the most penetrable specification-grade segment, leveraging DGFT advance authorization mechanisms for cost-competitive positioning in Bangladesh and Sri Lanka export markets.
For Investors and Strategic Acquirers: Re-rating potential sits with BIS-certified mid-scale compounders with captive formulation R&D capabilities given CDSCO regulatory catalysts opening medical device coating specifications. Long-term viability over a multi-year horizon favors acquisition targets with established electrical encapsulation dielectric testing infrastructure and pre-qualified supply relationships with CEA-mandated grid infrastructure contractors. Monitor BIS notification timelines as the critical inflection signal for portfolio retooling requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epichlorohydrin | Captive precursor supply at Atul Ltd insulates margin resilience against import volatility. |
| BIS Certification Investment | Pre-qualified formulation portfolios retain market access under REACH-aligned protocol convergence. |
| Long-term Supply Agreement | Direct procurement contracting with Tamil Nadu wind OEMs displaces spot purchasing patterns. |
| Bio-based Manufacturing Transition | Glycerin-derived epichlorohydrin hybrid systems pilot at Gujarat 40-meter mold stations. |
| Joint Venture with Korean Technology Licensor | KUKDO Chemical capital deployment transfers specialized electrical encapsulation grade expertise. |
Research Methodology
Trade statistics from the Ministry of Commerce, DGFT advance authorization filings, and BIS certification registries formed the secondary backbone for volume estimation, cross-referenced with primary interviews involving plant managers at Dahej PCPIR formulation facilities, procurement leads at Pune-Nashik automotive OEMs, and technical R&D directors at integrated chemical majors. Bottom-up and top-down triangulation validated segment-level consumption patterns against customs data for epichlorohydrin and bisphenol-A precursor flows.
Bottom-up modeling anchored the analytical lens, with top-down macroeconomic cross-checks ensuring consistency across the projection horizon. Segmentation dimensions included product type tier, end-use industry vertical, and regional manufacturing cluster concentration. CAGRs derived from trend extrapolation of CEA grid infrastructure targets, PLI scheme capacity addition announcements, and wind energy installation trajectories, with dielectric standard tightening schedules and BIS harmonization timelines as industry-specific forecast inputs.
Underlying measurement precision varies by segment; electrical encapsulation and medical device coating grades carry tighter precision than commodity construction adhesive flows due to specification-grade certification requirements. Forecasts reflect documented assumptions regarding regulatory implementation timelines and precursor import availability, with periodic stress-testing of base assumptions recommended given epichlorohydrin supply concentration risks and potential acrylic substitution acceleration in temperature-sensitive automotive applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Construction Polymer Market
Polymers & Resins
Resin Dispersion Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Europe Epoxy Resins Market
Polymers & Resins
Basic Methacrylate Copolymer Market
Polymers & Resins
Polymer Resin Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Acrylonitrile Styrene Acrylate (ASA) Market
Polymers & Resins
Water Dispersible Polymers Market
Polymers & Resins
Expanded Thermoplastic Polyurethane Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
Biopolymer Tubes Market