
 Filled Fluoropolymer Market | 2026-2036
Filled Fluoropolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Filled Fluoropolymer Market Analysis
Specialized polymer compounding expertise is rotating toward Asia-Pacific production hubs, tightening availability in North America and Europe. The Chemours Company leverages its integrated fluorspar-to-resin infrastructure to sustain captive supply of base PTFE for filled grades. Daikin Industries anchors Japanese demand through precision compounding capabilities serving semiconductor equipment fabricators. Solvay competes in European aerospace qualification programs where filled PFA grades must meet OEM process specifications.
Filled fluoropolymers combine base resins such as PTFE, FEP, PFA, or ETFE with reinforcing fillers including glass fiber, carbon, graphite, or bronze to enhance wear resistance, creep resistance, and thermal conductivity while retaining chemical inertness. These compounds are molded or machined into seals, bearings, linings, and electrical components for aggressive chemical and thermal environments. PTFE compounds occupy the largest volume position due to decades of specification in process industry equipment, though PFA-filled grades represent the fastest-growing category as semiconductor and pharmaceutical applications demand superior purity and weldability. The films and sheets form category carries above-average margins where aerospace and electronics buyers require tight thickness tolerances and lot-to-lot consistency.
EPA oversight of per- and polyfluoroalkyl substance releases shapes US manufacturing site permitting and waste handling protocols for fluoropolymer compounders. REACH restrictions on perfluorinated chemicals under ECHA review are forcing European formulators to document filler sourcing and alternative base resin strategies. China's GB standards and MEE environmental enforcement are raising compliance costs for domestic fluoropolymer production. Stakeholders must monitor regulatory divergence across these jurisdictions to anticipate which filler technologies and base resin qualifications will retain market access.
Market Dynamics
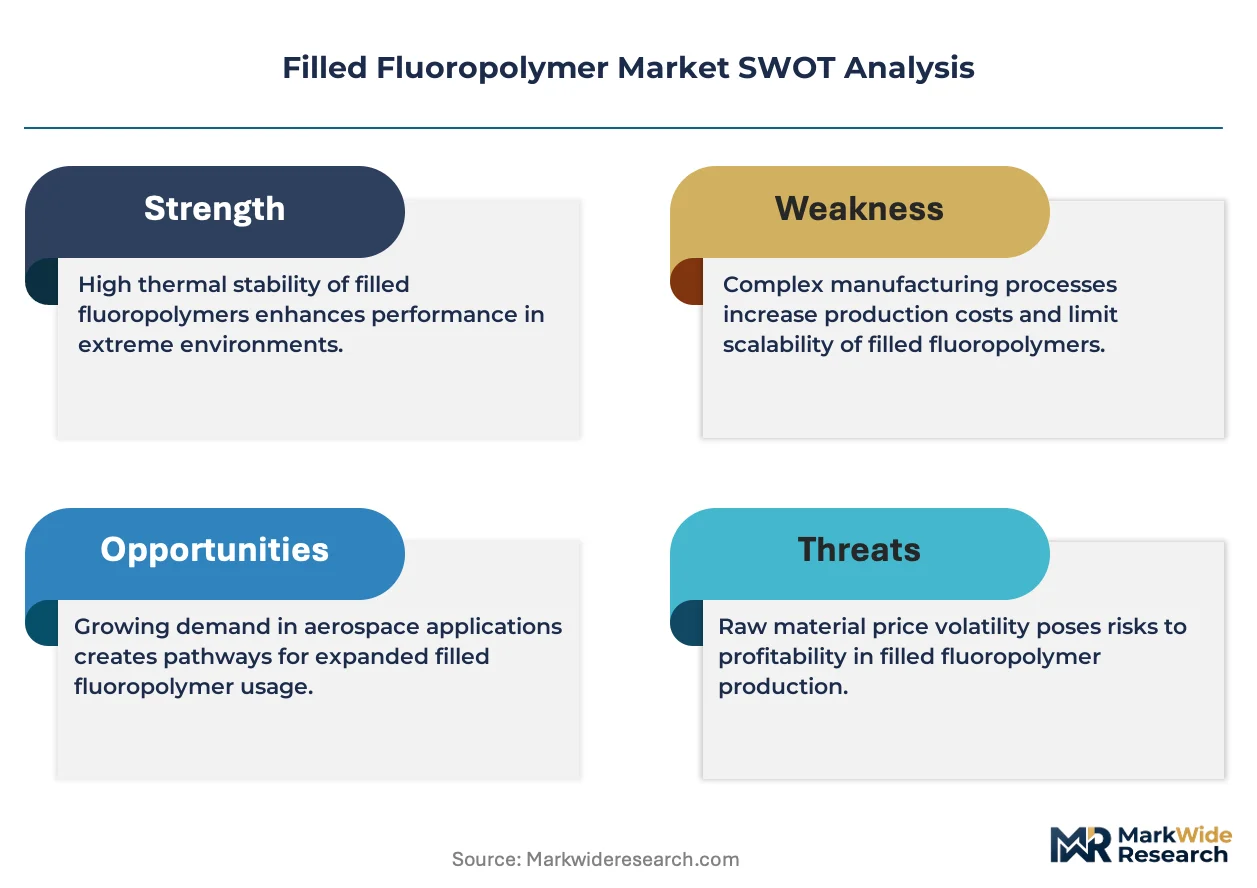
REACH restrictions on perfluorinated substances are redirecting European formulation strategies toward compliant filler systems, while Asia-Pacific production hubs absorb compounding expertise that tightens availability in established markets. This regulatory-sourcing tension defines current competitive positioning.
Growth Catalysts
- Semiconductor fabrication expansion:Filled PFA grades gain specification in wafer processing equipment where purity and weldability requirements exceed standard PTFE capabilities. Equipment fabricators in Japan and South Korea drive qualification programs.
- REACH Article 68 restrictions:European chemical processors must replace legacy seals and bearings with compliant filled fluoropolymer compounds, creating specification mandates for alternative filler systems.
- Glass fiber reinforcement:This filler technology enhances creep resistance in chemical processing seals, enabling service life extension in aggressive acid environments that degrade unfilled resins.
Market Restraints
- Fluorspar supply concentration:Captive mining assets in China and Mexico limit independent compounder access to base PTFE feedstock, concentrating upstream control among integrated producers.
- PFAS release liability:EPA oversight of per- and polyfluoroalkyl substance emissions raises site permitting costs and waste handling complexity for US manufacturing facilities.
- Ceramic matrix composite substitution:Aerospace bearing applications increasingly specify silicon carbide-reinforced ceramics where filled fluoropolymers previously dominated thermal envelope limits.
Strategic Opportunities
- India's pharmaceutical manufacturing corridor:Filled PFA demand from sterile processing equipment lags regional pharma output growth, creating specification white space for compliant compounders.
- Carbon filler thermal conductivity:Convergence of electric vehicle battery thermal management with semiconductor fabrication tooling creates cross-application demand for heat-dissipating compounds.
- EU F-Gas Regulation phase-down:This policy framework incentivizes process equipment retrofits with filled fluoropolymer seals that eliminate fugitive emissions from mechanical compression systems.
Industry Challenges
- Precision compounding talent scarcity:Dispersion of filler particles at sub-micron uniformity requires specialized polymer engineering expertise concentrated in Japan and Germany.
- Aerospace OEM qualification timelines:Filled PFA grades require 18-36 month certification cycles with airframe manufacturers, compressing effective product lifecycle returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filled Fluoropolymer Market |
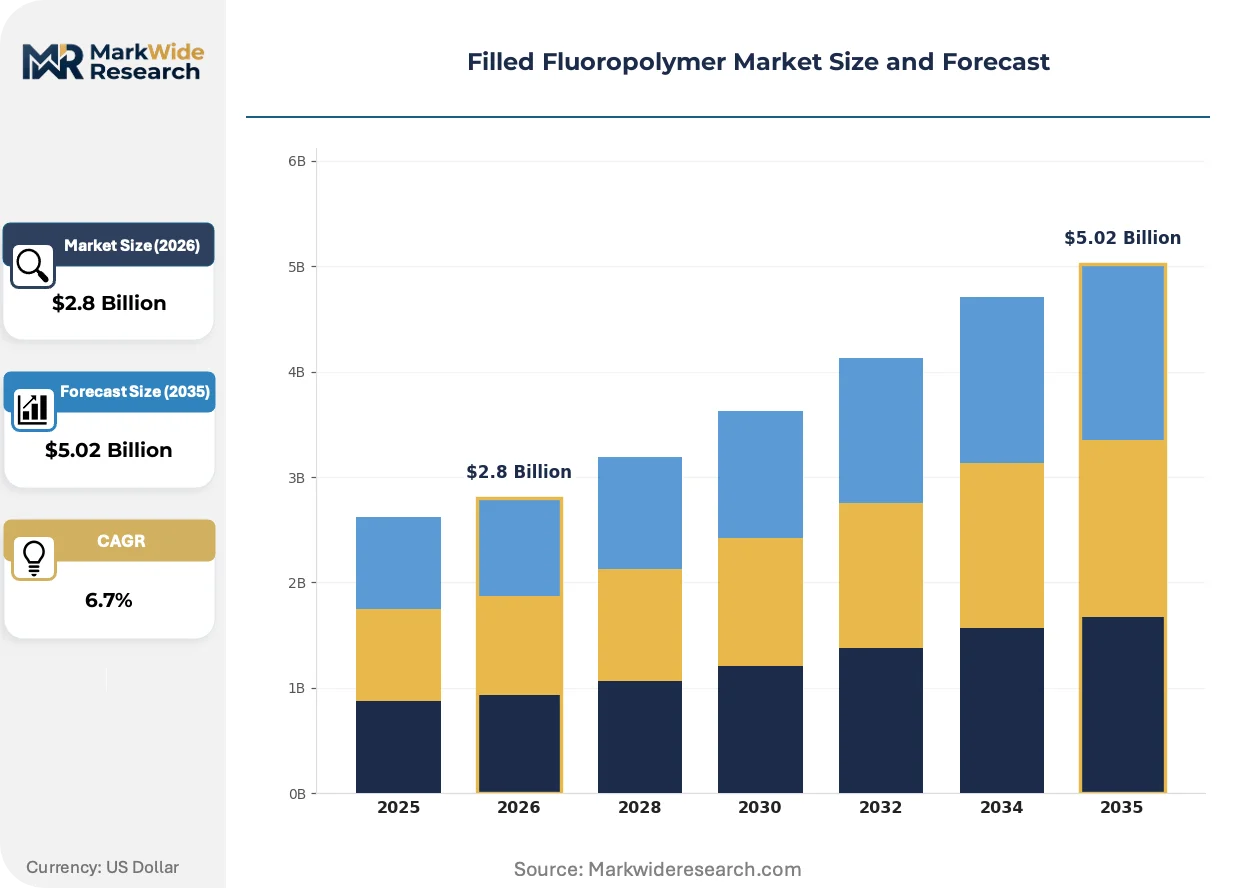
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, FEP, PFA, ETFE Application: Aerospace, Automotive, Electrical, Chemical Processing End User: Manufacturing, Electronics, Energy, Medical Form: Films, Sheets, Rods, Tubes |
| Companies Covered | The Chemours Company, Daikin Industries, Ltd., 3M, AGC Inc., Solvay, Mitsubishi Chemical Corporation, HaloPolymer OJSC, AFT Fluorotec Ltd, Saint-Gobain Performance Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filled Fluoropolymer Market Emerging Trajectories
Formulation chemistry is pivoting toward bio-based and mineral filler alternatives as regulatory pressure on perfluorinated substances intensifies across multiple jurisdictions. Material scientists and process engineers are redefining performance benchmarks.
Nano-scale ceramic fillers are decomposing traditional glass fiber reinforcement in high-wear bearing applications. Automotive transmission seal manufacturers in Germany specify these compounds for extended service intervals. The technology is decomposing established supply relationships between compounders and tier-one suppliers who built specifications around legacy filler systems.
ECHA's expanding PFAS restriction proposals under REACH are forcing European formulators to document alternative base resin strategies and filler sourcing. Compounders face reformulation costs that compress margin structures on existing product lines. Aerospace and pharmaceutical end-uses in France and Germany face the steepest compliance timelines.
Buyers in chemical processing are consolidating vendor relationships around compounders who control captive fluorspar-to-resin infrastructure. Long-term supply agreements are displacing spot procurement for filled PTFE bearings and seals. This concentration is most visible in Germany's industrial corridor where automotive and chemical OEMs specify single-source qualification for extreme-service components.
Filled Fluoropolymer Market Segmentation
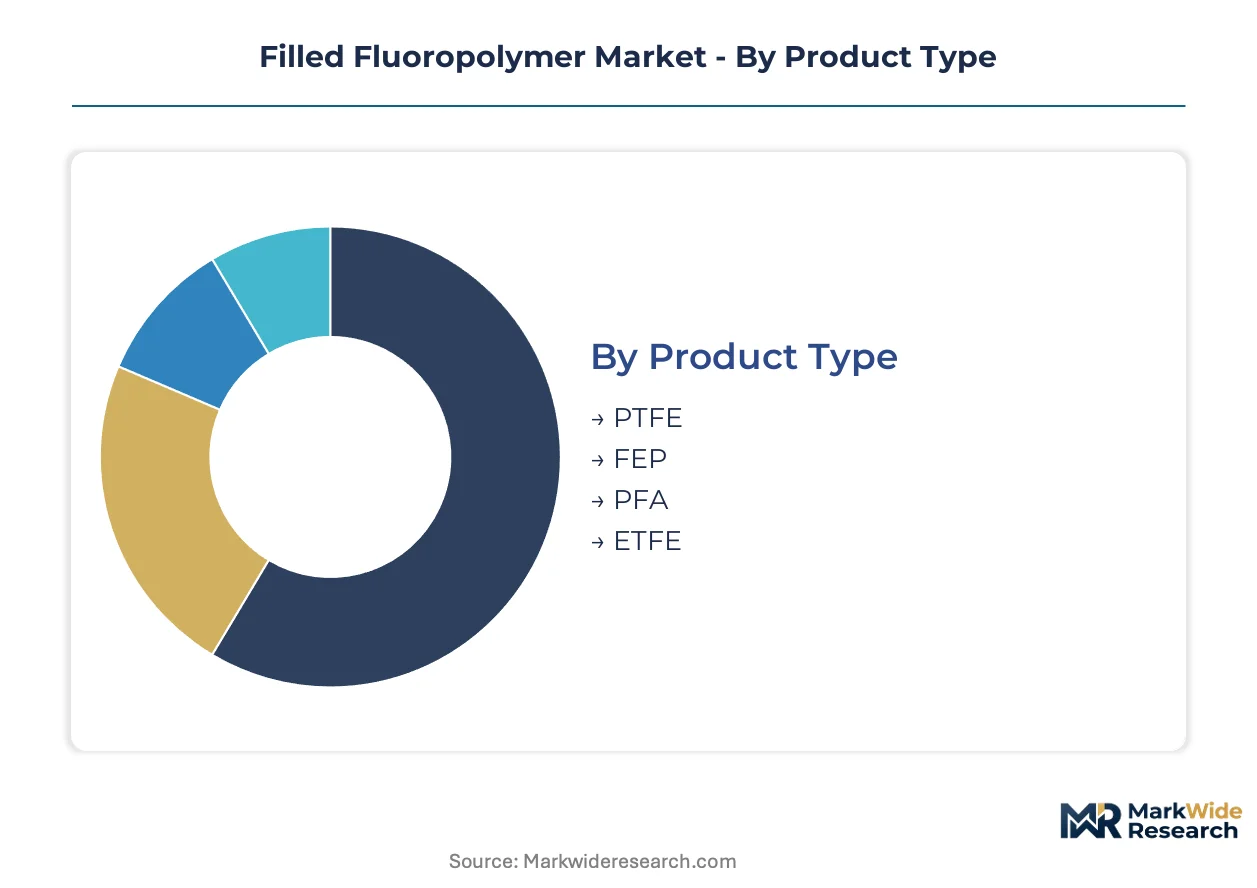
Segmentation in the filled fluoropolymer market reveals how base resin chemistry, application severity, and form factor precision create distinct commercial lanes with divergent margin profiles and qualification barriers. Buyers route procurement through different channels depending on whether they need commodity PTFE bearings or aerospace-certified PFA films.
Product Type:
PTFE compounds flow through distributor networks to chemical processors, while PFA and FEP grades move through direct OEM qualification channels with tighter technical service requirements.
- PTFE:Glass fiber, carbon, and bronze fillers enhance creep resistance and wear properties in this base resin. Chemical processing equipment fabricators in Germany specify PTFE compounds for seals and bearings exposed to sulfuric acid environments. REACH Article 68 restrictions are forcing reformulation toward compliant filler systems.
- PFA:Melt-processable fluoropolymer enabling welded joints and superior purity. Semiconductor equipment manufacturers in Japan and South Korea drive qualification programs for wafer processing components. This grade commands premium positioning where weldability exceeds standard PTFE capabilities.
- FEP:Lower processing temperature than PFA with comparable chemical resistance. Electrical insulation applications favor FEP compounds for wire coating and cable jacketing.
- ETFE:High mechanical strength and radiation resistance distinguish this resin. Architectural membrane and photovoltaic applications specify ETFE films.
By volume, PTFE leads. By growth pace, PFA is expanding most quickly.
Application:
Application segmentation tracks how thermal envelope, chemical exposure severity, and regulatory compliance requirements split demand across cost tiers.
- Aerospace:Filled PFA grades must survive 18-36 month OEM certification cycles with airframe manufacturers. FAA and EASA qualification protocols compress effective product lifecycle returns for compounders.
- Automotive:Transmission seals and bearing applications in Germany specify nano-scale ceramic fillers for extended service intervals. KBA type-approval requirements shape specification patterns.
- Electrical:Wire insulation and connector applications demand tight thickness tolerances. ETFE and FEP compounds dominate this segment.
- Chemical Processing:Legacy seals and bearings face replacement mandates under EU F-Gas Regulation phase-down policies. Process equipment retrofits specify filled fluoropolymer seals eliminating fugitive emissions.
Aerospace carries the steepest qualification barriers. Chemical processing offers the broadest volume base.
End User:
End user segmentation aligns with capital expenditure cycles and regulatory inspection intensity across industrial sectors.
- Manufacturing:Process industry maintenance budgets drive recurring demand for PTFE bearings and seals. German automotive and chemical OEMs consolidate vendor relationships around single-source qualifications.
- Electronics:Semiconductor fabrication expansion in Japan and South Korea concentrates demand for high-purity PFA compounds. Cleanroom equipment specifications exceed standard purity grades.
- Energy:Battery thermal management in electric vehicles creates cross-application demand for carbon-filled heat-dissipating compounds.
- Medical:Sterile processing equipment in India's pharmaceutical manufacturing corridor lags regional output growth, creating specification white space.
Manufacturing absorbs the highest absolute volume. Electronics shows the steepest margin expansion.
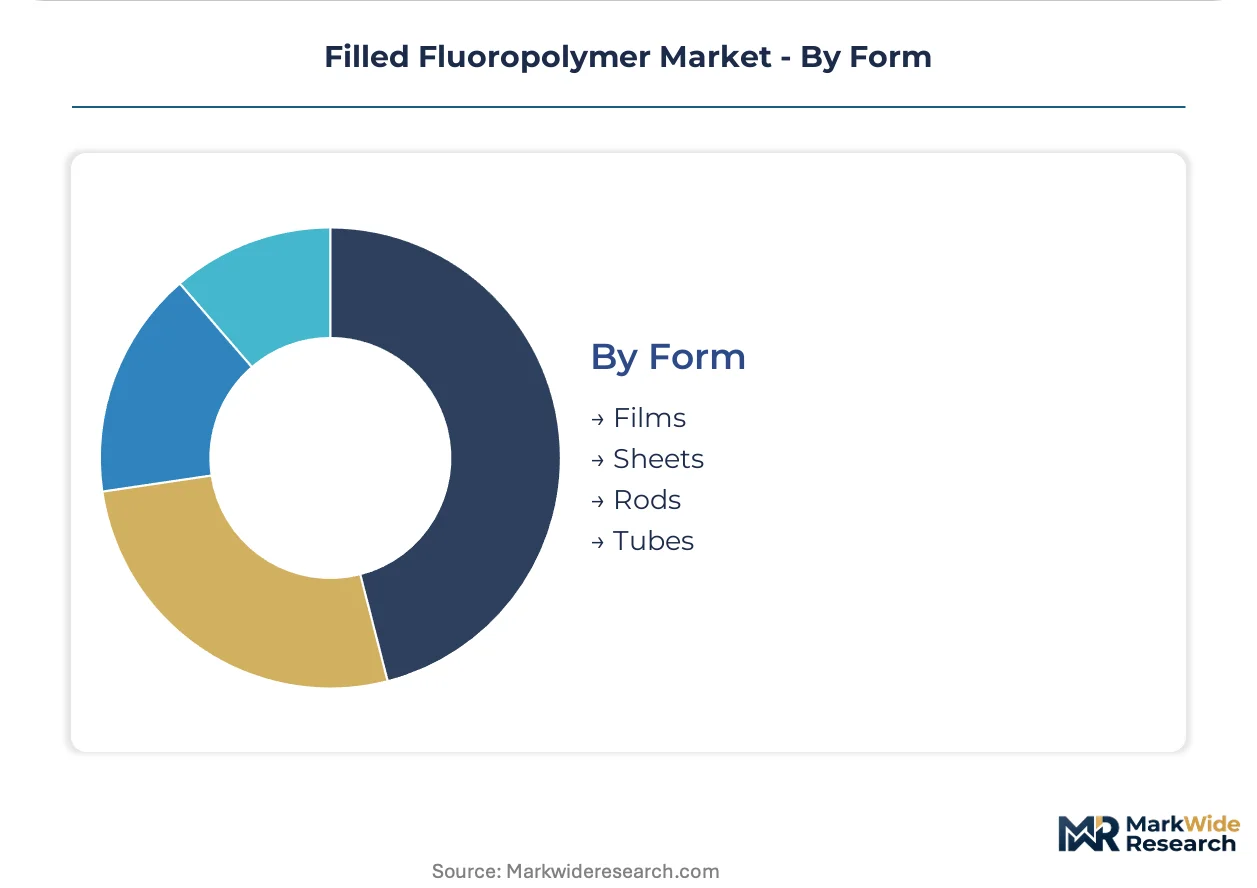
Form:
Form factor determines whether compounders capture value through precision machining services or raw material supply.
- Films:Aerospace and electronics buyers require tight thickness tolerances and lot-to-lot consistency. Above-average margins reflect precision extrusion capabilities.
- Sheets:Chemical lining applications specify compression-molded PTFE sheets for tank and vessel protection. Thickness uniformity drives specification.
- Rods:Machining stock for seals and bearings. Distributor channels dominate rod procurement.
- Tubes:Fluid handling and electrical insulation applications. Extrusion precision separates premium from commodity supply.
Films command the highest unit margins. Rods move through the most fragmented channel structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes filled fluoropolymers primarily for chemical processing seals and automotive transmission components, whereas Japan and South Korea concentrate demand in semiconductor wafer processing equipment. This application-mix differential shapes distinct procurement channels and qualification requirements across major consuming geographies.
Germany
Automotive OEMs in Stuttgart and Munich specify nano-scale ceramic-filled PTFE compounds for extended-service transmission seals. KBA type-approval requirements enforce rigorous material qualification protocols. The industrial corridor spanning North Rhine-Westphalia and Baden-Württemberg consolidates vendor relationships around single-source qualifications for extreme-service components.
United States
EPA oversight of PFAS releases elevates site permitting costs for fluoropolymer compounders serving aerospace and chemical processing end-uses. FAA qualification protocols for filled PFA grades in airframe applications impose 18-36 month certification cycles. Houston's petrochemical cluster drives specification of glass fiber-reinforced PTFE seals for sulfuric acid environments.
Japan
Semiconductor equipment fabricators in Tokyo and Osaka drive qualification programs for high-purity filled PFA grades where weldability exceeds standard PTFE capabilities. METI industrial policy supports precision compounding capabilities for cleanroom component manufacturing. The Chubu region around Nagoya anchors precision machining of fluoropolymer films for electronics applications.
China
GB standards and MEE environmental enforcement raise compliance costs for domestic fluoropolymer production serving process industries. The Yangtze River Delta concentration of chemical processing equipment fabricators specifies filled PTFE bearings for aggressive acid service. Captive fluorspar mining assets concentrate upstream control among integrated producers.
South Korea
Memory and logic chip manufacturers in Gyeonggi Province demand filled PFA compounds for wafer processing equipment with purity requirements exceeding standard grades. MFDS pharmaceutical equipment specifications create secondary demand for sterile processing components. The Busan-Ulsan industrial complex specifies carbon-filled compounds for battery thermal management in electric vehicle production.
Filled Fluoropolymer Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the filled fluoropolymer market. Integrated producers controlling captive fluorspar-to-resin infrastructure capture premium positioning in long-term supply agreements with automotive and chemical OEMs. Specialist compounders compete on precision compounding capabilities for semiconductor and aerospace qualification programs. Dominant competitive moves include backward integration into fluorspar mining assets and geographic expansion of precision compounding facilities to serve Asia-Pacific semiconductor clusters.
Among integrated producers with captive supply chains, The Chemours Company and Daikin Industries occupy positions exemplifying upstream control strategies. Solvay represents the European archetype competing in aerospace qualification programs where filled PFA grades must meet OEM process specifications. Specialist tier presence includes AFT Fluorotec Ltd and HaloPolymer OJSC, which sit within regional compounding expertise concentrations serving process industry equipment fabricators.
| Leading Market Players |
|---|
| The Chemours Company |
| Daikin Industries, Ltd. |
| 3M |
| AGC Inc. |
| Solvay |
| Mitsubishi Chemical Corporation |
| HaloPolymer OJSC |
| AFT Fluorotec Ltd |
| Saint-Gobain Performance Plastics |
| Others |
Supply Flow & Price Mechanics
FAA and EASA qualification protocols gate both supplier entry and price stratification in filled fluoropolymer procurement, compressing margins for uncertified compounders while embedding premium positioning for aerospace-qualified grades. REACH Article 68 compliance costs and fluorspar supply concentration simultaneously reshape sourcing economics and contract structures across chemical processing end-uses.
Pricing Analysis
Long-term offtake agreements dominate filled fluoropolymer procurement, displacing spot transactions as automotive and chemical OEMs consolidate vendor relationships around single-source qualifications. Pricing stratifies across aerospace-certified PFA, industrial-grade PTFE compounds, and commodity rod stock, with differentiation driven by certification tier and captive fluorspar integration. Cost compression in standard PTFE grades intensifies as Chinese integrated producers expand output. Chemical processors show highest price sensitivity; semiconductor equipment fabricators prioritize purity guarantees over unit cost.
Supply Chain Analysis
Fluorspar mining concentration in China and Mexico creates upstream chokepoints that tether global PTFE compound pricing to captive asset control. Base resin production draws from integrated fluorspar-to-resin infrastructure in China, Japan, and the United States, with specialty compounding concentrated in Germany and Japan. Single-source vulnerability runs through Chinese fluorspar export licensing. Distribution runs through direct OEM channels for PFA grades and distributor networks for standard PTFE bearings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic matrix composites threaten filled fluoropolymer dominance in aerospace bearing applications, forcing incumbents to defend specification position through accelerated qualification programs and purity differentiation.
For Market Incumbents: Secure captive fluorspar supply through backward integration or long-term mining agreements to insulate feedstock costs from Chinese export policy shifts. Accelerate PFA qualification timelines with FAA and EASA to outpace ceramic substitution in thermal management applications. Reinforce technical service capabilities in semiconductor clusters to lock in specification stickiness. For New Entrants and Emerging Players: Lead with carbon-filled thermal conductivity compounds targeting electric vehicle battery management in South Korea and semiconductor fabrication tooling in Japan, where cross-application demand creates specification white space. Establish precision compounding partnerships with German automotive Tier 1 suppliers seeking extended-service transmission seal alternatives. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across PFA qualification infrastructure as aerospace OEM certification cycles lengthen. Target acquisition profiles center on Japanese and German specialist compounders with established cleanroom manufacturing capabilities and existing semiconductor equipment fabricator relationships. Monitor ECHA PFAS restriction proposal advancement as signal for reformulation cost inflection across European manufacturing exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Mining | Chemours and Daikin anchor cost position through captive supply of base PTFE feedstock. |
| Precision Compounding Facility Expansion | Specialist compounders in Japan and Germany capture semiconductor equipment fabricator specifications. |
| Aerospace OEM Qualification Acceleration | Filled PFA grades require 18-36 month FAA and EASA certification cycles. |
| Carbon Filler Thermal Conductivity Development | Electric vehicle battery thermal management converges with semiconductor fabrication tooling demand. |
| REACH Compliant Filler Reformulation | European compounders face margin compression from ECHA PFAS restriction documentation requirements. |
Methodological Framework
The analysis maps PTFE compounds, PFA grades, FEP formulations, and ETFE films, each validated through primary interviews with plant managers at chemical processing equipment fabricators, procurement leads at automotive OEMs, technical R&D directors at fluoropolymer compounders, and distribution channel partners serving semiconductor clusters. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of integrated producers, and ECHA regulatory documentation. Bottom-up volume modeling triangulates against top-down value estimates across resin chemistry, filler technology, and form factor segments.
Consistency checks validated volume and value outputs against external benchmarks including trade flow data and regional production capacity disclosures. The forecast framework segments by base resin chemistry, application severity tier, end-use industry, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections and capacity expansion schedules. Key inputs include semiconductor fabrication capital expenditure patterns, automotive transmission seal replacement intervals, and REACH compliance cost assumptions.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor equipment investment, stable fluorspar trade flows, or unaltered PFAS regulatory trajectories would require recalibration. Practitioners should keep alternative scenarios live as ECHA restriction proposals, Chinese environmental enforcement intensity, and ceramic composite substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyethylene Terephthalate (PET) Compounding Market
Polymers & Resins
Resin Cement for Luting Market
Polymers & Resins
Molding and Trim Materials Market
Polymers & Resins
Semi-Crystalline Polymers Market
Polymers & Resins
Cast Polymers Market
Polymers & Resins
Asia-Pacific Flooring Resins Market
Polymers & Resins
Polylysine Market
Polymers & Resins
Flexible Polymer Foam Market
Polymers & Resins
North America Thermoplastics Market
Polymers & Resins
Bio-Based Emulsion Polymers Market
Polymers & Resins
Polymer Filler Market
Polymers & Resins
Solid State Resins Market
Polymers & Resins
Polycyclohexylenedimethylene Terephthalate (PCT) Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Market
Polymers & Resins
Sodium Polyacrylate Market
Polymers & Resins
US Acrylic Solid Surface Market