
 Medical Grade Liquid Crystal Polymer Market | 2026-2036
Medical Grade Liquid Crystal Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Grade Liquid Crystal Polymer Market Intelligence
REACH compliance in Europe is decoupling small compounders from the medical LCP supply base by imposing substance-of-very-high-concern testing burdens that only scaled producers absorb. Celanese Corporation leverages its captive Vectra resin technology to sustain cost leadership across implant-grade formulations. Solvay S.A. anchors its position through fluoropolymer-LCP hybrid expertise in diagnostic housing applications. Polyplastics Co., Ltd. dominates Asian supply chains with integrated polymerization-to-compounding operations in Fujisawa.
Medical grade liquid crystal polymer is a high-performance aromatic polyester characterized by rigid rod-like mesogenic units, melt temperatures between 280°C and 350°C, and tensile strengths exceeding 150 MPa in flow direction, engineered for precision-molded components requiring dimensional stability in sterilization cycles. Thermoplastics capture the dominant value pool due to established injection molding infrastructure, while reinforced composites command premium positioning in orthopedic implant load-bearing elements. 3D printing filaments represent the fastest-expanding technology segment as OEMs prototype patient-specific surgical guides without tooling investment.
FDA 21 CFR Part 177 indirect food additive regulations, EU MDR Class III device requirements, and Japan's PMDA ministerial ordinances on polymer biocompatibility collectively elevate testing documentation thresholds for market entry. ISO 10993 cytotoxicity and sensitization protocols now function as de facto filters excluding uncertified resin suppliers from hospital procurement networks. Stakeholders must track evolving EPA per- and polyfluoroalkyl substance restrictions, as fluorinated process aids in LCP synthesis face prospective phase-out timelines that would force reformulation investments across the value chain.
Market Dynamics
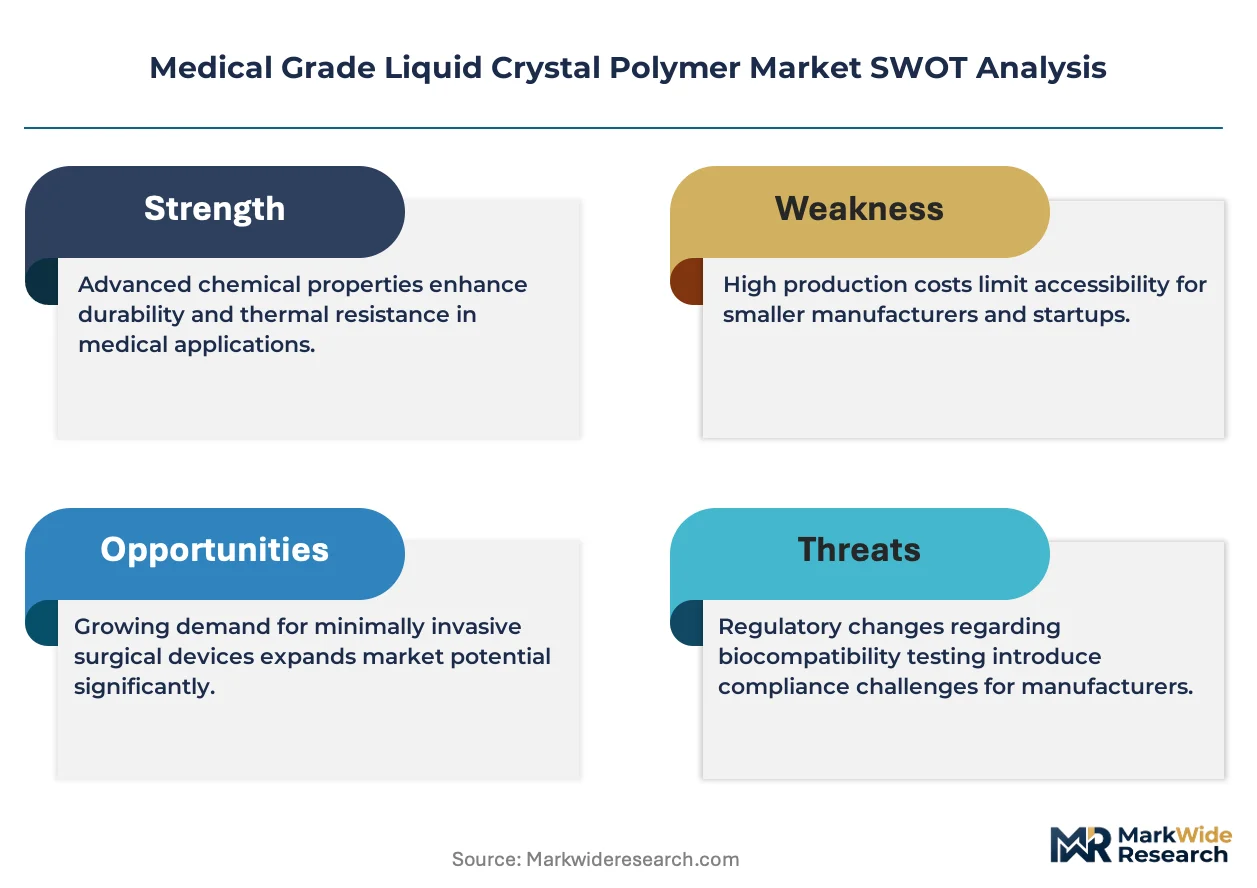
FDA biocompatibility standard tightening and Japan's PMDA acceleration of novel polymer approvals are compressing supplier qualification timelines while concentrating procurement among scaled compounders with captive resin technology.
Growth Catalysts
- Minimally invasive surgical instrument demand:OEMs in Germany's Stuttgart-Freiburg precision medical cluster source high-purity LCP grades for catheter and endoscope components requiring sterilization-cycle dimensional stability.
- EU MDR Class III device requirements:Elevated testing documentation thresholds filter uncertified resin suppliers from hospital procurement networks, advantaging ISO 10993-cytotoxicity-certified producers.
- 3D printing filament adoption:Patient-specific surgical guide prototyping without tooling investment accelerates filament demand from orthopedic device manufacturers seeking design-cycle compression.
Market Restraints
- REACH SVHC testing burdens:European substance-of-very-high-concern compliance costs decouple small compounders from the medical LCP supply base, reducing qualified supplier pools.
- Fluorinated process aid dependency:Prospective EPA per- and polyfluoroalkyl substance phase-out timelines threaten forced reformulation investments across LCP synthesis operations.
- Polymerization-to-compounding capital intensity:Integrated manufacturing infrastructure requirements exceed mid-tier processor balance sheet capacity, constraining new market entry.
Strategic Opportunities
- Implantable load-bearing composite expansion:Reinforced LCP formulations command premium positioning in orthopedic implant segments requiring flow-direction tensile strength exceeding 150 MPa.
- Diagnostic housing fluoropolymer-LCP hybridization:Solvay S.A.'s anchored expertise creates white space for radiation-transparent enclosure applications in imaging equipment.
- Asian supply chain integration:Polyplastics Co., Ltd.'s Fujisawa operations demonstrate backward integration models transferable to emerging medical device manufacturing clusters in South Korea.
Industry Challenges
- ISO 10993 certification timeline compression:Cytotoxicity and sensitization protocol documentation requirements extend new grade qualification cycles beyond OEM product development windows.
- Melt temperature processing expertise scarcity:Injection molding infrastructure for 280°C-350°C aromatic polyester flow regimes concentrates among specialized medical thermoplastics processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Grade Liquid Crystal Polymer Market |
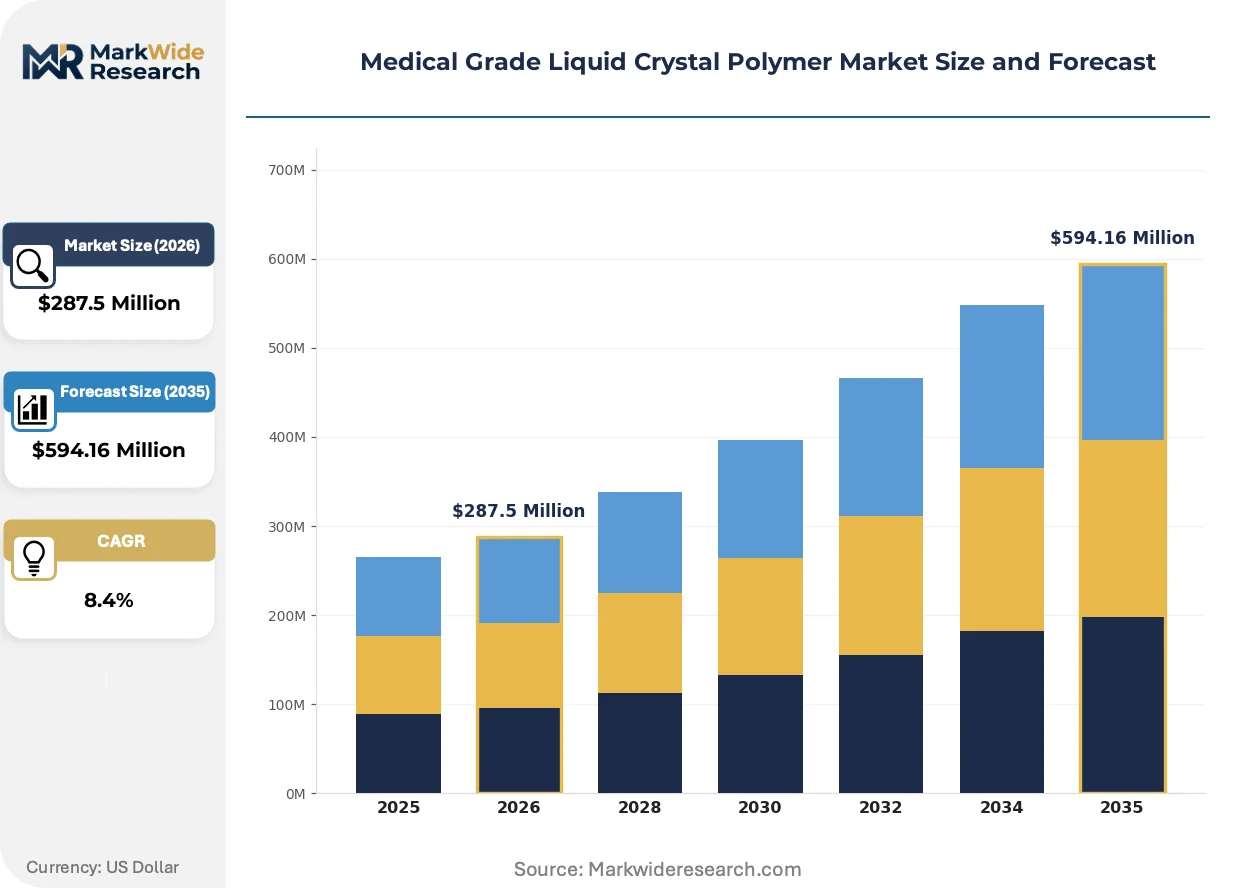
| Market Size in 2026 | $287.5 Million |
| Market Size in 2035 | $594.16 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastics, Reinforced Composites, Alloys, Blends Application: Medical Devices, Surgical Instruments, Implants, Diagnostic Equipment End User: Hospitals, Clinics, OEMs, Research Laboratories Technology: Injection Molding, 3D Printing, Extrusion, Coating |
| Companies Covered | Toray International, Ueno Fine Chemicals Industry Ltd, Polyplastics Co., Ltd., Samsung Fine Chemicals, Shanghai PRET Composites, Co. Ltd., Celanese Corporation, Solvay S.A., RTP Company, Sumitomo Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Grade Liquid Crystal Polymer Market Strategic Shifts & Innovations
Medical grade liquid crystal polymer markets are experiencing active restructuring around additive manufacturing qualification, regulatory documentation automation, and sterilization-cycle performance verification protocols.
Reinforced LCP composites engineered for orthopedic implant load-bearing elements are expanding into trauma fixation and spinal fusion applications previously dominated by titanium and PEEK. Trauma device OEMs in Switzerland and Germany pilot hybrid metal-polymer constructs leveraging LCP's anisotropic strength-to-weight ratios. This expansion is compressing traditional metal machining value capture in mid-tier implant portfolios.
Japan's PMDA ministerial ordinances on polymer biocompatibility now mandate real-time adverse event reporting linkages for implantable LCP-containing devices. Device sponsors must demonstrate supply chain traceability to resin batch polymerization records. Diagnostic housing manufacturers face accelerated MDR-equivalent technical documentation requirements that favor pre-qualified Asian compounders with established PMDA master file submissions.
Hospital procurement networks increasingly specify ISO 10993-certified resin grades in single-source contracts with polymerization-to-compounding integrated suppliers. Group purchasing organizations in the US consolidate vendor panels around FDA 21 CFR Part 177 indirect food additive compliance documentation completeness. Switzerland's university hospital clusters pioneer blockchain-anchored batch certification verification, reducing incoming quality assurance testing overhead for catheter component assemblers.
Medical Grade Liquid Crystal Polymer Market Segmentation
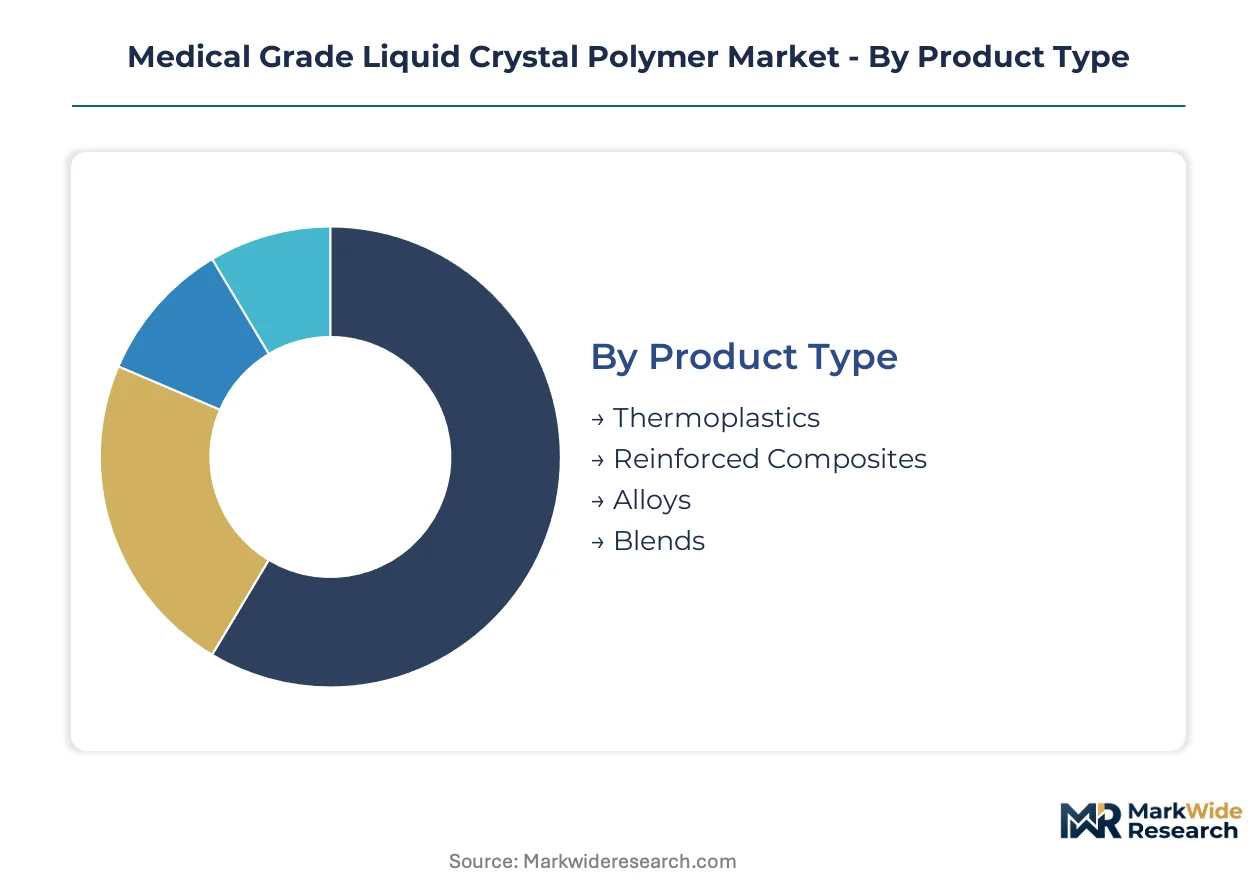
Medical grade LCP procurement decisions pivot on sterilization-cycle performance, regulatory documentation depth, and manufacturing process compatibility. Segmentation reveals how material form, clinical application, and fabrication technology intersect to determine supplier qualification and pricing power.
Product Type:
Buyers prioritize melt-processability against dimensional stability requirements when selecting among LCP material forms.
- Thermoplastics:Aromatic polyester formulations with melt temperatures between 280°C and 350°C dominate catheter and endoscope component manufacturing. Germany's Stuttgart-Freiburg precision medical cluster sources these grades for multi-cycle autoclave resistance.
- Reinforced Composites:Flow-direction tensile strength exceeding 150 MPa positions these formulations in orthopedic implant load-bearing elements. Trauma device OEMs in Switzerland pilot hybrid constructs leveraging anisotropic strength-to-weight ratios against titanium alternatives.
- Alloys:Hybrid polymer systems combining LCP with fluoropolymer or PEEK matrices for diagnostic housing radiation transparency.
- Blends:Cost-optimized formulations incorporating mineral fillers for non-implantable surgical instrument handles.
Thermoplastics lead on scale; reinforced composites lead on momentum.
Application:
Clinical use environment dictates biocompatibility certification tier and sterilization protocol compatibility.
- Medical Devices:Catheters, drug delivery systems, and minimally invasive instruments requiring ISO 10993 cytotoxicity certification. FDA 21 CFR Part 177 compliance anchors procurement specifications for US hospital networks.
- Surgical Instruments:Precision-molded graspers, retractors, and trocar components. Japan's PMDA ministerial ordinances now mandate real-time adverse event reporting linkages for implantable LCP-containing devices in this category.
- Implants:Spinal fusion cages and trauma fixation plates. EU MDR Class III device requirements filter uncertified resin suppliers through elevated testing documentation thresholds.
- Diagnostic Equipment:Imaging system housings and laboratory consumables. Solvay S.A.'s fluoropolymer-LCP hybrid expertise anchors radiation-transparent enclosure applications.
Medical devices lead on scale; implants lead on momentum.
End User:
Procurement authority and volume concentration vary sharply across buyer types, with direct manufacturer relationships commanding preferential pricing.
- OEMs:Original equipment manufacturers in Germany, Switzerland, and Japan consolidate volume through single-source contracts with polymerization-to-compounding integrated suppliers.
- Hospitals:US group purchasing organizations consolidate vendor panels around FDA compliance documentation completeness.
- Clinics:Smaller-volume buyers dependent on distributor intermediaries with limited formulation customization access.
- Research Laboratories:Prototype and preclinical testing demand for 3D printing filaments and small-batch custom compounds.
OEMs lead on scale; research laboratories lead on momentum.
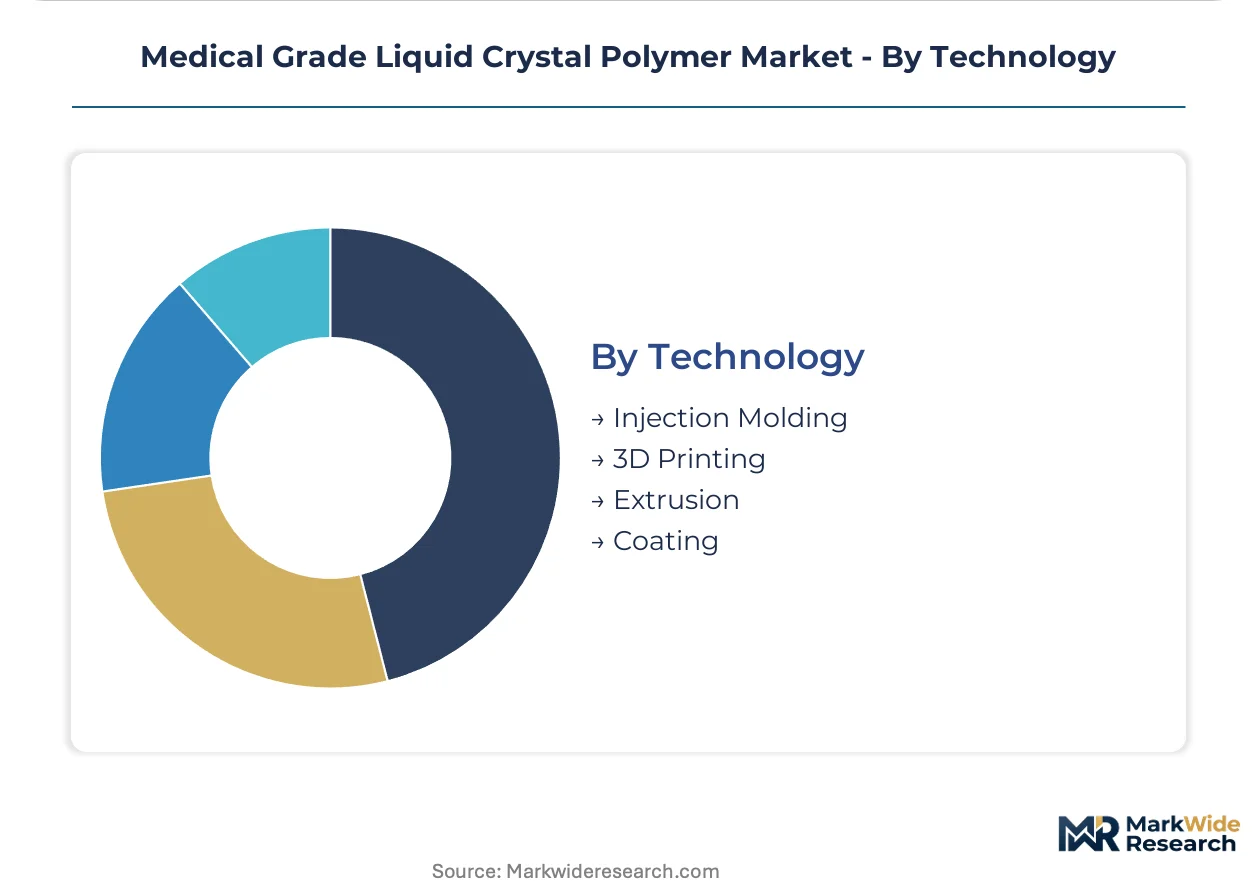
Technology:
Processing temperature regimes and tooling investment requirements segment manufacturing capability among converters.
- Injection Molding:Established infrastructure for 280°C-350°C aromatic polyester flow regimes concentrates among specialized medical thermoplastics processors in Germany and Japan.
- 3D Printing:Filament-based additive manufacturing enables patient-specific surgical guide prototyping without tooling investment. Orthopedic device manufacturers seeking design-cycle compression drive steepest expansion trajectory in this segment.
- Extrusion:Continuous profile production for catheter shafts and multi-lumen tubing with tight tolerances.
- Coating:Thin-film deposition for metallic implant surface modification and drug-eluting applications.
Injection molding leads on scale; 3D printing leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical grade liquid crystal polymer commercialization traces its industrial lineage to Japan's precision polymerization advances in the 1980s, subsequently scaling through German precision medical device clusters and US regulatory-driven implant material adoption. Contemporary procurement patterns reflect this tripartite foundation, with manufacturing concentration and regulatory stringency varying sharply across national boundaries.
United States
FDA 21 CFR Part 177 indirect food additive regulations anchor hospital procurement specifications, with group purchasing organizations consolidating vendor panels around compliance documentation completeness. EPA per- and polyfluoroalkyl substance restrictions threaten fluorinated process aid dependencies in LCP synthesis, forcing prospective reformulation investments. Minnesota and Massachusetts host specialized medical thermoplastics processors serving catheter OEMs.
Germany
EU MDR Class III device requirements filter uncertified resin suppliers through elevated ISO 10993 cytotoxicity testing documentation thresholds. REACH substance-of-very-high-concern compliance costs decouple small compounders from supply bases, advantaging scaled producers. The Stuttgart-Freiburg precision medical cluster sources high-purity grades for endoscope components requiring autoclave-cycle dimensional stability.
Japan
PMDA ministerial ordinances on polymer biocompatibility mandate real-time adverse event reporting linkages for implantable LCP-containing devices. METI industrial policy supports novel polymer approval acceleration, compressing supplier qualification timelines. Fujisawa operations demonstrate integrated polymerization-to-compounding models transferable to emerging medical device manufacturing clusters.
China
NMPA biocompatibility standards for implantable devices tighten import resin documentation requirements, favoring domestic compounders with established master file submissions. MIIT industrial upgrading programs target high-performance aromatic polyester self-sufficiency. Yangtze River Delta medical device manufacturing clusters expand LCP procurement for minimally invasive surgical instruments.
Switzerland
Swissmedic device authorization requirements align with EU MDR technical documentation depth, creating parallel compliance burdens for trauma fixation plate manufacturers. University hospital clusters pioneer blockchain-anchored batch certification verification, reducing incoming quality assurance testing overhead. Zurich and Basel anchor hybrid metal-polymer construct development for orthopedic applications.
Medical Grade Liquid Crystal Polymer Market Key Industry Players
The competitive structure tilts toward polymerization-to-compounding integrated specialists with captive resin technology and ISO 10993 certification depth. Tiered positioning separates scaled aromatic polyester producers from regional compounders dependent on merchant resin supply. Three archetypes dominate: integrated resin-to-compound manufacturers, fluoropolymer hybrid specialists, and precision medical thermoplastics processors. Capacity expansion and regulatory documentation automation constitute the dominant competitive moves, with M&A activity targeting certified compounders in Germany and Japan.
Within the integrated manufacturing tier, Celanese Corporation and Polyplastics Co., Ltd. exemplify archetypes of backward-controlled supply chains. Solvay S.A. occupies a hybrid-specialist position bridging fluoropolymer expertise with medical-grade aromatic polyester applications. These three entities represent distinct strategic postures—North American scale integration, Asian vertical coordination, and European materials science hybridization—without implying specific market share positions or recent transactional activity.
| Leading Market Players |
|---|
| Toray International |
| Ueno Fine Chemicals Industry Ltd |
| Polyplastics Co., Ltd. |
| Samsung Fine Chemicals |
| Shanghai PRET Composites, Co. Ltd. |
| Celanese Corporation |
| Solvay S.A. |
| RTP Company |
| Sumitomo Chemical |
| Others |
Cost & Logistics Intelligence
Captive polymerization-to-compounding operations in Japan and Germany anchor supply positions while simultaneously determining pricing power through ISO 10993 certification depth and REACH compliance cost absorption. Buyers face stark trade-offs between high-purity implant-grade premiums and standard catheter-grade availability as regulatory documentation thresholds filter supplier pools.
Pricing Analysis
Bundled regulatory documentation and certification services separate premium-tier suppliers from unbundled resin-only vendors serving price-sensitive instrument handle manufacturers. Price differentiation hinges on FDA 21 CFR Part 177 compliance completeness and EU MDR Class III device testing depth. Cost compression in standard thermoplastic grades intensifies as REACH SVHC testing burdens force small compounders out of qualified supplier pools. Research laboratories and clinics exhibit highest price sensitivity due to limited volume and distributor markup exposure, while OEMs in Germany's Stuttgart-Freiburg cluster accept premium positioning for sterilization-cycle dimensional stability guarantees.
Supply Chain Analysis
Dual-sourcing requirements from US hospital group purchasing organizations and Japanese trauma device OEMs mandate multi-supplier qualification across Celanese, Polyplastics, and Solvay networks. Geographic supply concentrates in Japan, Germany, and the United States, with Fujisawa and Stuttgart-Freiburg anchoring polymerization capacity. Raw material dependencies include aromatic monomers, fluorinated process aids, and high-purity catalyst systems. Single-source vulnerability looms as EPA per- and polyfluoroalkyl substance restrictions threaten forced reformulation timelines. Distribution runs through polymerization-to-compounding integrated suppliers for OEM direct contracts, with regional distributors serving clinic and laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between Japan's accelerated PMDA approval pathways and Europe's REACH compliance cost burdens, with cost differentials favoring Asian supply base expansion for implant-grade formulations.
For Market Incumbents: Deploy certification automation to compress ISO 10993 documentation timelines as emerging 3D printing filament specialists threaten traditional injection molding value capture. Defend catheter and endoscope component positions through backward integration into high-purity monomer supply. Accelerate PMDA master file submission depth to preempt Asian compounder qualification advantages. For New Entrants and Emerging Players: Direct-to-clinic filament distribution routes bypass established OEM procurement networks and unlock research laboratory demand for patient-specific surgical guide prototyping. Target South Korean medical device manufacturing clusters with transferable Fujisawa-style integration models. Penetrate diagnostic housing segments through fluoropolymer-LCP hybrid expertise gaps left by Solvay's anchored positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH SVHC testing burdens exceed mid-tier processor balance sheet capacity, creating acquisition opportunities for ISO 10993-certified German compounders. Long-term viability favors polymerization-to-compounding integrated specialists with captive resin technology over merchant resin-dependent regional processors. Watch EPA per- and polyfluoroalkyl substance phase-out announcements as inflection indicators for forced reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Documentation Automation | Compresses ISO 10993 qualification cycles to match OEM product development windows. |
| Backward Integration into Monomer Supply | Secures high-purity aromatic polyester feedstock against REACH SVHC disruption. |
| PMDA Master File Expansion | Accelerates novel polymer approval timelines for implantable device applications. |
| 3D Printing Filament Qualification | Captures fastest-expanding technology segment in patient-specific surgical guides. |
| Fluoropolymer-LCP Hybrid Development | Addresses radiation-transparent diagnostic housing demand in imaging equipment. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymerization plant managers, medical device OEM procurement leads, hospital GPO contracts managers, and regulatory affairs directors with secondary validation through FDA 510(k) filings, PMDA approval databases, EU MDR technical documentation repositories, and customs trade records. Bottom-up resin volume estimates and top-down medical device production forecasts were triangulated against catheter, endoscope, and orthopedic implant shipment data.
Segment-weighting approaches applied differential growth assumptions across thermoplastics, reinforced composites, and 3D printing filament technologies, with injection molding and additive manufacturing process compatibility modeled separately. CAGRs were derived from sterilization-cycle performance verification trends and minimally invasive surgical instrument adoption curves across Germany, Japan, and the United States. Forecast inputs included PMDA approval velocity indices and REACH SVHC testing cost trajectories.
The model assumes a particular technology adoption path; alternative pathways for additive manufacturing qualification would alter the outlook if filament-based prototyping displaces traditional injection molding faster than projected. Deviation in EPA per- and polyfluoroalkyl substance phase-out timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Renewable PVDF Market
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
Europe Chromatography Resins Market
Polymers & Resins
Antiviral Polymers for Packaging Market
Polymers & Resins
Thailand Plastics Market
Polymers & Resins
Conditioning Polymers Market
Polymers & Resins
Global Resin Market
Polymers & Resins
Water Dispersible Polymers Market
Polymers & Resins
Indonesia Flooring Resins Market
Polymers & Resins
Global Corrosion Resistant Resin Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Polysorbate Market
Polymers & Resins
Saturated Polyester Resin Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
India Automotive Thermoplastic Polymer Composites Market