
 Ballistic Protection Materials Market | 2026-2036
Ballistic Protection Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Ballistic Protection Materials Market Analysis
Law enforcement procurement is decoupling from traditional military-driven volume as municipal agencies upgrade officer protection independently. Honeywell International Inc. leverages its Spectra fiber vertical integration to anchor North American supply security. DuPont de Nemours Inc. sustains Kevlar brand dominance through decades of certified body armor deployments. Rheinmetall AG dominates European hard armor plate production with captive metallurgical expertise.
Ballistic protection materials are engineered fiber composites and ceramic-metal systems designed to absorb and dissipate kinetic energy from projectile impact, typically rated against NIJ Level II through IV threats or equivalent STANAG standards. These materials serve the essential commercial purpose of preserving human survivability in armed engagement scenarios across military, security, and select civilian applications. Plates and fabrics represent the core product form categories, with plates capturing premium margin pools due to ceramic processing complexity while fabrics sustain higher unit volumes in vest and helmet applications. The military application segment leads absolute demand, though private security end users are expanding fastest as corporate executive protection details proliferate across emerging market capitals.
NIJ certification protocols in the United States, STANAG 4569 testing frameworks across NATO, and Germany's KBA-equivalent national procurement standards collectively dictate product eligibility for institutional contracts, creating structural barriers for uncertified suppliers. The EU Green Deal's emerging requirements for sustainable material sourcing are beginning to constrain aramid fiber supply chains, favoring manufacturers with recycled content capabilities. Stakeholders must monitor pending revisions to NIJ Standard-0101.07 and position polymer-ceramic hybrid investments ahead of anticipated weight-reduction mandates.
Market Dynamics
NIJ standard revisions in the United States are compressing certification cycles and forcing manufacturers to accelerate next-generation armor development ahead of weight-reduction mandates. This regulatory pressure is reshaping R&D allocation across fiber composite and ceramic-metal system producers.
Growth Catalysts
- Bundeswehr modernization:German defense procurement is expanding personal protection system orders through Rheinmetall's domestic supply chain integration, creating anchor demand for hard armor plates.
- NIJ Standard-0101.07:Pending revisions to United States body armor certification protocols are accelerating replacement cycles for municipal law enforcement agencies upgrading officer protection independently.
- Polymer-ceramic hybrids:Advanced fiber-matrix combinations are enabling Level IV threat protection at reduced areal density, opening new helmet and vehicle armor applications.
Market Restraints
- Aramid fiber supply constraints:EU Green Deal sustainable sourcing requirements are limiting recycled content availability and constraining traditional para-aramid production pathways.
- Ceramic processing concentration:Boron carbide and silicon carbide plate manufacturing remains concentrated among limited metallurgical specialists, creating single-source vulnerability for hard armor integrators.
- STANAG 4569 testing backlog:NATO qualification framework capacity limitations are extending institutional contract eligibility timelines for new market entrants.
Strategic Opportunities
- Private security expansion:Corporate executive protection details across emerging market capitals are creating fastest-growing demand for concealable soft armor systems.
- EU Green Deal compliance:Sustainable material sourcing mandates favor manufacturers with closed-loop aramid recycling capabilities and bio-based fiber alternatives.
- Helmet-visor integration:Converging advances in transparent armor ceramics and heads-up display electronics are enabling next-generation soldier system platforms.
Industry Challenges
- Ballistic metallurgist scarcity:Ceramic sintering expertise and composite layup engineering talent pools are insufficient to match accelerated certification timelines.
- Multi-standard compliance:Simultaneous NIJ, STANAG 4569, and KBA-equivalent testing requirements fragment R&D resources and extend product development cycles.
- Legacy vest retrofit complexity:Modular plate carrier systems face integration friction with existing municipal agency equipment inventories and training protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ballistic Protection Materials Market |
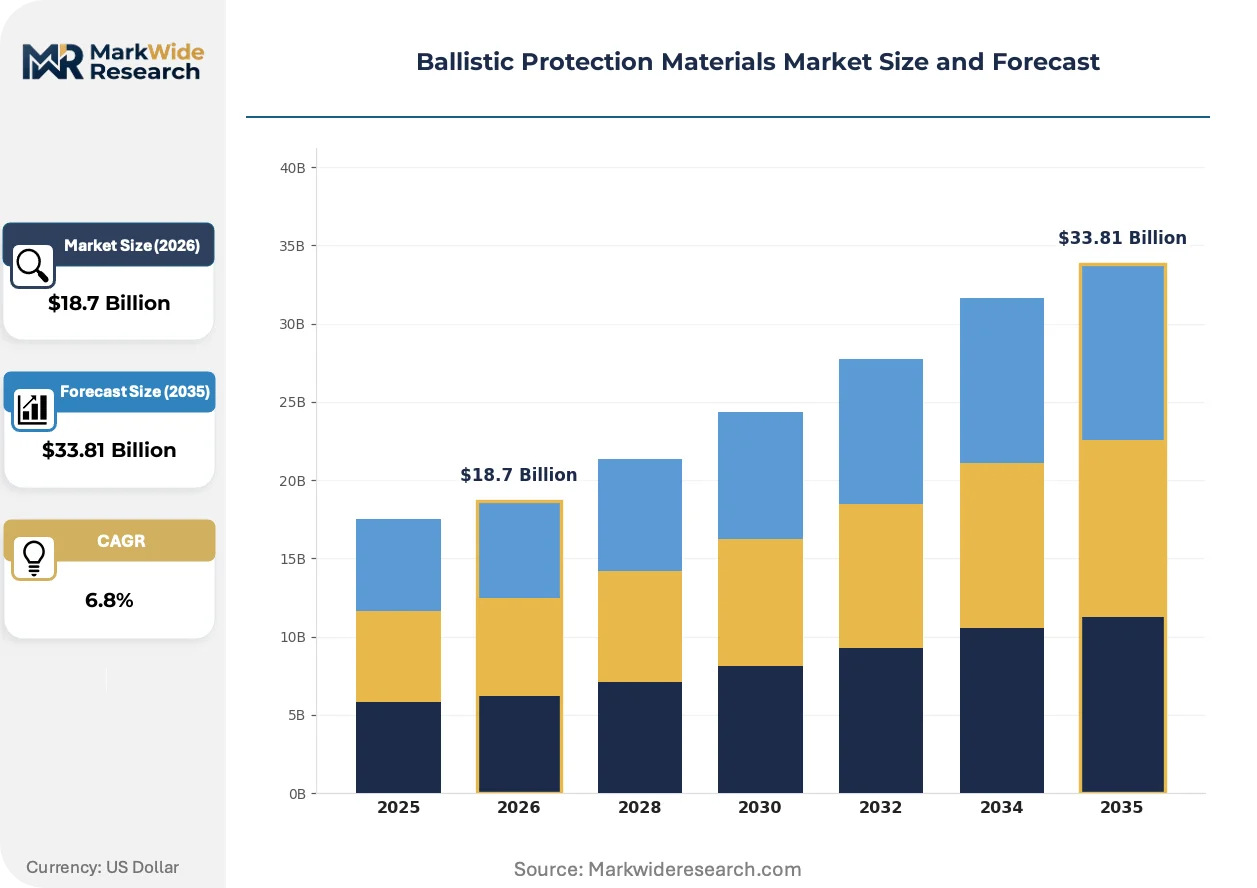
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Kevlar, Twaron, Dyneema, Spectra Product Form: Fabrics, Plates, Helmets, Vests Application: Military, Law Enforcement, Civilian, Security End User: Government, Private Security, Defense Contractors, Manufacturers |
| Companies Covered | Honeywell International Inc., Rheinmetall AG, DuPont de Nemours Inc., TenCate Advanced Armor, Morgan Advanced Materials plc, Teijin Limited, BAE Systems plc, Avon Protection plc, Avient Protective Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ballistic Protection Materials Market Emerging Trajectories
Material science advances and procurement decentralization are simultaneously enabling lighter protection systems and fragmenting traditional military-centric demand patterns. Three developments warrant particular attention.
Ultra-high-molecular-weight polyethylene fiber systems are consolidating market share in soft armor applications previously dominated by aramid composites. Municipal law enforcement agencies in the United States are adopting Spectra and Dyneema-based vests for their superior strength-to-weight ratios and moisture resistance. This transition is consolidating procurement decisions around fiber vertical integration capabilities rather than brand heritage.
REACH regulation amendments and EU Green Deal implementation are imposing mandatory recycled content thresholds on aramid fiber supply chains. European manufacturers must now document circular material flows or face exclusion from institutional contracts. Germany's KBA-equivalent procurement standards are most affected, with domestic integrators accelerating partnerships with fiber recyclers.
Law enforcement agencies are unbundling body armor procurement from federal grant cycles and establishing independent municipal replacement schedules. This decoupling from military-driven volume is fragmenting demand across thousands of small-batch orders. The United States exhibits this pattern most acutely, with city-level police departments negotiating direct manufacturer relationships.
Ballistic Protection Materials Market Segmentation
Ballistic protection procurement splits sharply between volume-driven soft armor programs and premium hard plate systems. Segmentation clarity reveals where margin pools concentrate versus where unit scale accumulates across defense, security, and institutional buyers.
Material Type:
Aramid fibers dominate unit volume while ultra-high-molecular-weight polyethylene fibers capture premium expansion trajectories.
- Kevlar:Para-aramid fiber composite with established NIJ certification heritage and decades of field deployment data. Municipal law enforcement agencies in the United States sustain bulk procurement through federal grant programs, though EU Green Deal recycled content thresholds now constrain virgin fiber availability.
- Dyneema:Ultra-high-molecular-weight polyethylene filament delivering superior strength-to-weight ratios and moisture immunity compared to aramid alternatives. German Bundeswehr modernization programs are accelerating helmet and soft armor adoption, displacing legacy materials in next-generation soldier systems.
- Twaron:Alternative para-aramid formulation with comparable ballistic performance to dominant brands but constrained by smaller production scale and limited vertical fiber control.
- Spectra:Honeywell's proprietary polyethylene fiber system anchoring North American supply security through captive polymerization and gel-spinning operations.
Today's leader: Kevlar. Tomorrow's challenger: Dyneema.
Product Form:
Plates command margin concentration while fabrics sustain replacement cycle volumes across institutional buyers.
- Plates:Ceramic-metal composite systems engineered for Level III and IV threat protection through boron carbide or silicon carbide facing bonded to aramid or polyethylene backings. Rheinmetall's captive metallurgical expertise in Germany anchors European hard armor production, with single-source vulnerability persisting for boron carbide sintering capacity.
- Fabrics:Woven and unidirectional fiber textiles forming soft armor panels rated for Level II and IIIA handgun threats. United States municipal agencies are decoupling procurement from military volume cycles, establishing independent replacement schedules that fragment demand into thousands of small-batch orders.
- Helmets:Molded composite shells integrating ballistic fiber layers with suspension systems, experiencing accelerated upgrade cycles from polymer-ceramic hybrid advances enabling weight reduction.
- Vests:Integrated garment systems combining soft armor panels with plate carriers, facing retrofit complexity with legacy equipment inventories across municipal law enforcement agencies.
Margin pools center on plates. Volume velocity concentrates in fabrics.
Application:
Military procurement anchors absolute demand while private security applications expand most quickly across emerging market capitals.
- Military:Soldier modernization programs driving integrated head-torso-limb protection systems with STANAG 4569 qualification requirements. NATO member states are expanding personal protection system orders through defense procurement budget growth.
- Security:Corporate executive protection details and high-net-worth individual services creating fastest-growing demand for concealable soft armor systems in emerging market capitals.
- Law Enforcement:Municipal agency procurement upgrading officer protection independently from federal military cycles, with NIJ Standard-0101.07 revisions accelerating replacement timelines.
- Civilian:Limited but regulated demand from hunting, shooting sports, and occupational hazard protection, constrained by legal restrictions in multiple jurisdictions.
Institutional buyers dominate current procurement. Private security represents the steepest expansion trajectory.
End User:
Government contracts provide volume stability while defense contractors concentrate technology development investment.
- Government:National defense ministries and interior security agencies issuing multi-year framework agreements with certified suppliers, creating structural barriers for uncertified market entrants.
- Defense Contractors:Systems integrators consolidating subsystem procurement for vehicle, aircraft, and naval platform armor, demanding STANAG 4569 and KBA-equivalent multi-standard compliance.
- Private Security:Corporate protection services and executive detail providers sourcing concealable systems through direct manufacturer relationships outside traditional distribution channels.
- Manufacturers:Tier suppliers of protective equipment and vehicle armor subsystems, dependent on certified material flows from fiber and ceramic specialists.
Procurement authority concentrates with government. Technology development investment clusters with defense contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rheinmetall's captive metallurgical complex in Unterlüß anchors European hard armor plate production. NATO defense procurement expansion and NIJ certification acceleration are redrawing material flow patterns across three continents.
United States
Municipal law enforcement agencies are decoupling body armor procurement from federal military cycles, establishing independent replacement schedules. NIJ Standard-0101.07 revisions are compressing certification timelines for fiber composite suppliers. Honeywell's Spectra fiber operations in Virginia anchor North American supply security through captive polymerization capacity.
Germany
Bundeswehr modernization programs are expanding personal protection system orders through domestic supply chain integration. KBA-equivalent procurement standards enforce multi-tier testing requirements for vehicle and soldier armor. Rheinmetall's metallurgical expertise in Lower Saxony dominates boron carbide plate sintering for STANAG 4569-qualified systems.
United Kingdom
Defense procurement prioritizes STANAG 4569-compliant vehicle armor for NATO interoperability commitments. BAE Systems' platform integration contracts concentrate demand for certified ceramic-metal composite subsystems. The Midlands industrial corridor hosts specialized ballistic testing facilities serving continental European qualification requirements.
China
MIIT standards for protective equipment are converging toward NATO-equivalent performance benchmarks for export-oriented manufacturers. Domestic security agency procurement sustains volume demand for aramid and polyethylene fiber vests. Yangtze River Delta chemical clusters are scaling boron carbide powder production for regional hard armor integrators.
Israel
Defense export regulations channel advanced ceramic armor technologies toward NATO-aligned certification pathways. Domestic military procurement drives integrated head-torso protection system development. Tel Aviv-area R&D clusters specialize in polymer-ceramic hybrid formulations for weight-reduced helmet applications.
Ballistic Protection Materials Market Vendor Landscape
Capacity expansion dominates the current landscape as fiber specialists and ceramic metallurgists race to meet compressed NIJ and STANAG certification deadlines. The vendor base splits between integrated fiber-to-fabric producers and specialized hard armor plate fabricators. Three archetypes define competitive positioning: polyethylene fiber vertical integrators, captive ceramic sintering specialists, and multi-material systems integrators. Strategic partnerships and backward integration into raw material supply are the dominant competitive moves reshaping procurement relationships.
Among North American fiber specialists, Honeywell International Inc. and DuPont de Nemours Inc. occupy positions reflecting decades of certified body armor deployment heritage. Rheinmetall AG exemplifies the European captive metallurgy archetype, with its German corporate structure indicating integrated hard armor production capabilities. These three entities represent distinct strategic postures: polyethylene fiber supply security, para-aramid brand dominance, and ceramic-metal systems integration.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Rheinmetall AG |
| DuPont de Nemours Inc. |
| TenCate Advanced Armor |
| Morgan Advanced Materials plc |
| Teijin Limited |
| BAE Systems plc |
| Avon Protection plc |
| Avient Protective Materials |
| Others |
Supply Flow & Price Mechanics
NIJ Standard-0101.07 revision timelines are compressing municipal procurement cycles and forcing fiber suppliers to absorb certification retesting costs while maintaining spot pricing for law enforcement buyers. This demand-side acceleration fragments volume commitments and transfers specification risk upstream to composite weavers and ceramic sintering houses.
Pricing Analysis
Input-cost pass-through from boron carbide powder and para-aramid fiber feeds directly into hard armor plate quotations, with ceramic-metal systems commanding contract-based long-term offtake structures. Price differentiation separates STANAG 4569-certified systems from NIJ-only equivalents, with brand premium attaching to decades of field deployment data. Cost compression in soft armor fabrics is intensifying because municipal agencies are unbundling from federal volume programs and negotiating small-batch orders. Private security buyers exhibit highest price sensitivity due to direct manufacturer relationships, while defense contractors show lowest sensitivity given platform integration requirements.
Supply Chain Analysis
Freight cost volatility for boron carbide powder shipments from Yangtze River Delta chemical clusters to European sintering facilities is amplifying working capital requirements for hard armor integrators. Geographic supply concentration centers on Germany for ceramic plate metallurgy, the United States for polyethylene fiber polymerization, and China for raw boron carbide feedstock. Raw material dependencies rest on para-aramid filament, ultra-high-molecular-weight polyethylene resin, and silicon carbide precursor chemicals. Single-source vulnerability persists for boron carbide sintering capacity. Distribution runs through defense contractor subsystem procurement and direct municipal agency contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ballistic protection materials market reads as a late-cycle quality story. Bundeswehr modernization specifications are elevating performance thresholds and rewarding suppliers with captive metallurgical expertise and certified fiber vertical control.
For Market Incumbents: Deploy backward integration into boron carbide powder supply to neutralize Chinese feedstock concentration risk. Accelerate closed-loop aramid recycling partnerships ahead of EU Green Deal enforcement. Ceramic sintering specialists face displacement from polymer-ceramic hybrid entrants unless they deepen composite layup engineering capabilities. For New Entrants and Emerging Players: Polymer-ceramic hybrid formulations for weight-reduced helmet applications offer the most penetrable wedge against entrenched hard armor suppliers. Target private security detail procurement in emerging market capitals where concealable soft armor demand outpaces certified supplier capacity. Pursue direct municipal law enforcement relationships outside traditional federal distribution channels. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier fiber recyclers possessing EU Green Deal-compliant circular material flows and KBA-equivalent certification relationships. Long-term viability favors suppliers with demonstrated multi-standard compliance across NIJ, STANAG 4569, and emerging MIIT benchmarks. Watch for NIJ Standard-0101.07 final publication as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Carbide Supply | Captive powder sourcing neutralizes Chinese concentration risk for Rheinmetall-class metallurgists. |
| Closed-Loop Aramid Recycling Partnership | EU Green Deal compliance secures KBA-equivalent contract eligibility for German integrators. |
| Polymer-Ceramic Hybrid R&D Investment | Level IV protection at reduced areal density opens helmet and vehicle armor platform wins. |
| Direct Municipal Agency Contracting | Bypassing federal distribution captures fragmented law enforcement procurement outside military cycles. |
| Multi-Standard Certification Acceleration | Simultaneous NIJ and STANAG 4569 qualification reduces development cycle friction for NATO suppliers. |
Methodological Framework
Bottom-up law enforcement and defense contractor procurement modeling reconciled against top-down fiber and ceramic production tracking forms the analytical core of this study. Primary interviews with ballistic material R&D directors, municipal police procurement officers, defense platform integration engineers, and para-aramid fiber plant managers combined with secondary validation from NIJ certification registries, STANAG 4569 test facility records, Bundeswehr framework agreement disclosures, and EU Green Deal implementation guidance. Customs data for boron carbide powder trade flows and SEC filings from listed fiber specialists provided supply-side triangulation.
Historical trendline analysis across material type, product form, and application segments established baseline growth patterns over the projection horizon. Segmentation dimensions modeled include soft versus hard armor systems, NIJ certification tier, military versus security versus law enforcement end-use, and regional procurement standard clusters. CAGRs derived from weighted average of segment trajectories, with specific inputs from Bundeswehr modernization program announcements and municipal agency replacement schedule surveys.
The model holds under stable NATO defense budget commitments and gradual NIJ standard phase-in; deviation in abrupt procurement freeze triggers or accelerated EU recycled content mandates would shift volume and value outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Water Soluble Film Market
Specialty Materials
Specialty Silica Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Global Ajinomoto Build-Up Film Substrate Market
Specialty Materials
Erbium-169 Market
Specialty Materials
Fumed Silica Market
Specialty Materials
Spermaceti Wax Market
Specialty Materials
Edge Banding Materials Market
Specialty Materials
Cellulose Gel Market
Specialty Materials
Charge Generation Materials (CGM) Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
Marine Mineral Complexes from Mediterranean Shells Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Specialty Coating Market
Specialty Materials
North America Microspheres Market