
 Silicone Solutions Market | 2026-2036
Silicone Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Solutions Market Intelligence
The modularization of silicone systems, which provides customized formulations for specific end-uses, is rebalancing buyer preference away from standard off-the-shelf products. Dow Inc. leverages its extensive chemical portfolio to offer integrated solutions for the automotive sector. Wacker Chemie AG sustains its market position through specialized R&D in high-purity silicones for medical applications, while Shin-Etsu Chemical Co., Ltd. dominates the electronics-grade silicone segment through its manufacturing scale in Japan.
Silicone solutions comprise a family of polymers based on a siloxane backbone, which imparts high thermal stability and chemical inertness. These materials are engineered through specific curing systems to achieve desired properties like flexibility or rigidity for use in sealing, adhesion, and insulation. Silicone elastomers and sealants constitute the largest product categories due to widespread industrial use. The medical devices application segment represents the fastest-growing opportunity, demanding high-purity formulations for biocompatibility.
Market access is governed by stringent regulations like the European Union's REACH framework, which scrutinizes chemical substances. In the United States, the FDA sets biocompatibility standards for silicones used in medical devices and food contact applications. China's NMPA also imposes strict requirements on materials for healthcare products. Future success for suppliers hinges on navigating these divergent regional standards while investing in sustainable production processes.
Market Dynamics
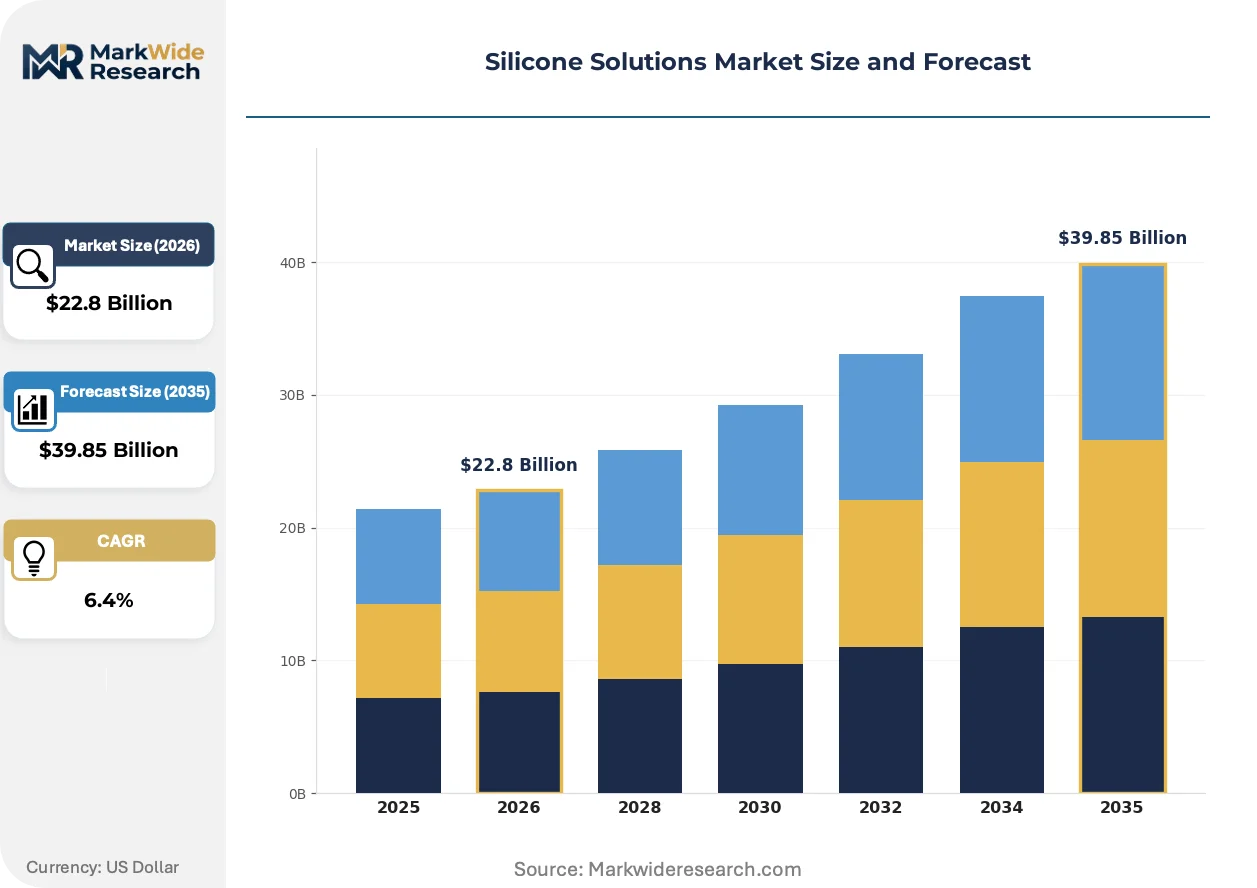
The silicone solutions market is defined by the need to balance increasing demand for application-specific formulations against a complex and diverging global regulatory landscape. This dynamic forces suppliers to innovate on material properties for sectors like medical devices while ensuring compliance with frameworks like the EU's MDR and the FDA's biocompatibility standards.
Growth Catalysts
- Medical Grade Demand:Stricter regulations such as the EU's Medical Device Regulation (MDR) are mandating higher purity and biocompatibility, driving development and adoption of specialized medical-grade silicones for implants and devices.
- Electric Vehicle Production:The automotive industry's transition to electric vehicles creates substantial demand for silicone solutions in battery thermal management, high-voltage cable insulation, and environmental sealing.
- Asia-Pacific Manufacturing:Industrial expansion in China and India, particularly in electronics and automotive sectors, fuels domestic consumption of silicone elastomers and adhesives, supporting regional production capacity growth.
Market Restraints
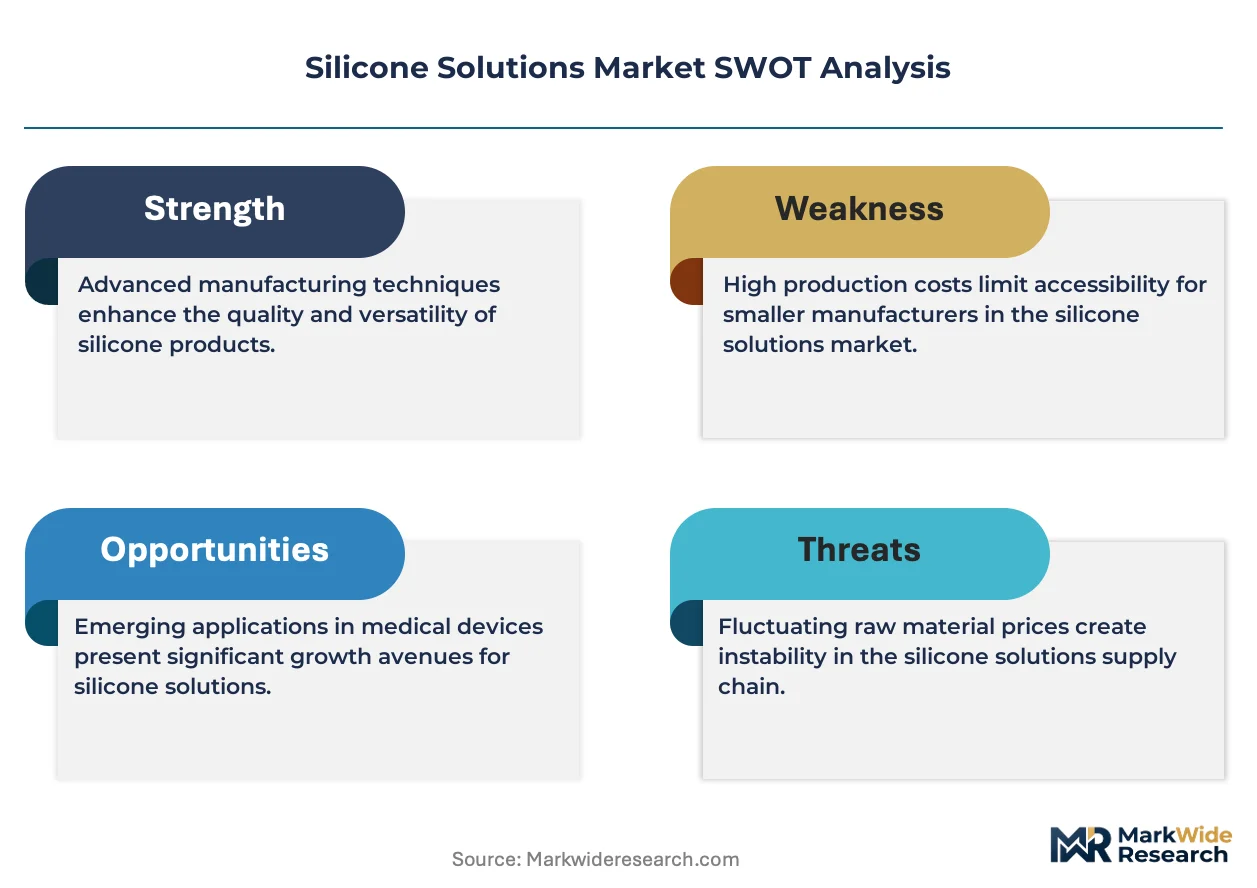
- Raw Material Volatility:The price and availability of key precursors like silicon metal and methanol are subject to fluctuations based on energy costs and supply chain disruptions, impacting overall production cost stability.
- Divergent Regulatory Hurdles:Navigating disparate chemical control laws, such as the EU's REACH and China's NMPA requirements, increases compliance costs and can delay market access for new formulations.
- Substitution in Low-End Applications:In less demanding sealing and caulking applications within the construction sector, lower-cost polymers like polyurethanes and acrylics present a persistent substitution threat to standard silicone grades.
Strategic Opportunities
- Additive Manufacturing Materials:Developing silicone formulations specifically for 3D printing opens new possibilities for rapid prototyping and the production of complex, customized parts in the medical and industrial sectors.
- Sustainable Formulations:Investment in bio-based feedstocks and solvent-free curing processes provides an opportunity to meet corporate sustainability goals and appeal to environmentally conscious end-users.
- High-Performance Construction:Targeting infrastructure projects in Southeast Asia with advanced silicone sealants for structural glazing and weatherproofing addresses needs in a region with significant construction activity.
Industry Challenges
- Lengthy Certification Cycles:The process for achieving biocompatibility certification from bodies like the FDA or notified bodies under the EU MDR is time-consuming and capital-intensive, creating a high barrier for new medical-grade materials.
- Supply Chain Resilience:Geographic concentration of siloxane production in specific regions creates vulnerabilities, forcing companies to re-evaluate their global supply chain strategies to mitigate geopolitical and logistical risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Solutions Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Gels, Silicone Adhesives, Silicone Elastomers, Silicone Sealants Application: Aerospace, Automotive, Electronics, Medical Devices End User: Manufacturers, Distributors, Retailers, Contractors Technology: Curing Systems, Extrusion Processes, Injection Molding, Coating Technologies |
| Companies Covered | Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., Dow Inc., Momentive Performance Materials, Inc., Elkem ASA, Lanxess, BASF SE, Siltech Corporation, The Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Solutions Market Strategic Shifts & Innovations
Material science advancements are enabling the creation of highly tailored silicone systems. This evolution allows formulators to move beyond generic properties and engineer materials with precise performance characteristics for sophisticated applications in electronics, healthcare, and mobility.
Additive manufacturing using silicone elastomers allows for the rapid creation of prototypes and functional parts with complex internal structures. Medical device firms and automotive R&D labs are early adopters, using the technology to accelerate design validation. This capability is unifying the distinct processes of material science and component engineering, enabling integrated product development cycles.
The European Union's REACH framework continues to influence global formulation strategies through its ongoing evaluation of chemical substances. This scrutiny on specific siloxane compounds compels suppliers to invest heavily in toxicological data and alternative chemistry. The consumer care and healthcare segments are most affected, prioritizing materials with comprehensive safety documentation to ensure market access in Europe.
A notable behavioral shift is occurring as industrial customers increasingly procure silicone based on performance specifications rather than by standard product codes. This trend disrupts the role of traditional distributors focused on volume, favoring direct collaboration between end-users and formulators. This is most prominent in the high-tech electronics sector, where material properties are critical to final device performance.
Silicone Solutions Market Segmentation
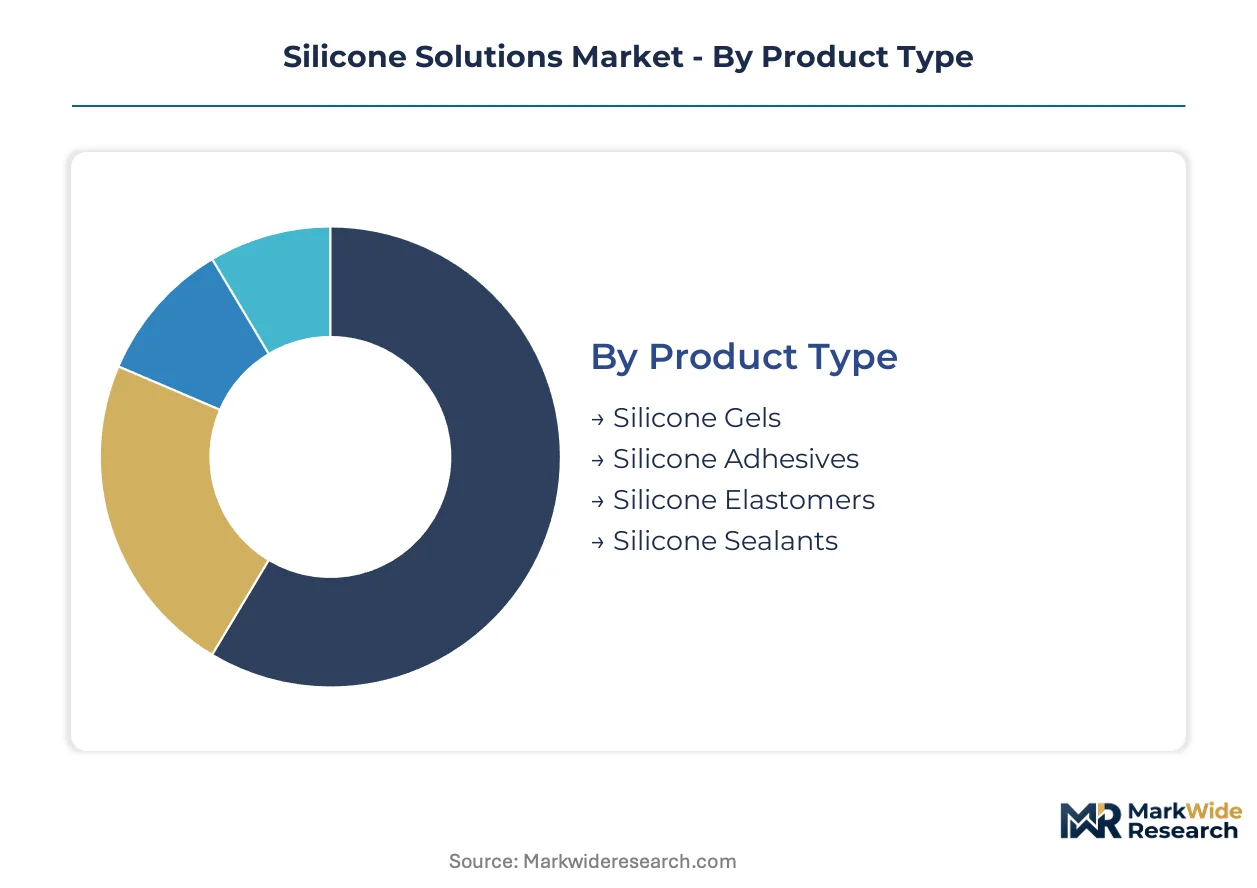
Understanding the segmentation of the silicone solutions market is essential for identifying specific growth trajectories and navigating diverse regulatory landscapes. Manufacturers must tailor product development and market entry strategies to align with the distinct requirements of each product type, application, end-user, and underlying technology.
Product Type:
The silicone solutions market differentiates its offerings across a spectrum from highly standardized bulk products to intricately customized formulations, reflecting diverse performance needs.
- Silicone Elastomers:These polymers possess a flexible, rubber-like consistency, formed through specific curing systems. Silicone elastomers are crucial for applications requiring durability and resistance to extreme temperatures, finding extensive use in automotive gaskets and industrial seals.
- Silicone Sealants:Viscous compounds designed for sealing gaps and joints, offering strong adhesion and weather resistance. Construction projects in Southeast Asia demand advanced silicone sealants for structural glazing and weatherproofing applications.
- Silicone Gels:Soft, compliant materials often used for cushioning or dielectric protection in sensitive electronic components.
- Silicone Adhesives:Formulations providing strong, flexible bonds across various substrates, essential for assembly in electronics and medical devices.
Most installed capacity flows through Silicone Elastomers. Expansion is steepest in Silicone Sealants.
Application:
Demand for silicone solutions varies significantly across end-use applications, each presenting unique performance requirements and regulatory challenges.
- Medical Devices:These applications require high-purity, biocompatible silicone formulations for implants, catheters, and surgical instruments. Stricter regulations like the EU's Medical Device Regulation (MDR) drive development of specialized medical-grade silicones.
- Automotive:Silicone solutions provide critical functions in electric vehicles, including battery thermal management, high-voltage cable insulation, and environmental sealing. The transition to electric vehicles fuels substantial demand in this sector.
- Electronics:This sector utilizes silicones for encapsulation, thermal management, and electrical insulation in components and devices.
- Aerospace:High-performance silicone materials offer temperature stability and flame resistance for critical sealing and insulation in aircraft systems.
The Medical Devices segment is expanding most quickly, driven by stringent biocompatibility requirements. Automotive applications also demonstrate robust growth.
End User:
The procurement channels for silicone solutions are shaped by the diverse operational models of various end-user types, influencing product specifications and delivery logistics.
- Manufacturers:These large-volume buyers integrate silicone solutions directly into their production processes for products like automotive components or electronic devices. They often demand highly specific formulations and reliable supply chains.
- Contractors:Engaged in construction and infrastructure projects, these users require specialized sealants and adhesives for on-site application. Their purchasing decisions are often project-specific, focusing on performance and ease of use.
- Distributors:These intermediaries manage inventory and supply chains, catering to a broad base of smaller industrial and commercial customers.
- Retailers:Primarily serve DIY consumers and small businesses with off-the-shelf silicone sealants and adhesives for general repair and household use.
Manufacturers account for the largest volume consumption of silicone solutions. Contractors represent a significant segment for specialized product delivery.
Technology:
Advancements in silicone processing technologies are enabling the creation of materials with tailored properties, moving beyond conventional manufacturing limits.
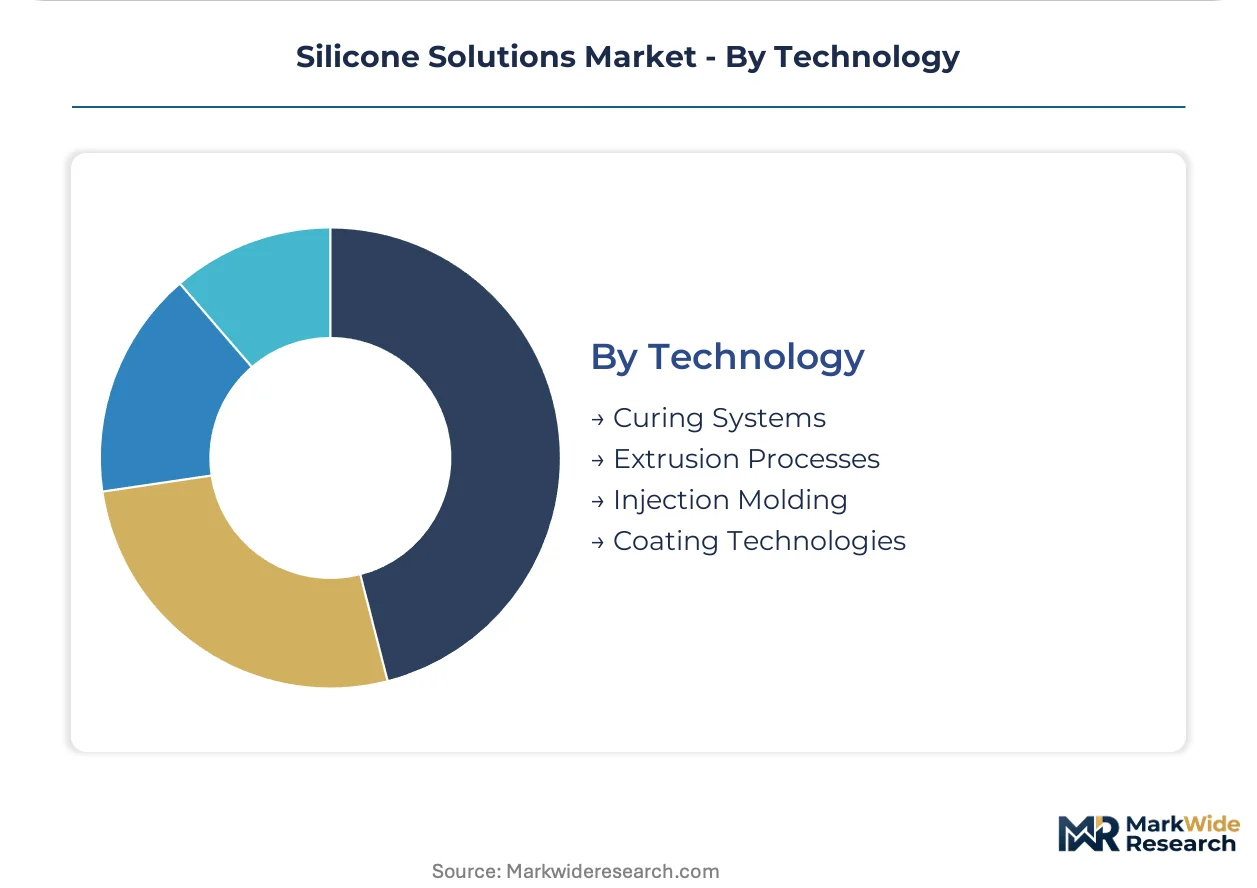
- Curing Systems:These chemical processes polymerize liquid silicone into solid forms, determining the final material properties such as flexibility, hardness, and thermal stability. They are critical for achieving specific end-use characteristics.
- Injection Molding:A high-volume manufacturing method for producing complex silicone parts with precision and consistency. This technology is increasingly used for medical devices and intricate automotive components.
- Extrusion Processes:Continuous manufacturing techniques used to produce silicone profiles, tubes, and sheets for industrial and construction applications.
- Coating Technologies:Methods for applying thin layers of silicone onto substrates, enhancing properties like water repellency, non-stick surfaces, or electrical insulation.
Curing Systems remain foundational for silicone material development. Injection Molding is experiencing significant innovation for complex part fabrication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The silicone solutions market initially saw significant development in established industrial economies like Germany and the United States, driven by early chemical innovations. Production gravity has increasingly shifted towards Asia, particularly China and Japan, reflecting their dominance in electronics and automotive manufacturing. This geographic rebalancing impacts supply chains and regulatory compliance worldwide.
China
China's robust industrial expansion in electronics and automotive sectors drives substantial demand for silicone elastomers and adhesives. The NMPA imposes strict requirements on materials for healthcare products, influencing local formulation strategies. Manufacturing hubs in the Yangtze River Delta actively integrate advanced silicone solutions for high-volume production.
India
Accelerated industrialization in India, particularly within its electronics and automotive industries, generates substantial demand for silicone materials. The PLI scheme encourages domestic manufacturing, stimulating local supply chain development for silicone solutions. Major production centers in Bengaluru and Hyderabad integrate advanced silicones for diverse electronic applications.
Japan
Japan sustains high demand for electronics-grade silicones and high-purity formulations due to its advanced manufacturing base. METI policies support R&D in specialized materials, ensuring compliance with global performance benchmarks. The Kanto region's technology clusters develop next-generation silicone applications for precision electronics.
Germany
Germany's robust medical devices sector and automotive industry drive demand for high-purity silicones and advanced elastomers. The EU's Medical Device Regulation (MDR) mandates stringent material biocompatibility, impacting product development. Research centers in Bavaria and Baden-Württemberg focus on specialized silicone formulations for critical applications.
United States
The United States market requires specialized silicone solutions for its medical devices, electric vehicle, and aerospace industries. The FDA sets strict biocompatibility standards for medical and food contact applications, influencing material innovation. Silicon Valley and Boston's biotech hubs actively integrate advanced silicones into next-generation medical technologies.
Silicone Solutions Market Key Industry Players
Premium-margin players sit above commodity-margin players across the silicone solutions market, driven by specialization in high-performance formulations. The market structure exhibits a tiered consolidation, with large chemical conglomerates offering integrated solutions alongside niche specialists. Strategic archetypes include diversified chemical giants, focused high-purity material developers, and regional volume producers. Companies pursue competitive differentiation through advanced R&D investments and expanding manufacturing scale in key geographies.
On the premium-tier vector, Germany-based Wacker Chemie AG exemplifies specialized R&D in high-purity silicones, particularly for medical applications. Japan's Shin-Etsu Chemical Co., Ltd. occupies a position of dominance in electronics-grade silicones, leveraging its extensive manufacturing scale. US-headquartered Dow Inc. represents a diversified chemical conglomerate, leveraging its broad portfolio to offer integrated solutions across various industrial sectors and end-uses. These entities collectively anchor the market's high-value segments.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd. |
| Dow Inc. |
| Momentive Performance Materials, Inc. |
| Elkem ASA |
| Lanxess |
| BASF SE |
| Siltech Corporation |
| The Dow Chemical Company |
| Others |
Cost & Logistics Intelligence
Silicon metal prices, a primary raw material, directly influence production costs for silicone solutions, affecting pricing across all product tiers. Fluctuations in energy costs for manufacturing also transmit through the supply chain, impacting end-user pricing.
Pricing Analysis
Contract-based long-term offtake agreements define the dominant pricing model for high-volume silicone solutions. Price differentiation stems from certification levels, particularly for medical-grade silicones, and the degree of customization for specialized formulations. Pricing softness in standard grades reflects competition from lower-cost polymers. Manufacturers of medical devices exhibit low price sensitivity due to stringent performance requirements, while construction contractors are highly price-sensitive for basic sealants.
Supply Chain Analysis
Workforce availability in manufacturing hubs across China and India influences the stability of silicone solutions production. The supply chain draws from key precursors like silicon metal and methanol, often sourced globally. Single-source vulnerability for specialized siloxane compounds presents a structural risk. Distribution runs through a hybrid model, combining direct sales to large manufacturers with intermediaries serving smaller industrial and commercial customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silicone solutions market offers significant margin expansion opportunities through a strategic shift towards high-purity medical-grade formulations. Stricter biocompatibility regulations enable premium pricing for specialized materials, driving value capture and sustained profitability.
For Market Incumbents: Acquire specialized R&D capabilities in additive manufacturing materials to counter the threat of generic substitutes in traditional applications. Invest heavily in advanced certification infrastructure for new medical-grade silicones, reinforcing market position against emerging entrants and ensuring compliance. Expand manufacturing capacity in Southeast Asia to address regional construction demand and mitigate supply chain vulnerabilities.
For New Entrants and Emerging Players: Launch via direct collaboration models with end-users in the high-tech electronics sector, focusing on specific performance specifications and rapid iteration. Target the underpenetrated segment of sustainable silicone formulations with bio-based feedstocks, appealing to environmentally conscious buyers. Develop specialized 3D printing materials for rapid prototyping in medical devices, leveraging niche application expertise for complex geometries.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory compliance costs for high-purity materials become prohibitive for smaller players, favoring larger, established firms. The market demonstrates long-term viability over the next decade due to persistent demand from critical medical and automotive sectors. Identify acquisition targets with established biocompatibility certifications and strong intellectual property in novel curing systems. Watch for significant shifts in regional regulatory frameworks as an inflection indicator for market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Supports growing electronics and automotive industries in China and India. |
| Biocompatibility Certification Investment | Ensures market access for medical devices under EU MDR and FDA standards. |
| Advanced Curing System R&D | Tailors silicone properties for demanding applications in aerospace and electric vehicles. |
| Backward Integration into Siloxane Production | Mitigates raw material volatility and strengthens supply chain resilience. |
| Sustainable Formulation Development | Appeals to environmentally conscious end-users and meets corporate sustainability goals. |
Research Approach
Coverage spans China, India, Japan, Germany, and the United States, with primary inputs from each region. The analysis combines in-depth interviews with R&D directors, procurement leads, and regulatory affairs specialists. Secondary validation draws from customs data, industry association reports, and SEC 10-K filings. This approach ensures robust bottom-up and top-down triangulation for market sizing.
Rate-of-change decomposition models market dynamics by segmenting across product type, application, end-user, and underlying technology. The analytical framework projects growth over the projection horizon, with CAGRs derived from historical performance and anticipated shifts. Key forecast inputs include electric vehicle production forecasts and medical device regulatory timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme raw material volatility or unforeseen regulatory shifts. This analysis reflects assumptions regarding global economic stability and technological progression. Material deviation in precursor supply or medical device certification processes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Organic Scintillators Market
Specialty Materials
Nitrocellulose Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Dysprosium Oxide Sputtering Target Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
Conductive Fluted Sheets Market
Specialty Materials
Microwave Absorbing Materials Market
Specialty Materials
Middle East and Africa Anti-Friction Coatings Market
Specialty Materials
Light Diffusion Materials Market
Specialty Materials
Polyimide Films Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Magnesium Fluoride Market
Specialty Materials
Asia Pacific Cellulose Acetate Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Specialty Coating Market