
 EMI and RFI Shielding Materials Market | 2026-2036
EMI and RFI Shielding Materials Market Size, Share, and Industry Trends Forecast 2026-2036
EMI and RFI Shielding Materials Market Analysis
Multi-source procurement for conductive coatings is decoupling from legacy sole-supplier arrangements across tier-one electronics manufacturers. TDK Electronics leverages its ferrite material science heritage to anchor high-frequency shielding portfolios in Asian supply chains. Henkel competes through adhesive-conductive formulations that integrate thermal and electromagnetic management. Parker Chomerics specializes in fabric-over-foam gaskets that dominate military and aerospace qualification programs.
EMI and RFI shielding materials are engineered composites, typically metallized polymers or conductive particle-filled elastomers, designed to attenuate electromagnetic interference across frequency ranges from kilohertz to gigahertz through reflection, absorption, or multiple internal reflections. Their primary purpose is ensuring electromagnetic compatibility in densely packaged electronic assemblies where signal integrity and regulatory compliance are non-negotiable. Copper and aluminum formulations currently occupy the largest volume share in telecommunications infrastructure, though silver-bearing coatings command premium positioning in satellite and defense applications where oxidation resistance and solderability are critical. Sheet and foil form factors sustain mature demand in consumer electronics housings, while coating technologies are displacing traditional metal cans in automotive radar modules where weight reduction and design flexibility drive specification changes.
FCC Part 15 emissions limits in the United States, EU EMC Directive 2014/30/EU with CE marking requirements, and China's GB/T 9254 standard collectively shape product certification pathways and determine market access eligibility for shielding material suppliers. Automotive OEMs now face overlapping compliance obligations from UNECE R10 for electromagnetic compatibility and EPA fuel-economy targets that intensify lightweighting pressure on shielding architectures. Stakeholders must monitor how 5G millimeter-wave deployment and vehicle-to-everything communication standards redefine frequency coverage requirements and material performance specifications.
Market Dynamics
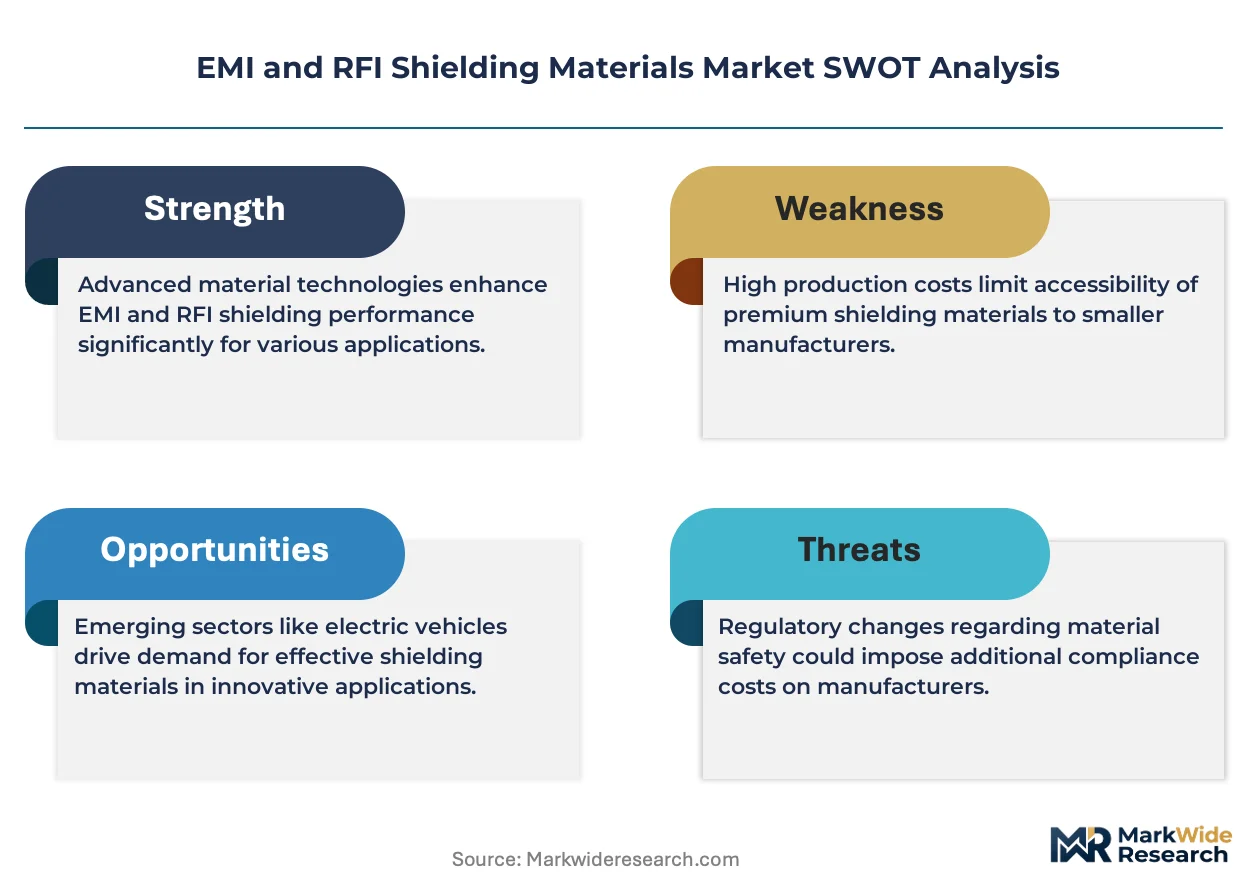
Vehicle electrification is compressing shielding design cycles as automotive OEMs integrate radar, lidar, and V2X modules into unified electronic architectures. Tier-one suppliers now specify materials that satisfy both electromagnetic compatibility and thermal management in single-component solutions.
Growth Catalysts
- UNECE R10 automotive EMC mandates:European vehicle manufacturers must certify electromagnetic compatibility across all electronic subsystems, expanding qualified material procurement.
- 5G millimeter-wave infrastructure:Telecommunications equipment deploys absorptive shielding for base station densification in urban corridors.
- Copper foil demand from Korean battery manufacturers:Cell-to-pack architectures require electromagnetic isolation between high-voltage busbars and control electronics.
Market Restraints
- Silver price volatility:Defense and satellite-grade coatings depend on silver-bearing formulations exposed to commodity exchange fluctuations.
- Single-source ferrite supply concentration:Asian rare-earth processing limits constrain high-frequency magnetic shielding availability.
- RoHS substance restrictions:EU REACH substance-of-very-high-concern listings force reformulation of legacy conductive adhesives containing cadmium or hexavalent chromium.
Strategic Opportunities
- India electronics manufacturing incentives:PLI scheme subsidies for semiconductor packaging attract shielding material localization.
- Printed electronics convergence:Screen-printable conductive inks integrate antenna and shielding functions for wearable medical devices.
- Green hydrogen electrolyzer scaling:Power electronics for megawatt-scale electrolysis require custom magnetic shielding for grid interconnection.
Industry Challenges
- Multiphysics simulation talent scarcity:Engineers must simultaneously optimize electromagnetic, thermal, and mechanical performance in compact automotive modules.
- MIL-STD-461G certification timelines:Defense qualification programs extend 18-24 months, delaying revenue recognition for new material formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMI and RFI Shielding Materials Market |
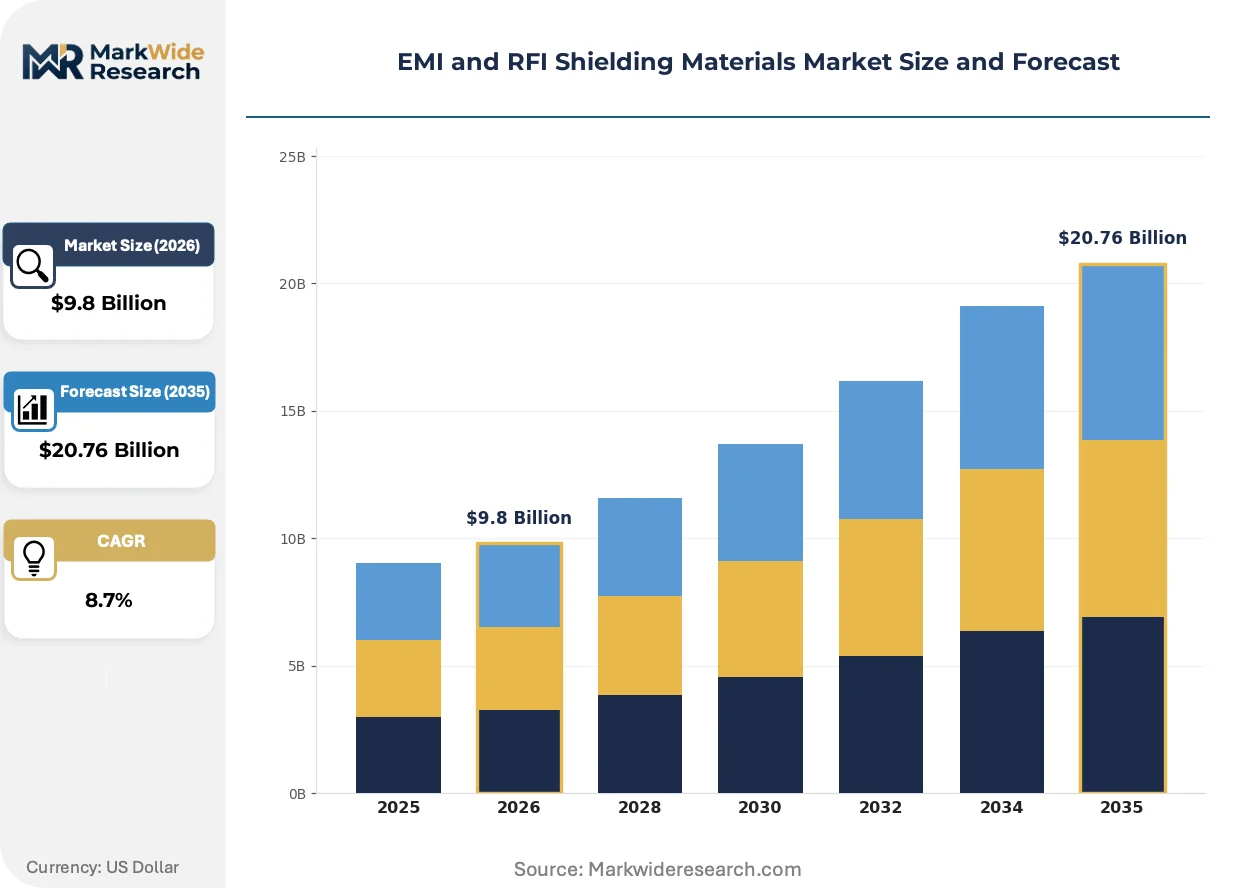
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Copper, Aluminum, Silver, Nickel Application: Telecommunications, Automotive Electronics, Consumer Electronics, Aerospace Form Factor: Sheet, Coating, Foil, Mesh End User: Manufacturers, OEMs, Research Institutes, Component Suppliers |
| Companies Covered | Leader Tech, TDK Electronics, 3M, Würth Elektronik, TE Connectivity, Parker Chomerics, Henkel, PPG Industries, Laird Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMI and RFI Shielding Materials Market Emerging Trajectories
Material architectures are fragmenting into application-specific formulations as end-users reject one-size-fits-all shielding. Suppliers now engineer composites for precise frequency bands and thermal envelopes rather than broadband performance.
Conductive polymer composites are modularizing shielding implementation across consumer electronics housings. Smartphone manufacturers specify discrete material zones that combine electromagnetic attenuation with structural rigidity. This approach collapses separate metal cans and plastic frames into unified mid-frame assemblies, reducing part count and assembly labor.
EU F-Gas Regulation phase-down schedules are accelerating fluoropolymer substrate transitions in high-frequency cable shielding. Manufacturers reformulate expanded PTFE tapes to maintain dielectric performance with reduced greenhouse gas content. Aerospace wire harness suppliers in France and Germany now prioritize suppliers with verified low-GWP material chains.
Automotive tier-one electronics buyers are consolidating vendor panels for conductive coating procurement. Radar module manufacturers in Germany's Stuttgart supplier cluster now qualify dual-source arrangements for spray-applied copper-nickel systems. This concentration rewards suppliers with integrated formulation and application equipment capabilities, marginalizing pure material vendors without process expertise.
EMI and RFI Shielding Materials Market Segmentation
EMI and RFI shielding materials fragment into specialized formulations where electromagnetic performance requirements, weight constraints, and regulatory compliance intersect differently across end-use environments. Procurement teams specify materials through multi-attribute selection criteria rather than single-property optimization, creating distinct competitive arenas within each segment category.
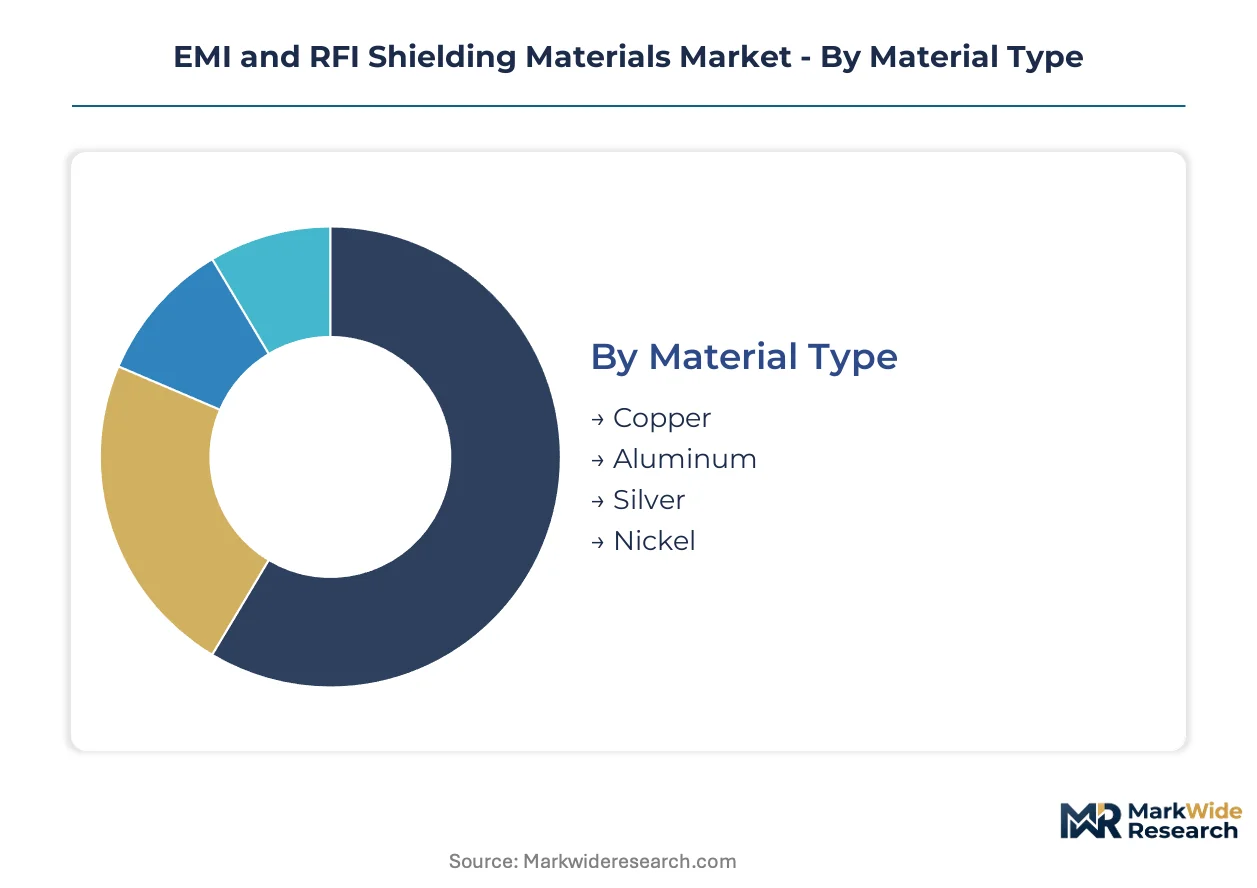
Material Type:
Customization intensity spans from commodity metal foils to engineered silver-bearing coatings, with standardization dominant at volume tiers and bespoke formulations commanding premium positioning.
- Copper:High-conductivity annealed foils and electroplated deposits deliver broadband shielding effectiveness exceeding 100 dB across kilohertz to gigahertz ranges. Korean battery manufacturers specify copper electromagnetic isolation layers in cell-to-pack architectures, driven by high-voltage busbar proximity requirements.
- Aluminum:Lightweight stamped and extruded housings dominate telecommunications infrastructure where weight reduction complements corrosion resistance. German automotive radar module suppliers specify aluminum conductive coatings to satisfy UNECE R10 EMC mandates while meeting EPA fuel-economy lightweighting targets.
- Silver:Oxidation-resistant electroplated and thick-film formulations serve satellite and defense applications requiring solderability retention over mission lifetimes.
- Nickel:Magnetic permeability suits low-frequency magnetic field attenuation in industrial motor drives and power electronics enclosures.
Leading the category by volume: Copper. Growing fastest: Silver.
Application:
End-use diversification creates four distinct demand profiles shaped by frequency coverage, environmental exposure, and certification burden.
- Telecommunications:Base station densification for 5G millimeter-wave deployment drives absorptive shielding specifications in urban corridors. Chinese GB/T 9254 compliance requirements shape material selection for equipment destined for domestic networks.
- Automotive Electronics:Radar, lidar, and V2X module integration compresses design cycles and demands combined electromagnetic-thermal management solutions. Stuttgart and Wolfsburg supplier clusters concentrate procurement for spray-applied conductive systems.
- Consumer Electronics:Smartphone mid-frame assemblies combine structural rigidity with electromagnetic attenuation, collapsing separate metal cans and plastic frames into unified components.
- Aerospace:MIL-STD-461G qualification timelines extend 18-24 months, delaying revenue recognition for new material formulations in defense programs.
Volume leadership sits with Telecommunications. Steepest expansion trajectory belongs to Automotive Electronics.
Form Factor:
Physical implementation formats range from legacy stamped metal to additive-manufactured conformal coatings, with process integration capabilities determining supplier selection.
- Sheet:Mature stamped and formed metal cans sustain consumer electronics housing applications where design flexibility requirements remain modest.
- Coating:Spray-applied and screen-printable conductive systems displace traditional metal cans in automotive radar modules where weight reduction and geometric complexity drive specification changes. Henkel and TDK Electronics compete through integrated formulation and application equipment capabilities.
- Foil:Rolled annealed copper and aluminum products serve telecommunications cable shielding and battery cell isolation layers with established supply chains.
- Mesh:Knitted and woven conductive fabrics provide gasketing and ventilation panel solutions where airflow and electromagnetic attenuation must coexist.
Sheet maintains volume dominance. Coating gains share fastest through automotive and telecommunications substitution.
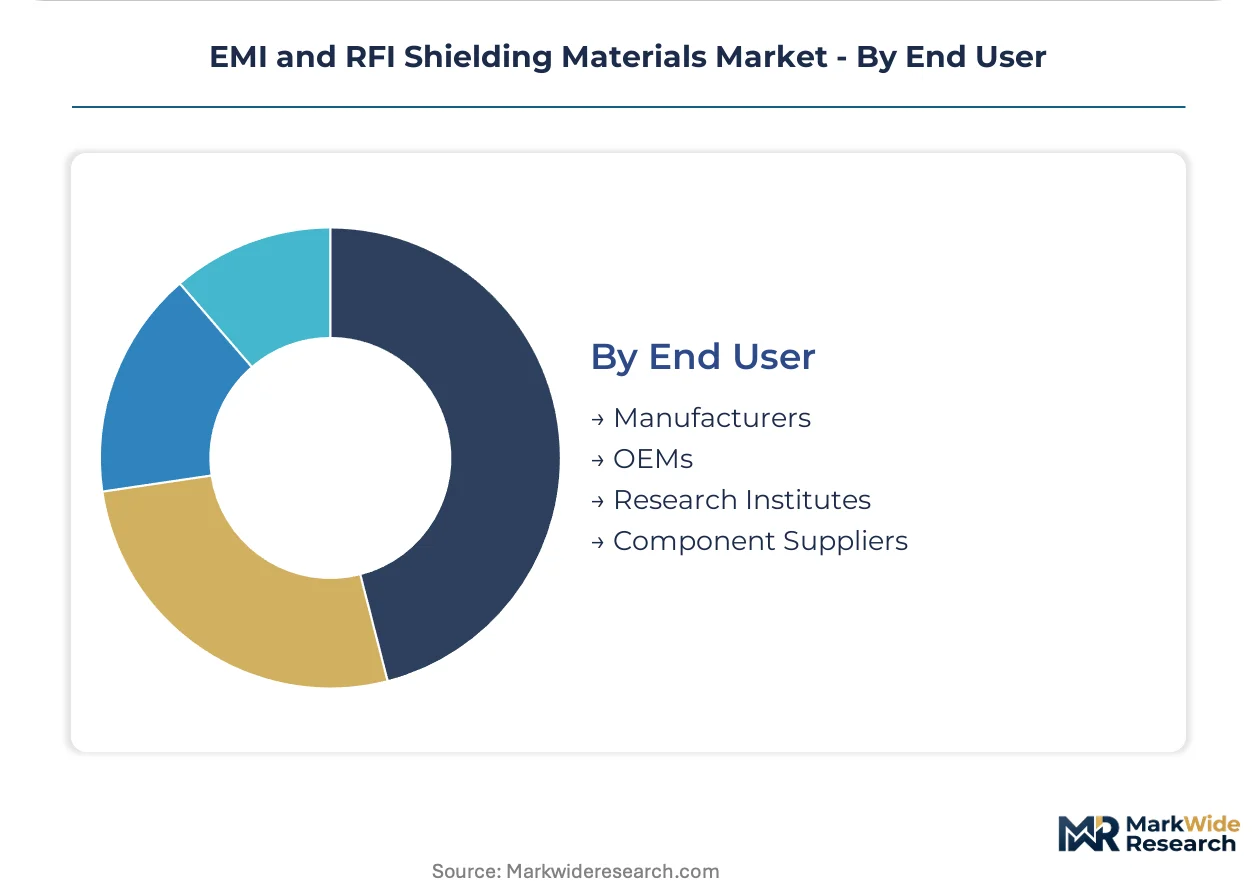
End User:
Customer organizational type determines procurement sophistication, with OEMs and tier-one manufacturers driving qualification standards that cascade through supply chains.
- Manufacturers:Electronics contract manufacturers specify shielding materials through customer-directed sourcing agreements with limited formulation autonomy.
- OEMs:Automotive and telecommunications original equipment manufacturers consolidate vendor panels and mandate dual-source arrangements for critical conductive coating procurement. EU RoHS and REACH compliance verification sits at this tier.
- Research Institutes:National laboratories and university centers pilot printed electronics convergence and screen-printable conductive ink development for wearable medical devices.
- Component Suppliers:Tier-two and tier-three suppliers inherit material specifications from upstream customers, competing on application expertise and process integration rather than formulation innovation.
OEMs lead procurement volume. Research Institutes expand most quickly through printed electronics and green hydrogen electrolyzer development programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth processing concentration in China and ferrite material heritage in Japan anchor supply-side geography for high-frequency magnetic shielding. German automotive electronics clusters and Korean battery manufacturing drive demand-side procurement intensity across three continents.
United States
FCC Part 15 emissions enforcement and defense satellite programs sustain silver-bearing coating demand. EPA fuel-economy targets intersect with NHTSA safety mandates to accelerate lightweight shielding adoption in electric vehicle architectures. The Greater Boston corridor hosts printed electronics research bridging conductive ink development with wearable medical device prototyping.
Germany
UNECE R10 automotive EMC certification requirements and Stuttgart-Wolfsburg supplier clusters concentrate radar module procurement. EU REACH substance restrictions and RoHS compliance thresholds force cadmium-free adhesive reformulation across tier-one electronics manufacturers. The Baden-Württemberg region anchors spray-applied copper-nickel system qualification programs for dual-source arrangements.
China
GB/T 9254 standard enforcement for telecommunications equipment and 5G millimeter-wave base station densification drive absorptive shielding specifications. MIIT industrial policy supports domestic rare-earth processing for ferrite supply chain security. The Yangtze River Delta hosts cell-to-pack battery manufacturing requiring copper electromagnetic isolation layers between high-voltage busbars.
South Korea
Korean battery manufacturers specify copper foil electromagnetic isolation in cell-to-pack architectures for electric vehicle platforms. The country's national industrial regulator enforces electromagnetic compatibility standards aligned with UNECE frameworks for automotive export markets. The Busan-Ulsan industrial corridor concentrates procurement for power electronics shielding in green hydrogen electrolyzer development.
India
PLI scheme subsidies for semiconductor packaging attract shielding material localization investments from multinational suppliers. BIS standards alignment with IEC frameworks shapes product certification pathways for domestic electronics manufacturing. The Karnataka-Telangana corridor hosts emerging printed electronics convergence programs targeting wearable medical device applications.
EMI and RFI Shielding Materials Market Vendor Landscape
Global majors compete with regional champions across formulation expertise and application equipment integration. The vendor base separates into three tiers: integrated material-process suppliers, pure formulation specialists, and application equipment providers. Two strategic archetypes dominate competitive positioning—ferrite heritage players leveraging magnetic material science and adhesive-conductive integrators combining thermal with electromagnetic management. Capacity expansion in Asian rare-earth processing and strategic partnerships for dual-source qualification programs represent the dominant competitive moves.
Within the integrated formulation tier, TDK Electronics and Henkel occupy positions exemplifying divergent technical anchors. TDK Electronics represents ferrite material science heritage applied to high-frequency shielding portfolios. Henkel exemplifies adhesive-conductive convergence integrating thermal and electromagnetic management in single-component solutions. Parker Chomerics sits within the specialized gasket segment, anchoring fabric-over-foam qualification programs for military and aerospace certification pathways.
| Leading Market Players |
|---|
| Leader Tech |
| TDK Electronics |
| 3M |
| Würth Elektronik |
| TE Connectivity |
| Parker Chomerics |
| Henkel |
| PPG Industries |
| Laird Connectivity |
| Others |
Supply Flow & Price Mechanics
Multiphysics simulation talent concentration in Germany's Baden-Württemberg region anchors labor-cost differentials that stretch pricing-tier spreads between premium qualified coatings and commodity foil alternatives. Tier-one automotive electronics buyers absorb 15-25% cost premiums for dual-source qualified spray-applied copper-nickel systems that satisfy UNECE R10 mandates.
Pricing Analysis
Warranty and application equipment bundling separates integrated formulation-process suppliers from pure material vendors in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with MIL-STD-461G qualified silver-bearing coatings commanding substantial premiums over unqualified alternatives. Cost compression in standard-grade copper foils intensifies as Korean battery manufacturers consolidate procurement volumes. Contract manufacturers exhibit highest price sensitivity, while defense primes prioritize qualification retention over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from Stuttgart-Wolfsburg automotive clusters force qualification of secondary suppliers for spray-applied conductive systems. Geographic supply concentration centers on China for rare-earth ferrite processing, Japan for high-frequency magnetic material heritage, and Germany for automotive application expertise. Raw material dependencies include copper cathodes, silver bullion, and rare-earth oxides. Single-source ferrite vulnerability from Asian processing limits poses structural risk. Distribution runs through tier-one electronics manufacturers who consolidate vendor panels and cascade specifications downstream.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where rare-earth processing bottlenecks prop pricing premiums for high-frequency magnetic shielding formulations. Capacity scarcity in qualified ferrite supply chains sustains margin structures despite downstream cost pressure.
For Market Incumbents: Deploy formulation-application integration as the primary lever to defend against pure material vendors lacking process expertise. Deepen captive supply of rare-earth oxide feedstocks through backward integration into Asian processing partnerships. Accelerate dual-source qualification programs for radar module coatings before tier-one consolidation hardens vendor panels. Lock in long-term offtake agreements with Korean battery manufacturers for copper electromagnetic isolation layers. For New Entrants and Emerging Players: Begin with printed electronics convergence in India's PLI-subsidized semiconductor packaging corridor, where shielding material localization incentives reduce incumbent advantages. Target wearable medical device applications for screen-printable conductive inks, where qualification timelines remain shorter than aerospace programs. Pursue green hydrogen electrolyzer power electronics as an emerging vertical with custom magnetic shielding requirements and limited incumbent presence. For Investors and Strategic Acquirers: Re-rating potential sits with integrated formulation-process specialists given tier-one vendor panel consolidation and dual-source mandate expansion. Five-to-ten-year viability favors suppliers with ferrite material science heritage or adhesive-conductive convergence capabilities rather than pure commodity foil processors. Monitor Indian PLI scheme disbursement velocity as the critical signal for shielding material localization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Qualification Program | Stuttgart radar module manufacturers mandate secondary supplier validation to reduce sole-source risk. |
| Rare-Earth Processing Partnership | Backward integration into Chinese ferrite supply chains secures high-frequency magnetic shielding capacity. |
| Printed Electronics Convergence | Screen-printable conductive ink development targets wearable medical devices with shortened qualification paths. |
| PLI Localization Investment | Indian semiconductor packaging subsidies attract shielding material manufacturing to Karnataka-Telangana corridor. |
| Green Hydrogen Electrolyzer Shielding | Custom magnetic solutions for megawatt-scale power electronics open capacity-constrained demand vertical. |
Methodological Framework
Document review covered regulatory filings with FCC, ECHA, and MIIT, complemented by interviews with tier-one automotive electronics procurement directors, ferrite material R&D leads, and telecommunications equipment specification engineers. Secondary validation drew from UNECE R10 certification databases, EU REACH substance restriction updates, and Korean battery manufacturer supply chain disclosures. Bottom-up segment modeling triangulated against top-down macroeconomic drivers.
Output frameworks projected material demand across the analysis window by material type, application end-use, form factor implementation, and geographic production cluster. Segmentation incorporated frequency coverage requirements, thermal management integration intensity, and certification burden tiers. CAGRs derived from historical shipment correlations with 5G infrastructure deployment schedules and electric vehicle platform ramp rates.
Silver price volatility, rare-earth export restriction implementation, and UNECE R10 enforcement intensity are the dominant revision risks to modeled forecasts. Deviation in rare-earth processing capacity expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Silicone Film Market
Specialty Materials
Electroactive Polymers (EAP) Market
Specialty Materials
Specialty Carbon Black Market
Specialty Materials
Marine Mineral Complexes from Mediterranean Shells Market
Specialty Materials
Middle East and Africa Anti-Friction Coatings Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Sheath Materials Market
Specialty Materials
Magnesium Fluoride Market
Specialty Materials
Global Cellulose Esters Market
Specialty Materials
PCB Prepreg Material Market
Specialty Materials
Halloysite Market
Specialty Materials
Solar Control Films Market
Specialty Materials
Melamine Foam Market
Specialty Materials
Medical Injection Molded Plastics Market
Specialty Materials
ePTFE Electronic Film Market