
 Polyester Medical Films Market | 2026-2036
Polyester Medical Films Market Size, Share, and Industry Trends Forecast 2026-2036
Polyester Medical Films Market Analytics
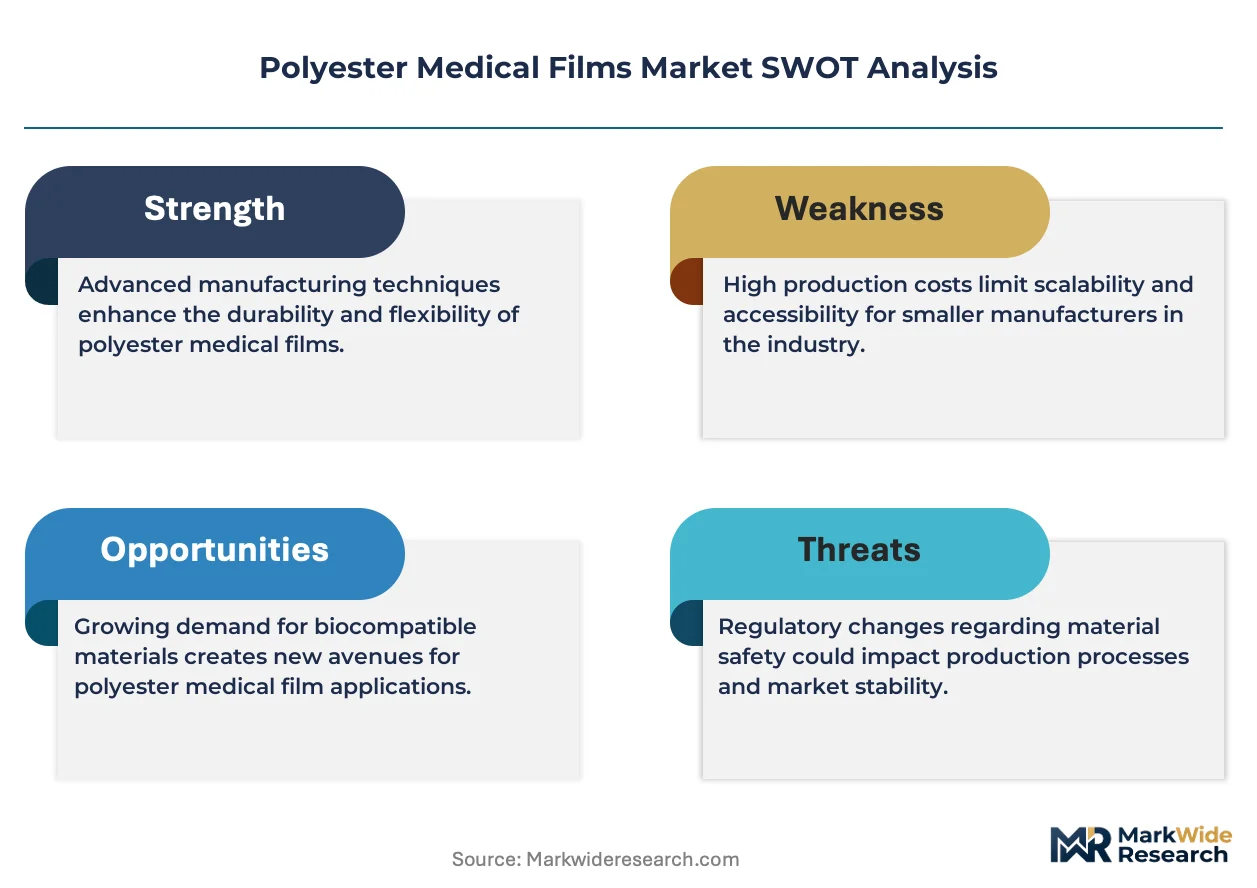
Specialized polymer engineering talent is bifurcating the competitive landscape, separating firms with in-house film extrusion expertise from those dependent on toll converters. Teijin leverages its aromatic polyester research legacy to dominate high-performance medical grades. DuPont anchors North American supply through vertically integrated resin-to-film operations. SKC competes aggressively on thermal laminating scale for Asian device manufacturers.
Polyester medical films are biaxially oriented polyethylene terephthalate (PET) substrates engineered for dimensional stability, optical clarity, and chemical resistance in healthcare environments, typically manufactured via cast film extrusion followed by sequential stretching to achieve controlled thickness tolerances between 12 and 250 micrometers. These films serve as critical barrier layers, release liners, and functional substrates in sterile packaging, diagnostic consumables, and wearable therapeutic devices. Transparent films lead volume shipments due to their dominance in diagnostic packaging and fluid-contact applications where visual inspection matters. Drug delivery applications represent the fastest-expanding segment as pharmaceutical companies adopt polyester backings for transdermal patch platforms. Coated variants command premium positioning where silicone or acrylic functionalization enables specific adhesion profiles for advanced wound care systems.
The FDA enforces ISO 10993 biocompatibility standards for polymer films contacting human tissue or fluids, while the EU MDR requires enhanced clinical evidence for device components including film substrates. REACH compliance in Europe restricts certain phthalate plasticizers historically used in flexible medical films, forcing reformulation toward non-orthophthalate alternatives. Stakeholders must monitor evolving sterilization compatibility requirements as gamma and electron-beam methods alter polyester film mechanical properties differently than ethylene oxide cycles.
Market Dynamics
Specialized polymer engineering talent pools are bifurcating competitive positioning, separating firms with captive film extrusion expertise from those dependent on toll converters across sterile packaging and diagnostic substrate supply chains.
Growth Catalysts
- EU MDR clinical evidence mandates:Device manufacturers are upgrading film substrate specifications to meet enhanced component-level documentation requirements, driving premium-grade polyester adoption across wound care and transdermal platforms.
- Gamma sterilization compatibility:Hospital central sterile supply departments are prioritizing polyester films that maintain dimensional stability under ionizing radiation, displacing legacy PVC alternatives in fluid-contact applications.
- Rhine-Main manufacturing corridor concentration:Precision film converters clustered around Frankfurt-Darmstadt infrastructure enable rapid prototyping-to-scale transitions for European medical device OEMs.
Market Restraints
- Specialized resin feedstock volatility:Purified terephthalic acid and ethylene glycol pricing fluctuations compress margin structures for non-integrated film processors lacking backward control over monomer supply.
- German converter dominance:Toll extrusion capacity concentrates among three mid-scale operators near Ludwigshafen, creating bottleneck risk for device manufacturers without qualified secondary sources.
- Phthalate plasticizer substitution costs:REACH restrictions on orthophthalate chemistries force reformulation investments for flexible film variants, extending qualification timelines by 12-18 months.
Strategic Opportunities
- Transdermal patch expansion:Pharmaceutical companies are adopting polyester backings for controlled-release drug delivery platforms, creating demand for silicone-coated functionalized films with precise adhesion profiles.
- ISO 10993-5 cytotoxicity streamlining:Harmonized biocompatibility testing protocols reduce redundant qualification costs, enabling faster geographic expansion for film suppliers with established regulatory dossiers.
- Electron-beam sterilization adoption:Device manufacturers seeking alternatives to ethylene oxide residue concerns are qualifying polyester grades optimized for e-beam processing, opening specification windows for radiation-stable formulations.
Industry Challenges
- Biaxial orientation engineering scarcity:Sequential stretching process expertise resides with a narrow cohort of technicians trained at legacy PET packaging operations, constraining capacity expansion for medical-grade tolerances.
- Multi-standard certification complexity:Film suppliers must maintain parallel ISO 10993, USP Class VI, and EP 3.1.15 compliance dossiers, fragmenting quality management resources across jurisdictional requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyester Medical Films Market |
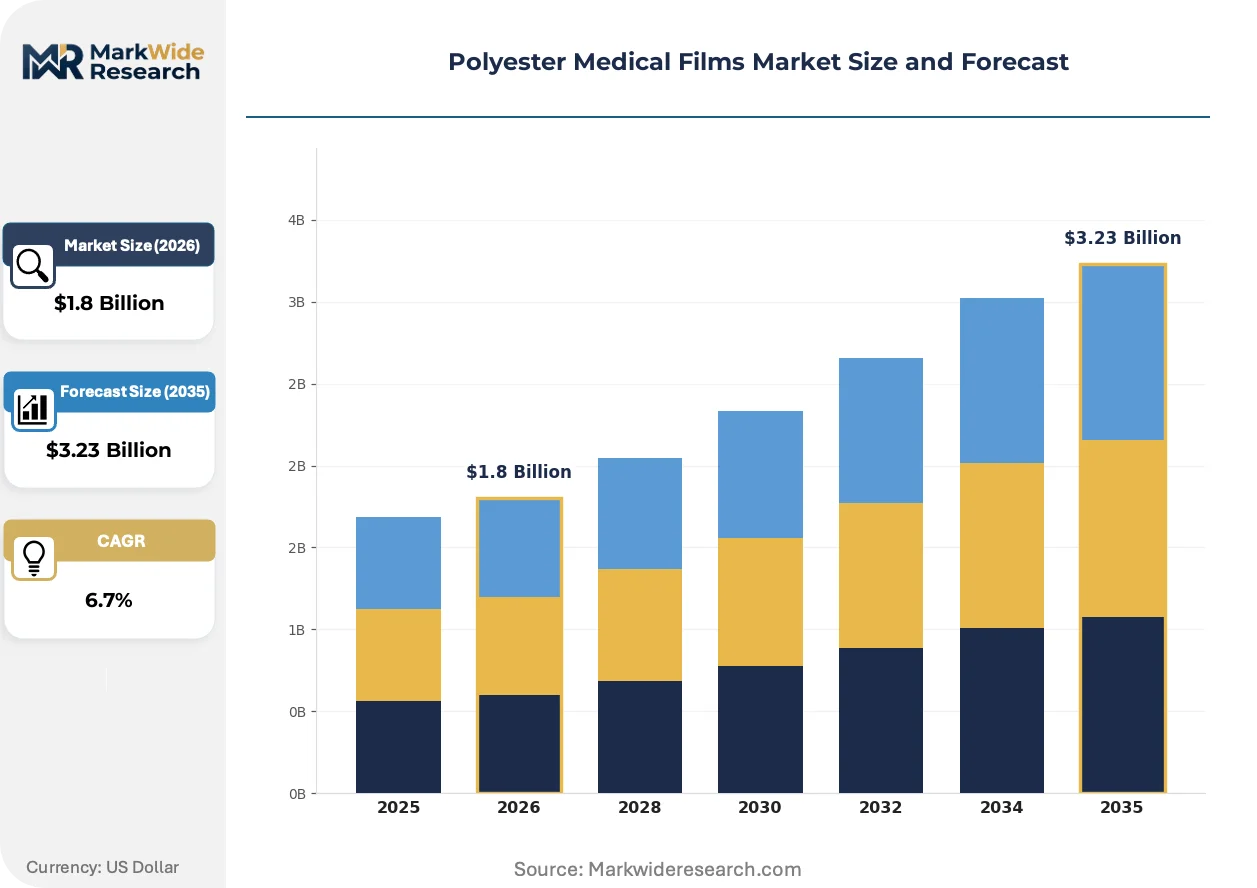
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
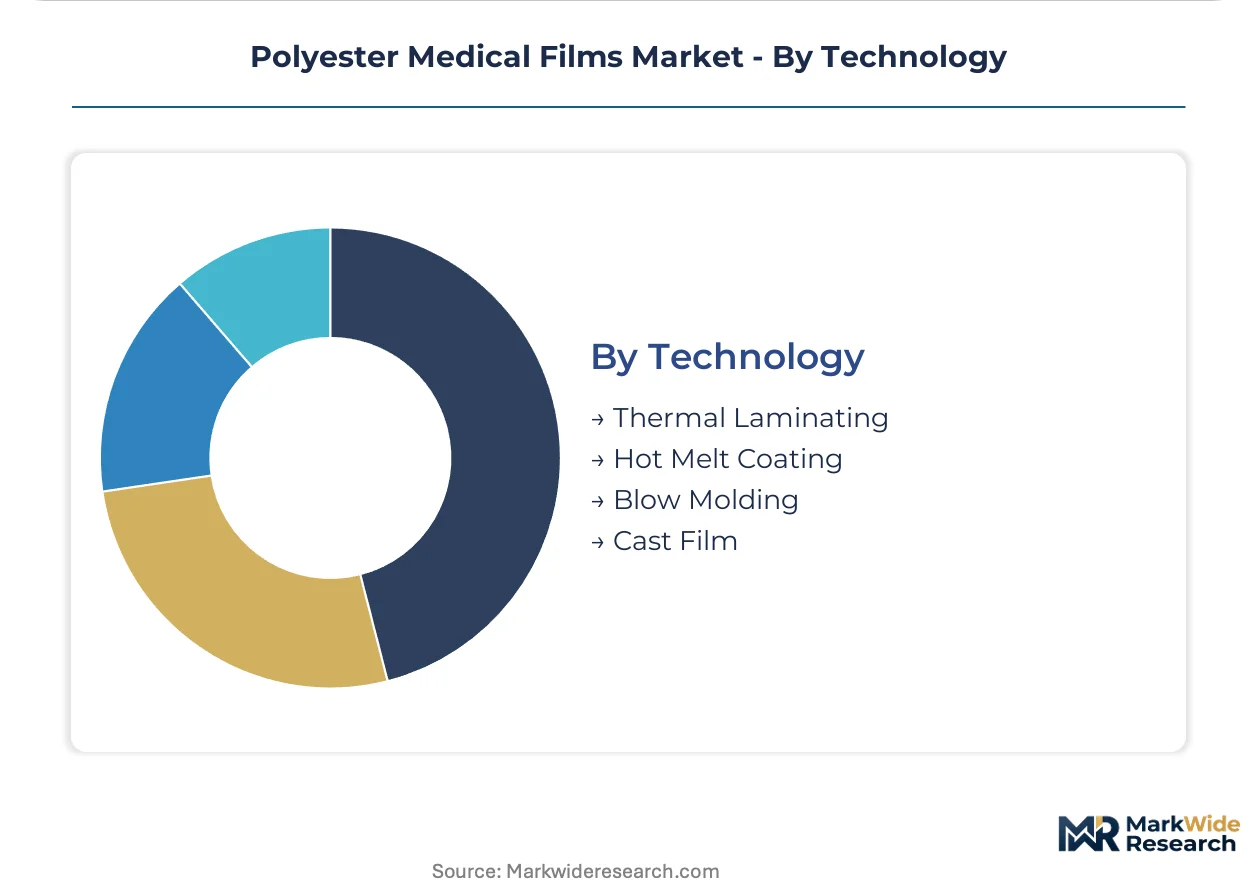
| Segmentation | Product Type: Transparent, Adhesive, Coated, Laminated End User: Hospitals, Clinics, Laboratories, Research Institutions Application: Packaging, Medical Devices, Wound Care, Drug Delivery Technology: Thermal Laminating, Hot Melt Coating, Blow Molding, Cast Film |
| Companies Covered | Teijin, Tekra Corporation, Toray Industries, Futamura Chemicals, Cosmo Films, DuPont, Mitsubishi Chemicals, SKC, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyester Medical Films Market Evolving Landscape
Film functionalization technologies are compressing device form factors while regulatory sterilization mandates and procurement consolidation are restructuring supply relationships across sterile barrier and diagnostic consumable segments.
Multilayer coextrusion with ethylene vinyl acetate tie layers is miniaturizing wearable therapeutic device profiles. Diagnostic OEMs are specifying sub-25-micrometer constructions for glucose monitoring patches and continuous drug delivery systems. This thickness compression is miniaturizing overall device footprints while maintaining barrier integrity against moisture vapor transmission.
REACH Annex XVII restrictions on phthalate plasticizers are forcing reformulation of flexible medical film grades toward non-orthophthalate alternatives. Compounders serving the European market are accelerating citrate and trimellitate ester validation programs. German wound care manufacturers are responding with accelerated supplier audits to secure compliant raw material pipelines ahead of enforcement deadlines.
Hospital group purchasing organizations are consolidating sterile packaging specifications across regional health systems. Procurement teams at multi-hospital networks are reducing qualified film suppliers from twelve to four vendors per category. This concentration is most visible in the US Midwest, where IDN consolidation has compressed switching cycles and locked in three-year supply agreements with volume-tier pricing structures.
Polyester Medical Films Market Segmentation
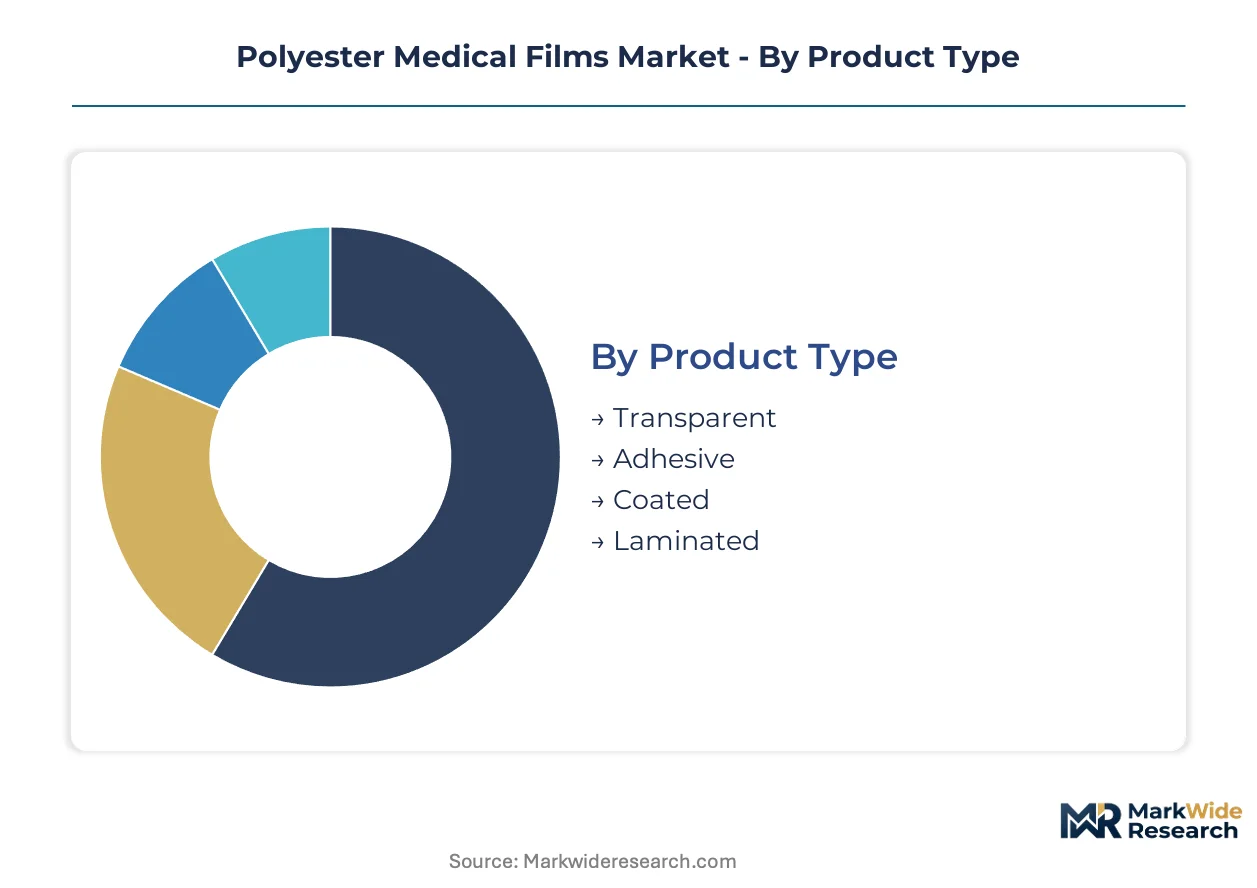
Polyester medical films serve heterogeneous technical requirements across sterile barriers, therapeutic interfaces, and diagnostic platforms. Segmentation reveals how formulation chemistry, sterilization compatibility, and end-use performance specifications create distinct commercial tiers with diverging margin structures.
Product Type:
FDA biocompatibility classifications and EU MDR component-level documentation requirements separate medical-grade films from industrial polyester variants, with transparency and surface functionalization commanding distinct regulatory dossiers.
- Transparent:Unpigmented biaxially oriented PET with optical clarity exceeding 90% light transmission serves diagnostic packaging and fluid-contact applications. German wound care manufacturers specify these grades for visual inspection protocols in operating theaters.
- Coated:Silicone or acrylic functionalized surfaces enable controlled adhesion profiles for transdermal drug delivery platforms. Pharmaceutical companies in the Rhine-Main corridor are accelerating qualification of these grades for controlled-release patch backings.
- Adhesive:Pressure-sensitive formulations bond directly to device substrates without secondary lamination steps.
- Laminated:Multilayer constructions with ethylene vinyl acetate tie layers compress wearable device profiles while maintaining moisture vapor barriers.
Transparent films handle the majority of throughput; coated variants are expanding most quickly on share as transdermal delivery platforms proliferate.
End User:
Procurement scale and sterilization infrastructure differentiate customer tiers, with centralized sterile supply departments imposing stricter qualification protocols than decentralized clinical settings.
- Hospitals:Central sterile supply departments at multi-hospital networks drive volume consolidation through three-year supply agreements. IDN procurement teams in the US Midwest have compressed qualified suppliers from twelve to four vendors per film category.
- Laboratories:Diagnostic consumable manufacturers specify sub-25-micrometer constructions for glucose monitoring patches. These users prioritize dimensional stability under gamma irradiation over cost minimization.
- Clinics:Outpatient settings purchase smaller lot sizes with less stringent sterilization documentation requirements.
- Research Institutions:Academic medical centers prototype novel device configurations using custom film specifications before commercial scale-up.
Hospitals generate the dominant procurement volume; laboratories are gaining share fastest as point-of-care diagnostic platforms expand.
Application:
Barrier performance requirements and human tissue contact duration determine ISO 10993 testing intensity, with permanent implant adjacency demanding more extensive cytotoxicity validation than transient packaging applications.
- Wound Care:Advanced dressing systems require moisture vapor transmission rates between 2,000 and 8,000 g/m²/day. REACH Annex XVII phthalate restrictions are forcing German manufacturers toward citrate plasticizer alternatives in flexible film formulations.
- Drug Delivery:Transdermal patch backings demand precise adhesion profiles and chemical inertness against active pharmaceutical ingredients. FDA updated biocompatibility protocols are extending qualification timelines for new film submissions in this segment.
- Packaging:Sterile barrier systems for surgical instruments prioritize puncture resistance and seal integrity.
- Medical Devices:Diagnostic consumables and wearable therapeutics specify optical clarity or electrical insulation properties.
Wound care commands the largest installed base; drug delivery is climbing the fastest as pharmaceutical companies adopt patch-based controlled-release platforms.
Technology:
Capital intensity and process control precision create tiered supply structures, with sequential biaxial orientation expertise residing in a narrow technical cohort.
- Thermal Laminating:Heat-activated bonding of multilayer constructions enables moisture barrier enhancement without solvent residues. Asian device manufacturers are scaling this technology for high-volume wearable production.
- Cast Film:Extrusion through slot dies followed by chill-roll solidification produces base sheet for subsequent orientation. The Rhine-Main manufacturing corridor hosts concentrated precision converter capacity for medical-grade tolerances.
- Hot Melt Coating:Solvent-free adhesive application reduces volatile organic compound exposure in cleanroom environments.
- Blow Molding:Limited medical application due to thickness control limitations versus biaxial orientation methods.
Cast film underpins the broadest process foundation; thermal laminating is gaining share fastest as device miniaturization demands multilayer complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German wound care manufacturers consume polyester medical films primarily for advanced dressing systems, while US diagnostic OEMs drive sub-25-micrometer specifications for glucose monitoring platforms. Japanese pharmaceutical companies prioritize radiation-stable grades for transdermal patch backings. Chinese device manufacturers scale thermal laminating capacity for high-volume wearable production.
United States
Hospital group purchasing organizations consolidate sterile packaging specifications across multi-hospital networks in the US Midwest. FDA updated biocompatibility testing protocols for polymer-based medical materials reshape product qualification timelines. IDN procurement teams in Illinois and Ohio compress qualified suppliers from twelve to four vendors per film category.
Germany
Precision film converters cluster around the Rhine-Main manufacturing corridor to enable rapid prototyping-to-scale transitions for European medical device OEMs. REACH Annex XVII restrictions on phthalate plasticizers force reformulation toward citrate and trimellitate ester alternatives. Wound care manufacturers near Ludwigshafen accelerate supplier audits to secure compliant raw material pipelines.
Japan
Pharmaceutical companies adopt polyester backings for controlled-release transdermal patch platforms at accelerating rates. PMDA enforces ISO 10993 biocompatibility standards for polymer films contacting human tissue. METI supports domestic film extrusion expertise retention through targeted workforce development in Kansai industrial zones.
China
Asian device manufacturers scale thermal laminating operations for high-volume wearable therapeutic production. NMPA aligns medical device component regulations with international biocompatibility frameworks. Yangtze River Delta converters expand cast film capacity to serve diagnostic consumable export demand.
South Korea
MFDS qualification requirements drive premium-grade polyester adoption for sterile barrier applications in domestic hospital systems. Seoul-based film processors invest in electron-beam sterilization compatibility testing to capture device manufacturer qualification windows. Busan-Ulsan chemical complexes supply purified terephthalic acid feedstock to regional medical-grade film operations.
Polyester Medical Films Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in polyester medical films. Captive resin-to-film operations distinguish the upper tier from toll-dependent processors. Three archetypes dominate: aromatic polyester research specialists, vertically integrated resin producers, and precision toll converters clustered near pharmaceutical manufacturing corridors. Competitive moves concentrate on backward integration into monomer supply and multilayer coextrusion technology licensing.
Within the integrated leader tier, Teijin and DuPont exemplify divergent geographic anchoring strategies. Teijin occupies a position representing Japanese aromatic polyester research legacy applied to high-performance medical grades. DuPont anchors North American supply through in-house resin-to-film production control. SKC sits within the Asian scale-driven archetype, competing on thermal laminating capacity for device manufacturers. These three entities collectively illustrate how regional manufacturing corridor proximity shapes competitive positioning.
| Leading Market Players |
|---|
| Teijin |
| Tekra Corporation |
| Toray Industries |
| Futamura Chemicals |
| Cosmo Films |
| DuPont |
| Mitsubishi Chemicals |
| SKC |
| 3M |
| Others |
Value Network & Pricing Analysis
Capacity utilization at biaxial orientation lines near Ludwigshafen shapes both supply concentration and price floors for medical-grade polyester films, as toll converters extract premiums from device manufacturers lacking qualified secondary sources. German wound care OEMs face escalating feedstock costs as purified terephthalic acid pricing volatility compresses margin structures for non-integrated processors.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement relationships between hospital group purchasing organizations and qualified film suppliers, with three-year supply locks replacing annual spot purchasing. Price differentiation hinges on ISO 10993 certification tier and volume scale, with premium grades commanding substantial uplifts over standard medical variants. Cost compression in flexible film tiers is intensifying because REACH-mandated phthalate substitutions extend qualification timelines without corresponding price recovery. Research institutions exhibit highest price sensitivity due to fragmented lot sizes, while multi-hospital IDNs leverage procurement consolidation to extract volume-tier concessions.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for ethylene glycol feedstock arriving from Middle Eastern petrochemical complexes, compressing converter margins before production begins. Manufacturing gravity centers on Germany, Japan, and South Korea, with the Rhine-Main corridor hosting precision film extrusion expertise unavailable elsewhere. Raw material dependencies draw from purified terephthalic acid, ethylene glycol, and specialized silicone coating chemistries. Single-source vulnerability concentrates among three mid-scale toll converters near Ludwigshafen, creating qualification bottlenecks for European device OEMs. Distribution runs through medical device component distributors and direct mill relationships with tier-one hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyester medical films market sits in early-stage cyclical recovery as hospital capital expenditure normalization restores procurement velocity for sterile barrier applications. Device manufacturer inventory restocking across the US Midwest and German wound care corridors validates demand trajectory.
For Market Incumbents: Consolidate biaxial orientation engineering expertise through targeted retention programs and technical apprenticeship pipelines, as sequential stretching process knowledge resides with a narrowing cohort of legacy PET packaging technicians. Deepen backward integration into purified terephthalic acid supply through long-term offtake agreements with Busan-Ulsan chemical complexes, mitigating margin compression from feedstock volatility. Prioritize electron-beam sterilization compatibility certification to capture device manufacturer qualification windows as ethylene oxide alternatives accelerate.
For New Entrants and Emerging Players: Differentiate on transdermal patch backing specialization, where pharmaceutical companies demand silicone-coated functionalized films with precise adhesion profiles and qualification timelines remain fluid. Target laboratory diagnostic consumable segments in the Yangtze River Delta, where sub-25-micrometer specifications for glucose monitoring platforms offer white-space expansion with less entrenched incumbent relationships. Pursue co-development partnerships with Asian device manufacturers scaling thermal laminating operations for wearable therapeutic production.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision toll converters with captive biaxial orientation lines and established ISO 10993 regulatory dossiers, as qualification barriers protect returns through the analysis window. Long-term viability hinges on electron-beam sterilization compatibility and multilayer coextrusion licensing positions. Monitor FDA biocompatibility protocol harmonization progress as inflection indicator for geographic expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Multilayer Coextrusion Licensing | Enables wearable device miniaturization for diagnostic OEMs specifying sub-25-micrometer constructions. |
| Electron-Beam Sterilization Qualification | Captures device manufacturer migration from ethylene oxide residue concerns toward radiation-stable grades. |
| Backward Integration into Monomer Supply | Insulates margin structures from purified terephthalic acid pricing volatility at Ludwigshafen converters. |
| Non-Orthophthalate Formulation Validation | Secures REACH Annex XVII compliance for German wound care manufacturers ahead of enforcement deadlines. |
| Hospital System Partnership Expansion | Locks in three-year supply agreements with IDN procurement teams consolidating qualified vendor pools. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital GPO contracts managers, film extrusion technicians, and pharmaceutical packaging specialists anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, SEC 10-K disclosures from integrated resin producers, and German chemical industry association capacity reports. Bottom-up demand modeling across wound care, drug delivery, and diagnostic applications triangulated against top-down macroeconomic healthcare expenditure projections.
Sensitivity analysis tested forecast robustness across sterilization method adoption scenarios, REACH enforcement timelines, and hospital procurement consolidation trajectories over the projection horizon. Segmentation dimensions modeled include product transparency grade, end-user procurement scale, application barrier performance requirements, and biaxial orientation process technology. CAGRs derived from installed base erosion rates, replacement demand elasticity, and penetration assumptions for transdermal patch platforms. Industry-specific inputs incorporated gamma sterilization compatibility testing costs and silicone coating functionalization yield curves.
The analysis sits within stated boundaries; outcomes outside FDA-EU MDR regulatory harmonization progress or sustained purified terephthalic acid supply stability would require recalibration. Forecasts reflect documented assumptions regarding hospital capital expenditure recovery velocity and pharmaceutical patch platform adoption rates. Recalibration cycles align with material shifts in biocompatibility testing protocol updates and sterilization infrastructure investment patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
United States Neoprene Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Elastic Films Market
Specialty Materials
India Collagen Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Engineered Foam Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
Fumed Silica Market
Specialty Materials
Nanoencapsulation Market
Specialty Materials
Magnesium Fluoride Market
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Reflective Polarizing Films Market
Specialty Materials
Polyetherimide (PEI) Market