
 Open Cell Foam Market | 2026-2036
Open Cell Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Open Cell Foam Market Analytics
China is narrowing the cost-efficiency gap in open cell foam production through expanded TDI and polyether polyol capacity. BASF SE leverages integrated petrochemical feedstocks to sustain margin stability across polyurethane foam grades. Huntsman International LLC anchors its position through differentiated aromatic amine catalyst technologies. Covestro AG competes on bio-attributed polyol platforms that address downstream sustainability procurement criteria.
Open cell foam contains interconnected pores that permit air and moisture permeability, typically manufactured through controlled foaming of polyurethane, melamine, or latex precursors with cell-opening agents added post-expansion. The material functions primarily as acoustic absorption media, thermal insulation barriers, and cushioning substrates where breathability prevents heat or moisture entrapment. Polyurethane foam occupies the largest value share due to its tunable density range and established supply chains across construction and automotive end uses. Melamine foam represents the fastest-expanding category, driven by fire-retardant building codes and lightweight transit interior specifications. Soundproofing applications concentrate margin pools in aerospace and rail OEM qualification programs where certification timelines create supply stickiness.
EPA VOC emission standards under TSCA Title VI constrain formaldehyde-containing formulations in US furniture and construction applications. REACH SVHC restrictions and the EU Green Deal carbon border adjustments are redirecting European manufacturers toward bio-based feedstock certifications. China's GB standards on indoor air quality and MEE enforcement of foam plant emissions shape production location decisions for exporters. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualify for green procurement tenders.
Market Dynamics
REACH SVHC restrictions and EPA TSCA Title VI compliance are forcing polyurethane foam reformulation across automotive seating and furniture supply chains, redirecting procurement toward bio-attributed polyol platforms and certified low-emission grades.
Growth Catalysts
- Automotive cabin noise regulations:Stricter NVH standards in Germany and Japan are expanding polyurethane foam purchases for acoustic insulation in vehicle interiors.
- Urban retrofit programs:China's construction sector is accelerating melamine foam deployment for building insulation as energy efficiency mandates tighten.
- Bio-based polyol technology:Advances in renewable feedstock chemistry are qualifying foam producers for EU Green Deal procurement tenders and carbon border adjustment exemptions.
Market Restraints
- TDI feedstock volatility:Toluene diisocyanate price swings constrain margin stability for polyurethane foam manufacturers dependent on petrochemical supply chains.
- Supply concentration in China:Overreliance on domestic TDI and polyether polyol capacity creates vulnerability to MEE enforcement actions and export quota fluctuations.
- Formaldehyde substitution limits:EPA VOC emission standards under TSCA Title VI eliminate certain legacy formulations without fully cost-competitive alternatives for furniture applications.
Strategic Opportunities
- Aerospace certification programs:OEM qualification timelines for acoustic foam create supply stickiness and multi-year contract visibility for qualified suppliers.
- Rail interior specifications:Lightweight fire-retardant melamine foam demand is expanding across transit infrastructure projects in France and Germany.
- Construction sector pivot:China's GB standards on indoor air quality are opening specification windows for low-emission foam grades in commercial building retrofits.
Industry Challenges
- Certification timeline compression:Aerospace and rail OEM qualification programs require 18-36 month validation cycles that strain R&D resource allocation.
- Formulation chemistry expertise:Shortage of polyurethane catalyst specialists limits producer ability to execute REACH-compliant reformulation at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Open Cell Foam Market |
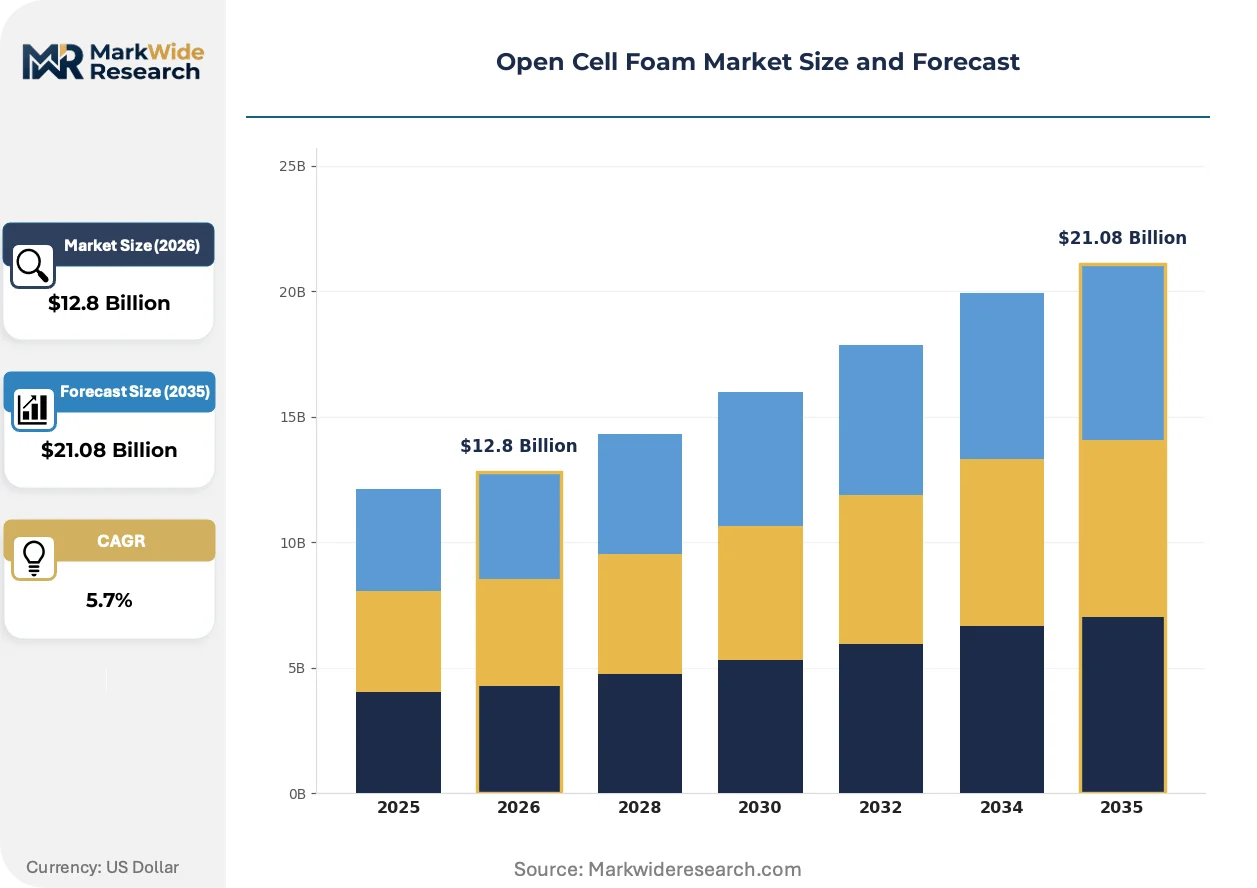
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Melamine Foam, Latex Foam, PVC Foam Application: Soundproofing, Thermal Insulation, Packaging, Upholstery End User: Construction, Automotive, Electronics, Furniture Density: Low Density, Medium Density, High Density, Ultra High Density |
| Companies Covered | BASF SE, Owens Corning, Huntsman International LLC, Armacell International SA, Dow Inc., Johns Manville, CertainTeed, LLC, Covestro AG, PPG Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Open Cell Foam Market Evolving Landscape
Bio-attributed polyol platforms and automated foam-cutting systems are compressing production economics while regulatory divergence between jurisdictions is fragmenting formulation strategies across regional supply chains.
Water-blown polyurethane systems are replacing traditional HFC-based blowing agents in automotive seating and construction insulation applications. Tier 1 suppliers in Germany and Japan are qualifying these grades for 2025 model year programs. This chemistry transition is collapsing the cost premium between low-GWP formulations and conventional foam grades, accelerating adoption curves.
REACH SVHC restrictions on aromatic amine catalysts are compelling European foam producers to validate alternative cure chemistry by 2026. The industrial consequence is a supply bottleneck for qualified polyurethane grades during the transition window. Furniture and mattress manufacturers in Italy and Poland are stockpiling legacy formulations while certifying bio-attributed replacements.
Buyers in China's construction sector are consolidating procurement around certified low-emission foam grades that satisfy both GB indoor air quality standards and export market REACH requirements. Direct contracting between state-owned developers and integrated chemical producers is displacing distributor-mediated spot purchasing. This concentration is most visible in Shanghai and Beijing commercial retrofit programs where single-source supply agreements now dominate specification decisions.
Open Cell Foam Market Segmentation
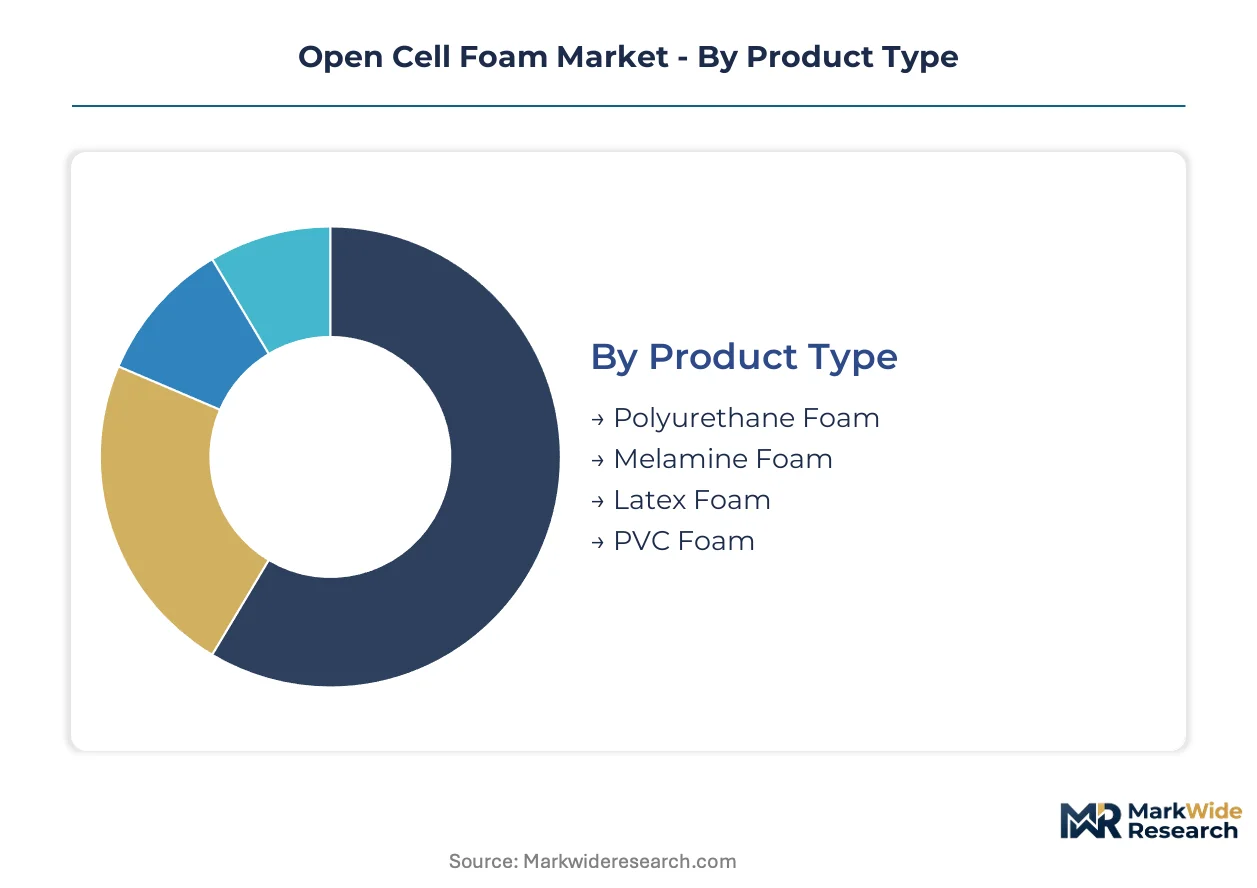
Segmentation in the Open Cell Foam Market reveals distinct margin profiles and technical qualification requirements across product chemistry, application intensity, and density specifications. Procurement patterns diverge sharply between automotive OEMs demanding certified acoustic grades and construction contractors prioritizing cost-efficient thermal barriers.
Product Type:
After-sales service intensity varies dramatically by foam chemistry, with polyurethane requiring formulation troubleshooting support and melamine demanding fire-performance certification maintenance.
- Polyurethane Foam:Manufactured through TDI or MDI reaction with polyether polyols, this chemistry permits density tuning from 16 to 80 kg/m³ for load-bearing or acoustic applications. Automotive seating manufacturers in Germany and Japan source certified low-VOC grades to meet cabin air quality mandates, with reformulation services bundled into multi-year supply contracts.
- Melamine Foam:Thermoset formaldehyde-melamine-sodium bisulfite copolymer yields open-cell structures with inherent fire retardancy and lightweight properties below 10 kg/m³. China's urban retrofit programs in Shanghai and Beijing specify melamine for commercial building insulation, with contractors requiring installation training and performance warranties.
- Latex Foam:Natural rubber-derived or synthetic SBR-based cellular structures serve premium mattress and upholstery segments with inherent antimicrobial properties.
- PVC Foam:Closed-cell dominant but open-cell variants serve marine flotation and specialty packaging with chemical resistance profiles.
By volume, polyurethane foam leads. By growth pace, melamine foam is ahead.
Application:
Application segmentation tracks capital intensity divergence between infrastructure-linked projects and consumer discretionary purchases.
- Soundproofing:Acoustic absorption coefficients drive specification in aerospace cabin liners, rail car interiors, and automotive NVH packages. OEM qualification programs for Boeing and Airbus create 18-36 month validation cycles that lock in supplier relationships.
- Thermal Insulation:Lambda values below 0.035 W/mK position open-cell grades for building envelope applications where breathability prevents moisture accumulation. China's GB standards enforcement is redirecting procurement toward certified low-emission polyurethane in Beijing commercial retrofits.
- Packaging:Electronics and medical device sectors utilize static-dissipative polyurethane for sensitive component protection.
- Upholstery:Furniture manufacturers in Italy and Poland balance REACH-compliant reformulation against legacy formulation stockpiles.
Soundproofing commands premium pricing through certification barriers. Thermal insulation offers the broadest volume base.
End User:
End-user segmentation reflects divergent procurement sophistication between specification-driven OEMs and price-sensitive contractors.
- Construction:State-owned developers in China consolidate procurement through direct contracts with integrated chemical producers, displacing distributor channels. Energy efficiency mandates in France and Germany expand melamine foam deployment in transit infrastructure.
- Automotive:Tier 1 seating suppliers qualify water-blown polyurethane systems for 2025 model year programs, collapsing cost premiums against HFC-based alternatives. NVH regulations in Japan and Germany drive acoustic foam purchases.
- Electronics:Precision packaging requirements favor static-controlled polyurethane formulations for semiconductor transport.
- Furniture:EPA TSCA Title VI and REACH SVHC restrictions force reformulation of formaldehyde-containing legacy grades.
Construction dominates volume throughput. Automotive delivers the highest margin per kilogram.
Density:
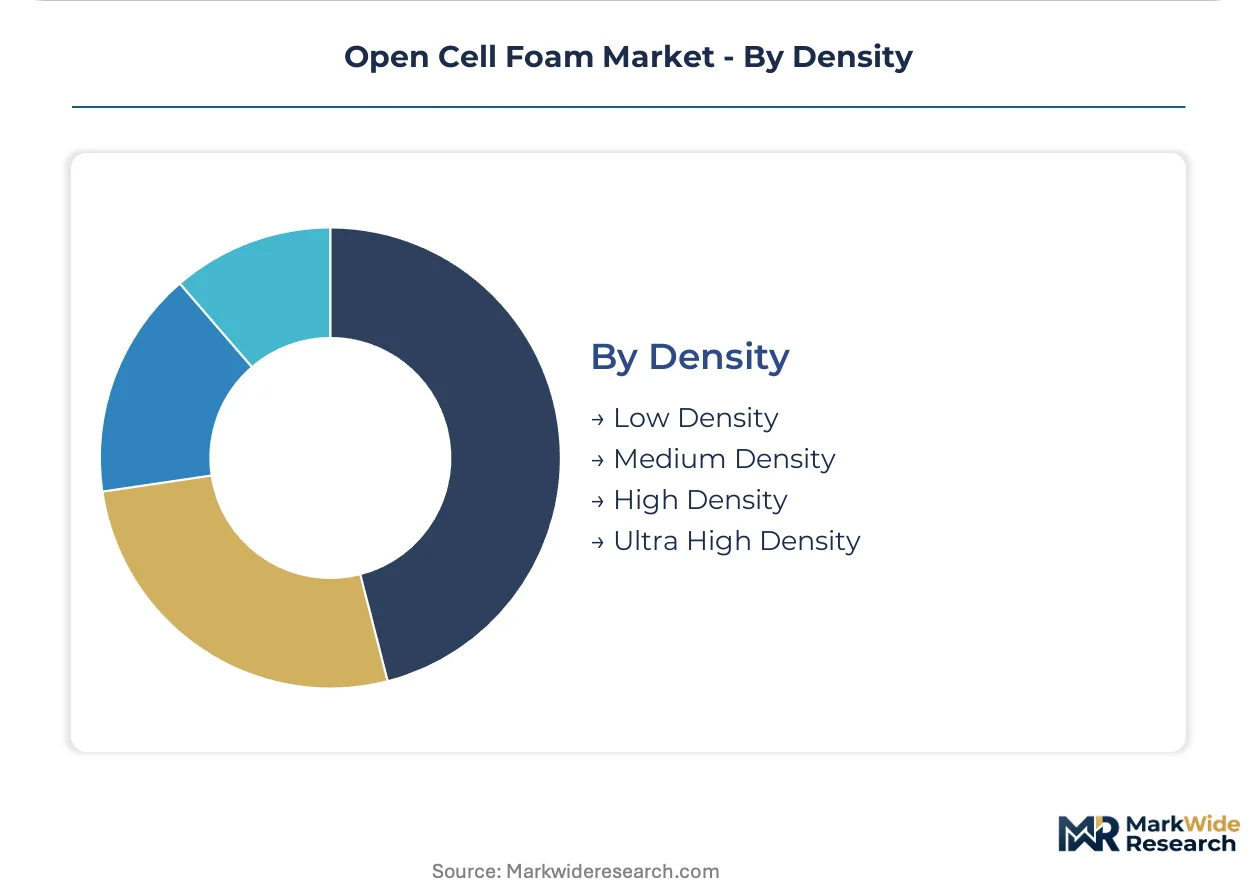
Density tiering aligns with load-bearing requirements and acoustic performance specifications across end-use segments.
- Low Density:Below 20 kg/m³ structures serve lightweight packaging and disposable cushioning where compressive strength is secondary.
- Medium Density:20-40 kg/m³ range balances acoustic absorption with structural integrity for automotive seating and mattress cores.
- High Density:40-80 kg/m³ grades support load-bearing upholstery and precision soundproofing in aerospace applications.
- Ultra High Density:Above 80 kg/m³ formulations serve specialty industrial seals and heavy-duty cushioning with extended duty cycles.
Medium density captures the widest application range. Ultra high density maintains the steepest expansion trajectory in aerospace qualification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE enforcement actions in China redirect export-oriented capacity toward domestic retrofit programs while REACH SVHC restrictions in Europe and EPA TSCA Title VI compliance in the United States fragment formulation strategies across three regulatory jurisdictions.
China
State-owned developers in Shanghai and Beijing consolidate procurement around certified low-emission polyurethane grades for commercial building retrofits. GB standards on indoor air quality and MEE emissions enforcement reshape production location decisions for exporters targeting European markets. Yangtze River Delta chemical producers expand TDI and polyether polyol capacity to narrow cost-efficiency gaps against integrated multinational supply chains.
Germany
Tier 1 automotive seating suppliers qualify water-blown polyurethane systems for 2025 model year programs to meet stricter NVH cabin noise regulations. REACH SVHC restrictions on aromatic amine catalysts compel foam producers to validate alternative cure chemistry by 2026. Industrial clusters in North Rhine-Westphalia and Bavaria anchor reformulation services bundled into multi-year supply contracts with furniture manufacturers in Italy and Poland.
United States
EPA TSCA Title VI constrains formaldehyde-containing formulations in furniture and construction applications, eliminating certain legacy grades without fully cost-competitive alternatives. Aerospace OEM qualification programs for Boeing create 18-36 month validation cycles that lock in supplier relationships for acoustic foam grades. Pacific Northwest and Southeast construction markets pivot toward low-VOC insulation materials as state-level energy efficiency mandates tighten.
Japan
METI-driven NVH standards expand polyurethane foam purchases for automotive acoustic insulation as domestic manufacturers respond to Germany-Japan regulatory convergence on cabin air quality. JIS standards certification creates supply stickiness for qualified grades in rail interior specifications. Kanto and Kansai industrial corridors concentrate procurement sophistication among specification-driven automotive Tier 1s.
France
EU Green Deal carbon border adjustments redirect manufacturers toward bio-based feedstock certifications for construction and transit infrastructure applications. Lightweight fire-retardant melamine foam demand expands across rail interior projects coordinated with German cross-border supply chains. Île-de-France and Auvergne-Rhône-Alpes clusters specialize in aerospace acoustic qualification programs serving Airbus supply networks.
Open Cell Foam Market Competitive Landscape
Integrated petrochemical conglomerates and specialized foam fabricators split the market between margin-stable feedstock control and application-specific certification expertise. Three archetypes dominate: multinational chemical producers with backward integration into TDI and polyol supply, regional foam converters with OEM qualification track records, and bio-attributed platform specialists addressing sustainability procurement criteria. Competitive moves concentrate on strategic partnerships for catalyst technology access and capacity expansion in Chinese TDI corridors.
Within the integrated chemical tier, BASF SE and Covestro AG exemplify feedstock-anchored positioning across polyurethane foam grades. Huntsman International LLC occupies a specialist position through aromatic amine catalyst technologies. Among diversified materials conglomerates, Dow Inc. and Owens Corning represent cross-sector foam exposure spanning construction and automotive end uses. Armacell International SA sits within the technical insulation specialist archetype serving OEM qualification programs.
| Leading Market Players |
|---|
| BASF SE |
| Owens Corning |
| Huntsman International LLC |
| Armacell International SA |
| Dow Inc. |
| Johns Manville |
| CertainTeed, LLC |
| Covestro AG |
| PPG Industries, Inc. |
| Others |
Value Network & Pricing Analysis
Chinese TDI and polyether polyol capacity concentration anchors margin capture for integrated petrochemical producers while compressing formulation economics for regional foam converters dependent on spot feedstock procurement. Polyurethane foam pricing stratifies across aerospace-certified grades, automotive NVH specifications, and construction thermal barriers with distinct margin pools tied to qualification timelines.
Pricing Analysis
Geographic price spreads between Yangtze River Delta production hubs and European automotive Tier 1s reflect certification grade premiums and REACH compliance bundling. Three-tier pricing structure separates aerospace-qualified acoustic foam from automotive NVH grades and commodity construction insulation. Cost compression in standard-density polyurethane intensifies as water-blown systems collapse historical premiums against HFC-based alternatives. Furniture manufacturers in Italy and Poland exhibit highest price sensitivity due to formaldehyde substitution pressures, while aerospace OEMs accept premium positioning for 18-36 month qualification lock-in.
Supply Chain Analysis
Tariff exposure between China and European Union member states dominates supply chain risk planning for exporters navigating carbon border adjustment mechanisms. Manufacturing gravity centers on China, Germany, and Japan with feedstock production concentrated in Yangtze River Delta and North Rhine-Westphalia chemical corridors. Raw material flows draw from toluene diisocyanate, polyether polyols, and melamine-formaldehyde precursors with limited qualified alternative sources. Single-source vulnerability persists for aromatic amine catalysts subject to REACH SVHC restrictions. Distribution runs through direct contracting between state-owned developers and integrated producers in China, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polyurethane catalyst expertise and bio-attributed polyol certification capabilities represent binding constraints that reshape competitive outcomes across automotive seating and construction insulation procurement cycles.
For Market Incumbents: Insulate margin stability through captive TDI and polyol supply in Yangtze River Delta corridors while accelerating bio-based feedstock certification to qualify for EU Green Deal procurement tenders. Defensive consolidation around aromatic amine catalyst technology access addresses formulation chemistry expertise shortages threatening REACH-compliant reformulation at scale. For New Entrants and Emerging Players: Build out melamine foam production capacity serving China's urban retrofit programs in Shanghai and Beijing where direct state-owned developer contracting creates specification windows outside established distributor relationships. Target rail interior specifications across French and German transit infrastructure projects as the most penetrable segment given lightweight fire-retardant demand expansion and cross-border supply chain coordination requirements. For Investors and Strategic Acquirers: Capital is best deployed toward technical insulation specialists with established OEM qualification track records in aerospace and rail applications where certification timelines create multi-year contract visibility and supply stickiness. Long-term viability hinges on bio-attributed platform positioning as carbon border adjustments and sustainability procurement criteria harden across European and Asian markets. Monitor MEE enforcement actions and export quota fluctuations as early signals of Chinese capacity redirection toward domestic retrofit programs versus export availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into TDI Feedstock | Captive supply from Yangtze River Delta producers insulates margin stability against petrochemical volatility. |
| Bio-Attributed Polyol Certification | REACH-compliant platforms qualify producers for EU Green Deal carbon border adjustment exemptions. |
| Aerospace OEM Qualification Program | Boeing and Airbus validation cycles lock in 18-36 month supplier relationships with premium positioning. |
| Direct Contracting with State-Owned Developers | Shanghai and Beijing retrofit programs displace distributor channels for certified low-emission grades. |
| Water-Blown System Transition | German and Japanese Tier 1s qualify these grades for 2025 model year programs, collapsing cost premiums. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and GB standards documentation. Interviews with polyurethane plant managers, automotive Tier 1 procurement leads, construction contractor purchasing heads, and technical R&D directors at foam converters informed supply chain and pricing dynamics. Bottom-up segment sizing across product chemistry, application intensity, and density specifications triangulates against top-down macroeconomic indicators.
Forecast inputs incorporate modeled expansion across polyurethane, melamine, and latex chemistry tiers with end-use segmentation spanning construction, automotive, aerospace, and furniture applications. The analytical framework evaluates water-blown system adoption curves, REACH SVHC reformulation timelines, and MEE enforcement intensity throughout the projection horizon. CAGRs derive from elasticity-adjusted demand modeling against regulatory compliance deadlines and OEM program launch cycles.
Practitioners should monitor aromatic amine catalyst substitution progress, carbon border adjustment implementation timing, and Chinese export quota announcements for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Global Ajinomoto Build-Up Film Substrate Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Solar Backsheet Films Market
Specialty Materials
Global Beeswax Market
Specialty Materials
Global PE Films Market
Specialty Materials
Gutta-Percha Market
Specialty Materials
Light Diffusion Materials Market
Specialty Materials
Silicone Gel Market
Specialty Materials
Specialty Carbon Black Market
Specialty Materials
Global Liquid Crystal Polymer (LCP) Films and Laminates Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Electroactive Polymers (EAP) Market
Specialty Materials
Europe Microspheres Market
Specialty Materials
Medical Injection Molded Plastics Market
Specialty Materials
Lab Grown Diamonds Market
Specialty Materials
Global Cellulose Acetate Market