
 Colloidal Silica Market | 2026-2036
Colloidal Silica Market Size, Share, and Industry Trends Forecast 2026-2036
Colloidal Silica Market Analysis
Japanese chemical producers is rebalancing regional colloidal silica supply following capacity rationalization at legacy sites. Nissan Chemical Corporation leverages its proprietary sol-gel technology to sustain premium positioning in semiconductor-grade materials. Evonik Industries anchors European supply through integrated fumed silica operations at its Rheinfelden complex. Cabot Corporation competes aggressively in foundry CMP slurries through dedicated Asian distribution infrastructure.
Colloidal silica comprises nanoscale amorphous silicon dioxide particles dispersed in aqueous or organic media, typically manufactured via ion-exchange or hydrolysis of sodium silicate with particle sizes ranging from five to one hundred nanometers. The material functions primarily as a surface-modifying agent, providing abrasive, binding, or anti-soiling properties across industrial formulations. Spherical silica commands the dominant share in electronics applications due to its uniform particle geometry enabling precise wafer polishing. Precipitated silica retains mature volume positions in paints and coatings, though margin pools have compressed amid raw material volatility. Fumed silica differentiation concentrates in high-purity pharmaceutical and personal care segments where regulatory barriers protect pricing.
EPA effluent guidelines and REACH substance restrictions shape formulation chemistry by limiting residual sodium and heavy metal content in commercial grades. FDA oversight of pharmaceutical excipients and semiconductor-grade purity standards enforced by SEMI further segment market access by certification tier. Stakeholders must monitor evolving dual-use export controls on advanced materials and foundry localization policies that redirect supply chain sourcing decisions.
Market Dynamics
Semiconductor foundry localization policies and tightening purity standards are restructuring colloidal silica procurement, forcing suppliers to rebuild certification portfolios around SEMI-grade specifications and dual-use export control compliance.
Growth Catalysts
- SEMI purity mandates:Semiconductor-grade specifications now require sub-ppb metallic impurity levels, locking qualified suppliers into long-term foundry supply agreements.
- Taiwan foundry expansion:TSMC and UMC capacity additions in Tainan and Taichung are pulling premium colloidal silica volumes for 3nm and 2nm node CMP processes.
- EU Green Deal chemistry restrictions:REACH Annex XVII amendments on silicate process residues are accelerating substitution toward aqueous sol-gel routes.
Market Restraints
- Sodium silicate feedstock volatility:Energy-intensive fusion furnace operations concentrate input cost exposure for precipitated silica manufacturers.
- East Asian supply concentration:Over seventy percent of electronics-grade spherical silica originates from Japanese and South Korean chemical complexes, creating single-source vulnerability.
- Fumed silica technical ceiling:Pyrogenic particle morphology limits surface area tunability below 200 square meters per gram for sub-50nm semiconductor applications.
Strategic Opportunities
- India PLI scheme for semiconductors:Domestic fabs in Gujarat and Karnataka will require localized colloidal silica supply chains absent today.
- Battery separator coatings:Ceramic-coated polyethylene membranes for lithium-ion cells represent a high-volume outlet for tailored particle size distributions.
- MEE wastewater standards:China's stricter effluent discharge limits on silica processing plants are creating first-mover advantage for closed-loop aqueous sol-gel operators.
Industry Challenges
- SEMI S2-S8 certification timelines:Equipment safety and environmental baseline documentation for new foundry suppliers extends eighteen to thirty-six months.
- Legacy sodium silicate asset stranding:Ion-exchange purification lines require full rebuilds to meet sub-10nm node contamination thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colloidal Silica Market |
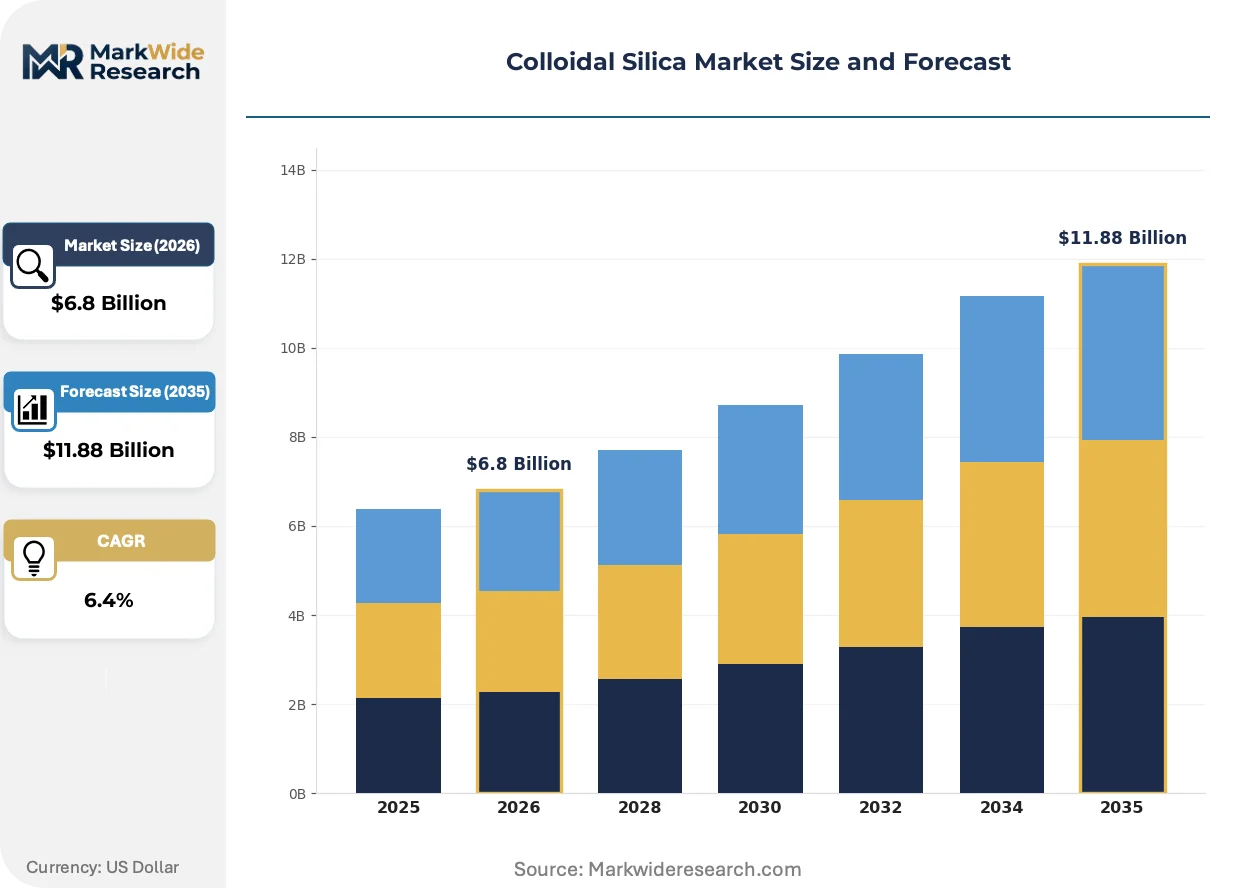
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spherical Silica, Fumed Silica, Precipitated Silica, Micronized Silica Application: Paints, Coatings, Adhesives, Sealants End User: Construction, Electronics, Pharmaceuticals, Personal Care Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Nissan Chemical Corporation, Merck KGaA, Evonik Industries, Cabot Corporation, Ecolab, Nouryon, FUSO CHEMICAL CO., LTD., ADEKA Corporation, W. R. Grace & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colloidal Silica Market Emerging Trajectories
Colloidal silica manufacturing is pivoting from commodity sodium silicate hydrolysis toward precision sol-gel platforms, with particle size distribution control becoming the primary competitive differentiator across electronics and pharmaceutical segments.
Monodisperse spherical silica synthesized via Stöber process variants is consolidating quality-tier supply for sub-7nm CMP slurries. Foundry material qualification teams at Samsung and Intel are narrowing approved supplier lists to three sol-gel specialists. This consolidation is compressing margins for legacy precipitated silica operations unable to meet particle uniformity specifications.
REACH authorization requirements for crystalline silica content are forcing reformulation of construction-grade colloidal additives. ECHA's 2023 harmonized classification triggered downstream user notification obligations across coating and adhesive formulators. German and French industrial paint manufacturers are accelerating migration to fully amorphous sol-gel alternatives ahead of 2026 sunset dates.
Long-term supply agreements now dominate procurement for semiconductor-grade material, displacing spot market transactions. Foundry procurement teams at TSMC and GlobalFoundries are locking five-year contracts with price-volume bands. This shift is most visible in Taiwan and South Korea, where foundry concentration permits supplier consolidation and technical co-development programs.
Colloidal Silica Market Segmentation
Colloidal silica segmentation tracks divergent purity requirements across semiconductor CMP slurries, pharmaceutical excipients, and construction additives. Each segment demands distinct particle morphology, surface chemistry, and certification tiers that reshape supplier capabilities and margin structures.
Product Type:
Particle geometry and synthesis route determine functional performance across electronics polishing, rheology modification, and binding applications.
- Spherical Silica:Monodisperse amorphous particles synthesized via Stöber or sol-gel routes deliver uniform abrasion for sub-7nm wafer planarization. TSMC and Samsung foundries in Taiwan and South Korea lock multi-year supply agreements for SEMI-grade spherical material.
- Fumed Silica:Pyrogenic silica produced by flame hydrolysis of silicon tetrachloride exhibits high surface area and thickening efficiency. Pharmaceutical formulators in Germany and Switzerland specify fumed grades for topical gel viscosity control under EMA excipient guidelines.
- Precipitated Silica:Sodium silicate acidification yields lower-cost amorphous particles for rubber reinforcement and paint matting. Mature volume positions in automotive coatings face margin compression from energy-intensive furnace operations.
- Micronized Silica:Mechanical milling of quartz or diatomaceous earth produces sub-micron particles for industrial sealants and construction adhesives. REACH crystalline silica restrictions are accelerating substitution toward synthetic amorphous alternatives.
Precipitated silica leads on scale; spherical silica leads on momentum.
Application:
Formulation chemistry requirements segment demand by film thickness control, adhesion promotion, and rheology modification intensity.
- Paints:Matting agents and sag control additives leverage colloidal silica's thixotropic properties. German industrial paint manufacturers reformulate toward fully amorphous sol-gel grades ahead of ECHA crystalline silica sunset dates.
- Coatings:Anti-corrosion primers and UV-curable clearcoats specify surface-modified silica for scratch resistance. Electronics conformal coatings for PCBs in Japan and South Korea demand ultra-low ionic content.
- Adhesives:Structural bonding formulations incorporate precipitated silica for viscosity build and moisture resistance. Automotive assembly plants in the US Midwest specify thixotropic rheology for automated dispensing lines.
- Sealants:Construction silicone and polyurethane sealants use micronized silica as reinforcing filler. EPA VOC regulations are pushing waterborne sealant growth that favors hydrophilic silica surface treatments.
Coatings command premium pricing; sealants expand most quickly in construction recovery cycles.
End User:
Regulatory certification tiers and purity thresholds segment end-use markets by qualification timeline and technical barrier height.
- Electronics:Semiconductor CMP slurries and PCB coatings require sub-ppb metallic impurity levels under SEMI standards. Taiwan foundry clusters consume the highest-grade spherical silica volumes for 3nm node production ramps.
- Pharmaceuticals:Oral solid dosage and topical formulations specify USP-NF or Ph.Eur. compliant excipient grades. FDA Type II drug master file submissions lock qualified suppliers into multi-year supply relationships.
- Construction:Cement admixtures and waterproofing systems use standard-grade precipitated silica for rheology control. China's MEE wastewater standards are forcing foundry-adjacent construction chemical plants toward closed-loop silica processing.
- Personal Care:Cosmetic thickeners and toothpaste abrasives demand low-irritation amorphous silica with controlled particle size. South Korean beauty manufacturers specify sol-gel spherical grades for optical diffusion in premium skincare.
Construction leads on volume scale; electronics leads on specification intensity and contract duration.
Distribution Channel:
Customer scale and technical service requirements determine channel selection across foundry procurement teams, regional formulators, and retail consumers.
- Direct Sales:Semiconductor-grade material moves through technical account teams co-located at foundry sites. Long-term agreements with TSMC and Intel bypass intermediaries for contamination-controlled logistics.
- Distributors:Regional chemical distributors stock precipitated and fumed grades for mid-tier paint and adhesive manufacturers. German distributors like Brenntag maintain blending facilities for customized particle size cuts.
- Wholesalers:Construction-grade micronized silica flows through building material wholesalers serving regional contractors. Price-sensitive volume procurement favors consolidated freight and inventory pooling.
- Online Retail:Laboratory-scale quantities and cosmetic DIY formulations sell through specialized chemical e-commerce platforms. Personal care ingredient suppliers in India leverage B2B marketplaces for small-batch pharmaceutical-grade orders.
Distributors dominate mid-market access; direct sales capture the steepest expansion trajectory in semiconductor-grade supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting colloidal silica investment toward jurisdictions with streamlined chemical permitting, while legacy production sites in high-compliance economies face asset-stranding risks from tightening purity mandates.
United States
Domestic foundry construction in Arizona and Texas is pulling semiconductor-grade material volumes. EPA effluent guidelines on silica processing residues limit expansion at legacy sodium silicate sites. The Phoenix-Tucson corridor hosts emerging CMP slurry blending operations serving Intel's Fab 52 and Fab 62 ramps.
Germany
Specialty chemical producers supply pharmaceutical-grade fumed silica under EMA excipient guidelines. REACH Annex XVII crystalline silica restrictions force reformulation timelines across industrial coatings. The Rheinfelden complex anchors integrated fumed silica capacity with captive chlorine chemistry.
Japan
Proprietary sol-gel technology holders serve premium semiconductor applications with sub-ppb metallic impurity specifications. METI's critical materials designation secures supply chain priority for domestic foundry customers. The Kanto region concentrates particle synthesis R&D alongside Tokyo Electron process equipment co-development.
South Korea
Samsung and SK Hynix memory expansion drives spherical silica consumption for advanced node CMP. MFDS pharmaceutical excipient regulations shape export qualification pathways for personal care grades. The Yongin-Suwon corridor hosts dedicated colloidal silica distribution infrastructure for foundry just-in-time delivery.
China
Domestic battery separator coating demand is emerging as a high-volume outlet for tailored particle size distributions. MEE wastewater discharge limits on silica processing plants favor closed-loop aqueous sol-gel operators over legacy precipitation routes. The Yangtze River Delta concentrates construction-grade precipitated silica capacity serving regional coatings manufacturers.
Colloidal Silica Market Vendor Landscape
Japanese producers anchor the premium semiconductor-grade tier; German and US specialists hold positions in pharmaceutical and industrial segments. Market structure reflects a bifurcation between sol-gel technology leaders qualified for sub-7nm foundry supply and commodity precipitation operators facing margin compression. Three archetypes dominate: integrated chemical conglomerates with captive silicon tetrachloride feedstock, independent sol-gel specialists with proprietary particle size control, and regional distributors with blending and technical service capabilities. Capacity expansion and long-term foundry qualification partnerships represent the dominant competitive moves.
Among Japanese chemical conglomerates, Nissan Chemical Corporation and FUSO CHEMICAL CO., LTD. occupy positions reflecting sol-gel technology heritage and foundry supply relationships. Merck KGaA exemplifies the European pharmaceutical-grade specialist archetype with excipient certification depth. Evonik Industries anchors the integrated fumed silica model with backward control over chlorosilane chemistry.
| Leading Market Players |
|---|
| Nissan Chemical Corporation |
| Merck KGaA |
| Evonik Industries |
| Cabot Corporation |
| Ecolab |
| Nouryon |
| FUSO CHEMICAL CO., LTD. |
| ADEKA Corporation |
| W. R. Grace & Co. |
| Others |
Supply Flow & Price Mechanics
SEMI-grade certification ladders separate semiconductor foundry supply from commodity construction grades, with that bifurcation translating into five-year contract lock-ins for sub-ppb purity material versus spot-market volatility for precipitated silica. Pricing power concentrates with sol-gel specialists serving TSMC and Samsung, while sodium silicate operators face margin compression from energy-intensive furnace economics and REACH compliance costs.
Pricing Analysis
Distributor margins for mid-tier paint and adhesive grades run 15-25 points above direct-to-foundry technical account structures. Three-tier pricing stratifies across SEMI-certified premium, industrial standard, and economy construction levels, with quality grade and certification tier as primary differentiation drivers. Cost compression in legacy precipitation routes is intensifying because of sodium silicate feedstock volatility. Construction chemical buyers exhibit highest price sensitivity; semiconductor foundry procurement teams prioritize contamination-controlled logistics over unit cost.
Supply Chain Analysis
India's PLI scheme for semiconductors and domestic-content mandates in Gujarat and Karnataka are reshaping sourcing decisions for battery separator coating applications. Geographic concentration centers on Japan, South Korea, and Taiwan for electronics-grade spherical silica, with sodium silicate, silicon tetrachloride, and chlorosilane as critical feedstocks. Single-source vulnerability from East Asian supply concentration creates structural risk. Distribution runs through technical account teams co-located at foundry sites for premium grades, with regional distributors handling mid-tier industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colloidal silica functions as a stable compounder anchored by irreplaceable demand from semiconductor planarization chemistry, where node shrinkage continuously refreshes specification requirements.
For Market Incumbents: Anchor premium positioning through captive sol-gel capacity additions in Taiwan and South Korea, co-located with TSMC and Samsung foundry clusters. Defend against emerging Indian suppliers by accelerating SEMI S2-S8 certification timelines for new qualification partnerships. Prioritize backward integration into chlorosilane chemistry to secure feedstock cost control. For New Entrants and Emerging Players: Battery separator coating specialists in China's Yangtze River Delta represent an underserved buyer archetype seeking tailored particle size distributions outside incumbent foundry supply relationships. Target India's domestic fab buildout in Gujarat before localized supply chains mature. Pursue technical co-development agreements with lithium-ion cell manufacturers as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where legacy sodium silicate assets face stranding from sub-10nm node contamination thresholds. Long-term viability favors sol-gel technology holders with proprietary particle size control over commodity precipitation operators. Monitor MFDS pharmaceutical excipient qualification pathways as the signal to watch for personal care grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Sol-gel plant additions in Taiwan serve TSMC's 2nm node ramp with contamination-controlled logistics. |
| Backward Integration | Chlorosilane chemistry control at Rheinfelden secures fumed silica feedstock cost stability for Evonik. |
| Long-term Supply Agreement | Five-year contracts with price-volume bands displace spot transactions for semiconductor-grade material. |
| Joint Venture | Co-development programs with Tokyo Electron align particle synthesis R&D with process equipment roadmaps. |
| Green Manufacturing Transition | Closed-loop aqueous sol-gel routes capture first-mover advantage under China's MEE wastewater standards. |
Methodological Framework
Direct dialogue with foundry material qualification teams, chemical procurement leads at semiconductor OEMs, plant managers at sodium silicate facilities, and distribution channel partners in Germany and Japan grounded the qualitative assessment. Secondary validation drew from SEMI standards documentation, EPA effluent guideline filings, ECHA REACH Annex XVII amendments, and customs trade data for silica precursor materials. Bottom-up and top-down triangulation cross-checked volume estimates against capacity announcements and foundry capex disclosures.
Bottom-up modeling built segment-level projections from node-specific CMP slurry consumption rates, pharmaceutical excipient qualification timelines, and construction chemical formulation trends. Segmentation dimensions included particle geometry tier, end-use industry, purity certification level, and regional production hub. CAGRs were derived from weighted average growth across these segments. Forecast inputs incorporated foundry localization policy trajectories and dual-use export control evolution.
Underlying measurement precision varies by segment; semiconductor-grade spherical silica carries tighter precision than commodity construction additives given foundry disclosure transparency. Forecasts reflect assumptions around SEMI specification stability, sodium silicate energy cost trajectories, and battery separator coating adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Specialty Silica Market
Specialty Materials
Semiconductor O-Rings Market
Specialty Materials
UK Lab-Grown Diamonds Market
Specialty Materials
Asia Pacific Cellulose Acetate Market
Specialty Materials
Silicone Film Market
Specialty Materials
Global Cellulose Acetate Market
Specialty Materials
Jesmonite Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Medical Injection Molded Plastics Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Engineered Foam Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Surface Technology Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Alginate Films Market
Specialty Materials
Reflective Polarizing Films Market