
 Medical Injection Molded Plastics Market | 2026-2036
Medical Injection Molded Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Injection Molded Plastics Market Intelligence
German precision molders is pivoting toward multi-cavity tooling for drug-delivery devices. Dow Inc. leverages its polyethylene portfolio to dominate sterile packaging grades across North American hospital networks. SABIC sustains technical leadership in polycarbonate blends engineered for gamma-ray sterilization cycles. Eastman Chemical Company anchors its position through copolyester innovations targeting diagnostic device housings.
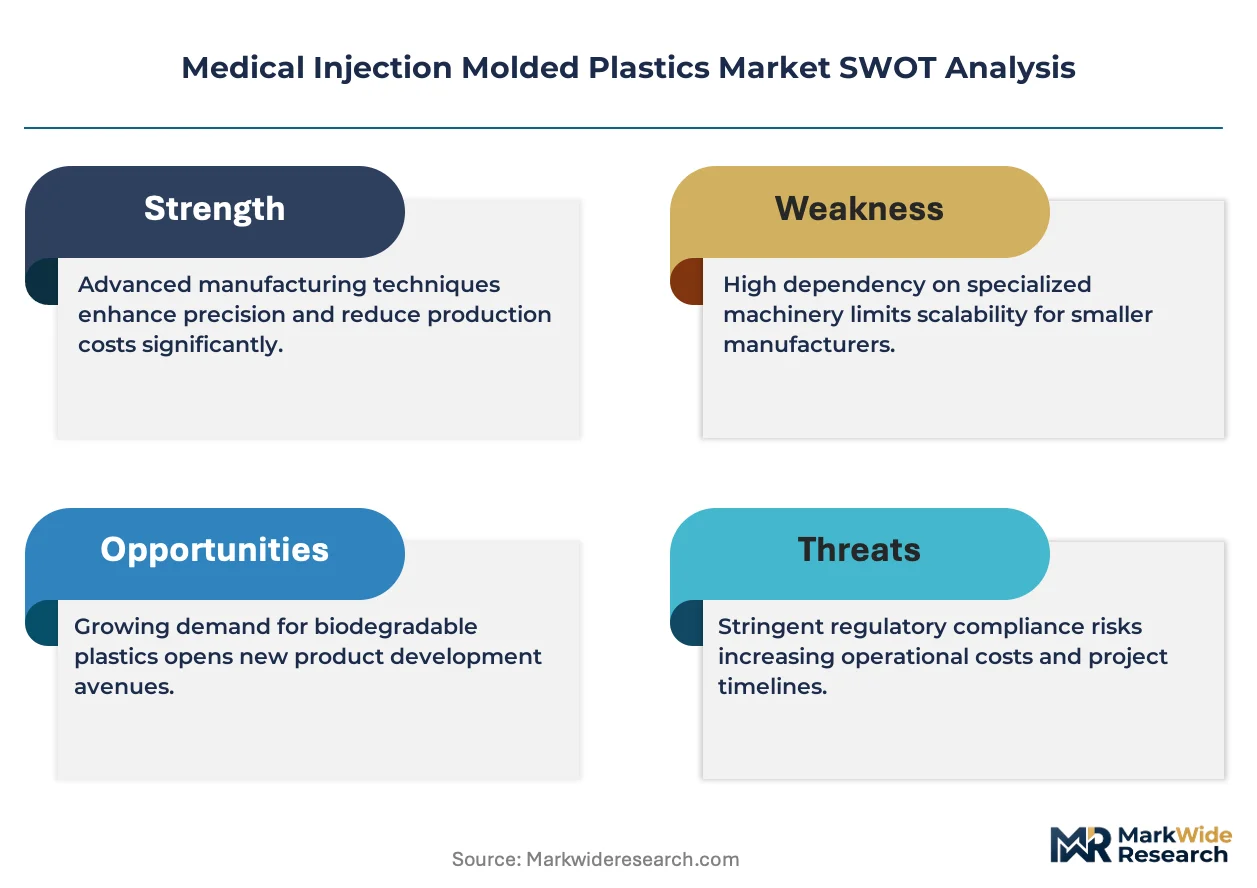
Medical injection molded plastics encompass thermoplastic resins formed under high pressure into complex geometries with tolerances often held to ±0.05 millimeters, serving primarily as sterile barriers, fluid pathways, and structural components in patient-contact applications. Polypropylene syringes and vials represent the most mature volume category, while polycarbonate diagnostic device housings command premium margins due to optical clarity requirements and autoclave compatibility. Nylon surgical instrument handles represent the fastest-expanding material-application intersection, driven by metal-replacement trends in laparoscopic tool sets.
FDA 21 CFR Part 820 quality system regulations and EU MDR device classification rules jointly shape material traceability and biocompatibility testing burdens for all market participants. ISO 10993 biological evaluation standards further constrain resin selection and additive packages across every major supply geography. Stakeholders must monitor evolving EPA per- and polyfluoroalkyl substance restrictions, as fluoropolymer processing aids face phased elimination that could force reformulation of critical high-performance grades.
Market Dynamics
ISO 13485 quality mandates are compressing supplier qualification timelines while simultaneously fragmenting the qualified vendor base, forcing medical device OEMs to consolidate molding partnerships around fewer, higher-capability processors.
Growth Catalysts
- EU MDR device classification rules:The expanded scope of Class III device requirements is accelerating demand for validated sterile barrier systems across German and French pharmaceutical packaging networks.
- Metal-replacement in laparoscopic instruments:Nylon 66 and PEEK polymer formulations are displacing stainless steel in surgical tool handles, driven by ergonomic weight reduction targets and autoclave cycle durability.
- Gamma-ray sterilization compatibility:Polycarbonate blends engineered for radiation stability are capturing preference in diagnostic device housings where optical clarity must survive repeated sterilization exposure.
Market Restraints
- High-purity resin supply concentration:Medical-grade polypropylene and polycarbonate production clusters in the US Gulf Coast and German chemical corridors, creating geographic vulnerability to feedstock disruptions.
- EPA PFAS processing aid phaseout:Fluoropolymer lubricants and mold release agents face elimination timelines that threaten processing yields for tight-tolerance components without qualified alternatives.
- Biocompatibility testing burden:ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization protocols extend material qualification cycles by 12-18 months, freezing resin switching decisions.
Strategic Opportunities
- Indian pharmaceutical packaging expansion:CDSCO's alignment with PIC/S standards is opening validated supply contracts for export-oriented sterile vial and syringe molding capacity near Mumbai and Hyderabad clusters.
- Connected drug-delivery devices:Integration of molded electronics housings with Bluetooth-enabled dose counters creates premium positioning in diabetes and respiratory therapeutic categories.
- Closed-loop recycled content mandates:EU Green Deal circular economy requirements for medical packaging are stimulating investment in validated mechanical recycling streams for polypropylene secondary applications.
Industry Challenges
- Multi-cavity mold design expertise:The scarcity of engineers capable of balancing runner systems for 32+ cavity drug-delivery device tooling is extending lead times for high-volume programs.
- Cleanroom certification maintenance:ISO 14644 Class 7 and Class 8 facility recertification cycles demand continuous capital reinvestment in HVAC and environmental monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Injection Molded Plastics Market |
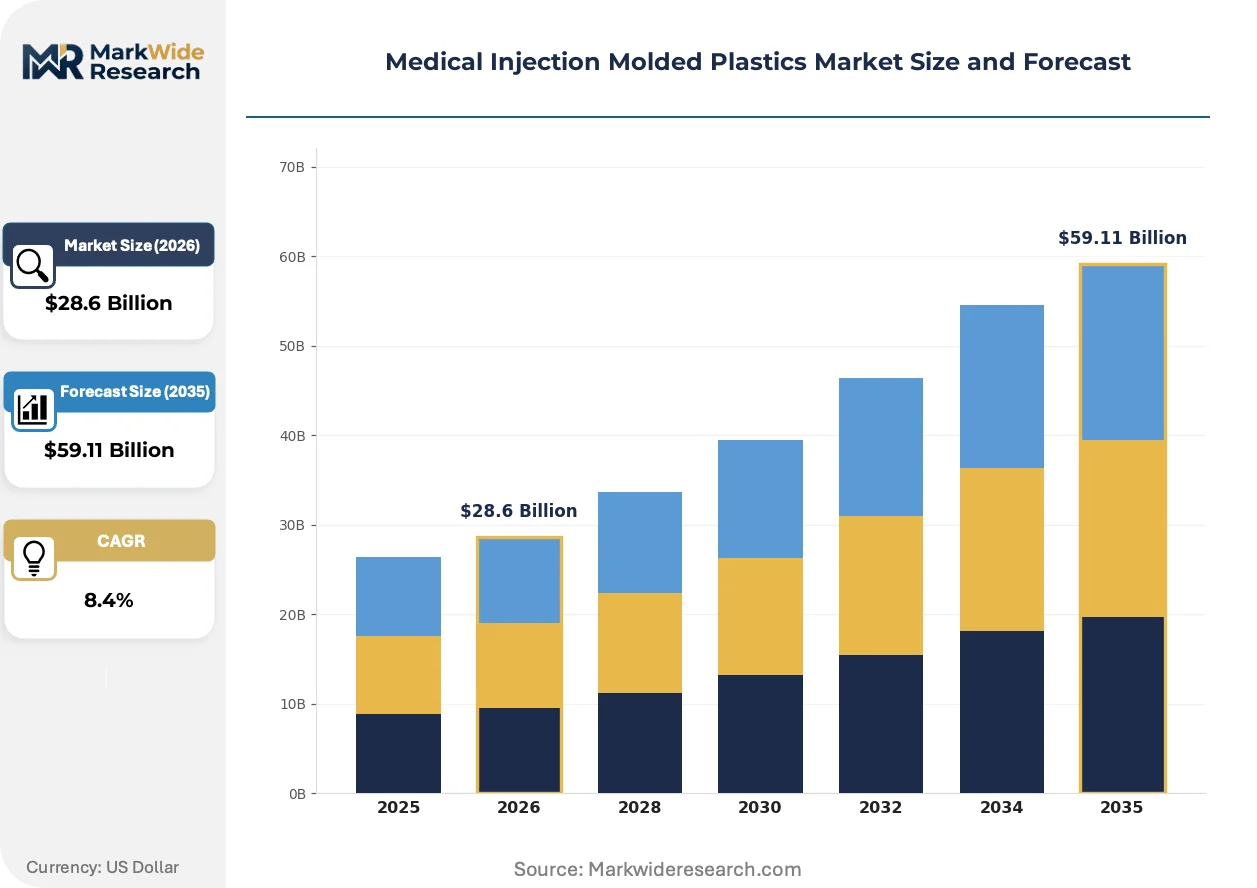
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Vials, Containers, Trays Material: Polypropylene, Polycarbonate, Polystyrene, Nylon End User: Hospitals, Clinics, Laboratories, Pharmaceuticals Application: Diagnostic Devices, Surgical Instruments, Drug Delivery, Packaging |
| Companies Covered | Dow Inc., SABIC, Eastman Chemical Company, Celanese Corporation, Covestro AG, Evonik Industries AG, Arkema, Sumitomo Chemical Co., Ltd., INEOS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Injection Molded Plastics Market Strategic Shifts & Innovations
Digital thread technologies are collapsing the gap between mold design simulation and production validation, compressing development cycles for complex geometries while simultaneously raising the bar for process documentation.
Micro-injection molding platforms capable of shot weights below 0.1 grams are decentralizing production of precision fluidic components for point-of-care diagnostic cartridges. Contract manufacturers in Switzerland and Singapore are deploying these systems to serve distributed diagnostic OEM networks. The technology is decentralizing supply chain risk by enabling regional production of previously centralized high-value components.
REACH restrictions on phthalate plasticizers and bisphenol-A analogs are forcing reformulation of flexible PVC and polycarbonate alternatives in neonatal and long-term implant applications. Compounders are accelerating bio-based polyester and TPE development programs to maintain material portfolios. Pediatric device segments and EU-exporting manufacturers face the most acute substitution pressure, with some German molders already qualifying entirely phthalate-free material sets.
Hospital network procurement consortia are consolidating purchasing authority for standardized commodity items like syringes and specimen containers, displacing fragmented distributor relationships. Large US integrated delivery networks and NHS Supply Chain in the United Kingdom are driving this concentration. The shift is most visible in North American acute care settings, where three-tier pricing structures are collapsing toward single-source contracts with volume-tier rebates.
Medical Injection Molded Plastics Market Segmentation
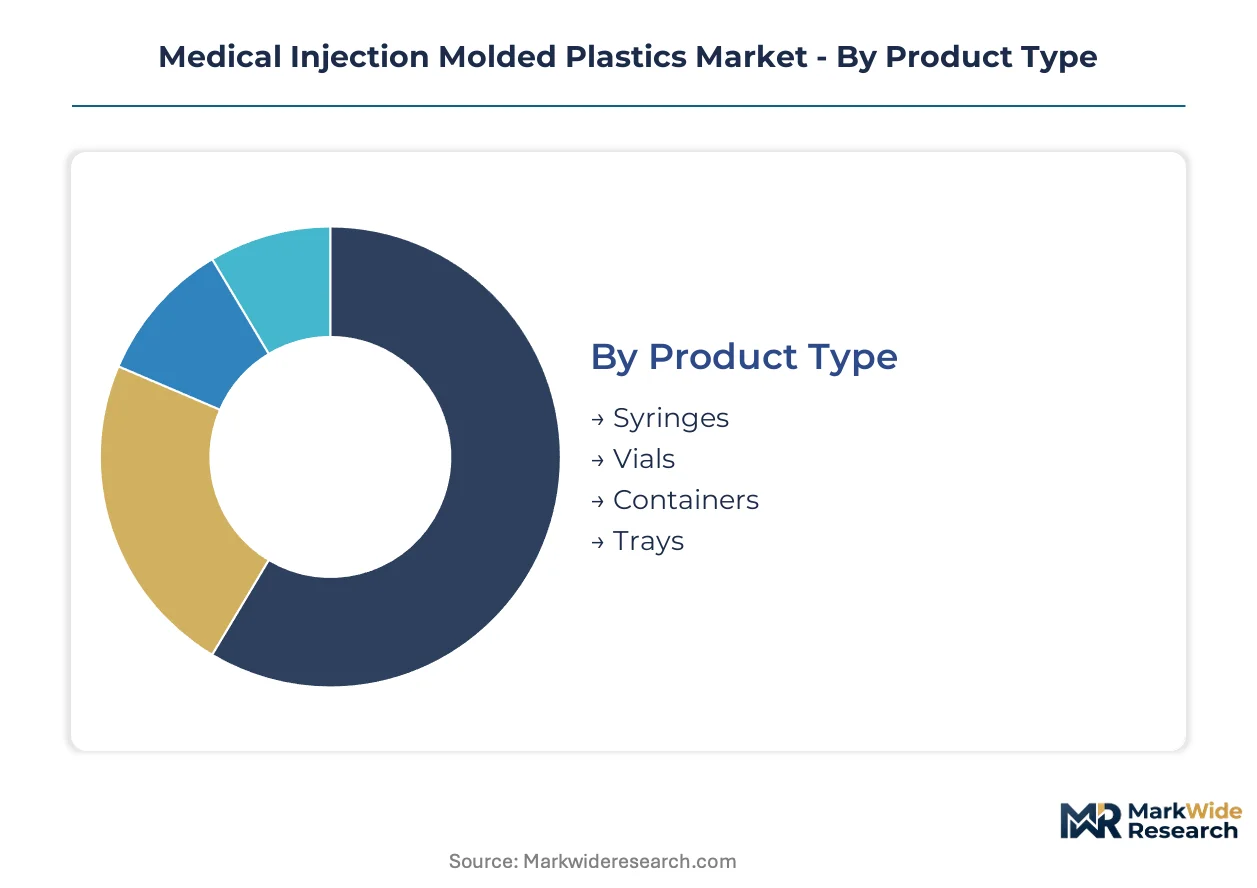
Segmentation in medical injection molded plastics reveals how supply chain capabilities align with divergent technical requirements across sterile barriers, fluid pathways, and structural components. Material selection and molding precision thresholds vary sharply between high-volume commodity formats and specialized diagnostic housings.
Product Type:
Supply concentration clusters around formats with validated sterile barrier performance and established high-speed molding infrastructure.
- Syringes:Polypropylene barrel and plunger assemblies dominate unit volume, with multi-cavity tooling investments concentrating in Germany, the United States, and China. ISO 13485-certified processors near Frankfurt and Mumbai command premium positioning for pre-filled syringe contracts.
- Vials:Sterile barrier integrity requirements drive qualification timelines exceeding 18 months for blow-fill-seal and injection-stretch blow formats. Demand concentrates in parenteral packaging networks serving biologic drug portfolios.
- Containers:Specimen collection and transport vessels span polypropylene and polystyrene formulations, with procurement consolidating through hospital network consortia.
- Trays:Surgical procedure kits and implant packaging require custom thermoformed and injection-molded formats with etched lot traceability.
Syringes absorb the bulk of installed capacity; vials are expanding most quickly.
Material:
Cost tiers separate commodity resins from engineered grades demanding specialized compounding and additive packages.
- Polypropylene:Homopolymer and random copolymer grades constitute the volume foundation, with medical-grade supply concentrating along the US Gulf Coast and German chemical corridors. Gamma-ray sterilization compatibility and clarified optical variants command price premiums.
- Polycarbonate:Optical clarity and autoclave durability position this material in diagnostic device housings and surgical instrument handles. Bisphenol-A regulatory pressure is accelerating migration to copolyester alternatives in neonatal applications.
- Polystyrene:General-purpose and high-impact grades serve lower-cost specimen containers and diagnostic cassettes where sterilization demands are less severe.
- Nylon:Nylon 66 and PEEK formulations represent the steepest expansion trajectory, displacing stainless steel in laparoscopic instrument handles through metal-replacement programs.
Polypropylene commands the largest share of resin consumption; nylon is climbing the fastest on metal-replacement momentum.
End User:
Customer type determines certification burden, with pharmaceutical direct procurement imposing the most stringent traceability requirements.
- Pharmaceuticals:Drug manufacturers demand validated sterile barrier systems with complete batch documentation and extractables testing. Direct molding contracts bypass distributor markups for high-volume parenteral packaging programs.
- Hospitals:Integrated delivery networks are consolidating purchasing authority for standardized commodity items, collapsing three-tier pricing toward single-source agreements with volume rebates.
- Laboratories:Diagnostic OEMs require precision fluidic components with tight dimensional tolerances for point-of-care cartridge platforms.
- Clinics:Ambulatory settings drive demand for pre-filled syringes and unit-dose packaging formats emphasizing ease of use and disposal safety.
Pharmaceuticals channel the majority of premium-grade volume; laboratories are gaining share fastest on diagnostic decentralization.
Application:
Maturity gradients separate established packaging formats from emerging device integration opportunities.
- Packaging:Sterile barrier systems for vials, syringes, and implant kits represent the most mature revenue category, with EU Green Deal circular economy requirements stimulating recycled content investments.
- Drug Delivery:Connected autoinjectors and inhaler platforms integrate molded electronics housings with Bluetooth-enabled dose counters, creating premium positioning in diabetes and respiratory therapeutic categories.
- Diagnostic Devices:Polycarbonate and copolyester housings for imaging and testing equipment require optical clarity surviving repeated gamma-ray sterilization cycles.
- Surgical Instruments:Nylon and PEEK polymer handles for laparoscopic tools are displacing metal through ergonomic weight reduction and autoclave durability specifications.
Packaging retains the deepest installed base; drug delivery is expanding most rapidly on connected device integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene feedstock concentration along the US Gulf Coast and German chemical corridors anchors regional production advantages. These petrochemical hubs supply medical-grade resin specifications that downstream molders in pharmaceutical packaging corridors transform into sterile barrier systems. Quality certification density varies sharply across manufacturing clusters.
United States
FDA 21 CFR Part 820 enforcement compresses supplier qualification timelines for sterile barrier systems. Hospital network procurement consortia consolidate purchasing authority for syringes and specimen containers through integrated delivery networks. Houston and Baytown chemical corridors feed medical-grade polypropylene to precision molders near Minneapolis and Boston medical device clusters.
Germany
EU MDR device classification rules accelerate demand for validated sterile barrier systems across pharmaceutical packaging networks. ISO 13485-certified processors near Frankfurt command premium positioning for pre-filled syringe contracts. Bavarian and Baden-Württemberg precision molders pivot toward multi-cavity tooling for drug-delivery devices serving export markets.
China
NMPA alignment with international standards opens validated supply contracts for export-oriented sterile vial capacity. Yangtze River Delta molders near Shanghai absorb bulk multi-cavity tooling investments for high-volume commodity formats. Guangdong pharmaceutical packaging corridors concentrate gamma-ray sterilization-compatible polycarbonate processing for diagnostic device exports.
India
CDSCO alignment with PIC/S standards stimulates export-oriented sterile vial and syringe molding capacity expansion. Mumbai and Hyderabad clusters attract pharmaceutical packaging investments serving regulated markets. Maharashtra and Gujarat molders qualify medical-grade polypropylene formulations for parenteral drug delivery systems.
Switzerland
Swissmedic quality requirements sustain premium positioning for precision fluidic components in diagnostic cartridges. Micro-injection molding platforms near Basel and Zurich decentralize production of sub-0.1-gram shot weight components. Contract manufacturers deploy these systems to serve distributed diagnostic OEM networks across European markets.
Medical Injection Molded Plastics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue connected device integration and recycled content validation. The supplier base concentrates around resin compounders with medical-grade certification and molders with ISO 13485 quality system infrastructure. Three archetypes dominate: integrated petrochemical-resin compounders, specialized medical-grade molders, and contract manufacturing organizations with cleanroom certification. Capacity expansion and strategic partnerships represent the dominant competitive vectors as OEMs consolidate molding relationships.
Within the integrated petrochemical tier, Dow Inc. and SABIC exemplify resin compounders leveraging feedstock integration to dominate sterile packaging grades. Eastman Chemical Company occupies a position among specialty material innovators targeting diagnostic device applications with copolyester alternatives. These three entities represent distinct strategic postures: commodity scale, radiation-stable engineering grades, and biocompatible polymer substitution respectively.
| Leading Market Players |
|---|
| Dow Inc. |
| SABIC |
| Eastman Chemical Company |
| Celanese Corporation |
| Covestro AG |
| Evonik Industries AG |
| Arkema |
| Sumitomo Chemical Co., Ltd. |
| INEOS Group |
| Others |
Cost & Logistics Intelligence
EU Green Deal circular economy requirements for medical packaging gate qualified supply and premium-tier pricing access, forcing molders to validate recycled content streams before securing contracts with pharmaceutical OEMs. This sustainability mandate compresses the vendor base while creating tiered access to higher-margin sterile barrier programs.
Pricing Analysis
Warranty and validation documentation bundling separates premium-tier molders from commodity competitors, with ISO 13485-certified processors commanding inclusion of extractables testing and batch traceability services. Three-tier pricing structure across premium, standard, and economy levels tracks certification density and cleanroom classification, with pharmaceutical direct procurement showing least price sensitivity while hospital network consortia drive cost compression in standardized syringe and specimen container categories.
Supply Chain Analysis
Freight costs from German chemical corridors and US Gulf Coast resin clusters to pharmaceutical packaging hubs in Mumbai and Shanghai anchor total landed cost calculations for medical-grade polypropylene. Raw material supply draws from propylene feedstock concentrations in Germany, the United States, and Saudi Arabia, with single-source vulnerability concentrated in gamma-ray sterilization-compatible polycarbonate additives. Distribution runs through validated cold-chain logistics partners serving FDA and EU MDR compliance requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical injection molded plastics sits in a technology-transition phase as micro-injection molding platforms displace centralized production of precision fluidic components for point-of-care diagnostics.
For Market Incumbents: Deploy multi-cavity tooling expertise as the primary defensive lever against emerging Asian competitors, while accelerating backward integration into medical-grade resin compounding to secure feedstock amid EPA PFAS processing aid phaseout pressures. For New Entrants and Emerging Players: Regional diagnostic OEMs in Switzerland and Singapore represent the most penetrable buyer archetype, with micro-injection molding capacity for sub-0.1-gram shot weight components offering entry into premium fluidic cartridge supply chains bypassing established German molders. For Investors and Strategic Acquirers: First-mover qualification of closed-loop recycled polypropylene streams under EU Green Deal mandates is the leading indicator that circular-economy-ready molders will capture pricing power in pharmaceutical packaging consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Validates sterile barrier production for EU MDR Class III device contracts. |
| Multi-Cavity Tooling Scale-Up | Captures high-volume drug-delivery device programs near Frankfurt and Mumbai. |
| Recycled Content Validation | Secures premium positioning under EU Green Deal circular economy requirements. |
| Micro-Injection Molding Deployment | Enables regional supply of precision diagnostic components near Basel and Zurich. |
| Backward Integration into Resin Compounding | Reduces geographic vulnerability to US Gulf Coast and German feedstock disruptions. |
Research Approach
SEC 10-K filings, customs and trade data, and ISO certification registries formed the secondary backbone, supplemented by primary interviews with medical device OEM procurement directors, pharmaceutical packaging engineers, cleanroom facility managers, and resin compounder technical sales leads. Bottom-up capacity assessments across German, US, and Chinese molding clusters were triangulated against top-down demand estimates from hospital network purchasing data and pharmaceutical packaging forecasts.
Historical trendline analysis of installed multi-cavity tooling capacity and medical-grade resin pricing established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type, material grade tier, end-user certification burden, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted volume projections and value-chain margin compression assumptions specific to gamma-ray sterilization-compatible polycarbonate and metal-replacement nylon formulations.
Revisions become necessary when EPA PFAS phaseout timelines accelerate, EU MDR enforcement intensity shifts, or pharmaceutical OEM consolidation patterns alter contract structures. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Asia-Pacific Reflective Tape Market
Specialty Materials
Europe Acrylic Sheet Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
Nitrocellulose Market
Specialty Materials
Silicone Film Market
Specialty Materials
Carbon Mold Market
Specialty Materials
Super-Hard Material Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Activated Carbon Bags Market
Specialty Materials
Africa Collagen Market
Specialty Materials
EVA Interlayer for Photovoltaic Market
Specialty Materials
Asia Pacific Cellulose Acetate Market
Specialty Materials
Mica Sheet Market
Specialty Materials
Decorative Surface Films Market