
 Non-Semiconductor Neon Market | 2026-2036
Non-Semiconductor Neon Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Semiconductor Neon Market Insights
Asset-light leasing models for cryogenic storage and transport equipment is fragmenting competitive barriers in the non-semiconductor neon supply chain. Linde PLC leverages long-term cylinder leasing programs to lock in recurring revenue from small fabricators. Air Products sustains geographic dominance through dense fill-plant networks across North American urban corridors. Iceblick Ltd competes by specializing in rare-gas recovery from Ukrainian steel mill off-gases, occupying a niche feedstock position.
Non-semiconductor neon denotes high-purity neon gas refined to 99.99 percent or greater, typically extracted via cryogenic air separation and deployed in sealed glass tube lighting, high-intensity discharge lamps, and helium-neon lasers requiring precise spectral output. Neon lights and neon signs anchor current revenue, with mature demand from urban retail corridors generating stable but low-margin volume. Specialty lasers represent the fastest-growing product category, driven by medical dermatology and precision measurement applications where wavelength stability commands premium pricing. The advertising application segment concentrates margin pools, as bespoke creative commissions for luxury brands tolerate higher per-meter gas costs than standardized lighting installations.
EPA hazardous air pollutant standards and OSHA permissible exposure limits govern handling protocols in the United States, while REACH registration requirements in Europe constrain import pathways for non-EU refined gas. The EU F-Gas Regulation phases down fluorinated greenhouse gas use, indirectly elevating neon's relative attractiveness in certain lighting architectures where thermal performance matters. Stakeholders must monitor evolving refrigerant-classification debates that could recategorize neon transport cylinders and reshape compliance costs for cross-border distributors.
Market Dynamics
The EU F-Gas Regulation's phase-down of fluorinated greenhouse gases is compressing alternatives and elevating neon's relative attractiveness in precision lighting architectures where thermal stability commands premium positioning.
Growth Catalysts
- Specialty laser medical adoption:Dermatology clinics in Germany and Japan deploy helium-neon systems for precise tissue targeting, creating pull for wavelength-stable gas supplies.
- Hospitality signage differentiation:Boutique hotels across Munich and Berlin commission bespoke neon installations to anchor brand identity in saturated urban retail corridors.
- REACH registration compliance:EU import pathway standardization for refined gas batches reduces friction for certified distributors serving commercial lighting fabricators.
Market Restraints
- Ukrainian feedstock concentration:Rare-gas recovery from steel mill off-gases clusters in Eastern European industrial zones, exposing supply chains to regional disruption risk.
- Cryogenic transport cost structure:Liquid nitrogen cooling requirements for cylinder logistics impose fixed cost burdens that scale poorly for low-volume fabricators.
- LED substitution pressure:Solid-state lighting architectures displace sealed glass tube installations in standardized commercial applications where color precision is secondary.
Strategic Opportunities
- Closed-loop recovery systems:EU F-Gas Regulation mandates are accelerating investment in gas reclamation infrastructure among German specialty distributors.
- Precision measurement instrumentation:Metrology laboratories in Switzerland and Austria integrate helium-neon interferometry for semiconductor wafer inspection applications.
- Asset-light leasing penetration:Cylinder and cryogenic storage equipment rental models reduce capital barriers for small-scale signage workshops in North American urban corridors.
Industry Challenges
- Cryogenic handling certification timelines:OSHA permissible exposure limit training programs create bottlenecks for technician workforce expansion in US distribution networks.
- Cross-border cylinder requalification:Divergent transport pressure vessel standards between EU member states fragment logistics coordination for multi-country suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Semiconductor Neon Market |
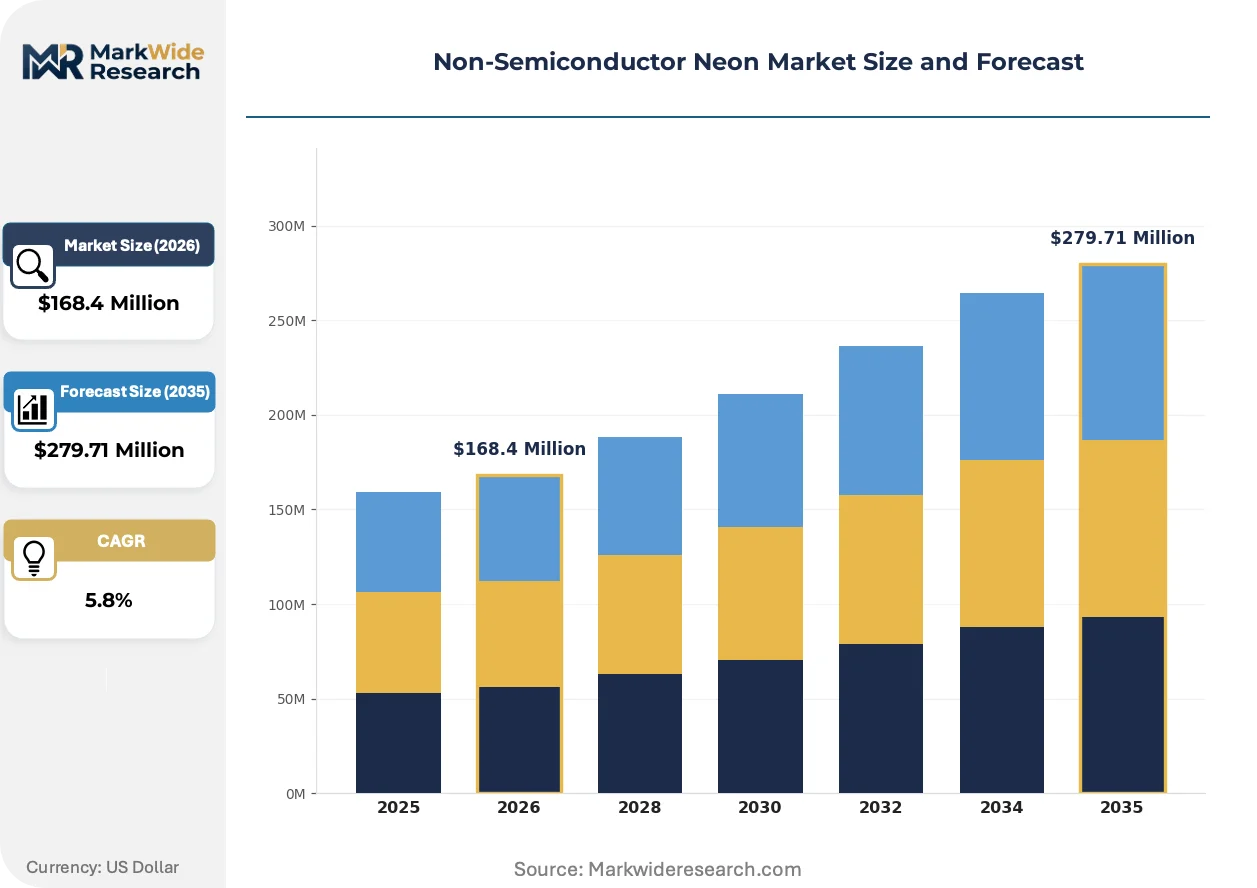
| Market Size in 2026 | $168.4 Million |
| Market Size in 2035 | $279.71 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neon Lights, Neon Signs, High-Intensity Lamps, Specialty Lasers Application: Advertising, Display, Lighting, Aesthetic Design End User: Retail, Hospitality, Art Galleries, Events Delivery Mode: Direct Sales, Online Retail, Distributors, Exports |
| Companies Covered | Air Liquide, Linde PLC, Air Products, Messer Group GmbH, Taiyo Nippon Sanso Corporation, Airgas, Matheson Tri-Gas, Iceblick Ltd, Ingas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Semiconductor Neon Market Trends and Innovations
Neon lighting technology is fragmenting into precision-specialized niches while regulatory pressure on fluorinated alternatives opens architectural space for inert gas solutions in thermal-sensitive applications.
Helium-neon laser systems is migrating from laboratory research environments into clinical dermatology and industrial metrology settings. Medical practices in Germany and Japan adopt these systems for procedures requiring sub-millimeter tissue targeting. The shift compresses demand for standardized signage-grade neon while expanding premium volumes for 99.995 percent purity specifications.
EU F-Gas Regulation phase-down mandates are tightening allowable fluorinated greenhouse gas volumes in commercial refrigeration and insulation applications. Industrial lighting designers respond by specifying neon-filled thermal barriers in high-performance architectural glazing. German building code enforcement in Munich and Berlin accelerates this specification shift in new commercial construction.
Buyer consolidation among luxury hospitality groups concentrates procurement authority for bespoke signage commissions. Design studios in Paris and Milan now contract directly with certified gas distributors rather than intermediating through general lighting contractors. This channel compression is most visible in French and Italian urban retail corridor developments where brand-flagship concentration demands unified creative-gas sourcing.
Non-Semiconductor Neon Market Segmentation
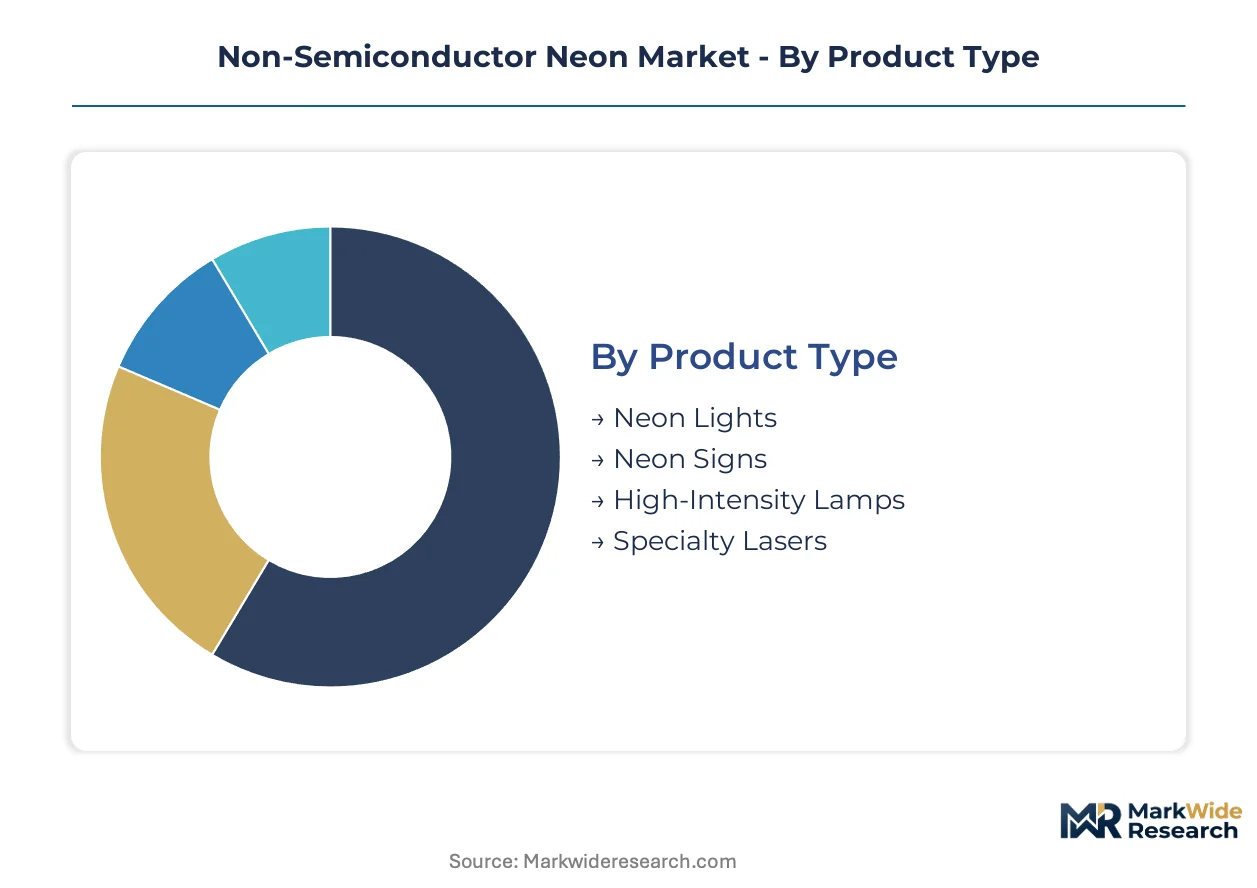
Segmentation in the non-semiconductor neon market reveals how purity specifications, installation complexity, and buyer procurement authority fragment revenue pools across divergent value chains. Understanding these divisions exposes where margin concentrates versus where volume commoditizes.
Product Type:
The use-case spectrum spans mass-market illumination to precision instrumentation, with each tier demanding distinct purity grades and cylinder handling protocols.
- Neon Lights:Standard 99.99 percent purity sealed glass tube installations dominate urban retail corridor retrofits. Demand concentrates in Munich and Berlin hospitality clusters where landlords specify warm-tone ambient lighting for street-facing facades; LED retrofit pressure constrains pricing power.
- Specialty Lasers:Helium-neon systems requiring 99.995 percent purity and wavelength stability within 0.1 nanometers serve medical dermatology and semiconductor metrology. German and Japanese clinics deploy these for sub-millimeter tissue targeting; wavelength precision commands cylinder premiums exceeding signage-grade gas by factor of three.
- Neon Signs:Custom glass bending for brand-flagship installations tolerates 99.99 percent purity with artistic color mixing via argon-mercury blends. Paris and Milan design studios contract directly with certified distributors for luxury hospitality commissions.
- High-Intensity Lamps:Discharge architectures for industrial and theatrical applications where thermal load tolerance outweighs color precision requirements.
Established volume favors Neon Lights; emerging adoption favors Specialty Lasers.
Application:
Cost tier differentiation separates commodity bulk installations from bespoke creative commissions with divergent gas cost tolerance.
- Advertising:Bespoke creative commissions for luxury brand flagships in French and Italian urban retail corridors tolerate per-meter gas costs exceeding standardized installations by substantial margins. Design studios now source directly from certified distributors, compressing intermediary margins.
- Lighting:Functional illumination for commercial and residential spaces where color precision is secondary to energy efficiency; LED substitution pressure is most acute here.
- Display:Point-of-sale and exhibition installations requiring rapid deployment and standardized tube geometries.
- Aesthetic Design:Gallery and installation art where gas purity and color consistency support artistic intent rather than commercial messaging.
Procurement authority concentrates in Advertising; standardization pressure weighs heaviest on Lighting.
End User:
Customer type determines whether procurement flows through general contractors or direct distributor relationships.
- Hospitality:Boutique hotels across Munich and Berlin commission bespoke neon installations to anchor brand identity; buyer consolidation among luxury groups concentrates sourcing authority with design studios.
- Retail:Urban corridor storefronts generating stable but low-margin volume through standardized signage specifications.
- Art Galleries:Installation-specific procurement with irregular volume and exacting color consistency requirements.
- Events:Temporary deployment with compressed lead times and rental-oriented cylinder logistics.
Margin pools favor Hospitality; volume scale favors Retail.
Delivery Mode:
Supply concentration shapes which channels capture value from cylinder logistics and certification handling.
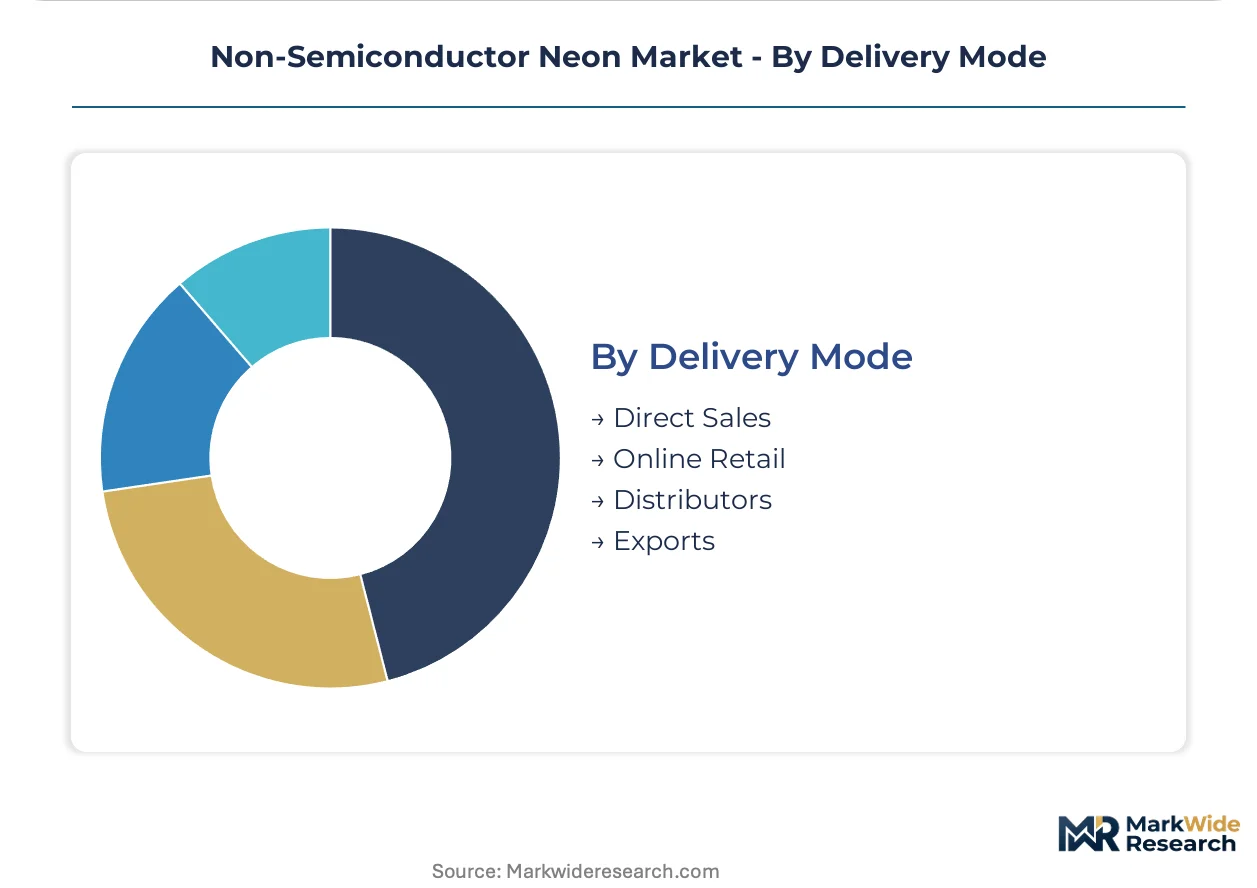
- Distributors:German specialty gas distributors with dense fill-plant networks dominate commercial lighting fabricator supply, bundling cylinder leasing with requalification services.
- Direct Sales:Large-scale hospitality and retail chains with consolidated procurement authority negotiate cylinder pooling agreements directly with refiners.
- Online Retail:Small-scale signage workshops in North American urban corridors accessing asset-light leasing models for cryogenic storage equipment.
- Exports:Cross-border flows constrained by REACH registration requirements and divergent transport pressure vessel standards between EU member states.
Channel control favors Distributors; disintermediation pressure targets Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows concentrate neon refining capacity in industrial gas corridors while demand clusters in hospitality and precision manufacturing zones. The United States maintains a structural import deficit for high-purity neon, sourcing from European cryogenic separation facilities and Ukrainian steel off-gas recovery operations. Germany, Japan, and China anchor consumption through divergent end-use mixes spanning medical lasers, architectural lighting, and metrology instrumentation.
United States
Helium-neon laser adoption in dermatology clinics across California and Texas drives specialty gas demand. EPA hazardous air pollutant standards govern cylinder handling protocols in industrial gas distribution networks. Greater Boston hosts precision metrology laboratories deploying interferometry systems for semiconductor wafer inspection.
Germany
Boutique hotel signage commissions in Munich and Berlin sustain dense networks of specialty gas distributors serving commercial lighting fabricators. EU F-Gas Regulation phase-down mandates accelerate closed-loop recovery system investments among Bavarian industrial gas suppliers. The Rhine-Ruhr corridor concentrates rare-gas refining capacity adjacent to steel mill off-gas feedstock sources.
Japan
Medical dermatology clinics in Tokyo and Osaka deploy helium-neon systems for sub-millimeter tissue targeting applications. METI industrial gas handling standards constrain import pathway certification timelines for non-domestic refined batches. The Kansai region hosts precision instrument manufacturers integrating wavelength-stable laser sources into semiconductor inspection equipment.
China
Metrology laboratory expansion in the Yangtze River Delta pulls high-purity neon for interferometry-based measurement systems. GB standards for cryogenic transport pressure vessels fragment cross-border cylinder logistics coordination with neighboring jurisdictions. Shenzhen and Guangzhou fabrication clusters generate standardized signage demand for urban retail corridor developments.
France
Luxury hospitality design studios in Paris contract directly with certified gas distributors for bespoke brand-flagship installations. REACH registration requirements standardize import pathway compliance for refined gas batches entering EU distribution networks. The Île-de-France region concentrates procurement authority among consolidated buyer groups in the luxury hotel segment.
Non-Semiconductor Neon Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock recovery and regional distribution. The non-semiconductor neon market structures around three tiers: multinational industrial gas conglomerates with integrated cryogenic separation networks, regional distributors bundling cylinder logistics with certification services, and niche feedstock specialists extracting rare gases from steel mill off-gas streams. Competitive moves concentrate on geographic fill-plant densification and asset-light leasing model penetration to capture small fabricator demand.
Within the multinational tier, Linde PLC and Air Products exemplify divergent approaches to cylinder logistics and geographic coverage. Linde leverages long-term leasing programs to lock in recurring revenue from fragmented fabricator bases. Air Products sustains position through dense fill-plant networks across North American urban corridors. Iceblick Ltd occupies a distinct upstream position, representing the steel off-gas recovery archetype concentrated in Eastern European industrial zones.
| Leading Market Players |
|---|
| Air Liquide |
| Linde PLC |
| Air Products |
| Messer Group GmbH |
| Taiyo Nippon Sanso Corporation |
| Airgas |
| Matheson Tri-Gas |
| Iceblick Ltd |
| Ingas |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Ruhr corridor's rare-gas refining concentration adjacent to steel mill off-gas sources shapes downstream pricing power for German specialty distributors serving Munich and Berlin hospitality clusters. EU F-Gas Regulation compliance costs and cryogenic transport overheads feed into cylinder lease rates that scale poorly for low-volume North American fabricators.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with three-tier pricing stratifying across 99.995 percent medical-laser purity, 99.99 percent signage-grade, and blended argon-mercury economy tiers. Price differentiation hinges on certification level (REACH-registered EU batches command premiums over non-certified imports) and volume scale (hospitality direct-pooling agreements undercut distributor markups). Pricing pressure stems from LED substitution in standardized commercial lighting where color precision is secondary. Retail corridor landlords show highest price sensitivity; luxury brand flagship studios tolerate per-meter gas costs exceeding standardized installations by substantial margins.
Supply Chain Analysis
Extended payment terms from Linde PLC and Air Products lock small fabricators into recurring cylinder lease obligations, compressing working capital flexibility. Feedstock recovery concentrates in Ukraine, Germany, and China, with cryogenic air separation drawing from steel mill off-gases, atmospheric distillation, and helium-neon laser manufacturing scrap. Rare-gas recovery from Eastern European steel zones creates single-source vulnerability exposure. Distribution runs through German specialty gas distributors with dense fill-plant networks bundling requalification services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against solid-state LED architectures displacing sealed glass tube installations in functional illumination applications. Incumbents must articulate premium value around wavelength precision and bespoke creative commissioning.
For Market Incumbents: Pre-empt LED encroachment by locking luxury hospitality groups into exclusive cylinder pooling agreements with embedded creative design services. Invest in closed-loop recovery infrastructure ahead of EU F-Gas Regulation enforcement timelines. Backward integration into Ukrainian steel off-gas feedstock secures supply continuity against regional disruption risk.
For New Entrants and Emerging Players: North American urban corridor signage workshops remain underpenetrated by asset-light leasing models, presenting white-space entry through cryogenic equipment rental programs. Target medical dermatology clinics in California and Texas with 99.995 percent purity helium-neon laser bundles. Go-to-market leverage: partner with metrology instrument OEMs for interferometry system gas supply integration.
For Investors and Strategic Acquirers: Long-term, this sits as a niche specialty-gas consolidation play because buyer consolidation among luxury hospitality groups concentrates procurement authority with design studios. Target regional distributors with REACH certification infrastructure and dense fill-plant networks in German urban corridors. Signal to watch: dermatology clinic helium-neon laser adoption rates in Germany and Japan as premium purity demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Recovery | Ukrainian steel off-gas capture secures rare-gas supply against Eastern European disruption exposure. |
| Closed-Loop Recovery System Deployment | EU F-Gas Regulation mandates accelerate gas reclamation infrastructure investment among Bavarian distributors. |
| Asset-Light Leasing Model Expansion | Cylinder rental programs reduce capital barriers for small-scale North American signage workshops. |
| Direct Design Studio Partnerships | Paris and Milan luxury hospitality procurement authority shifts from general contractors to certified gas distributors. |
| Medical Laser Purity Certification | 99.995 percent wavelength-stable specifications command cylinder premiums exceeding signage-grade by factor of three. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with neon lighting fabricators, specialty gas distribution managers, dermatology clinic procurement leads, and hospitality design studio directors. Secondary validation drew from EU F-Gas Regulation filings, REACH registration databases, EPA hazardous air pollutant standards documentation, and OSHA permissible exposure limit guidelines. Bottom-up volume estimates from cylinder logistics data triangulated against top-down cryogenic separation capacity assessments.
Calibration against historical purity-grade pricing differentials and segment adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type (neon lights, specialty lasers, signage, high-intensity lamps), application tier (advertising, lighting, display, aesthetic design), and delivery mode (distributor, direct sales, online retail, exports). CAGRs were derived from weighted average of segment growth trajectories, with medical dermatology laser adoption and hospitality signage commissioning as primary industry-specific inputs.
Practitioners should monitor LED substitution rates in commercial lighting and Ukrainian feedstock supply continuity for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Charge Generation Materials (CGM) Market
Specialty Materials
Asia-Pacific Reflective Tape Market
Specialty Materials
Surface Technology Market
Specialty Materials
Semiconductor O-Rings Market
Specialty Materials
Silicone Gel Market
Specialty Materials
UK Lab-Grown Diamonds Market
Specialty Materials
Super-Hard Material Market
Specialty Materials
Specialty Carbon Black Market
Specialty Materials
North America Solar Control Window Films Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Super Engineering Plastics Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Recyclable Thermosets Market
Specialty Materials
Sulphur Bentonite Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Acrylic Fine Particle Market