
 Europe Textile Films Market | 2026-2036
Europe Textile Films Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Textile Films Market Foresight
Subscription-based technical support and software-defined film customization is recalibrating how European textile film suppliers monetize long-term customer relationships. Covestro AG leverages its polyurethane R&D depth to anchor premium breathable film supply for medical and apparel OEMs. RKW Group competes through backward integration into resin compounding, sustaining margin control across polyethylene and polypropylene film lines.
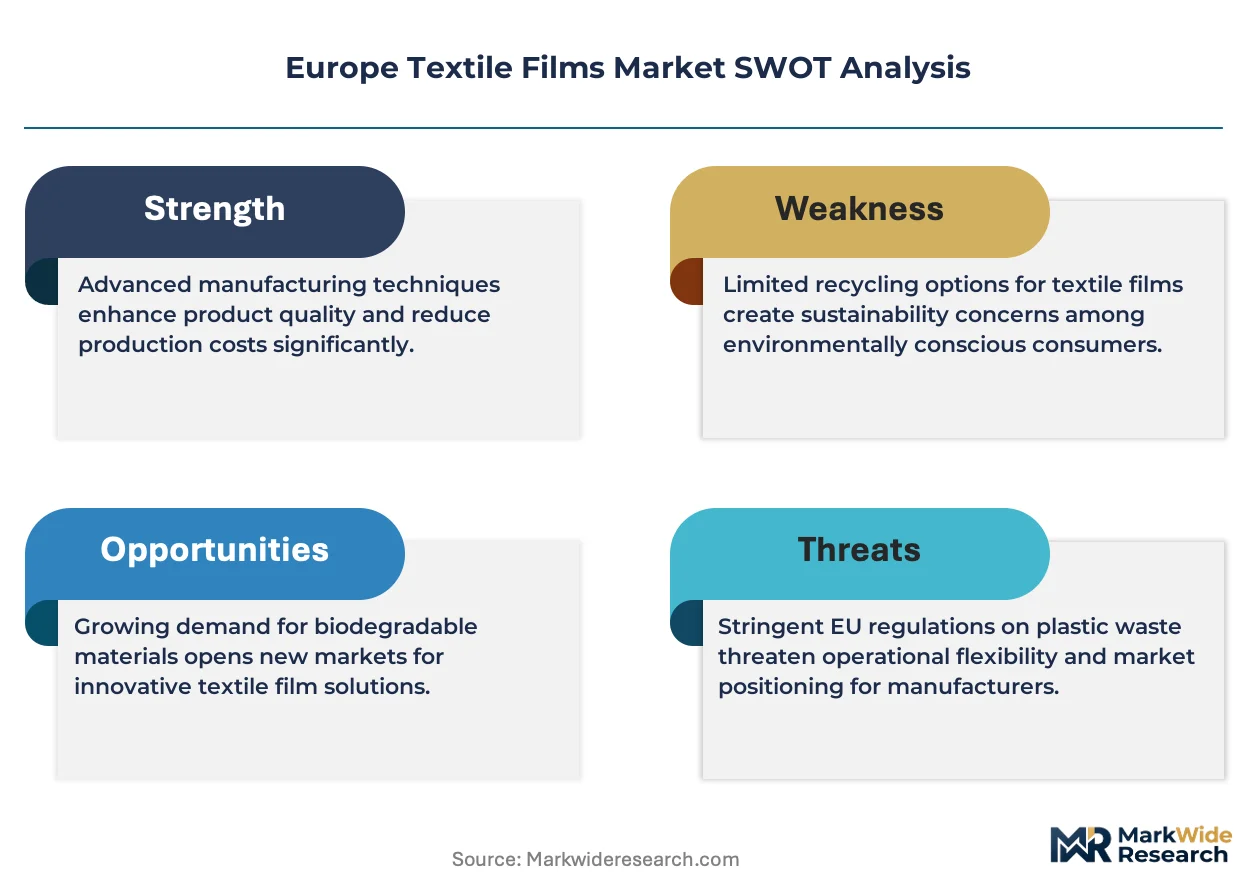
Europe textile films comprise engineered polymer membranes, typically 10–200 microns thick, manufactured via cast extrusion, blown film, or solvent coating processes to deliver controlled permeability, tensile strength, and barrier protection for industrial and consumer applications. Breathable films and biodegradable films are gaining structural priority as sustainability mandates intensify, while coated films retain the largest volume share due to mature cost structures in packaging and upholstery. Polyurethane and polyester material grades command the strongest margin pools where medical and high-performance apparel specifications require solvent resistance and elastic recovery.
REACH, the EU Green Deal, and the F-Gas Regulation collectively constrain petrochemical feedstock use and mandate recyclability disclosures, redirecting R&D budgets toward bio-based and recycled-content formulations. ECHA chemical restriction proposals on persistent substances are tightening compliance timelines for film converters serving medical and food-contact segments. Stakeholders must monitor polymer recycling infrastructure buildouts and bioplastic certification schemes to secure feedstock access and maintain product registration validity.
Market Dynamics
REACH chemical restrictions and the EU Green Deal are compressing formulation flexibility for European textile film converters, forcing accelerated R&D migration toward bio-based feedstocks and closed-loop recycling infrastructure.
Growth Catalysts
- Medical barrier fabric adoption:German and Swiss hospitals are expanding procurement of breathable polyurethane membranes for surgical drapes and isolation gowns, tightening specifications for viral penetration resistance.
- REACH compliance deadlines:ECHA restriction proposals on per- and polyfluoroalkyl substances are compelling film converters to eliminate fluorinated chemistry from food-contact and medical packaging lines.
- Baden-Württemberg technical textile clustering:Concentrated R&D facilities in Stuttgart and Reutlingen are shortening development cycles for high-performance coated films serving automotive seating and industrial filtration.
Market Restraints
- Propylene feedstock volatility:European polypropylene resin prices fluctuate with naphtha cracking margins and import arbitrage from Middle Eastern producers, squeezing blown film converter margins.
- Recycling infrastructure gaps:Limited industrial-scale capacity for multilayer film separation and purification in Eastern Europe constrains post-consumer recycled content claims for sustainability-minded OEMs.
- Biodegradation performance trade-offs:PLA and PHA formulations meeting EN 13432 composting standards often sacrifice tensile strength and heat resistance versus conventional polyethylene, restricting application scope.
Strategic Opportunities
- Poland and Czech Republic manufacturing expansion:Lower energy costs and proximity to German automotive OEMs are attracting cast extrusion investments for technical textile backings and synthetic leather substrates.
- CSRD-mandated supply chain disclosure:The Corporate Sustainability Reporting Directive creates service revenue pools for film suppliers offering certified carbon footprint documentation and blockchain traceability systems.
- Digital printing substrate convergence:Hybrid polyester-polyurethane films compatible with UV-cured and dye-sublimation inksets are capturing share in short-run apparel and soft signage applications.
Industry Challenges
- Polymer chemist talent scarcity:European universities produce insufficient graduates with specialized training in reactive extrusion and multilayer coextrusion die design, lengthening product development timelines.
- MDR certification complexity:Medical Device Regulation technical documentation requirements for Class I film components demand extended biocompatibility testing protocols, delaying market entry for novel formulations.
- Legacy solvent coating line retrofit costs:Converting to aqueous or hot-melt coating systems requires capital outlays for drying energy recovery and emissions control, straining mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Textile Films Market |
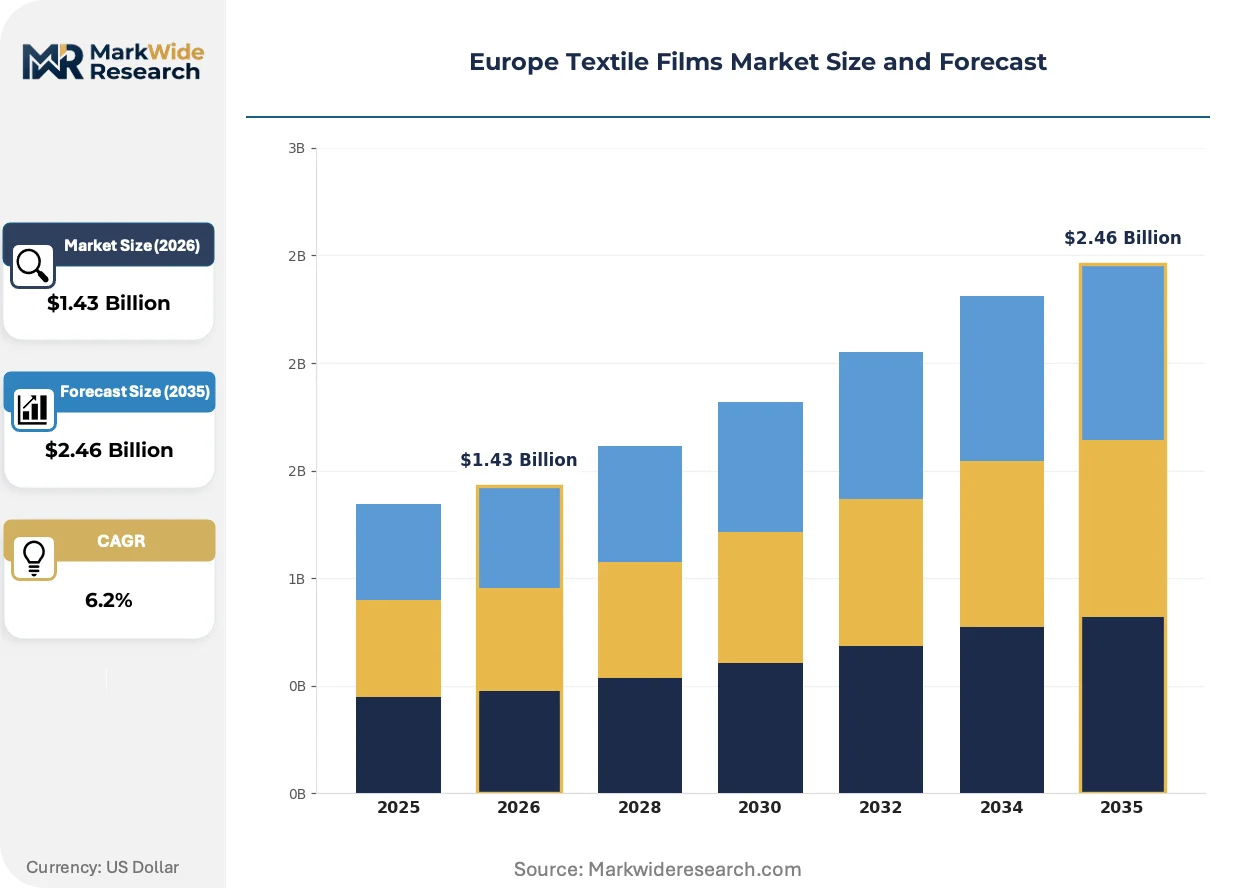
| Market Size in 2026 | $1.43 Billion |
| Market Size in 2035 | $2.46 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Films, Laminated Films, Breathable Films, Biodegradable Films Material: Polyethylene, Polypropylene, Polyurethane, Polyester Application: Apparel, Medical, Packaging, Upholstery End User: Manufacturers, Retailers, Wholesalers, Distributors |
| Companies Covered | RKW Group, Covestro AG, Toray Industries, Arkema, Schweitzer-Mauduit International, Berry Global, Evonik Industries AG, BASF SE, Fatra A.S., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Textile Films Market Shifts & Advancements
Reactive extrusion and inline spectroscopic monitoring are compressing quality assurance cycles, while regulatory disclosure mandates and procurement centralization are rewiring how film specifications reach end-use decision-makers.
Inline near-infrared spectroscopy paired with machine-vision defect detection is automating thickness uniformity control and gel contamination rejection in cast extrusion lines. Medical film suppliers in Germany and Switzerland are deploying these systems to reduce offline laboratory testing by half. The technology is automating compliance documentation for ISO 9001 and MDR traceability requirements, compressing audit preparation from weeks to days.
The EU F-Gas Regulation phase-down of hydrofluorocarbon blowing agents is forcing breathable film producers to adopt supercritical carbon dioxide foaming or calcium carbonate stretch-voiding technologies. Industrial consequences include reformulated adhesive layers and recalibrated lamination temperatures for hygiene and medical applications. converters serving Dutch and Belgian diaper and adult incontinence OEMs are most affected, with several completing line conversions ahead of the 2030 quota step-down.
Consolidated procurement by European hospital group purchasing organizations is compressing supplier rosters and unbundling technical support from base film supply contracts. Film converters must now bid through centralized tenders managed by entities like the French RESAH or German EKAP, replacing direct mill relationships with category managers. The shift is most visible in France and the Nordic countries, where regional health authorities have consolidated purchasing volumes exceeding 50 million euros annually for medical textiles and barrier fabrics.
Europe Textile Films Market Segmentation
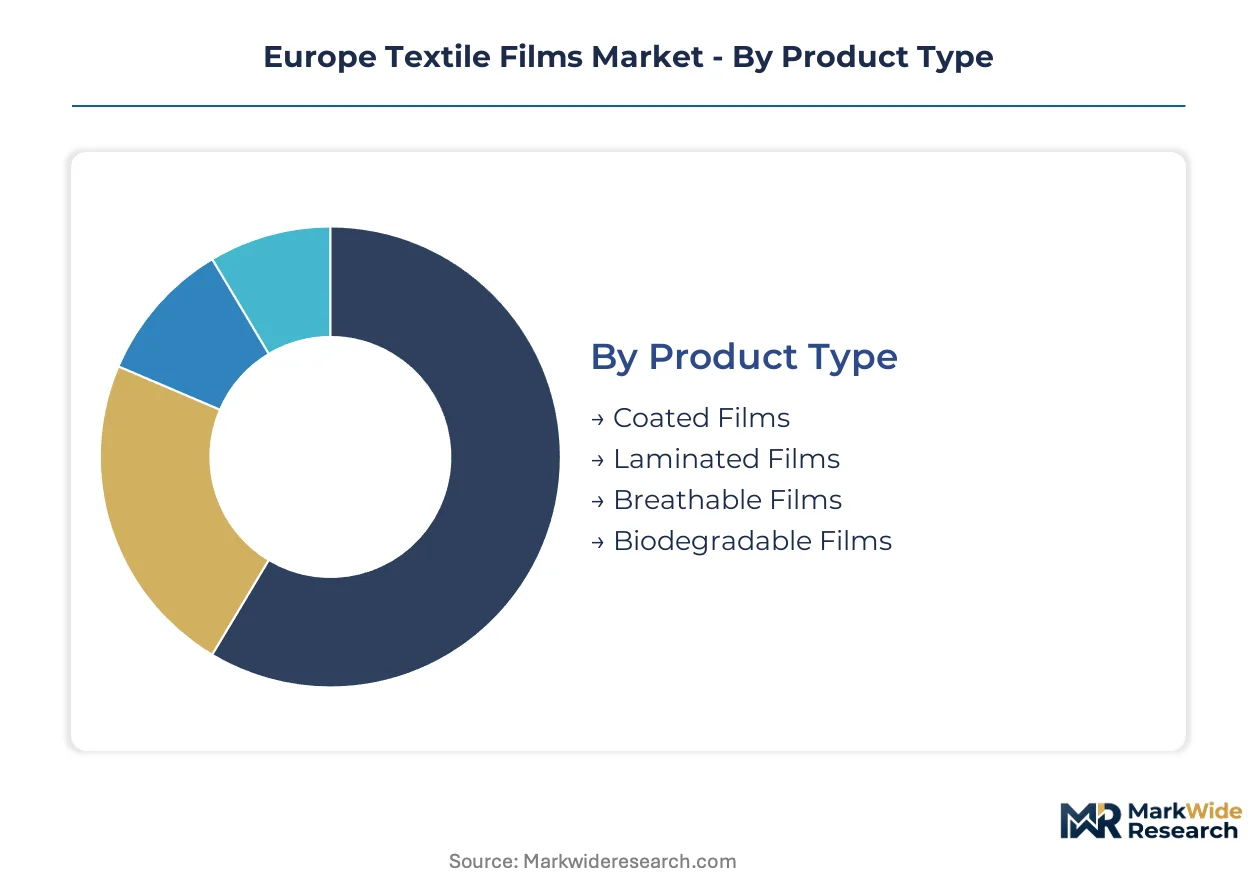
Technical specifications and regulatory compliance requirements reshape procurement patterns across textile film categories. European converters must align product portfolios with REACH-mandated formulation shifts and end-use certification demands.
Product Type:
Thickness, permeability, and barrier performance specifications determine selection logic for converters serving medical and industrial applications.
- Breathable Films:Microporous structures engineered via calcium carbonate stretch-voiding or supercritical CO2 foaming deliver controlled moisture vapor transmission. German and Swiss hospitals specify these for surgical drapes and isolation gowns under tightening viral penetration standards. The EU F-Gas Regulation phase-down accelerates conversion from hydrofluorocarbon-based processes.
- Coated Films:Solvent or aqueous polymer layers applied to woven or nonwoven substrates provide surface functionality and barrier protection. Mature cost structures sustain dominance in packaging and upholstery lines across France and Italy. Legacy solvent coating assets face retrofit pressure from emissions control mandates.
- Laminated Films:Multilayer constructions bond dissimilar polymers to combine mechanical strength with chemical resistance. Demand concentrates in automotive seating and industrial filtration from Baden-Württemberg technical textile clusters.
- Biodegradable Films:PLA and PHA formulations meeting EN 13432 composting standards serve single-use medical and hygiene applications. Tensile strength trade-offs limit deployment in high-performance apparel.
Mature deployment sits with Coated Films. Newer deployment is concentrated in Biodegradable Films.
Material:
Feedstock selection balances mechanical properties, chemical resistance, and recyclability credentials under EU Green Deal compliance timelines.
- Polyurethane:Segmented block copolymers deliver elastic recovery and solvent resistance for medical drapes and high-performance apparel. Covestro AG anchors premium supply from Leverkusen R&D facilities. REACH restrictions on isocyanate precursors tighten formulation windows.
- Polyethylene:Linear low-density and high-density grades dominate blown film extrusion for packaging and hygiene backings. RKW Group maintains margin control through backward integration into resin compounding. Naphtha cracking margin volatility squeezes converter economics.
- Polypropylene:Isotactic homopolymer and copolymer grades serve cast extrusion lines for technical textile backings. Automotive OEM proximity in Czech Republic and Poland drives manufacturing migration eastward.
- Polyester:Biaxially oriented polyethylene terephthalate films provide dimensional stability for digital printing substrates. UV-cured and dye-sublimation compatibility captures short-run apparel demand.
Volume concentration rests with Polyethylene. Margin expansion is steepest in Polyurethane.
Application:
End-use performance standards and certification complexity segment converter capabilities and customer relationships.
- Medical:Class I device components under MDR require biocompatibility testing and technical documentation. German hospital group purchasing organizations consolidate procurement through centralized tenders exceeding 50 million euros annually.
- Apparel:Waterproof-breathable membranes for outdoor and sportswear demand hybrid polyester-polyurethane constructions. Digital printing substrate convergence reshapes short-run production economics.
- Packaging:Food-contact films face EFSA migration limits and ECHA restriction proposals on persistent substances. Multilayer constructions complicate mechanical recycling pathways.
- Upholstery:Synthetic leather substrates and automotive seating backings leverage cast extrusion investments in Central Europe. Baden-Württemberg clusters anchor R&D for flame-retardant specifications.
Certification burden is heaviest in Medical. Application breadth is widest in Packaging.
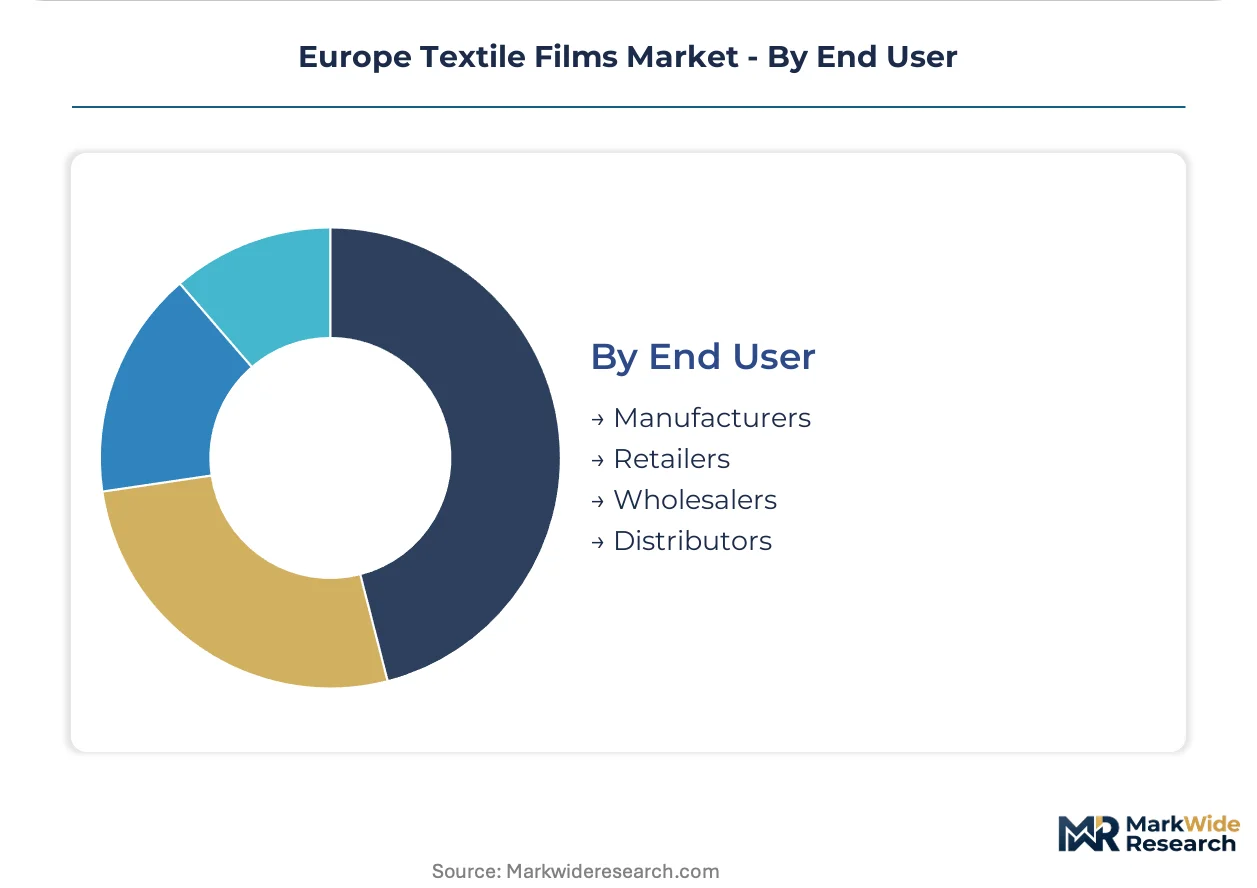
End User:
Supply chain position determines specification authority and technical support expectations.
- Manufacturers:Apparel and medical device OEMs dictate film specifications and audit converter quality systems. Direct mill relationships yield to category manager interfaces under consolidated procurement.
- Distributors:Inventory-holding intermediaries serve fragmented upholstery and packaging converters across Southern and Eastern Europe. Technical support unbundling from base supply contracts pressures service margins.
- Retailers:Private-label apparel and home textile brands specify certified sustainable content for consumer-facing claims. CSRD-mandated supply chain disclosure creates documentation service opportunities.
- Wholesalers:Volume aggregation for standardized grades serves mid-tier packaging and industrial applications. Price transparency compresses trading margins.
Specification authority concentrates with Manufacturers. Service intensity is highest with Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates production capacity for technical textile films, while demand spreads across hospital networks in France and the Nordics. Eastern European manufacturing migration is redrawing cost structures for automotive and hygiene applications.
Germany
Baden-Württemberg hosts R&D clusters for breathable polyurethane membranes serving surgical drape specifications under MDR. REACH compliance deadlines from ECHA force reformulation of fluorinated chemistries in medical packaging. Stuttgart and Reutlingen facilities shorten development cycles for automotive seating backings.
France
Hospital group purchasing organizations centralize procurement of barrier fabrics exceeding 50 million euros annually through RESAH tenders. EFSA migration limits constrain food-contact film formulations for packaging converters near Lyon. Technical textile R&D concentrates in the Hauts-de-France region around Lille.
Switzerland
Swissmedic certification requirements anchor premium medical film demand from Basel pharmaceutical clusters. Viral penetration resistance specifications tighten for isolation gown membranes supplied to Cantonal hospital systems. Swissmem industry association coordinates supply chain disclosure protocols ahead of CSRD implementation.
Poland
Lower energy costs attract cast extrusion investments for synthetic leather substrates serving German automotive OEMs. Limited multilayer film recycling infrastructure constrains post-consumer content claims for sustainability-minded converters. Manufacturing clusters emerge near Wrocław and Poznań.
Netherlands
Dutch and Belgian hygiene OEMs drive breathable film demand for diaper and adult incontinence applications. F-Gas Regulation phase-down accelerates conversion from hydrofluorocarbon blowing agents to supercritical CO2 foaming. Rotterdam logistics hubs facilitate resin import arbitrage from Middle Eastern producers.
Europe Textile Films Market Competitive Landscape
Top-tier vendors anchor premium polyurethane supply for medical specifications, while mid-tier converters compete on polyethylene volume and backward integration into resin compounding. Market structure shows moderate consolidation around German chemical conglomerates and specialized film fabricators. Three archetypes dominate: diversified materials conglomerates with captive polymer R&D, focused film converters with regional manufacturing footprints, and hygiene specialists with dedicated hygiene OEM relationships. Competitive moves center on capacity expansion in Central Europe and technology licensing for biodegradable formulations.
Within the diversified materials tier, Covestro AG and BASF SE exemplify conglomerate positioning through Leverkusen and Ludwigshafen R&D depth. RKW Group occupies a position among specialized converters with European manufacturing scale. Among focused chemical suppliers, Evonik Industries AG and Arkema represent specialty polymer positioning for high-barrier medical applications.
| Leading Market Players |
|---|
| RKW Group |
| Covestro AG |
| Toray Industries |
| Arkema |
| Schweitzer-Mauduit International |
| Berry Global |
| Evonik Industries AG |
| BASF SE |
| Fatra A.S. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between REACH-compliant formulations and legacy chemistries bifurcates pricing power across the value chain, with premium polyurethane membranes commanding sustained margins while commodity polyethylene backings face relentless cost compression from naphtha volatility and import arbitrage.
Pricing Analysis
Margin tightening in polyethylene blown film traces to Middle Eastern resin import arbitrage and naphtha cracking margin volatility. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade REACH-certified formulations from industrial packaging grades. Price differentiation rests on MDR certification status and backward integration into resin compounding. German hospital GPOs exhibit lowest price sensitivity for viral penetration-rated membranes; packaging converters in Southern Europe show highest sensitivity to resin index movements.
Supply Chain Analysis
Single-source vulnerability sits with German Baden-Württemberg clusters for breathable polyurethane R&D and Leverkusen-Ludwigshafen polymer production. Raw material dependencies draw from Saudi naphtha feedstocks, Belgian isocyanate precursors, and Dutch calcium carbonate stretch-voiding agents. Supply chain risk centers on ECHA restriction timelines for fluorinated chemistry phase-outs. Distribution runs through Rotterdam-Antwerp logistics hubs for resin importation and Stuttgart-Reutlingen technical textile clusters for finished film conversion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance cost curves erect formidable barriers-to-entry moats around incumbent film converters, with ECHA restriction timelines accelerating R&D amortization advantages for established players possessing dedicated polymer chemistry teams.
For Market Incumbents: Deploy supercritical CO2 foaming technology conversion ahead of F-Gas Regulation quotas to capture premium breathable film positioning from laggard competitors. Anchor capacity expansion in Poland and Czech Republic to exploit energy cost differentials serving German automotive OEM proximity. Consolidate technical textile clusters through selective acquisition of solvent-coating converters facing retrofit capital strain. For New Entrants and Emerging Players: Hygiene OEM procurement managers in Netherlands and Belgium represent the most penetrable channel partner type for biodegradable film formulations meeting EN 13432 standards. White-space concentrates in short-run digital printing substrates for apparel applications where hybrid polyester-polyurethane constructions displace conventional coated films. Go-to-market through CSRD documentation service bundling creates differentiation against commodity suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with specialized film converters possessing backward-integrated resin compounding given polypropylene feedstock volatility and margin compression dynamics. Long-term viability favors archetypes with demonstrated MDR certification pathways and hospital GPO contract tenure. Monitor ECHA restriction proposal advancement as inflection signal for fluorinated chemistry elimination timelines and reformulation capex demands.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | RKW Group's captive polyethylene supply insulates margins from naphtha arbitrage volatility. |
| Supercritical CO2 Foaming Conversion | F-Gas Regulation compliance secures breathable film supply contracts from Dutch hygiene OEMs. |
| CSRD Documentation Service Launch | Blockchain traceability systems capture service revenue from retailer sustainability disclosure mandates. |
| Central European Capacity Expansion | Polish manufacturing clusters exploit energy cost advantages for automotive seating substrate supply. |
| Biodegradable Formulation Certification | EN 13432 compliance opens single-use medical applications constrained by PLA tensile trade-offs. |
Research Methodology
Trade databases, ECHA restriction proposal filings, and SEC 10-K chemical segment disclosures formed the secondary backbone, cross-referenced with primary interviews of film converter plant managers, polymer procurement leads at German automotive OEMs, and hospital GPO contracts managers. Bottom-up and top-down triangulation validated volume estimates across breathable, coated, laminated, and biodegradable film categories.
Bottom-up modeling of extrusion line capacity utilization and resin consumption patterns anchored volume projections, while top-down macroeconomic drivers calibrated value trajectories across the analysis window. Segmentation dimensions spanned product type, material grade tier, end-use application, and regional production hub clustering. CAGRs derived from historical price-volume elasticity analysis and regulatory compliance cost curve modeling.
Caveats apply where ECHA restriction acceleration, naphtha cracking margin collapse, or multilayer recycling infrastructure breakthroughs could materially shift the outlook. Forecasts reflect assumptions around REACH enforcement intensity and hospital procurement consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Plastic Dielectric Films Market
Specialty Materials
Cellulose Gel Market
Specialty Materials
Asia-Pacific Colloidal Silica Market
Specialty Materials
Alginate Films Market
Specialty Materials
Solar Backsheet Films Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
North America Solar Control Window Films Market
Specialty Materials
Global Cellulose Esters Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Specialty Polyamides Market
Specialty Materials
Rigid Polyurethane Foams Market
Specialty Materials
Super-Hard Material Market
Specialty Materials
Magnesium Fluoride Market
Specialty Materials
Europe Microspheres Market