
 Decorative Surface Films Market | 2026-2036
Decorative Surface Films Market Size, Share, and Industry Trends Forecast 2026-2036
Decorative Surface Films Market Outlook
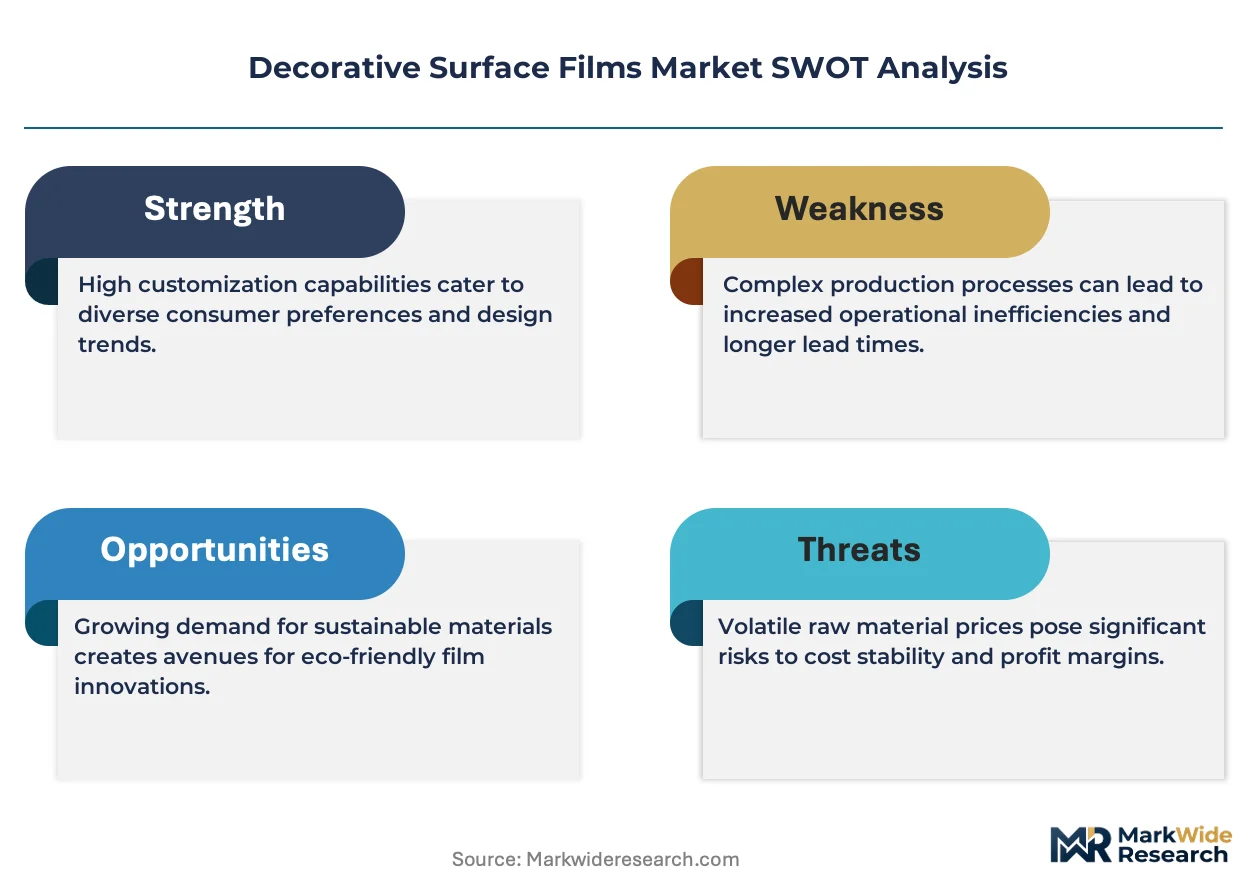
Polypropylene is restructuring decorative surface film economics as brand owners and laminators seek lower-density alternatives to PVC across furniture and automotive programs. Leonhard KURZ leverages its hot-stamping and transfer metallization expertise to dominate premium automotive interior applications. Avery Dennison Corporation anchors North American distribution through extensive converting partnerships with sign shops and fleet wrap installers. Covestro AG specializes in high-performance polyurethane coating raw materials that enable scratch-resistant appliance and electronics finishes.
Decorative surface films are engineered multilayer substrates—typically 12 to 250 micrometers thick—combining polymeric carriers with pigmented, printed, or metallized functional layers applied through extrusion, calendering, or adhesive lamination processes; their primary purpose is to simulate woodgrain, stone, metal, or custom graphics on substrates ranging from MDF panels to automotive fascias and consumer electronics housings. PET films command the premium tier in electronics and appliance coating due to dimensional stability and thermal resistance, while PVC films retain volume leadership in furniture and interior decoration despite regulatory headwinds in European markets. Metalized films represent the fastest-growing technology segment as vacuum-deposited aluminum and proprietary alloy layers enable lightweight reflective finishes without solid metal substrates.
REACH restrictions on phthalate plasticizers and heavy metal pigments constrain PVC formulation flexibility across EU member states, while the US EPA and state-level California Air Resources Board rules on volatile organic compound emissions shape adhesive and coating specifications for interior applications. China's GB standards and evolving MEE enforcement on industrial emissions are elevating compliance costs for domestic film converters serving export and local appliance markets. Stakeholders must monitor regulatory divergence between jurisdictions to determine where reformulation investments, regional sourcing shifts, or substrate transitions will yield sustainable access to premium specification markets.
Market Dynamics
REACH chemical restrictions on phthalate plasticizers and heavy metal pigments are forcing European furniture and automotive laminators to abandon PVC formulations, accelerating substrate transitions toward polypropylene and PET alternatives across specification-driven supply chains.
Growth Catalysts
- Automotive Interior Premiumization:OEMs in Germany, Japan, and the United States now specify metallized and textured finishes for fascias and instrument panels, creating specification pull for vacuum-deposited aluminum films.
- REACH Compliance Deadlines:ECHA enforcement windows for restricted substance lists are compelling European converters to validate alternative chemistries, opening procurement slots for compliant film suppliers.
- Appliance Export Manufacturing:China's GB standards alignment with EU emission norms is elevating film quality requirements for washing machine and refrigerator panels bound for European retail channels.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and PET resin prices track naphtha and paraxylene markets, compressing converter margins during upstream commodity spikes.
- Adhesive Solvent Regulations:US EPA and California Air Resources Board VOC emission limits constrain formulation flexibility for pressure-sensitive laminates used in interior architectural applications.
- Metallization Equipment Concentration:Vacuum deposition roll-coaters cluster in Germany, Japan, and South Korea, creating capacity bottlenecks for automotive programs requiring mirror-finish specifications.
Strategic Opportunities
- India Residential Furniture Scale-Up:Domestic manufacturers serving metro housing booms in Mumbai and Bangalore lack indigenous decorative film supply, creating import substitution potential for compliant regional production.
- Consumer Electronics Texturing:Laptop and smartphone OEMs are specifying soft-touch polyurethane-coated films for housing applications, diverting volume from traditional paint and plating processes.
- EU Green Deal Circular Economy Mandates:Design-for-recycling requirements for automotive interiors are favoring mono-material polypropylene constructions over multi-layer PVC alternatives in new platform development.
Industry Challenges
- Color Matching Expertise Scarcity:Metallized film converters face acute shortages of technicians capable of calibrating vacuum deposition thickness to achieve consistent optical properties across production lots.
- Multi-Jurisdiction Certification Burden:Suppliers serving EU, US, and Chinese appliance markets must maintain parallel testing protocols for flame retardancy, food contact, and electrical insulation specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decorative Surface Films Market |
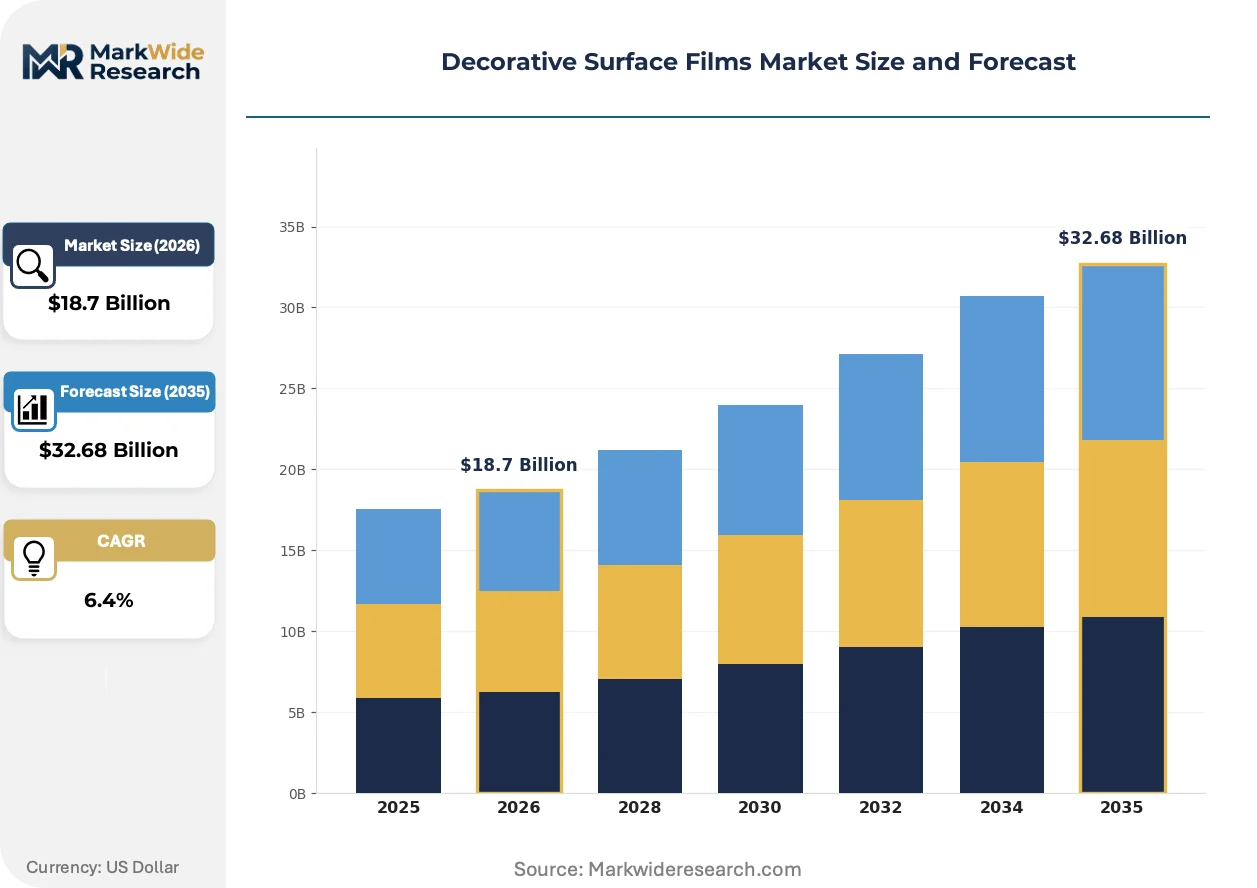
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC Films, PET Films, Polypropylene Films, Metalized Films End User: Automotive, Electronics, Furniture, Home Decor Application: Interior Decoration, Exterior Wrapping, Appliance Coating, Signage Technology: Printing, Laminating, Embossing, Coating |
| Companies Covered | Leonhard KURZ, Oracal, 3M Company, Mactac, Hexis, Avery Dennison Corporation, Covestro AG, Cosmo Films Ltd., LG Hausys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decorative Surface Films Market Strategic Shifts
Digital printing and water-based coating chemistries are compressing minimum order quantities and lead times, enabling mass customization in decorative surfacing while challenging the economics of traditional gravure and flexographic production.
Electron-beam-cured polyurethane topcoats are decentralizing high-performance scratch resistance from centralized coating lines to regional converting operations. Tier-two automotive suppliers in Poland and Mexico are adopting compact EB units to serve just-in-sequence interior programs without shipping unfinished film to Germany for final coating. This distributed capability model is compressing logistics costs and hedging against single-source supply concentration.
REACH Annex XVII expansions on per- and polyfluoroalkyl substances are eliminating fluorinated surface treatments from decorative film specifications. ECHA's restriction proposals are forcing coating raw material suppliers to reformulate stain-resistant top layers using silicone and hybrid inorganic-organic chemistries. Furniture and kitchen cabinet laminators in Italy and Spain are accelerating validation of PFAS-free alternatives ahead of enforcement timelines.
Fleet wrap installers and architectural sign fabricators are consolidating purchasing through national distribution cooperatives, displacing fragmented local supplier relationships. These buyer groups negotiate specification-grade film volumes directly with manufacturers, bypassing traditional regional distributors. The channel restructuring is most visible in the United States, where nationwide vehicle fleet branding contracts now route through three major purchasing alliances serving sign shop networks.
Decorative Surface Films Market Segmentation
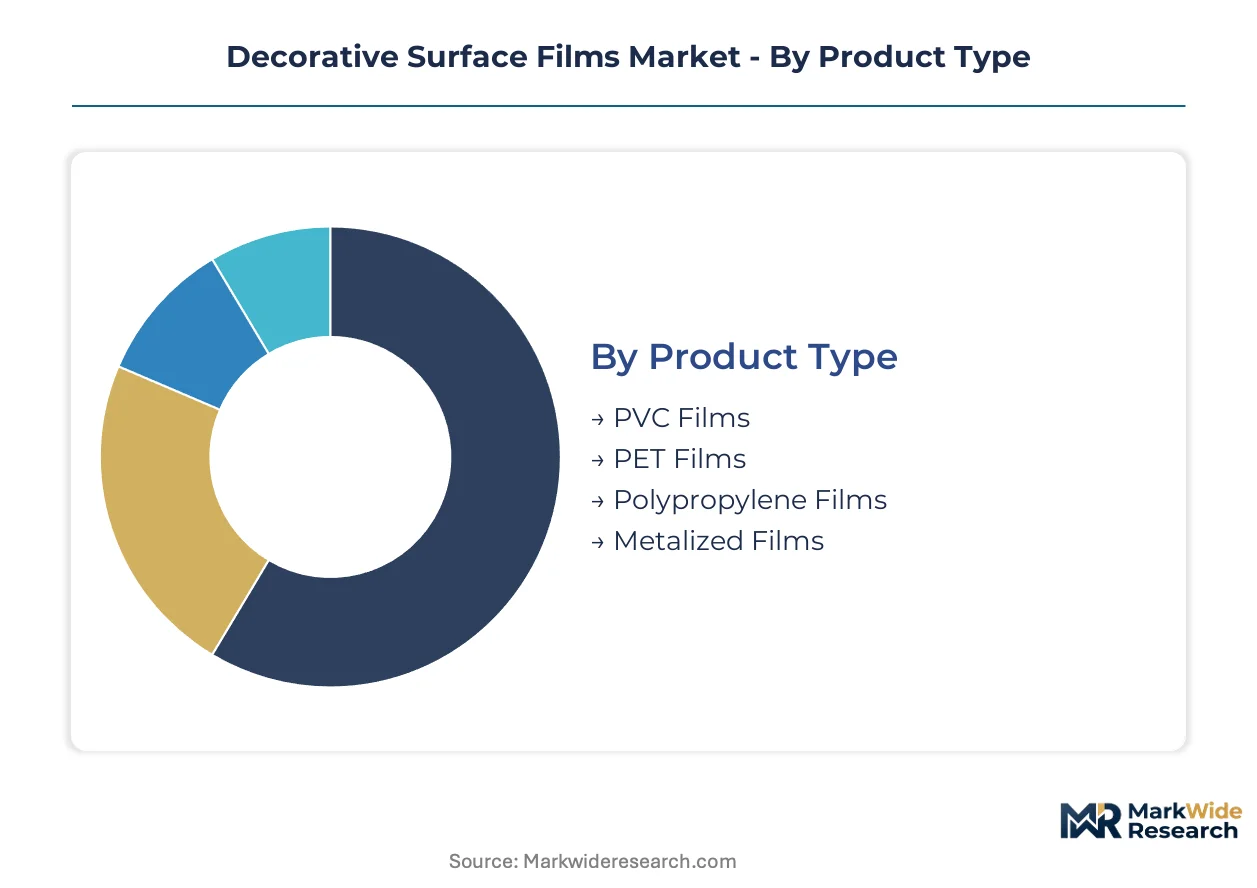
Segmentation in decorative surface films reveals how substrate chemistry, application environment, and finishing technology intersect to determine specification requirements and procurement economics. Understanding these divisions exposes where formulation investments and capacity expansion will capture premium positioning.
Product Type:
Replacement cycles for decorative films accelerate where regulatory pressure forces substrate transitions, creating upgrade windows for compliant alternatives.
- PVC Films:These plasticized polyvinyl chloride constructions dominate furniture lamination and interior architectural surfacing due to cost-efficient calendering and deep embossing capability. European REACH restrictions on phthalate plasticizers are compressing their specification viability in Germany, Italy, and France, forcing converters toward validation of alternative substrates.
- PET Films:Biaxially oriented polyethylene terephthalate delivers dimensional stability and thermal resistance for appliance panels and electronics housings requiring precise registration during thermoforming. Japanese and South Korean electronics OEMs specify PET for refrigerator door inserts and washing machine control panels bound for export markets.
- Polypropylene Films:Lower density and halogen-free chemistry position these films as the primary PVC replacement candidate across EU automotive and furniture programs.
- Metalized Films:Vacuum-deposited aluminum layers on polymer carriers enable lightweight reflective finishes without solid metal substrates.
PVC Films sits at the top of the volume ranking, with Metalized Films climbing the fastest.
End User:
Customer procurement sophistication varies sharply across end-use sectors, with automotive and electronics buyers imposing qualification protocols that exclude commodity converters.
- Automotive:OEM fascias, instrument panels, and interior trim require metallized and textured films validated through thermal cycling and UV exposure protocols. German and Japanese automakers specify vacuum-deposited finishes through tier-one suppliers in Poland and Mexico.
- Electronics:Soft-touch polyurethane-coated films for laptop and smartphone housings demand scratch resistance and fingerprint masking through electron-beam-cured topcoats.
- Furniture:Residential and commercial cabinetry laminators in India and Southeast Asia scale decorative film adoption as import substitution accelerates.
- Home Decor:Wall coverings and decorative panels utilize printed and embossed films with shorter qualification cycles than industrial applications.
Automotive commands the highest specification barrier, while Electronics expands most quickly as device OEMs displace paint and plating.
Application:
Application environment dictates durability requirements and adhesive chemistry, separating interior architectural programs from exterior exposure conditions.
- Interior Decoration:Wall panels, cabinetry, and furniture surfaces utilize pressure-sensitive and thermal laminating films with emphasis on scratch resistance and stain masking. Italian kitchen cabinet manufacturers are accelerating PFAS-free coating validation ahead of ECHA enforcement timelines.
- Exterior Wrapping:Fleet vehicle wraps and architectural facades demand cast vinyl and polyurethane films with UV stabilizers and conformability over complex curves. US fleet wrap installers consolidate purchasing through national distribution cooperatives bypassing regional distributors.
- Appliance Coating:Refrigerator and washing machine panels require films meeting GB standards alignment with EU emission norms for export-bound production.
- Signage:Digital printing compatibility and color consistency drive specification for wide-format graphic films.
Interior Decoration holds the largest installed base, though Exterior Wrapping gains share fastest through fleet branding consolidation.
Technology:
Process technology selection determines capital intensity, minimum efficient scale, and geographic distribution of finishing capability.
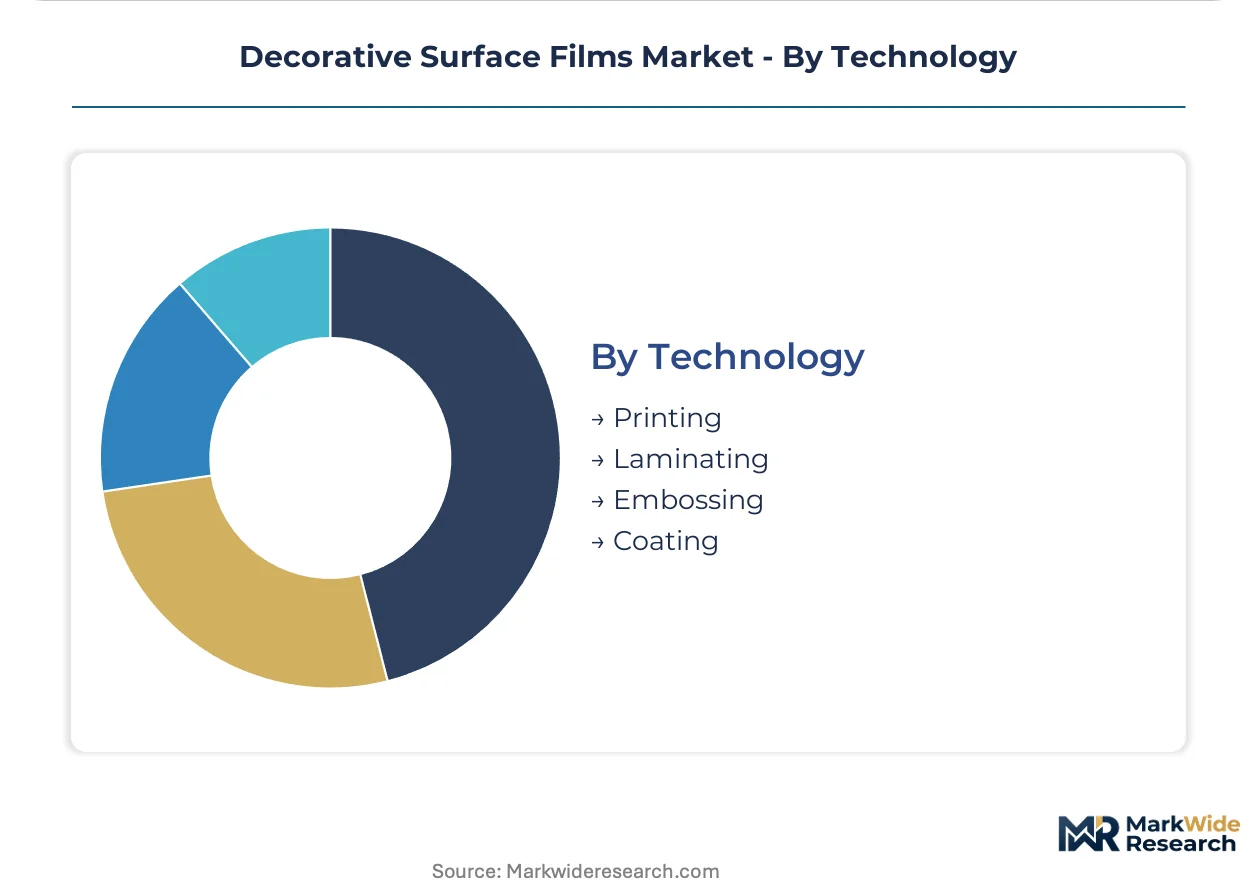
- Printing:Digital inkjet and electrophotographic systems compress minimum order quantities and enable mass customization, challenging gravure economics for short-run decorative patterns.
- Laminating:Adhesive and thermal bonding processes join decorative films to MDF, particleboard, and polymer substrates across furniture and construction applications.
- Embossing:Mechanical and laser-engraved roll patterns impart woodgrain, stone, and custom textures with depth variation critical to premium positioning.
- Coating:Electron-beam-cured polyurethane topcoats decentralize high-performance scratch resistance from centralized lines to regional converting operations in Poland and Mexico.
Printing anchors the technology mix by volume, with Coating showing the steepest expansion trajectory through distributed EB unit adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive clusters in Stuttgart and Munich drive metallized film specifications for instrument panels and fascias. ECHA REACH enforcement on phthalate plasticizers accelerates PVC substitution across EU furniture programs. Converter investments concentrate in Bavaria and Baden-Württemberg.
Germany
Tier-one automotive suppliers in Wolfsburg and Ingolstadt specify vacuum-deposited aluminum finishes for interior trim. ECHA REACH Annex XVII restrictions on heavy metal pigments force reformulation of legacy PVC laminates. Converter capacity clusters along the Rhine-Main corridor serving just-in-sequence programs.
United States
Fleet wrap installers in Texas and California consolidate purchasing through national distribution cooperatives. EPA and California Air Resources Board VOC emission limits constrain solvent-based adhesive formulations. Regional converting operations in the Midwest adopt electron-beam curing units to serve automotive interior programs.
China
Appliance manufacturers in the Yangtze River Delta scale decorative film coating for refrigerator and washing machine panels bound for export. GB standards alignment with EU emission norms elevates quality requirements. MEE enforcement on industrial emissions concentrates converter investments in Jiangsu and Zhejiang provinces.
India
Residential furniture manufacturers in Mumbai and Bangalore lack indigenous decorative film supply, creating import substitution openings. BIS certification requirements for imported laminates slow market entry for non-compliant suppliers. Domestic production investments concentrate in Gujarat and Maharashtra serving metro housing booms.
Japan
Electronics OEMs in Osaka and Nagoya specify PET films for appliance panels and device housings. METI guidance on chemical substance management shapes supplier qualification protocols. Metallization expertise concentrates in the Chubu region serving premium automotive programs.
Decorative Surface Films Market Competitive Environment
Global majors compete with regional champions across specification tiers and geographic coverage. The vendor base separates into metallization specialists, adhesive coaters, and resin raw material suppliers with limited overlap in end-to-end capability. Three archetypes dominate: integrated film converters with captive coating lines, specialized metallizers serving automotive qualification programs, and raw material suppliers controlling polyurethane and polypropylene chemistries. Competitive moves center on distributed electron-beam curing capacity and PFAS-free coating validation ahead of regulatory deadlines.
Within the metallization tier, Leonhard KURZ and Avery Dennison Corporation occupy positions anchored by hot-stamping and transfer expertise. Covestro AG exemplifies the raw material archetype, supplying high-performance polyurethane coating components that enable scratch-resistant finishes. These three entities represent distinct competitive vectors—specialized finishing, adhesive systems, and coating chemistry—rather than direct overlap in product portfolios.
| Leading Market Players |
|---|
| Leonhard KURZ |
| Oracal |
| 3M Company |
| Mactac |
| Hexis |
| Avery Dennison Corporation |
| Covestro AG |
| Cosmo Films Ltd. |
| LG Hausys |
| Others |
Value Chain & Pricing Dynamics
Naphtha and paraxylene price indices cascade through decorative surface film supply chains, compressing converter margins during upstream commodity spikes while stratifying procurement economics across automotive specification tiers, furniture commodity volumes, and electronics premium grades.
Pricing Analysis
Input-cost pass-through from polypropylene and PET resin markets governs converter pricing power, with petrochemical feedstock volatility transmitted differentially across customer segments. Three-tier pricing structure across premium automotive metallization, standard appliance lamination, and economy furniture wrapping reflects certification burden and qualification protocol intensity. Pricing pressure stems from REACH-driven reformulation costs as European converters absorb phthalate-free PVC alternative development. Fleet wrap installers consolidated through national purchasing cooperatives exhibit acute price sensitivity, while German automotive tier-ones prioritize specification compliance over unit cost.
Supply Chain Analysis
Photoresist-grade vacuum deposition equipment supply rests on German, Japanese, and South Korean precision engineering specialists, creating metallization capacity bottlenecks for mirror-finish automotive programs. Decorative surface film production draws from polypropylene resin feedstocks anchored in Middle Eastern and North American petrochemical complexes, biaxially oriented PET film from Taiwan and South Korea, and polyurethane coating raw materials from Covestro's European manufacturing network. Single-source vulnerability concentrates in vacuum deposition roll-coater technology, where three equipment builders control global capacity. Distribution runs through regional converting partnerships in Poland and Mexico serving just-in-sequence automotive programs, alongside national cooperative purchasing alliances displacing fragmented US sign shop supply relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Decorative surface film markets reward geographic arbitrage between European regulatory compliance costs and Asian manufacturing scale, with ECHA REACH enforcement timelines creating procurement window advantages for early PFAS-free validators against laggards facing reformulation surcharges.
For Market Incumbents: Hedge against PVC substitution acceleration by securing polypropylene raw material offtake agreements and validating mono-material constructions ahead of EU Green Deal circular economy mandates. Prioritize electron-beam curing capacity expansion in Poland and Mexico to defend automotive interior programs against distributed coating competition. Channel control through captive distribution partnerships with fleet wrap cooperatives protects volume against direct manufacturer purchasing consolidation.
For New Entrants and Emerging Players: Residential furniture manufacturers in India's Gujarat and Maharashtra industrial corridors represent an underserved buyer archetype lacking indigenous decorative film supply. White-space penetration targets include BIS-certified import substitution production and soft-touch polyurethane-coated films for consumer electronics housings displacing traditional paint processes. Go-to-market execution should anchor on technical service partnerships with Mumbai and Bangalore laminators facing quality validation gaps.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized metallization converters possessing automotive qualification protocols and PFAS-free coating validation ahead of ECHA enforcement timelines. Long-term viability across the projection horizon favors mono-material polypropylene specialists over multi-layer PVC legacy exposure. Watch ECHA Annex XVII expansion announcements as inflection indicators for accelerated substrate transition capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Validation | ECHA REACH Annex XVII compliance secures European automotive and furniture procurement slots ahead of enforcement. |
| Distributed EB Curing Capacity | Regional electron-beam unit deployment in Poland and Mexico compresses logistics costs for just-in-sequence automotive programs. |
| Backward Integration into Polypropylene Resin | Captive feedstock supply hedges petrochemical price volatility for PVC replacement volume scaling. |
| Automotive Qualification Protocol Completion | Thermal cycling and UV exposure validation unlocks tier-one supplier status with German and Japanese OEMs. |
| India Domestic Production Investment | BIS-certified manufacturing in Gujarat captures Mumbai and Bangalore residential furniture import substitution demand. |
Study Parameters
Bottom-up automotive, electronics, and furniture end-use modeling reconciled against top-down resin raw material and converting capacity tracking forms the analytical core of this study. Primary interviews with decorative film plant managers, procurement leads at appliance OEMs, distribution channel partners, and technical R&D directors combined with secondary validation from customs trade data, SEC filings of listed converters, ECHA restriction proposal documentation, and GB standards alignment reports. Triangulation across supply-side capacity announcements and demand-side qualification timelines anchors volume and value estimates.
Historical trendline analysis of substrate transition cycles, metallization equipment deployment patterns, and regulatory enforcement windows informed projection framework construction across the analysis window. Segmentation dimensions modeled include substrate chemistry tier, end-use industry qualification intensity, finishing technology capital requirements, and regional regulatory cluster alignment. CAGRs derived from fitted growth curves adjusted for REACH compliance deadline acceleration and fleet wrap purchasing consolidation inflection points. Industry-specific forecast inputs encompass vacuum deposition capacity utilization rates and electron-beam curing unit adoption trajectories.
Underlying measurement precision varies by segment; automotive metallization and electronics coating carry tighter precision than fragmented furniture commodity volumes. Forecasts reflect assumptions regarding ECHA enforcement timing, resin feedstock price correlation stability, and distributed coating technology adoption rates. Regulatory expansion beyond current Annex XVII proposals, petrochemical supply disruption events, and automotive platform standardization shifts constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
UK Lab-Grown Diamonds Market
Specialty Materials
Semiconductor O-Rings Market
Specialty Materials
Asia-Pacific Green Sic Market
Specialty Materials
Sheath Materials Market
Specialty Materials
Carrageenan Film Market
Specialty Materials
Middle East and Africa Anti-Friction Coatings Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Silicone Film Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Barium Borate Market
Specialty Materials
Latin America International CEP Market
Specialty Materials
Non-Semiconductor Neon Market
Specialty Materials
Carbon Mold Market
Specialty Materials
Methyl Silicone Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Glass Ionomer Cement Market