
 Global Elastic Adhesive Market | 2026-2036
Global Elastic Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Global Elastic Adhesive Market Analysis
The gap between solvent-based and advanced reactive curing systems is narrowing as manufacturers prioritize low-VOC formulations with rapid cure cycles. Henkel leverages its European R&D footprint to sustain leadership in automotive bonding applications. Sika anchors its position through construction-sector specialization, while Dow competes by extending silicone chemistry into electronics-grade reliability tiers.
Elastic adhesives are polymeric bonding agents engineered to maintain structural integrity under cyclic stress, typically formulated with elongation-at-break values exceeding 100% and shore hardness ranging from 20A to 60D depending on backbone chemistry. Polyurethane formulations dominate volume in construction sealing where flexibility and moisture resistance prove critical; silicone commands premium positioning in electronics and automotive under-the-hood applications where thermal stability exceeds 150°C continuous operation. Acrylic segments occupy faster-growing niches in consumer goods assembly where UV-cure speed and optical clarity drive substitution for mechanical fasteners.
EPA regulations on volatile organic compound emissions constrain solvent-containing formulations in the United States, while REACH authorization requirements in Europe restrict certain isocyanate precursors used in polyurethane systems. China's MEE enforces increasingly stringent hazardous substance limits on industrial chemical imports, reshaping supplier qualification protocols. Stakeholders must monitor evolving chemical hazard classifications across FDA, ECHA, and SAMR jurisdictions to anticipate formulation reformulation cycles and secure uninterrupted market access.
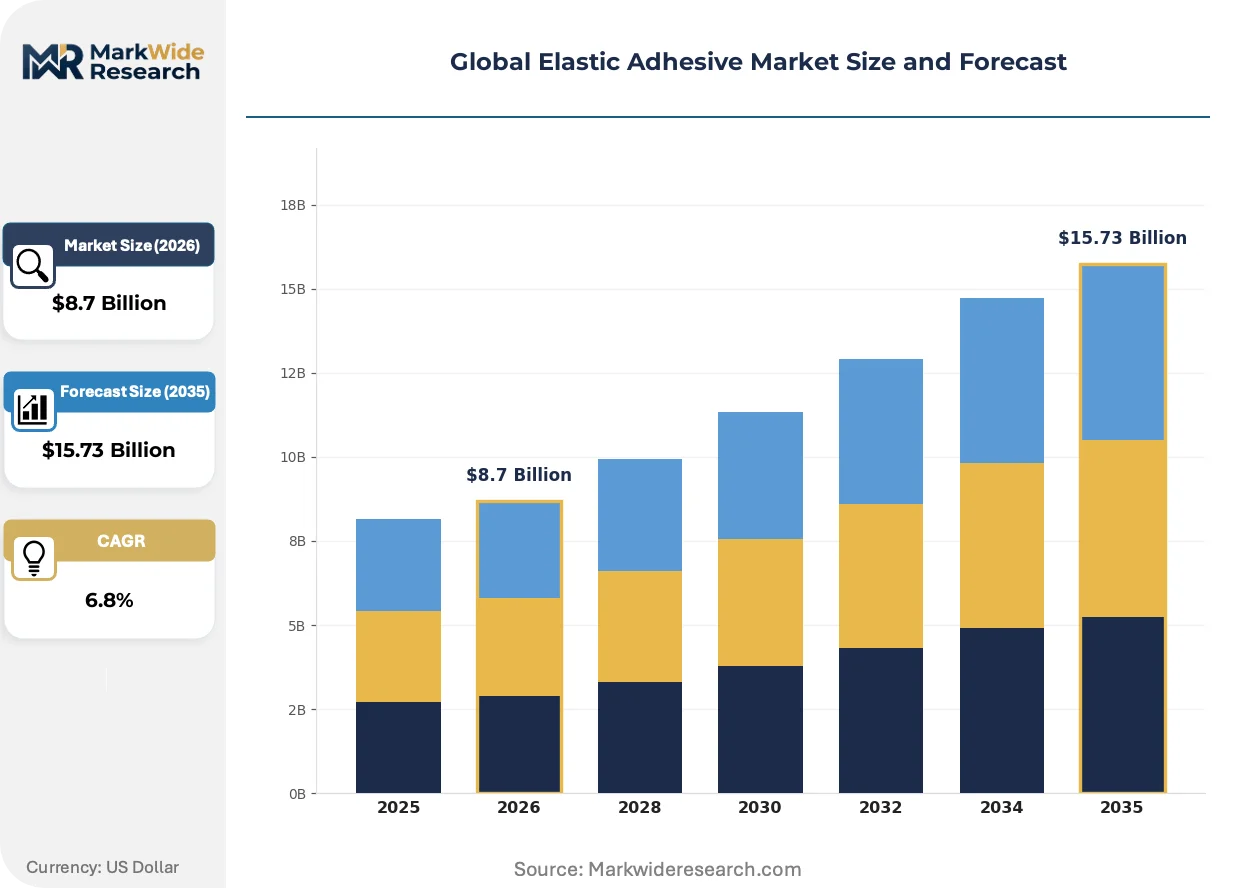
Market Dynamics
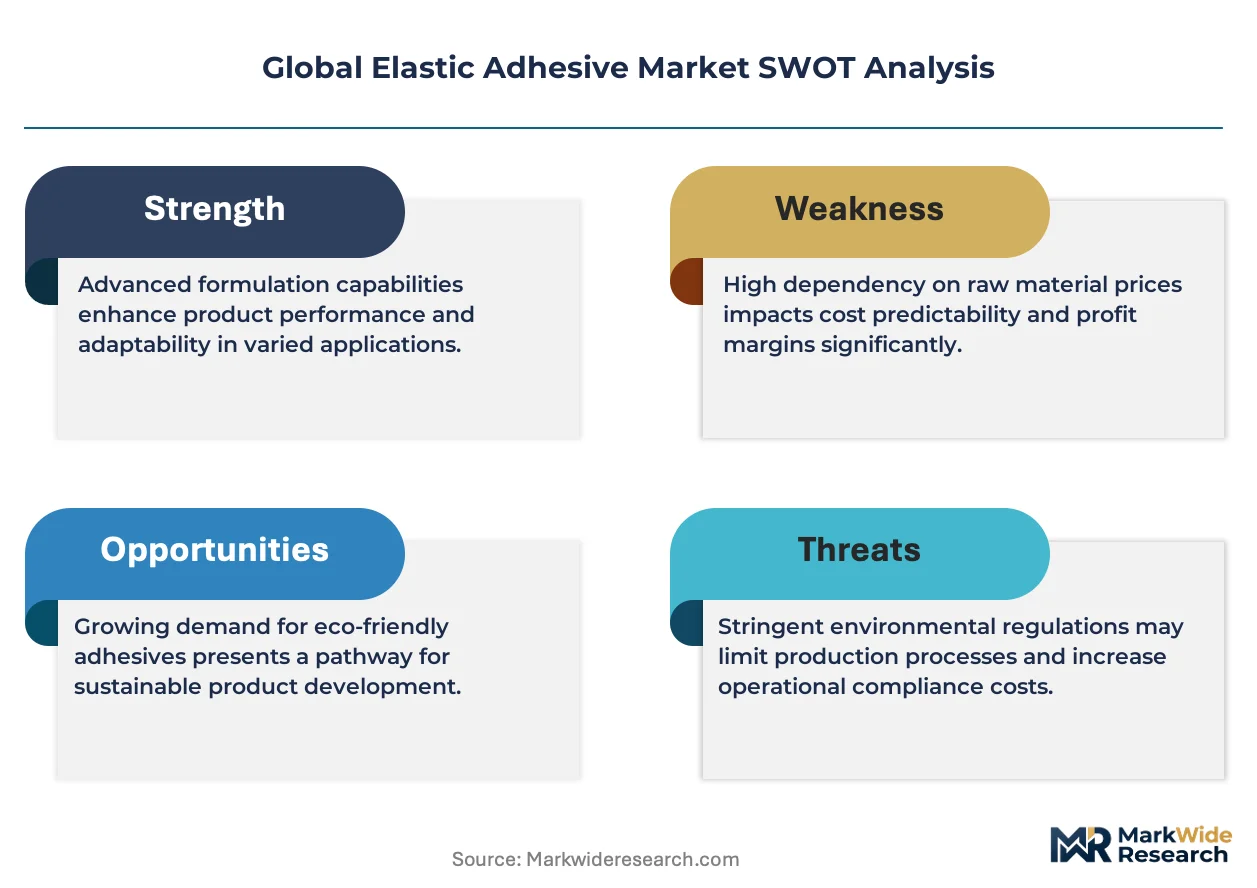
Automotive lightweighting mandates and construction energy-efficiency codes are compressing cure cycles and forcing solvent-phase elimination across polyurethane and silicone supply chains.
Growth Catalysts
- EPA VOC Emission Caps:US federal limits on solvent-based formulations accelerate waterborne and hot-melt elastic adhesive qualification in furniture and packaging assembly.
- Electric Vehicle Battery Enclosure Bonding:Automotive OEMs specify thermally conductive elastic adhesives for module-to-pack structural attachment, displacing mechanical fastening in Germany and China.
- Silane-Modified Polymer Advancement:Hybrid SMP chemistry eliminates primer requirements on difficult substrates, expanding applicator productivity in commercial glazing across the United States.
Market Restraints
- Aliphatic Isocyanate Supply Concentration:European and Chinese producers control 80% of HDI and IPDI feedstock, exposing formulators to price volatility and force majeure risk.
- REACH Authorization Delays:ECHA substance evaluation timelines extend 18-36 months for novel curing agents, freezing formulation pipelines ahead of sunset dates.
- Thermal Curing Energy Intensity:Oven-cured polyurethane systems require 120-150°C for 20-30 minutes, constraining adoption in heat-sensitive substrate applications.
Strategic Opportunities
- India PLI Scheme for Electronics:Domestic mobile and appliance assembly incentives create qualified demand for UV-acrylic and moisture-cure silicone bonding systems.
- Modular Construction Prefabrication:Off-site building panel assembly in Germany and the Netherlands specifies fast-cure elastic sealants for weatherproofing joints.
- Dual Carbon Goals Enforcement:China's MEE carbon intensity audits favor low-energy cure adhesives in state-funded infrastructure projects.
Industry Challenges
- Formulation Chemist Shortage:Specialized expertise in rheology modification and adhesion science concentrates at senior levels, constraining R&D team expansion.
- Multi-Jurisdiction Registration Burden:Parallel FDA, ECHA, and SAMR dossier preparation stretches regulatory affairs capacity for mid-tier suppliers.
- Legacy Equipment Retrofit Costs:Hot-melt and reactive systems require heated hose and tank infrastructure incompatible with ambient solvent-based application lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Elastic Adhesive Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic Application: Automotive, Construction, Electronics, Consumer Goods End User: Manufacturers, Contractors, Retailers, Distributors Distribution Channel: Direct Sales, Online Retail, Wholesale, Others |
| Companies Covered | Henkel, Sika, 3M, H.B. Fuller, Arkema, Wacker Chemie, Dow, Weicon, Threebond, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Elastic Adhesive Market Emerging Trajectories
Reactive chemistry platforms and digital manufacturing integration are compressing development cycles and enabling mass-customization of adhesive properties for specific substrate combinations.
UV-LED curable acrylic formulations are digitizing quality assurance in electronics assembly. Smartphone and wearable manufacturers in South Korea and Japan adopt inline spectroscopic cure monitoring. Real-time viscosity and conversion tracking is digitizing process control, reducing scrap rates and enabling predictive maintenance scheduling.
REACH restriction proposals on organotin catalysts are forcing tin-free polyurethane curing system qualification. European construction sealant producers accelerate bismuth and zirconium-based alternative validation. Germany's KBA and France's ANSM coordinate substance notification requirements, compressing reformulation timelines for automotive glazing applications.
Specification consolidation among tier-one automotive suppliers is concentrating procurement authority at platform engineering centers. Adhesive selection decisions migrate from plant-level purchasing to central technical committees in Stuttgart, Detroit, and Shanghai. German and US OEMs now mandate single-source qualification for structural bonding across model generations, locking in formulation partnerships for 7-10 year contract windows.
Global Elastic Adhesive Market Segmentation
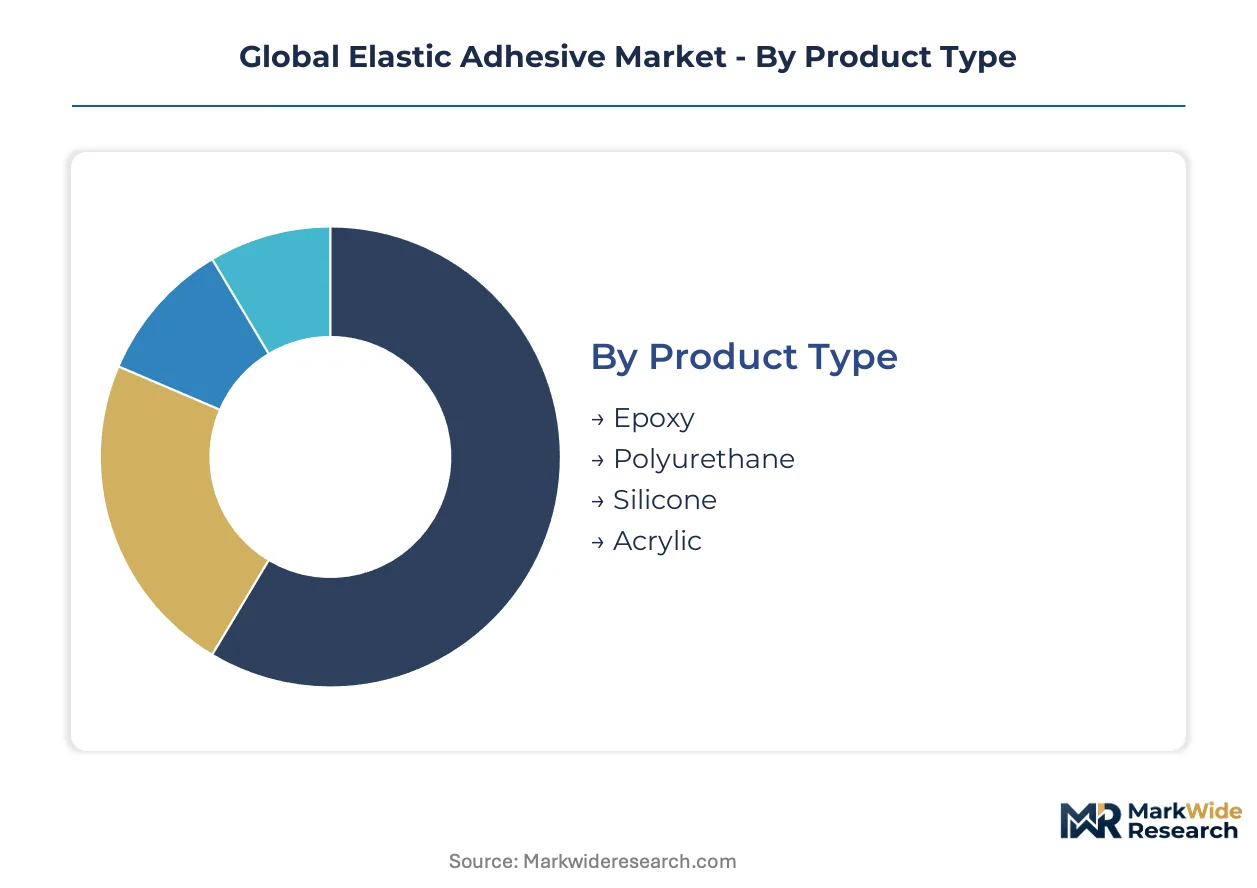
Elastic adhesive performance requirements diverge sharply across substrate chemistry and stress profiles. Segmentation reveals how formulation platforms align with cure speed, thermal tolerance, and elongation specifications demanded by distinct industrial workflows.
Product Type:
Chemistry backbone determines cure mechanism, thermal ceiling, and substrate compatibility across industrial specifications.
- Polyurethane:Moisture-cure or two-part systems deliver shore hardness tunability from 20A to 60D with elongation exceeding 400%. Construction sealant demand concentrates in Germany and the United States where energy-efficiency codes mandate air-tight building envelopes.
- Silicone:Condensation-cure and addition-cure formulations maintain elasticity from -60°C to 230°C continuous operation. Electronics and automotive under-the-hood applications in China and South Korea specify platinum-catalyzed grades for thermal management modules.
- Epoxy:Toughened formulations with rubber-modified backbones bridge rigid structural bonding with limited flexibility. Wind turbine blade assembly and industrial equipment mounting specify these systems.
- Acrylic:UV-cure and anaerobic variants achieve fixture strength in seconds. Consumer goods assembly lines favor these for optical clarity and rapid throughput.
Polyurethane commands the established base. The steepest expansion runs through silicone.
Application:
End-use environment dictates adhesive selection through thermal cycling intensity, chemical exposure, and regulatory compliance burden.
- Automotive:Structural bonding of dissimilar materials—aluminum to carbon fiber, steel to thermoplastics—requires crash-durable elasticity. Battery enclosure sealing in Germany and China specifies thermally conductive grades displacing mechanical fasteners.
- Construction:Expansion joint sealing, curtain wall glazing, and waterproofing membranes demand 25-year durability certification. Dutch and German prefabrication projects specify fast-cure hybrid systems for off-site panel assembly.
- Electronics:Display lamination, wearable device assembly, and semiconductor packaging require ionic purity below 10ppm. South Korean and Japanese manufacturers adopt inline spectroscopic cure monitoring for quality assurance.
- Consumer Goods:Appliance assembly, furniture construction, and packaging applications prioritize cost efficiency and rapid line speed over extreme environmental resistance.
Construction holds the volume anchor. Electronics is climbing the fastest.
End User:
Purchasing authority and technical specification involvement vary by scale and integration depth.
- Manufacturers:OEM engineering teams specify adhesives at platform design stage, locking formulations for multi-year production cycles. Central technical committees in Stuttgart, Detroit, and Shanghai consolidate procurement authority.
- Contractors:Field applicators prioritize open time, skin-over characteristics, and ambient cure reliability. Training certification requirements from Germany's KBA and France's ANSM shape product selection.
- Retailers:DIY channels stock simplified formulations with consumer-accessible application instructions and limited substrate preparation demands.
- Distributors:Technical distributors maintain blending and repackaging capabilities, offering localized inventory and application support.
Manufacturers dominate specification control. Contractors represent the most fragmented expansion vector.
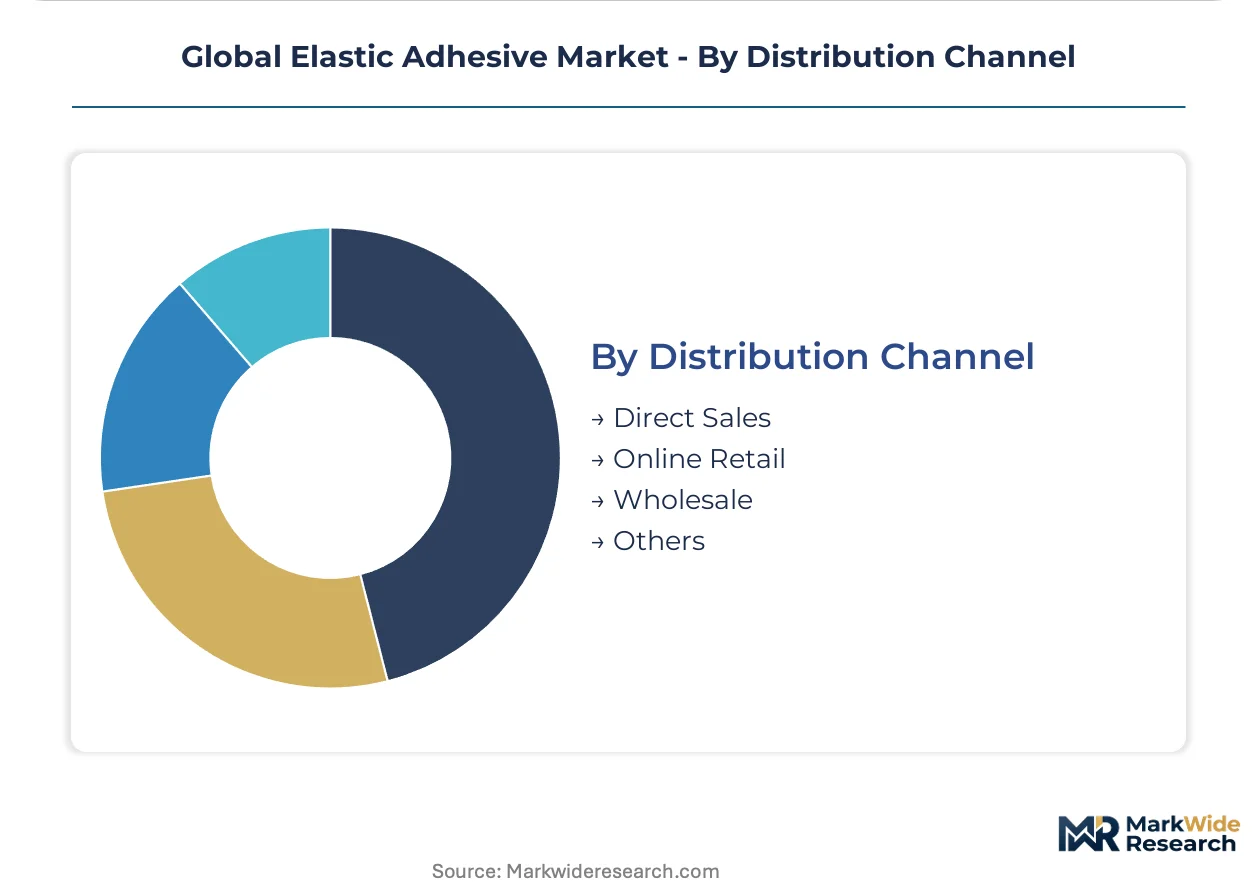
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic coverage needs.
- Direct Sales:Adhesive suppliers deploy technical field engineers for structural bonding qualifications at automotive and electronics OEMs. Long-term supply agreements span 7-10 year contract windows.
- Wholesale:Industrial distributors stock bulk quantities for construction and manufacturing sectors, providing just-in-time replenishment and credit terms.
- Online Retail:E-commerce platforms serve small-batch researchers, maintenance departments, and regional formulators with rapid fulfillment and technical documentation access.
- Others:Agent networks and cooperative purchasing arrangements address specialized regional markets with localized regulatory expertise.
Direct sales commands premium formulation partnerships. Online retail is gaining share fastest among emerging application developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German adhesive exports flow primarily into Dutch and Belgian construction supply chains, while Chinese manufacturers supply thermally conductive grades to South Korean battery assembly lines.
United States
Automotive OEMs in Detroit specify crash-durable elastic adhesives for aluminum-to-composite bonding. EPA VOC emission caps under the Clean Air Act constrain solvent-based formulation sales. Michigan and Ohio industrial corridors concentrate hot-melt qualification programs for furniture assembly.
Germany
Construction sealant demand concentrates in energy-efficiency retrofit projects and prefabricated building panel assembly. REACH authorization timelines from ECHA extend 18-36 months for novel curing agents. Stuttgart engineering centers consolidate adhesive specification authority across Volkswagen and Mercedes-Benz platforms.
China
Electric vehicle battery enclosure bonding drives thermally conductive silicone and polyurethane consumption. MEE carbon intensity audits favor low-energy cure adhesives in state-funded infrastructure. Yangtze River Delta manufacturing clusters supply module-to-pack bonding systems to CATL and BYD.
South Korea
Electronics manufacturers adopt UV-LED curable acrylics for display lamination and wearable device assembly. MFDS chemical substance notification requirements align with REACH substance restrictions. Seoul metropolitan area fabs integrate inline spectroscopic cure monitoring for quality assurance.
India
Domestic mobile and appliance assembly incentives under the PLI scheme create qualified demand for moisture-cure silicone systems. BIS certification requirements reshape supplier qualification protocols for imported formulations. Gujarat and Maharashtra electronics manufacturing clusters specify UV-acrylic bonding for consumer goods assembly.
Global Elastic Adhesive Market Vendor Landscape
Channel-controlling players compete with product-specialist players across formulation platforms and application engineering capabilities. The vendor base organizes into three tiers: multinational chemical conglomerates with full portfolio coverage, regional construction specialists with distribution depth, and technology-focused entrants in UV-cure and hybrid chemistries. Dominant competitive moves include backward integration into silane and isocyanate feedstocks, plus strategic partnerships with automotive OEM engineering centers for multi-year qualification cycles.
Among European chemical conglomerates, Henkel and Sika occupy positions exemplifying construction-specialist and automotive-bonding archetypes respectively. Dow represents the diversified materials science platform extending silicone chemistry into electronics-grade reliability tiers. These three anchors illustrate distinct strategic postures: formulation partnership depth, sector-specific technical service, and backbone chemistry control.
| Leading Market Players |
|---|
| Henkel |
| Sika |
| 3M |
| H.B. Fuller |
| Arkema |
| Wacker Chemie |
| Dow |
| Weicon |
| Threebond |
| Others |
Supply Flow & Price Mechanics
European and Chinese producers control 80% of HDI and IPDI aliphatic isocyanate feedstock, concentrating margin capture upstream while downstream formulators absorb volatility through long-term contract structures. This feedstock concentration forces polyurethane adhesive suppliers into either captive supply arrangements or indexed pricing clauses that pass through raw material swings.
Pricing Analysis
Current-generation silicone formulations command 40-60% premiums over prior-generation condensation-cure systems, while next-generation UV-LED curable acrylics are capturing price points between standard and premium tiers. Three-tier pricing structure across platinum-catalyzed electronics grades, construction-specified hybrids, and commodity furniture adhesives separates buyers by certification burden and thermal performance requirements. Price differentiation hinges on REACH compliance documentation and ISO 10993 biocompatibility tiers for medical-adjacent applications. Pricing pressure stems from aliphatic isocyanate spot market volatility, with automotive OEM procurement teams in Stuttgart and Detroit most sensitive to unit cost fluctuations.
Supply Chain Analysis
Export-control regimes on organotin catalyst precursors are restricting flow from European suppliers to Asian formulators, forcing qualification of bismuth and zirconium alternatives. Manufacturing gravity centers on Germany, China, and the United States, with Yangtze River Delta clusters feeding South Korean battery assembly lines and Dutch-Belgian construction supply chains drawing from German chemical corridors. Raw material dependencies rest on silane monomers from Wacker Chemie and Dow, platinum catalysts from South African refining, and acrylic oligomers from Japanese specialty chemical producers. Single-source vulnerability concentrates in high-purity electronics-grade silicones where three producers qualify for semiconductor packaging. Distribution runs through technical field engineers for automotive OEMs and industrial distributors for construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The elastic adhesive market rewards service-attach models where formulation partnership contracts and on-site technical support generate recurring revenue streams expanding faster than base chemical sales. Application engineering retainers and joint development agreements with automotive platform teams represent the fastest-growing revenue layer.
For Market Incumbents: Entrench position through backward integration into silane and isocyanate feedstocks, securing supply continuity against force majeure disruptions from European and Chinese producers. Lock in 7-10 year formulation partnerships with Stuttgart, Detroit, and Shanghai engineering centers before REACH sunset dates freeze specification windows. Prioritize tin-free polyurethane catalyst qualification to preempt regulatory obsolescence.
For New Entrants and Emerging Players: Build out UV-LED curable acrylic capabilities targeting Indian electronics manufacturing clusters under PLI scheme incentives, where incumbent presence remains thin. Penetrate modular construction prefabrication in the Netherlands and Germany through fast-cure hybrid sealant offerings. Lead with distributor technical service partnerships rather than direct sales infrastructure.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier formulators with captive silane-modified polymer technology and established automotive qualification dossiers. Long-term viability hinges on regulatory affairs capacity spanning FDA, ECHA, and SAMR jurisdictions. Watch ECHA substance evaluation timelines as inflection indicators—authorization delays beyond 24 months signal consolidation pressure on formulation pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Feedstocks | Captive HDI supply from German or Chinese production shields formulators from force majeure price spikes. |
| Tin-Free Catalyst Qualification | REACH organotin restrictions are forcing bismuth and zirconium system validation ahead of sunset dates. |
| Automotive Platform Engineering Partnerships | Stuttgart and Detroit OEMs now mandate single-source structural bonding across 7-10 year model generations. |
| UV-LED Curable Acrylic Capacity Expansion | South Korean and Japanese electronics manufacturers adopt inline spectroscopic cure monitoring for quality assurance. |
| India PLI Scheme Localization | BIS certification requirements for imported formulations create qualified demand for domestic moisture-cure silicone production. |
Methodological Framework
Cross-validation between primary interviews with adhesive formulators, automotive platform engineers, and construction procurement leads anchors the qualitative findings against secondary validation from ECHA substance databases, EPA VOC emission filings, and customs trade flow records. Plant managers at polyurethane and silicone production facilities provided capacity utilization perspectives, while technical R&D directors at tier-one suppliers detailed formulation pipeline timelines. Bottom-up segment sizing triangulates against top-down chemical industry production data from Cefic and ACC reports.
Calibration against historical price elasticity and substitution patterns informs the projection framework across the analysis window. Segmentation dimensions include chemistry backbone, cure mechanism, end-use industry, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating electric vehicle battery enclosure bonding intensity and construction energy-efficiency code adoption rates. Forecast inputs incorporate REACH authorization timeline probabilities and MEE carbon intensity audit enforcement patterns.
Stress conditions across aliphatic isocyanate supply disruption, REACH substance restriction acceleration, and automotive lightweighting mandate delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on cure technology substitution rates and regional regulatory harmonization timelines. Material shifts in ECHA evaluation timelines or MEE enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Urea Formaldehyde Concrete Market
Adhesives & Sealants
UV Adhesives Market
Adhesives & Sealants
Anti-Corrosion Tape Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
Asia-Pacific Construction Adhesives and Sealants Market
Adhesives & Sealants
Rubber Repair Adhesives Market
Adhesives & Sealants
Anti-Tacking Agents Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Waterproof Tapes Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Polyurethane Sealant Market
Adhesives & Sealants
Global Ceramic Adhesives Market