
 Jesmonite Market | 2026-2036
Jesmonite Market Size, Share, and Industry Trends Forecast 2026-2036
Jesmonite Market Insights
Traditional gypsum plaster is realigning toward water-based acrylic-modified cementitious systems as specifiers prioritize fire-rated, lightweight alternatives for interior and exterior applications. Allscot Ltd leverages its distribution network across British craft supply channels to sustain visibility among artisan producers. Resineco - Green Composites anchors its position through specialized formulations targeting sustainable construction certifications. Bohriali competes by emphasizing rapid-cure properties that reduce mold-cycle times for decorative concrete fabricators.
Jesmonite is a composite material comprising a reactive mineral base and a pure acrylic resin, typically formulated to achieve Class A fire ratings, tensile strengths exceeding 15 MPa, and casting thicknesses from 3 mm to structural sections. The material serves primarily as a moldable, pigment-stable substitute for concrete, plaster, and fiberglass-reinforced polymers in architectural and artistic fabrication. Jesmonite AC100 dominates volume production for decorative casting and small-batch sculpture due to its workability and cost accessibility, while 3D Printing technology within the Jesmonite category captures expanding interest from bespoke furniture studios seeking digitally fabricated, hand-finished surfaces. Repair Works applications represent a maturing revenue pool where infrastructure maintenance budgets sustain consistent offtake.
REACH registration requirements in Europe govern acrylic resin constituents and mineral filler sourcing, compelling reformulation investments from suppliers serving EU project specifications. BIS certification pathways in India and evolving EPA VOC emissions guidelines in the United States create divergent compliance landscapes that fragment formulation standardization. Stakeholders must monitor how regional fire-safety codes and embodied-carbon disclosure rules redirect specification authority among architects, contractors, and material procurement officers across their target geographies.
Market Dynamics
Water-based acrylic-modified cementitious systems are redirecting specification authority from traditional gypsum plaster toward fire-rated, lightweight alternatives as REACH compliance and low-VOC mandates tighten formulation requirements across construction procurement.
Growth Catalysts
- REACH Registration:ECHA oversight of acrylic resin constituents compels suppliers to reformulate toward compliant water-based systems, accelerating specification shifts among EU facade contractors.
- Architectural Cladding Demand:Interior designers and facade contractors prioritize Class A fire-rated surfacing for commercial interiors, pulling volume toward moldable mineral composites.
- 3D Printing Convergence:Bespoke furniture studios adopt digitally fabricated Jesmonite surfaces, expanding addressable demand beyond traditional casting workshops.
Market Restraints
- Acrylic Resin Price Volatility:Petrochemical feedstock fluctuations compress margin stability for formulators dependent on pure acrylic resin supply.
- UK Supply Concentration:Artisanal manufacturing clusters in the United Kingdom anchor premium product development, creating geographic vulnerability for non-UK distributors.
- Fiberglass Substitution:Glass-reinforced polymers retain cost advantages in large-scale architectural applications where hand-finished surfaces are non-critical.
Strategic Opportunities
- India BIS Certification Pathways:Emerging construction material standards create first-mover positioning for compliant suppliers targeting infrastructure maintenance budgets.
- Repair Works Vertical:Infrastructure maintenance expenditure sustains consistent offtake for structural rehabilitation applications with established specification channels.
- CSRD Embodied-Carbon Disclosure:EU corporate sustainability reporting mandates redirect procurement toward low-carbon composite systems with verified environmental product declarations.
Industry Challenges
- Artisan Skill Scarcity:Hand-finishing techniques required for premium decorative surfacing face generational transfer gaps as traditional craft networks contract.
- Multi-Jurisdiction Compliance:Divergent EPA VOC guidelines, BIS certification requirements, and REACH registration obligations fragment formulation standardization and extend product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jesmonite Market |
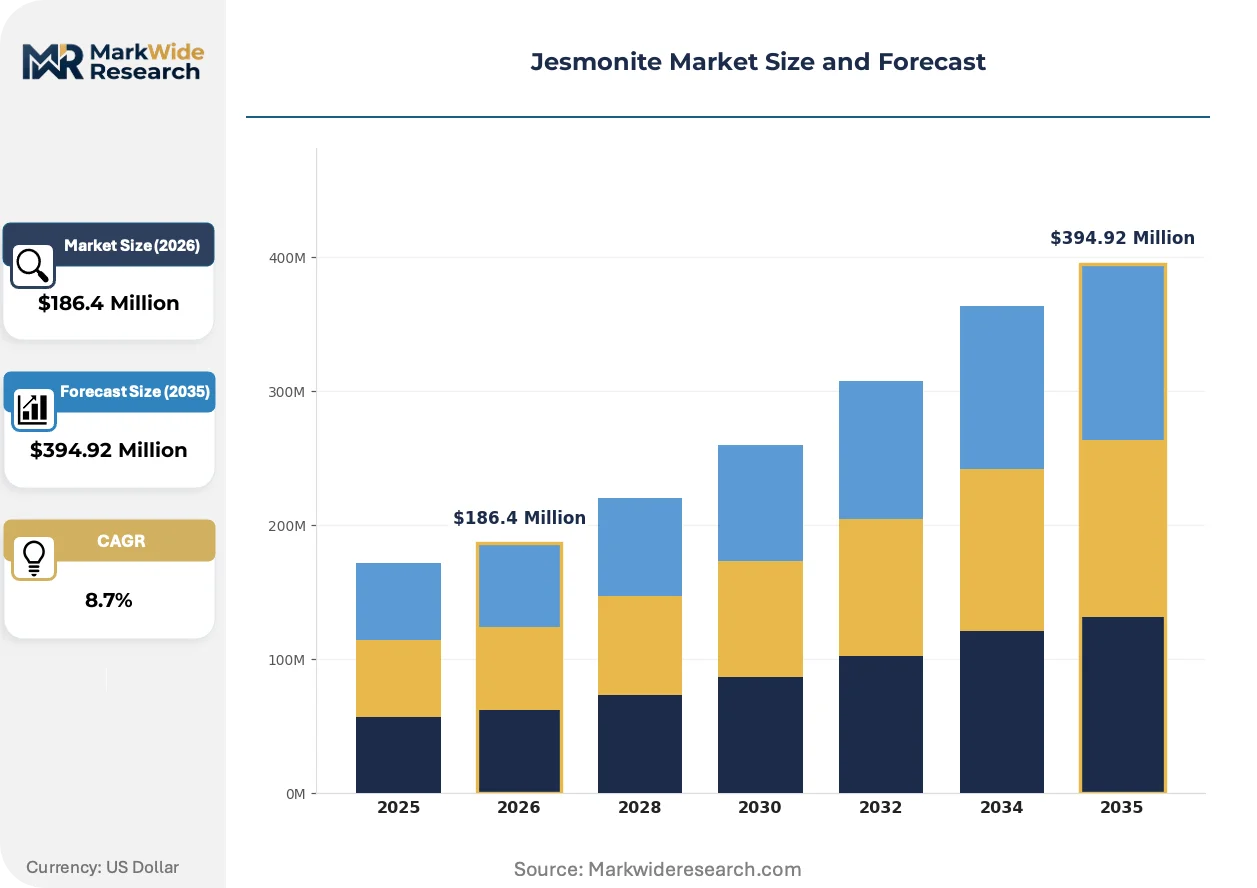
| Market Size in 2026 | $186.4 Million |
| Market Size in 2035 | $394.92 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jesmonite AC100, Jesmonite AC200, Jesmonite AC300, Jesmonite AC500 Application: Architectural Elements, Sculptures, Furniture, Repair Works End User: Construction, Art & Design, Signage, Specialty Manufacturing Technology: Casting, 3D Printing, Laminating, Coating |
| Companies Covered | Allscot Ltd, Resineco - Green Composites, Bohriali, Industrial Plasters, Lindberg & Lund AS, Globalchimica S.R.L., Epoxy S.R.O., Polysil Ltd., Coast Fiber-Tek Products Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jesmonite Market Trends and Innovations
Digital fabrication methods and regulatory disclosure requirements are compressing traditional specification cycles while elevating material transparency as a procurement criterion across architectural and artistic fabrication segments.
AC100 formulations dominate decorative casting through optimized workability and cost accessibility for small-batch production. Artisan studios and bespoke furniture fabricators adopt these systems at accelerating pace for interior surfacing commissions. This material convergence is unifying previously separate craft and industrial fabrication workflows into shared technical standards.
REACH compliance governs acrylic resin constituents and mineral filler sourcing across European project specifications. ECHA registration requirements compel reformulation investments from suppliers serving EU architectural procurement. Decorative concrete fabricators respond by consolidating supplier relationships around pre-registered resin systems with documented substance safety data.
Certification-driven preference shifts redirect authority toward procurement officers with verified environmental product declaration requirements. Architects and contractors now specify composite systems based on embodied-carbon metrics rather than traditional performance benchmarks alone. This behavioral change is most visible in United Kingdom commercial interiors where CSRD-aligned disclosure mandates penetrate downstream construction procurement.
Jesmonite Market Segmentation
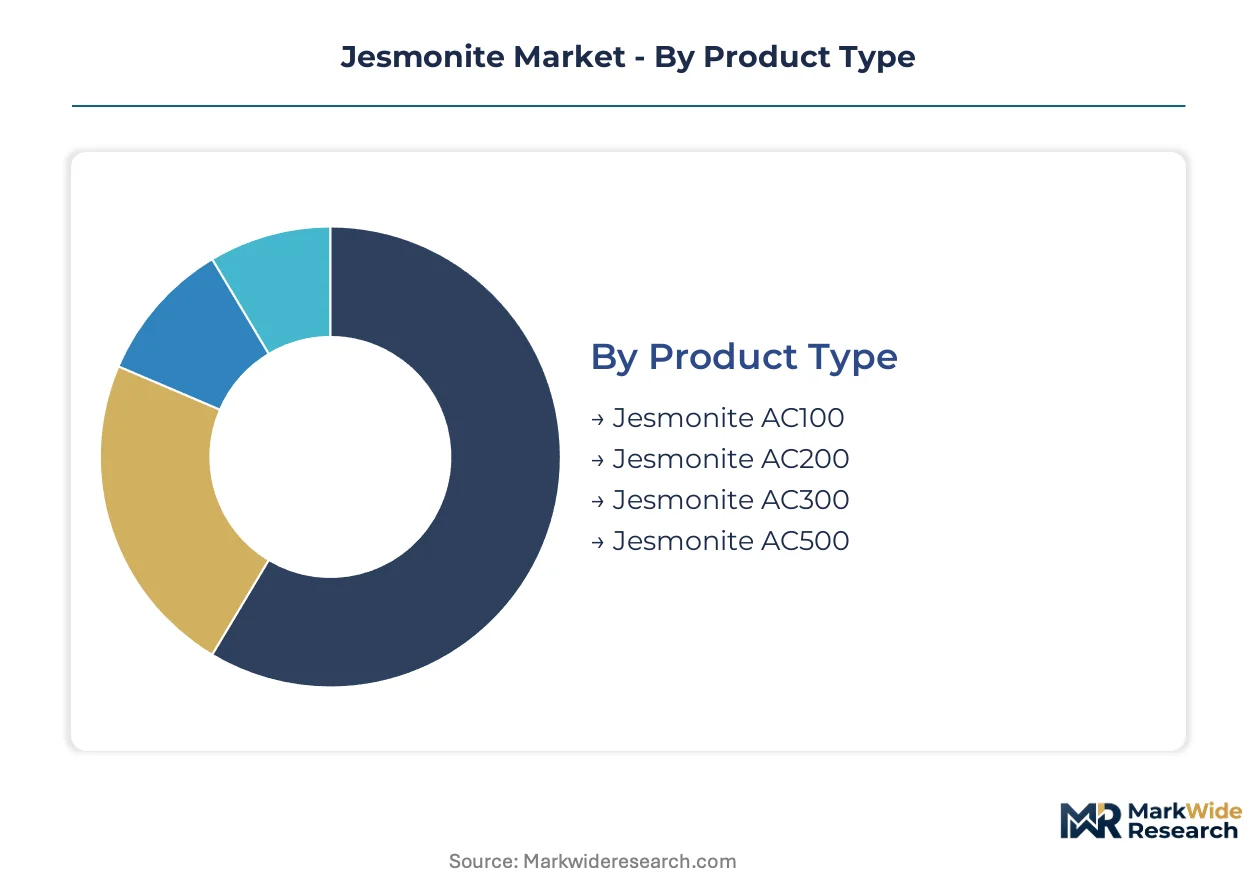
Formulation chemistry and fabrication method determine specification authority across Jesmonite procurement. Architects, artists, and industrial fabricators each prioritize distinct performance thresholds that fragment demand across product grades and processing technologies.
Product Type:
Volume production concentrates in entry-grade formulations, while premium grades command specialized architectural specifications requiring elevated fire ratings and structural performance.
- Jesmonite AC100:Standard water-based acrylic-modified gypsum composite optimized for decorative casting and small-batch sculpture work. Demand concentrates among United Kingdom artisan studios and bespoke furniture fabricators seeking pigment-stable, hand-finishable surfaces with Class A fire ratings. Cost accessibility sustains dominance in craft supply channels.
- Jesmonite AC200:Enhanced formulation with modified acrylic resin content for improved tensile strength and reduced water absorption. Facade contractors in commercial interiors specify AC200 for architectural cladding requiring sustained exterior exposure performance. REACH-compliant resin sourcing elevates procurement scrutiny among EU specification officers.
- Jesmonite AC300:High-performance grade targeting structural applications with elevated impact resistance and flexural strength thresholds.
- Jesmonite AC500:Premium formulation engineered for maximum durability and specialized industrial fabrication requirements.
Mature deployment sits with AC100 across established craft networks. Newer deployment is concentrated in AC200 as facade contractors adopt fire-rated surfacing for commercial interiors.
Application:
Specification authority migrates from artistic fabrication toward built-environment applications as regulatory disclosure requirements elevate material transparency in construction procurement.
- Architectural Elements:Molded cladding panels, column casings, and decorative cornice systems fabricated to Class A fire-rated specifications. United Kingdom commercial interiors drive volume as CSRD-aligned embodied-carbon disclosure redirects procurement toward low-carbon composite systems with verified environmental product declarations.
- Sculptures:Cast figurative and abstract works requiring fine surface detail reproduction and pigment stability across batch variations. Artisan studios in British manufacturing clusters sustain premium pricing for hand-finished commissions.
- Furniture:Bespoke seating, tables, and interior objects combining digitally fabricated substrates with hand-finished surfaces.
- Repair Works:Structural rehabilitation and infrastructure maintenance applications with established specification channels and consistent budget allocation.
Established revenue pools center on Repair Works through infrastructure maintenance budgets. Steepest expansion trajectory appears in Architectural Elements as facade contractors consolidate specification authority.
End User:
Customer type determines formulation complexity, with construction procurement prioritizing compliance documentation and art sectors emphasizing workability characteristics.
- Construction:Commercial builders and facade contractors specifying fire-rated surfacing for interior and exterior architectural applications. REACH registration requirements and evolving low-VOC mandates redirect specification decisions toward pre-registered water-based systems with documented substance safety data.
- Art & Design:Sculptors, interior designers, and bespoke fabricators prioritizing moldability, pigment stability, and hand-finishing characteristics. United Kingdom craft supply channels anchor distribution relationships.
- Signage:Fabricators of dimensional lettering, wayfinding systems, and branded environmental graphics.
- Specialty Manufacturing:Industrial producers of custom components requiring precise material specifications and batch consistency.
Procurement standardization advances fastest in Construction as compliance documentation becomes mandatory. Art & Design retains specification fragmentation across individual practitioner preferences.
Technology:
Processing method constrains achievable geometry and surface finish, with traditional casting retaining volume leadership while additive methods capture design-forward commissions.
- Casting:Conventional mold-based fabrication dominating volume production for decorative elements and structural components. Small-batch sculpture workshops and architectural precasters across British manufacturing clusters sustain equipment investment and technical skill transmission.
- 3D Printing:Additive fabrication of digitally designed geometries with subsequent hand-finishing for bespoke furniture and interior surfacing. Expanding interest from design studios seeking geometric complexity unavailable through mold-based methods.
- Laminating:Layered construction of thin-section composite skins for lightweight panel systems.
- Coating:Surface application of Jesmonite-based finishes over substrate materials for decorative effect.
Equipment concentration and skill availability favor Casting for standardized production. Capability investment is accelerating in 3D Printing as furniture studios adopt digitally fabricated workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Jesmonite concentrates in the United Kingdom, where artisanal manufacturing clusters originated the material and continue to anchor premium product development for decorative surfacing applications.
United Kingdom
Architectural cladding specifications and interior design commissions drive volume across British craft supply channels. REACH registration requirements govern acrylic resin constituents used in commercial facade applications. Artisan studios in London and the Midlands sustain hand-finishing expertise for bespoke furniture and sculptural work.
Germany
Facade contractors specify fire-rated mineral composites for commercial interiors requiring Class A certification. ECHA oversight of pure acrylic resin formulations compels suppliers to document substance safety data for EU project bids. Industrial fabricators in North Rhine-Westphalia consolidate procurement around pre-registered water-based systems.
United States
Low-VOC material mandates from the EPA redirect specification decisions toward water-based composite systems in construction procurement. Decorative concrete fabricators seek rapid-cure properties to reduce mold-cycle times for architectural elements. Design studios in California and New York adopt digitally fabricated surfaces for bespoke interior commissions.
India
Infrastructure maintenance budgets sustain consistent offtake for structural rehabilitation applications in repair works. BIS certification pathways for construction materials create compliance requirements for suppliers targeting government procurement channels. Fabricators in Maharashtra and Gujarat develop formulation adaptations for regional climate exposure conditions.
France
CSRD-aligned embodied-carbon disclosure mandates penetrate construction procurement decisions for commercial interiors. Architects specify composite systems based on verified environmental product declarations rather than traditional performance benchmarks alone. Specification authority concentrates in Paris-based procurement offices serving large-scale development projects.
Jesmonite Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with artisan supply channels favoring established distribution relationships while construction procurement prioritizes compliance documentation. The vendor base organizes around three strategic archetypes: UK-originated material specialists with craft network access, regional formulators adapting to jurisdiction-specific certification requirements, and industrial distributors consolidating procurement across decorative surfacing categories. Competitive moves center on geographic expansion into emerging certification markets and portfolio diversification toward digitally fabricated product lines.
Among UK-originated specialists, Allscot Ltd exemplifies the craft-channel archetype through sustained visibility across British artisan supply networks. Resineco - Green Composites occupies a position within the sustainability-focused tier, representing suppliers targeting construction certification requirements. Bohriali anchors the rapid-cure specialization segment for decorative concrete fabricators seeking reduced mold-cycle economics.
| Leading Market Players |
|---|
| Allscot Ltd |
| Resineco - Green Composites |
| Bohriali |
| Industrial Plasters |
| Lindberg & Lund AS |
| Globalchimica S.R.L. |
| Epoxy S.R.O. |
| Polysil Ltd. |
| Coast Fiber-Tek Products Ltd |
| Others |
Pricing and Supply Chain Analysis
Artisan hand-finishing expertise concentrated in United Kingdom craft networks creates labor-cost differentials that widen pricing-tier spreads between premium bespoke commissions and standardized architectural cladding. REACH-compliant resin sourcing and BIS certification investments fragment cost structures across supplier tiers, compressing margins for non-compliant entrants while sustaining premium capture among established British manufacturers.
Pricing Analysis
Volume production of AC100 decorative casting formulations operates on thin margins driven by petrochemical feedstock volatility in pure acrylic resin supply, while premium AC200 and AC300 grades for facade contractors sustain healthier spreads through REACH registration documentation and Class A fire-rating certification. Price differentiation hinges on compliance documentation depth and batch customization level, with standard-grade pigment-stable composites facing acute price erosion from fiberglass substitution in large-scale architectural applications. Construction procurement officers demonstrate lowest price sensitivity due to mandated low-VOC and fire-safety specifications, whereas craft supply channels and small-batch sculpture workshops exhibit highest elasticity, frequently substituting toward gypsum plaster alternatives when resin costs spike.
Supply Chain Analysis
Dual-sourcing requirements from EU facade contractors and Indian infrastructure procurement officers compel formulators to qualify multiple resin suppliers across United Kingdom, Germany, and India, insulating project bids from single-source disruption. Raw material flows draw from petrochemical complexes in Northwest Europe for acrylic resin constituents and mineral extraction operations in France and Spain for gypsum and aluminous cement fillers. Single-source vulnerability concentrates in specialty additive supply for rapid-cure formulations, where Bohriali and select British specialists control proprietary catalyst chemistry. Distribution runs through British craft supply channels for artisan-grade products and direct specification relationships with facade contractors for architectural volumes, with industrial distributors consolidating procurement across decorative surfacing categories in North American and Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in qualified artisan labor and REACH-registered resin capacity prop pricing power for incumbents with established British manufacturing footprints, creating durable margin structures against commodity substitution threats.
For Market Incumbents: To counter fiberglass-reinforced polymer cost advantages in large-scale architectural applications, Allscot Ltd and established British specialists should deepen backward integration into captive resin compounding capacity within REACH jurisdiction, while consolidating distribution control through exclusive craft supply channel partnerships that transmit hand-finishing expertise across generational transfer gaps. For New Entrants and Emerging Players: 3D Printing technology convergence offers the most penetrable wedge for digitally native furniture studios and design-forward architectural practices seeking geometric complexity unavailable through mold-based methods, with white-space concentration in California and New York bespoke interior commissions and Maharashtra infrastructure repair works requiring BIS-certified rapid-cure formulations. For Investors and Strategic Acquirers: Re-rating potential sits with sustainability-focused formulators holding pre-registered REACH documentation and verified environmental product declarations given CSRD-aligned embodied-carbon disclosure mandates penetrating EU construction procurement, with long-term viability hinging on acquisition of specialist firms with established artisan training networks rather than pure capacity plays, and the signal to watch being consolidation of specification authority among procurement officers with EPD requirements versus traditional architect-driven selection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | REACH-registered captive supply secures margin stability against petrochemical volatility for EU project bids. |
| Artisan Training Network Expansion | Generational skill transfer programs in Midlands and London clusters sustain premium pricing for hand-finished commissions. |
| BIS Certification Investment | Compliance pathways unlock government infrastructure procurement channels in Maharashtra and Gujarat repair works. |
| 3D Printing Capability Buildout | Digital fabrication adoption by California and New York studios expands addressable demand beyond mold-based casting. |
| Environmental Product Declaration Development | Verified EPDs align with CSRD mandates redirecting Paris-based procurement officer specification authority. |
Research Methodology
Multi-period observation of REACH registration timelines, BIS certification pathway developments, and artisan studio equipment investment patterns anchored the trend analysis, supplemented by interviews with British craft supply distributors, facade contractor procurement leads, ECHA regulatory affairs specialists, bespoke furniture studio founders, and Indian infrastructure maintenance engineers. Secondary validation drew from ECHA substance safety data filings, BIS construction material standards documentation, British craft supply channel sales records, EU corporate sustainability reporting disclosures, and SEC filings from listed chemical distributors. Bottom-up volume estimates from individual formulation grades triangulated against top-down construction spending projections and artistic fabrication market assessments.
The input-output matrix framed demand as a function of regulatory compliance requirements, fabrication technology adoption curves, and end-use substitution elasticity across the projection horizon. Segmentation dimensions modeled include product grade tier, application category, end-user type, and processing technology, with regional regulatory cluster and artisan skill availability as cross-cutting variables. CAGRs derived from regression analysis of historical specification shifts and forward projection of CSRD disclosure penetration, EPA VOC mandate evolution, and infrastructure maintenance budget allocations in target geographies.
Several conditions sit outside the modeled scope, including abrupt petrochemical feedstock disruptions, generational collapse of British hand-finishing expertise, and non-linear substitution toward bio-based composite alternatives. Forecasts assume continuation of current regulatory trajectories without harmonization between REACH, EPA, and BIS frameworks. Deviation in acrylic resin price volatility or ECHA substance restriction timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Global Consumer Foam Market
Specialty Materials
Global Cellulose Esters Market
Specialty Materials
Sheath Materials Market
Specialty Materials
Electroactive Polymers (EAP) Market
Specialty Materials
Retro Reflective Materials Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Europe Solar Control Window Films Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Open Cell Foam Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Carrageenan Film Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Compostable Cotton Swab Market