
 APAC Fluoroelastomer Market | 2026-2036
APAC Fluoroelastomer Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Fluoroelastomer Market Analysis
The performance gap between aerospace-grade terpolymers and general-purpose dipolymers is repositioning procurement strategies across the APAC fluoroelastomer value chain. Daikin Industries leverages captive fluorine chemistry to sustain premium positioning in semiconductor fabrication seals. Dongyue Group anchors its cost structure through backward integration into hydrofluoric acid feedstock. Gujarat Fluorochemicals competes on export scale, occupying a dominant share of India's domestic compounding capacity.
Fluoroelastomers are synthetic rubber compounds containing vinylidene fluoride and hexafluoropropylene, engineered to withstand temperatures exceeding 200°C while resisting aggressive fuels, acids, and solvents. Their primary purpose centers on static and dynamic sealing in environments where hydrocarbon-based elastomers degrade rapidly. Terpolymer formulations lead margin pools due to aerospace certification requirements and extended service intervals. Automotive O-ring demand is accelerating fastest as turbocharged direct-injection engines proliferate across Chinese and Indian passenger vehicle platforms. Fluorosilicone remains a niche segment, specializing in cold-climate fuel system applications where flexibility at sub-zero temperatures overrides pure chemical resistance.
China's MEE enforces dual carbon emission caps that restrict perfluorocarbon byproduct releases from fluoroelastomer polymerization facilities. Japan's METI maintains JIS K 6250 testing protocols that govern compression set and tensile strength benchmarks for automotive suppliers. India's BIS mandates localized certification for imported elastomer compounds under its phased manufacturing program for industrial chemicals. Stakeholders must monitor how carbon border adjustments and per- and polyfluoroalkyl substance restrictions reshape raw material access and reformulation timelines across the region.
Market Dynamics
China's dual carbon emission caps are forcing fluoroelastomer producers to reconfigure polymerization processes, compressing supply timelines while elevating compliance costs across the APAC manufacturing corridor.
Growth Catalysts
- Automotive turbocharging proliferation:Chinese and Indian OEMs are specifying fluoroelastomer O-rings for direct-injection engines operating above 200°C, expanding material substitution away from hydrocarbon-based seals.
- MEE emission enforcement:China's Ministry of Ecology and Environment restrictions on perfluorocarbon byproduct releases are accelerating capital deployment toward cleaner polymerization technologies.
- Semiconductor fabrication expansion:Wafer processing equipment manufacturers in Japan and South Korea are specifying aerospace-grade terpolymers for chamber seals requiring extended service intervals.
Market Restraints
- Hydrofluoric acid feedstock volatility:Price swings in fluorine precursor chemicals constrain margin predictability for non-integrated compounders across the region.
- Supply concentration in eastern China:Domestic suppliers and multinational compounders cluster in a single manufacturing corridor, creating geographic vulnerability to localized disruptions.
- Fluorosilicone cold-climate substitution:Fuel system applications below minus 40°C favor fluorosilicone flexibility, limiting pure fluoroelastomer penetration in arctic-adjacent deployments.
Strategic Opportunities
- India's phased manufacturing program:BIS localized certification mandates for imported elastomer compounds create first-mover advantage for domestic compounding capacity expansion.
- Hydrogen fuel cell sealing:Proton exchange membrane stacks require chemically resistant static seals, opening new specification pathways beyond conventional automotive applications.
- Carbon border adjustment preparation:EU CBAM alignment investments by Chinese exporters will differentiate low-carbon-intensity fluoroelastomer production for premium export tiers.
Industry Challenges
- Aerospace certification timeline compression:JIS K 6250 and equivalent testing protocols require 18-24 month validation cycles, delaying new terpolymer formulation commercialization.
- Per- and polyfluoroalkyl substance reformulation complexity:Anticipated restrictions on long-chain fluorinated chemistries force R&D redirection without guaranteed regulatory clarity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Fluoroelastomer Market |
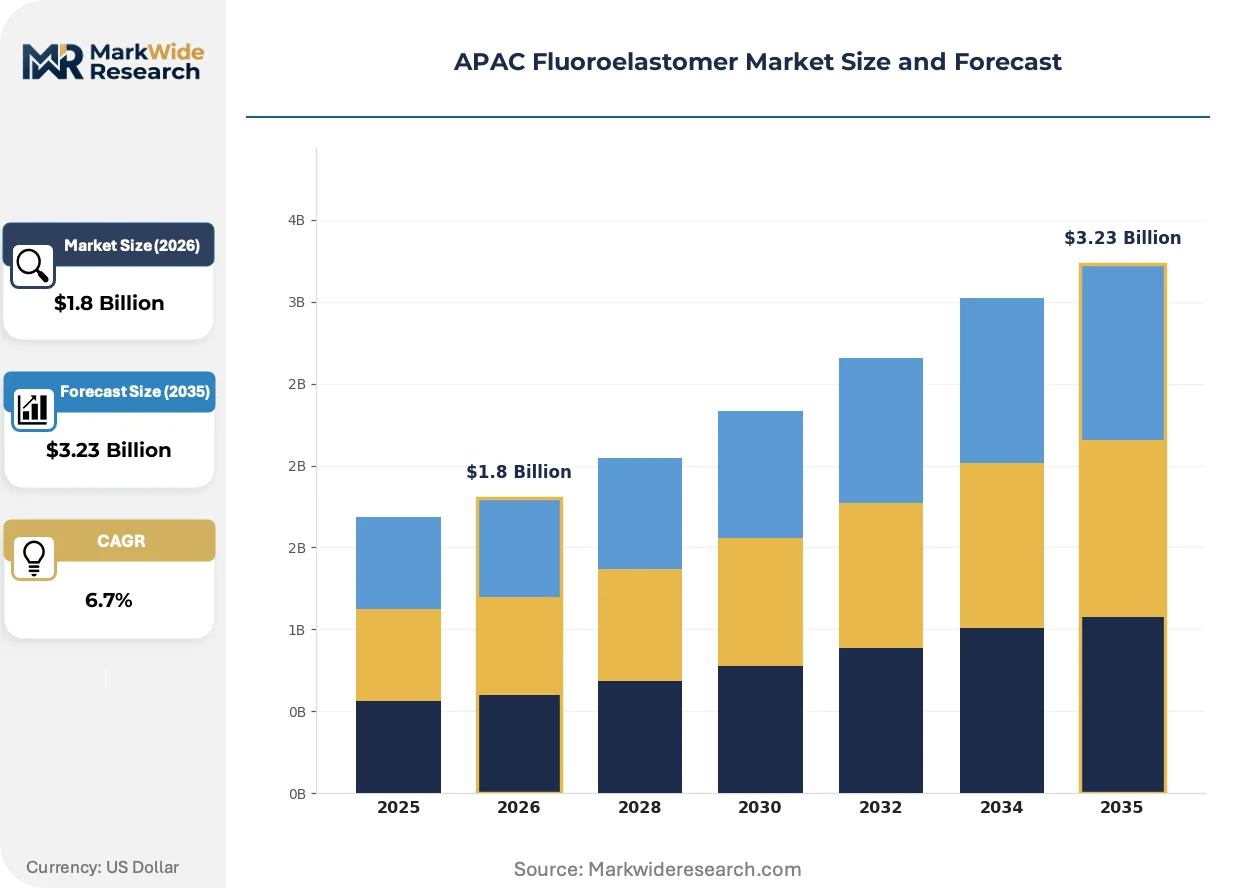
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dipolymer, Terpolymer, Fluorocarbon, Fluorosilicone End User: Aerospace, Automotive, Electronics, Industrial Equipment Application: Seals, Gaskets, Hoses, O-Rings Distribution Channel: Direct Sales, Distributors, Online Retail, Resellers |
| Companies Covered | AGC Inc., Dongyue Group, Daikin Industries, The Chemours Company, Solvay SA, Shin-Etsu Chemical Co., Ltd., Shanghai 3F New Materials Co., Ltd, 3M, Gujarat Fluorochemicals Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Fluoroelastomer Market Emerging Trajectories
Thermoplastic processing technologies are disrupting conventional vulcanization workflows, while regulatory pressure on fluorinated byproducts accelerates closed-loop chemistry investments across the value chain.
Peroxide-curable fluoroelastomer grades are converging with injection molding automation to enable complex seal geometries previously machined from compression-molded blanks. Japanese automotive Tier 1 suppliers are adopting these grades at pilot scale for turbocharger intercooler hoses. This convergence is compressing lead times from compound to finished component while reducing material scrap rates in high-mix production environments.
China's MEE dual carbon framework now mandates verified perfluorocarbon emission reporting from polymerization facilities, with penalties tied to provincial carbon intensity benchmarks. Fluoroelastomer producers are retrofitting thermal oxidizer systems to capture and destroy byproduct streams. The semiconductor fabrication seal segment bears the highest compliance cost pass-through, as aerospace-grade terpolymer buyers prioritize supply security over price elasticity.
Specification-driven procurement consolidation is concentrating buyer power among Chinese and Indian automotive OEMs, who now mandate compounder co-location within 200 kilometers of assembly plants. Tier 2 seal fabricators are losing direct material sourcing autonomy as OEMs centralize elastomer qualification and volume commitments. This pattern is most visible in China's eastern manufacturing corridor, where Dongfeng and SAIC have implemented supplier park requirements for critical sealing components.
APAC Fluoroelastomer Market Segmentation
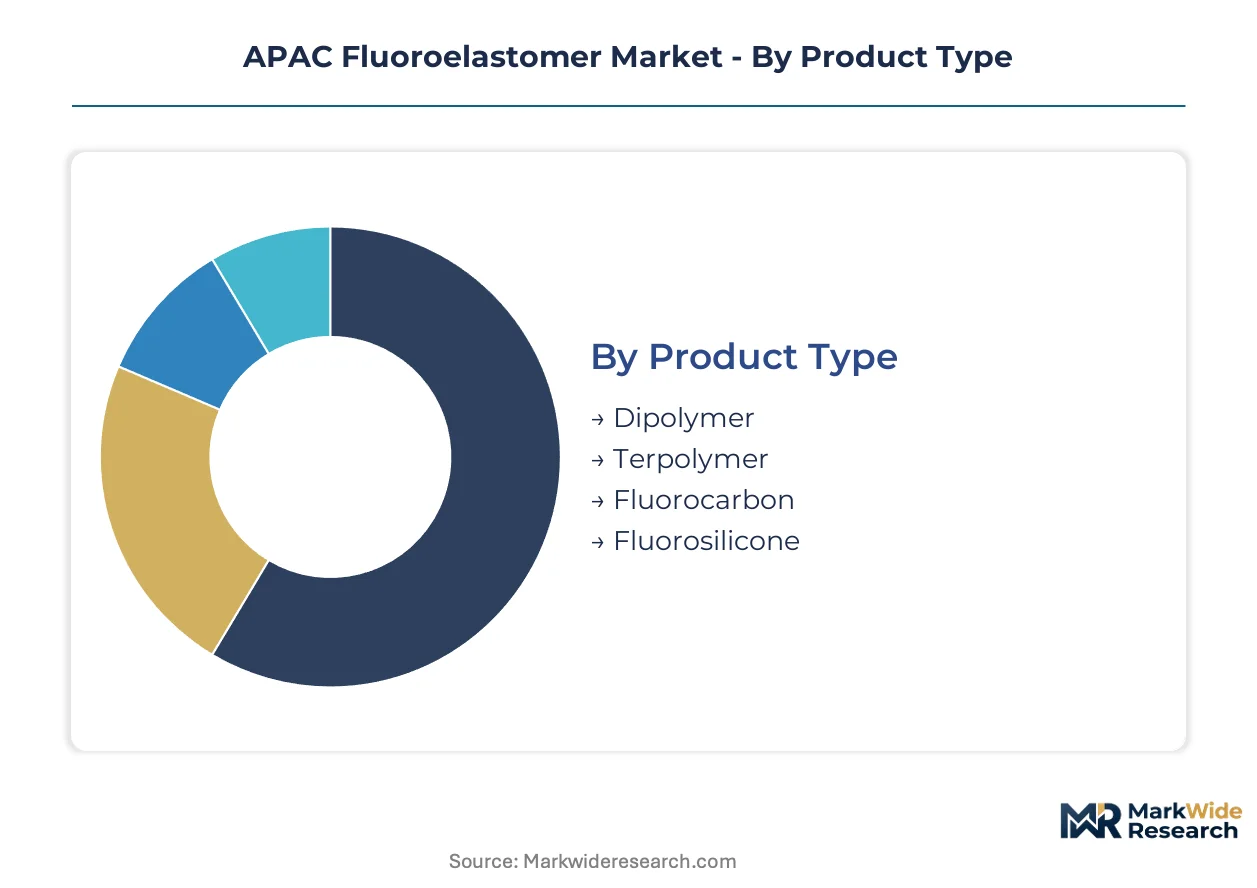
Fluoroelastomer procurement patterns diverge sharply across specification grades and end-use severity. Understanding these splits reveals where margin pools concentrate and where substitution threats emerge.
Product Type:
Performance specifications and thermal tolerance define the technology hierarchy across APAC compounder portfolios.
- Terpolymer:Peroxide-curable formulations containing vinylidene fluoride, hexafluoropropylene, and tetrafluoroethylene deliver the highest thermal stability for aerospace certification. Semiconductor fabrication equipment manufacturers in Japan and South Korea specify these grades for chamber seals requiring extended service intervals under aggressive plasma exposure.
- Dipolymer:Binary copolymers of vinylidene fluoride and hexafluoropropylene dominate automotive O-ring specifications where cost sensitivity outweighs extreme temperature demands. Chinese OEM turbocharger applications are accelerating specification shifts from hydrocarbon seals toward these mid-tier fluoroelastomers.
- Fluorocarbon:Broad-spectrum chemical resistance supports industrial process equipment across India's petrochemical corridor.
- Fluorosilicone:Cold-flexibility specialization captures fuel system applications below minus 40°C in northern China and high-altitude Indian deployments.
Mature deployment sits with Dipolymer grades. Newer deployment is concentrated in Terpolymer formulations for aerospace and semiconductor end-uses.
End User:
Application severity and certification burden create distinct margin tiers across industrial demand clusters.
- Automotive:Turbocharged direct-injection engine proliferation across Chinese and Indian passenger vehicle platforms is expanding O-ring and hose specifications. OEM co-location mandates within 200 kilometers of assembly plants are compressing supply chain configurations for Tier 1 seal fabricators.
- Aerospace:JIS K 6250 and equivalent testing protocols govern compression set and tensile strength benchmarks, enforcing 18-24 month validation cycles that delay new formulation commercialization. Japanese METI oversight maintains the region's most stringent qualification environment.
- Electronics:Wafer processing equipment demand anchors premium terpolymer consumption in South Korean fabrication facilities.
- Industrial Equipment:Process valve and pump sealing applications across Southeast Asian chemical plants favor cost-optimized dipolymer grades.
Volume leadership belongs to Automotive. Steepest expansion trajectory is emerging in Electronics fabrication equipment.
Application:
Functional geometry and dynamic stress exposure determine compound selection and fabrication method.
- Seals:Static and dynamic sealing configurations for aggressive fuel, acid, and solvent environments represent the core functional purpose of fluoroelastomer chemistry. Semiconductor chamber seals command premium positioning due to zero-failure tolerance and extended replacement cycles.
- O-Rings:Compression-molded and injection-molded circular cross-sections dominate automotive fluid system specifications. Peroxide-curable grades converging with molding automation are enabling complex geometries previously machined from blanks.
- Hoses:Turbocharger intercooler applications in Chinese automotive Tier 1 suppliers are adopting pilot-scale thermoplastic processing.
- Gaskets:Flange sealing in industrial process equipment favors sheet goods and custom-cut profiles.
Specification density peaks in Seals. Manufacturing process innovation is concentrating in O-Ring geometries.
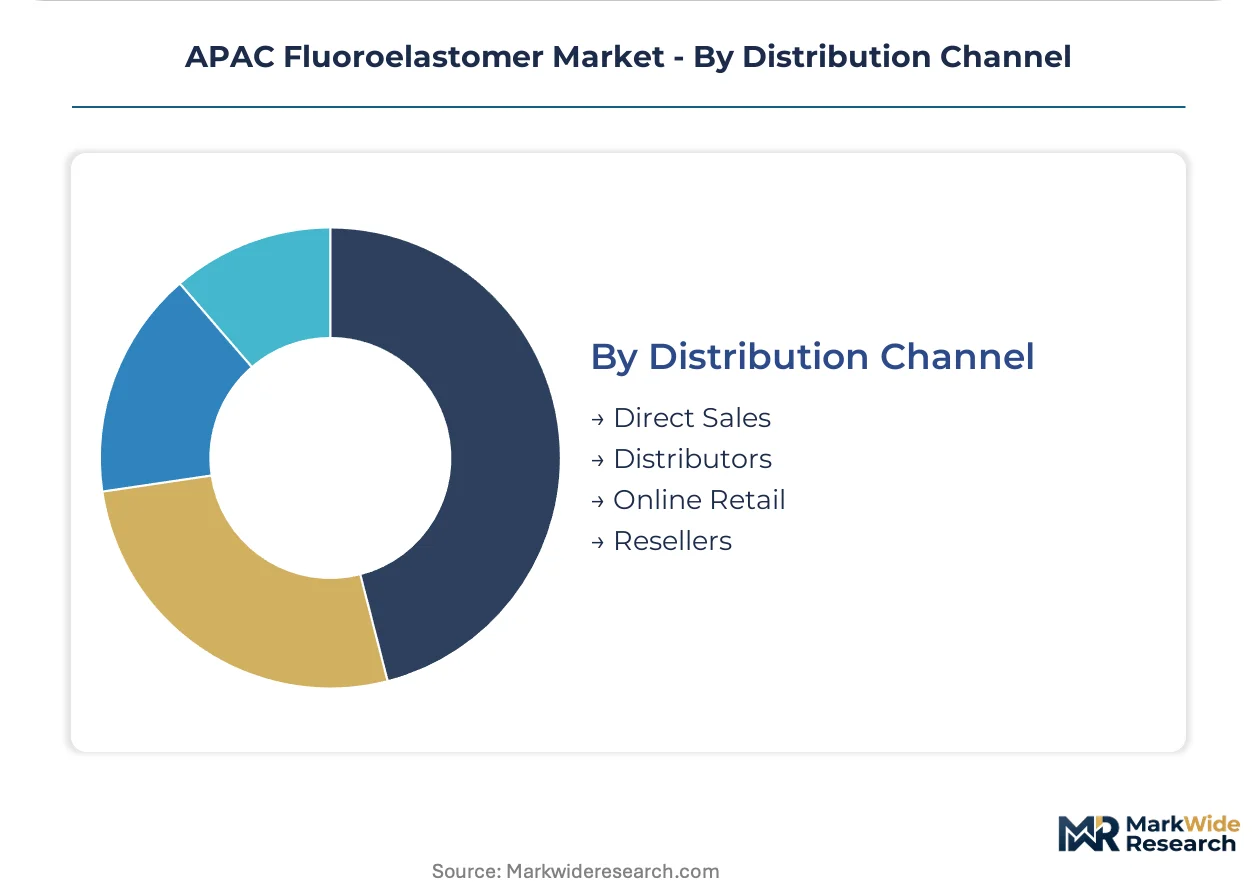
Distribution Channel:
Buyer scale and technical support requirements fragment procurement pathways across the value chain.
- Direct Sales:Automotive OEM centralized qualification programs are eliminating Tier 2 fabricator autonomy, forcing compounder-direct relationships for volume commitments. Dongfeng and SAIC supplier park requirements mandate this channel for critical sealing components.
- Distributors:Technical stocking and local formulation support serve mid-scale industrial equipment buyers across fragmented Southeast Asian markets.
- Resellers:Spot purchasing for maintenance, repair, and operations demand in secondary Indian industrial clusters.
- Online Retail:Catalog-grade O-ring and gasket sales for non-critical replacement cycles.
Channel control is consolidating around Direct Sales. Distributors retain relevance in geographically dispersed industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor from Shanghai to Ningbo anchors regional fluoroelastomer demand, where automotive OEM supplier parks concentrate polymer consumption within tight radius requirements.
China
Automotive turbocharging and semiconductor fabrication equipment drive specification-grade consumption. MEE dual carbon emission caps mandate verified perfluorocarbon reporting from polymerization facilities with provincial benchmark penalties. Dongyue Group and multinational compounders co-locate in Shandong and Zhejiang provinces to serve SAIC and Dongfeng supplier park mandates.
Japan
Wafer processing equipment manufacturers specify aerospace-grade terpolymers for chamber seals requiring extended service intervals. METI maintains JIS K 6250 testing protocols governing compression set and tensile strength benchmarks for automotive suppliers. Nagoya and Osaka industrial clusters host precision seal fabricators serving Toyota and Honda centralized qualification programs.
India
Turbocharged direct-injection engine proliferation across Maruti Suzuki and Hyundai passenger vehicle platforms expands O-ring specifications. BIS mandates localized certification for imported elastomer compounds under phased manufacturing program timelines. Gujarat Fluorochemicals anchors domestic compounding capacity in Vadodara to capture first-mover advantage from import substitution requirements.
South Korea
Semiconductor fabrication equipment demand anchors premium terpolymer consumption for plasma-exposed chamber seals. MFDS chemical safety frameworks align with export qualification requirements for EU and US-bound components. Samsung and SK Hynix supplier ecosystems in Gyeonggi-do concentrate specification-driven procurement among approved compounder lists.
Vietnam
Industrial process equipment installations across petrochemical and power generation sectors favor cost-optimized dipolymer grades for valve and pump sealing. General Department of Vietnam Customs enforces import documentation for fluorinated polymer compounds under industrial chemical classification protocols. Hai Phong and Ho Chi Minh City industrial zones attract Southeast Asian distributor stocking points for maintenance demand.
APAC Fluoroelastomer Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered structure where backward integration into hydrofluoric acid feedstock separates cost leaders from margin-dependent compounders. The vendor base concentrates around three strategic archetypes: integrated fluorine chemistry majors, regional compounders with captive polymerization, and specification-focused seal fabricators. Dominant competitive moves include geographic co-location to satisfy OEM radius mandates and portfolio diversification toward peroxide-curable grades for thermoplastic processing.
Within the integrated chemistry tier, Daikin Industries and Dongyue Group exemplify divergent feedstock strategies—Japanese fluorine chemistry depth against Chinese hydrofluoric acid backward integration. Gujarat Fluorochemicals occupies a position among export-scale compounders leveraging India's domestic capacity expansion window. These three anchors illustrate how regulatory compliance burden and feedstock access reshape competitive positioning across the APAC manufacturing corridor.
| Leading Market Players |
|---|
| AGC Inc. |
| Dongyue Group |
| Daikin Industries |
| The Chemours Company |
| Solvay SA |
| Shin-Etsu Chemical Co., Ltd. |
| Shanghai 3F New Materials Co., Ltd |
| 3M |
| Gujarat Fluorochemicals Ltd |
| Others |
Supply Flow & Price Mechanics
Automotive OEM centralized qualification programs anchor pricing power in the APAC fluoroelastomer corridor, compressing Tier 2 fabricator margins while elevating compounder-direct contract values for terpolymer grades serving semiconductor fabrication equipment.
Pricing Analysis
Extended service interval guarantees anchor value-based pricing for aerospace-grade terpolymers specified by Japanese wafer processing equipment manufacturers. Pricing stratifies across certification tiers, with JIS K 6250 validation cycles commanding 40-60% premiums over uncertified dipolymer grades. Cost compression in automotive O-ring specifications intensifies as Chinese OEMs consolidate procurement through supplier park mandates. Semiconductor fabrication seals exhibit lowest price elasticity due to zero-failure tolerance requirements.
Supply Chain Analysis
Single-source vulnerability sits with hydrofluoric acid feedstock concentration in China's Shandong and Zhejiang provinces, where Dongyue Group and multinational compounders cluster within 200 kilometers of SAIC and Dongfeng assembly plants. Fluoroelastomer polymerization draws from captive fluorine chemistry, perfluorocarbon byproduct handling systems, and imported tetrafluoroethylene monomer. Tariff exposure on fluorinated precursor chemicals threatens margin predictability for non-integrated compounders. Distribution runs through OEM-mandated direct sales channels for volume commitments, with technical distributors serving fragmented Southeast Asian industrial maintenance demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MEE dual carbon emission caps erect a cost-of-compliance moat that favors capital-rich incumbents with thermal oxidizer retrofit capabilities, while stranding smaller compounders unable to absorb verified perfluorocarbon reporting infrastructure investments.
For Market Incumbents: Deepen backward integration into hydrofluoric acid feedstock to insulate margin structures from precursor volatility threatening non-integrated competitors. Accelerate peroxide-curable grade portfolios to capture thermoplastic processing automation adoption by Japanese automotive Tier 1 suppliers. Defend against fluorosilicone substitution in cold-climate fuel systems by co-developing hybrid formulations with Indian OEMs under BIS phased manufacturing timelines. For New Entrants and Emerging Players: Peroxide-curable injection molding compatibility offers a technology-first wedge into automotive O-ring specifications where lead time compression commands premium positioning. Target India's domestic compounding capacity gap created by BIS localized certification mandates for imported elastomer compounds. Pursue hydrogen fuel cell sealing qualifications as specification pathways open beyond conventional turbocharger applications. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale compounders with captive polymerization assets in Vietnam's Hai Phong industrial zone, where petrochemical valve and pump maintenance demand outpaces local supply. Long-term viability hinges on EU CBAM alignment investments differentiating low-carbon-intensity production for premium export tiers. Watch for MEE provincial carbon intensity benchmark penalties as inflection indicators forcing consolidation among non-compliant producers.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Oxidizer Retrofit | MEE dual carbon compliance enables continued polymerization operations in Shandong and Zhejiang corridors. |
| Peroxide-Curable Grade Expansion | Injection molding automation adoption by Japanese Tier 1 suppliers compresses compound-to-component lead times. |
| Supplier Park Co-location | Dongfeng and SAIC radius mandates force compounder proximity within 200 kilometers of assembly plants. |
| India Domestic Compounding Buildout | BIS phased manufacturing program creates first-mover advantage for Vadodara-based capacity investments. |
| Semiconductor Seal Qualification | Samsung and SK Hynix approved compounder lists concentrate premium terpolymer procurement in Gyeonggi-do. |
Methodological Framework
Multi-period observation of MEE emission enforcement patterns, automotive OEM supplier park mandates, and semiconductor fabrication equipment procurement cycles anchored the trend analysis, supplemented by interviews with fluoroelastomer plant managers, procurement leads at Chinese and Indian OEMs, distribution channel partners in Southeast Asia, and technical R&D directors at Japanese compounders. Secondary validation drew from customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings of listed fluorochemical producers, and JIS K 6250 testing protocol documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the APAC manufacturing corridor.
Input-output matrices modeled fluoroelastomer consumption across product type tiers, end-use severity classifications, application geometries, and regional production hub clusters throughout the projection horizon. CAGRs derived from regression analysis of historical polymerization capacity expansion, automotive turbocharger penetration rates, and semiconductor fabrication equipment capital expenditure cycles. Industry-specific forecast inputs included perfluorocarbon emission intensity benchmarks and BIS phased manufacturing program implementation timelines.
Several conditions sit outside the modeled scope, including unannounced per- and polyfluoroalkyl substance regulatory restrictions, abrupt hydrofluoric acid feedstock supply disruptions, and geopolitical tariff escalations affecting fluorinated precursor chemical trade flows. Forecasts reflect documented assumptions about MEE enforcement continuity and OEM co-location mandate persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Dura Substitute Market
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
Super Engineering Plastics Market
Specialty Materials
Specialty Carbon Black Market
Specialty Materials
Carbon Blacks for Non-Rubber Applications Market
Specialty Materials
Specialty Silica Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Engineered Foam Market
Specialty Materials
Absorbent Booms and Socks Market
Specialty Materials
Carbon Mold Market
Specialty Materials
Global Supplementary Cementitious Materials Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Acrylic Fine Particle Market
Specialty Materials
Activated Carbon Bags Market
Specialty Materials
Light Diffusion Materials Market