
 Middle East and Africa Anti-Friction Coatings Market | 2026-2036
Middle East and Africa Anti-Friction Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Anti-Friction Coatings Market Foresight
Multi-source procurement among petrochemical and automotive buyers is decoupling coating supply from traditional single-vendor lubricant contracts across the Middle East and Africa. DuPont de Nemours Inc leverages its polymer chemistry heritage to anchor specification-grade dry film programs for aerospace maintenance hubs in the Gulf. Fuchs Petrolub SE sustains extensive blending and distribution infrastructure that dominates industrial equipment channels from South Africa through Egypt. Klüber Lubrication specializes in high-temperature formulation expertise that positions it for powertrain applications in the region's growing automotive assembly plants.
Middle East and Africa anti-friction coatings are thin engineered films—typically 5–50 microns thick, incorporating PTFE, molybdenum disulfide, or ceramic particulates in solvent-borne or water-based matrices—designed to reduce wear coefficients and eliminate stick-slip in metal-to-metal contact interfaces. Liquid coatings lead volume throughput due to compatibility with existing spray and dip application infrastructure at OEM facilities, while dry film lubricants represent the fastest-growing category as maintenance providers adopt aerosol and brush-applied formats for field repair scenarios. Composite coatings command premium positioning where extreme pressure and temperature thresholds in industrial equipment exceed the performance envelope of standard polymer formulations.
Saudi Arabia's SFDA and South Africa's national standards regulator enforce chemical composition and workplace exposure limits that shape import clearance and local blending requirements for coating formulations. The EU REACH framework exerts extraterritorial influence through supply chain compliance demands on European-headquartered multinationals operating regional subsidiaries. Stakeholders must monitor how Gulf standardization initiatives and South African automotive masterplan technical specifications converge on coating durability testing protocols.
Market Dynamics
Saudi Arabia's Vision 2030 localization mandates and South Africa's automotive masterplan are forcing coating suppliers to reconfigure supply chains around domestic blending facilities and certified local content thresholds.
Growth Catalysts
- Powertrain ceramic adoption:Automotive OEMs in South Africa's Eastern Cape corridor specify ceramic-reinforced dry films for transmission assemblies to meet extended warranty durability requirements.
- SFDA chemical clearance pathways:Saudi Arabia's streamlined import registration for industrial coatings accelerates product entry for maintenance providers serving Jubail's petrochemical cluster.
- High-temperature polymer formulations:Molybdenum disulfide-PTFE composites gain traction in UAE aerospace MRO facilities seeking reduced friction coefficients in landing gear rebuilds.
Market Restraints
- Fluoropolymer feedstock volatility:PTFE resin prices fluctuate with global fluorspar concentrate availability, squeezing margin structures for solvent-borne coating blenders.
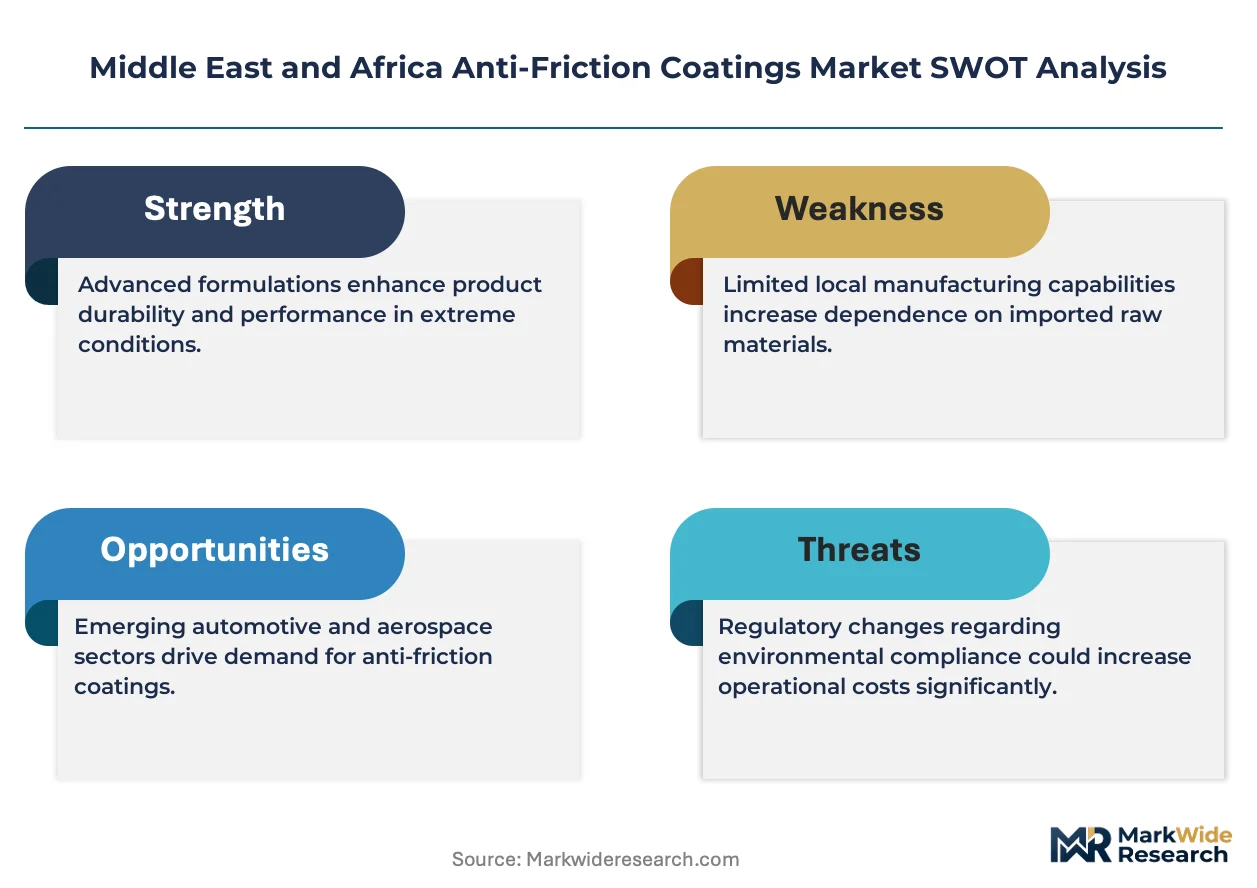
- Single-source ceramic particulate dependence:High-purity hexagonal boron nitride supply concentrates in East Asian specialty chemical producers, exposing regional formulators to disruption risk.
- REACH extraterritorial compliance burden:European-headquartered multinationals operating Middle East subsidiaries must maintain dual registration dossiers, elevating administrative overhead versus local competitors.
Strategic Opportunities
- Egyptian industrial corridor penetration:Suez Canal Economic Zone manufacturing investments create first-mover advantage for coating suppliers establishing Alexandria blending capacity.
- Water-based formulation conversion:VOC reduction mandates across Gulf Cooperation Council jurisdictions favor aqueous dispersion technologies over solvent-borne legacy systems.
- Drone-applied maintenance formats:Aerosol dry film lubricants packaged for unmanned aerial vehicle deployment enable offshore platform and pipeline inspection teams to access previously unreachable friction points.
Industry Challenges
- Formulation chemist scarcity:Regional universities produce limited graduates with expertise in tribology and polymer-solvent compatibility testing, constraining R&D expansion.
- Dual certification timelines:Products must sequentially clear Saudi SFDA and South Africa's national standards regulator protocols, extending commercialization cycles by 8-14 months.
- Legacy equipment compatibility:Existing spray infrastructure at established OEM facilities requires retrofitting to handle next-generation high-solids ceramic suspensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Anti-Friction Coatings Market |
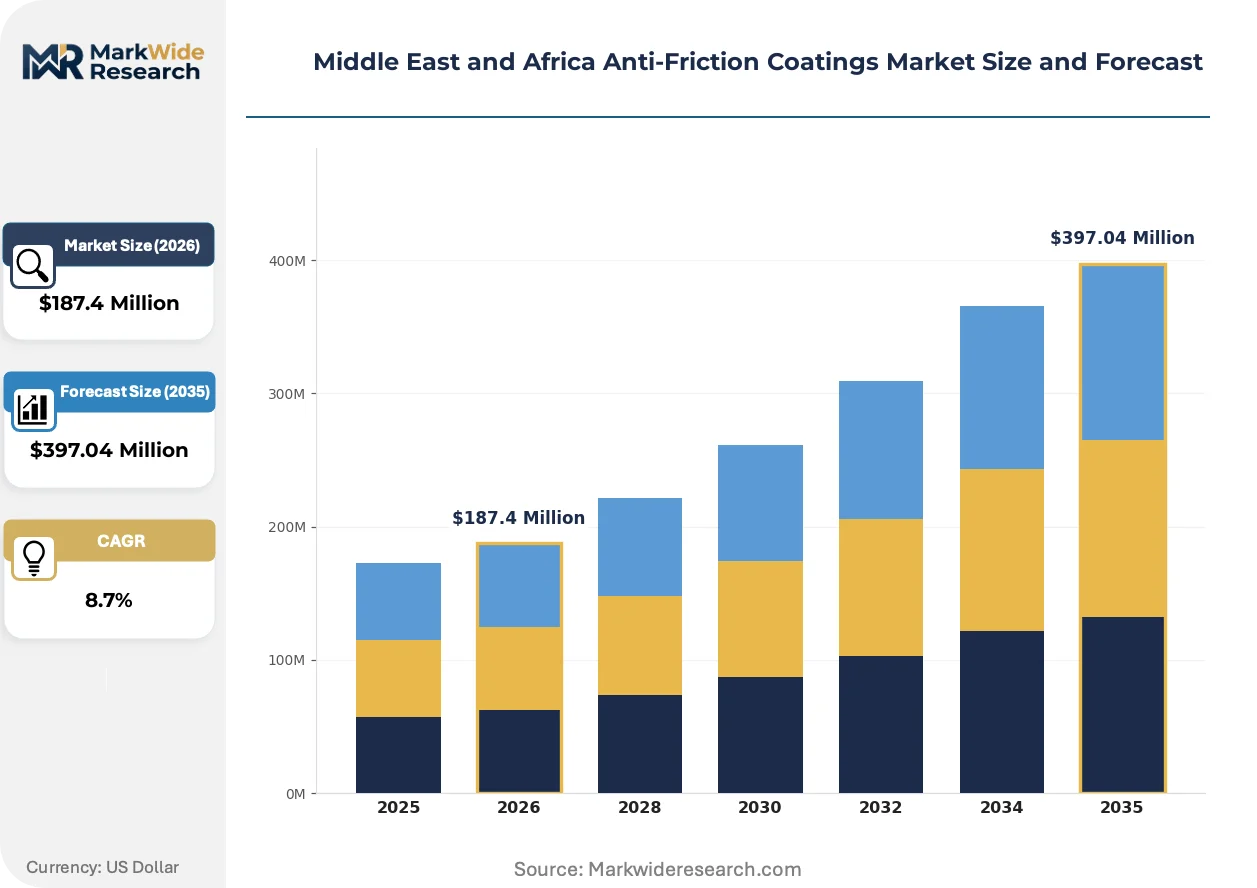
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Film Lubricants, Liquid Coatings, Greases, Composite Coatings Application: Aerospace, Automotive, Industrial Equipment, Electronics End User: Manufacturers, OEMs, Maintenance Providers, Repair Services Material: Polymer Coatings, Metal-Based Coatings, Ceramic Coatings, Others |
| Companies Covered | DuPont de Nemours Inc, Parker Hannifin Corp, Carl Bechem GmbH, Fuchs Petrolub SE, Klüber Lubrication, Aalberts Surface Technologies, ASV Multichemie Private Limited, GMM Coatings Private Limited, IKV Tribology Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Anti-Friction Coatings Market Shifts & Advancements
Ceramic-polymer hybrid technologies and application method innovations are compressing performance gaps between maintenance-grade and specification-grade coating tiers across Middle East and Africa industrial hubs.
Nano-structured alumina-silica composites are absorbing thermal loads previously requiring pure ceramic overlays. Automotive transmission rebuilders in South Africa's Port Elizabeth manufacturing zone adopt these hybrids at triple the rate of conventional PTFE formulations. The technology is absorbing market share from thicker plasma-sprayed alternatives by matching wear resistance at one-third the applied thickness.
Saudi Arabia's SFDA and South Africa's national standards regulator are converging on ISO 1518 scratch resistance testing protocols for industrial coating durability claims. This harmonization reduces redundant laboratory certification costs for suppliers operating across both jurisdictions. Formulators serving pan-regional automotive OEMs must now validate products against unified performance benchmarks rather than country-specific legacy methods.
Maintenance procurement teams at Jubail petrochemical operators unbundle coating supply from integrated lubricant service contracts. Discrete anti-friction film purchasing enables direct specification of ceramic-reinforced formulations for high-wear pump rebuilds. This pattern concentrates most visibly in Saudi Arabia's Eastern Province, where equipment uptime penalties have sharpened buyer sophistication around tribological performance differentiation.
Middle East and Africa Anti-Friction Coatings Market Segmentation
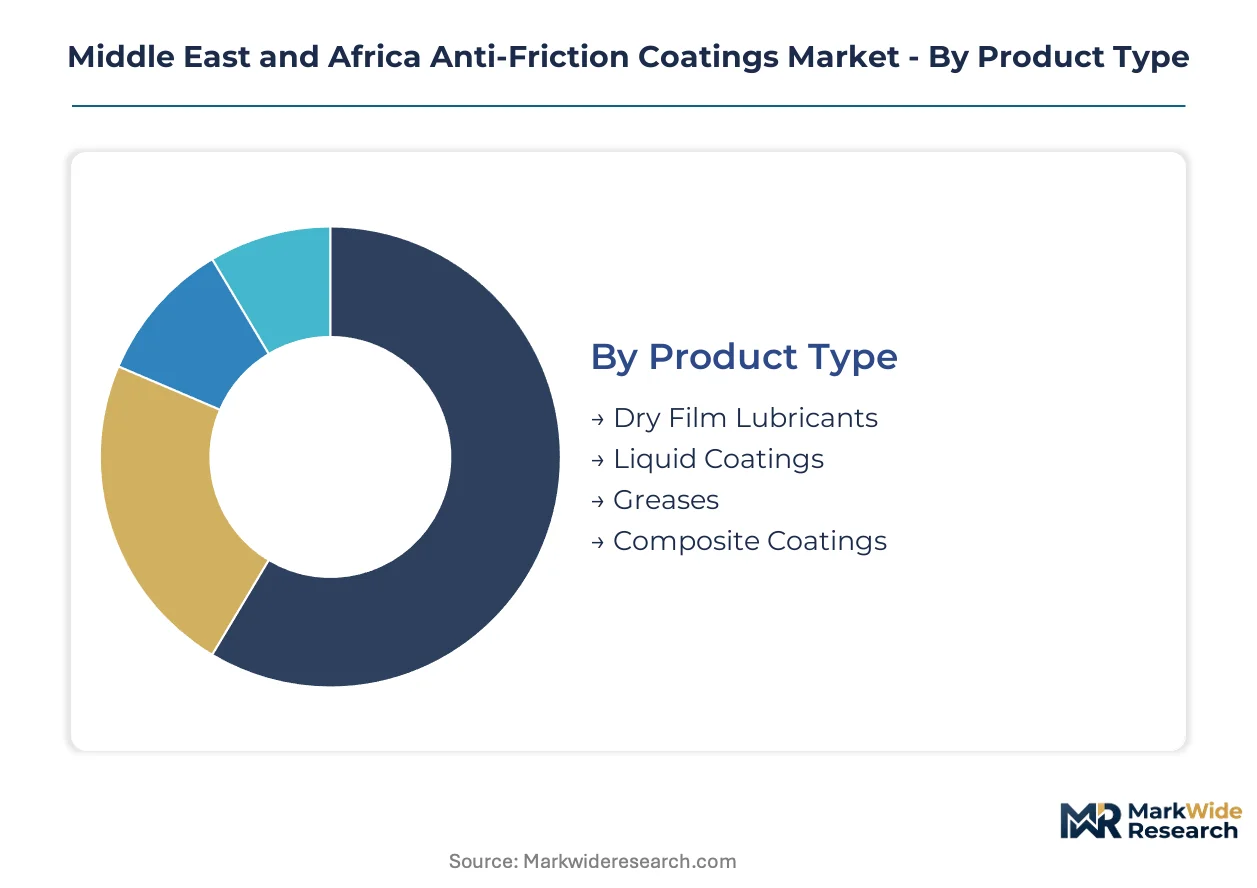
Anti-friction coatings in the Middle East and Africa fragment across formulation chemistry, application method, and procurement channel. Each dimension carries distinct margin structures and regulatory exposure that shape supplier positioning across Saudi Arabia's Jubail cluster and South Africa's Eastern Cape automotive corridor.
Product Type:
Customization intensity varies sharply across this category, from specification-grade dry films engineered to OEM blueprints to commodity greases purchased on bulk contract terms.
- Liquid Coatings:Solvent-borne and water-based dispersions of PTFE or molybdenum disulfide in resin carriers, applied via spray or dip lines at established OEM facilities. Volume concentrates in South Africa's Port Elizabeth transmission plants, where compatibility with legacy spray infrastructure sustains procurement continuity despite VOC compliance pressures.
- Dry Film Lubricants:Aerosol or brush-applied formats incorporating bonded solid lubricant films for field maintenance scenarios. Demand is climbing fastest at UAE aerospace MRO hubs and Saudi pipeline inspection teams, where equipment accessibility constraints favor portable application methods over fixed-line systems.
- Greases:Semi-fluid lubricants with dispersed anti-wear additives for bearing and gear applications. Standardized procurement through industrial distributors dominates Egyptian manufacturing zones.
- Composite Coatings:Multi-layer ceramic-polymer systems engineered for extreme pressure and temperature thresholds. Premium positioning at Jubail petrochemical pump rebuilds reflects performance requirements beyond standard polymer envelopes.
Most installed capacity flows through Liquid Coatings. Expansion is steepest in Dry Film Lubricants.
Application:
Performance specifications diverge across this category based on thermal load severity and regulatory certification burden rather than volume scale.
- Automotive:Powertrain and chassis assemblies in South Africa's Eastern Cape corridor specify ceramic-reinforced formulations to satisfy extended warranty durability protocols. OEM technical offices validate coatings against ISO 1518 scratch resistance benchmarks unified across Saudi and South African jurisdictions.
- Aerospace:Landing gear and control surface applications at UAE maintenance hubs demand molybdenum disulfide-PTFE composites with documented friction coefficient stability across temperature cycling. SFDA import registration pathways accelerate product entry for maintenance providers serving this segment.
- Industrial Equipment:Pump, valve, and compressor rebuilds across Saudi Arabia's Eastern Province concentrate procurement of high-temperature polymer formulations. Unbundling from integrated lubricant contracts enables direct specification of ceramic-reinforced grades.
- Electronics:Precision connector and switch applications require ultra-thin films with controlled thickness uniformity. Limited regional demand concentrates in UAE semiconductor packaging facilities.
Certification complexity peaks in Aerospace. Volume scale centers on Automotive.
End User:
Procurement sophistication and specification authority separate this category, from engineering-driven OEM technical offices to price-sensitive maintenance contractors.
- OEMs:Original equipment manufacturers in South Africa's automotive masterplan and Saudi Vision 2030 localization mandates drive specification-grade demand with embedded local content thresholds. Technical validation cycles extend 8-14 months across dual SFDA and South African national standards protocols.
- Maintenance Providers:Independent service contractors serving Jubail's petrochemical cluster and pipeline networks prioritize rapid-turn dry film formats. Discrete purchasing from coating specialists replaces legacy bundled lubricant contracts.
- Manufacturers:Industrial fabricators in Egypt's Suez Canal Economic Zone blend coating procurement with broader consumables purchasing, limiting supplier margin capture.
- Repair Services:Small-scale rebuild shops across Gulf secondary cities source through distributor channels with limited technical specification input.
Margin capture concentrates with OEMs. Procurement flexibility is widest among Maintenance Providers.
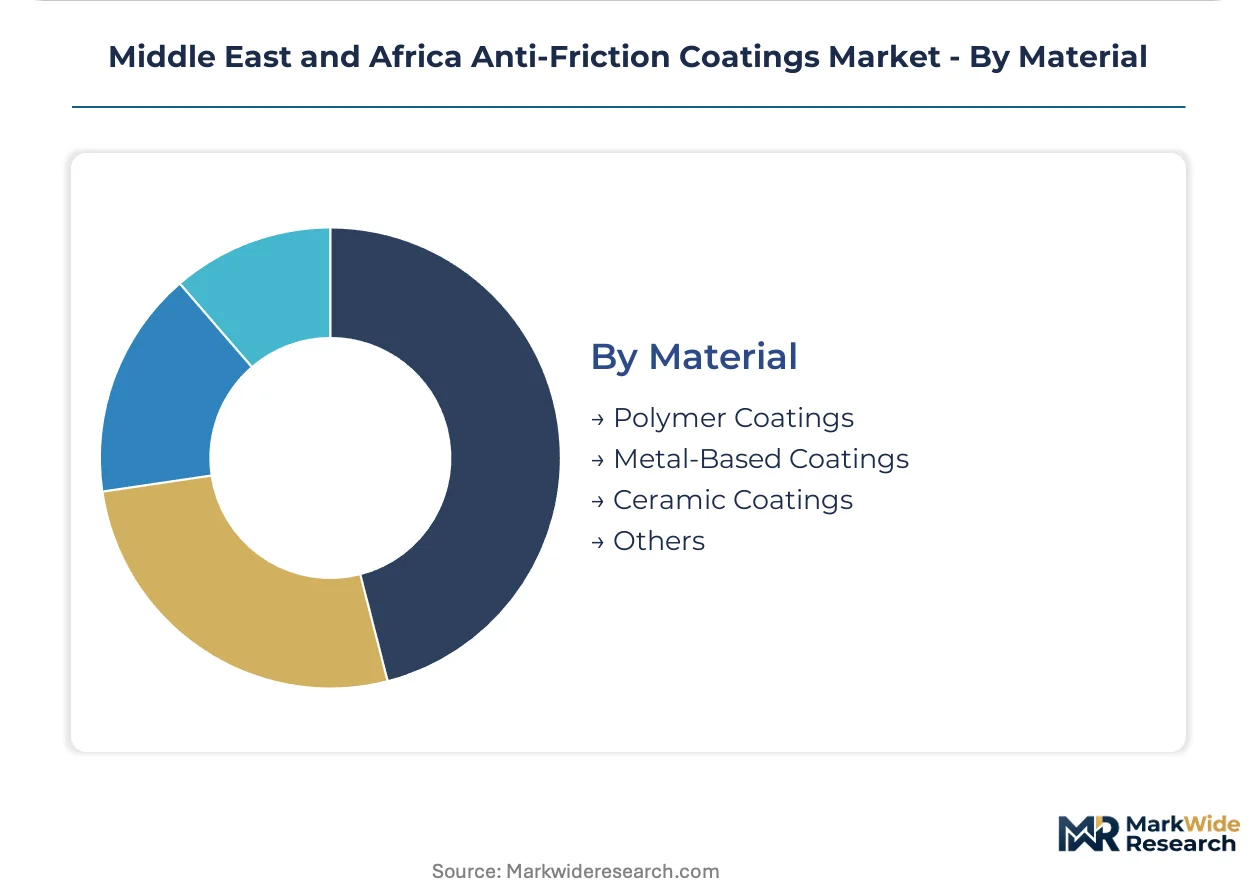
Material:
Feedstock cost volatility and supply chain concentration define competitive positioning across this category.
- Polymer Coatings:PTFE and fluoropolymer-based formulations dominate volume throughput. PTFE resin prices fluctuate with global fluorspar concentrate availability, squeezing blenders serving solvent-borne segments.
- Ceramic Coatings:Alumina-silica and hexagonal boron nitride composites command premium positioning where thermal loads exceed polymer limits. High-purity hexagonal boron nitride supply concentrates in East Asian specialty chemical producers, exposing regional formulators to disruption risk.
- Metal-Based Coatings:Molybdenum disulfide and tungsten disulfide formulations serve high-load industrial applications. Standardized specifications enable multi-source procurement.
- Others:Emerging nano-structured and bio-based formulations occupy experimental niches with limited commercial scale.
Volume flows through Polymer Coatings. Technology migration is strongest toward Ceramic Coatings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between Gulf standardization regimes and South African protocols are reshaping where coating formulators locate blending capacity. Suppliers face divergent chemical registration timelines that advantage regional hubs with streamlined clearance pathways.
Saudi Arabia
Vision 2030 localization mandates drive domestic blending investments for petrochemical maintenance providers. SFDA import registration pathways accelerate product entry for industrial coatings serving Jubail's equipment rebuild clusters. Eastern Province pump service contractors unbundle coating procurement from legacy lubricant contracts.
South Africa
Automotive masterplan technical specifications enforce ISO 1518 scratch resistance validation for powertrain coatings. The national standards regulator maintains dual-protocol requirements with extended certification cycles. Eastern Cape transmission plants specify ceramic-reinforced dry films for extended warranty assemblies.
United Arab Emirates
Aerospace MRO hubs at Dubai and Abu Dhabi demand molybdenum disulfide-PTFE composites for landing gear rebuilds. MOHAP chemical clearance frameworks align with Gulf standardization initiatives. Maintenance providers adopt portable dry film formats for field accessibility constraints.
Egypt
Suez Canal Economic Zone manufacturing investments attract coating suppliers establishing Alexandria blending capacity. The country's national industrial regulator enforces workplace exposure limits shaping import formulation requirements. Fabricators in the corridor prioritize rapid-turn procurement from regional distributors.
Israel
Defense and aerospace subcontractors source specification-grade coatings for precision mechanical assemblies. The national standards authority maintains stringent chemical composition documentation for industrial imports. Tel Aviv-area precision engineering clusters validate products against durability benchmarks exceeding regional norms.
Middle East and Africa Anti-Friction Coatings Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue water-based formulation niches and drone-applied maintenance formats. The supplier base concentrates around three strategic archetypes: polymer chemistry specialists leveraging formulation heritage, industrial distributors dominating blended product channels, and ceramic composite innovators serving extreme-temperature applications. Capacity expansion and geographic licensing agreements represent the dominant competitive moves as suppliers respond to localization mandates.
Within the polymer chemistry tier, DuPont de Nemours Inc exemplifies specification-grade dry film positioning for aerospace maintenance applications. Fuchs Petrolub SE anchors industrial equipment channel presence through extensive blending infrastructure. Klüber Lubrication occupies the high-temperature formulation specialist position for powertrain applications in regional automotive assembly plants.
| Leading Market Players |
|---|
| DuPont de Nemours Inc |
| Parker Hannifin Corp |
| Carl Bechem GmbH |
| Fuchs Petrolub SE |
| Klüber Lubrication |
| Aalberts Surface Technologies |
| ASV Multichemie Private Limited |
| GMM Coatings Private Limited |
| IKV Tribology Ltd |
| Others |
Supply & Pricing Matrix
Specification-grade dry films and commodity solvent-borne coatings diverge sharply across Middle East and Africa procurement channels, with ceramic-reinforced formulations commanding premium positioning through ISO 1518 validation while standard PTFE dispersions compete on bulk contract terms. This bifurcation concentrates margin capture with Saudi Arabia's SFDA-registered suppliers and South Africa's certified blenders, while price-sensitive maintenance contractors in Egypt's Suez corridor source through distributor networks with limited technical specification leverage.
Pricing Analysis
Distributor margins absorb 15-25 point spreads between formulation tiers, with direct-to-OEM channels for ceramic-polymer composites bypassing intermediary markups entirely. Three-tier pricing structure across specification-grade, industrial-standard, and maintenance-economy levels reflects certification burden and local content thresholds rather than raw material cost alone. Cost compression in solvent-borne PTFE segments intensifies as fluorspar feedstock volatility squeezes blender margins, while OEM technical offices in South Africa's Eastern Cape demonstrate lowest price sensitivity due to warranty liability exposure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Saudi Arabia's Jubail petrochemical cluster and South Africa's Port Elizabeth transmission plants, while industrial distributors serve fragmented maintenance providers across Gulf secondary cities. Geographic supply concentration centers on Germany, China, and Japan for high-purity hexagonal boron nitride ceramic particulates, with PTFE resin feedstock drawing from global fluorspar processing hubs. Single-source vulnerability in East Asian specialty chemical producers exposes regional formulators to disruption risk. Distribution runs through certified local blending facilities mandated under Vision 2030 and South Africa's automotive masterplan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anti-friction coatings function as a regulatory compounder across Middle East and Africa, with Saudi Arabia's SFDA streamlining and South Africa's ISO 1518 harmonization accelerating product entry for compliant suppliers while elevating barriers for non-certified competitors.
For Market Incumbents: Anticipate margin compression in standard PTFE solvent-borne segments as Egyptian and UAE-based emerging entrants capture price-sensitive maintenance contracts through distributor partnerships. Prioritize backward integration into ceramic particulate sourcing to reduce East Asian supply dependency, and secure dual SFDA-South African certification dossiers to defend specification-grade positioning in automotive powertrain channels. For New Entrants and Emerging Players: Field maintenance contractors serving Saudi Arabia's Eastern Province pipeline networks represent the most penetrable buyer archetype, with discrete coating procurement unbundling from legacy lubricant contracts creating first-mover white space. Target water-based formulation conversion opportunities under Gulf Cooperation Council VOC mandates, and establish Alexandria blending capacity to serve Egypt's Suez Canal Economic Zone manufacturing investments with rapid-turn local fulfillment. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist scarcity constrains R&D expansion for mid-tier regional blenders lacking polymer-solvent compatibility expertise. Long-term viability favors acquirers of certified local blending assets with established SFDA registration pathways over greenfield capacity builds. Watch for harmonization of Saudi-South African durability testing protocols as the inflection signal for pan-regional specification-grade suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Blending Capacity Expansion | Vision 2030 localization mandates require Jubail-adjacent production facilities to satisfy local content thresholds. |
| Water-Based Formulation Conversion | Gulf Cooperation Council VOC reduction mandates favor aqueous dispersion technologies over solvent-borne legacy systems. |
| Dual Certification Investment | Sequential SFDA and South African national standards clearance compresses commercialization cycles for specification-grade entrants. |
| Ceramic Particulate Supply Agreement | Long-term offtake contracts with East Asian hexagonal boron nitride producers mitigate single-source disruption exposure. |
| Drone-Applied Maintenance Format Development | Aerosol dry film packaging for unmanned aerial vehicle deployment enables offshore platform friction point access. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with coating formulators, procurement leads at Saudi petrochemical operators, South African OEM technical offices, and Egyptian industrial distributors with secondary validation against customs trade data, SEC filings of listed chemical companies, and Gulf standardization initiative documentation. Bottom-up volume modeling across formulation chemistry tiers triangulated with top-down value estimates derived from regional production cluster outputs.
Segment-weighting approaches distributed value across liquid coatings, dry film lubricants, greases, and composite coatings proportional to verified procurement volumes at Jubail, Port Elizabeth, and Dubai aerospace MRO hubs. Modeled dimensions spanned formulation type, application method, end-user procurement sophistication, and material chemistry across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating automotive masterplan localization targets and petrochemical maintenance cycle frequencies.
Inputs from SFDA registration databases and South African national standards protocols were available through the study window; gaps in real-time ceramic particulate inventory levels at East Asian suppliers introduce uncertainty bands around composite coating supply assumptions. Forecasts reflect documented assumptions regarding harmonization timelines and feedstock price stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Niobium Pentoxide Market
Specialty Materials
Europe Textile Films Market
Specialty Materials
Sulphur Bentonite Market
Specialty Materials
Metalized Biaxially Oriented Polypropylene Films Market
Specialty Materials
Elastic Films Market
Specialty Materials
Silicone Solutions Market
Specialty Materials
Specialty Carbon Black Market
Specialty Materials
Edge Banding Materials Market
Specialty Materials
Alginate Films Market
Specialty Materials
Asia-Pacific Reflective Tape Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market
Specialty Materials
Silicone Film Market
Specialty Materials
Surface Technology Market
Specialty Materials
Absorbent Booms and Socks Market
Specialty Materials
Global Polybenzimidazoles (PBI) Market
Specialty Materials
Open Cell Foam Market