
 Alginate Films Market | 2026-2036
Alginate Films Market Size, Share, and Industry Trends Forecast 2026-2036
Alginate Films Market Outlook
Pharmaceutical end-use demand is hardening as alginate films gain traction in controlled-release drug delivery systems. DuPont de Nemours, Inc. leverages its polymer science heritage to sustain high-barrier film formulations for medical applications. FMC Corporation anchors North American supply through integrated seaweed extraction and refining operations. KIMICA Corporation dominates Asian pharmaceutical-grade alginate production with vertically controlled supply from Japanese kelp harvests.
Alginate films are thin, flexible membranes composed of linear copolymers of β-D-mannuronic acid and α-L-guluronic acid extracted from brown seaweed, typically cross-linked with calcium ions to achieve gelation and mechanical stability for moisture-responsive barrier applications. Flexible films lead commercial volume due to conformability in food wrapping and wound dressing formats, while bioactive films represent the fastest-expanding margin pool as antimicrobial and growth-factor-loaded variants penetrate advanced wound care. Barrier films occupy the premium tier where oxygen and moisture transmission specifications determine pharmaceutical packaging acceptance.
FDA pharmaceutical packaging standards and the EU MDR framework govern alginate film biocompatibility and sterility assurance for medical and drug delivery applications, while REACH chemical registration requirements in Europe constrain residual heavy metal limits in seaweed-derived raw materials. Japan's PMDA maintains distinct documentation demands for alginate-based medical devices that complicate cross-border product registration. Stakeholders must monitor evolving biodegradability certification protocols and regional seaweed supply security as climate variability affects Atlantic and Pacific kelp harvest yields.
Market Dynamics
The alginate films sector is experiencing structural compression as the EU Green Deal mandates accelerate the displacement of petroleum-derived packaging materials, forcing converters to requalify entire supply chains around seaweed-derived barrier substrates within compressed compliance timelines.
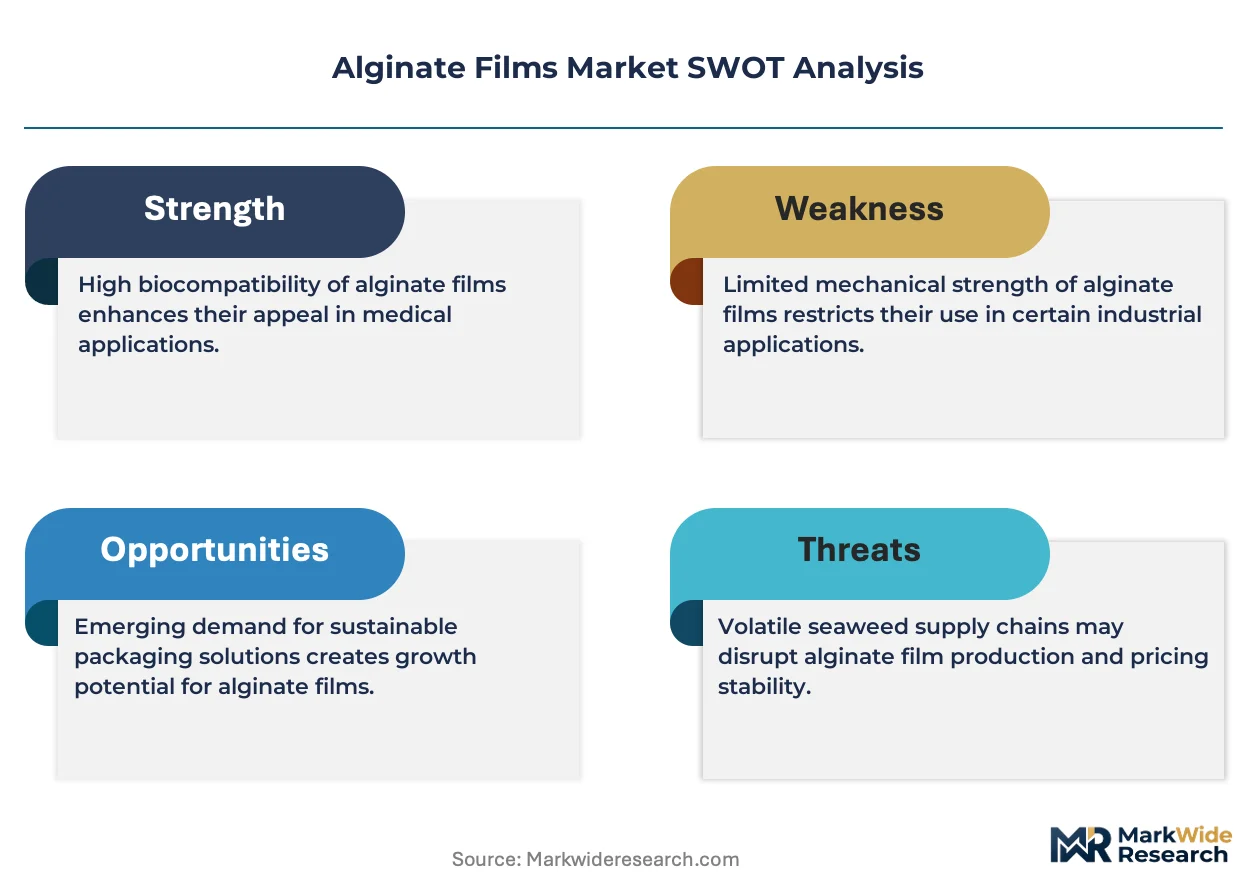
Growth Catalysts
- EU Green Deal packaging mandates:Biodegradable film quotas under the European Commission's Circular Economy Action Plan are compelling food processors to substitute alginate barriers for conventional plastics in fresh produce wrapping applications.
- Controlled-release pharmaceutical demand:Drug delivery manufacturers are expanding alginate film utilization for oral dosage matrix systems that enable precise API release kinetics in gastric environments.
- Japanese kelp harvest clusters:Vertically controlled supply from Hokkaido extraction facilities ensures pharmaceutical-grade raw material security for medical device film producers serving Asian markets.
Market Restraints
- Atlantic seaweed supply volatility:Climate-induced kelp yield fluctuations off the coasts of Norway and Scotland create raw material availability uncertainty for European film processors.
- Calcium chloride cross-linker cost sensitivity:Industrial-grade cross-linking agent price swings directly compress margin structures for mid-volume alginate film converters.
- REACH heavy metal thresholds:ECHA residual metal content limits for seaweed-derived inputs impose costly purification burdens on extraction operations serving European pharmaceutical packaging customers.
Strategic Opportunities
- Advanced wound care bioactive films:Antimicrobial and growth-factor-loaded alginate membranes represent unpenetrated white space in chronic wound management protocols across German hospital networks.
- US pharmaceutical packaging requalification:FDA guidance on biodegradable primary packaging materials creates first-mover advantage for alginate barrier films in oral solid dose applications.
- Electrospinning-nanofiber convergence:Hybrid manufacturing processes combining traditional solvent casting with electrospun nanofiber layers enable ultrathin high-barrier medical films with enhanced mechanical properties.
Industry Challenges
- Pharmaceutical-grade certification timelines:USP Class VI and ISO 10993 biocompatibility testing protocols extend product qualification cycles to 18-24 months for new alginate film formulations.
- Seaweed processing talent scarcity:Specialized expertise in alginate extraction chemistry and film-forming rheology remains concentrated among a limited cohort of marine biotechnology researchers in Japan and Norway.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alginate Films Market |
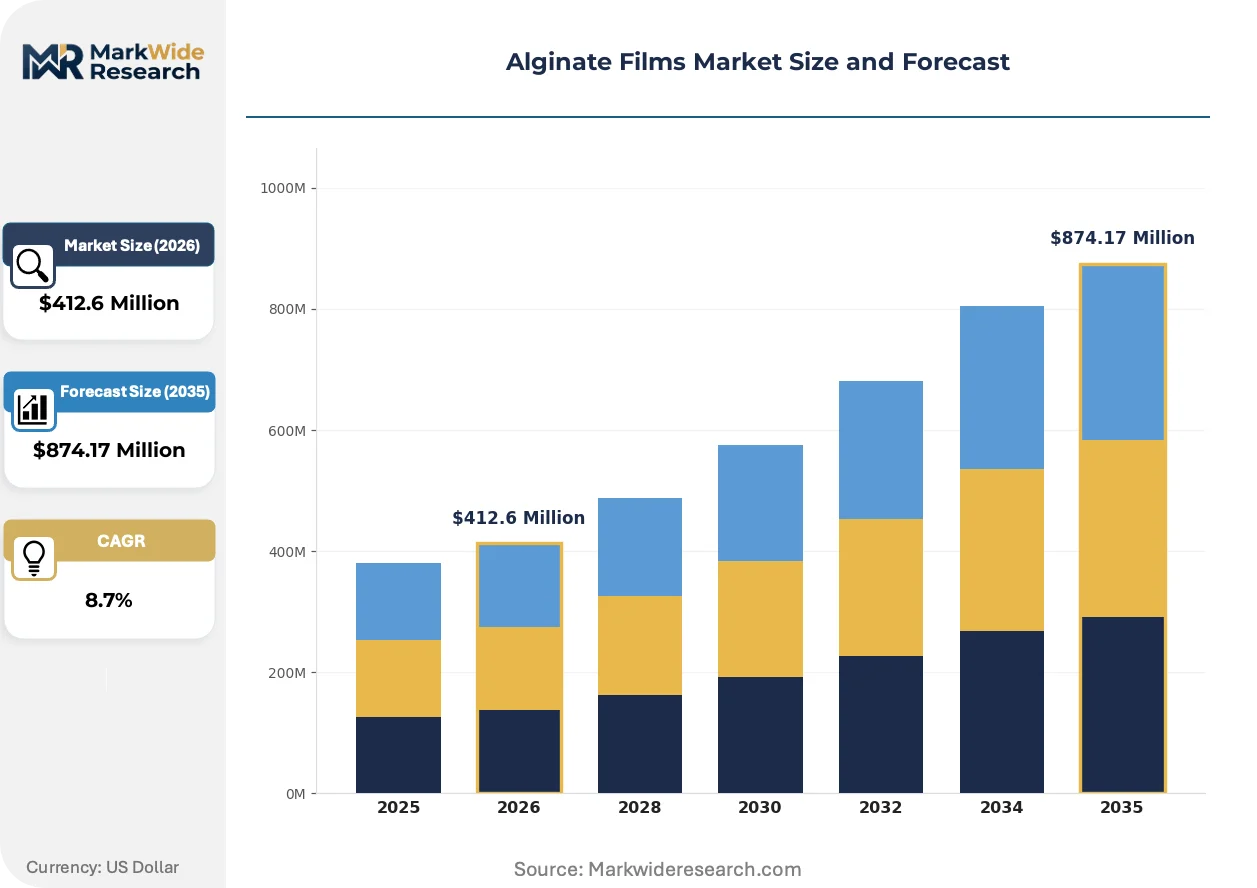
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Films, Rigid Films, Bioactive Films, Barrier Films Application: Food Packaging, Medical Dressings, Drug Delivery, Tissue Engineering End User: Healthcare, Food Industry, Pharmaceuticals, Biotechnology Formulation: Coated Films, Laminated Films, Hydrogels, Composites |
| Companies Covered | DuPont de Nemours, Inc., FMC Corporation, KIMICA Corporation, Cargill, Incorporated, Ashland Global Holdings Inc., Ceamsa, Marine Biopolymers Ltd., Qingdao Bright Moon Seaweed Group Co., Ltd., Shandong Jiejing Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alginate Films Market Strategic Shifts
Active material science breakthroughs are redefining performance benchmarks for alginate films across medical and food contact applications, with functional additive integration and manufacturing precision emerging as decisive competitive differentiators.
Layer-by-layer electrostatic assembly of oppositely charged polysaccharides is electrifying barrier property enhancement in oxygen-sensitive pharmaceutical packaging. Japanese medical device manufacturers are accelerating adoption of these nanolaminated structures for parenteral drug stability applications. The technology is electrifying competitive positioning among film converters capable of achieving sub-0.1 cc/m²/day oxygen transmission rates without synthetic polymer lamination.
REACH chemical registration amendments are tightening residual solvent specifications for alginate film intermediates used in European food contact materials. ECHA enforcement actions against non-compliant Asian importers are redirecting procurement toward EU-certified extraction facilities. German retail packaging suppliers are responding by mandating third-party solvent residue documentation across their alginate film supply base.
Hospital procurement departments are consolidating wound dressing suppliers around integrated film-converter-device manufacturers capable of delivering sterile finished products rather than bulk substrate rolls. This specification compression favors alginate film producers with in-house cutting, sterilization, and pouching capabilities. The behavioral shift is most pronounced in United States acute care networks seeking to reduce SKU complexity and vendor management overhead.
Alginate Films Market Segmentation
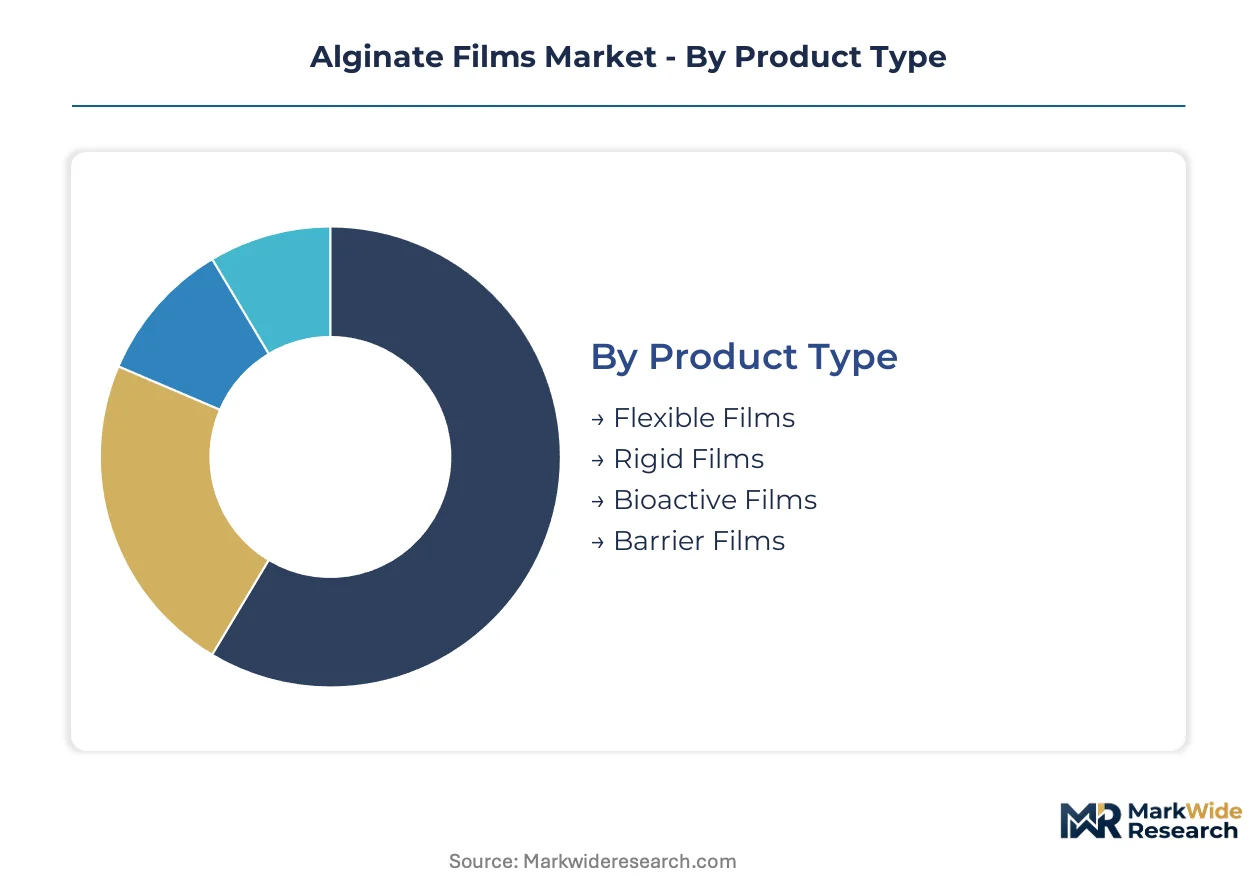
Alginate film performance requirements diverge sharply across end-use applications, forcing manufacturers to calibrate cross-linking density, plasticizer loading, and barrier specifications for each customer segment. Product customization intensity determines margin capture, with pharmaceutical-grade formulations commanding substantial premiums over commodity food wrapping substrates.
Product Type:
Standardization decreases from flexible to barrier variants, with bioactive films occupying the most bespoke development spectrum.
- Flexible Films:Thin, pliable membranes formed through calcium ion cross-linking of medium-viscosity sodium alginate solutions, optimized for conformability in fresh produce wrapping and basic wound covering formats. Demand concentrates in German retail packaging networks where EU Green Deal mandates accelerate petroleum plastic displacement. Calcium chloride cross-linker price volatility compresses margins for mid-volume converters.
- Barrier Films:High-density formulations engineered for sub-0.1 cc/m²/day oxygen transmission rates through nanolaminated polysaccharide layering, serving parenteral drug stability applications. Japanese medical device manufacturers in Osaka and Tokyo prefectures anchor demand as PMDA documentation requirements favor domestic suppliers. Layer-by-layer electrostatic assembly technology electrifies competitive differentiation among capable converters.
- Rigid Films:High-G-content alginate structures with elevated modulus for structural packaging inserts and orthopedic casting substrates.
- Bioactive Films:Antimicrobial and growth-factor-loaded variants penetrating chronic wound management protocols, with steepest expansion trajectory in German hospital procurement consolidations.
Most installed capacity flows through Flexible Films. Expansion is steepest in Bioactive Films.
Application:
Volume scale inversely correlates with technical complexity, with tissue engineering representing the smallest but most defensible niche.
- Food Packaging:Moisture-responsive barrier layers for fresh produce, meat, and seafood wrapping where biodegradability certification drives procurement decisions. EU Circular Economy Action Plan quotas harden demand across French and Italian retail chains. REACH solvent residue enforcement redirects sourcing toward EU-certified extraction facilities.
- Drug Delivery:Oral dosage matrix systems enabling precise API release kinetics through pH-dependent alginate dissolution in gastric environments. US pharmaceutical manufacturers expand utilization following FDA guidance on biodegradable primary packaging. USP Class VI biocompatibility testing extends qualification cycles to 18-24 months.
- Medical Dressings:Absorbent wound contact layers for exuding chronic wounds, with hospital procurement consolidation favoring integrated film-converter-device suppliers.
- Tissue Engineering:Cell scaffold substrates requiring ultra-low endotoxin specifications and customizable degradation profiles for regenerative medicine applications.
Food Packaging absorbs the greatest substrate tonnage. Drug Delivery climbs the fastest as controlled-release formulations multiply.
End User:
Customer sophistication and regulatory burden intensify from food industry through biotechnology, reshaping supplier qualification requirements.
- Healthcare:Hospital networks and outpatient clinics procuring sterile wound dressings and ostomy products with consolidated vendor preferences. United States acute care networks reduce SKU complexity through single-source film-converter-device contracts. In-house sterilization and pouching capabilities determine supplier selection.
- Pharmaceuticals:Drug delivery manufacturers requiring documentary evidence of heavy metal compliance, endotoxin limits, and batch-to-batch viscosity consistency. ECHA residual metal thresholds impose costly purification burdens on seaweed extraction operations serving European customers.
- Food Industry:Processors and retailers seeking biodegradable wrapping alternatives with cost parity to conventional plastics.
- Biotechnology:Cell therapy developers and regenerative medicine specialists demanding custom degradation kinetics and ultra-pure raw material provenance.
Healthcare channels move the highest unit volumes. Biotechnology posts the steepest expansion trajectory as cell therapy manufacturing scales.
Formulation:
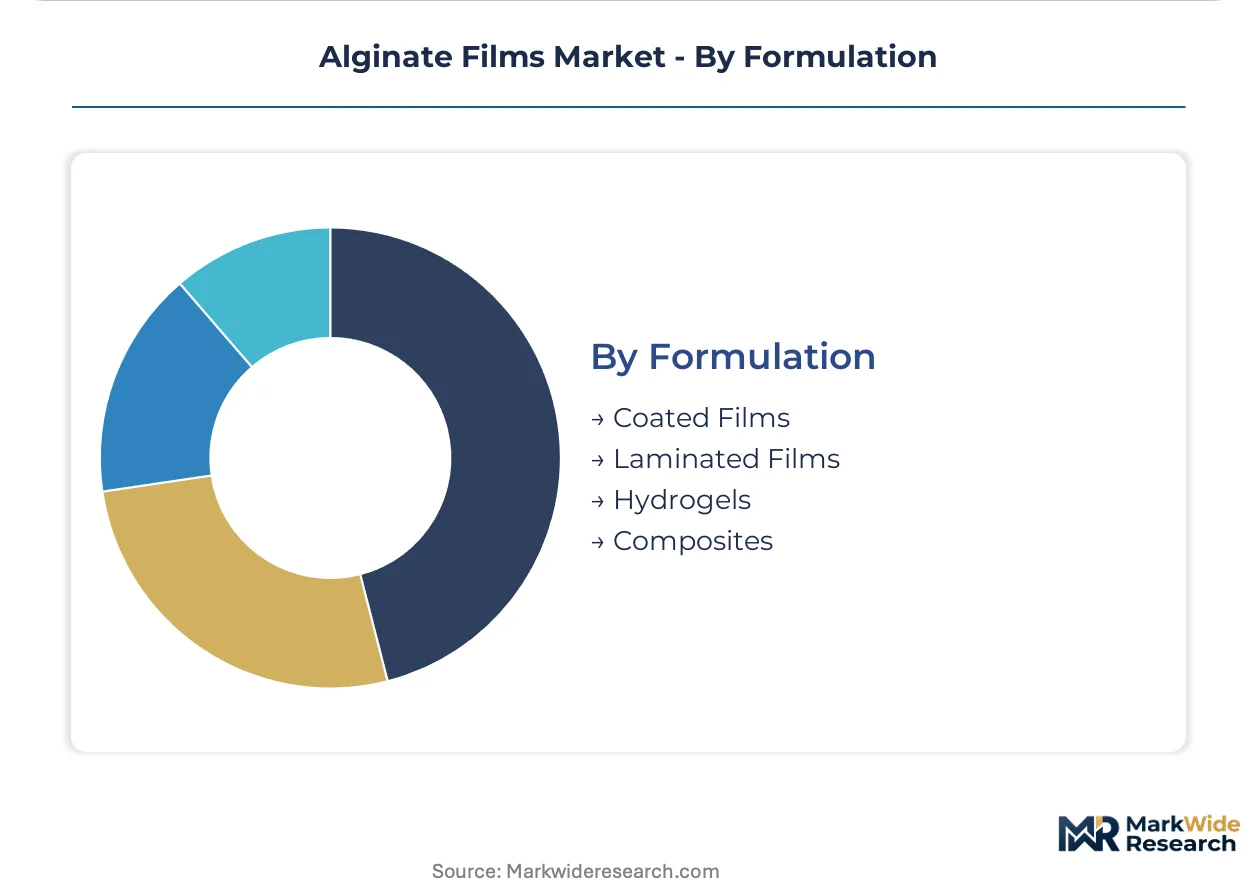
Manufacturing complexity and capital intensity escalate from simple hydrogels through multi-layer composites, filtering the supplier base.
- Hydrogels:Water-swollen alginate networks formed through ionotropic gelation, serving moisture-retentive wound dressing and drug reservoir applications. Japanese kelp harvest clusters in Hokkaido ensure pharmaceutical-grade raw material security for Asian market suppliers. Climate-induced yield fluctuations create availability uncertainty for non-integrated processors.
- Composites:Hybrid structures incorporating ceramic fillers, synthetic polymers, or protein reinforcements for mechanical property enhancement in orthopedic and dental applications. Electrospinning-nanofiber convergence enables ultrathin high-barrier medical films with enhanced tensile strength. German research institutes lead process development.
- Coated Films:Surface-modified substrates with antimicrobial or moisture-resistant top layers for targeted functional performance.
- Laminated Films:Multi-ply constructions combining alginate barriers with synthetic or natural polymer support layers for structural integrity.
Hydrogels command the greatest installed capacity. Composites gain share fastest as mechanical property requirements harden across advanced medical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping alginate film production geography as manufacturers migrate toward jurisdictions with lower cost-of-compliance for seaweed extraction and pharmaceutical-grade certification. The EU Green Deal's stringent REACH thresholds push mid-tier processors toward Asian kelp harvest clusters where heavy metal purification burdens remain lighter. Japanese and Chinese extraction facilities capture volume as European converters seek alternative raw material sourcing.
United States
FDA pharmaceutical packaging guidance drives alginate film requalification for oral solid dose applications. USP Class VI biocompatibility testing extends product qualification cycles to 18-24 months. New Jersey and Massachusetts pharmaceutical clusters anchor demand from controlled-release drug delivery manufacturers.
Germany
EU Circular Economy Action Plan quotas harden demand for biodegradable food wrapping across French and Italian retail chains supplied by German converters. ECHA residual solvent enforcement redirects procurement toward EU-certified extraction facilities. Bavarian packaging suppliers mandate third-party solvent residue documentation across their alginate film supply base.
Japan
PMDA documentation demands for alginate-based medical devices complicate cross-border product registration and favor domestic suppliers. Hokkaido kelp harvest clusters ensure pharmaceutical-grade raw material security for Asian market film producers. Osaka and Tokyo prefectures anchor medical device manufacturing demand for high-barrier parenteral drug stability applications.
China
National seaweed processing capacity expands to serve European pharmaceutical packaging customers seeking REACH-compliant alternative sourcing. Qingdao and Shandong extraction facilities scale pharmaceutical-grade alginate output for export markets. Domestic food packaging demand accelerates as biodegradable film mandates proliferate across provincial retail regulations.
Norway
Climate-induced kelp yield fluctuations off Norwegian coasts create raw material availability uncertainty for European film processors. Specialized alginate extraction chemistry expertise remains concentrated among marine biotechnology researchers in Trondheim and Bergen clusters. National regulators emphasize biodegradability certification protocols as Atlantic harvest security deteriorates.
Alginate Films Market Competitive Environment
Capacity expansion dominates the current landscape as alginate film converters scale extraction and film-forming operations to capture EU Green Deal-driven packaging substitution demand. The vendor base stratifies across integrated seaweed harvesters, specialized pharmaceutical-grade refiners, and regional film-forming converters. Three archetypes prevail: kelp-harvesting extraction specialists with captive raw material supply, pharmaceutical-grade purity processors serving medical device customers, and commodity converters supplying food packaging networks. M&A activity concentrates on backward integration into Atlantic and Pacific seaweed harvesting assets. Technology licensing partnerships proliferate around layer-by-layer electrostatic assembly processes for high-barrier medical applications.
Within the integrated extraction tier, KIMICA Corporation exemplifies vertical control from Japanese kelp harvests through pharmaceutical-grade alginate production. DuPont de Nemours, Inc. occupies a position representing polymer science heritage applied to high-barrier medical film formulations. FMC Corporation anchors North American supply chain security through integrated seaweed extraction and refining operations serving regional pharmaceutical packaging demand.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| FMC Corporation |
| KIMICA Corporation |
| Cargill, Incorporated |
| Ashland Global Holdings Inc. |
| Ceamsa |
| Marine Biopolymers Ltd. |
| Qingdao Bright Moon Seaweed Group Co., Ltd. |
| Shandong Jiejing Group Corporation |
| Others |
Value Chain & Pricing Dynamics
Calcium chloride cross-linker price volatility cascades through alginate film manufacturing tiers, compressing margins for mid-volume converters while pharmaceutical-grade processors absorb cost shocks through long-term kelp supply contracts. EU REACH heavy metal purification mandates amplify this stratification, forcing European food packaging buyers toward premium-certified extraction facilities as Atlantic harvest security deteriorates.
Pricing Analysis
Retailer markup layers atop distributor margins create substantial spread between raw extraction costs and hospital procurement prices for sterile wound dressing films. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and commodity wrapping levels reflects certification burden and batch testing intensity. Pricing pressure stems from calcium chloride feedstock cost swings and REACH compliance investments, with food industry buyers exhibiting highest price sensitivity compared to pharmaceutical contract manufacturers prioritizing supply security over unit economics.
Supply Chain Analysis
Freight cost differentials between Atlantic and Pacific kelp sourcing routes reshape procurement geography as European converters seek REACH-compliant alternatives. Raw material supply draws from Japanese Hokkaido harvest clusters, Norwegian Atlantic extraction facilities, and Chinese Qingdao processing centers. Sodium alginate and calcium chloride dependencies create single-source vulnerability for non-integrated processors. Distribution runs through specialized chemical distributors serving pharmaceutical packaging converters and direct hospital supply contracts for finished wound care devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alginate films represent a late-cycle quality story as hospital procurement consolidation favors integrated film-converter-device suppliers capable of delivering sterile finished products with documented heavy metal compliance.
For Market Incumbents: To counter climate-induced Atlantic kelp yield volatility, secure backward integration into Pacific harvest assets through offtake agreements with Japanese or Chinese extraction facilities. Invest in layer-by-layer electrostatic assembly capabilities to defend premium positioning in high-barrier parenteral drug packaging applications where sub-0.1 cc/m²/day oxygen transmission specifications determine supplier selection. For New Entrants and Emerging Players: Begin with bioactive antimicrobial film development for German hospital network procurement consolidations, where chronic wound management protocols remain underpenetrated by specialized alginate membrane suppliers. Target US pharmaceutical packaging requalification opportunities following FDA biodegradable primary packaging guidance, leveraging electrospinning-nanofiber hybrid manufacturing partnerships to bypass capital-intensive solvent casting infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where pharmaceutical-grade certification timelines extend 18-24 months and specialized alginate extraction chemistry expertise concentrates among limited marine biotechnology research clusters. Long-term viability favors acquisition targets with captive kelp supply and in-house USP Class VI testing capabilities. Watch PMDA documentation requirement harmonization discussions as inflection signal for cross-border medical device registration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pacific Kelp Harvest Assets | Secures pharmaceutical-grade raw material supply against Atlantic climate volatility affecting Norwegian extraction yields. |
| Layer-by-Layer Electrostatic Assembly Adoption | Enables sub-0.1 cc/m²/day oxygen barrier performance for Japanese parenteral drug stability applications without synthetic lamination. |
| USP Class VI Biocompatibility Certification Investment | Qualifies alginate films for FDA-regulated oral solid dose packaging requalification programs in New Jersey pharmaceutical clusters. |
| Integrated Film-Converter-Device Manufacturing Scale-Up | Matches hospital procurement consolidation preferences for sterile finished wound dressings rather than bulk substrate rolls. |
| REACH-Compliant Alternative Sourcing Partnership | Redirects European pharmaceutical packaging procurement toward ECHA-certified Chinese extraction facilities as Atlantic supply tightens. |
Study Parameters
Multiple input streams — primary interviews with alginate extraction plant managers, pharmaceutical packaging procurement leads, and hospital GPO contracts managers; secondary validation through ECHA enforcement records, FDA guidance documents, and Japanese PMDA submission databases; customs trade data and SEC filings from publicly traded seaweed processors — were reconciled through bottom-up tonnage modeling and top-down value estimation across product and application segments.
Historical volume trajectories were cross-referenced against expert panel assessments of EU Green Deal packaging mandate implementation pace and pharmaceutical controlled-release formulation adoption curves. Segmentation modeling spanned product type, application, end user, and formulation complexity tiers throughout the projection horizon. CAGRs were derived from elasticity-adjusted demand functions incorporating kelp harvest yield variability and cross-linker cost cycle assumptions.
Several conditions sit outside the modeled scope, including abrupt regulatory harmonization between PMDA and FDA medical device documentation requirements, breakthrough synthetic polymer biodegradability technologies displacing alginate barriers, and severe Atlantic kelp ecosystem collapse from ocean temperature anomalies. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
MLCC Silicone Release Film Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Compostable Cotton Swab Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
Electroactive Polymers (EAP) Market
Specialty Materials
Global Liquid Crystal Polymer (LCP) Films and Laminates Market
Specialty Materials
Global PU Films Market
Specialty Materials
Light Diffusion Materials Market
Specialty Materials
Global Montan Wax Market
Specialty Materials
Europe Green Sic Market
Specialty Materials
Carbon Blacks for Non-Rubber Applications Market
Specialty Materials
Mica Sheet Market
Specialty Materials
PVB Interlayers Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
Semiconductor O-Rings Market
Specialty Materials
Hydrolysis Stable Polyester Films Market