
 Global Cellulose Acetate Market | 2026-2036
Global Cellulose Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cellulose Acetate Market Foresight
A shift from single-source wood pulp supply toward multi-source cellulose procurement is recalibrating raw material security across the value chain. Eastman Chemical Company leverages vertical integration from cotton linter through acetate flake production to sustain cost discipline. Daicel Corporation anchors its position through specialized manufacturing scale in cigarette filter tow. Celanese Corporation competes on geographic reach across North American and European conversion facilities.
Cellulose acetate is a thermoplastic polymer derived from cellulose esterification with acetic anhydride, typically exhibiting acetyl content between 38% and 40% for standard molding grades and serving primarily as a biodegradable alternative to petroleum-derived plastics in filtration and textile applications. Cigarette filter tow dominates volume throughput as a mature, high-tonnage segment with thin margin pools, while coating material commands premium positioning in specialty adhesive and barrier film end uses. Filament fiber maintains steady demand from textile manufacturers seeking silk-like drape properties in woven and knitted goods.
EPA industrial chemical oversight and REACH substance registration in Europe constrain phthalate plasticizer formulations and mandate extended biodegradability documentation for consumer-facing applications. FDA food-contact regulations and ISO 9001 quality management standards further delineate market access thresholds for packaging and film-grade cellulose acetate. Stakeholders must track regulatory divergence between jurisdictions while evaluating bio-based feedstock certification schemes as emerging competitive differentiators.
Market Dynamics
REACH substance registration in Europe and evolving EPA industrial chemical oversight in the United States are forcing reformulation of plasticizer systems across cellulose acetate grades, compressing product development cycles and recalibrating raw material sourcing strategies.
Growth Catalysts
- China's domestic tobacco value chain:Cigarette filter producers in Shandong and Yunnan provinces sustain high-volume material offtake through state-controlled manufacturing consolidation.
- REACH biodegradability mandates:Extended documentation requirements for consumer-facing applications accelerate substitution of petroleum-derived plastics in European packaging segments.
- Textile filament fiber demand:Manufacturers in Italy and Japan seek silk-like drape properties for luxury woven goods, creating premium-grade acetate consumption.
Market Restraints
- Wood pulp supply concentration:Softwood and hardwood pulp markets exhibit price volatility tied to Canadian and Scandinavian forestry cycles.
- Phthalate regulatory friction:EPA and REACH constraints on traditional plasticizer chemistries limit formulation flexibility for legacy molding equipment.
- Polylactic acid substitution:Bio-based PLA competes for biodegradable packaging applications with comparable compostability credentials.
Strategic Opportunities
- India's specialty textile expansion:Surat and Tiruppur clusters represent underpenetrated demand for filament-grade acetate in silk-substitute fabrics.
- ISO 9001 certification premiums:Food-contact grade acetate commands pricing advantages in Japanese and South Korean barrier film markets.
- Acetate tow-filter convergence:Next-generation heat-not-burn tobacco devices create novel filtration substrate requirements in South Korea and Japan.
Industry Challenges
- Acetylation process engineering expertise:Specialized chemical engineering talent for controlled esterification remains concentrated in legacy production regions.
- Multi-jurisdiction compliance timelines:Simultaneous FDA food-contact reviews and ECHA substance evaluations extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cellulose Acetate Market |
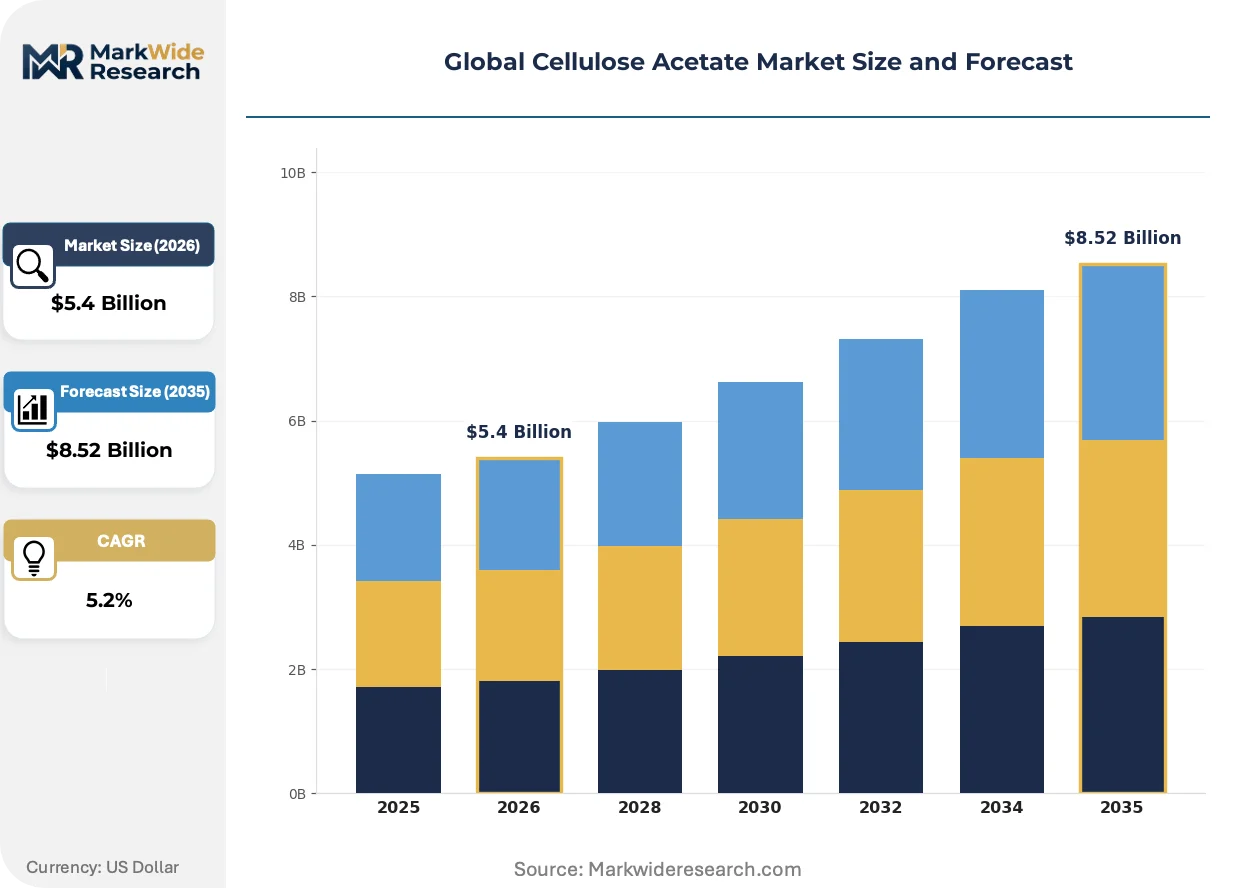
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.52 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filament Fiber, Photographic Film, Cigarette Filter, Textile Yarn, Coating Material Form: Flakes, Granules, Powder, Sheets, Pellets Application: Textile Manufacturing, Film Production, Packaging Solutions, Filter Production, Adhesive Development End User: Textile Manufacturers, Film Processors, Packaging Companies, Filter Producers, Adhesive Suppliers |
| Companies Covered | Eastman Chemical Company, Celanese Corporation, Daicel Corporation, Cerdia International GmbH, Mitsubishi Chemical Corporation, Sichuan Push Acetati Co., Ltd., Rayonier Advanced Materials, Sappi Limited, China National Tobacco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cellulose Acetate Market Shifts & Advancements
Cellulose feedstock diversification and plasticizer chemistry reinvention are compressing traditional supply relationships while opening new performance tiers across filtration and textile end uses.
Enzymatic acetylation processes are decentralizing production economics for specialty cellulose acetate grades. Biocatalytic modification reduces energy intensity in flake manufacturing. Small-scale producers in Germany and the Netherlands adopt these systems to serve regional coating and adhesive compounders previously dependent on imported flake.
ECHA's restriction roadmap for microplastic additives is forcing filter tow producers to accelerate biodegradable plasticizer validation. Industrial consequence includes reformulation of cigarette filter binding systems. Asian-Pacific manufacturers in Indonesia and Vietnam face compressed compliance timelines as EU-bound export requirements tighten.
Textile spinners in Como and Kyoto now specify acetyl content tolerances within 0.5 percentage points for color-matched filament batches. This precision procurement replaces commodity-grade spot purchasing. The shift compresses supplier qualification periods and concentrates volume commitments among acetate tow specialists with in-house fiber extrusion capabilities.
Global Cellulose Acetate Market Segmentation
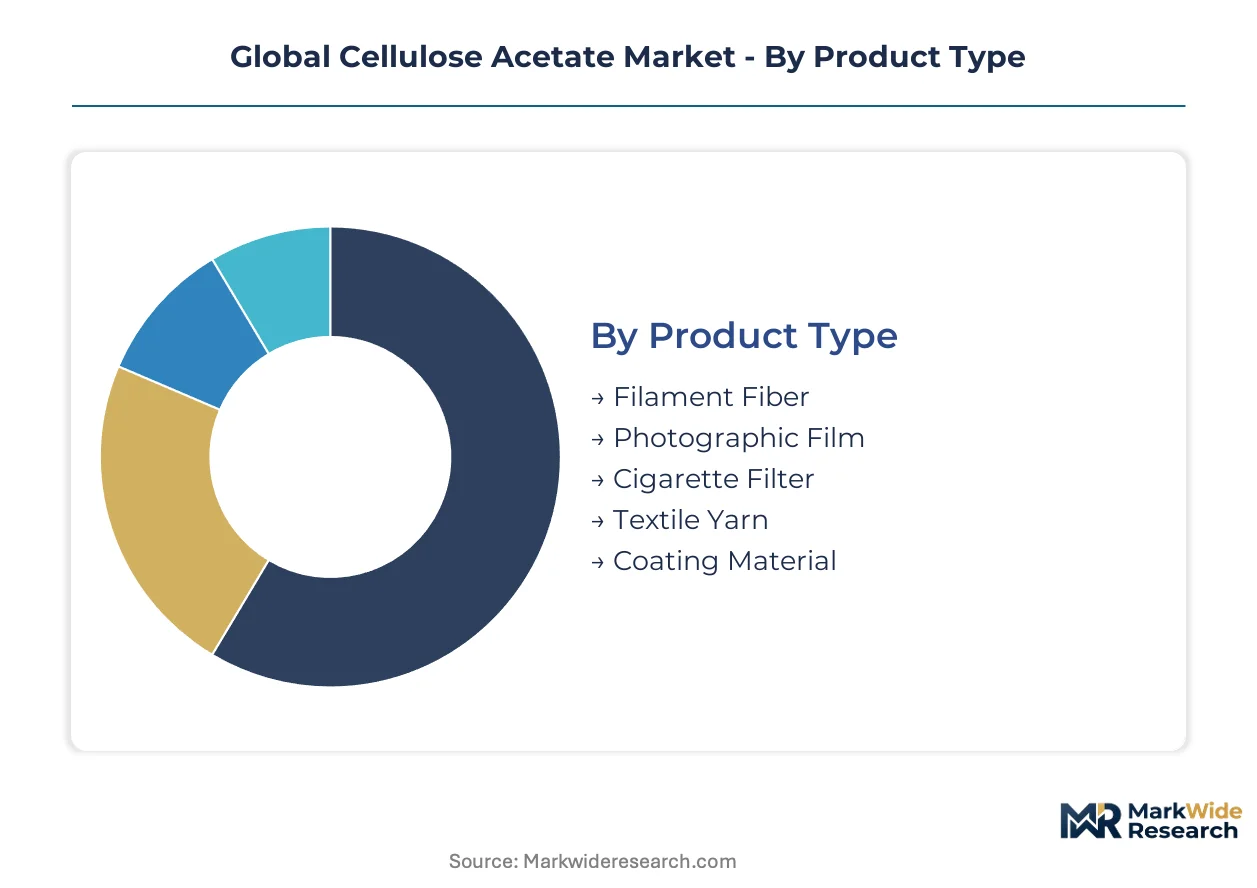
Cellulose acetate markets fragment across five distinct value chains, each with divergent specification tolerances and customer procurement rhythms. Product type determines acetyl content ranges and plasticizer compatibility, while form factor dictates conversion economics for downstream compounders.
Product Type:
Standalone applications dominate high-volume segments, whereas embedded systems in composite materials command specification premiums.
- Cigarette Filter:High-purity acetate tow with controlled denier per filament serves heat-not-burn and conventional filtration devices. State-controlled tobacco value chains in China and Indonesia sustain bulk offtake volumes despite regulatory pressure on combustible products.
- Filament Fiber:Extruded continuous filaments with silk-like luster and drape properties feed luxury textile weaving operations. Italian spinners in Como and Japanese manufacturers in Kyoto specify tight acetyl tolerances for color-matched batch production.
- Photographic Film:Specialized base material for archival imaging and motion picture stock. Demand concentrates in niche professional and heritage preservation segments.
- Textile Yarn:Staple fiber and spun yarn grades for blended fabric applications. Surat and Tiruppur clusters in India represent emerging consumption nodes.
- Coating Material:Solution-grade acetate for adhesive and barrier film formulations. European packaging converters seek biodegradable alternatives to petroleum-derived coatings under ECHA microplastic restrictions.
Cigarette Filter leads volumes today; Coating Material is gaining share fastest.
Form:
Physical configuration determines handling characteristics and dissolution kinetics for solvent-based processing lines.
- Flakes:Primary feedstock for solution casting and spinning operations. Eastman Chemical and Daicel Corporation ship flake grades to regional compounders for captive tow extrusion.
- Granules:Free-flowing pellets optimized for thermoplastic molding and extrusion. Automotive interior trim and eyeglass frame manufacturers specify granule flow indices for injection equipment compatibility.
- Powder:Fine particle size for adhesive lacquers and coating formulations. Shelf stability requirements favor powder packaging for long-distance supply chains.
- Sheets:Calendered film stock for lamination and thermoforming applications. Limited specialty demand from display and signage producers.
- Pellets:Compounded grades with pre-mixed plasticizers for direct processing. Reduces solvent handling for small-scale textile spinners.
Flakes dominate commercial throughput; Granules are climbing the fastest on thermoplastic substitution demand.
Application:
End-use processing intensity separates commodity volume plays from specification-driven premium positioning.
- Filter Production:Tow conversion and filter rod assembly for tobacco and air filtration. Indonesian and Vietnamese manufacturers face compressed timelines for biodegradable plasticizer validation under EU export rules.
- Textile Manufacturing:Filament spinning and fabric weaving for apparel and home furnishings. Precision procurement contracts now specify acetyl content within 0.5 percentage points.
- Film Production:Solution casting for photographic and packaging films. Archival-grade specifications demand ultra-low residual acidity.
- Packaging Solutions:Barrier films and compostable containers for food-contact applications. FDA and EFSA compliance documentation extends qualification cycles.
- Adhesive Development:Solvent-based and hot-melt formulations for industrial bonding. Coating compounders in Germany and the Netherlands source regional flake for biocatalytic processing.
Filter Production anchors volume commitments; Packaging Solutions shows steepest expansion trajectory on regulatory substitution mandates.
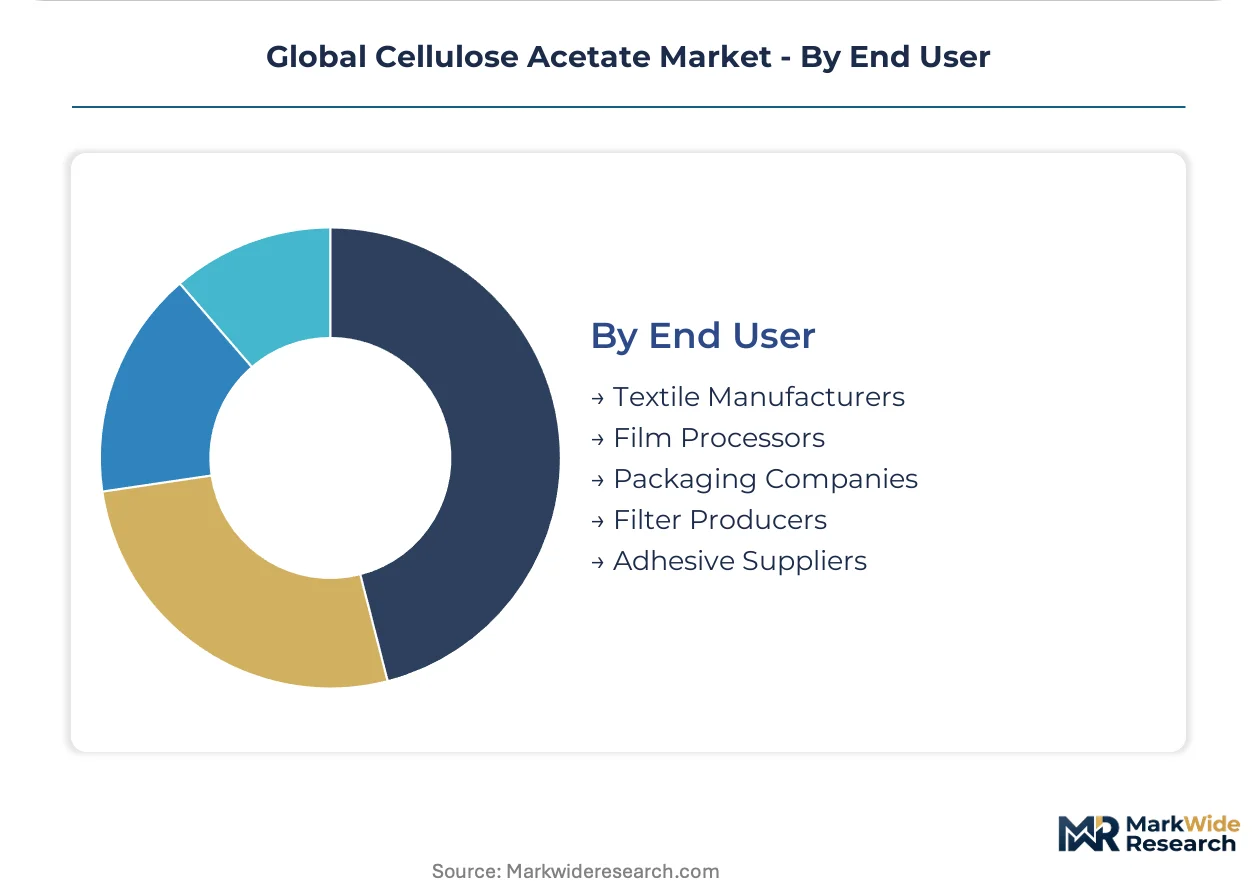
End User:
Customer scale and technical capability determine specification negotiation leverage and contract structures.
- Filter Producers:Integrated tow-to-filter manufacturers and independent rod makers. China's state tobacco monopoly consolidates purchasing through designated supply agreements.
- Textile Manufacturers:Filament spinners, weavers, and knitters across apparel value chains. Japanese and South Korean mills pay ISO 9001 certification premiums for food-contact barrier applications.
- Film Processors:Photographic laboratories and motion picture studios. Declining volume base concentrates among heritage archival specialists.
- Packaging Companies:Converters of flexible film and rigid containers. Biodegradability documentation requirements under REACH reshape supplier qualification.
- Adhesive Suppliers:Industrial compounders and coating formulators. Regional sourcing preferences favor small-scale European producers with enzymatic acetylation capabilities.
Filter Producers command largest volume share; Packaging Companies are expanding most quickly on sustainability-driven material substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-controlled tobacco value chain concentrates downstream demand for cellulose acetate tow and flake, with Shandong and Yunnan provinces anchoring high-volume filter production. Regulatory divergence across major consuming regions is fragmenting supply relationships and forcing localized compliance investments.
United States
EPA industrial chemical oversight and evolving state-level plasticizer restrictions are reshaping formulation requirements for domestic compounders. FDA food-contact regulations delineate market access thresholds for packaging-grade acetate. Texas and Louisiana host specialty chemical manufacturing clusters where producers adapt to compressed product development cycles.
Germany
ECHA substance registration and REACH biodegradability mandates accelerate substitution of petroleum-derived plastics in European packaging segments. Industrial converters in the Ruhr region and Bavaria source regional flake from small-scale producers with enzymatic acetylation capabilities. The country's national chemical regulator enforces extended documentation requirements for consumer-facing applications.
Japan
Textile spinners in Kyoto and Nagoya specify acetyl content tolerances within 0.5 percentage points for color-matched filament batches. METI standards and JIS quality certifications support premium positioning in luxury woven goods. Next-generation heat-not-burn tobacco devices create novel filtration substrate requirements in Kansai manufacturing corridors.
India
Surat and Tiruppur clusters represent underpenetrated demand for filament-grade acetate in silk-substitute fabrics. BIS certification requirements and DGFT import regulations shape raw material sourcing strategies for domestic textile manufacturers. The country's national standards body is tightening quality specifications for specialty chemical imports.
Indonesia
Cigarette filter producers face compressed timelines for biodegradable plasticizer validation under EU export rules. State-controlled and independent manufacturers sustain bulk offtake volumes despite regulatory pressure on combustible products. Java-based conversion facilities are recalibrating supply relationships to meet tightening ECHA microplastic restrictions.
Global Cellulose Acetate Market Competitive Landscape
Global majors compete with regional champions across raw material security and specialized manufacturing scale. The vendor base separates into integrated chemical conglomerates with captive pulp supply, mid-scale specialists concentrating on filter tow production, and emerging biocatalytic processors serving niche coating segments. Two dominant competitive moves are reshaping positioning: backward integration into cotton linter and wood pulp sourcing to control input costs, and geographic expansion through regional flake distribution partnerships to capture textile and packaging demand.
Within the integrated chemical conglomerate tier, Eastman Chemical Company and Daicel Corporation exemplify divergent strategic anchors. Eastman represents North American vertical integration from raw cellulose through acetate flake production. Daicel occupies a position as a Japanese specialist with concentrated manufacturing scale in cigarette filter tow. Celanese Corporation sits within the geographic reach archetype, competing through conversion facility networks across North American and European markets.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Celanese Corporation |
| Daicel Corporation |
| Cerdia International GmbH |
| Mitsubishi Chemical Corporation |
| Sichuan Push Acetati Co., Ltd. |
| Rayonier Advanced Materials |
| Sappi Limited |
| China National Tobacco Corporation |
| Others |
Supply & Pricing Matrix
Captive integration from cotton linter through acetate flake production anchors cost discipline and pricing power for North American majors, while Asian competitors rely on spot pulp markets that transmit volatility into margin compression.
Pricing Analysis
Wood pulp cost pass-through dominates cellulose acetate pricing mechanics, with softwood and hardwood fiber indices from Canadian and Scandinavian suppliers resetting quarterly contract baselines. Three-tier pricing structure across premium, standard, and economy levels separates food-contact certified grades from industrial molding stock and commodity filter tow. Pricing pressure stems from polylactic acid substitution in biodegradable packaging segments. Filter producers exhibit highest price sensitivity due to thin margin pools, while coating compounders for barrier films accept certification premiums.
Supply Chain Analysis
Dual-sourcing requirements from European packaging converters now mandate qualification of at least two flake suppliers to mitigate REACH compliance timeline risks. Supply concentrates in the United States, Japan, and China, with the latter anchoring downstream tow conversion for domestic tobacco value chains. Raw material dependencies center on dissolving-grade pulp, acetic anhydride, and plasticizer chemistries. Single-source vulnerability in wood pulp supply creates exposure to Canadian forestry cycle disruptions. Distribution runs through regional compounder networks that convert flake to tow, granule, or solution-grade products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
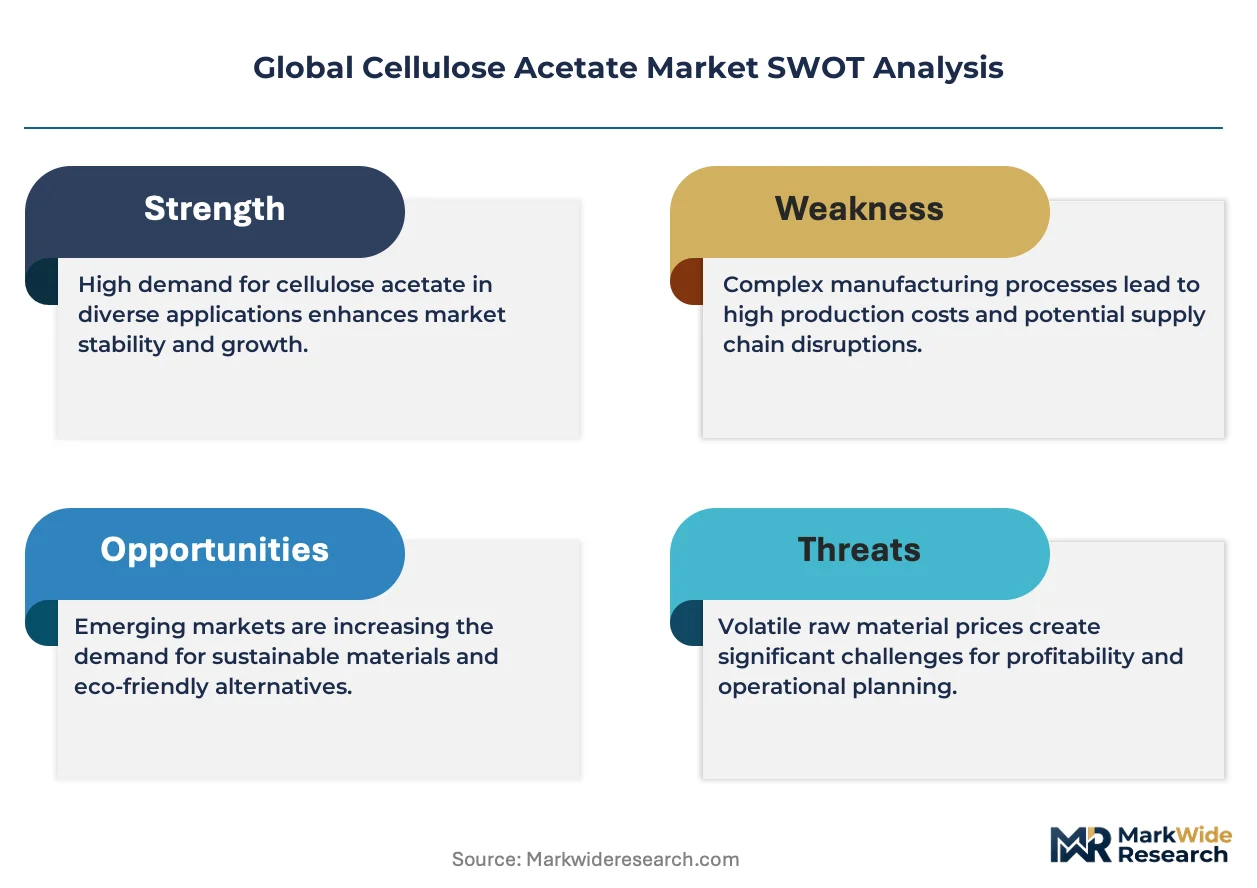
Margin expansion opportunities concentrate in enzymatic acetylation cost-down trajectories and premium-grade filament fiber positioning for luxury textile spinners.
For Market Incumbents: Cement backward integration into dissolving pulp supply to insulate margin pools from Canadian and Scandinavian fiber price cycles. Expand enzymatic acetylation capacity in Germany and the Netherlands to capture coating compounder demand under ECHA microplastic restrictions. Prioritize ISO 9001 certification maintenance for Japanese and South Korean food-contact barrier film premiums.
For New Entrants and Emerging Players: The premium-to-economy tier price gap in filament fiber offers white-space entry for Surat and Tiruppur textile clusters seeking silk-substitute acetate. Target underpenetrated Indian specialty textile demand with regional flake distribution partnerships. Pursue biocatalytic processing capabilities to serve European adhesive compounders with localized supply.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale filter tow specialists because China's state tobacco consolidation is compressing supplier counts and creating distressed asset opportunities. Five-to-ten year viability hinges on heat-not-burn device filtration substrate positioning. Watch biodegradable plasticizer validation timelines as the inflection signal for EU export compliance premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dissolving Pulp | Eastman Chemical's captive linter supply insulates margin pools from Scandinavian fiber volatility. |
| Enzymatic Acetylation Scale-Up | Biocatalytic processing reduces energy intensity for German coating compounders under REACH mandates. |
| Food-Contact Certification Investment | ISO 9001 documentation commands pricing premiums in Japanese barrier film markets. |
| Regional Flake Distribution Partnerships | Localized supply networks capture Surat textile spinner demand with compressed lead times. |
| Biodegradable Plasticizer Reformulation | ECHA microplastic restrictions force Indonesian filter producers to validate alternative binding systems. |
Research Methodology
Multiple input streams — primary interviews with plant managers and procurement leads at downstream OEMs, secondary validation through customs/trade data and SEC 10-K filings, and technical R&D director surveys — were reconciled through bottom-up and top-down triangulation. Conversations with cigarette filter manufacturers, textile spinners in Como and Kyoto, and European coating compounders informed demand-side assumptions. Chemical industry association reports and dissolving pulp market databases provided supply-side calibration.
Data-stream reconciliation across product type, form factor, application intensity, and regional production hub dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from segment-level growth rate blending anchored to acetyl content specification trends and regulatory substitution mandates. Forecast inputs incorporated enzymatic processing adoption curves and REACH biodegradability documentation timelines.
Caveats apply where wood pulp price volatility, phthalate regulatory friction, or PLA substitution acceleration could materially shift the outlook. Deviation in biodegradable plasticizer validation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Global PE Films Market
Specialty Materials
Global Ajinomoto Build-Up Film Substrate Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
Crusher Backing Materials Market
Specialty Materials
Semiconductor O-Rings Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Europe Acrylic Sheet Market
Specialty Materials
Carbon Blacks for Non-Rubber Applications Market
Specialty Materials
Gutta-Percha Market
Specialty Materials
Teschemacherite Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Global Fluorosilicone Market
Specialty Materials
Middle East and Africa Anti-Friction Coatings Market
Specialty Materials
Europe Textile Films Market