
 Global Poly Vents Market | 2026-2036
Global Poly Vents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Poly Vents Market Intelligence
Demand for poly vents is bifurcating away from commoditized residential construction projects toward specialized industrial applications requiring high-performance materials. W. L. Gore & Associates leverages its expertise in microporous membranes to serve demanding electronics and automotive clients. Donaldson Company specializes in filtration solutions for heavy-duty industrial equipment. Parker Hannifin competes with a broad portfolio targeting diverse industrial fluid and gas handling systems.
Poly vents are engineered polymer components that incorporate a microporous membrane, often made of ePTFE or similar materials. Their primary function is to equalize pressure within a sealed enclosure by allowing air and gas to pass through while blocking the entry of liquids and solid particulates. While polypropylene and PVC materials dominate the high-volume residential homes segment, advanced materials like polycarbonate serve specialized industrial facilities. The material choice directly influences performance and cost, defining the application scope.
Product specifications are shaped by multiple regulatory frameworks, including Europe's REACH regulations on chemical substances and CE marking requirements for market entry. In the United States, UL standards for component safety in electronic devices are critical for market access. Future competitiveness will depend on navigating these disparate standards while balancing material innovation against cost pressures from commoditized segments.
Market Dynamics
The market's central dynamic is the technical divergence between high-volume, low-spec construction applications and performance-driven industrial segments. This split forces suppliers to manage dual supply chains for commodity polymers versus advanced materials like ePTFE for electronics and automotive enclosures.
Growth Catalysts
- Ingress Protection Standards:The widespread adoption of IEC Ingress Protection (IP) ratings as a prerequisite for electronic device market access creates a direct demand pull for certified venting solutions.
- Automotive Electrification:The expansion of electric vehicle battery packs and advanced driver-assistance systems (ADAS) requires sophisticated vents to manage pressure fluctuations and protect sensitive electronics.
- Manufacturing Concentration:The consolidation of electronics assembly within industrial clusters in China, particularly in the Pearl River Delta, concentrates demand and simplifies logistics for specialized vent suppliers.
Market Restraints
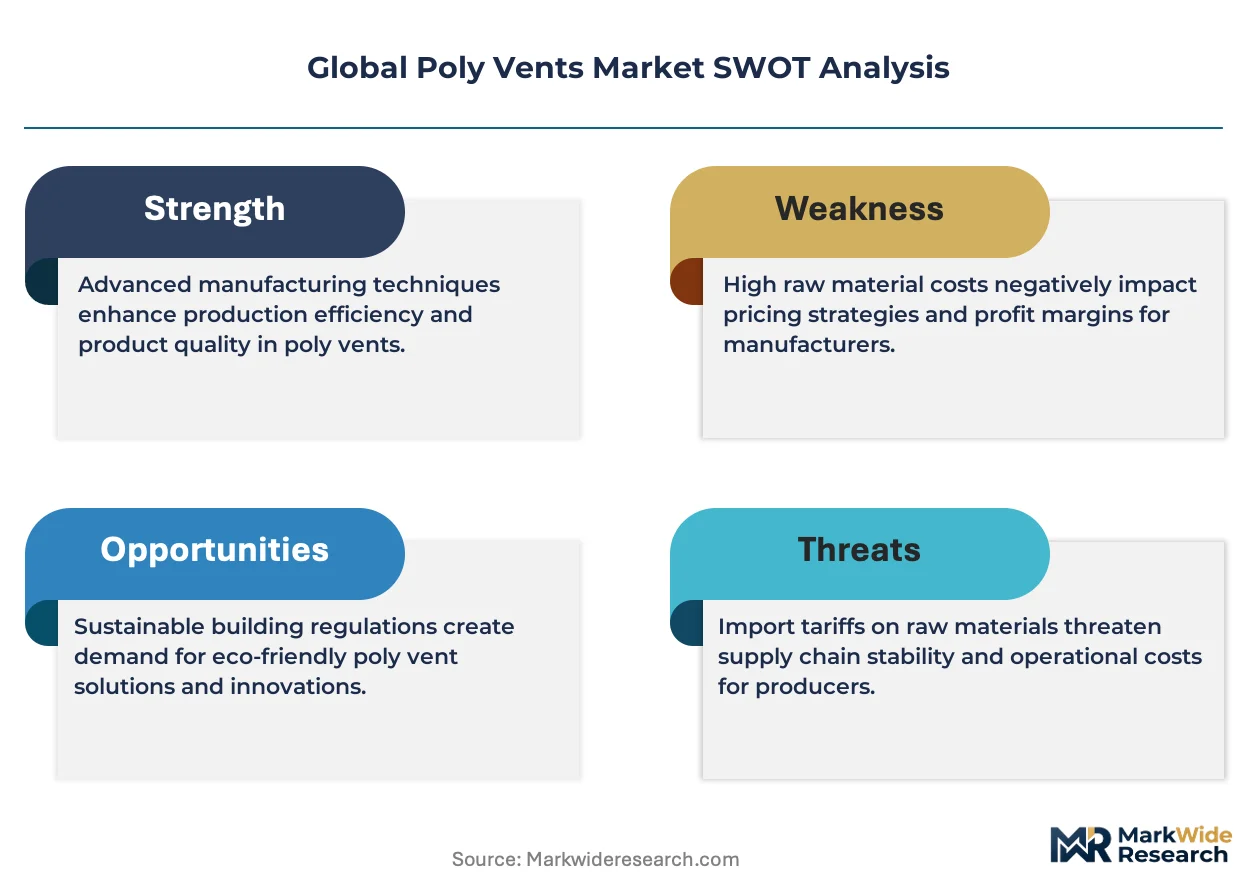
- Material Cost Premium:The high cost of specialized polymers like expanded polytetrafluoroethylene (ePTFE) and polycarbonate creates a significant price barrier compared to commodity materials used in less demanding applications.
- Regulatory Fragmentation:Navigating disparate compliance frameworks, such as Europe's REACH chemical regulations and UL safety standards in the United States, increases testing costs and time-to-market for manufacturers.
- Alternative Sealing Technologies:The development of hermetically sealed enclosures for certain electronic devices presents a substitution threat, potentially eliminating the need for pressure equalization vents in specific niches.
Strategic Opportunities
- Emerging IoT Applications:The proliferation of outdoor Internet of Things (IoT) sensors and 5G telecommunications equipment creates new demand for vents that can withstand harsh environmental conditions.
- Sustainable Materials:Development of vents from recycled or bio-based polymers offers a path to meet corporate sustainability goals and appeal to environmentally conscious industrial customers.
- Industrial Automation in Southeast Asia:Rapid industrialization and factory automation in countries like Vietnam and Thailand present an underpenetrated market for high-performance vents in machinery and control cabinets.
Industry Challenges
- Performance Validation Complexity:Establishing consistent, real-world performance correlations for airflow, water repellency, and oleophobicity across different testing protocols from IEC and UL is a persistent technical hurdle.
- Membrane Supply Concentration:The poly vent industry depends on a limited number of specialized suppliers for high-performance microporous membranes, creating vulnerability to supply chain disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Poly Vents Market |
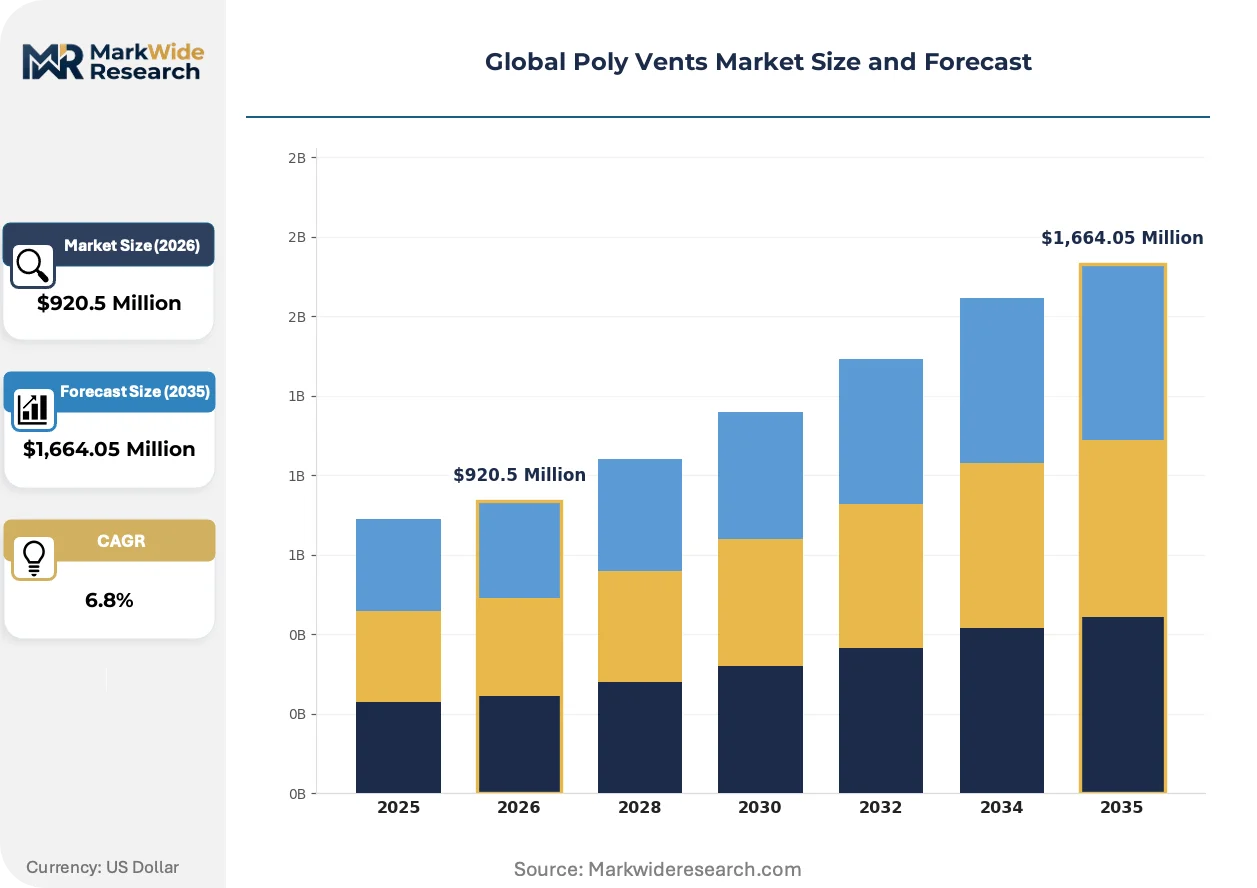
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,664.05 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rectangular Vents, Round Vents, Adjustable Vents, Fixed Vents End User: Commercial Buildings, Residential Homes, Industrial Facilities, Agricultural Applications Installation Type: Wall Mounted, Ceiling Mounted, Floor Mounted, Integrated Systems Material: Polypropylene, Polycarbonate, PVC, Others |
| Companies Covered | W. L. Gore & Associates, Porex Corporation, Interstate Specialty Products, Saint-Gobain, Donaldson Company, Sumitomo Electric Industries, Filtration Group Corporation, Polyglass, Parker Hannifin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Poly Vents Market Strategic Shifts & Innovations
Material science advancements are pushing performance boundaries for specialized applications, while design innovations focus on simplifying integration into ever-smaller electronic devices. These parallel developments address the market's fundamental split between high-performance and high-volume segments.
Adhesive-backed vents incorporating ePTFE membranes are a key product evolution. Designers of compact consumer electronics, medical wearables, and portable sensors are rapidly adopting these components. This technology is miniaturizing the entire protective vent, enabling its integration into devices with extremely limited internal space and complex surface geometries.
Europe's REACH regulation is a significant policy driver shaping material selection. This framework compels manufacturers to verify and declare the chemical composition of all components, including polymer housings and membranes. The automotive electronics sector is particularly impacted, investing heavily in supply chain audits to ensure full compliance for continued access to the EU market.
A distinct behavioral shift is the prioritization of vents with pre-validated IP ratings during the component selection process. This disrupts the traditional model of engineers specifying components based on material data sheets alone, favoring suppliers who offer system-level certification. This preference is most pronounced within the industrial automation and LED lighting sectors in North America.
Global Poly Vents Market Segmentation
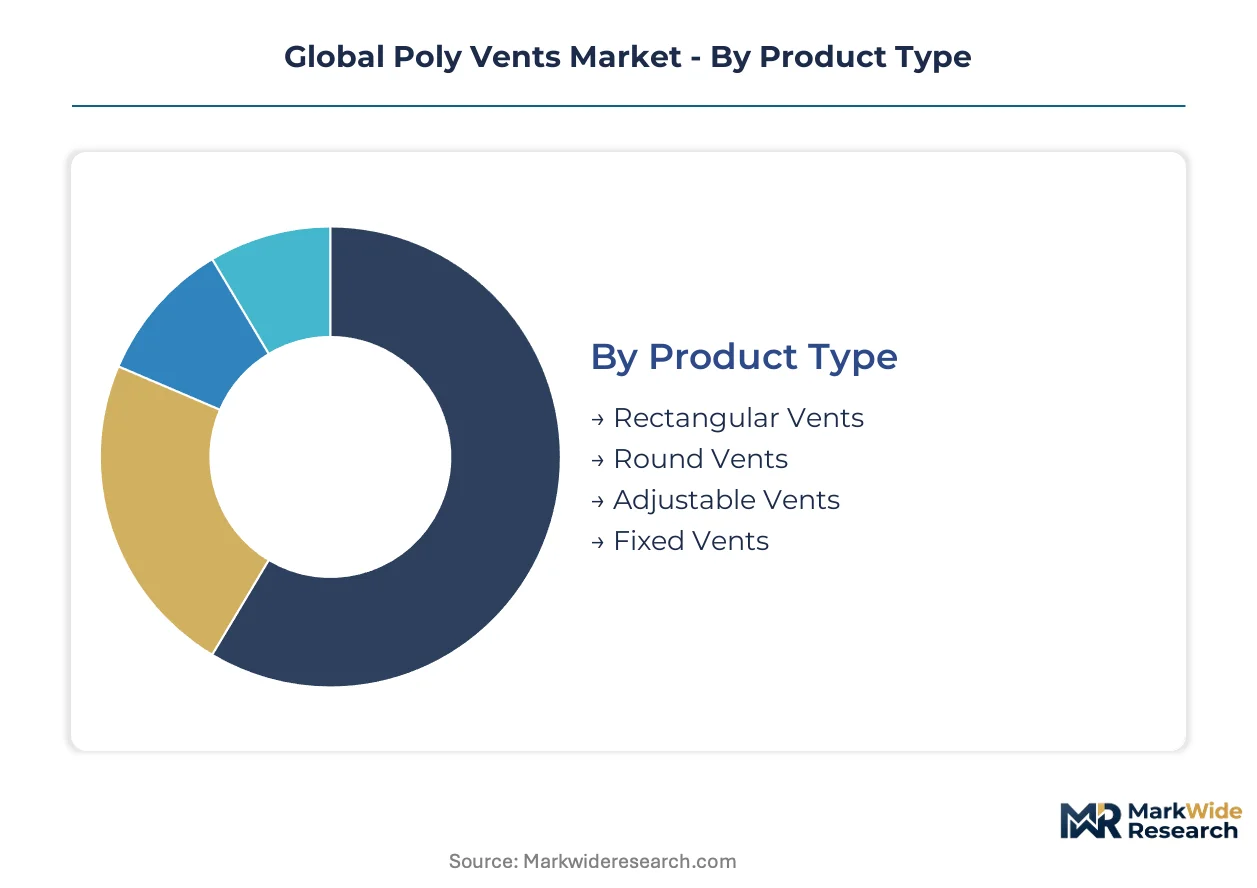
The poly vents market diversifies across various product forms, end-user applications, installation methods, and material compositions. Understanding these distinct segments is crucial for identifying specific demand drivers, technological requirements, and competitive landscapes. Each segment presents unique challenges and opportunities for manufacturers and suppliers.
Product Type:
Product type segmentation reveals how different vent designs cater to specific functional needs and geographic market preferences, influencing export versus domestic production dynamics.
- Rectangular Vents:These components typically feature a broad, flat profile, often integrated into larger panels or enclosures for industrial machinery and control cabinets. Demand for rectangular vents is high in German manufacturing and Japanese automation sectors, driven by standardized equipment designs and robust environmental protection requirements.
- Round Vents:Characterized by their circular shape, round vents are prevalent in both residential and commercial HVAC systems, as well as some electronic enclosures. Their ease of installation and common sizing make them a staple in construction projects across the United States and India.
- Adjustable Vents:These vents offer variable airflow control, adapting to changing environmental conditions. They are utilized in specialized laboratory equipment and climate-controlled storage facilities.
- Fixed Vents:Fixed vents provide continuous, unregulated airflow for constant pressure equalization. Their simplicity and cost-effectiveness suit high-volume consumer electronics and outdoor lighting.
Fixed Vents holds the largest share; momentum sits with Adjustable Vents.
End User:
End-user segments diverge significantly based on the complexity and criticality of their application requirements, influencing material selection and performance specifications.
- Industrial Facilities:This segment demands high-performance, durable vents capable of withstanding harsh operating conditions, chemical exposure, and extreme temperatures. Applications range from heavy machinery in Brazilian mining operations to control cabinets in German automotive plants, requiring stringent IP ratings.
- Residential Homes:Poly vents in residential settings primarily serve general ventilation and moisture control in areas like attics, crawl spaces, and bathrooms. This segment prioritizes cost-effectiveness and ease of installation, driving demand for commoditized polypropylene and PVC solutions in markets like the United States and India.
- Commercial Buildings:Vents manage airflow in commercial HVAC systems and data centers. Compliance with local building codes, such as those in France, dictates material and design choices.
- Agricultural Applications:Vents control climate in greenhouses and livestock facilities. Durability against dust and humidity is paramount for operations in Canadian farmlands or Australian agriculture.
The volume base resides within Residential Homes, while Industrial Facilities drives innovation.
Installation Type:
Customer preferences for installation methods vary significantly across different project scales and aesthetic considerations, influencing product design and integration complexity.
- Wall Mounted:These vents are affixed directly to vertical surfaces, offering straightforward installation and easy access for maintenance. They are widely adopted in both residential and light commercial settings, particularly in renovation projects across the United Kingdom and Japan.
- Integrated Systems:These vents are designed as integral components of larger assemblies, such as electronic enclosures, battery packs, or specialized machinery. Their seamless integration is critical for maintaining device aesthetics and performance, common in German automotive and Chinese electronics manufacturing.
- Ceiling Mounted:Used for exhaust or supply air in HVAC systems, ceiling-mounted vents distribute air efficiently. They are common in office buildings and public spaces.
- Floor Mounted:Essential for raised floor systems in data centers or underfloor heating, these vents manage specific airflow. They require robust construction to withstand foot traffic.
Traditional installations are dominated by Wall Mounted, with Integrated Systems gaining traction for advanced applications.
Material:
Material selection involves distinct trade-offs between cost efficiency, durability, and specific performance attributes, directly impacting application scope and market positioning.
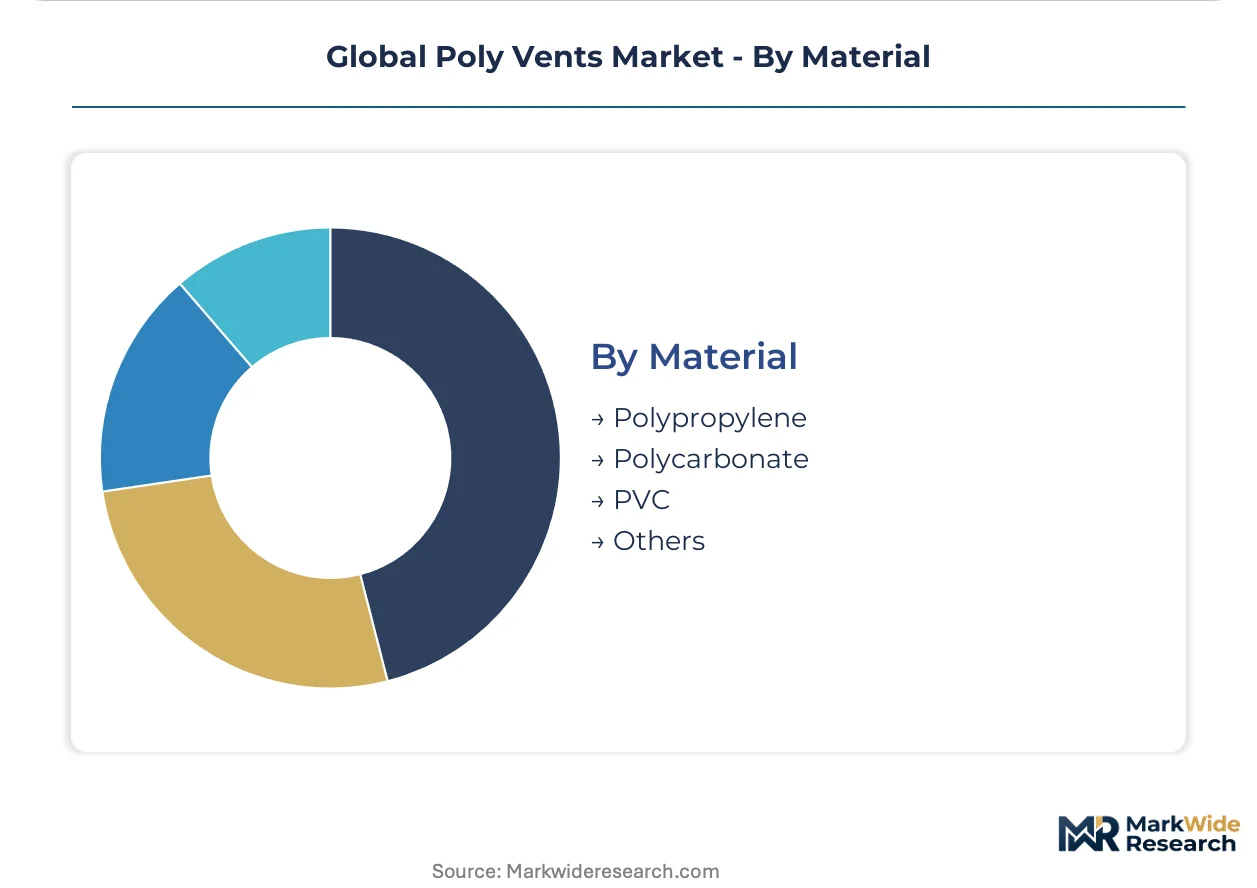
- Polypropylene:Valued for its excellent chemical resistance, low cost, and good mechanical properties, polypropylene is a staple in high-volume, general-purpose venting applications. It dominates residential construction projects and basic industrial enclosures across emerging markets like Vietnam and Mexico.
- Polycarbonate:This material offers superior impact resistance, high heat deflection temperature, and optical clarity, making it suitable for demanding industrial and electronic applications. Polycarbonate vents protect sensitive components in outdoor IoT devices and LED lighting fixtures in North America and South Korea.
- PVC:Polyvinyl chloride is favored for cost-effectiveness, weather resistance, and ease of fabrication. It is widely used in residential and commercial HVAC systems.
- Others:This category includes specialized polymers like ePTFE for microporous membranes and other engineering plastics. These materials serve niche markets requiring extreme chemical inertness or temperature resistance.
Cost-effectiveness drives demand for Polypropylene, whereas Polycarbonate addresses demanding performance envelopes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The manufacturing and consumption of poly vents are heavily concentrated in electronics production hubs, particularly within China. This concentration shapes global supply chains and procurement strategies for specialized venting solutions. Demand drivers vary significantly across different industrial applications and regional regulatory landscapes.
China
The manufacturing and consumption of poly vents are heavily concentrated in electronics production hubs. Demand from electronics assembly and EV battery production creates a direct pull for venting solutions. GB standards regulate component safety and performance for these devices. The Pearl River Delta region leads global electronics manufacturing and vent integration.
United States
Widespread adoption of IEC IP ratings drives demand for certified vents in electronic devices. UL standards are critical for market access, ensuring component safety in electronic devices. Silicon Valley and other tech hubs integrate advanced venting solutions into IoT and consumer electronics.
Germany
High-performance vents are essential for industrial machinery and advanced automotive electronics manufacturing. CE marking requirements ensure compliance for market entry across the European Union. Bavaria and Baden-Württemberg host advanced manufacturing facilities requiring robust venting for sensitive equipment.
Japan
Precision engineering and automation sectors require specialized poly vents for sensitive equipment and robotics. JIS standards influence material selection and performance validation for industrial components. Tokyo and Osaka's industrial clusters drive innovation in compact and integrated venting systems.
South Korea
The electronics sector, including displays and mobile devices, creates demand for miniaturized vents with high IP ratings. MFDS regulations apply to medical devices incorporating venting technology, ensuring patient safety. Gyeonggi Province's tech companies focus on high-performance vents for advanced consumer electronics.
Global Poly Vents Market Key Industry Players
Concentration sits with specialized material science companies providing high-performance solutions, alongside broader industrial conglomerates. The market exhibits a tiered structure, with a distinct divide between high-volume, commoditized vent producers and innovation-driven specialists. Strategic archetypes include membrane technology leaders, diversified industrial component suppliers, and regional fabricators. Competitive moves focus on portfolio diversification into adjacent industrial applications and securing intellectual property for advanced membrane technologies.
Within the high-performance segment, W. L. Gore & Associates exemplifies expertise in microporous membrane technology, particularly ePTFE, serving demanding electronics and automotive clients globally. Donaldson Company occupies a position as a specialist in filtration solutions for heavy-duty industrial equipment, leveraging its core capabilities in industrial venting. Parker Hannifin represents a diversified industrial component supplier, offering a broad portfolio of fluid and gas handling systems that incorporate poly vents. These entities collectively anchor innovation in advanced material science and application-specific engineering, driving performance standards for critical industrial and electronic applications.
| Leading Market Players |
|---|
| W. L. Gore & Associates |
| Porex Corporation |
| Interstate Specialty Products |
| Saint-Gobain |
| Donaldson Company |
| Sumitomo Electric Industries |
| Filtration Group Corporation |
| Polyglass |
| Parker Hannifin |
Cost & Logistics Intelligence
Long-term contract agreements for specialized poly vents lock in supply access and provide price visibility for industrial clients. This structure mitigates volatility from commodity polymer markets and ensures consistent component delivery for critical applications.
Pricing Analysis
IEC Ingress Protection (IP) ratings dictate the pricing tier structure for poly vents, differentiating solutions based on certified performance levels. Pricing stratifies across premium ePTFE-based vents for electronics, standard polycarbonate for industrial uses, and economy polypropylene for residential construction. Pricing softness reflects intense competition in commoditized segments, particularly for basic residential applications. Industrial facilities, demanding stringent IP ratings, exhibit the lowest price sensitivity, prioritizing validated performance over cost.
Supply Chain Analysis
Inventory management for high-performance poly vents often involves longer lead times due to specialized membrane production, particularly for ePTFE materials. Geographic supply concentration centers on China for electronics assembly, Germany for industrial machinery, and Japan for automation components. The industry relies on a limited number of specialized suppliers for microporous membranes, creating vulnerability to single-source disruptions. Downstream distribution typically occurs through direct sales to original equipment manufacturers and specialized industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The poly vents market offers a defensive moat due to regulatory entrenchment, with specific IEC IP ratings acting as critical barriers to market access for electronic devices.
For Market Incumbents:Secure intellectual property for advanced membrane technologies to counter the threat of alternative sealing solutions and maintain performance leadership. Consolidate market share in critical industrial applications by investing in enhanced certification processes, particularly for UL standards in North America. Expand manufacturing capacity in key electronics production hubs like China to optimize supply chain responsiveness. Diversify product portfolios to include sustainable materials, appealing to environmentally conscious industrial clients.
For New Entrants and Emerging Players:Lead with specialized solutions for emerging outdoor Internet of Things (IoT) sensors and 5G telecommunications equipment, targeting underpenetrated markets in Southeast Asia. Focus on niche applications requiring extreme environmental resistance, leveraging material science advancements in polycarbonate. Develop bio-based polymer vents as a distinct go-to-market angle, appealing to corporate sustainability mandates. Offer system-level pre-validation of IP ratings to simplify component selection for industrial automation clients.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among specialized membrane technology providers dueating to their critical role in high-performance poly vents. Long-term viability hinges on continued demand from automotive electrification and industrial automation, supporting steady cash flows. Acquisition targets include mid-sized manufacturers with strong intellectual property in ePTFE or advanced material formulation. The signal to watch is the increasing adoption rate of higher IP standards across new electronic device categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Membrane R&D | This initiative drives performance leadership for demanding electronics and automotive clients. |
| Expand Certified Product Portfolio | This move broadens market access by meeting diverse IEC IP and UL regulatory standards. |
| Localize Production in Southeast Asia | This strategy capitalizes on burgeoning industrial automation demand in countries like Vietnam. |
| Develop Bio-based Polymer Solutions | This action meets corporate sustainability goals for environmentally conscious industrial customers. |
| Acquire Niche Material Science Firms | This secures critical intellectual property for high-performance microporous membrane technology. |
Research Approach
Operator-level perspectives from R&D directors, OEM procurement leads, plant managers, and regulatory compliance officers anchored the qualitative base for this study. Primary interviews with these industry stakeholders were triangulated with extensive secondary validation from IEC standards, UL certifications, customs data, and relevant industry association reports. This approach ensured a robust bottom-up and top-down analysis of market dynamics.
Sensitivity analysis informed the forecast framework, modeling volume and value across the analysis window by product type, end user, installation type, and material. Compound annual growth rates were derived from historical trends and projected demand drivers, including IP rating adoption rates and electric vehicle production forecasts. The quantitative model integrates market sizing with micro-level segment performance.
Forecasts assume regulatory continuity in Europe's REACH framework and US UL standards; material policy shifts would require re-modeling. Potential supply chain disruptions for specialized membranes or rapid shifts in alternative sealing technologies represent key risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Recyclable Thermosets Market
Specialty Materials
Super Engineering Plastics Market
Specialty Materials
Marine Mineral Complexes from Mediterranean Shells Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Global Liquid Crystal Polymer (LCP) Films and Laminates Market
Specialty Materials
Electroactive Polymers (EAP) Market
Specialty Materials
Teschemacherite Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Melamine Foam Market
Specialty Materials
Nanoencapsulation Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market
Specialty Materials
Engineered Quartz Surface Market
Specialty Materials
Carbon Blacks for Non-Rubber Applications Market
Specialty Materials
Polyimide Foam Market