
 Global Lactose Intolerance Treatment Market | 2026-2036
Global Lactose Intolerance Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lactose Intolerance Treatment Market Intelligence
Subscription-based replenishment programs for lactase supplements is restructuring how consumers access treatment, shifting one-time pharmacy purchases into recurring digital relationships. Johnson & Johnson leverages its retail pharmacy network to anchor distribution in North American drugstore channels. Nestlé Health Science competes through specialized metabolic health platforms that integrate dietary management with direct-to-consumer delivery. Abbott Laboratories differentiates via clinical nutrition credibility built on decades of hospital formulary relationships.
Lactose intolerance treatment encompasses enzyme replacement therapies, microbial interventions, and modified food matrices designed to hydrolyze lactose or colonize the gut with lactase-producing bacteria, typically requiring activity thresholds above 3,000 FCC units per dose for clinical efficacy. The primary commercial purpose centers on enabling dairy consumption without gastrointestinal distress while preserving calcium and vitamin D intake pathways. Lactase Supplements command the largest revenue pool due to immediate symptom relief and over-the-counter accessibility, while Probiotic Supplements represent the fastest-growing category as sustained microbiome modulation gains clinical traction. Online Retailers occupy an expanding margin channel by collapsing traditional pharmacy markups through direct manufacturer relationships.
FDA oversight of dietary supplement Good Manufacturing Practices and EMA guidance on enzyme stability claims shape product development timelines and cross-border market access requirements for manufacturers. The EU Green Deal's sustainable packaging mandates and REACH chemical compliance protocols add layer costs for European market entry. Stakeholders must monitor evolving probiotic strain-specific health claim regulations in major jurisdictions to anticipate which product formats will retain competitive shelf positioning.
Market Dynamics
Subscription-based replenishment programs for lactase supplements are restructuring how consumers access treatment, shifting one-time pharmacy purchases into recurring digital relationships anchored by direct manufacturer channels.
Growth Catalysts
- Pediatric nutrition program expansion:School-based dairy fortification initiatives in Japan and South Korea are normalizing enzyme supplementation among children, creating early habitual usage patterns.
- FDA enzyme stability guidance:Clarified labeling requirements for lactase activity thresholds above 3,000 FCC units are reducing consumer confusion and accelerating over-the-counter trial rates.
- East Asian demand concentration:Population-level lactase non-persistence rates exceeding 90% in China and Mongolia are concentrating volume in specialized metabolic health platforms.
Market Restraints
- Enzyme input cost volatility:Fermentation-derived lactase production depends on yeast strain availability and carbohydrate feedstock pricing, creating margin pressure for contract manufacturers.
- EU Green Deal packaging mandates:Sustainable material requirements for blister packs and bottles are adding layer costs without immediate consumer willingness to absorb premiums.
- Plant-based dairy substitution:Oat, almond, and soy milk alternatives are displacing lactose-free dairy processing demand in North American and European retail channels.
Strategic Opportunities
- Underpenetrated Southeast Asian markets:Indonesia, Vietnam, and the Philippines exhibit high lactase non-persistence prevalence with minimal enzyme supplement penetration, offering first-mover positioning.
- Microbiome modulation convergence:Combining lactase-producing probiotic strains with immediate-release enzyme formulations is unifying acute symptom relief and sustained gut colonization benefits.
- Direct-to-consumer channel innovation:Telehealth-integrated prescription workflows for high-potency lactase are bypassing traditional pharmacy distribution in Germany and Switzerland.
Industry Challenges
- Probiotic strain-specific claim compliance:EFSA and FDA divergence on microbiome health claim substantiation is forcing dual regulatory track development for multinational product portfolios.
- Cold chain integrity for live cultures:Temperature-sensitive probiotic formulations require specialized logistics infrastructure that conflicts with cost-efficient e-commerce fulfillment models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lactose Intolerance Treatment Market |
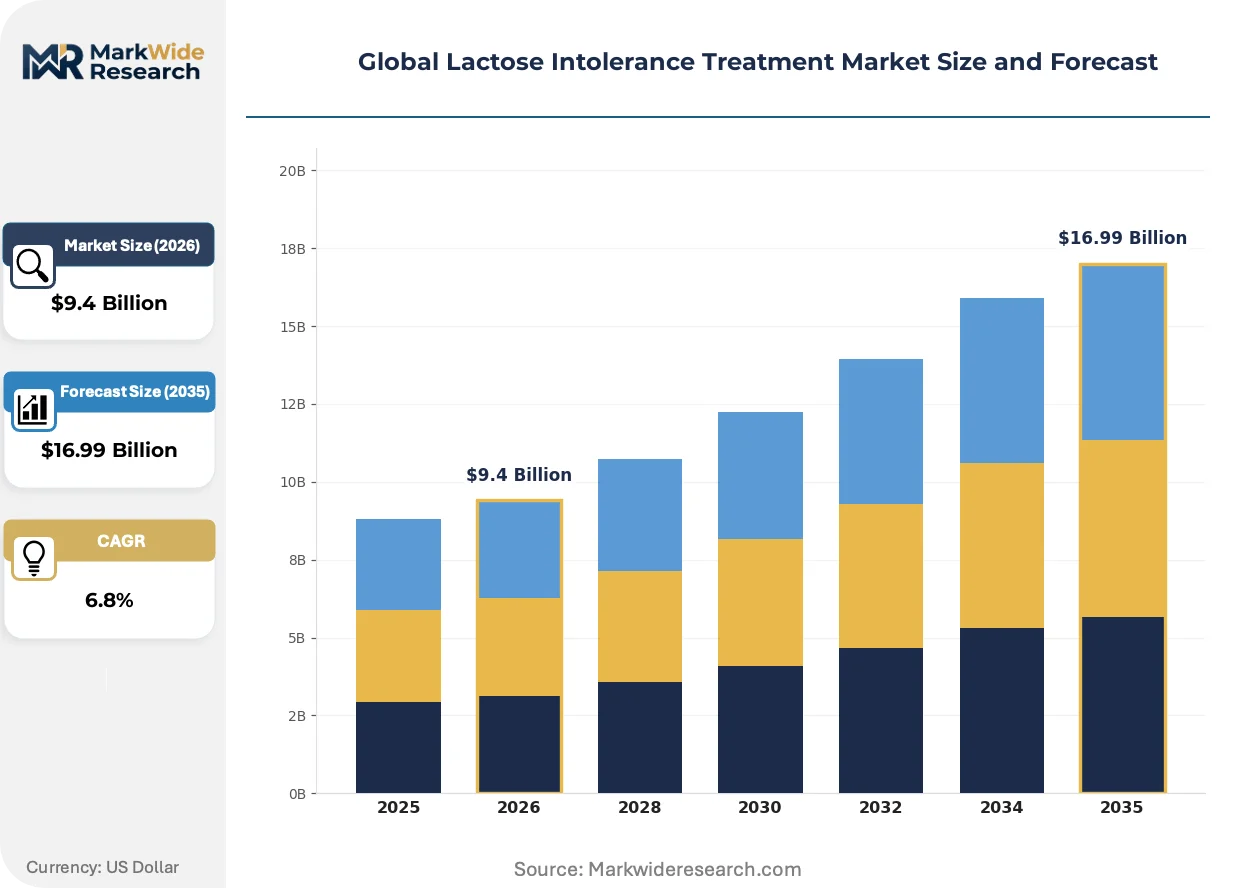
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactase Supplements, Probiotic Supplements, Digestive Enzymes, Fortified Dairy Products, Herbal Remedies Form: Tablets, Capsules, Powders, Liquids, Chewable Tablets Application: Symptomatic Relief, Dietary Management, Nutritional Supplementation, Preventive Care End User: Pharmacies, Specialty Clinics, Wellness Centers, Online Retailers |
| Companies Covered | Johnson & Johnson, Nestlé Health Science, Abbott Laboratories, Danone, Arla Foods, NOW Foods, Chr. Hansen Holding, Novozymes, Nature’s Way Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lactose Intolerance Treatment Market Strategic Shifts & Innovations
Enzyme engineering and delivery mechanism advances are compressing the functional gap between immediate symptom relief and sustained microbiome adaptation, reshaping how manufacturers position across the treatment spectrum.
Microencapsulated lactase formulations with pH-responsive coatings are unifying gastric protection and intestinal release precision. Pediatric and geriatric patient segments are adopting these formats at accelerating rates due to swallowability improvements. The technology is unifying previously separate immediate-release and sustained-action product categories into single-dose solutions.
EMA guidance on enzyme stability shelf-life claims is forcing manufacturers to invest in real-time stability monitoring systems. Industrial consequence includes extended product development timelines and reformulation costs for legacy SKUs. Probiotic-lactase combination products face the most stringent documentation requirements, with German and French regulators leading enforcement stringency.
Buyer concentration through employer-sponsored wellness programs is displacing individual pharmacy purchasing for lactase supplements. Large self-insured employers in the United States are negotiating direct contracts with enzyme manufacturers, bypassing retail markup structures. This procurement consolidation is most visible in technology and financial services sectors where workforce dairy consumption is culturally embedded.
Global Lactose Intolerance Treatment Market Segmentation
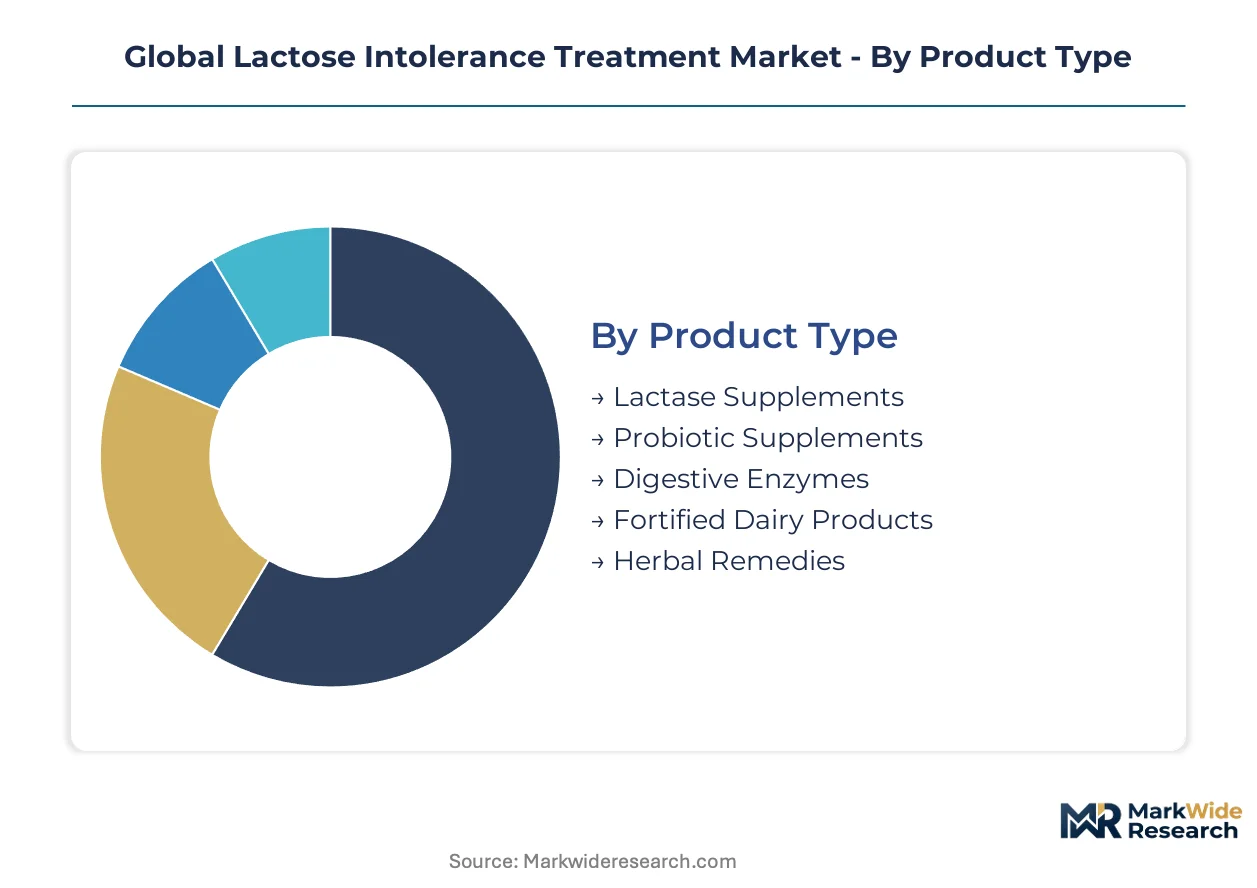
Treatment modality selection in this market hinges on symptom severity, patient age, and dairy consumption patterns. Manufacturers calibrate formulation complexity and dosing precision to match these variables, creating distinct competitive arenas across product architectures.
Product Type:
Standardization dominates at the commodity enzyme tier, while premium positioning requires strain-specific differentiation or multi-mechanism combinations.
- Lactase Supplements:Beta-galactosidase enzymes derived from Kluyveromyces or Aspergillus fermentation deliver immediate lactose hydrolysis at activity thresholds above 3,000 FCC units. Demand concentrates in Japanese and South Korean school nutrition programs where habitual childhood supplementation is displacing adult-onset trial behavior. Enzyme input cost volatility from yeast strain availability constraints compresses margins for contract manufacturers.
- Probiotic Supplements:Lactase-producing bacterial strains including Lactobacillus acidophilus and Bifidobacterium longum colonize the intestinal mucosa for sustained microbiome adaptation. German and Swiss telehealth platforms are integrating these into prescription workflows for patients seeking alternatives to acute enzyme dosing. Cold chain integrity requirements for live cultures conflict with cost-efficient e-commerce fulfillment models.
- Digestive Enzymes:Multi-enzyme complexes combining lactase with lipase and protease address broader maldigestion syndromes beyond isolated lactose intolerance.
- Fortified Dairy Products:Pre-hydrolyzed lactose milk and yogurt formats eliminate consumer compliance barriers through integrated dietary solutions.
- Herbal Remedies:Ginger, fennel, and peppermint-based formulations target symptom masking rather than enzymatic lactose breakdown.
Leading the category by volume: Lactase Supplements. Growing fastest: Probiotic Supplements.
Form:
Patient swallowability and gastric transit timing determine format selection across pediatric, adult, and geriatric populations.
- Tablets:Compressed lactase with standard disintegration profiles dominates pharmacy shelf presence. US employer-sponsored wellness programs negotiate direct manufacturer contracts for bulk tablet procurement, bypassing retail markup structures. pH-responsive coating technologies are unifying immediate-release and sustained-action categories.
- Capsules:Gelatin or hypromelsellose shells protect acid-labile enzymes through gastric transit for intestinal release.
- Powders:Bulk enzyme formulations enable dose titration for variable dairy meal sizes.
- Liquids:Dropper-dosed lactase appeals to infant feeding integration and precise pediatric dosing.
- Chewable Tablets:Flavored, rapid-dissolve formats overcome swallowing barriers in children and elderly patients.
Tablets capture the highest shipment volumes. Chewable formats are climbing the fastest as pediatric segments expand.
Application:
Clinical positioning ranges from reactive symptom management to proactive nutritional assurance.
- Symptomatic Relief:Acute dosing protocols address post-consumption bloating, cramping, and diarrhea through rapid enzyme action. Chinese and Mongolian consumers with population-level lactase non-persistence exceeding 90% drive volume concentration in specialized metabolic health platforms. Plant-based dairy substitution in North American retail channels is displacing some demand for reactive enzyme use.
- Dietary Management:Structured supplementation enables planned dairy consumption while preserving calcium and vitamin D intake pathways.
- Nutritional Supplementation:Integration with pediatric growth protocols and geriatric bone health programs positions enzymes as preventive nutrition tools.
- Preventive Care:Prophylactic dosing before anticipated dairy exposure reduces anxiety-driven avoidance behaviors.
Symptomatic Relief leads by patient volume. Preventive Care shows the steepest expansion trajectory as wellness culture penetrates East Asian markets.
End User:
Channel selection determines margin capture and patient relationship depth.
- Pharmacies:Brick-and-mortar drugstore networks anchor North American distribution through pharmacist counseling and impulse purchase placement. Johnson & Johnson leverages retail pharmacy relationships to maintain shelf dominance. Subscription-based replenishment programs are restructuring one-time purchases into recurring digital relationships.
- Specialty Clinics:Gastroenterology and metabolic disease centers prescribe high-potency formulations with clinical monitoring.
- Wellness Centers:Integrative medicine practices bundle enzyme supplementation with broader dietary intervention protocols.
- Online Retailers:Direct-to-consumer platforms collapse traditional pharmacy markups through manufacturer relationships. Nestlé Health Science and Abbott Laboratories compete through specialized platforms integrating dietary management with home delivery.
Pharmacies retain the largest transaction volume. Online Retailers are gaining share fastest as digital health commerce matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors enzyme manufacturing capacity for East Asian markets, with fermentation facilities supplying lactase to Japanese school nutrition programs and Chinese direct-to-consumer platforms.
United States
Employer-sponsored wellness programs at technology and financial services firms negotiate direct enzyme procurement contracts, bypassing retail pharmacy markups. FDA dietary supplement Good Manufacturing Practices enforcement shapes product development timelines. Boston's biotechnology corridor hosts clinical nutrition research centers advancing microbiome modulation therapies.
Germany
Telehealth-integrated prescription workflows for high-potency lactase bypass traditional pharmacy distribution channels. EMA enzyme stability guidance mandates real-time shelf-life monitoring systems for manufacturers. Frankfurt's pharmaceutical logistics hub manages cold chain distribution for temperature-sensitive probiotic formulations across Central Europe.
Japan
School-based dairy fortification initiatives normalize habitual enzyme supplementation among children, creating early usage patterns that persist into adulthood. METI standards on functional food labeling clarify health claim substantiation requirements. Osaka's fermentation technology cluster supplies beta-galactosidase enzymes to domestic and export markets.
China
Population-level lactase non-persistence rates exceeding 90% concentrate demand in specialized metabolic health platforms and e-commerce channels. National Medical Products Administration oversight of dietary supplement registration creates compliance barriers for imported products. Shanghai's cross-border e-commerce zone facilitates direct-to-consumer enzyme imports from European and North American manufacturers.
Switzerland
Precision nutrition startups integrate lactase supplementation into personalized dietary management protocols. Swissmedic oversight of enzyme stability claims requires extensive documentation for probiotic-lactase combination products. Basel's pharmaceutical research corridor advances microencapsulation technologies for pH-responsive enzyme delivery systems.
Global Lactose Intolerance Treatment Market Key Industry Players
Capital-heavy fermentation producers compete with asset-light brand marketers and specialized distribution platforms across the lactose intolerance treatment landscape. The vendor base spans multinational pharmaceutical conglomerates, dedicated enzyme manufacturers, and emerging direct-to-consumer wellness platforms. Three archetypes dominate: clinical nutrition credibility builders, retail pharmacy network anchors, and microbiome-focused metabolic health specialists. Competitive maneuvering centers on backward integration into fermentation capacity and subscription-based customer relationship models that displace one-time pharmacy purchases.
Among North American pharmaceutical conglomerates, Johnson & Johnson and Abbott Laboratories occupy positions anchored by decades of hospital formulary relationships and retail pharmacy network dominance. Nestlé Health Science exemplifies the metabolic health platform archetype, competing through specialized direct-to-consumer delivery systems that integrate dietary management with home fulfillment. These three entities represent distinct competitive vectors—clinical credibility, retail scale, and digital subscription integration—shaping how enzyme supplementation reaches end consumers across major markets.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Nestlé Health Science |
| Abbott Laboratories |
| Danone |
| Arla Foods |
| NOW Foods |
| Chr. Hansen Holding |
| Novozymes |
| Nature's Way Products |
| Others |
Cost & Logistics Intelligence
Microencapsulation technology adoption is compressing cost differentials between immediate-release and sustained-action lactase formats while concentrating production capability among fermentation specialists with pH-responsive coating expertise. This process innovation simultaneously elevates R&D amortization burdens for new entrants and reinforces pricing power for established manufacturers with captive enzyme engineering capabilities.
Pricing Analysis
Outcome-based pricing anchored to symptom relief duration and FCC unit activity thresholds above 3,000 units dominates premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates microencapsulated pediatric formulations from conventional tablets and bulk powder commodities. Cost compression in the economy tier is intensifying because contract manufacturers face yeast strain availability constraints and carbohydrate feedstock volatility. Employer-sponsored wellness programs exhibit lowest price sensitivity due to direct procurement contracts, while individual pharmacy purchasers in Southeast Asian markets demonstrate highest elasticity.
Supply Chain Analysis
Fermentation-derived lactase supply rests on Danish, Japanese, and German specialty enzyme producers with Kluyveromyces and Aspergillus strain libraries. Raw material dependencies include pharmaceutical-grade yeast cultures, carbohydrate feedstocks, and pH-responsive coating polymers. Single-source vulnerability concentrates in beta-galactosidase master cell banks held by a limited supplier set. Distribution runs through direct-to-consumer platforms, retail pharmacy networks, and hospital formulary channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lactose intolerance treatment sector is transitioning from acute enzyme replacement toward microbiome modulation convergence, with probiotic-lactase combination products displacing standalone supplements in premium positioning.
For Market Incumbents: Anchor fermentation capacity in East Asian markets through backward integration into Osaka and Shanghai biotechnology corridors. Defend against plant-based dairy substitution by embedding enzymes into employer-sponsored wellness programs with multi-year procurement contracts. Prioritize cold chain infrastructure investment to support live culture probiotic distribution. For New Entrants and Emerging Players: Telehealth platforms in Germany and Switzerland offer the most penetrable channel for high-potency lactase prescription workflows. Target Indonesia, Vietnam, and the Philippines with localized e-commerce partnerships addressing minimal enzyme supplement penetration despite high lactase non-persistence prevalence. Pursue microbiome modulation convergence as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in metabolic health platform acquisitions by consumer health conglomerates seeking direct-to-consumer subscription integration. Long-term viability favors manufacturers with strain-specific intellectual property and captive fermentation assets. Watch EFSA-FDA divergence on probiotic health claim substantiation as the inflection signal for dual-track regulatory investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Microbiome Modulation Convergence | Unifies acute lactase relief with sustained gut colonization benefits in single-dose formats. |
| Direct-to-Consumer Channel Expansion | Bypasses retail pharmacy markups through manufacturer-integrated telehealth platforms in German-speaking markets. |
| Cold Chain Infrastructure Investment | Enables live culture probiotic distribution through specialized logistics networks conflicting with standard e-commerce fulfillment. |
| Pediatric Format Development | Captures habitual usage patterns through chewable microencapsulated formulations in Japanese school nutrition programs. |
| Regulatory Dual-Track Preparation | Anticipates EMA-FDA divergence on enzyme stability and probiotic strain claim documentation requirements. |
Research Approach
Independent corroboration across fermentation technology specialists, pediatric nutrition program directors, and hospital formulary managers underwrites the qualitative findings. Primary fieldwork encompassed regulatory affairs leads at enzyme manufacturers, direct-to-consumer platform operators, and cold chain logistics coordinators. Secondary validation drew from FDA dietary supplement GMP enforcement records, EMA enzyme stability guidance documents, METI functional food labeling standards, and NMPA dietary supplement registration databases. Bottom-up volume modeling triangulated against top-down market sizing across treatment modalities.
Historical reference periods anchored the projection horizon through trend extrapolation and driver elasticity analysis. Segmentation dimensions encompassed product type, formulation technology, patient age cohort, distribution channel, and regional regulatory cluster. CAGRs were derived from normalized growth rate distributions across comparable therapeutic categories. Forecast inputs included school nutrition program expansion trajectories, telehealth platform penetration curves, and probiotic strain patent expiration schedules.
Several conditions sit outside the modeled scope, including unforeseen regulatory reclassifications of enzyme supplements as medical devices, catastrophic fermentation facility disruptions, and rapid plant-based dairy substitution acceleration. Forecasts reflect documented assumptions about FDA and EMA guidance stability, East Asian e-commerce regulatory continuity, and employer wellness program budget persistence. A small set of named triggers warrants ongoing watch: EFSA probiotic health claim enforcement stringency, EU Green Deal packaging mandate implementation timelines, and yeast strain patent litigation outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Europe Gluten-Free Oats Market
Food Intolerance Products
France Gluten-Free Food and Beverage Market
Food Intolerance Products
Gluten-Free Popcorn Products Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
Lactose Free Products Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Nut-Free Cookies Market
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market
Food Intolerance Products
Dyspepsia Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
Asia-Pacific Gluten-Free Breakfast Cereals Market
Food Intolerance Products
Sugar Free Food and Beverage Market
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
United States Gluten Free Foods and Beverages Market
Food Intolerance Products
Food Intolerance Products Market