
 North America Free from Food Market | 2026-2036
North America Free from Food Market Size, Share, and Industry Trends Forecast 2026-2036
North America Free from Food Market Analytics
Private-label formulation services is fragmenting across North America as retailers build in-house capabilities and dilute incumbent margins. Conagra Brands Inc. anchors its position through backward integration into dedicated allergen-free production facilities. The Hain Celestial Group differentiates via R&D intensity focused on organic-certified free-from lines. General Mills Inc. leverages its manufacturing scale to occupy shelf space across mainstream supermarkets and club channels.
Free from food comprises formulated products excluding specific allergenic ingredients—gluten, dairy, nuts, or eggs—while maintaining sensory and nutritional parity through modified starch systems, plant protein isolates, and controlled-environment processing. Gluten-Free product lines command the deepest margin pools due to celiac-diagnosed consumers' price inelasticity, while Dairy-Free alternatives capture the fastest growth trajectory as oat and pea protein technologies mature. Health-Conscious Consumers drive volume across Supermarkets and Online Retailers, though Specialty Stores retain outsized influence on trend origination and brand discovery.
The FDA enforces allergen-labeling rules under the Food Allergen Safety, Treatment, Education, and Research Act, compelling manufacturers to validate supply-chain segregation protocols. Health Canada and the Canadian Food Inspection Agency apply parallel strictures through the Safe Food for Canadians Regulations, creating a dual-compliance burden for cross-border suppliers. Stakeholders must monitor evolving state-level transparency laws in California and New York while calibrating procurement to certified ingredient sources that satisfy both jurisdictions.
Market Dynamics
Clean-label mandates from Health Canada and the FDA are compressing formulation timelines while oat-protein extraction advances unlock sensory parity at commercial scale.
Growth Catalysts
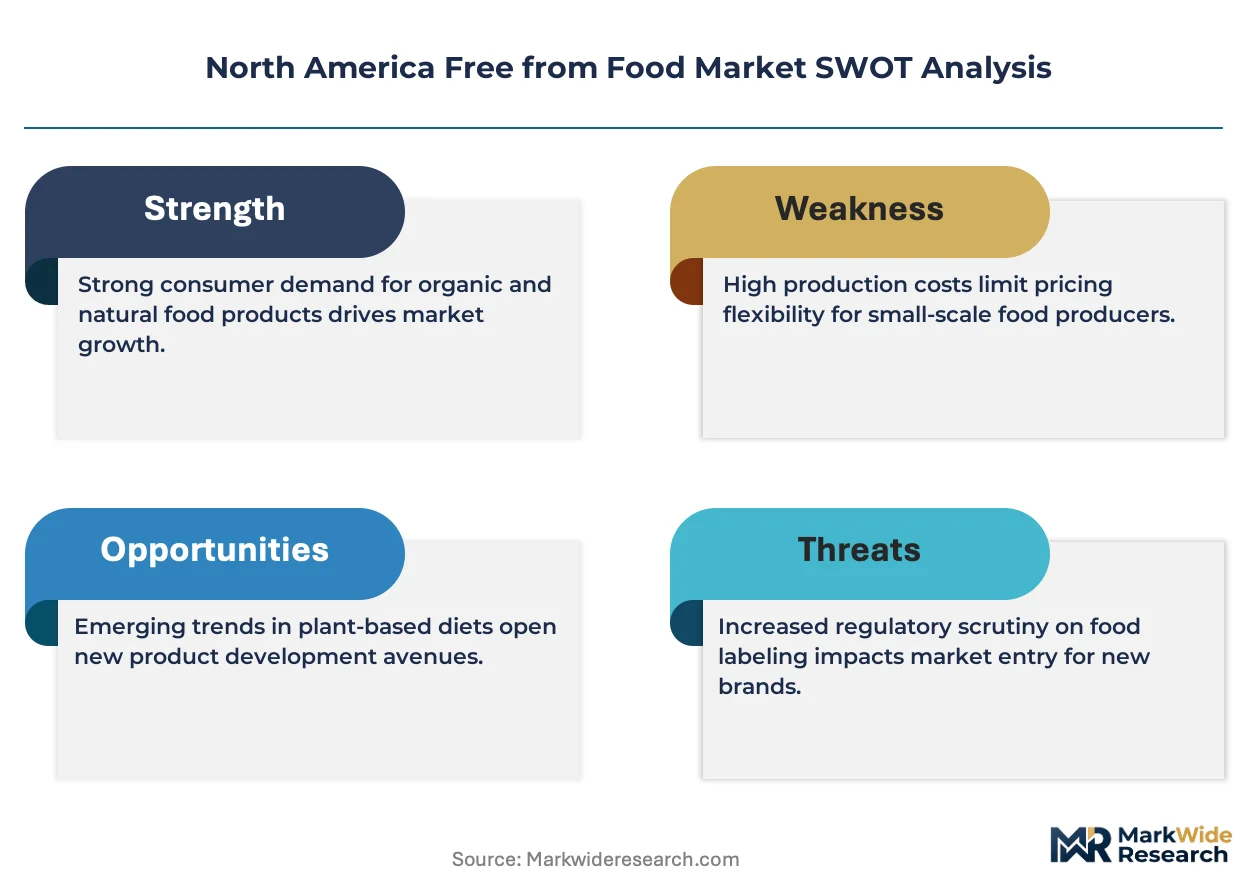
- FDA Food Allergen Safety Act:Mandatory supply-chain segregation protocols compel manufacturers to invest in certified ingredient sourcing, expanding the addressable market for validated free-from suppliers.
- Pea protein isolate technology:Mature extraction methods now deliver functional emulsification properties matching dairy proteins, accelerating Dairy-Free adoption across bakery and beverage applications.
- California innovation corridor:Concentrated venture funding and pilot-scale manufacturing infrastructure draw formulation startups, creating a self-reinforcing cluster of R&D talent and ingredient innovation.
Market Restraints
- Modified starch input volatility:Tapioca and potato starch prices fluctuate with climate-induced harvest variability in Southeast Asian sourcing regions, squeezing margin predictability for gluten-free bakers.
- Controlled-environment processing capex:Dedicated allergen-free production lines require HEPA filtration and positive-airlock systems that amortize poorly below threshold volumes.
- Dual-compliance burden:Cross-border suppliers face divergent Health Canada and FDA validation requirements for the same ingredient certifications, extending time-to-market.
Strategic Opportunities
- Greater Toronto Area retail-distribution nexus:Underpenetrated shelf space in club and discount channels offers first-mover positioning for mid-tier free-from brands seeking volume scale.
- Online Retailers channel innovation:Direct-to-subscription models bypass slotting-fee barriers and capture recurring revenue from diagnosed celiac households with predictable replenishment cycles.
- Organic-certified convergence:Stacking free-from and USDA Organic claims commands price premiums in California and Pacific Northwest markets where dual-attribute purchasing is normative.
Industry Challenges
- Food safety auditor scarcity:Qualified third-party certifiers for gluten-free and allergen-free protocols face backlogs extending validation timelines by four to six months.
- Legacy ERP integration friction:Lot-traceability requirements for FDA compliance collide with outdated inventory systems at mid-sized co-manufacturers, forcing expensive middleware deployments.
- Cross-contamination liability exposure:Precautionary labeling disputes generate litigation risk that outpaces insurance coverage evolution in the specialty food sector.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Free from Food Market |
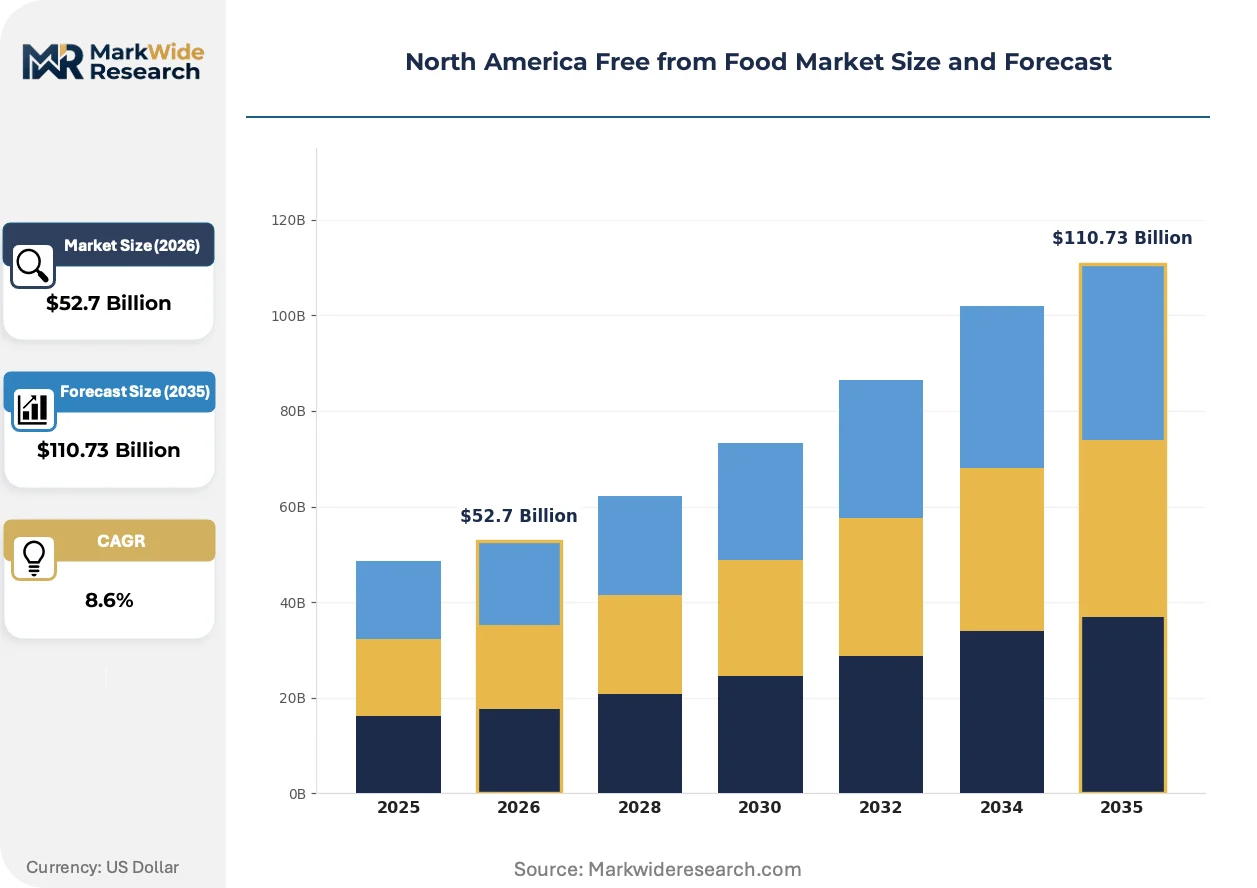
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Dairy-Free, Nut-Free, Egg-Free End User: Health-Conscious Consumers, Allergic Individuals, Diabetics, Fitness Enthusiasts Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Specialty Stores Packaging Type: Bulk Packaging, Single-Serve Packages, Eco-Friendly Packaging, Resealable Bags |
| Companies Covered | Conagra Brands Inc., The Hain Celestial Group, General Mills Inc., Kraft Heinz Company, Danone S.A., PepsiCo Inc., Nestlé S.A., Kellanova, Bob’s Red Mill Natural Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Free from Food Market Evolving Landscape
Blockchain-enabled ingredient provenance and enzymatic modification of plant proteins are compressing the gap between free-from claims and mainstream sensory expectations.
Near-infrared spectroscopy is digitizing real-time allergen detection at production lines. California-based co-manufacturers deploy these systems to validate cleaning protocols between allergen-containing and free-from runs. The technology is digitizing quality-assurance workflows that previously required 24-hour lab hold periods, collapsing batch-release timelines from days to hours.
Health Canada's 2026 front-of-package labeling mandate for priority allergens intensifies disclosure obligations. Manufacturers must redesign packaging graphics to accommodate expanded warning statements. Small-format specialty brands serving the Greater Toronto Area face disproportionate redesign costs relative to revenue base, accelerating private-label absorption.
Subscription-based replenishment is displacing conventional supermarket stocking for diagnosed celiac households. Direct channels capture pantry-automation demand from time-constrained health-conscious consumers in urban California clusters. Specialty Stores retain discovery influence but lose volume share as pantry consolidation shifts toward curated digital bundles.
North America Free from Food Market Segmentation
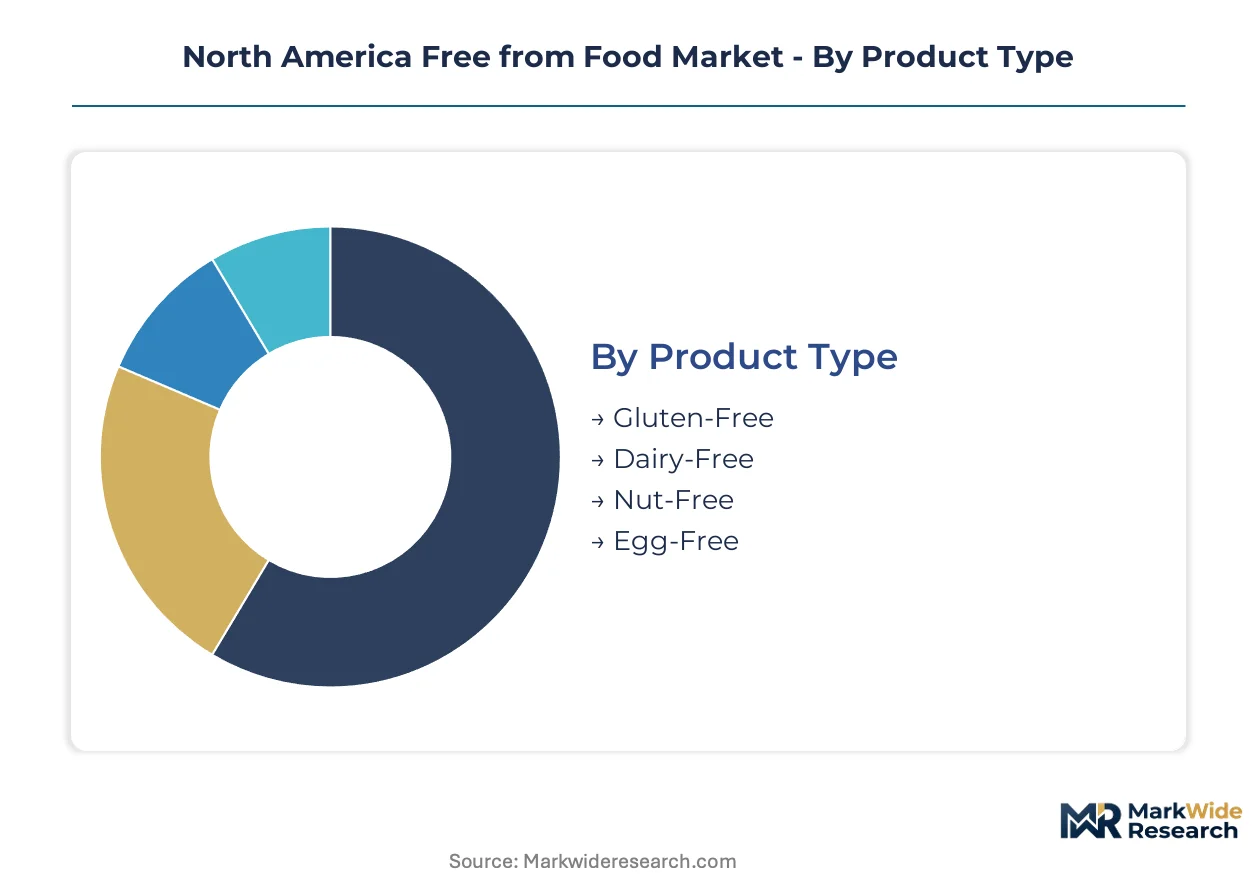
Free from food segmentation reflects divergent consumer motivations and channel economics across North America. Product type stratification separates medically necessitated purchases from lifestyle-driven alternatives, while distribution channel selection determines margin capture and brand positioning.
Product Type:
Mature extraction technologies anchor two segments while enzymatic innovation accelerates the remaining pair.
- Gluten-Free:Formulations rely on modified tapioca and potato starch systems to replicate wheat's viscoelastic properties in baked applications. Celiac-diagnosed households in California's innovation corridor sustain price premiums that subsidize R&D amortization across broader portfolios.
- Dairy-Free:Oat and pea protein isolates now achieve functional emulsification parity with casein and whey in beverage and frozen dessert categories. The segment is climbing the fastest as oat milk processing scales reduce unit costs below almond and soy alternatives.
- Nut-Free:Controlled-environment protocols and sunflower seed butter substitutions address anaphylaxis-risk households with zero-tolerance supply chain requirements.
- Egg-Free:Aquafaba and mung bean protein concentrates replicate foaming and binding functions in bakery and mayonnaise applications.
Gluten-Free handles the majority of throughput; Dairy-Free is the fastest mover on share.
End User:
Customer archetypes span diagnostic necessity to discretionary wellness, reshaping formulation priorities and marketing spend allocation.
- Health-Conscious Consumers:Clean-label preferences drive purchasing decisions beyond allergen exclusion toward ingredient list brevity and processing transparency. This cohort concentrates in urban California clusters and Pacific Northwest metro areas where organic-certified convergence commands normative behavior.
- Allergic Individuals:Medically diagnosed households exhibit extreme price inelasticity and zero-tolerance quality assurance demands, generating recurring revenue stability for validated supply chains.
- Diabetics:Glycemic index management priorities intersect with free-from claims in low-carbohydrate bakery and snack categories.
- Fitness Enthusiasts:Macro-tracking behaviors favor high-protein dairy-free alternatives and egg-free baking mixes supporting meal-prep routines.
Health-Conscious Consumers anchor volume scale; Allergic Individuals generate the highest lifetime value per account.
Distribution Channel:
Channel selection determines slotting-fee exposure, data capture depth, and brand discovery mechanics.
- Supermarkets:Mainstream grocers in the Greater Toronto Area retail-distribution nexus consolidate free-from SKUs into dedicated aisle sets, reducing search friction for diagnosed households. Club channel penetration remains underdeveloped relative to conventional grocery.
- Online Retailers:Direct-to-subscription models bypass slotting-fee barriers and capture predictable replenishment cycles from celiac-diagnosed consumers. California-based fulfillment infrastructure supports same-day delivery expectations.
- Health Food Stores:Staff-curated assortments retain outsized influence on trend origination and early-stage brand discovery.
- Specialty Stores:Independent retailers in urban clusters function as testing grounds for novel ingredient technologies before mainstream rollout.
Supermarkets process the highest absolute volume; Online Retailers is expanding most quickly on share.
Packaging Type:
Format economics intersect with sustainability mandates and consumption occasion fragmentation.
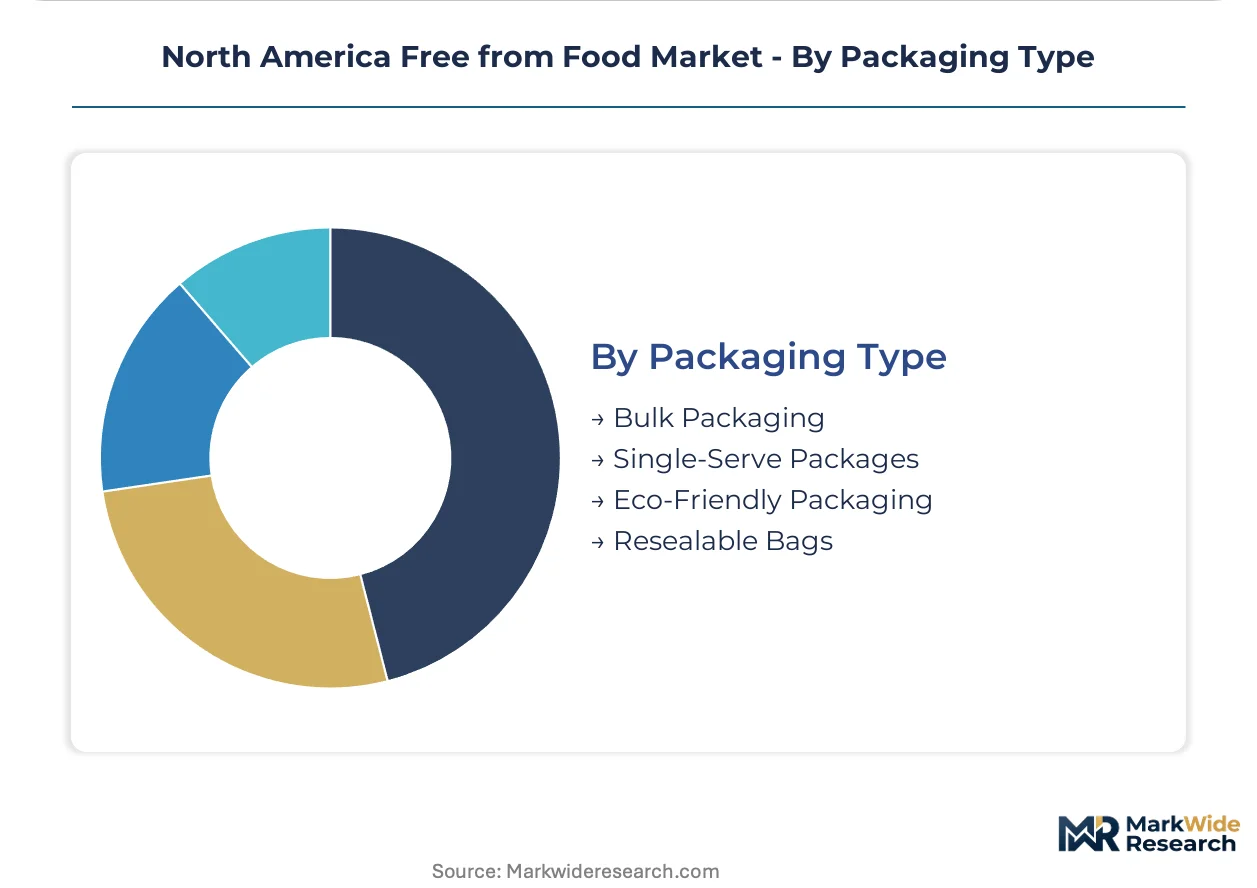
- Bulk Packaging:Foodservice and institutional channels in California's innovation corridor favor cost-efficient formats for ingredient-scale procurement.
- Single-Serve Packages:Portion-controlled formats address on-the-go consumption and cross-contamination anxiety in shared environments.
- Eco-Friendly Packaging:Compostable films and fiber-based structures respond to Pacific Northwest consumer willingness to absorb green premiums.
- Resealable Bags:Extended freshness claims reduce spoilage rates in low-turnover specialty SKUs.
Single-Serve Packages dominate velocity; Eco-Friendly Packaging is gaining share fastest on sustainability premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across North American markets. Celiac-diagnosed households in California accept steep premiums, while Mexican consumers drive volume through accessible price points. Canadian buyers occupy the middle ground, balancing quality validation with cost consciousness.
United States
FDA allergen-labeling enforcement under FASTER Act protocols compels manufacturers to maintain segregated supply chains. California's innovation corridor concentrates venture-backed formulation startups and pilot-scale manufacturing infrastructure. The Pacific Northwest metro clusters generate outsized demand for organic-certified free-from convergence.
Canada
Health Canada's front-of-package labeling mandate intensifies disclosure obligations for priority allergens. The Greater Toronto Area functions as the regional retail-distribution nexus with underpenetrated club-channel shelf space. Cross-border suppliers face dual-compliance validation requirements extending time-to-market timelines.
Mexico
Expanding middle-class health consciousness accelerates dairy-free and gluten-free adoption in urban centers. COFEPRIS alignment with international Codex standards facilitates ingredient import flows from US suppliers. Mexico City Metro and Guadalajara clusters concentrate modern trade expansion for specialty food distribution.
North America Free from Food Market Competitive Landscape
Vertically integrated multinationals and specialty pure-plays split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: diversified food conglomerates with captive allergen-free production lines, organic-certified specialists with R&D-intensive formulation pipelines, and private-label service providers facing margin compression from retailer in-house buildouts. Competitive moves cluster on backward integration into dedicated facilities and portfolio diversification across multiple free-from claim categories.
Within the diversified conglomerate tier, Conagra Brands Inc. and General Mills Inc. exemplify scale-driven positioning through manufacturing footprint and mainstream channel penetration. The Hain Celestial Group occupies the organic-certified specialist position, anchoring R&D intensity focused on dual-attribute product development. These three entities collectively represent the competitive spectrum spanning mass-market volume capture to premium-tier claim stacking.
| Leading Market Players |
|---|
| Conagra Brands Inc. |
| The Hain Celestial Group |
| General Mills Inc. |
| Kraft Heinz Company |
| Danone S.A. |
| PepsiCo Inc. |
| Nestlé S.A. |
| Kellanova |
| Bob's Red Mill Natural Foods Inc. |
| Others |
Value Network & Pricing Analysis
The I-5 freight corridor linking California's innovation corridor to Pacific Northwest distribution hubs concentrates inbound ingredient flows and outbound finished goods, with fuel surcharge volatility transmitting directly into gluten-free starch system costs and downstream shelf-price differentiation between club-channel economy tiers and specialty-store premium positioning.
Pricing Analysis
After-sales subscription revenue from direct-to-celiac-household replenishment programs drives lifetime value capture beyond initial basket transactions. Three-tier pricing structure across premium organic-certified, standard mass-market, and economy private-label levels segments buyers by certification intensity and channel format. Cost compression in the economy tier is intensifying as retailer in-house formulation capabilities erode incumbent co-manufacturer margins. Allergic Individuals exhibit the lowest price sensitivity due to zero-tolerance quality requirements, while Health-Conscious lifestyle buyers in urban California clusters absorb moderate premiums for clean-label convergence.
Supply Chain Analysis
Tariff exposure between the United States and Southeast Asian tapioca starch sourcing regions dominates margin risk planning for gluten-free bakers. Ingredient procurement draws from Thailand, Vietnam, and Indonesia for modified starch systems, while Canadian prairie provinces supply pea protein isolates and oat processing inputs. Single-source vulnerability concentrates in HEPA filtration equipment for controlled-environment production lines, with limited qualified vendors extending lead times. Distribution runs through the Greater Toronto Area retail-distribution nexus for Canadian market penetration, with California fulfillment infrastructure anchoring direct-to-consumer subscription flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from retailer private-label buildouts that replicate validated allergen-free claims at 20-30% price discounts, compressing brand equity premiums and forcing portfolio repositioning toward defensible certification tiers.
For Market Incumbents: Entrench supply security through backward integration into dedicated allergen-free production facilities in California's innovation corridor, mirroring Conagra Brands Inc.'s captive facility strategy. Lock in multi-year contracts with Health Canada-certified third-party auditors to preempt validation backlog delays that threaten batch-release timelines. Prioritize R&D investment in enzymatic plant protein modification to maintain sensory parity distance from emerging oat-protein competitors.
For New Entrants and Emerging Players: Build out direct-to-subscription fulfillment capabilities targeting diagnosed celiac households in underpenetrated Mexican urban centers, where COFEPRIS alignment with Codex standards simplifies US ingredient import protocols. Exploit club-channel shelf space gaps in the Greater Toronto Area retail-distribution nexus before incumbent diversification reaches those formats. Lead with organic-certified free-from convergence to capture Pacific Northwest consumer willingness to absorb dual-attribute premiums.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates seeking to divest non-core specialty portfolios amid margin compression from retailer in-house capabilities. Mid-tier free-from brands with validated Health Canada and FDA dual-compliance infrastructure offer 5-10 year viability as cross-border supply chain complexity persists. Monitor FDA enforcement action intensity against precautionary labeling disputes as an inflection signal for litigation risk repricing in the specialty food sector.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Allergen-Free Production | Captive facilities in California bypass co-manufacturer queue bottlenecks and protect margin from retailer private-label erosion. |
| Dual-Certification Compliance Investment | Parallel Health Canada and FDA validation protocols extend competitive moats for cross-border suppliers against single-jurisdiction competitors. |
| Direct-to-Subscription Channel Launch | Pantry-automation models bypass supermarket slotting fees and lock in recurring revenue from celiac-diagnosed households. |
| Organic-Certified Convergence R&D | Stacking USDA Organic with free-from claims commands price premiums in Pacific Northwest markets where dual-attribute purchasing is normative. |
| Blockchain Ingredient Provenance Deployment | Real-time allergen detection systems collapse batch-release timelines from days to hours, accelerating inventory velocity. |
Research Methodology
Cross-validation between primary interviews with category buyers at major supermarket chains and secondary analysis of FDA enforcement letters anchors the qualitative findings on compliance burden evolution. The research program combined structured discussions with formulation R&D directors, supply chain managers at starch ingredient suppliers, third-party food safety auditors, and e-commerce fulfillment operators with validation against Health Canada regulatory guidance documents, SEC 10-K filings from diversified food conglomerates, Nielsen retail audit data for free-from SKU velocity, and customs records tracking tapioca starch import flows. Bottom-up SKU-level demand modeling and top-down market sizing triangulated volume estimates across product type and channel segments.
Calibration against historical growth trajectories in adjacent clean-label categories informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type stratification, end-user diagnostic necessity versus lifestyle motivation, distribution channel format economics, and geographic regulatory cluster intensity. CAGRs were derived from weighted scenario analysis incorporating oat-protein extraction cost curves and controlled-environment processing capacity expansion timelines. Industry-specific forecast inputs encompassed Health Canada's front-of-package labeling mandate implementation pace and California venture funding flows into formulation startups.
Stress conditions across modified starch input price volatility, FDA auditor backlog duration, and retailer private-label absorption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on pea protein isolate functional parity achievement and dual-compliance validation timeline standardization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
Sugar Free Food and Beverage Market
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Global Gluten-Free Ready Meals Market
Food Intolerance Products
Fermented Garlic and Onion Digestive Comfort Bases Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market
Food Intolerance Products
Gluten-Free Pasta Market
Food Intolerance Products
Food Allergy and Intolerance Products Market
Food Intolerance Products
Argentina Gluten-Free Food and Beverage Market
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
Allergen Free Food Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
Low GI Food Market
Food Intolerance Products
Egg Allergy Market
Food Intolerance Products
Citrus-Derived Gastrointestinal Comfort Blends Market
Food Intolerance Products
Gluten Free Food Market