
 Nut-Free Cookies Market | 2026-2036
Nut-Free Cookies Market Size, Share, and Industry Trends Forecast 2026-2036
Nut-Free Cookies Market Intelligence
The traditional distinction between generalist bakers and specialized food scientists trained in allergen-free protocols is collapsing under new production pressures. Global food giant Mondelēz International leverages its vast distribution network to introduce nut-free options within its established brands. In contrast, specialist player Homefree differentiates entirely on its dedicated nut-free facility and brand promise, targeting consumers with severe allergies. Conagra Brands also competes by reformulating popular snack products to meet nut-free standards.
Nut-free cookies are baked goods specifically formulated without peanuts or tree nuts as ingredients. Production requires stringent manufacturing protocols, often involving dedicated facilities or segregated production lines to eliminate cross-contamination risks and meet allergen-free certification standards. Sales through supermarkets and health food stores command the largest share, while online retail represents the fastest-growing distribution channel. Among end users, the households segment remains dominant, but demand from schools is accelerating due to strict allergy management policies.
Regulatory frameworks are central to market access and consumer confidence. In the United States, the FDA's Food Allergen Labeling and Consumer Protection Act sets strict labeling rules, while the European Food Safety Authority provides scientific advice underpinning similar EU regulations. These rules force transparent ingredient disclosure and cross-contamination warnings. Stakeholders must now decide how to invest in verifiable supply chain segregation to support increasingly stringent 'free-from' claims and certifications.
Market Dynamics
The central dynamic shaping the nut-free cookies market is the strategic divergence between mass-market players reformulating existing products and specialist brands built entirely on dedicated, allergen-free production. This split is driven by consumer trust issues surrounding cross-contamination and tightening regulatory definitions of "free-from" claims.
Growth Catalysts
- Regulatory Mandates:Stricter allergen disclosure rules, including the FDA's Food Allergen Labeling and Consumer Protection Act and guidance from Europe's EFSA, compel transparent labeling that builds consumer confidence and expands the addressable market.
- Institutional Procurement:Demand from the schools segment is accelerating as districts in the United States, Canada, and parts of Europe implement stringent allergy policies, creating large-volume purchasing contracts for certified safe products.
- Ingredient Science:Innovations in alternative flours derived from sources like chickpeas, sunflower seeds, and oats provide manufacturers with new tools to improve the taste, texture, and nutritional profile of nut-free cookies, closing the gap with traditional recipes.
Market Restraints
- Cost Structure Inflation:The requirement for segregated production lines or dedicated facilities, coupled with the higher price of certified nut-free ingredients, imposes significant cost burdens that limit price competitiveness against conventional cookies.
- Supply Chain Verification:Ensuring that every ingredient, from chocolate chips to flavorings, is free from nut cross-contamination throughout its entire supply chain is a complex and resource-intensive process for manufacturers.
- Sensory Profile Challenges:Replicating the specific textural properties and flavor contributions of nut-based butters and flours remains a significant food science challenge, sometimes resulting in products that consumers find less appealing than traditional counterparts.
Strategic Opportunities
- Geographic Expansion:Producers can target markets with rising disposable incomes and growing allergy awareness, such as urban centers in Brazil and South Korea, where the "free-from" food trend is gaining traction.
- Channel Diversification:Developing direct-to-consumer subscription services allows brands to build loyalty with households managing severe allergies, offering them exclusive access to new products and reliable, cross-contamination-free delivery.
- Product Adjacencies:Leveraging brand trust established in nut-free cookies to expand into adjacent categories like allergen-free baking mixes, snack bars, and breakfast pastries creates new revenue streams from a captive consumer base.
Industry Challenges
- Certification and Compliance:The operational burden and expense of securing and maintaining multiple third-party certifications, such as those for nut-free, gluten-free, and non-GMO status, create barriers to entry for smaller companies.
- Specialized Talent Scarcity:A shortage of food scientists and quality assurance managers with deep expertise in allergen management protocols and segregated manufacturing environments constrains the ability of producers to scale up production safely.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nut-Free Cookies Market |
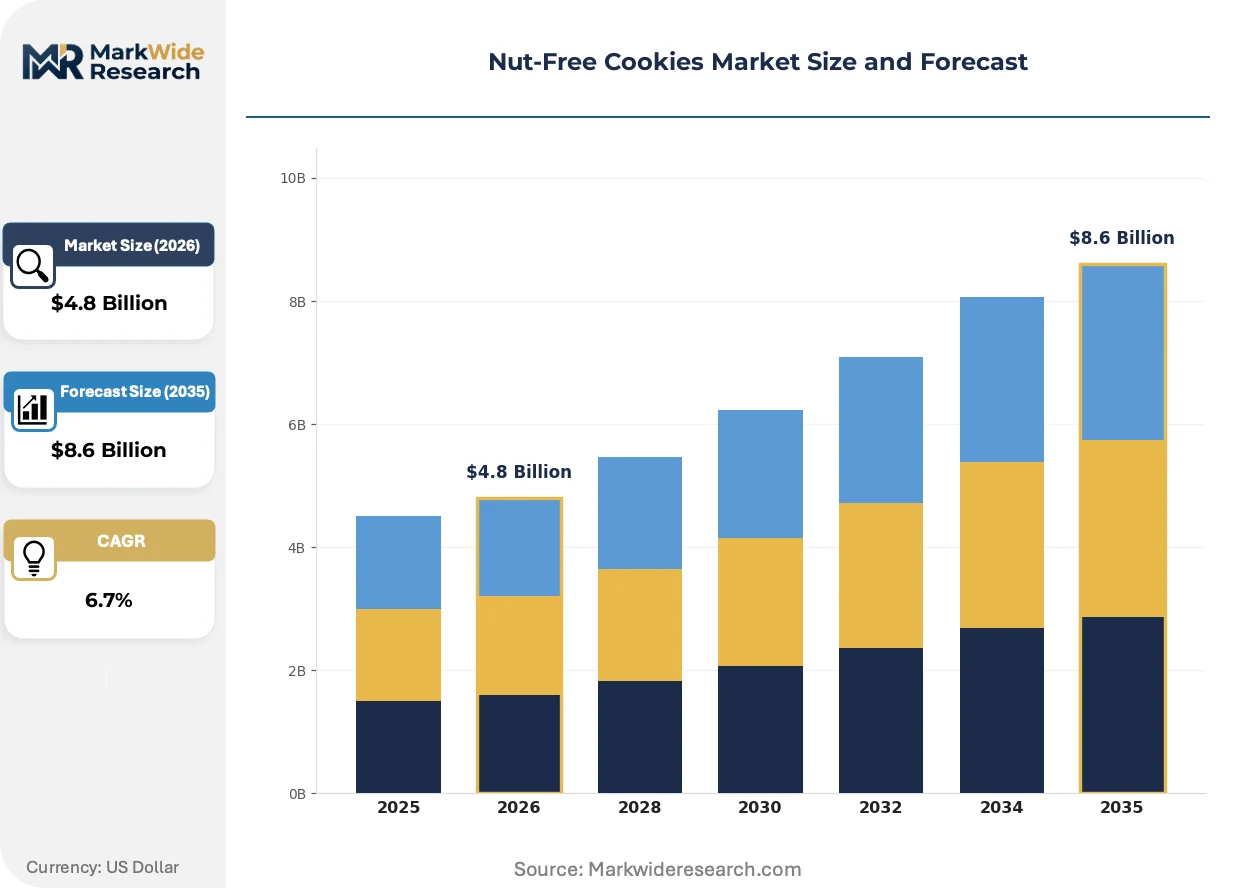
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Chip, Oatmeal Raisin, Sugar Cookies, Snickerdoodle End User: Households, Cafes, Bakeries, Schools Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Packaging Type: Boxes, Bags, Bulk, Trays |
| Companies Covered | Mondelēz International, Conagra Brands, Nestlé, Homefree, Rich Products Corporation, Divvies, Skeeter Snacks, Not a Trace, Treasure Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nut-Free Cookies Market Strategic Shifts & Innovations
The market's evolution from a niche health-food category to a mainstream grocery segment is creating new competitive pressures. This shift is compelling producers to make fundamental choices about brand positioning, supply chain investment, and the level of scientific validation behind their "free-from" claims.
Advanced allergen detection technologies, such as ELISA and PCR testing, provide a scientific method for validating cleaning processes and finished products. Quality control departments in both specialist and large-scale food companies are adopting these tools to verify that cross-contamination has been eliminated. This validation capability is bifurcating the market into premium products with verifiable, lab-tested claims and standard-tier products that rely on ingredient segregation alone.
Regulatory frameworks like the U.S. FDA's Food Safety Modernization Act (FSMA) are shifting the industry's focus from reaction to prevention. The act's emphasis on preventative controls for allergens is forcing manufacturers to document and implement comprehensive risk management plans across their entire operation. This particularly affects mid-sized producers, who must now invest in the sophisticated process controls and documentation systems needed to demonstrate compliance.
Consumer purchasing behavior is moving beyond dedicated health food aisles toward expecting nut-free options in mainstream supermarket channels and online. This trend disrupts the historical advantage of specialist brands, as major retailers like those in Germany and the United States now actively seek nut-free lines from their largest CPG suppliers. The most visible impact is the reformulation of popular, established snack brands to meet nut-free criteria.
Nut-Free Cookies Market Segmentation
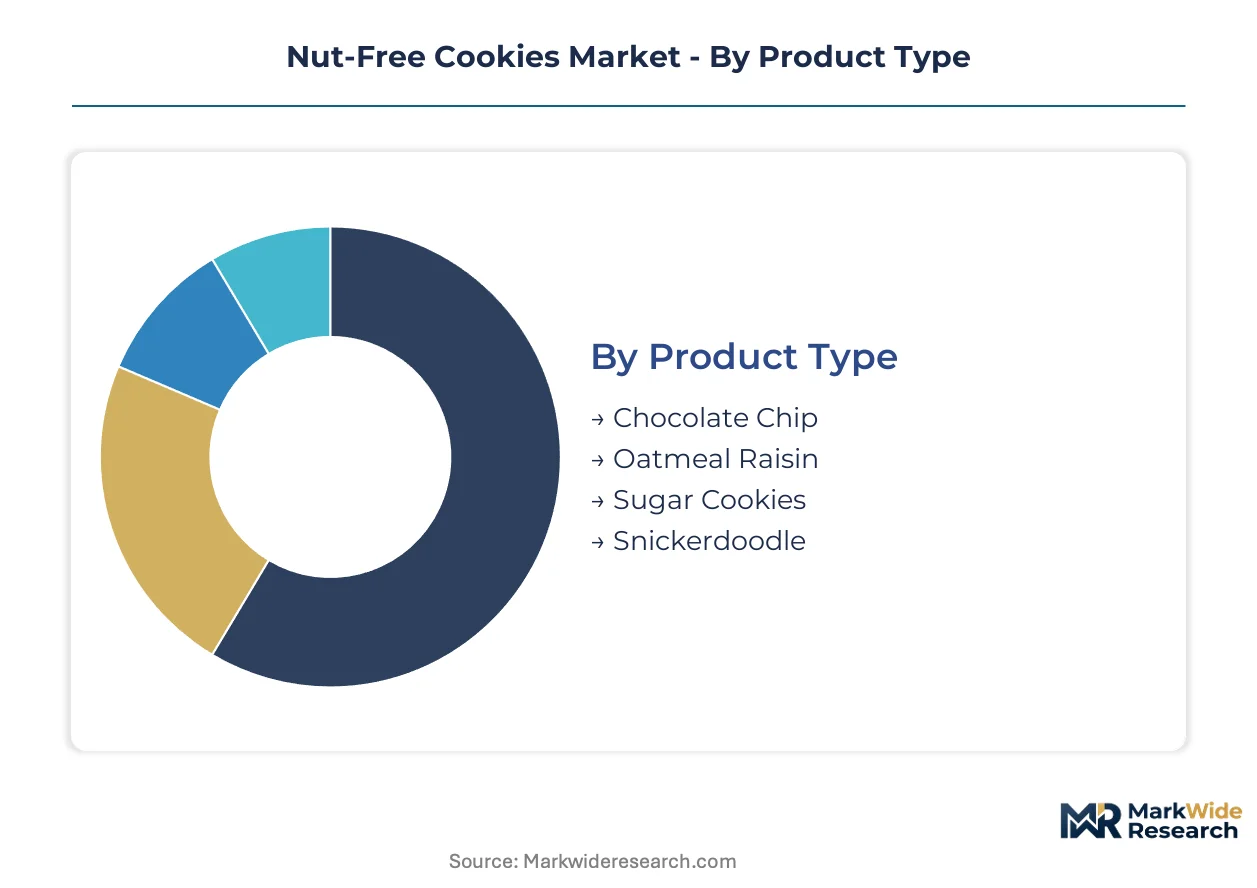
The nut-free cookies market is highly segmented, reflecting diverse consumer preferences and stringent safety requirements across various sales channels. Understanding these segments provides manufacturers with crucial insights into product development, distribution strategies, and targeted marketing efforts. This granular view helps stakeholders align production with specific demand drivers.
Product Type:
The product type segment faces considerable substitution pressure from traditional nut-containing cookies, necessitating superior taste and texture profiles to capture market share.
- Chocolate Chip:These classic cookies feature a base dough often made with alternative flours, studded with chocolate chips, and formulated to be entirely free of peanuts and tree nuts. Demand concentrates in household consumption, where familiarity and broad appeal drive repeat purchases.
- Sugar Cookies:Characterized by their simple, buttery flavor and often decorated, sugar cookies provide a versatile nut-free option for various occasions, including school events and parties. Their widespread appeal makes them a staple in retail settings, particularly during holiday seasons.
- Oatmeal Raisin:These cookies combine oats and raisins, offering a chewy texture and distinct flavor profile, appealing to consumers seeking traditional cookie varieties in a nut-free format.
- Snickerdoodle:Known for their cinnamon-sugar coating and soft, tangy interior, snickerdoodles provide a unique flavor experience within the nut-free cookie category.
Chocolate Chip retains volume leadership; Sugar Cookies hold the steepest expansion curve.
End User:
End user segmentation highlights distinct application needs, from individual household consumption to large-scale institutional procurement with specific allergen safety protocols.
- Households:This segment represents the largest consumer base, driven by individual and family purchases for daily consumption and special occasions, prioritizing convenience and taste in nut-free options. Consumers often seek certified products to manage severe allergies within their homes.
- Schools:Procurement from educational institutions is accelerating due to strict allergy management policies and the need to provide safe snack options for students with nut allergies. These institutions often require bulk purchasing and verifiable allergen-free certifications.
- Cafes:These establishments offer nut-free cookies as a specialty item, catering to customers seeking allergen-safe treats alongside beverages.
- Bakeries:Specialist bakeries integrate nut-free cookies into their broader allergen-friendly product lines, serving consumers with specific dietary needs.
Accelerating demand in Households and Schools is redefining market priorities.
Distribution Channel:
Distribution channel dynamics are shaped by varying consumer access preferences and the logistical complexities associated with maintaining product integrity across diverse retail environments.
- Supermarkets:These large-format retail stores command the largest share of nut-free cookie sales, offering broad accessibility and shelf space for established brands and new product introductions. Consumers benefit from convenient one-stop shopping.
- Online Retail:Representing the fastest-growing distribution channel, online platforms provide extensive product ranges, direct-to-consumer options, and discreet delivery, particularly appealing to households managing severe allergies. This channel enables niche brands to reach a wider audience.
- Health Food Stores:These specialized retailers cater to health-conscious consumers, often stocking a curated selection of premium and certified allergen-free products.
- Specialty Shops:These smaller, often independent stores offer unique or artisanal nut-free cookie options, focusing on personalized service and local sourcing.
The market is observing a significant shift in consumer access, with Supermarkets and Online Retail leading the transformation.
Packaging Type:
Packaging type reflects consumer preference for convenience, portion control, and product protection, while also playing a critical role in communicating allergen safety and brand identity.
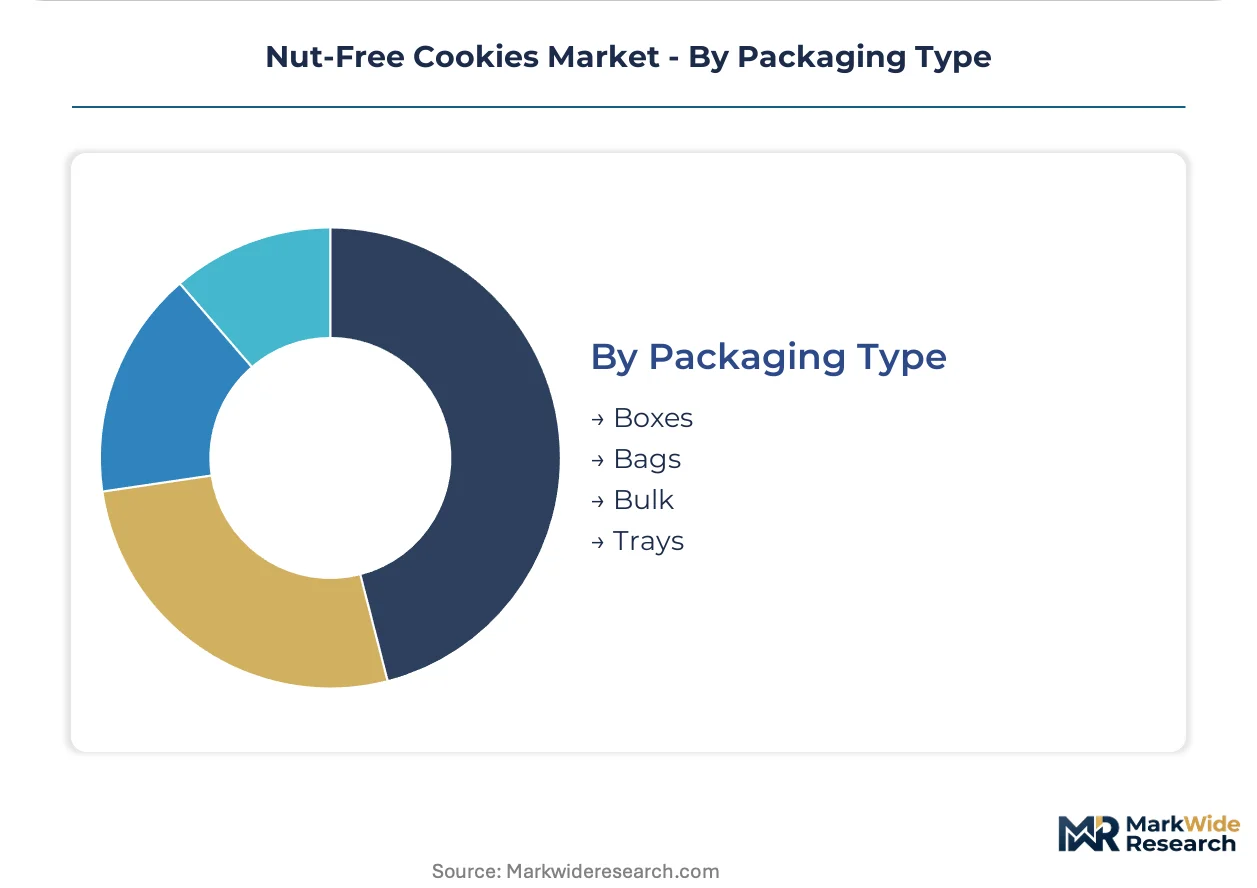
- Boxes:Commonly used for multi-pack or larger quantity cookies, boxes offer robust protection during transit and storage, while providing ample space for branding and allergen information. This format is prevalent in supermarket aisles.
- Bags:Flexible bags are popular for individual servings or smaller portions, offering convenience for on-the-go consumption and often featuring resealable closures to maintain freshness. This packaging type is cost-effective for manufacturers.
- Bulk:Bulk packaging caters primarily to institutional buyers like schools and cafes, providing cost-effective large quantities for food service operations.
- Trays:Often used for delicate or freshly baked nut-free cookies, trays offer presentation appeal and protection, typically found in bakeries or specialty stores.
Optimizing packaging for both shelf appeal and product integrity remains a core objective for manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for nut-free cookies vary significantly by geography, reflecting diverse cultural norms and regulatory environments. Some nations exhibit strong household demand for daily consumption, while others prioritize institutional procurement for allergen-safe school environments. This differentiation influences product development and distribution strategies across regions.
United States
Household consumption and accelerating school procurement drive demand for nut-free cookies across the United States. The FDA's Food Allergen Labeling and Consumer Protection Act mandates strict labeling, enhancing consumer confidence. Food manufacturing hubs in California are innovating new product lines and expanding production capacity.
Germany
Germany exhibits high allergy awareness, translating into strong demand for nut-free options, especially through health food stores. European Food Safety Authority (EFSA) advice underpins stringent EU allergen labeling regulations. Specialized food producers in Bavaria are focusing on premium, certified allergen-free product development.
Japan
Growing health consciousness and convenience store expansion contribute to rising nut-free cookie demand in Japan. The Ministry of Health, Labour and Welfare (MHLW) establishes allergen labeling standards for food products. Tokyo's urban retail centers see strong sales of convenient, individually packaged nut-free snacks.
Australia
School canteen policies and increasing supermarket availability boost nut-free cookie consumption in Australia. Food Standards Australia New Zealand (FSANZ) mandates clear allergen declarations on food packaging. Melbourne's food processing sector is developing new nut-free product formulations for domestic and export markets.
Canada
Strict school allergy policies and household safety concerns drive significant nut-free cookie demand in Canada. Health Canada's Food Allergen Labelling regulations ensure clear communication of potential allergens. Packaged food manufacturers in Ontario are expanding their production of certified nut-free baked goods.
Nut-Free Cookies Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive landscape. Mass-market players, often large food conglomerates, reformulate existing products to meet nut-free standards. Specialist brands, conversely, build their entire business around dedicated allergen-free production facilities and certifications. This market sees competitive moves centered on strategic partnerships for distribution and continuous portfolio diversification into adjacent allergen-free categories.
Within the mass-market reformulation segment, Mondelēz International and Conagra Brands exemplify the strategy of leveraging established brands and extensive distribution networks to introduce nut-free options. These companies adapt popular snack products to meet allergen-free criteria. In contrast, Homefree occupies a position within the dedicated specialist tier, built entirely on its certified nut-free facility and brand promise. This approach targets consumers with severe allergies, prioritizing stringent production protocols and verifiable 'free-from' claims.
| Leading Market Players |
|---|
| Mondelēz International |
| Conagra Brands |
| Nestlé |
| Homefree |
| Rich Products Corporation |
| Divvies |
| Skeeter Snacks |
| Not a Trace |
| Treasure Mills |
| Others |
Cost & Logistics Intelligence
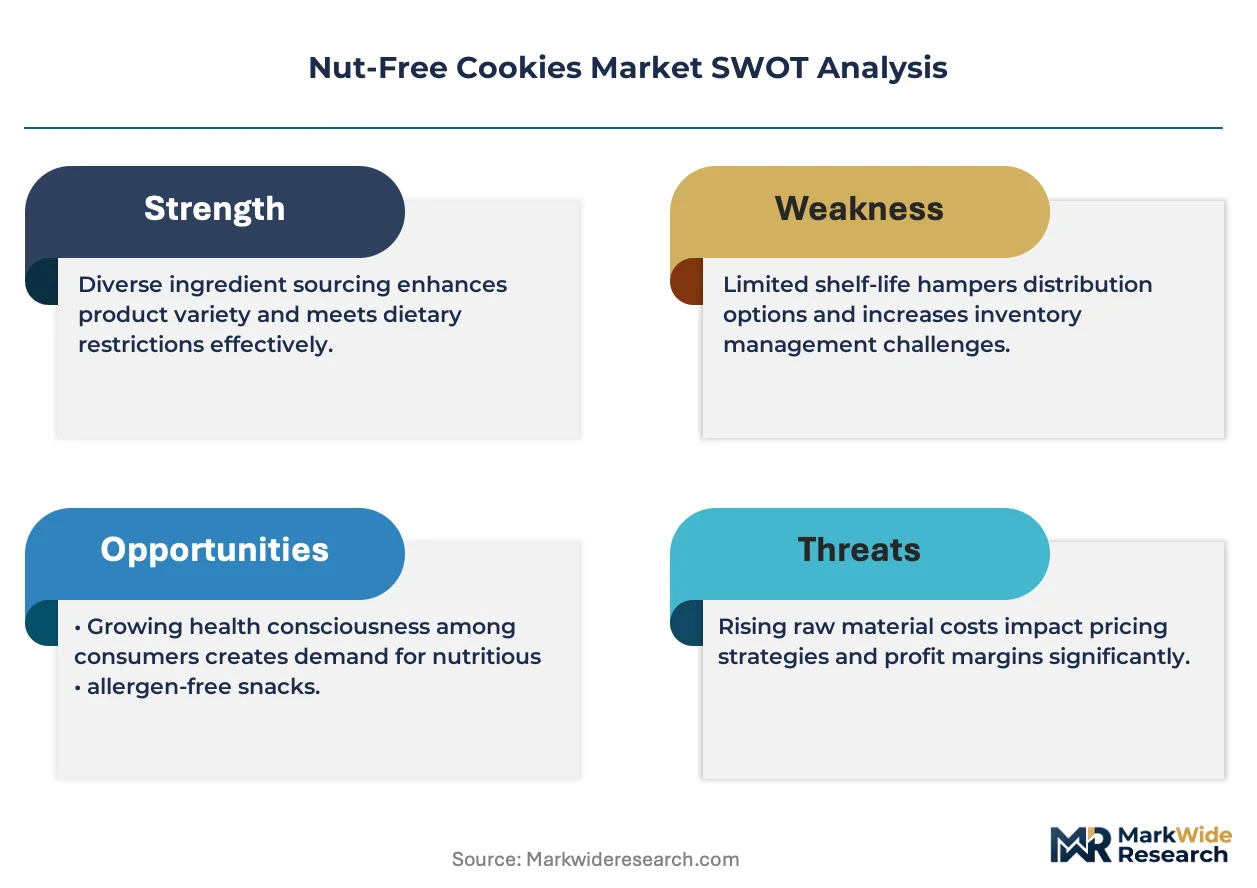
Dedicated production capacity for allergen-free products establishes high fixed costs, shaping supply concentration and elevating price floors across the nut-free cookies market. This cost structure impacts both mass-market players and specialized brands.
Pricing Analysis
Contract-based long-term offtake agreements characterize pricing for institutional buyers like schools, ensuring stable supply and predictable costs. Price differentiation stems from stringent certification levels, such as certified nut-free facilities, and established brand premium for trusted names. Pricing pressure stems from the higher cost structure associated with segregated production lines and certified ingredients. Households, driven by convenience and taste, exhibit higher price sensitivity compared to schools, which prioritize verifiable allergen safety.
Supply Chain Analysis
Strategic stockpiling of certified ingredients is crucial for manufacturers to mitigate supply disruptions, given the specialized nature of nut-free production. Geographic supply concentration for key alternative flours and specialized ingredients centers on the United States, Germany, and Canada. Raw material dependencies include alternative flours derived from oats or chickpeas, and certified nut-free chocolate chips. Single-source vulnerability for specialized allergen-free flavorings represents a structural supply chain risk. Distribution runs through established supermarket channels for broad consumer access and online retail for direct-to-consumer delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nut-free cookies market is experiencing early-cycle expansion, driven by increasing consumer awareness of food allergies and stricter regulatory mandates for allergen safety.
For Market Incumbents: Consolidate existing market share by investing in advanced allergen detection technologies to validate "free-from" claims scientifically. This move counters the threat from specialist brands built solely on dedicated facilities. Expand production capacity in key geographies like the United States to meet accelerating demand from institutional procurement, leveraging existing distribution networks. Invest in R&D for next-generation alternative flours to improve sensory profiles and maintain competitive positioning.
For New Entrants and Emerging Players: A certification fast-track through targeted third-party audits offers a clear pathway to market entry for specialist brands. Target the accelerating schools segment with bulk-packaged, certified nut-free products designed for large-volume procurement. A direct-to-consumer subscription model provides a viable go-to-market angle, building loyalty with households managing severe allergies through reliable, cross-contamination-free delivery and product exclusivity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialist brands with dedicated facilities and strong direct-to-consumer channels, reflecting high customer loyalty. Acquisition targets should include mid-sized specialist producers with verifiable allergen-free certifications and established supply chain segregation. Watch for shifts in regulatory enforcement or new scientific understandings of allergen thresholds as an inflection indicator for market dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Key Regions | Manufacturers increase production in the United States to meet growing demand from schools and households. |
| Advanced Allergen Detection Systems | Producers implement ELISA and PCR testing to scientifically validate cleaning processes and finished products. |
| Direct-to-Consumer Subscription Services | Brands build loyalty with households by offering exclusive access and reliable, cross-contamination-free delivery. |
| Reformulation of Mainstream Products | Large food companies adapt popular snack items to meet nut-free standards, expanding market accessibility. |
| Strategic Partnerships for Distribution | Specialist brands collaborate with major retailers to broaden their reach beyond health food stores. |
Research Approach
Operator-level perspectives from food scientists, quality assurance managers, procurement officers, and brand managers anchored the qualitative base for this analysis. Primary interviews were conducted with industry stakeholders, complemented by secondary validation from regulatory reports from the FDA and EFSA, food industry trade journals, and company reports. This approach employed both bottom-up and top-down triangulation to ensure data accuracy.
Sensitivity analysis framed the quantitative projections across the analysis window, integrating various market scenarios. The analytical framework modeled segmentation dimensions including product type, end user, distribution channel, packaging type, and regional regulatory compliance. Compound annual growth rates were derived through a robust statistical modeling approach, incorporating industry-specific inputs such as allergen prevalence rates and school meal program budgets.
Decision-makers should treat outputs as directional under current base assumptions regarding regulatory stability and consumer behavior; material deviation would warrant model refresh. Forecasts reflect assumptions documented through extensive research and expert consensus. Revision becomes warranted when new allergen discoveries or significant shifts in regulatory enforcement cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Global Lactose Intolerance Treatment Market
Food Intolerance Products
Low GI Food Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Citrus-Derived Gastrointestinal Comfort Blends Market
Food Intolerance Products
Dyspepsia Market
Food Intolerance Products
Gluten Free Malt Extracts Market
Food Intolerance Products
Lactose-Free Food Market
Food Intolerance Products
Europe Gluten-Free Oats Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Global Gluten Free Prepared Foods Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
Celiac Disease Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Lactose Free Products Market