
 Green Tea Supplements Market | 2026-2036
Green Tea Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Green Tea Supplements Market Outlook
Plant-based extraction technology is fragmenting legacy solvent-based manufacturing across the green tea supplements supply chain. NOW Foods leverages vertical integration from raw leaf sourcing to finished capsules, sustaining quality control across multiple production nodes. Herbalife Nutrition Ltd. competes through direct-to-consumer channel dominance in weight management positioning, while Gaia Herbs differentiates via organic certification and regenerative agriculture partnerships with growers.
Green tea supplements deliver concentrated bioactive catechins—primarily epigallocatechin gallate (EGCG) at standardized potencies ranging from 50% to 98% purity—manufactured through aqueous extraction followed by spray-drying or freeze-drying to preserve thermolabile polyphenols. Capsule formats occupy the largest revenue share due to dosing precision and consumer convenience, though liquid extract formulations register the fastest growth trajectory among athletes seeking rapid absorption. Online retail channels capture expanding margin pools as subscription models reduce customer acquisition costs relative to brick-and-footprint health food stores.
The FDA's Current Good Manufacturing Practice regulations and the EPA's pesticide residue monitoring programs jointly elevate compliance costs for domestic manufacturers while restricting import access for non-compliant foreign suppliers. China's NMPA and SAMR enforce dual carbon goals that reshape extraction facility energy sourcing, pressuring processors toward renewable-powered operations. Stakeholders must monitor evolving catechin content labeling requirements across multiple jurisdictions to anticipate reformulation mandates before enforcement windows tighten.
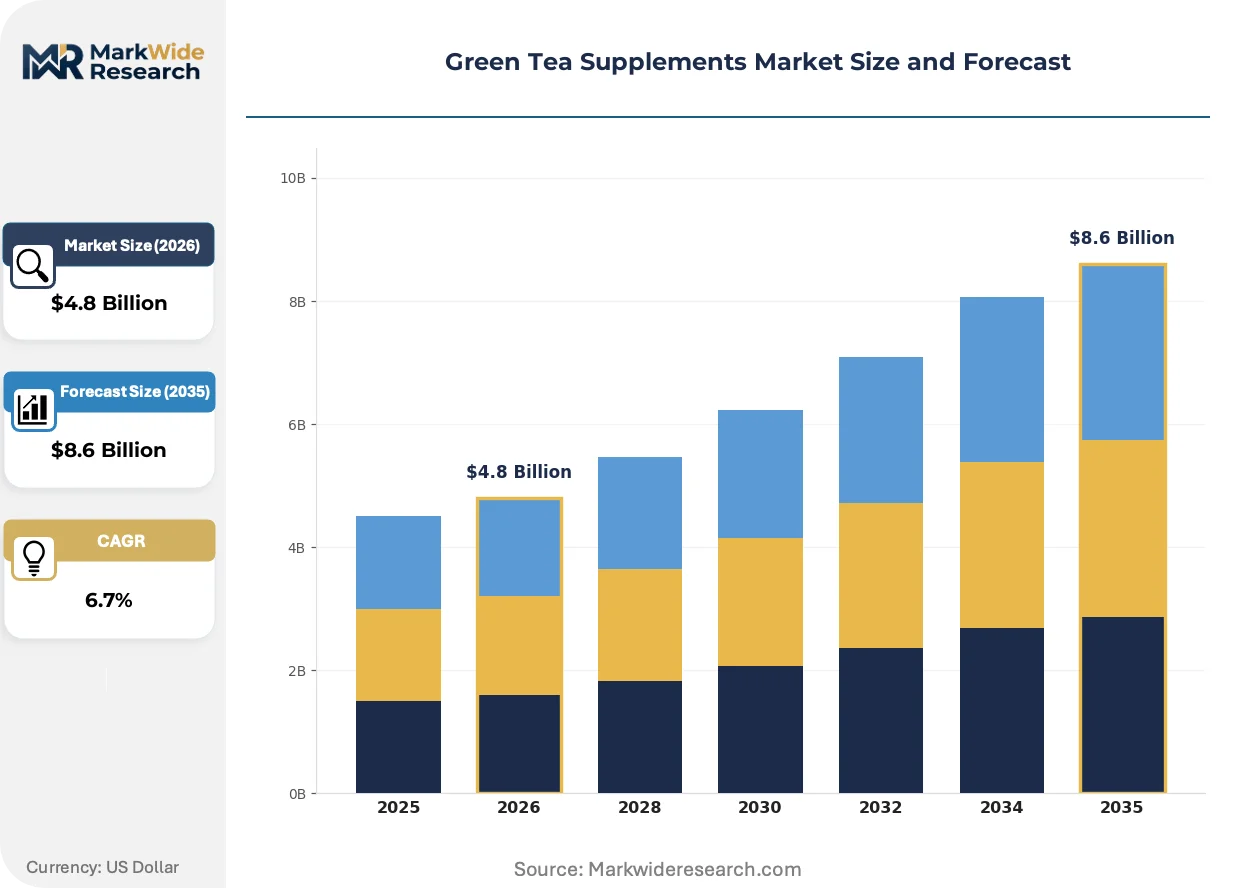
Market Dynamics
Plant-based extraction technology is fragmenting legacy solvent-based manufacturing across the green tea supplements supply chain, forcing processors to retool facilities or lose contract volumes to aqueous extraction competitors.
Growth Catalysts
- EGCG standardization protocols:Standardized epigallocatechin gallate potencies from 50% to 98% purity enable precise dosing claims that resonate with sports nutrition formulators and clinical researchers seeking reproducible outcomes.
- China's dual carbon goals:NMPA and SAMR enforcement of renewable energy mandates for extraction facilities accelerates processor consolidation around solar-powered operations in Jiangsu and Zhejiang provinces.
- Subscription commerce models:Direct-to-consumer platforms reduce customer acquisition costs versus brick-and-mortar health food stores, capturing expanding margin pools for replenishment-driven categories like daily wellness supplements.
Market Restraints
- Camellia sinensis leaf price volatility:Weather-driven harvest fluctuations in China's primary growing regions transmit directly to extract input costs, compressing processor margins during poor yield cycles.
- FDA New Dietary Ingredient pathway friction:The notification requirement for novel catechin formulations extends time-to-market for American manufacturers, favoring incumbents with existing NDIs over new entrants.
- Caffeine-free decaffeination substitutes:Water-processed decaf green tea extracts compete for the stimulant-sensitive consumer segment, threatening standard extract volumes in evening-use positioning.
Strategic Opportunities
- India's Ayurveda-aligned wellness expansion:FSSAI regulatory harmonization with traditional medicine frameworks creates entry pathways for catechin products positioned within India's preventive health culture.
- Liposomal delivery technology convergence:Nano-encapsulation combined with green tea bioactives addresses absorption limitations, opening sports recovery applications where rapid uptake commands premium positioning.
- EU CSRD sustainability disclosure mandates:Corporate sustainability reporting requirements for supply chain transparency favor suppliers with regenerative agriculture certifications and carbon-accounted extraction processes.
Industry Challenges
- Polyphenol stability expertise scarcity:Formulation chemists capable of preserving thermolabile catechins through spray-drying and freeze-drying protocols command premium compensation, constraining R&D expansion at mid-tier manufacturers.
- Multi-jurisdiction labeling compliance:Divergent catechin content declaration requirements across FDA, EFSA, and NMPA jurisdictions force parallel SKU development, inflating inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Tea Supplements Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powder, Tea Bags, Liquid Extract End User: Health-Conscious Consumers, Athletes, Seniors, Weight Management Programs Distribution Channel: Online Retail, Health Food Stores, Pharmacies, Supermarkets Formulation: Organic, Standardized Extract, Blended, Flavor-Infused |
| Companies Covered | NOW Foods, The Nature’s Bounty Co., Herbalife Nutrition Ltd., Jarrow Formulas, Inc., Life Extension, Pure Encapsulations, Gaia Herbs, BulkSupplements.com, Swanson Health Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Tea Supplements Market Strategic Shifts
Extraction technology advances and regulatory disclosure mandates are compressing legacy competitive advantages while opening white space for certified-sustainable and enhanced-bioavailability formats.
Supercritical CO2 extraction systems are rendering obsolete ethanol-dependent solvent methods that degrade heat-sensitive epigallocatechin gallate during concentration. Sports nutrition departments at university athletic programs now specify CO2-extracted materials for recovery protocols. This shift compresses processor margins for facilities without capital reserves for pressurized vessel upgrades.
REACH registration requirements for novel extraction solvents are elevating compliance costs for European contract manufacturers sourcing from non-EEA processors. The industrial consequence is a supplier consolidation trend favoring vertically integrated extractors with in-house toxicology dossiers. Capsule and tablet formulators serving EU markets are responding by dual-sourcing from REACH-registered Chinese facilities and domestic European extractors.
Athlete and clinical buyer segments now demand certificate-of-analysis documentation with every lot, displacing trust-based supplier relationships that previously relied on annual testing. This verification burden falls heaviest on smaller brick-and-mortar health food store channels lacking laboratory partnerships. The shift is most visible in North American and Western European markets where litigation exposure drives documentation rigor.
Green Tea Supplements Market Segmentation
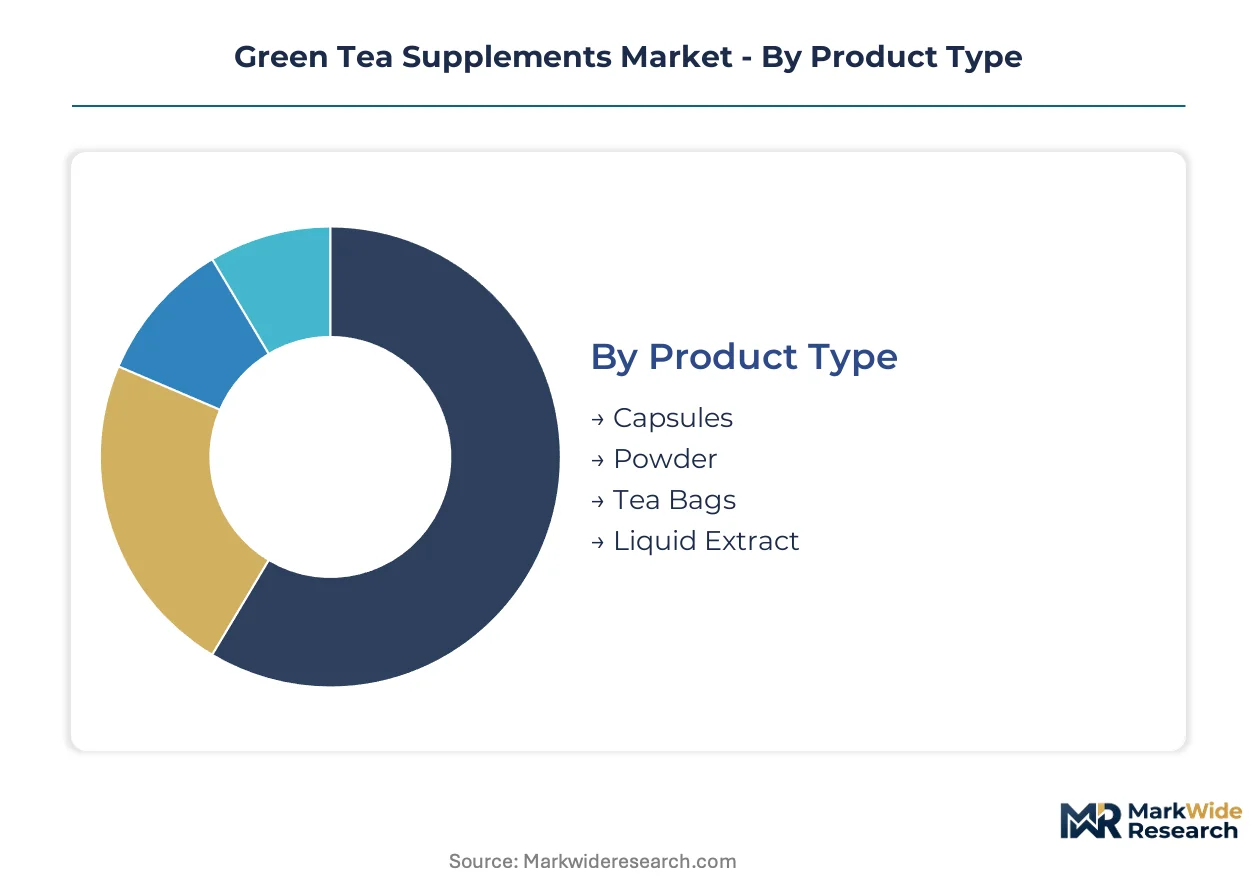
Green tea supplements fragment across four distinct axes that determine margin capture and channel strategy. Product format dictates manufacturing capital intensity, while end-user targeting separates premium positioning from commodity competition.
Product Type:
Capsule formats turn inventory fastest through subscription replenishment cycles, while liquid extracts move slowest due to stability testing requirements and shorter shelf lives.
- Capsules:Hard-shell and soft-gel formats deliver standardized EGCG doses from 200mg to 500mg with precision that appeals to clinical researchers and sports nutritionists. Demand concentrates in North American direct-to-consumer channels where monthly auto-ship programs lock in recurring revenue with lower acquisition costs than retail.
- Powder:Bulk catechin powders enable custom dosing for functional food manufacturers and compounding pharmacies, with bulk buyers in Jiangsu province driving contract volumes for ingredient suppliers serving beverage and nutrition bar producers.
- Tea Bags:Whole-leaf and cut-leaf formats retain broader polyphenol profiles beyond isolated EGCG, appealing to traditional wellness consumers in Japan and South Korea who prioritize ceremonial consumption rituals over extract potency.
- Liquid Extract:Tincture and dropper formats offer rapid sublingual absorption for athletes seeking immediate bioavailability, though thermal degradation risks during shipping constrain geographic distribution.
Capsules dominate installed base. Liquid extract is where expansion concentrates.
End User:
Cost tier separation runs sharpest across user segments, with athletes and weight management programs commanding premium pricing while seniors and general health-conscious buyers filter toward value formulations.
- Health-Conscious Consumers:Daily wellness seekers purchase lower-potency standardized extracts for antioxidant support, with subscription platforms capturing loyalty through convenience rather than clinical positioning.
- Athletes:University sports programs and professional training facilities now specify CO2-extracted materials with certificate-of-analysis documentation for every lot, creating compliance barriers for smaller suppliers lacking laboratory partnerships.
- Seniors:Age-related metabolic concerns drive caffeine-free decaffeinated extract demand for evening consumption, with water-processed decaf variants competing directly with standard extracts in pharmacy channels.
- Weight Management Programs:Clinical and commercial diet protocols leverage EGCG's thermogenic properties at 98% purity levels, with Herbalife Nutrition and similar direct sellers dominating this high-margin application through coaching-based distribution.
Health-conscious consumers anchor volume base. Weight management programs is where margin expansion concentrates.
Distribution Channel:
Volume concentration clusters in online retail where customer acquisition costs have fallen below brick-and-mortar equivalents, while pharmacies retain slowest inventory turns due to professional consultation requirements.
- Online Retail:Amazon, brand-direct sites, and subscription platforms capture expanding margin pools through replenishment automation, with Gaia Herbs and NOW Foods investing in proprietary e-commerce infrastructure to reduce platform dependency.
- Health Food Stores:Independent retailers and regional chains like Whole Foods Market emphasize organic certification and regenerative agriculture sourcing, though verification burdens for lot-specific testing strain smaller operators lacking lab partnerships.
- Pharmacies:CVS, Walgreens, and Rite Aid stock standardized extracts with USP verification, where pharmacist recommendation drives trial but slower restocking cycles compress working capital efficiency.
- Supermarkets:Mass-market placement in Walmart and Target reaches price-sensitive buyers with lower-potency blended formulations, though slotting fees and promotional spending erode net margins for manufacturers.
Online retail dominates installed base. Health food stores is where premium positioning concentrates.
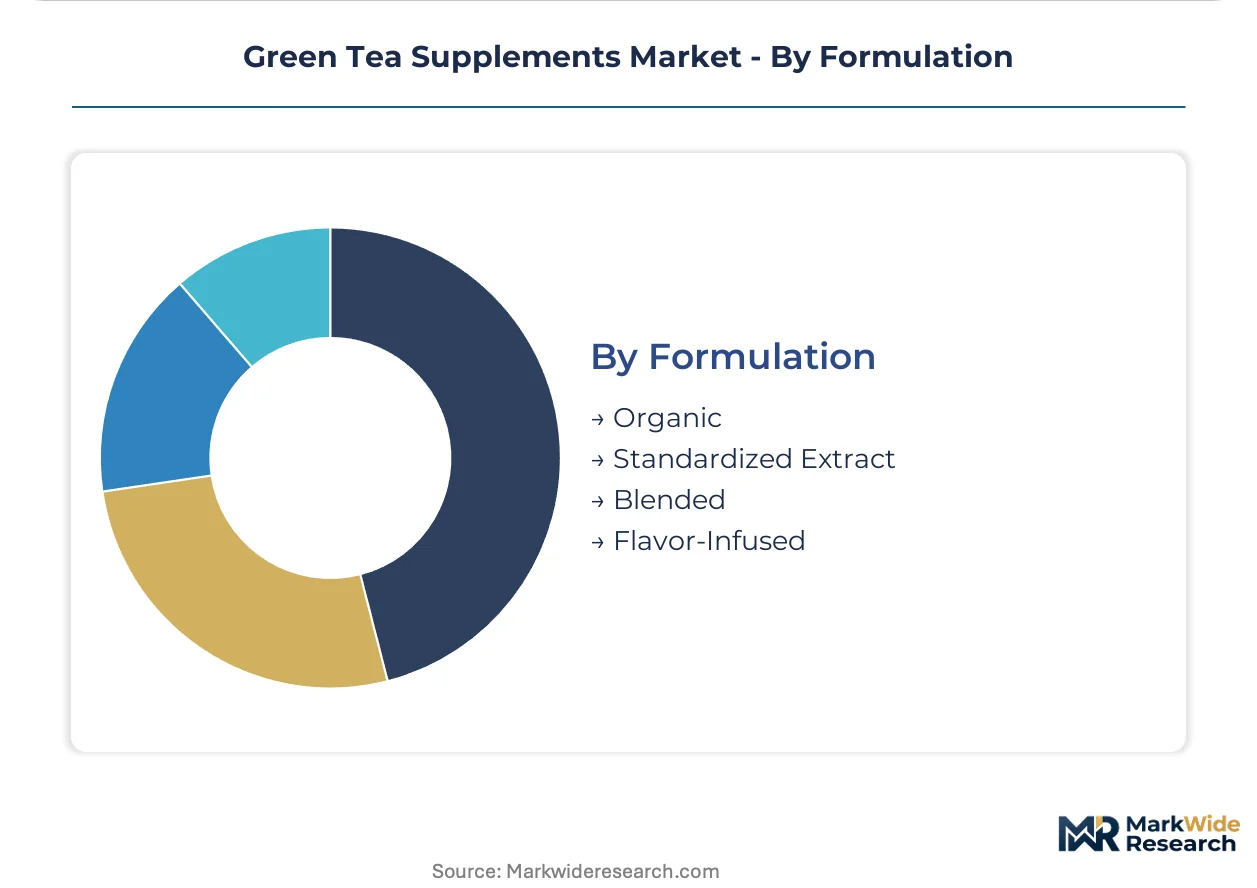
Formulation:
Supply concentration favors standardized extracts where Jiangsu and Zhejiang processors cluster near raw material sources, while organic certification requires dispersed regenerative agriculture partnerships with longer lead times.
- Organic:USDA Organic and EU Organic certifications command 15-30% price premiums through supply chain transparency that satisfies CSRD disclosure mandates for European corporate buyers.
- Standardized Extract:EGCG potencies from 50% to 98% purity enable reproducible clinical outcomes that sports nutrition formulators and university researchers require for protocol validation.
- Blended:Combination products with turmeric, ginger, or ashwagandha target Ayurveda-aligned wellness positioning in India where FSSAI harmonization with traditional medicine frameworks creates regulatory pathways.
- Flavor-Infused:Citrus, mint, and berry masking agents improve palatability for liquid extracts and powders, with natural flavor systems avoiding synthetic additive labeling that triggers clean-label rejection.
Standardized extract dominates installed base. Organic is where certification-driven pricing power concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu and Zhejiang provinces export concentrated EGCG extracts to American sports nutrition formulators and European wellness brands, with shipment volumes tracking university athletic program procurement cycles in the United States.
United States
University sports programs and professional training facilities drive specification-grade demand for CO2-extracted materials with lot-specific certificates of analysis. The FDA's Current Good Manufacturing Practice regulations and New Dietary Ingredient notification pathway shape domestic formulation decisions and extend time-to-market for novel catechin products. Extraction material imports concentrate through West Coast ports serving California-based finished goods manufacturers.
China
Jiangsu and Zhejiang province processors cluster near Camellia sinensis raw material sources, supplying standardized extracts at 50% to 98% EGCG purity to global formulators. The NMPA and SAMR enforce dual carbon goals that reshape extraction facility energy sourcing, pressuring processors toward renewable-powered operations. Solar-powered extraction capacity is consolidating around state-designated green industrial zones in the Yangtze River Delta.
Germany
REACH registration requirements for novel extraction solvents elevate compliance costs for contract manufacturers sourcing from non-EEA processors. The ECHA regulatory framework drives supplier consolidation toward vertically integrated extractors with in-house toxicology dossiers. Industrial buyers in Baden-Württemberg and North Rhine-Westphalia now dual-source from REACH-registered Chinese facilities and domestic European extractors.
India
FSSAI regulatory harmonization with traditional medicine frameworks creates entry pathways for catechin products positioned within India's preventive health culture and Ayurveda-aligned wellness expansion. The PLI scheme for nutritional supplements incentivizes domestic manufacturing capacity for export-oriented extract processing. Maharashtra and Gujarat-based formulators are developing blended products combining green tea bioactives with turmeric and ashwagandha.
Japan
Whole-leaf and cut-leaf formats retain demand among traditional wellness consumers who prioritize ceremonial consumption rituals over extract potency. The PMDA maintains distinct catechin content labeling requirements that force parallel SKU development for multinational suppliers. Tokyo and Osaka metropolitan areas concentrate premium retail distribution for organic-certified and regenerative agriculture-sourced products.
Green Tea Supplements Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that fragments between direct-to-consumer platforms, health food retail, and pharmacy distribution. NOW Foods leverages backward integration from raw leaf sourcing to finished capsules, while Herbalife Nutrition dominates weight management positioning through coaching-based distribution. Three archetypes anchor competitive positioning: vertically integrated quality controllers, direct-selling wellness platforms, and certified-organic specialists. Dominant competitive moves include strategic partnerships with regenerative agriculture growers and technology licensing for liposomal delivery formats.
Among North American quality-focused manufacturers, NOW Foods, Gaia Herbs, and Life Extension occupy positions spanning the vertical integration and organic certification archetypes. NOW Foods exemplifies the backward-integrated model with captive supply chain control from raw material through finished goods. Gaia Herbs represents the certified-organic specialist tier through regenerative agriculture partnerships. Life Extension anchors the clinical-research-aligned positioning that serves certificate-of-analysis demanding segments including university sports programs.
| Leading Market Players |
|---|
| NOW Foods |
| The Nature's Bounty Co. |
| Herbalife Nutrition Ltd. |
| Jarrow Formulas, Inc. |
| Life Extension |
| Pure Encapsulations |
| Gaia Herbs |
| BulkSupplements.com |
| Swanson Health Products |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta freight corridors connecting Jiangsu and Zhejiang extraction facilities to Shanghai port terminals shape cost-to-serve differentials across the green tea supplements market, with solar-powered processors capturing freight savings that translate into pricing flexibility against solvent-dependent competitors.
Pricing Analysis
CO2-extraction technology commands 20-35% premiums over legacy ethanol-based methods, while aqueous extraction occupies the mid-tier and solvent-dependent processing faces margin compression from environmental compliance costs. Three-tier pricing structure across premium, standard, and economy levels separates certified-organic regenerative-sourced extracts from conventional standardized grades and commodity blended formulations. Pricing pressure stems from water-processed decaffeination substitutes competing for stimulant-sensitive evening-use segments. University sports programs and clinical researchers show lowest price sensitivity due to certificate-of-analysis requirements, while mass-market supermarket buyers filter toward economy tiers.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for American finished goods manufacturers sourcing concentrated EGCG extracts. Raw material supply concentrates in China's Jiangsu and Zhejiang provinces, with secondary processing capacity emerging in India under PLI scheme incentives. Extraction operations draw from Camellia sinensis leaf inputs, aqueous processing chemicals, and renewable energy infrastructure. Single-source vulnerability runs through Yangtze River Delta port congestion during peak harvest seasons. Distribution runs through West Coast port entry for US-bound volumes, with European REACH-registered facilities serving EU markets through dual-sourcing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
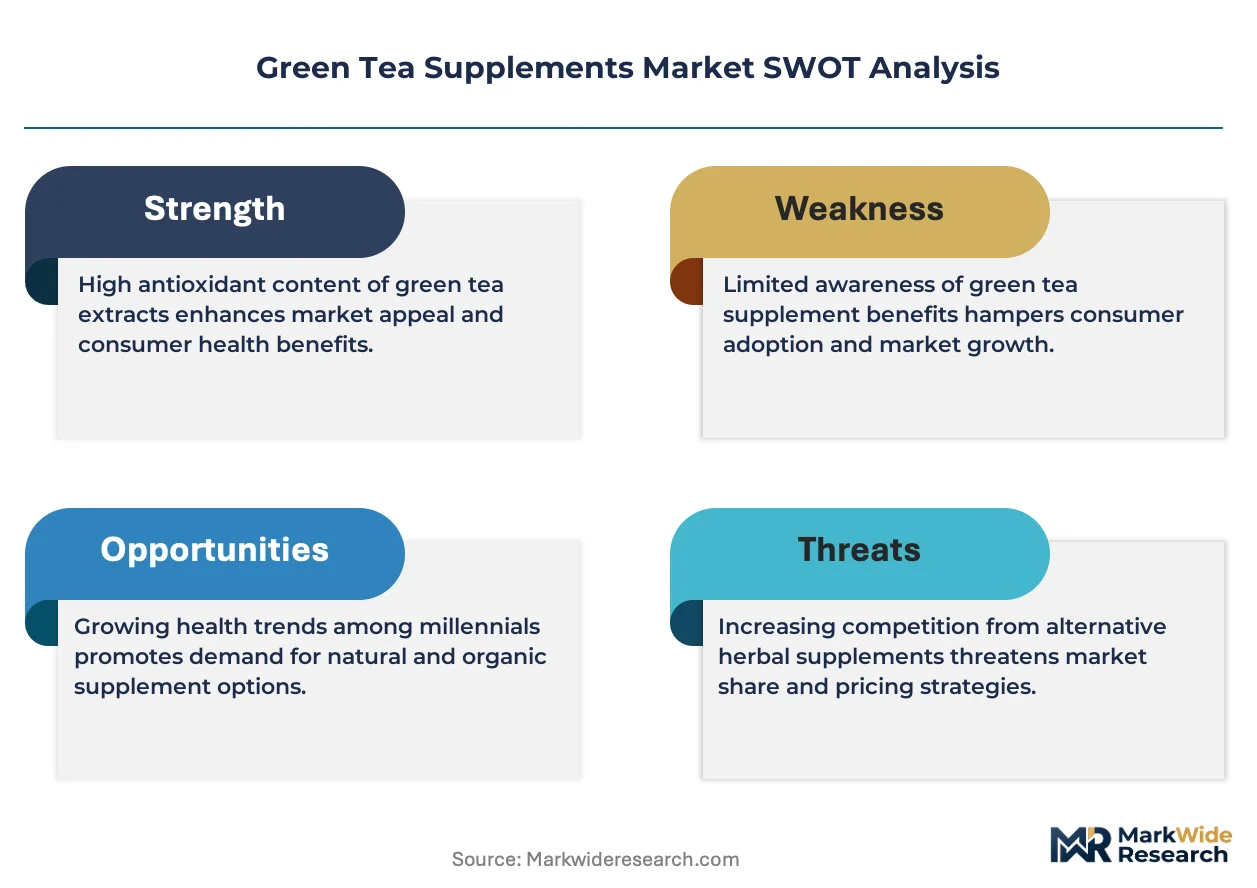
Analyst Recommendations
The green tea supplements market exhibits cyclical recovery characteristics tied to university athletic program procurement cycles, where sports nutrition department budget refreshes drive specification-grade demand spikes every 24-36 months.
For Market Incumbents: Harden quality control infrastructure against aqueous extraction competitors by securing certificate-of-analysis documentation partnerships with third-party laboratories. Deepen backward integration into regenerative agriculture grower networks to lock organic-certified supply ahead of EU CSRD disclosure mandate enforcement. Prioritize liposomal delivery technology licensing to defend premium positioning against nano-encapsulation entrants targeting sports recovery applications.
For New Entrants and Emerging Players: Build out India-based Ayurveda-aligned wellness positioning where FSSAI regulatory harmonization creates lower barriers than FDA NDI pathways. Target caffeine-free decaffeinated extract segments in pharmacy channels where water-processed substitutes show fastest penetration. Establish direct-to-consumer subscription platforms with auto-ship replenishment to reduce customer acquisition costs versus incumbent retail dependence.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food-ingredient conglomerates with underperforming botanical extract divisions lacking sports nutrition channel access. Long-term viability hinges on renewable-powered extraction capacity consolidation in Jiangsu and Zhejiang green industrial zones. Monitor NMPA dual carbon goal enforcement timelines as inflection indicators for processor margin compression and acquisition opportunity windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Partnership | Gaia Herbs and NOW Foods secure organic-certified supply chains satisfying EU CSRD transparency mandates. |
| Liposomal Delivery Licensing | Nano-encapsulation technology addresses absorption limitations for sports recovery premium positioning. |
| Subscription Platform Buildout | Direct-to-consumer auto-ship models reduce acquisition costs versus brick-and-mortar health food stores. |
| REACH-Registered Dual Sourcing | German formulators split procurement between Chinese facilities and domestic European extractors. |
| Solar-Powered Extraction Upgrade | Jiangsu and Zhejiang processors consolidate around state-designated green industrial zones. |
Study Parameters
Initial hypotheses were tested against primary input from extraction facility operations managers, sports nutrition formulators at university athletic programs, FSSAI regulatory affairs specialists, and health food store category buyers, then refined through secondary validation against FDA NDI notification databases, ECHA REACH registration filings, NMPA dual carbon policy directives, and customs trade flow records covering Camellia sinensis extract shipments. Bottom-up volume estimates from processor capacity utilization and top-down demand segmentation triangulated to consensus figures.
Demand-supply-balance modeling across the projection horizon incorporated product format segmentation by capsule, powder, liquid extract, and tea bag; end-user targeting across athletes, seniors, weight management programs, and general wellness seekers; distribution channel dynamics spanning online retail, health food stores, pharmacies, and supermarkets; and formulation differentiation between organic, standardized extract, blended, and flavor-infused variants. CAGRs derived from historical shipment velocity analysis and forward-looking procurement cycle indicators from university sports programs.
Practitioners should monitor NMPA renewable energy mandate enforcement intensity, FDA NDI pathway processing delays, and Camellia sinensis harvest yield variability for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Plant Based Protein Supplements Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Human Milk Oligosaccharides (HMO) Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
North America Saffron Supplements Market
Nutritional Supplements
Sleep Gummies Market
Nutritional Supplements
Vegan Collagen Powder Market
Nutritional Supplements
Mood Support Supplements Market
Nutritional Supplements
Brain Health Supplement Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Dextrose Monohydrate Market
Nutritional Supplements
Microalgae DHA Market
Nutritional Supplements
Isoleucine Market
Nutritional Supplements
Personalized Nutrition and Supplements Market
Nutritional Supplements
Calcium Malate Market