
 Europe Gluten-Free Oats Market | 2026-2036
Europe Gluten-Free Oats Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gluten-Free Oats Market Intelligence
Capital-intensity divergence between integrated millers and contract-packers is redrawing competitive boundaries in the Europe gluten-free oats sector. Bob's Red Mill Natural Foods leverages its dedicated gluten-free facility network to sustain premium positioning across German and UK retail channels. Glebe Farm Food Limited anchors its presence through in-house oat processing and farm-to-pouch traceability that larger multinationals struggle to replicate.
Europe gluten-free oats comprise Avena sativa kernels processed under controlled conditions to maintain gluten content below regulatory thresholds, typically requiring dedicated harvesting equipment, sealed transport, and optical or enzymatic sorting to eliminate cross-contact with wheat, barley, or rye. Their primary commercial purpose is supplying safe grain alternatives for celiac patients, gluten-sensitive consumers, and clean-label product formulations across retail and food manufacturing. Rolled oats and instant oats dominate volume flows through supermarkets and health food stores, where pouch formats command margin premiums over bulk packaging. Single-serve packs are gaining traction through e-commerce subscription models targeting urban households in France and the Netherlands.
EU Regulation 828/2014 on gluten-free labeling, enforced by national food safety authorities and aligned with EFSA risk assessments, mandates strict contamination controls that shape manufacturing investments and import compliance costs. REACH chemical safety protocols and national organic certification schemes in Italy and Austria add layered compliance requirements for oat processors sourcing across multiple member states. Stakeholders must monitor evolving EU Green Deal agricultural standards and carbon footprint disclosure rules that will reshape sourcing decisions and packaging material choices.
Market Dynamics
Optical sorting technology is compressing contamination thresholds and forcing millers to choose between capital-intensive purity infrastructure and exit from certified gluten-free oat processing entirely.
Growth Catalysts
- EFSA gluten threshold enforcement:Stricter purity protocols under EU Regulation 828/2014 are compelling food manufacturers to source certified gluten-free oats for liability protection.
- Bakery reformulation:German artisan bakers are substituting wheat with gluten-free oat flour to capture celiac and flexitarian households seeking clean-label alternatives.
- Optical sorter deployment:Near-infrared spectroscopy systems now detect wheat kernels at 99.9% accuracy, enabling processors to meet sub-20 ppm standards without batch destruction.
Market Restraints
- Seed supply concentration:Certified gluten-free oat seed stock concentrates in Nordic breeding programs, creating geographic dependency for southern European millers.
- Harvest equipment scarcity:Dedicated combines and sealed transport trailers require capital outlays that contract-packers cannot amortize at current volume levels.
- Cross-contamination liability:Shared grain elevators at port terminals in Rotterdam and Hamburg force processors to absorb insurance premiums or build captive storage.
Strategic Opportunities
- Netherlands direct-to-consumer channels:Urban households in Amsterdam and Rotterdam are subscribing to monthly gluten-free oat deliveries, bypassing traditional retail markups.
- EU Green Deal agricultural standards:Carbon footprint disclosure mandates will favor domestic oat processors over North American imports in public procurement tenders.
- Enzymatic sorting convergence:Combining optical detection with gluten-degrading enzyme treatments could unlock sub-10 ppm certification for infant food applications.
Industry Challenges
- Optical technician scarcity:Millers struggle to hire operators capable of calibrating near-infrared sorters for variable kernel moisture and color profiles.
- Multi-certification complexity:Simultaneous pursuit of organic, gluten-free, and carbon-neutral labels stretches quality assurance teams across overlapping audit schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gluten-Free Oats Market |
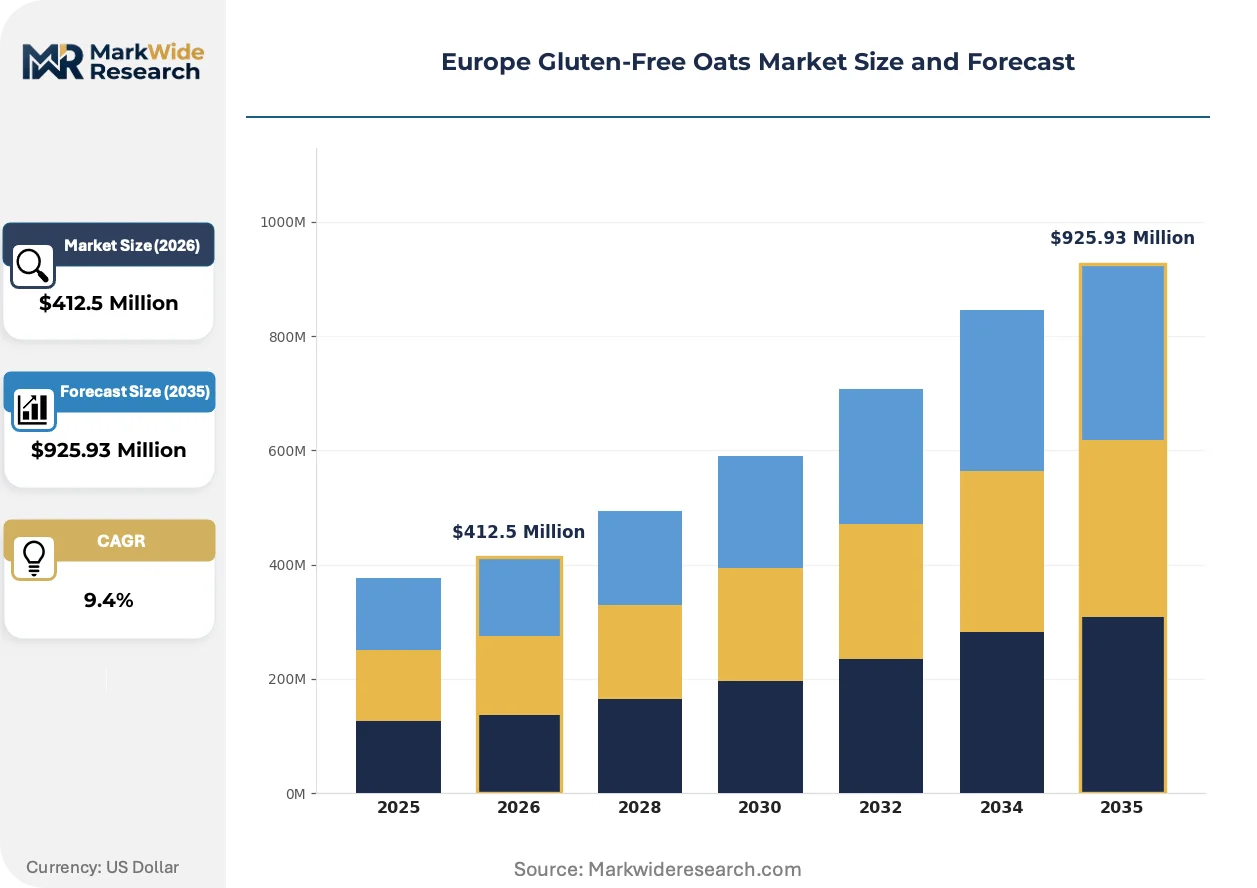
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $925.93 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Oats, Rolled Oats, Steel-Cut Oats, Flavored Oats End User: Households, Food Service, Health Stores, Online Retail Packaging Type: Bulk Packaging, Pouches, Cans, Single-Serve Packs Distribution Channel: Supermarkets, Specialty Stores, E-Commerce, Health Food Stores |
| Companies Covered | Bob's Red Mill Natural Foods, Kinnusen Mylly Oy, Dr. Schär AG/SPA, Genius Foods Ltd, General Mills Inc, Warburtons Ltd, Nature's Path Foods, Grain Millers Inc, Glebe Farm Food Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gluten-Free Oats Market Strategic Shifts & Innovations
Processing technology and procurement logic are diverging simultaneously, with purity automation advancing while buyer relationships fragment across direct and traditional channels.
Near-infrared spectroscopy paired with pneumatic rejection systems is supplanting manual visual inspection and density-based separation in European oat mills. German and UK food manufacturers now specify optical-sorted oats in supply contracts, rejecting legacy-processed batches. This technology compression is eroding margin for mid-scale millers lacking capital to retrofit facilities.
EU Green Deal agricultural standards are mandating farm-level carbon accounting for grain entering public procurement channels. Italian and Austrian processors must now document tractor fuel, fertilizer inputs, and transport emissions to retain institutional contracts. This regulatory layer favors vertically integrated farm-to-pouch operators over traders aggregating anonymous supply.
Urban households in France and the Netherlands are abandoning quarterly supermarket restocking for subscription-based single-serve oat deliveries. E-commerce platforms capture these buyers through algorithmic personalization of flavor and texture preferences. This channel shift concentrates volume with digital-native brands while compressing shelf-space negotiations for legacy packaged goods.
Europe Gluten-Free Oats Market Segmentation
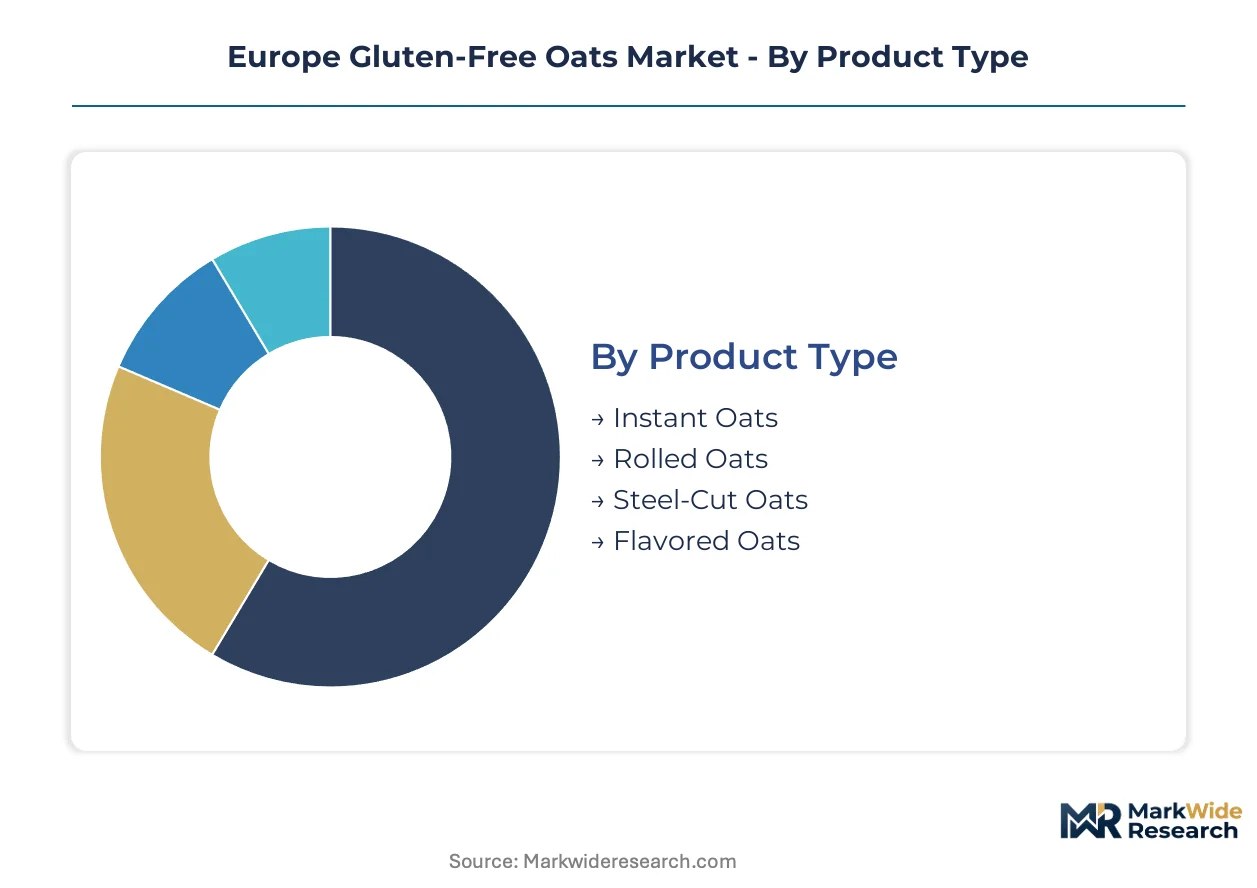
Channel fragmentation across Europe's gluten-free oats sector demands granular segmentation to map how purity-certified products reach distinct buyer cohorts. Each dimension reveals divergent margin structures and compliance burdens that reshape processor investment priorities.
Product Type:
Rolled oats and instant formats flow through divergent channel architectures, with convenience positioning dictating packaging and pricing tiers.
- Rolled Oats:Flattened Avena sativa flakes processed through steam and roller compression retain structural integrity in baking applications. German artisan bakeries and UK health stores concentrate demand here, driven by clean-label reformulation trends in wheat-free bread and pastry categories.
- Instant Oats:Pre-cooked and thin-rolled kernels enable sub-two-minute preparation, commanding premium positioning in French and Dutch direct-to-consumer subscription channels where urban households prioritize speed without purity compromise.
- Steel-Cut Oats:Irish pinhead oats—groats chopped rather than rolled—serve texture-focused consumers in specialty health stores across Austria and Switzerland.
- Flavored Oats:Pre-sweetened or fruit-infused variants target convenience-seeking segments in Benelux supermarkets, though EFSA additive scrutiny constrains formulation flexibility.
Rolled oats dominates installed base. Instant oats is where expansion concentrates.
End User:
Customer type determines certification stringency, with institutional buyers imposing batch-traceability requirements that household channels rarely match.
- Households:Celiac and gluten-sensitive consumers purchasing through retail and e-commerce drive volume, with German households showing highest per-capita consumption of certified products.
- Food Service:Hotels and restaurant chains in France and Italy require third-party gluten-free certification for liability protection, creating demand for sealed bulk formats with documented supply chain custody.
- Health Stores:Independent retailers across Scandinavia and the Alps curate premium assortments, favoring farm-to-pouch traceability that justifies 40-60% price premiums over supermarket equivalents.
- Online Retail:Algorithm-driven personalization platforms in the Netherlands and UK capture subscription-based recurring revenue, bypassing traditional retail margin stacking.
Households anchor volume throughput. Online retail shows steepest expansion trajectory.
Packaging Type:
Unit economics and contamination risk shape format selection, with hermetic sealing requirements favoring capital-intensive pouch lines over bulk handling.
- Pouches:Multi-layer barrier bags with resealable closures dominate health store and e-commerce channels, preserving sub-20 ppm purity through moisture and oxygen exclusion.
- Single-Serve Packs:Portion-controlled sachets enable trial and travel use cases, gaining traction in French urban subscription models where convenience commands disproportionate willingness-to-pay.
- Bulk Packaging:Food manufacturers and institutional buyers in Germany and Poland source 25kg sacks for bakery reformulation, accepting higher cross-contamination risk mitigation costs.
- Cans:Metal packaging persists in Italian retail for perceived shelf stability, though EU Green Deal packaging waste directives threaten format viability.
Pouches command margin leadership. Single-serve packs are climbing the fastest.
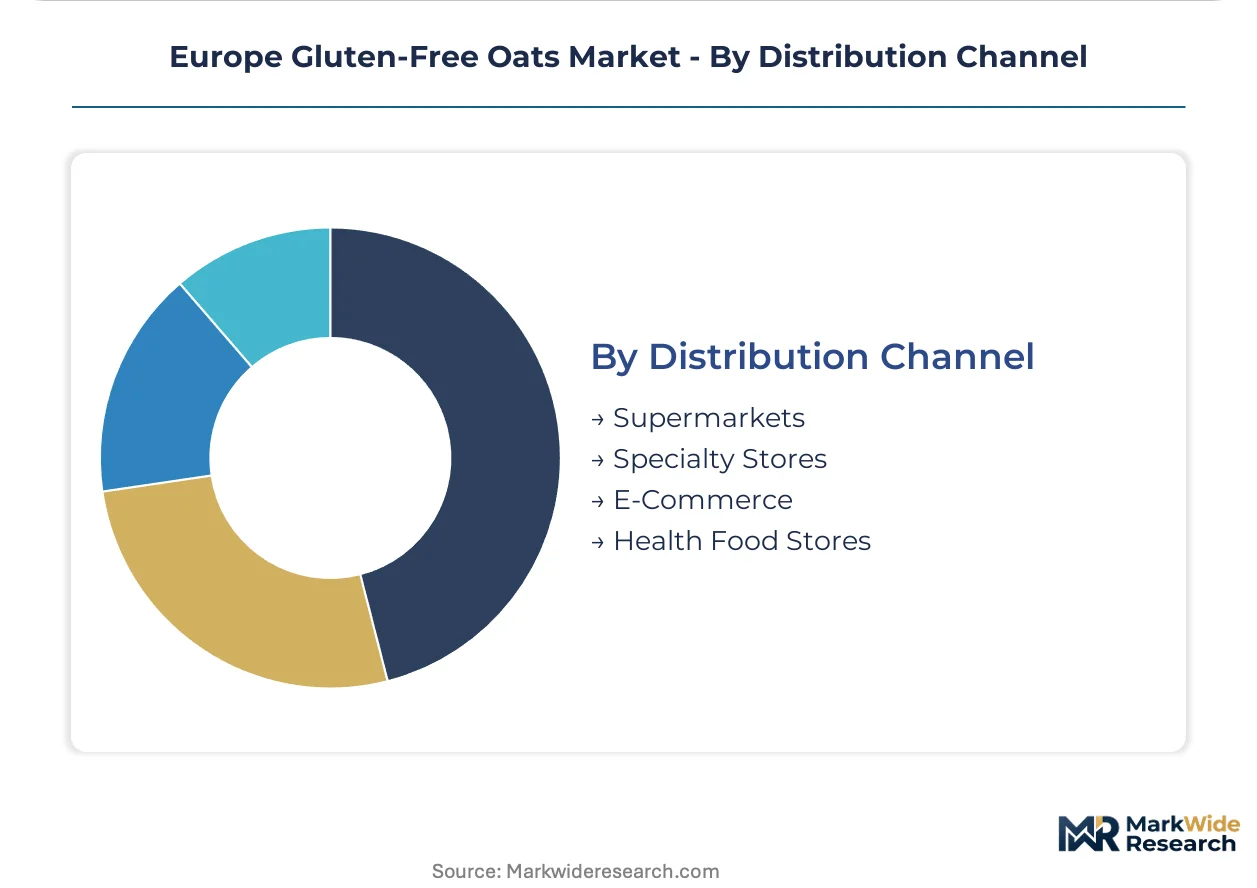
Distribution Channel:
Channel selection determines regulatory exposure, with EFSA enforcement intensity varying across supervised retail versus direct-to-consumer pathways.
- Supermarkets:German and UK multiples dominate volume, using category management to squeeze supplier margins while demanding optical-sorting certification proof.
- E-Commerce:Platform algorithms in the Netherlands and France personalize assortments, capturing household data that enables predictive replenishment and flavor customization.
- Specialty Stores:Independent grocers in Austria and Switzerland curate premium assortments, prioritizing provenance storytelling over price competition.
- Health Food Stores:Dedicated gluten-free retailers across Scandinavia enforce stricter purity thresholds than regulatory minimums, creating a certification tier above mass-market compliance.
Supermarkets anchor installed throughput. E-commerce is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across European markets. German households absorb premium pricing for certified purity, while Polish and Spanish buyers prioritize cost efficiency in bulk formats. This divergence shapes regional investment patterns and channel strategies.
Germany
Artisan bakery reformulation and direct-to-consumer subscription channels drive German demand. EFSA gluten threshold standards under EU Regulation 828/2014 mandate sub-20 ppm certification for retail placement. Bavarian oat processors near Munich deploy optical sorting infrastructure to supply reformulated bread lines for celiac households.
United Kingdom
Health store expansion and e-commerce personalization algorithms capture UK volume growth. REACH chemical safety protocols govern packaging material compliance for imported oat products. London-based specialty retailers curate premium assortments with farm-to-pouch traceability that justifies 40% price premiums.
Netherlands
Urban subscription models in Amsterdam and Rotterdam bypass traditional retail markups for convenience-seeking households. EU Green Deal agricultural standards mandate carbon footprint disclosure for grain entering public procurement. Rotterdam port terminals force processors to absorb insurance premiums or build captive storage against cross-contamination risk.
France
Single-serve pack adoption accelerates through algorithm-driven e-commerce platforms targeting time-constrained urban consumers. EFSA additive scrutiny constrains flavored oat formulation flexibility for mass-market placement. Parisian direct-to-consumer brands capture recurring revenue through predictive replenishment systems.
Italy
Organic certification schemes and metal-packaged retail formats persist in Italian health stores despite EU Green Deal packaging waste pressures. National organic certification requirements add layered compliance for processors sourcing across multiple member states. Lombardy-based millers document tractor fuel and fertilizer inputs to retain institutional contracts.
Europe Gluten-Free Oats Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Europe gluten-free oats sector. Integrated millers with dedicated gluten-free facilities command premium positioning through purity infrastructure, while contract-packers compete on volume throughput with lower capital intensity. The market structures around three archetypes: vertically integrated farm-to-pouch operators, multinational consumer goods conglomerates, and regional specialty millers. Dominant competitive moves include optical sorter deployment for certification compliance and direct-to-consumer channel development to bypass retail margin stacking.
Within the integrated milling tier, Bob's Red Mill Natural Foods and Glebe Farm Food Limited represent contrasting geographic anchors for purity-focused positioning. Bob's Red Mill exemplifies the dedicated facility network approach to sustained premium retail placement. Glebe Farm Food Limited occupies a position emphasizing in-house oat processing and traceability systems that larger multinationals struggle to replicate. Among Nordic operators, Kinnusen Mylly Oy sits within the regional specialty archetype serving proximity markets with certified seed stock concentration.
| Leading Market Players |
|---|
| Bob's Red Mill Natural Foods |
| Kinnusen Mylly Oy |
| Dr. Schär AG/SPA |
| Genius Foods Ltd |
| General Mills Inc |
| Warburtons Ltd |
| Nature's Path Foods |
| Grain Millers Inc |
| Glebe Farm Food Limited |
| Others |
Cost & Logistics Intelligence
Optical sorter deployment replacing legacy manual inspection simultaneously redraws supply geography toward Nordic seed programs and compresses pricing premiums for purity-certified batches. EFSA sub-20 ppm enforcement under EU Regulation 828/2014 forces southern European millers to absorb transport premiums or exit certified processing entirely.
Pricing Analysis
Subscription renewal revenue from direct-to-consumer channels in Amsterdam and Rotterdam now drives lifetime value for digital-native oat brands. Three-tier pricing structure across premium, standard, and economy levels separates optical-sorted farm-to-pouch traceability from contract-packed supermarket lines. Price differentiation hinges on certification stringency and channel control, with health store premiums eroding as e-commerce algorithms compress recurring revenue models. German households show lowest price sensitivity, while Polish bakery reformulation buyers prioritize volume scale over purity premiums.
Supply Chain Analysis
Strategic seed stockpiling dominates Nordic breeding programs, contrasting with just-in-time milling runs forced by moisture-sensitive kernel degradation. Certified gluten-free oat supply concentrates in Sweden, Finland, and Denmark, with southern European processors drawing from these northern origins. Raw material dependencies include dedicated harvest combines, sealed transport trailers, and optical sorter consumables. Single-source vulnerability runs through Rotterdam and Hamburg port elevators shared with wheat handling. Distribution runs through supermarket category management, e-commerce platform algorithms, and health store curation tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-consumer platform economics are displacing traditional retail margin stacking as algorithm-driven personalization captures recurring revenue. Interoperability between farm-level carbon accounting systems and EU Green Deal procurement portals reshapes competitive positioning.
For Market Incumbents: Fortify optical sorting infrastructure against contract-packer price erosion by securing captive Nordic seed contracts. Expand backward integration into dedicated harvest equipment pools to reduce cross-contamination liability exposure at Rotterdam terminals. Prioritize EU Green Deal carbon disclosure certification to defend institutional tender positioning against North American imports. For New Entrants and Emerging Players: Lead with enzymatic sorting convergence targeting sub-10 ppm infant food applications where incumbent capital deployment lags. Capture white-space in French single-serve subscription channels through predictive replenishment algorithms. Establish farm-to-pouch traceability narratives in Austrian and Swiss specialty stores where provenance premiums persist. For Investors and Strategic Acquirers: The market sits at a technology-infusion phase that favors vertically integrated mid-scale operators with optical sorting deployment and direct channel control. Long-term viability centers on carbon-accounting compliance infrastructure and purity certification moats. Acquisition targets should demonstrate Nordic seed program relationships and sealed transport capacity. Watch EFSA threshold tightening toward sub-10 ppm standards as inflection indicator for enzymatic treatment valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorter Deployment | Near-infrared spectroscopy enables EFSA sub-20 ppm compliance without batch destruction. |
| Direct-to-Consumer Channel Development | Algorithm-driven personalization in Amsterdam and Rotterdam bypasses retail margin stacking. |
| Farm-to-Pouch Traceability Investment | Carbon accounting integration with EU Green Deal procurement favors domestic processors. |
| Enzymatic Sorting Convergence | Gluten-degrading enzyme treatments unlock sub-10 ppm certification for infant food segments. |
| Captive Nordic Seed Contracting | Long-term supply agreements with Swedish and Finnish breeding programs reduce geographic dependency. |
Research Approach
Two parallel data streams informed the analysis: structured conversations with oat millers, health store category managers, and EFSA regulatory affairs specialists, and secondary validation through customs trade records, EU food safety authority enforcement disclosures, and carbon accounting platform documentation. Primary fieldwork captured optical sorter deployment timelines, seed program concentration patterns, and direct-to-consumer subscription mechanics. Secondary sources included REACH chemical safety filings, EU Green Deal agricultural standard drafts, and retail audit data from German and UK supermarket channels. Bottom-up volume modeling triangulated against top-down category spending estimates.
Across the projection horizon, the analytical framework segmented by product type, end user, packaging format, and distribution channel, with purity certification tier and carbon disclosure status as industry-specific dimensions. CAGRs derived from installed base erosion rates and expansion cohort penetration curves. Forecast inputs incorporated optical sorting capital expenditure cycles, EFSA enforcement intensity gradients across member states, and e-commerce platform algorithm personalization adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained EFSA sub-20 ppm enforcement, continued Nordic seed program yield stability, or EU Green Deal carbon disclosure mandate timelines would require recalibration. Forecasts reflect documented assumptions regarding optical sorter accuracy improvements, port elevator contamination incident frequencies, and direct-to-consumer churn rates. Revision becomes warranted when enzymatic sorting efficacy crosses commercial viability thresholds or EFSA initiates sub-10 ppm consultation proceedings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Food Intolerance Products Market
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Sugar Free Food and Beverage Market
Food Intolerance Products
Nut-Free Cookies Market
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
Gluten-Free Pasta Market
Food Intolerance Products
Citrus-Derived Gastrointestinal Comfort Blends Market
Food Intolerance Products
Lactose Free Products Market
Food Intolerance Products
Global Gluten Free Prepared Foods Market
Food Intolerance Products
Lactose-Free Food Market
Food Intolerance Products
North America Gluten-Free Food and Beverage Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market