
 Sugar Free Food and Beverage Market | 2026-2036
Sugar Free Food and Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Free Food and Beverage Market Analysis
Demand composition within the sugar free food and beverage sector is shifting as health-conscious consumers displace traditional diabetic segments as the primary volume driver. PepsiCo Inc. leverages its beverage portfolio breadth to anchor shelf presence across multiple retail formats. Nestlé S.A. specializes in dairy and confectionery alternatives with clean-label positioning. The Coca-Cola Company dominates carbonated zero-sugar formulations through concentrated marketing investment.
Sugar free food and beverage products are formulated with non-caloric or reduced-caloric sweetening systems—steviol glycosides, sucralose, erythritol, or aspartame—designed to replicate sensory profiles of sucrose-sweetened goods while meeting metabolic health objectives. Beverages lead volume contribution due to established reformulation infrastructure and consumer familiarity with diet variants. Natural sweeteners represent the fastest-expanding ingredient source segment as clean-label preferences reshape procurement priorities across retail channels. Confectionery trails in penetration but carries premium margin pools where technical barriers to texture replication remain elevated.
FDA nutrition labeling mandates and WHO sugar intake guidelines shape product development timelines and marketing claims across North American and European markets. EFSA evaluations of novel sweeteners determine market access timelines for reformulated introductions in the European Union. Stakeholders must monitor evolving regulatory stances on artificial sweetener safety classifications and adapt formulation strategies accordingly.
Market Dynamics
Reformulation pressure from FDA labeling mandates and WHO sugar reduction targets is compressing product development cycles and forcing ingredient sourcing diversification across beverage and confectionery portfolios.
Growth Catalysts
- FDA Nutrition Labeling:Updated serving-size disclosure rules compel manufacturers to reduce added sugars or face shelf-space penalties in US retail channels.
- Steviol Glycoside Extraction:Enzymatic bioconversion methods from stevia leaf biomass are lowering input costs for natural zero-calorie sweetening systems.
- Health-Conscious Millennials:This demographic cohort in the United States now exceeds diabetic populations as the primary volume driver for sugar-free carbonated beverages.
Market Restraints
- Erythritol Price Volatility:Fermentation-based production of this bulk sweetener faces corn supply fluctuations and energy cost spikes that compress formulation margins.
- EFSA Novel Food Timelines:European safety evaluations for emerging sweeteners extend market access delays by 18-36 months versus US FDA pathways.
- Texture Replication Barriers:Sugar's functional properties in confectionery—humectancy, browning, crystallization control—lack cost-competitive replacements at scale.
Strategic Opportunities
- India FSSAI Reformulation Incentives:India's food safety regulator offers expedited approval pathways for products meeting specified sugar reduction thresholds.
- Direct-to-Consumer Subscription:Beverage brands bypass traditional retail slotting fees through personalized zero-sugar product bundles shipped to household subscribers.
- Clean-Label Convergence:Pairing stevia with monk fruit extract and allulose is unifying natural positioning with acceptable sensory profiles in premium chocolate segments.
Industry Challenges
- Flavor Chemist Scarcity:Formulation expertise bridging sensory science and metabolic biochemistry commands premium salaries that strain mid-tier manufacturer R&D budgets.
- Legacy Equipment Retrofit Costs:Existing sucrose-calibrated mixing and heating infrastructure requires capital-intensive modification to handle hygroscopic alternative sweeteners without caking or degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Free Food and Beverage Market |
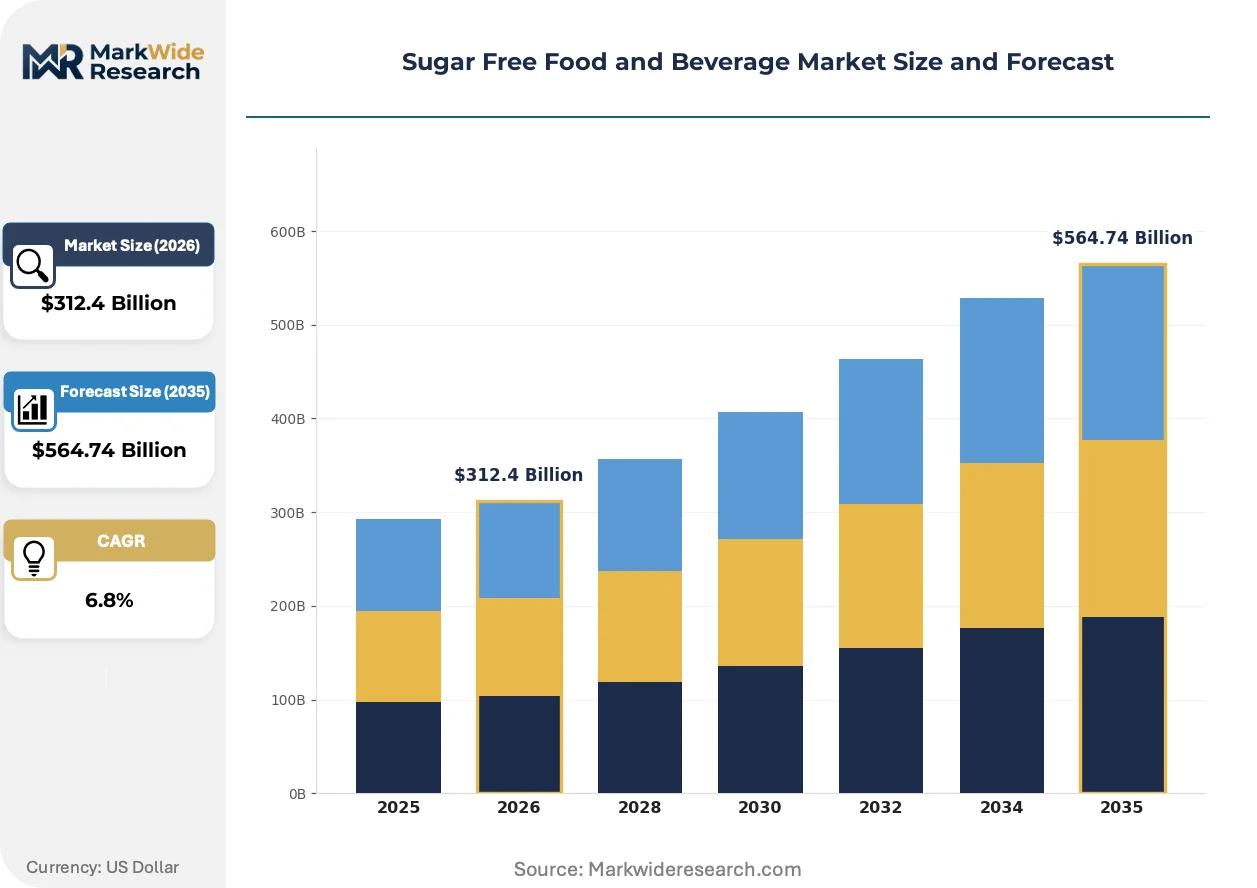
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Beverages, Dairy, Confectionery End User: Health-Conscious Consumers, Diabetics, Children, Athletes Ingredient Source: Natural Sweeteners, Artificial Sweeteners, Sugar Alcohols, Others Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Stores |
| Companies Covered | Mondelēz International Inc., The Kraft Heinz Company, The Coca-Cola Company, Keurig Dr Pepper, Monster Beverage Corporation, PepsiCo Inc., Mars Incorporated, Zevia, Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Free Food and Beverage Market Emerging Trajectories
Ingredient biotechnology and regulatory harmonization pressures are simultaneously expanding formulation toolkits and compressing geographic differentiation in product positioning.
Enzymatically produced rare sugars—particularly allulose—are unifying low-calorie claims with clean-label demands. Beverage manufacturers in the United States have accelerated adoption since FDA granted allulose exempt status from added sugar declarations. This technology is unifying previously separate premium and mass-market positioning tiers.
EU F-Gas Regulation phase-down schedules are pressuring cooling-dependent fermentation processes for erythritol and similar polyols. Manufacturers face capital allocation decisions between process reengineering and geographic production relocation. Eastern European facilities with access to renewable district heating are absorbing capacity investments previously destined for Western EU sites.
Retail pharmacy channels are displacing conventional grocery as the primary discovery point for functional sugar-free products. CVS Health and Walgreens shelf resets prioritize metabolic health positioning alongside diabetes management. This channel migration is most visible in US suburban markets where pharmacy density exceeds supermarket access.
Sugar Free Food and Beverage Market Segmentation
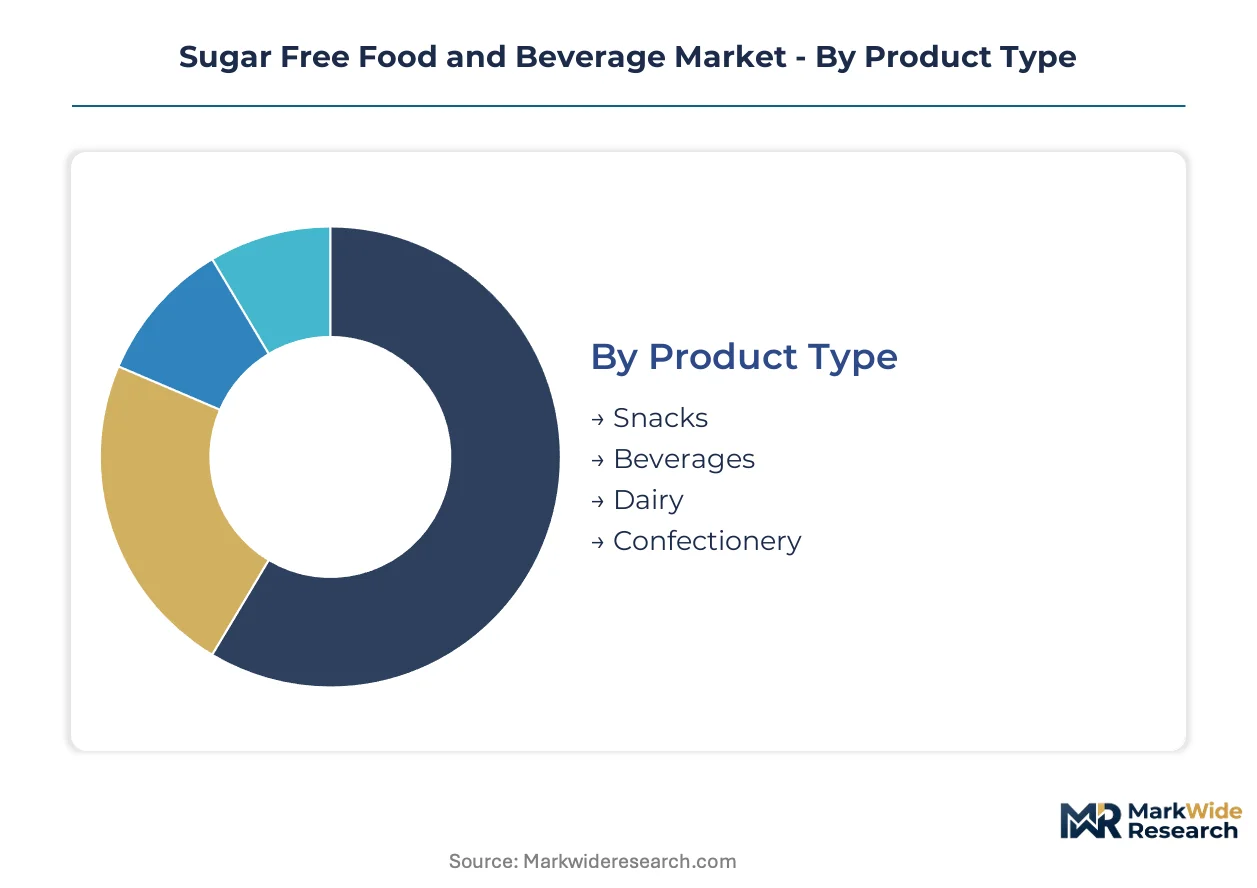
Segmentation in the sugar free food and beverage sector reveals divergent growth trajectories between mass-market volume plays and premium functional positioning. Reformulation complexity and distribution channel economics create distinct margin architectures across each dividing line.
Product Type:
Beverages dominate absolute volume while confectionery commands per-unit premiums, creating a bifurcated investment thesis across the category.
- Beverages:Carbonated soft drinks, flavored waters, and ready-to-drink teas constitute the largest addressable base. PepsiCo and Coca-Cola manufacturing infrastructure in the United States supports rapid line extensions, though aluminum can supply constraints periodically throttle promotional velocity.
- Confectionery:Chocolate and hard candies face steep technical barriers around bulk sweetener substitution. Texture replication demands from European consumers sustain premium pricing power where stevia-allulose blends achieve acceptable sensory parity.
- Snacks:Baked chips, crackers, and protein bars incorporate erythritol or monk fruit for reduced glycemic impact. Shelf-stable formulation expertise concentrates with contract manufacturers serving private-label retailers.
- Dairy:Yogurt and ice cream alternatives leverage fermentation-derived sweetness for clean-label claims. Cold-chain distribution requirements limit geographic expansion beyond established refrigerated networks.
Today's leader: Beverages. Tomorrow's challenger: Confectionery.
End User:
Health-conscious millennials have displaced traditional diabetic segments as the primary volume driver, redirecting marketing spend toward lifestyle positioning rather than clinical utility.
- Health-Conscious Consumers:This cohort prioritizes clean-label credentials over calorie reduction alone. Stevia and monk fruit formulations in premium bottled water and functional beverages capture disproportionate wallet share in coastal United States markets.
- Diabetics:Blood glucose management remains the core use case for sugar alcohols and fiber-enriched bakery. Pharmacy channel placement at CVS Health and Walgreens sustains predictable replenishment cycles.
- Children:Parental scrutiny of artificial sweetener safety limits category penetration. Natural positioning with allulose or rare sugars opens limited access through school-compliant snack programs.
- Athletes:Protein-fortified recovery beverages and electrolyte replacements incorporate zero-sugar formulations. Sports nutrition specialty retailers and direct-to-consumer subscription models bypass conventional grocery slotting fees.
Health-conscious consumers anchor current volume. Athletes represent the steepest expansion trajectory as performance nutrition mainstreams.
Ingredient Source:
Procurement priorities are shifting from cost-optimized artificial systems toward fermentation-derived and botanical alternatives that satisfy clean-label demands.
- Natural Sweeteners:Steviol glycosides and monk fruit extracts command premium positioning. Enzymatic bioconversion methods from stevia leaf biomass are compressing input costs for beverage manufacturers.
- Artificial Sweeteners:Sucralose and aspartame retain cost advantages in mass-market carbonated drinks. FDA safety classifications and consumer perception headwinds constrain brand architecture options.
- Sugar Alcohols:Erythritol and xylitol provide bulk and cooling effects in confectionery. EU F-Gas Regulation phase-down schedules pressure fermentation-dependent production economics.
- Others:Allulose and rare sugars occupy an emerging regulatory niche. FDA exempt status from added sugar declarations in the United States accelerates adoption across previously separate premium and mass tiers.
Natural sweeteners gain share fastest. Sugar alcohols face margin compression from energy and regulatory costs.
Distribution Channel:
Channel migration from conventional grocery toward pharmacy and digital direct-to-consumer is reshaping promotional calendars and trade spend allocation.
- Supermarkets:Center-store shelf resets favor zero-sugar line extensions with recognizable parent brands. Slotting fee structures disadvantage emerging entrants without scale.
- Online Retail:Subscription models for personalized beverage bundles bypass retail intermediaries. Amazon and specialized health platforms enable trial-size sampling that reduces consumer risk.
- Convenience Stores:Immediate consumption occasions favor single-serve chilled beverages. Refrigerated door space constraints limit SKU proliferation beyond top-moving variants.
- Health Food Stores:Whole Foods Market and regional cooperatives curate premium natural-positioned assortments. Certification requirements for non-GMO or organic credentials filter supplier pools.
Supermarkets retain volume dominance. Online retail is climbing the fastest as fulfillment infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States metropolitan retail corridors anchor sugar-free formulation capacity, with FDA labeling mandates and pharmacy channel expansion driving geographic deployment decisions across the sector.
United States
Health-conscious millennials and pharmacy channel migration at CVS Health and Walgreens propel volume. FDA updated serving-size disclosure rules compress product development timelines. Greater Atlanta and Dallas-Fort Worth concentrate contract manufacturing for stevia-sweetened beverage lines.
Germany
Clean-label confectionery demand and premium chocolate texture replication sustain margin pools. EFSA novel food evaluations extend market access timelines for emerging sweeteners. Bavaria hosts fermentation-based erythritol production facilities adapting to EU F-Gas Regulation phase-down schedules.
India
Urban middle-class expansion and diabetes prevalence create dual demand anchors. FSSAI reformulation incentives offer expedited approval pathways for sugar-reduced products. Maharashtra's Pune-Ahmednagar corridor attracts beverage contract manufacturing investments serving domestic and export markets.
Japan
Aging demographics and functional food positioning drive rare sugar adoption. METI standards for enzymatically produced sweeteners shape ingredient sourcing protocols. Kansai region fermentation specialists supply allulose to domestic confectionery reformulation programs.
Brazil
Stevia leaf cultivation proximity and price-sensitive mass-market demand favor natural sweetener integration. ANVISA safety classifications for sugar alcohols influence formulation choices. São Paulo state processing clusters handle steviol glycoside extraction for Pan-Latin American distribution.
Sugar Free Food and Beverage Market Vendor Landscape
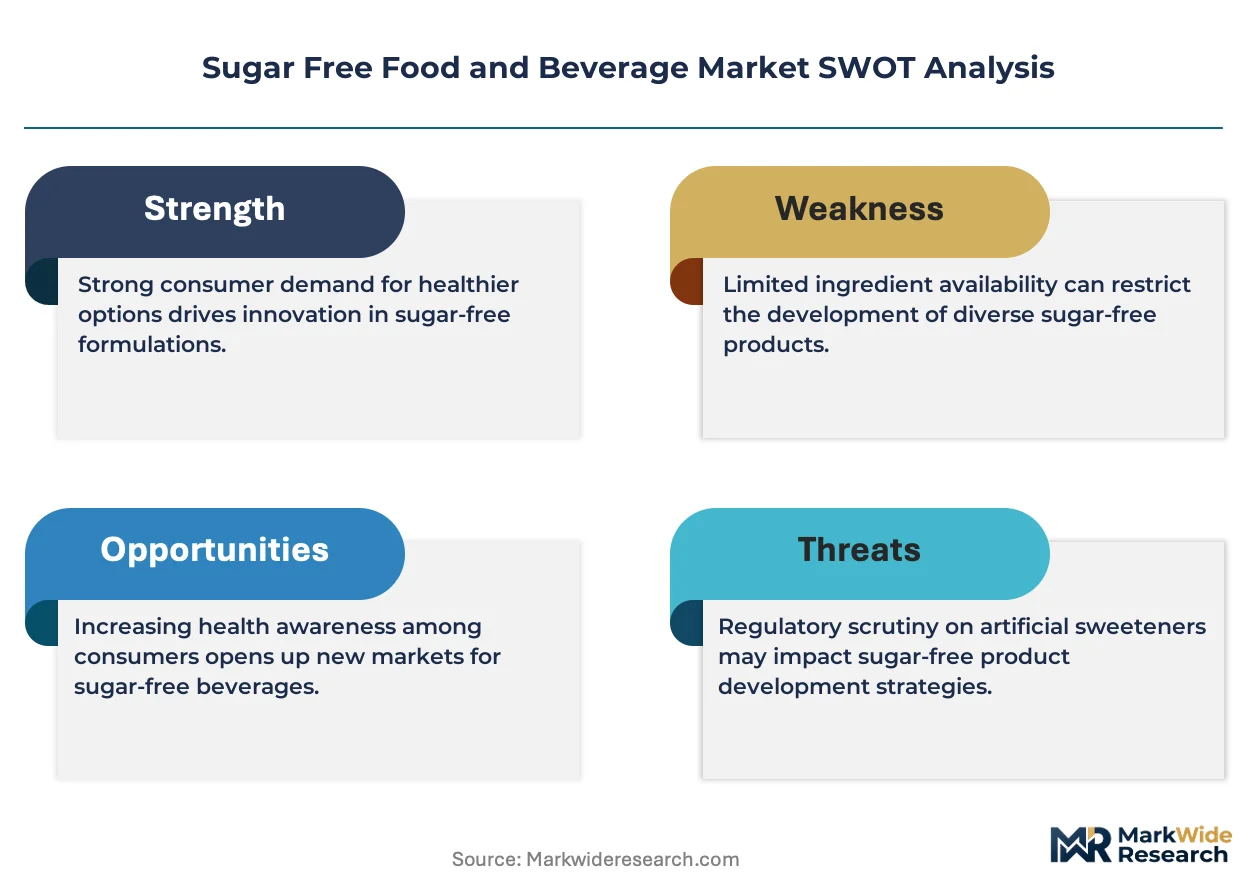
Portfolio diversification dominates the current landscape, with multinational beverage conglomerates and confectionery specialists competing through reformulation speed and clean-label positioning. Market structure concentrates around three tiers: global scale players with integrated sweetener supply chains, regional specialists leveraging local botanical sourcing, and emerging direct-to-consumer brands bypassing retail slotting structures. Strategic archetypes include stevia-allulose blend innovators, pharmacy-channel distributors, and fermentation-technology licensors. Competitive intensity manifests through M&A activity targeting natural sweetener extraction capabilities and strategic partnerships with enzymatic bioconversion technology providers.
Among North American beverage and packaged food conglomerates, PepsiCo Inc., The Coca-Cola Company, and Nestlé S.A. exemplify distinct strategic postures. PepsiCo Inc. occupies a position spanning carbonated drinks and snack adjacencies. The Coca-Cola Company anchors zero-sugar carbonated formulation expertise. Nestlé S.A. represents dairy and confectionery alternative specialization with clean-label architecture. Each sits within a tier where scale advantages in procurement and regulatory compliance create defensive positioning against mid-tier challengers.
| Leading Market Players |
|---|
| Mondelēz International Inc. |
| The Kraft Heinz Company |
| The Coca-Cola Company |
| Keurig Dr Pepper |
| Monster Beverage Corporation |
| PepsiCo Inc. |
| Mars Incorporated |
| Zevia |
| Nestlé S.A. |
| Others |
Supply Flow & Price Mechanics
Enzymatic bioconversion methods for steviol glycoside extraction are compressing input costs for natural sweeteners while simultaneously concentrating production capabilities among fermentation specialists in the United States, Brazil, and China. This technological transition rewards scale players with captive enzyme production capacity and squeezes mid-tier formulators dependent on spot-market stevia leaf procurement.
Pricing Analysis
Input-cost pass-through from corn-derived erythritol and stevia leaf biomass volatility shapes margin structures across formulation tiers. Three-tier pricing structure across premium, standard, and economy levels separates clean-label stevia-monk fruit blends from sucralose-based mass formulations and private-label artificial sweetener products. Pricing pressure stems from energy cost spikes affecting fermentation-based polyol production. Health-conscious millennials in coastal United States markets exhibit lowest price sensitivity, while price-conscious diabetic segments in pharmacy channels drive volume at compressed margins.
Supply Chain Analysis
Workforce availability constraints in Greater Atlanta and Dallas-Fort Worth contract manufacturing clusters are elevating labor costs for stevia-sweetened beverage production. Supply concentrates in the United States, Brazil, and Germany, with Brazilian stevia leaf cultivation, American enzymatic processing, and German erythritol fermentation anchoring upstream flows. Raw material dependencies include stevia leaf biomass, corn feedstock for polyols, and specialized enzyme cultures. Single-source vulnerability in Brazilian stevia leaf supply creates geographic concentration risk. Distribution runs through retail pharmacy channels at CVS Health and Walgreens alongside conventional supermarket slotting structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sugar free food and beverage market functions as a stable compounder, with FDA labeling mandates and WHO sugar reduction guidelines providing durable reformulation tailwinds that sustain multi-year growth visibility.
For Market Incumbents: Extend zero-sugar line architectures into adjacent snack and dairy categories before emerging direct-to-consumer brands capture pharmacy channel shelf resets. Acquire enzymatic bioconversion capabilities to secure captive steviol glycoside supply and defend margin position against erythritol price volatility. Lock in long-term stevia leaf offtake agreements with Brazilian cultivation cooperatives to preempt input cost spikes. For New Entrants and Emerging Players: Direct-to-consumer subscription models for personalized beverage bundles bypass retail slotting fees and enable trial-size sampling that reduces consumer risk. Target the athlete performance nutrition segment where sports nutrition specialty retailers and digital channels offer lower barriers to shelf access than conventional grocery. White-space exists in clean-label confectionery texture replication where technical barriers sustain premium pricing power. For Investors and Strategic Acquirers: Valuations sit cheapest among regional stevia extraction specialists with proven enzymatic bioconversion yields but limited brand distribution reach. Long-term viability framing centers on five-to-ten year regulatory harmonization across FDA, EFSA, and FSSAI jurisdictions that rewards early movers with compliant formulation libraries. Watch for EFSA novel food approval accelerations as inflection indicators for European market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Bioconversion Capacity Expansion | Captive steviol glycoside production locks in cost advantages against spot-market procurement volatility. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees and enables personalized zero-sugar product bundling at premium price points. |
| Pharmacy Channel Distribution Expansion | CVS Health and Walgreens shelf resets prioritize metabolic health positioning alongside diabetes management. |
| Clean-Label Confectionery Texture Innovation | Stevia-allulose blends achieving sensory parity unlock premium margin pools in European chocolate segments. |
| Regulatory Compliance Certification Investment | Early FSSAI reformulation pathway entry in India secures expedited approval for sugar-reduced product launches. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with formulation scientists at beverage conglomerates, procurement leads at stevia extraction facilities, regulatory affairs directors navigating FDA and EFSA pathways, and category buyers at CVS Health and Walgreens. Secondary validation drew from FDA GRAS notifications, EFSA novel food opinions, FSSAI reformulation guidelines, and Nielsen retail audit data. Bottom-up volume modeling and top-down market sizing triangulated to constrain estimate variance.
Comparable-period anchoring established baseline reference points across historical reformulation cycles and regulatory implementation phases. Segmentation dimensions modeled include product type, end-user demographic, ingredient source, and distribution channel alongside geographic regulatory cluster variations. CAGRs were derived from trend extrapolation adjusted for technology adoption curves and policy implementation timelines. Forecast inputs incorporated stevia leaf yield projections, enzyme cost decline trajectories, and pharmacy channel expansion rates.
The model assumes a particular technology adoption path; alternative pathways for allulose production scale-up or novel rare sugar commercialization would alter the outlook. Forecasts reflect assumptions regarding regulatory stance stability on artificial sweetener safety classifications and clean-label preference persistence. Material deviation in FDA enforcement intensity, EFSA evaluation timelines, or Brazilian stevia crop yields warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
South America Gluten Free Foods and Beverages Market
Food Intolerance Products
Celiac Disease Market
Food Intolerance Products
Food Allergy and Intolerance Products Market
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
Food Intolerance Products Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
North America Gluten-Free Food and Beverage Market
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Argentina Gluten-Free Food and Beverage Market
Food Intolerance Products
France Gluten-Free Food and Beverage Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
Allergen Free Food Products Market
Food Intolerance Products
Egg Allergy Market