
 Food Allergy Market | 2026-2036
Food Allergy Market Size, Share, and Industry Trends Forecast 2026-2036
Food Allergy Market Analysis
North American biopharmaceutical manufacturing capacity is broadening for oral immunotherapy and biologic production. Aimmune Therapeutics leverages its FDA-approved peanut allergy treatment platform to anchor commercial scale in the United States. Novartis Pharmaceuticals sustains deep R&D pipelines across immunology while Regeneron competes through monoclonal antibody development for allergic conditions.
Food allergy encompasses adverse immune-mediated reactions to dietary proteins, with IgE-mediated responses triggering histamine release within minutes of exposure and requiring precise diagnostic thresholds for clinical management. The condition serves industrial and commercial purposes through pharmaceutical intervention, specialized food manufacturing, and clinical diagnostic testing to prevent anaphylaxis and manage chronic sensitization. Allergen-free foods dominate product type revenue as established brands command shelf space across supermarkets and health food outlets, while online retailers represent the fastest-growing distribution channel as direct-to-consumer subscription models bypass traditional grocery intermediaries. Gluten-free ingredients lead ingredient type volume due to celiac disease overlap, though nut-free additives capture premium pricing from severe allergy risk management protocols.
FDA accelerated approval pathways compress development timelines for novel biologic therapies while EPA standards govern environmental allergen labeling in packaged goods and ISO 15189 accreditation requirements shape clinical laboratory diagnostic reliability. The EU F-Gas Regulation indirectly affects cold chain logistics for temperature-sensitive allergen extracts and biologics. Stakeholders must monitor how evolving FDA guidance on digital health tools for allergy monitoring intersects with reimbursement decisions from CMS and private payers.
Market Dynamics
FDA accelerated approval pathways compress development timelines for novel biologic therapies, while pediatric allergen immunotherapy programs expand across hospital systems. This regulatory velocity collides with manufacturing capacity constraints for temperature-sensitive allergen extracts.
Growth Catalysts
- Accelerated Approval Frameworks:FDA's streamlined pathways for biologic therapies reduce time-to-market for novel treatments. Allergy specialists gain earlier access to monoclonal antibody interventions.
- Pediatric Program Expansion:Hospital systems across the United States scale immunotherapy infrastructure for children. Early intervention protocols reshape long-term patient management economics.
- Specialist Clinic Density:Germany's reimbursement frameworks support advanced care adoption. Concentrated specialist infrastructure drives biologic penetration rates above regional peers.
Market Restraints
- Cold Chain Cost Volatility:Temperature-sensitive allergen extracts and biologics require continuous refrigeration. EU F-Gas Regulation compliance adds logistics complexity and energy cost exposure.
- Diagnostic Threshold Variability:IgE-mediated response measurement lacks universal standardization. Clinical laboratories face ISO 15189 accreditation pressure that fragments diagnostic reliability.
- Biologic Manufacturing Concentration:North American production capacity for oral immunotherapy remains limited to a handful of specialized facilities. Geographic supply concentration creates vulnerability to localized disruptions.
Strategic Opportunities
- Direct-to-Consumer Channels:Online retailers bypass traditional grocery intermediaries through subscription models. Allergen-free food brands capture margin expansion from disintermediation.
- Digital Health Integration:FDA guidance on allergy monitoring tools intersects with CMS reimbursement decisions. Connected devices for exposure tracking create new service revenue streams.
- Nut-Free Additive Premiumization:Severe allergy risk management protocols command pricing power for specialized ingredients. Food manufacturers reformulate around liability reduction.
Industry Challenges
- Allergy Specialist Workforce Constraints:Pediatric immunotherapy program expansion outpaces fellowship-trained clinician supply. Training pipeline limitations throttle service capacity growth.
- Cross-Contamination Certification Complexity:Allergen-free manufacturing facilities require dedicated production lines. Third-party audit timelines for gluten-free and nut-free claims extend facility commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Allergy Market |
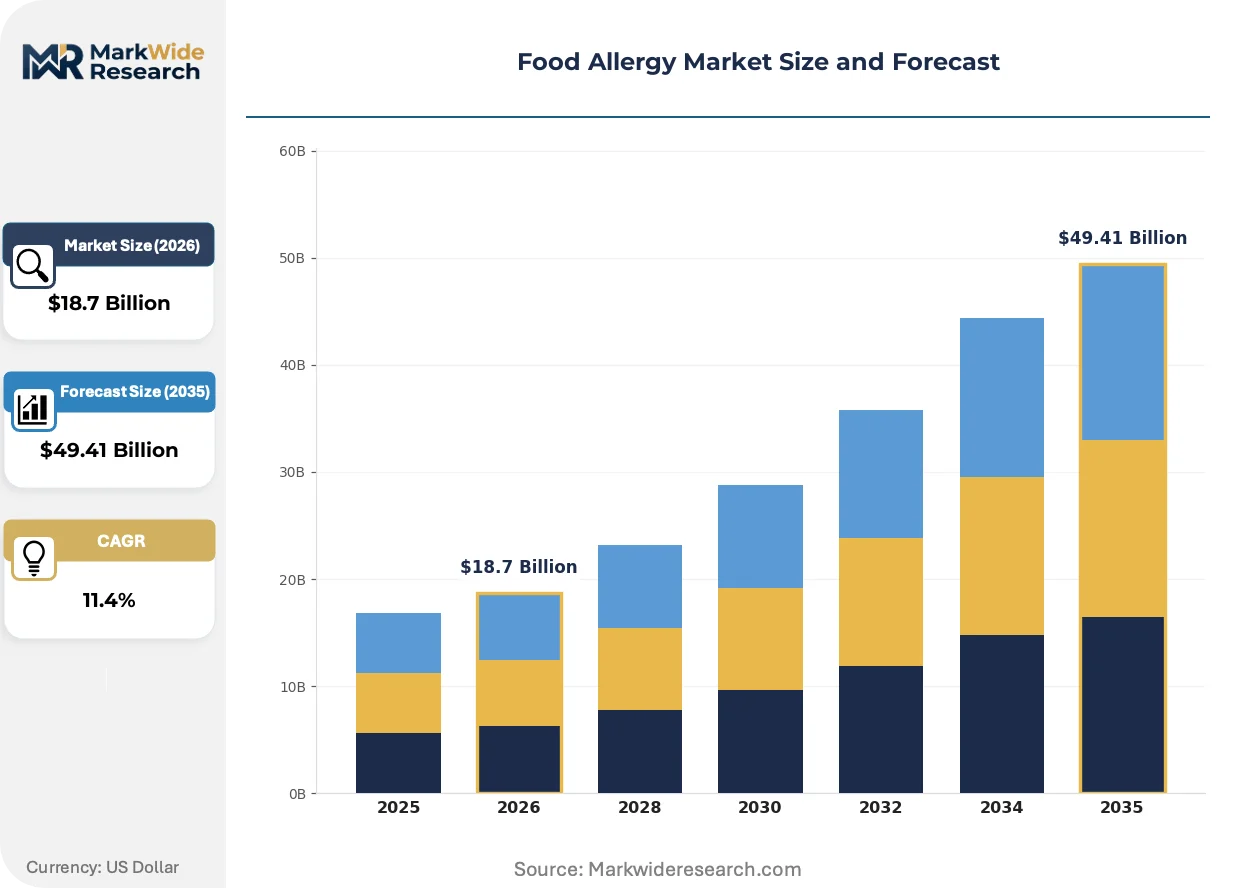
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Allergen-Free Foods, Cross-Contamination Safe Foods, Packaged Allergy-Friendly Snacks, Allergy-Safe Beverages End User: Healthcare Providers, Allergy Sufferers, Parents of Allergic Children, Schools and Educational Institutions Distribution Channel: Online Retailers, Specialty Food Stores, Supermarkets, Health Food Outlets Ingredient Type: Gluten-Free Ingredients, Dairy-Free Components, Nut-Free Additives, Soy-Free Substitutes |
| Companies Covered | Aimmune Therapeutics, Novartis Pharmaceuticals, Regeneron, DBV Technologies, Astellas Pharma, Allergy Therapeutics, Genentech, Thermo Fisher Scientific, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Allergy Market Emerging Trajectories
Oral immunotherapy protocols are absorbing clinical investment as biologic development accelerates. Regulatory frameworks and distribution models adapt to accommodate patient-administered desensitization versus clinic-based biologic infusion.
Epicutaneous immunotherapy patches are absorbing development resources from pharmaceutical manufacturers seeking reduced adverse event profiles. Pediatric allergists adopt these transdermal delivery systems for peanut desensitization protocols. The technology is absorbing liability concerns associated with oral challenge dosing, compressing the risk-adjusted cost structure of early intervention programs.
EMA's evolving guidance on allergen extract potency labeling is reshaping European manufacturing compliance requirements. Extract producers reformulate standardization protocols to meet batch consistency thresholds. Pediatric allergy clinics in Germany and France face inventory transition costs as legacy extract stocks deplete.
Subscription-based allergen-free meal delivery is displacing supermarket shelf reliance among severe allergy households. Direct channels capture patient data that informs personalized formulation development. This behavioral shift concentrates most visibly in urban United States markets where specialty logistics infrastructure supports cold chain requirements.
Food Allergy Market Segmentation
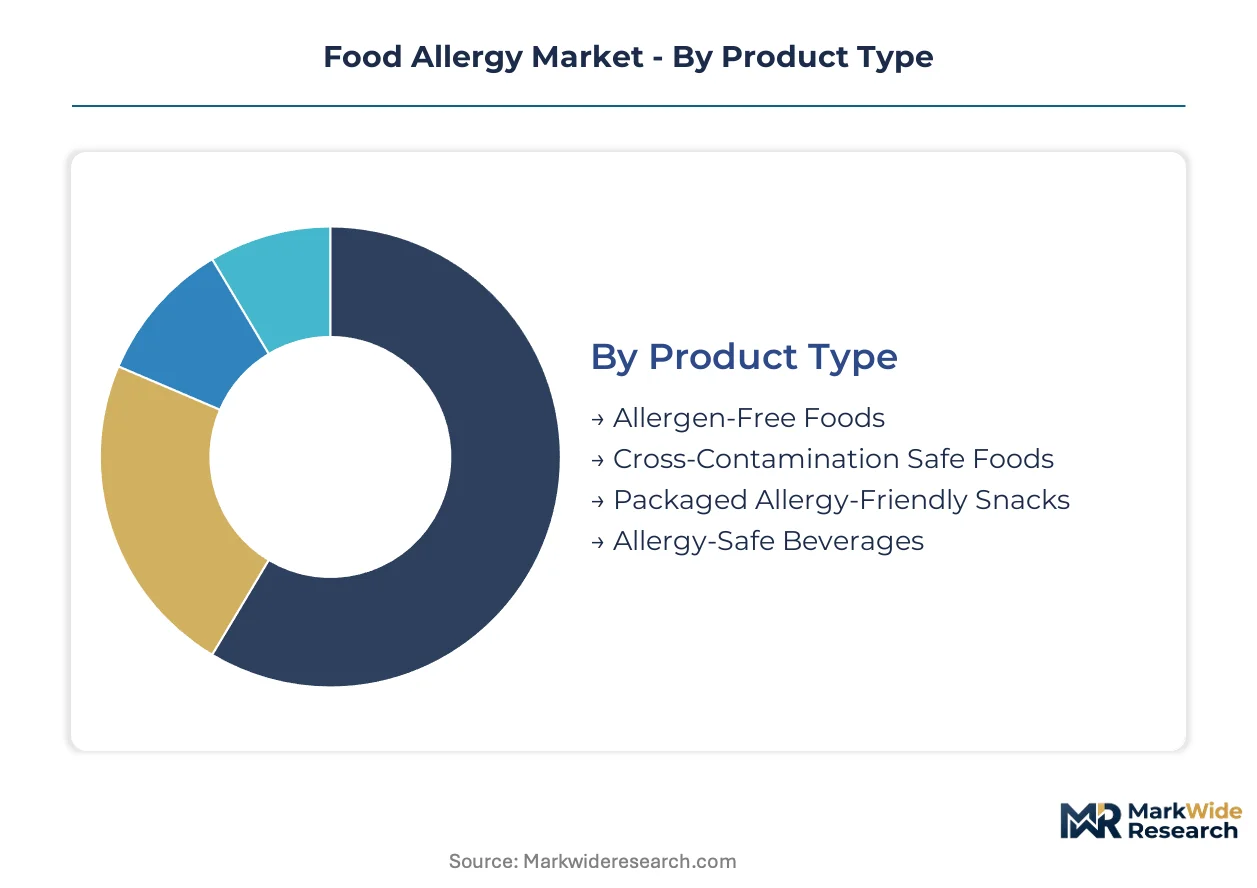
Food allergy market segmentation reflects divergent supply chain requirements between pharmaceutical interventions and specialized food manufacturing. Each category carries distinct regulatory burdens, cold chain dependencies, and patient safety protocols that reshape competitive positioning across value chains.
Product Type:
Formulation complexity and shelf stability requirements differentiate product tiers across manufacturing investment thresholds.
- Allergen-Free Foods:Dedicated production lines eliminate cross-contact risks through facility segregation. Established brands command retail shelf space across Germany and United States supermarkets while bearing third-party audit costs for certification maintenance.
- Cross-Contamination Safe Foods:Manufactured in shared facilities with validated cleaning protocols and allergen swab testing. Demand concentrates among parents of allergic children seeking lower-cost alternatives to dedicated-facility products.
- Packaged Allergy-Friendly Snacks:Single-serve formats dominate school lunch compliance requirements.
- Allergy-Safe Beverages:Plant-based milk alternatives lead volume within this segment.
Mature deployment sits with Allergen-Free Foods. Newer deployment is concentrated in Cross-Contamination Safe Foods.
End User:
Prescription authority and reimbursement access create divergent purchasing power across patient-facing stakeholders.
- Healthcare Providers:Hospitals and specialist clinics administer biologic therapies and oral immunotherapy under FDA oversight. Pediatric allergen immunotherapy program expansion across United States hospital systems is reshaping procurement volumes for allergen extracts.
- Allergy Sufferers:Direct purchasing of allergen-free foods and epinephrine auto-injectors. Subscription-based meal delivery adoption is climbing the fastest among urban households with multiple allergen restrictions.
- Parents of Allergic Children:Drive premium pricing for nut-free additives through liability-sensitive purchasing decisions.
- Schools and Educational Institutions:Bulk procurement of epinephrine stock and allergen-free meal programs.
Institutional procurement dominates volume. Individual purchasing commands margin expansion through direct channels.
Distribution Channel:
Cold chain capabilities and customer data capture differentiate channel economics for temperature-sensitive products.
- Online Retailers:Subscription models bypass traditional grocery intermediaries while capturing patient data for personalized formulation development. Direct-to-consumer channels are gaining share fastest among severe allergy households in United States urban markets.
- Specialty Food Stores:Curated assortments and staff expertise support premium pricing for newly diagnosed patients.
- Supermarkets:Allergen-free shelf space expansion reflects mainstream category maturation.
- Health Food Outlets:Historic channel for gluten-free ingredient pioneers.
Traditional retail maintains volume concentration. Digital channels capture steepest expansion trajectory through disintermediation.
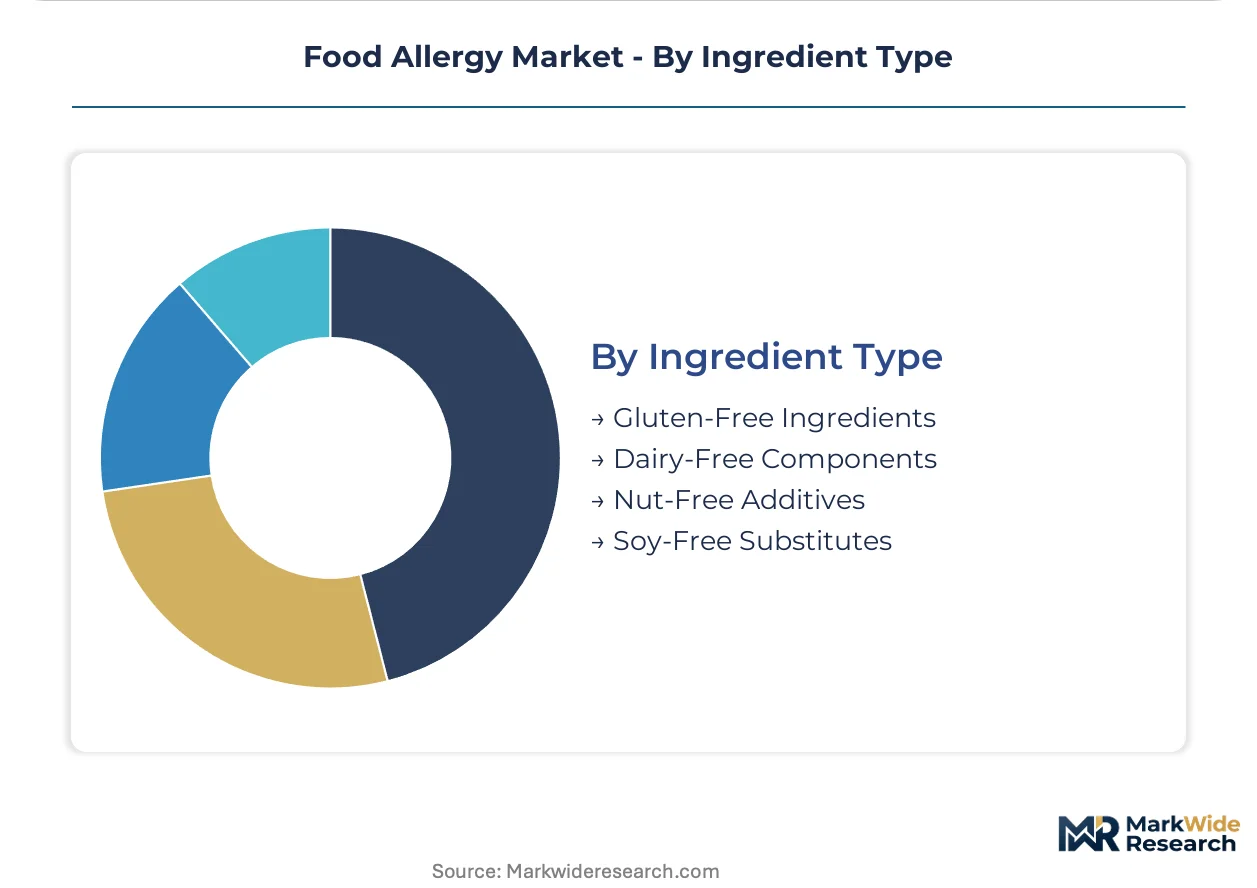
Ingredient Type:
Substitution chemistry and functional performance in baked goods determine manufacturing reformulation costs.
- Gluten-Free Ingredients:Rice flour and tapioca starch blends serve celiac disease overlap populations. Volume leadership reflects decades of formulation refinement across commercial baking applications.
- Nut-Free Additives:Sunflower seed and pumpkin seed butters command premium pricing from severe allergy risk management protocols. Food manufacturers reformulate around liability reduction in school and childcare settings.
- Dairy-Free Components:Oat and pea protein isolates replace casein and whey in infant nutrition.
- Soy-Free Substitutes:Chickpea and fava bean proteins address legume cross-reactivity concerns.
Commodity-scale deployment centers on Gluten-Free Ingredients. Premium reformulation investment targets Nut-Free Additives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peanut cultivation zones in Georgia and Alabama anchor North American allergen extract sourcing, while European pharmaceutical manufacturing clusters concentrate in Germany's Rhine-Main corridor and Switzerland's Basel region.
United States
Pediatric allergen immunotherapy programs expand across hospital systems in Texas, California, and New York. FDA accelerated approval pathways compress development timelines for biologic therapies. Aimmune Therapeutics anchors commercial scale in California's Bay Area biotech corridor.
Germany
Specialist allergy clinics concentrate in Bavaria and North Rhine-Westphalia, driving biologic penetration rates above regional peers. EU F-Gas Regulation compliance adds logistics complexity for temperature-sensitive allergen extracts. Frankfurt's pharmaceutical logistics hub supports cold chain distribution across Central Europe.
United Kingdom
NHS England funds specialist allergy centers in London, Manchester, and Birmingham. EMA guidance on allergen extract potency labeling reshapes manufacturing compliance for UK-based extract producers. Cambridge's biotech cluster absorbs venture capital for novel immunotherapy platforms.
Japan
PMDA reviews accelerate for epicutaneous immunotherapy patches targeting pediatric peanut desensitization. METI standards govern diagnostic device accuracy for IgE-mediated response measurement. Tokyo's university hospitals pilot digital health integration for allergy monitoring tools.
France
ANSM oversight shapes allergen-free food labeling requirements for gluten-free and nut-free product categories. Île-de-France hosts pharmaceutical manufacturing for oral immunotherapy formulations. Lyon clusters diagnostic laboratory capacity under ISO 15189 accreditation frameworks.
Food Allergy Market Vendor Landscape
Global majors compete with regional champions across biologic development and oral immunotherapy manufacturing. The vendor base stratifies between FDA-approved therapy platforms and specialized diagnostic equipment suppliers. Three archetypes dominate: biopharmaceutical developers with immunology pipelines, allergen extract manufacturers with cold chain expertise, and diagnostic instrument providers with clinical laboratory relationships. Capacity expansion and strategic partnerships represent the dominant competitive vectors as firms secure manufacturing scale and distribution reach.
Within the biopharmaceutical developer tier, Aimmune Therapeutics and Novartis Pharmaceuticals occupy positions exemplifying divergent scale strategies. Aimmune Therapeutics, a U.S.-based entity, anchors the oral immunotherapy segment through FDA-approved platforms. Novartis Pharmaceuticals, a Swiss-based AG, sustains deep R&D pipelines across immunology indications. Regeneron, a U.S.-based Inc., represents the monoclonal antibody development archetype for allergic conditions. These three entities collectively illustrate how geographic origin and corporate structure map to therapeutic modality specialization in this market.
| Leading Market Players |
|---|
| Aimmune Therapeutics |
| Novartis Pharmaceuticals |
| Regeneron |
| DBV Technologies |
| Astellas Pharma |
| Allergy Therapeutics |
| Genentech |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance gates qualified supply for temperature-sensitive allergen extracts and biologics, while simultaneously filtering premium-tier pricing access to manufacturers with validated cold chain infrastructure and third-party audit certifications.
Pricing Analysis
Service-bundling separates certified cold chain logistics from unbundled product-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and geographic delivery cost differentiation. Price compression in the standard tier intensifies because contract manufacturing capacity expansion outpaces specialized biologic demand. Hospital procurement committees exhibit highest price sensitivity, while parents of children with severe nut allergies demonstrate lowest sensitivity due to liability-driven purchasing protocols.
Supply Chain Analysis
Workforce availability constraints in California's Bay Area biotech corridor and Germany's Rhine-Main pharmaceutical cluster limit production scale-up for oral immunotherapy formulations. Supply concentrates in the United States, Germany, and Switzerland for biologic manufacturing, drawing from peanut cultivation zones in Georgia and Alabama for allergen extract sourcing. Single-source vulnerability pervades the temperature-controlled logistics segment. Distribution runs through hospital system procurement channels and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oral immunotherapy protocols are displacing legacy clinic-based biologic infusion models, compressing treatment economics and reshaping competitive entry points across patient-administered desensitization platforms.
For Market Incumbents: Lock in pediatric allergen immunotherapy program partnerships with United States hospital systems before fellowship-trained clinician supply constraints harden. Acquire cold chain logistics capabilities in Frankfurt's pharmaceutical hub to defend against EU F-Gas Regulation compliance cost escalation. Backward integration into allergen extract sourcing from Georgia cultivation zones secures input cost stability.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable channel for nut-free additive brands seeking to bypass established supermarket shelf allocation. Target urban United States households with multiple allergen restrictions through personalized formulation development informed by captured patient data. White-space exists in epicutaneous immunotherapy patch manufacturing for European markets awaiting EMA potency labeling guidance finalization.
For Investors and Strategic Acquirers: FDA accelerated approval pathway designations for pediatric biologic therapies are the leading indicator that monetization timelines for immunology pipelines are compressing. Acquisition target archetypes include allergen extract manufacturers with ISO 15189-accredited diagnostic laboratory relationships and validated cold chain infrastructure. Long-term viability hinges on portfolio exposure to patient-administered desensitization modalities rather than infusion-dependent biologic platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Pediatric oral immunotherapy protocols advance through FDA accelerated approval pathways. |
| Manufacturing Scale-Up | Bay Area biotech corridor expands production capacity for temperature-sensitive allergen extracts. |
| Regulatory Approval Pathway | EMA potency labeling guidance reshapes European extract standardization protocols. |
| Strategic Partnership | Hospital system alliances secure procurement volume for immunotherapy program expansion. |
| Direct-to-Consumer Launch | Subscription models capture margin expansion from grocery intermediary disintermediation. |
Methodological Framework
Independent corroboration across allergy specialist clinicians, hospital procurement managers, pharmaceutical regulatory affairs leads, and cold chain logistics operators underwrites the qualitative findings. Primary interviews with pediatric allergists and formulary directors combined with secondary validation from FDA filings, EMA submission databases, ClinicalTrials.gov records, and ISO 15189 accreditation registries. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Comparable historical reference periods spanning oral immunotherapy commercialization trajectories anchored the forecast window across the analysis window. Segmentation dimensions modeled include product type, end user category, distribution channel, and ingredient substitution chemistry. CAGRs derived from therapeutic modality adoption curves and reimbursement pathway velocity. Forecast inputs incorporated pediatric immunotherapy program expansion rates and digital health tool CMS reimbursement decision timelines.
Caveats apply where FDA guidance evolution on digital health monitoring tools or EU F-Gas Regulation enforcement intensity could materially shift the outlook. Forecasts reflect assumptions regarding specialist clinician training pipeline throughput and cold chain energy cost trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
Food Allergy and Intolerance Products Market
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Reduced Salt Food Products Market
Food Intolerance Products
Gluten-Free Pasta Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Low GI Food Market
Food Intolerance Products
Citrus-Derived Gastrointestinal Comfort Blends Market
Food Intolerance Products
Europe Gluten-Free Oats Market
Food Intolerance Products
Allergen Free Food Market
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
Argentina Gluten-Free Food and Beverage Market
Food Intolerance Products
Asia-Pacific Gluten-Free Breakfast Cereals Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
Food Intolerance Products Market
Food Intolerance Products
France Gluten-Free Food and Beverage Market