
 Natural Source Vitamin E Market | 2026-2036
Natural Source Vitamin E Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Source Vitamin E Market Intelligence
Supercritical CO2 extraction from deodorizer distillate is reconfiguring how natural tocopherol concentrates are refined and standardized for pharmaceutical-grade applications. Cargill Inc. leverages backward integration into oilseed processing to secure crude tocopherol feedstock at scale. DSM-Firmenich AG anchors its position through R&D intensity in lipid stabilization science. BASF SE differentiates via proprietary molecular distillation systems that yield high-purity alpha-tocopherol.
Natural source vitamin E comprises tocopherols and tocotrienols extracted from vegetable oils, with alpha-tocopherol exhibiting the highest biological activity at 1.36 IU per milligram and serving primarily as a lipid-soluble antioxidant in cellular membrane protection. Mixed tocopherols dominate volume due to broader functional utility across food preservation and feed applications, while alpha-tocopherol commands premium positioning in pharmaceutical and clinical nutrition segments where USP-grade certification is mandatory. Softgel capsules lead form-based revenue pools, though powder formats are gaining traction in fortified beverage applications.
EMA pharmacopeial standards and FDA dietary supplement cGMP rules jointly enforce identity testing and contaminant thresholds that determine market access for natural vitamin E imports into Europe and the United States. China's NMPA and SAMR regulate health food registration claims, constraining how domestic producers label tocopherol content for consumer products. Stakeholders must monitor evolving purity benchmarks from pharmacopeial harmonization initiatives and assess extraction technology investments against feedstock cost volatility in sunflower and soybean oil markets.
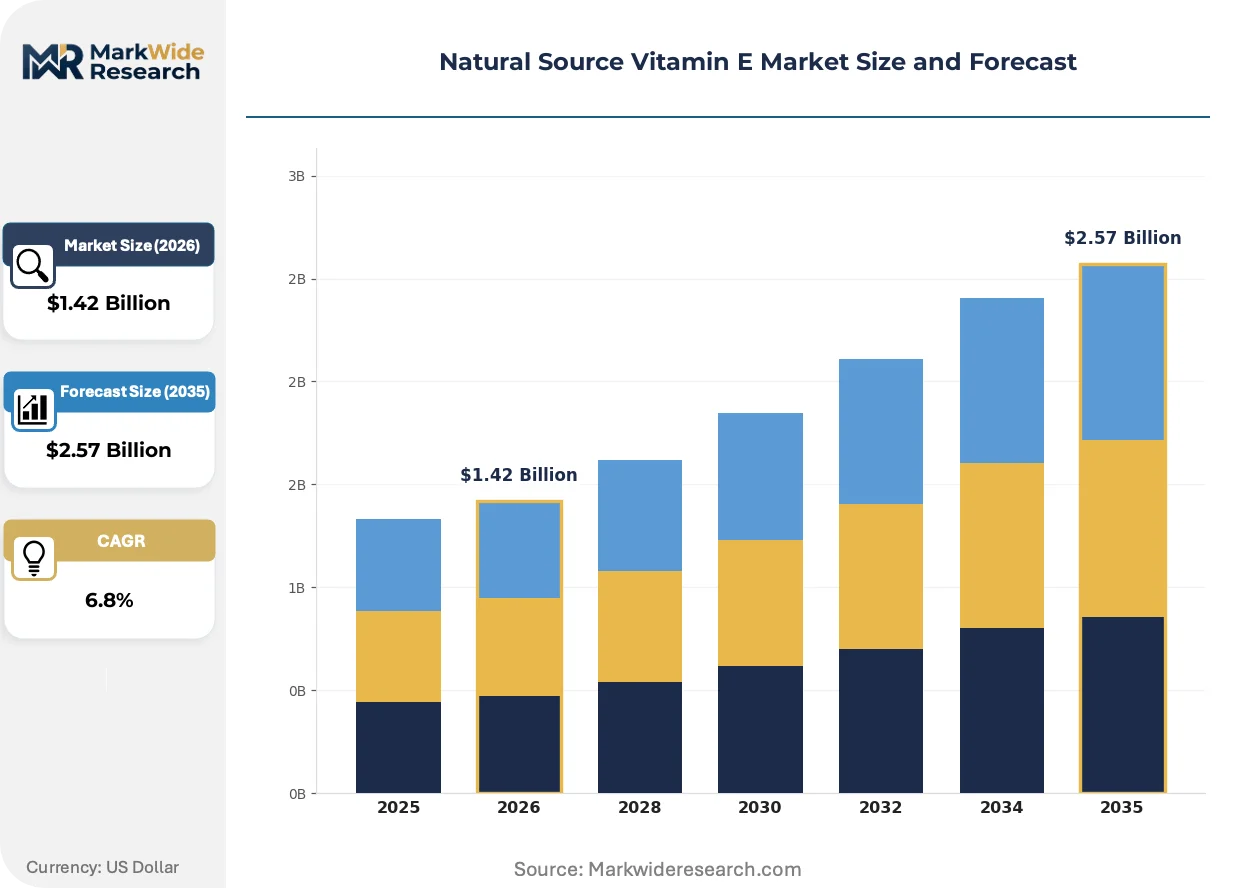
Market Dynamics
REACH authorization timelines and EU Green Deal additive restrictions are compressing synthetic vitamin E availability, redirecting formulation demand toward plant-derived tocopherol concentrates and restructuring procurement priorities across nutraceutical and food preservative supply chains.
Growth Catalysts
- REACH synthetic additive restrictions:ECHA's tightening authorization requirements for petrochemical-derived antioxidants are eliminating synthetic vitamin E from multiple food and cosmetic applications, forcing formulators toward deodorizer distillate-sourced tocopherols.
- Pharmaceutical-grade certification demand:USP-grade alpha-tocopherol requirements in clinical nutrition and parenteral emulsion applications are creating premium pricing tiers that justify supercritical CO2 extraction capital investments.
- Jiangsu-Zhejiang extraction cluster expansion:Chinese tocopherol concentrate capacity scaling in these provinces is reducing feedstock transportation costs and enabling just-in-time delivery to Asia-Pacific nutraceutical manufacturers.
Market Restraints
- Sunflower and soybean oil feedstock volatility:Crude vegetable oil price swings directly compress tocopherol concentrate margins, with deodorizer distillate supply tied to regional oilseed crush volumes.
- Alpha-tocopherol biological activity standardization:The 1.36 IU per milligram potency benchmark creates technical barriers for mixed tocopherol producers seeking pharmaceutical-grade positioning without molecular distillation infrastructure.
- EMA-FDA pharmacopeial divergence:Differing contaminant thresholds and identity testing protocols between European and American regulators force dual certification investments that burden mid-scale extractors.
Strategic Opportunities
- Fortified beverage powder formats:Water-dispersible tocopherol emulsions are opening new application vectors beyond traditional softgel capsules, with sports nutrition brands in Germany and the Netherlands piloting clean-label antioxidant fortification.
- EU Green Deal bio-based mandate alignment:Formulators achieving mass-balance certification for plant-derived vitamin E can access public procurement preferences and sustainability-linked financing instruments.
- Tocotrienol clinical research translation:Emerging neuroprotective and lipid-lowering efficacy data for gamma- and delta-tocotrienol isomers is creating R&D pipelines distinct from saturated alpha-tocopherol markets.
Industry Challenges
- Supercritical CO2 extraction specialist scarcity:Process engineers capable of optimizing tocopherol recovery rates from deodorizer distillate command premium compensation, constraining capacity expansion timelines for independent processors.
- SAMR health food registration complexity:China's dual-track regulatory pathway for tocopherol content claims requires 12-18 month approval cycles that delay product launches and tie up working capital in stability testing.
- Pharmacopeial harmonization uncertainty:Pending ISO alignment initiatives between USP, EP, and JP monographs create specification ambiguity that complicates multi-territory inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Source Vitamin E Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alpha-Tocopherol, Beta-Tocopherol, Gamma-Tocopherol, Delta-Tocopherol, Mixed Tocopherols Application: Dietary Supplements, Cosmetics & Personal Care, Food & Beverage Fortification, Pharmaceuticals End User: Supplement Manufacturers, Skincare Brands, Nutraceutical Companies, Pharmaceutical Firms Form: Oil, Softgel Capsules, Powder, Emulsions, Liquid Concentrate |
| Companies Covered | Cargill Inc., Zhejiang Medicine Co., Archer Daniels Midland Company, Merck KGaA, Brenntag AG, BASF SE, Wilmar International Ltd., ExcelVite Inc., DSM-Firmenich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Source Vitamin E Market Strategic Shifts & Innovations
Extraction technology maturation and regulatory chemistry restrictions are converging to elevate natural tocopherol positioning, with process innovation and certification differentiation emerging as the primary vectors for margin defense.
Supercritical CO2 extraction systems are migrating from batch-operated pilot configurations to continuous-flow industrial installations capable of processing multi-ton deodorizer distillate volumes daily. Pharmaceutical-grade alpha-tocopherol producers in Switzerland and Germany are adopting these units to achieve 99%+ purity without thermal degradation. The capital intensity of this migration from conventional molecular distillation is compressing viable participation to processors with backward integration into oilseed crushing or long-term feedstock offtake agreements.
EU Green Deal chemical sustainability criteria are systematically disqualifying synthetic antioxidant additives from organic-labeled food products and clean-positioned cosmetics. EFSA's updated guidance on tocopherol additive specifications now explicitly favors vegetable-derived sources in novel food assessments. Nutraceutical brands targeting European supermarket pharmacy channels are reformulating around natural tocopherol concentrates to preempt regulatory exclusion from premium shelf placements.
Direct-procurement relationships between nutraceutical finished-product manufacturers and tocopherol concentrate processors are displacing traditional distributor intermediaries in high-volume supplement categories. German and Dutch brands with certified sustainability programs now source mixed tocopherols through audited supply agreements rather than spot-market purchasing. This channel consolidation concentrates volume with extraction specialists capable of providing batch-specific carbon footprint documentation and mass-balance chain-of-custody verification.
Natural Source Vitamin E Market Segmentation
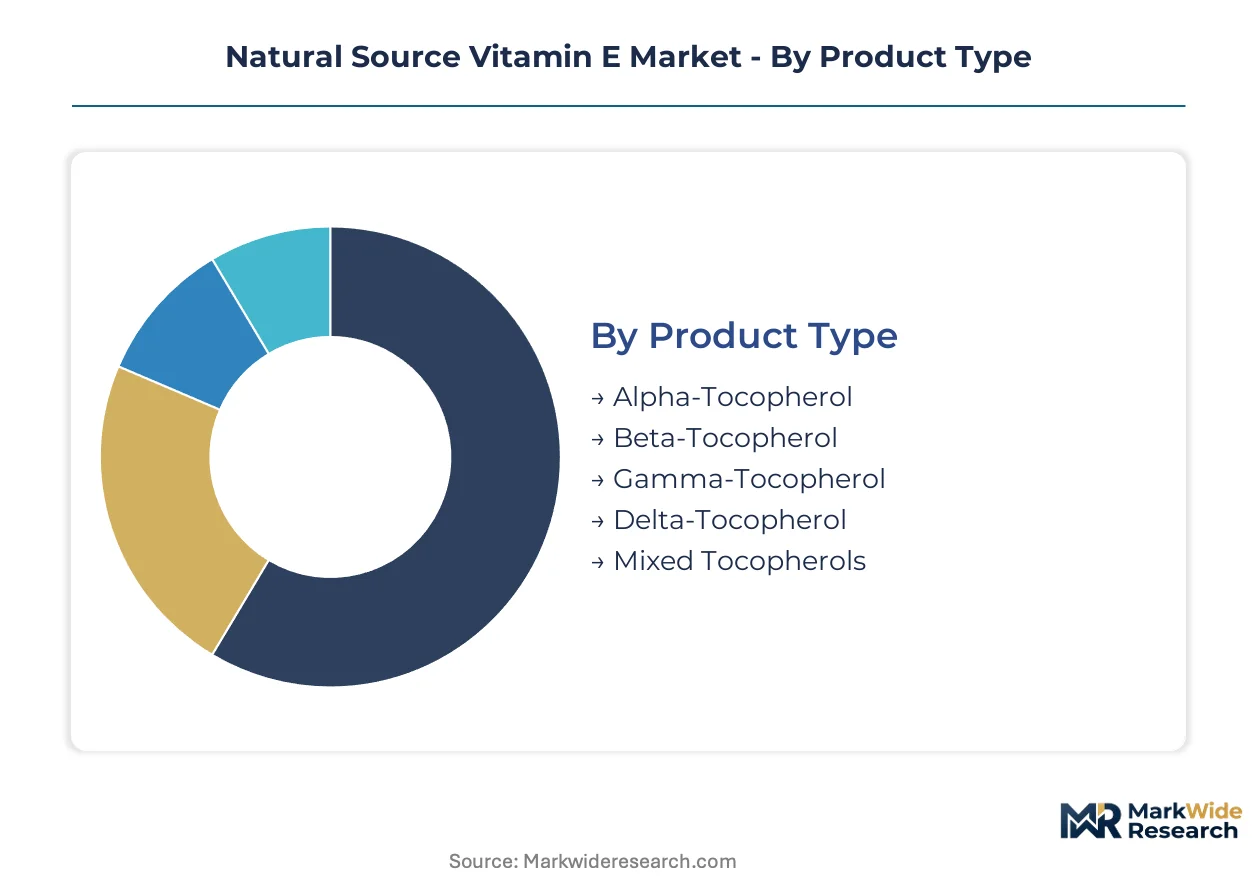
Segmentation in the natural source vitamin E market reveals how extraction technology investments and pharmacopeial certification requirements create distinct competitive arenas. Each dimension—product chemistry, application specification, end-user procurement patterns, and delivery format—carries unique margin structures and regulatory barriers that determine supplier viability.
Product Type:
After-sales service intensity varies sharply across tocopherol isomers, with pharmaceutical-grade alpha-tocopherol requiring batch-specific stability documentation and technical support that commodity mixed tocopherol buyers rarely demand.
- Alpha-Tocopherol:This isomer delivers the highest biological activity at 1.36 IU per milligram and commands USP-grade certification for clinical nutrition and parenteral emulsion applications. German and Swiss pharmaceutical manufacturers concentrate procurement here, driven by EMA pharmacopeial standards that mandate identity testing and contaminant thresholds for injectable formulations.
- Mixed Tocopherols:Broader functional utility spans food preservation and feed applications, with deodorizer distillate-sourced concentrates replacing synthetic antioxidants under REACH authorization pressures. Nutraceutical companies in Germany expanding premium supplement lines represent the fastest-expanding demand cluster for standardized mixed tocopherol concentrates.
- Beta-Tocopherol:Minor constituent in natural extracts with limited standalone commercialization, primarily recovered as co-product in alpha-tocopherol purification streams.
- Gamma-Tocopherol:Predominant form in soybean oil deodorizer distillate, valued for food antioxidant applications where nitrogen radical scavenging properties exceed alpha-tocopherol performance.
- Delta-Tocopherol:Lowest molecular weight tocopherol with superior oxidative stability in high-temperature food processing, increasingly specified by clean-label preservative formulators.
By volume, mixed tocopherols lead. By growth pace, alpha-tocopherol is ahead.
Application:
Cost tier stratification separates commodity food additive volumes from premium pharmaceutical and clinical nutrition segments where certification investments justify 3-5x pricing multiples.
- Dietary Supplements:Softgel capsules dominate revenue, though powder formats gain traction in fortified beverage applications. German and Dutch sports nutrition brands pilot clean-label antioxidant fortification using water-dispersible tocopherol emulsions.
- Pharmaceuticals:Parenteral emulsions and clinical nutrition formulations require USP-grade alpha-tocopherol with supercritical CO2 extraction achieving 99%+ purity. Swiss and German producers anchor supply through proprietary molecular distillation and continuous-flow CO2 systems.
- Cosmetics & Personal Care:EU Green Deal chemical sustainability criteria systematically disqualify synthetic antioxidants from organic-labeled products, redirecting formulators toward deodorizer distillate-sourced tocopherols with mass-balance certification.
- Food & Beverage Fortification:EFSA updated guidance explicitly favors vegetable-derived sources in novel food assessments, compressing synthetic vitamin E availability across European supermarket channels.
Pharmaceuticals capture the steepest margin expansion trajectory. Dietary supplements maintain the largest absolute volume position.
End User:
Procurement patterns diverge between spot-market purchasers and direct-audited supply agreements, with sustainability-program brands consolidating volume through chain-of-custody verified relationships.
- Nutraceutical Companies:German firms expanding mixed tocopherol procurement for premium supplement lines represent the most active demand segment, requiring batch-specific carbon footprint documentation.
- Pharmaceutical Firms:Dual certification investments for EMA-FDA pharmacopeial convergence burden mid-scale extractors, concentrating supply relationships with backward-integrated processors.
- Supplement Manufacturers:Direct-procurement relationships with tocopherol concentrate processors displace traditional distributor intermediaries in high-volume categories.
- Skincare Brands:Clean-positioned cosmetics brands reformulate around natural tocopherol concentrates to preempt regulatory exclusion from premium European shelf placements.
Pharmaceutical firms pay the highest unit prices. Nutraceutical companies are expanding procurement fastest.
Form:
Application flexibility determines format selection, with oil and softgel formats defending established positions while powder and emulsion formats open new vector penetration.
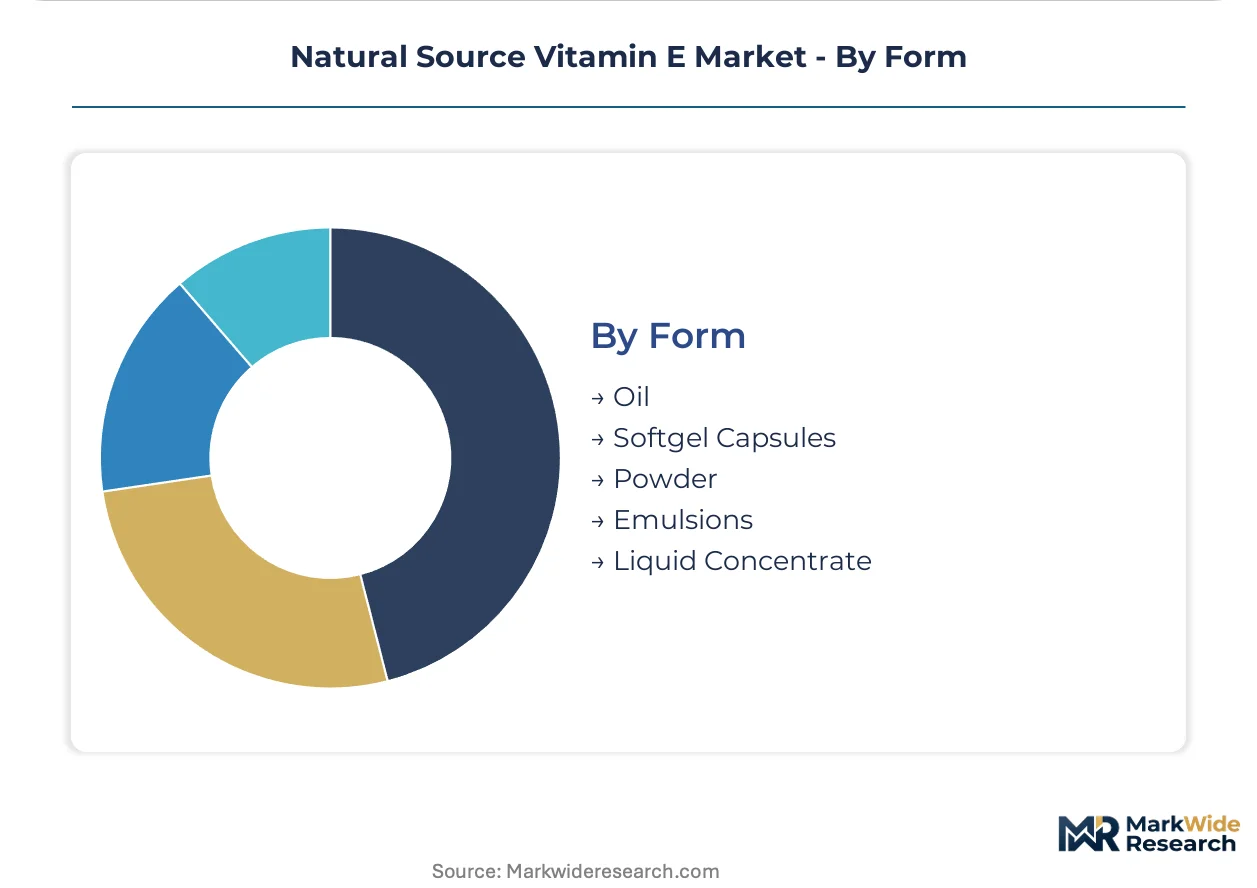
- Softgel Capsules:Lead form-based revenue pools through established dietary supplement positioning, with encapsulation technology investments creating switching costs for finished-product manufacturers.
- Powder:Water-dispersible tocopherol emulsions enable fortified beverage applications beyond traditional delivery formats, with sports nutrition brands in Germany and the Netherlands driving pilot adoption.
- Oil:Standard delivery format for food preservation and feed applications, with tocopherol concentrate blending into vegetable oil carriers for ease of handling.
- Emulsions:Specialized water-dispersible systems requiring additional processing investment, specified where homogeneity in aqueous matrices is mandatory.
- Liquid Concentrate:Bulk intermediate format for downstream formulation, with purity grades ranging from technical feed-grade to pharmaceutical specification.
Softgel capsules dominate current revenue. Powder formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports tocopherol concentrates to Germany and the Netherlands, where REACH restrictions have eliminated synthetic vitamin E from premium nutraceutical formulations. This trade corridor now handles the majority of deodorizer distillate-derived supply for European pharmaceutical and supplement manufacturers.
Germany
Nutraceutical companies in Germany are expanding procurement of mixed tocopherols for premium supplement lines. ECHA's tightening REACH authorization requirements for petrochemical-derived antioxidants are redirecting formulators toward plant-derived alternatives. The country's oilseed processing hubs in Lower Saxony and North Rhine-Westphalia are developing backward integration into crude tocopherol feedstock supply.
China
Demand is concentrating in Jiangsu and Zhejiang provinces, where tocopherol extraction capacity has scaled significantly. SAMR's dual-track regulatory pathway for health food registration claims constrains domestic product launches, pushing concentrate output toward export markets. These coastal provinces now host continuous-flow supercritical CO2 installations capable of pharmaceutical-grade alpha-tocopherol production.
United States
FDA dietary supplement cGMP rules enforce identity testing and contaminant thresholds that determine market access for natural vitamin E imports. Softgel capsule manufacturers in New Jersey and California represent the largest absolute demand for USP-grade alpha-tocopherol. The country's sunflower oil crush volumes in North Dakota directly influence deodorizer distillate feedstock availability for domestic extractors.
Switzerland
Swiss pharmaceutical manufacturers anchor European demand for parenteral emulsion-grade alpha-tocopherol requiring 99%+ purity. Swissmedic pharmacopeial standards align with EMA requirements, creating certification efficiency for multi-territory suppliers. Basel and Zurich host extraction specialists with proprietary molecular distillation systems serving clinical nutrition formulators.
Netherlands
Dutch sports nutrition brands are piloting clean-label antioxidant fortification using water-dispersible tocopherol emulsions. EFSA's updated guidance on tocopherol additive specifications explicitly favors vegetable-derived sources in novel food assessments. Rotterdam's port infrastructure enables just-in-time delivery of Chinese tocopherol concentrates to European finished-product manufacturers.
Natural Source Vitamin E Market Key Industry Players
On the supply side, the industry is consolidating around extraction specialists with backward integration into oilseed processing or long-term feedstock offtake agreements. The capital intensity of continuous-flow supercritical CO2 systems compresses viable participation to processors with scale advantages or captive supply. Two strategic archetypes dominate: backward-integrated agricultural conglomerates securing crude tocopherol from oilseed crush operations, and pharmaceutical-grade specialists investing in molecular distillation infrastructure. Competitive moves concentrate on direct-procurement relationship formation and mass-balance certification achievement for EU Green Deal alignment.
Among the backward-integrated agricultural processors, Cargill Inc., Archer Daniels Midland Company, and Wilmar International Ltd. occupy positions securing feedstock access at scale. Within the pharmaceutical-grade extraction tier, DSM-Firmenich AG and BASF SE exemplify specialists with proprietary purification systems. Zhejiang Medicine Co. represents the Chinese extraction cluster scaling capacity in Jiangsu and Zhejiang provinces. These named entities serve as anchors for understanding how technology investment and regulatory certification create tiered competitive positioning across commodity and premium market segments.
| Leading Market Players |
|---|
| Cargill Inc. |
| Zhejiang Medicine Co. |
| Archer Daniels Midland Company |
| Merck KGaA |
| Brenntag AG |
| BASF SE |
| Wilmar International Ltd. |
| ExcelVite Inc. |
| DSM-Firmenich AG |
| Others |
Cost & Logistics Intelligence
Undercapacity in continuous-flow supercritical CO2 extraction systems across European pharmaceutical-grade processors is compressing spot-market availability and amplifying pricing power for backward-integrated suppliers with captive deodorizer distillate access. REACH authorization timelines and EU Green Deal additive restrictions are simultaneously eliminating synthetic vitamin E alternatives, tightening the supply-demand balance and forcing formulators into long-term offtake negotiations rather than transactional purchasing.
Pricing Analysis
Prior-generation molecular distillation systems now trade at 30-40% discounts to continuous-flow supercritical CO2 installations, creating a three-tier pricing structure across premium, standard, and economy levels. USP-grade alpha-tocopherol certification and mass-balance chain-of-custody documentation drive price differentiation between pharmaceutical and commodity food-grade concentrates. Pricing pressure stems from sunflower and soybean oil feedstock volatility, with deodorizer distillate costs tracking regional oilseed crush volumes. Nutraceutical finished-product manufacturers exhibit highest price sensitivity due to reformulation flexibility, while parenteral emulsion formulators show lowest sensitivity given regulatory lock-in.
Supply Chain Analysis
Deodorizer distillate feedstock draws from oilseed crushing operations concentrated in China, Germany, and the United States, with Jiangsu-Zhejiang extraction clusters now processing multi-ton daily volumes. Crude tocopherol concentrates, pharmaceutical-grade alpha-tocopherol, and water-dispersible emulsion intermediates constitute the critical input dependencies. Single-source vulnerability runs through Chinese supercritical CO2 extraction specialist scarcity, where process engineers command premium compensation and constrain capacity expansion timelines. Distribution runs through direct-procurement relationships displacing traditional distributor intermediaries, with Rotterdam and Hamburg ports enabling just-in-time delivery to European finished-product manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized process engineering talent capable of optimizing tocopherol recovery rates from deodorizer distillate has become the binding constraint on capacity expansion, with fewer than two dozen engineers globally qualified for continuous-flow supercritical CO2 system commissioning. This scarcity concentrates margin capture with extraction specialists already possessing operational expertise.
For Market Incumbents: Pre-empt synthetic vitamin E displacement by accelerating mass-balance certification achievement for EU Green Deal alignment before EFSA guidance hardens into mandatory specifications. Secure long-term feedstock offtake agreements with oilseed crushers in Lower Saxony and North Rhine-Westphalia to defend margin position against Chinese Jiangsu-Zhejiang cluster expansion. Prioritize supercritical CO2 extraction capacity additions over molecular distillation investments to maintain pharmaceutical-grade positioning. For New Entrants and Emerging Players: Fortified beverage powder formats in German and Dutch sports nutrition represent the most penetrable white-space target, with water-dispersible tocopherol emulsions piloting clean-label antioxidant fortification ahead of mainstream adoption. Tocotrienol clinical research translation offers a second entry vector distinct from saturated alpha-tocopherol markets. Pursue audited supply agreements with certified sustainability-program brands rather than spot-market participation to bypass incumbent distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade extraction specialists with proprietary molecular distillation systems and multi-territory EMA-FDA certification infrastructure. Long-term viability across the projection horizon favors processors with backward integration into oilseed crushing or captive deodorizer distillate supply. Monitor SAMR health food registration approval velocity as the inflection indicator for Chinese domestic demand absorption versus export market flooding. Cross-checking against NMPA registration database trends is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Continuous-flow installations achieve 99%+ alpha-tocopherol purity for Swiss and German pharmaceutical manufacturers. |
| Backward Integration into Oilseed Crushing | Cargill and ADM secure crude tocopherol feedstock at scale through captive deodorizer distillate supply. |
| Mass-Balance Certification Achievement | EU Green Deal alignment unlocks public procurement preferences and sustainability-linked financing instruments. |
| Direct-Procurement Relationship Formation | German nutraceutical brands consolidate volume through audited supply agreements with batch-specific carbon footprint documentation. |
| Tocotrienol Clinical Research Pipeline | Gamma- and delta-tocotrienol neuroprotective efficacy data creates R&D positioning distinct from saturated alpha-tocopherol markets. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EMA pharmacopeial standards, FDA dietary supplement cGMP guidance, and REACH authorization databases to establish regulatory constraint boundaries. Extraction technology specialists, nutraceutical procurement directors, pharmaceutical formulation scientists, and oilseed crushing operations managers provided operational validation. Bottom-up capacity modeling across Jiangsu-Zhejiang extraction clusters triangulates against top-down demand segmentation by application and form factor.
Forecast inputs span tocopherol isomer purity grades, delivery format adoption curves, and end-user procurement pattern shifts across the analysis window. Segmentation dimensions include product chemistry (alpha-tocopherol versus mixed tocopherols versus tocotrienols), application specification (pharmaceutical, dietary supplement, food preservation, cosmetics), and regional regulatory cluster (EMA-FDA convergence, SAMR dual-track pathway, Swissmedic alignment). CAGRs derive from feedstock cost trajectory modeling and extraction technology diffusion curves.
Practitioners should monitor pharmacopeial harmonization uncertainty between USP, EP, and JP monographs for early signals of specification ambiguity affecting multi-territory inventory planning. Forecasts reflect assumptions regarding sunflower and soybean oil price stability and supercritical CO2 extraction specialist labor market elasticity. Cross-checking against ECHA authorization timeline announcements and SAMR registration approval databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
Food Grade Vitamin C Market
Vitamin Fortified
Vitamin B Complex Market
Vitamin Fortified
Esterified Vitamins Market
Vitamin Fortified
Global Mineral Fortification Market
Vitamin Fortified
Calcium-Fortified Food Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Enriched Flour Market
Vitamin Fortified
Food Grade Vitamin B1 Market
Vitamin Fortified
Fortified Food Market
Vitamin Fortified
Global Vitamin Tonics Market
Vitamin Fortified
Vitamin B12 Drops Market
Vitamin Fortified
Vitamin D3 Oil Market
Vitamin Fortified
Multivitamin Gummies Market