
 Food Intolerance Products Market | 2026-2036
Food Intolerance Products Market Size, Share, and Industry Trends Forecast 2026-2036
Food Intolerance Products Market Intelligence
The food intolerance products sector is recalibrating around a widening gap between premium certified-clean-label offerings and commodity-positioned free-from alternatives. Nestlé S.A. leverages its dairy science heritage to dominate lactose-free infant nutrition and adult beverage lines across European retail. Dr. Schär AG/SPA anchors its competitive position through dedicated gluten-free manufacturing facilities and pharmacy-channel distribution that sustains premium pricing power. General Mills, Inc. competes in North American mass retail by extending its mainstream cereal and snack brands into certified gluten-free variants with scaled production economics.
Food intolerance products comprise formulated foods and beverages engineered to exclude specific allergens or difficult-to-digest compounds—primarily gluten, lactose, nuts, and added sugars—through ingredient substitution, enzymatic hydrolysis, or dedicated processing lines that prevent cross-contact below threshold levels. These products serve clinical dietary management for diagnosed conditions, preventive consumption by self-identified sensitive individuals, and lifestyle positioning among health-motivated buyers seeking digestive comfort or metabolic control. Gluten-free product lines occupy the largest revenue pool given celiac disease prevalence and broad consumer familiarity, while lactose-free dairy alternatives command the fastest expansion as enzymatic lactase treatment and plant-based fermentation technologies improve taste parity and nutritional equivalence. Sugar-free formulations targeted at diabetic and ketogenic diet adherents represent a concentrated margin segment where clean-label sweetener blends differentiate premium positioning from mass-market alternatives.
The FDA enforces gluten-free labeling standards at 20 parts per million maximum content, while the EU's Food Information for Consumers Regulation mandates allergen bold-type disclosure and quantitative ingredient declaration that shapes formulation transparency across export-bound production. Health Canada and FSANZ in Australia maintain parallel strictures on precautionary allergen labeling that influence multinational product architecture and limit single-formula geographic deployment. Stakeholders must monitor evolving thresholds for novel proteins and fermented ingredients as regulators reassess tolerance benchmarks and as enzymatic processing creates new molecular structures with uncertain allergenicity profiles.
Market Dynamics
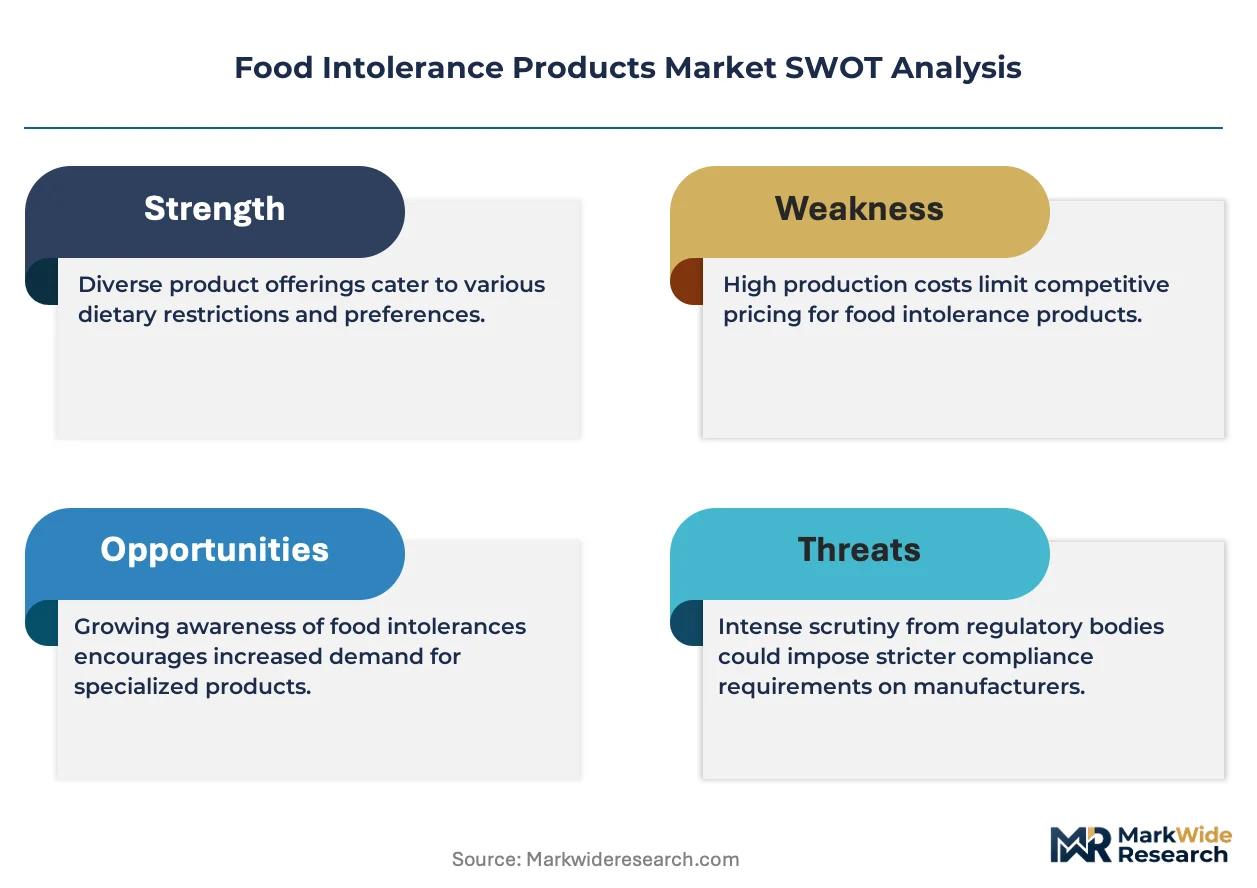
Enzymatic processing breakthroughs are compressing formulation costs while tightening clean-label certification standards across multiple jurisdictions, forcing manufacturers to choose between scaled commodity production and premium pharmacy-channel positioning.
Growth Catalysts
- FDA Gluten-Free Labeling Standards:The 20 parts per million threshold creates enforceable product differentiation that supermarket retailers use to rationalize shelf space allocation toward certified suppliers.
- Enzymatic Lactase Hydrolysis:Advanced immobilized enzyme reactors cut lactose-free dairy processing costs by half, enabling taste parity with conventional milk in German and French retail channels.
- Pharmacy Distribution Networks:Dr. Schär AG/SPA's dedicated gluten-free manufacturing and pharmacy-channel penetration in Italy and Spain sustains premium pricing power through clinical credibility.
Market Restraints
- Specialty Ingredient Cost Volatility:Tapioca starch and rice protein concentrate prices swing with Thai and Indian harvest cycles, squeezing margins on gluten-free bakery formulations.
- Supply Concentration in Enzyme Manufacturing:Novozymes and DuPont Nutrition command captive positions in food-grade lactase and transglutaminase supply, creating input dependency for mid-tier processors.
- EU Precautionary Allergen Labeling:The Food Information for Consumers Regulation's mandatory bold-type disclosure requirements complicate multi-market packaging standardization and inflate label redesign costs.
Strategic Opportunities
- Brazilian Retail Modernization:ANVISA's evolving allergen framework and expanding supermarket private-label programs create first-mover advantages for certified exporters establishing local blending facilities.
- Ketogenic Diet Sugar-Free Formulations:Allulose and monk fruit sweetener blends targeting diabetic and low-carbohydrate adherents command 40% gross margins in North American specialty retail.
- Direct-to-Consumer Subscription Channels:Personalized intolerance testing kits paired with curated product boxes bypass retail slotting fees and capture lifetime value through recurring revenue models.
Industry Challenges
- Cross-Contact Prevention Certification:Third-party gluten-free and allergen-free audits require dedicated production lines that idle conventional capacity, stretching capital deployment timelines for contract manufacturers.
- Legacy ERP Integration:Lot-level traceability systems for enzymatic processing parameters and ingredient provenance clash with decades-old dairy and bakery plant control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Intolerance Products Market |
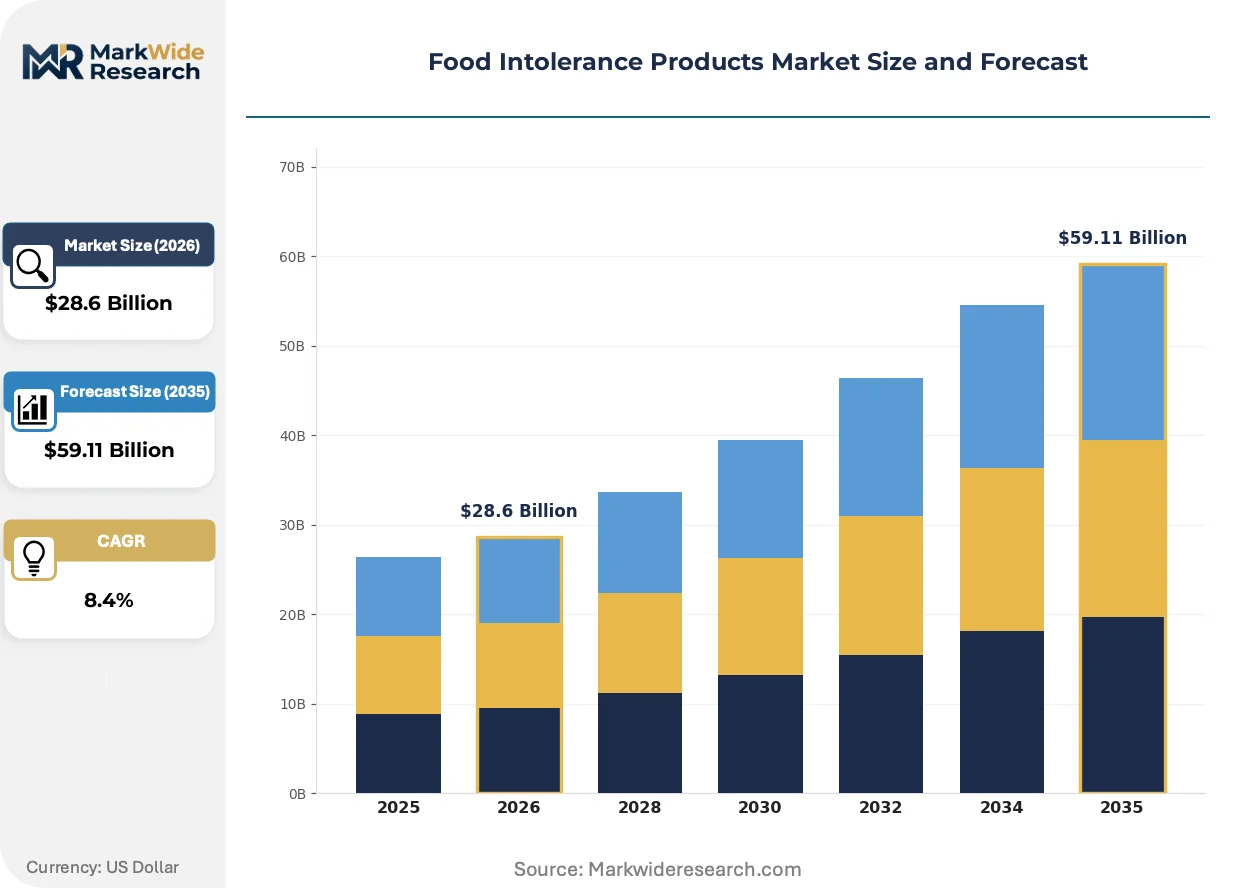
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Lactose-Free, Nut-Free, Sugar-Free End User: Individuals, Health-Conscious Consumers, Athletes, Families Delivery Mode: Online, Retail, Subscription, Direct Sales Packaging Type: Bottles, Boxes, Pouches, Tubs |
| Companies Covered | Abbott Laboratories, Conagra Brands, Inc., Nestlé S.A., Amy's Kitchen Inc., Dr. Schär AG/SPA, Danone S.A., The Hain Celestial Group, Inc., Kellogg Company, General Mills, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Intolerance Products Market Strategic Shifts & Innovations
Clean-label enzyme alternatives and precision fermentation are displacing chemical processing aids while regulatory disclosure mandates reshape competitive transparency across formulation science.
Immobilized enzyme reactor systems for lactose hydrolysis and gluten proteolysis are automating continuous-flow processing that cuts batch-to-batch variation. Mid-sized dairy processors in the Netherlands and Denmark are retrofitting existing pasteurization lines with plug-in enzymatic modules. This automation compresses quality-control labor costs while enabling real-time adjustment of hydrolysis depth for customized lactose residual levels.
The EU's Food Information for Consumers Regulation mandates quantitative ingredient declaration and bold-type allergen labeling that exposes formulation shortcuts previously obscured by generic descriptors. Manufacturers exporting to Germany, France, and Italy must reformulate or split product architectures to meet diverging national interpretations of "may contain" precautionary statements. The bakery segment faces the steepest compliance costs as composite ingredient suppliers resist transparency on sub-component allergen profiles.
Health-conscious buyers in supermarket channels are prioritizing certified-clean-label positioning over price-driven free-from alternatives, compressing demand for commodity-positioned products. German and Austrian retailers now demand third-party gluten-free certification as a listing prerequisite, displacing uncertified private-label suppliers. This preference shift concentrates shelf space with vertically integrated manufacturers controlling dedicated allergen-free production infrastructure.
Food Intolerance Products Market Segmentation
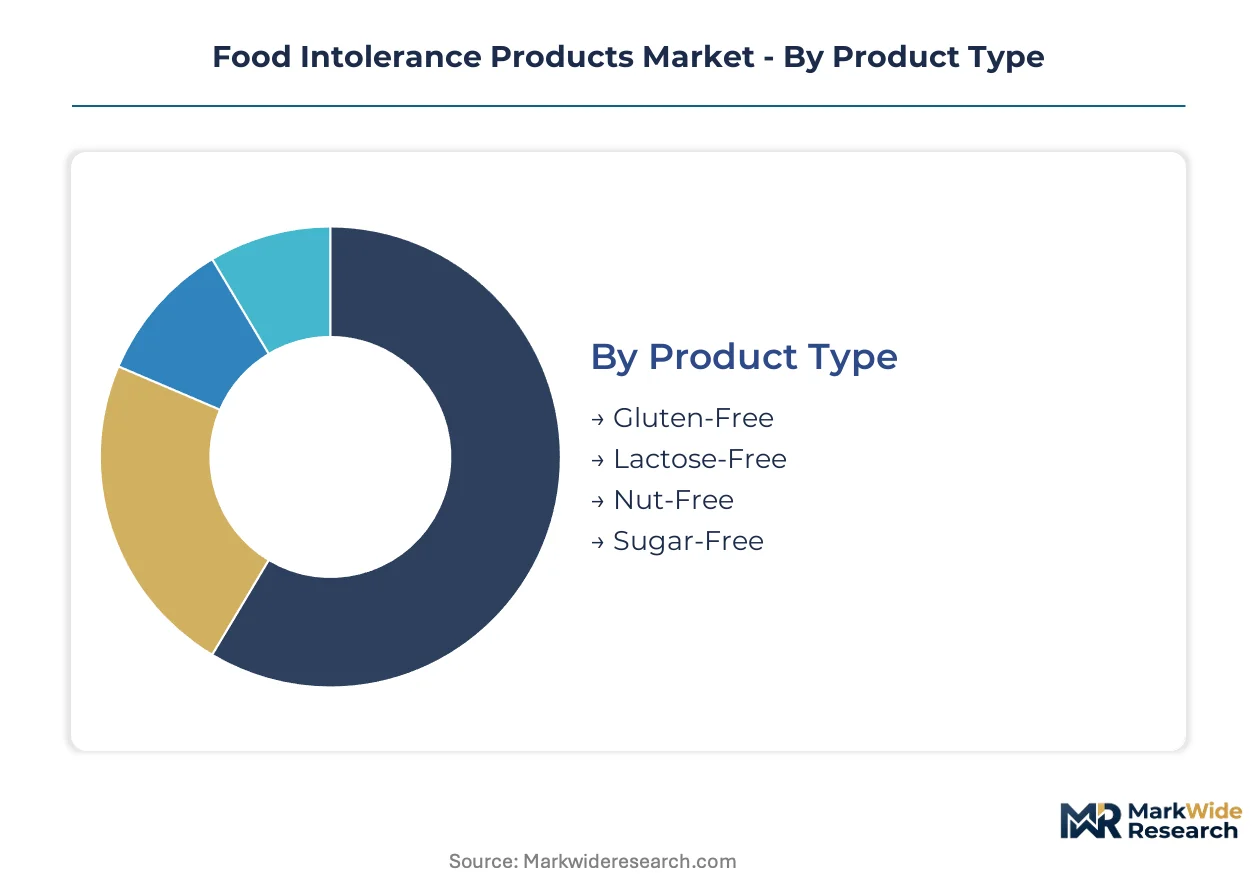
Food intolerance product manufacturers must align formulation architecture with distinct consumption occasions and purchase pathways. Segmentation reveals where enzymatic processing investments and certification spending yield differentiated returns across patient populations and retail channels.
Product Type:
Consumer upgrade cycles from commodity free-from alternatives toward certified-clean-label formulations are compressing shelf space for uncertified suppliers.
- Gluten-Free:Formulations exclude wheat, barley, and rye proteins through ingredient substitution or enzymatic proteolysis, with residual gluten held below 20 parts per million. German and Austrian supermarket retailers now mandate third-party certification as a listing prerequisite, displacing uncertified private-label competitors.
- Lactose-Free:Dairy products treated with immobilized lactase enzymes hydrolyze lactose into glucose and galactose, achieving taste parity with conventional milk. Advanced reactor systems in the Netherlands and Denmark have cut processing costs by half, accelerating retail penetration in French and German channels.
- Nut-Free:Dedicated production lines prevent cross-contact with tree nuts and peanuts through segregated ingredient handling and airborne particle control.
- Sugar-Free:Diabetic and ketogenic diet formulations utilize allulose, monk fruit, and erythritol blends to replace sucrose without glycemic impact.
Volume placements concentrate in Gluten-Free; the faster expansion belongs to Lactose-Free.
End User:
Cost-tier stratification separates clinical dietary management from lifestyle-oriented consumption, with reimbursement pathways and retail premiums diverging sharply.
- Individuals:Diagnosed celiac disease and lactose intolerance patients require strict allergen avoidance with documented threshold compliance.
- Health-Conscious Consumers:Self-identified sensitive individuals prioritize digestive comfort and clean-label positioning over price minimization. This segment commands premium pricing in German supermarket channels where certified products sustain 15-25% shelf price premiums.
- Athletes:Sports nutrition applications demand rapid glycemic control and gastrointestinal tolerance during high-intensity training.
- Families:Household purchasing decisions balance multiple intolerance profiles across children and adults, favoring multi-allergen-free product lines.
Health-Conscious Consumers capture the steepest margin tier; Individuals provide the most predictable recurring volume.
Delivery Mode:
Channel fragmentation is forcing manufacturers to maintain parallel inventory systems for retail slotting fees versus direct fulfillment economics.
- Online:E-commerce platforms enable personalized intolerance testing kits paired with curated subscription boxes, bypassing retail slotting fees.
- Retail:Supermarket and pharmacy channels dominate in Italy and Spain where Dr. Schär AG/SPA sustains premium positioning through clinical credibility.
- Subscription:Recurring revenue models capture lifetime value through automated replenishment of specialized formulations.
- Direct Sales:Healthcare practitioner and clinic channels serve diagnosed patients with prescription-linked dietary protocols.
Retail maintains volume dominance; Subscription channels are climbing the fastest.
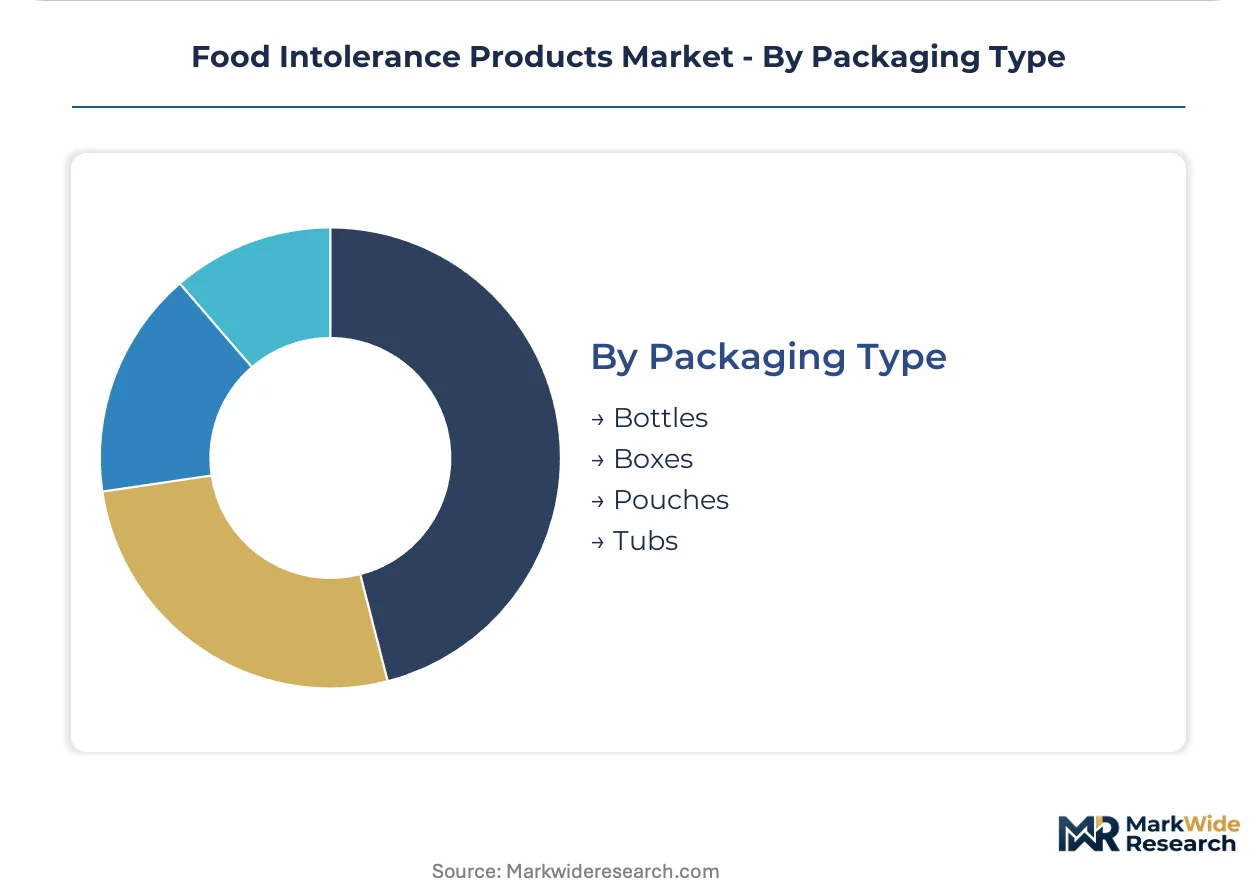
Packaging Type:
Packaging format selection tracks consumption occasion segmentation, with portability requirements and portion control driving material innovation.
- Bottles:Liquid dairy alternatives and ready-to-drink beverages utilize aseptic filling for extended shelf stability.
- Boxes:Dry bakery mixes and cereal products require moisture barriers and structural integrity for supply chain handling.
- Pouches:Flexible films reduce material cost and shipping weight for snack and convenience formats.
- Tubs:Rigid containers serve spreads, yogurts, and refrigerated dough with resealability for multi-use occasions.
Boxes lead in shipment volume; Pouches are gaining share fastest in convenience-oriented segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan anchors European food intolerance product manufacturing through Dr. Schär AG/SPA's dedicated gluten-free facilities and pharmacy-channel distribution networks that sustain premium pricing across Italian and Spanish retail.
Germany
German supermarket retailers now mandate third-party gluten-free certification as a listing prerequisite, displacing uncertified private-label competitors. The EU's Food Information for Consumers Regulation shapes formulation transparency through bold-type allergen disclosure requirements. Bavaria's enzymatic processing infrastructure in Munich-Stuttgart corridors enables taste parity between lactose-free and conventional dairy products.
United States
FDA's 20 parts per million gluten-free labeling threshold creates enforceable product differentiation that supermarket retailers exploit for shelf space rationalization. Health Canada maintains parallel strictures on precautionary allergen labeling that influence North American product architecture. Chicago and Minneapolis-based dairy processors deploy immobilized lactase reactors to cut processing costs and expand retail penetration.
France
French retail channels accelerate adoption of certified allergen-free formulations as health-conscious consumers prioritize clean-label positioning over price minimization. ANSM enforces pharmaceutical-grade standards for clinical nutrition products distributed through pharmacy networks. Paris-Lyon manufacturing corridors concentrate enzymatic hydrolysis capacity for lactose-free dairy alternatives.
Italy
Italian pharmacy distribution networks sustain premium pricing power for clinically positioned gluten-free products through prescription-linked dietary protocols. EFSA guidelines on novel protein allergenicity reshape formulation pipelines for fermented ingredients. Bologna's food technology cluster advances enzymatic processing innovations for gluten proteolysis applications.
Netherlands
Dutch dairy processors retrofit existing pasteurization lines with plug-in enzymatic modules that automate continuous-flow lactose hydrolysis. REACH compliance requirements influence ingredient substitution patterns for clean-label enzyme alternatives. Rotterdam-Amsterdam logistics corridors enable efficient distribution of certified allergen-free formulations across northwest European retail channels.
Food Intolerance Products Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification-grade and distribution-channel dimensions. The market structures around three tiers: multinational consumer goods conglomerates with scaled production economics, dedicated allergen-free specialists with captive manufacturing infrastructure, and private-label suppliers competing on retail slotting fees. Strategic moves concentrate on backward integration into enzyme supply and geographic licensing partnerships that bypass capital-intensive facility construction.
Within the dedicated specialist tier, Dr. Schär AG/SPA exemplifies pharmacy-channel positioning through clinically credible distribution networks. Nestlé S.A. and General Mills, Inc. occupy positions representing scaled commodity production and brand extension strategies respectively. These three anchors illustrate divergent pathways for capturing value across certification-grade segmentation.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Conagra Brands, Inc. |
| Nestlé S.A. |
| Amy's Kitchen Inc. |
| Dr. Schär AG/SPA |
| Danone S.A. |
| The Hain Celestial Group, Inc. |
| Kellogg Company |
| General Mills, Inc. |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between third-party validated gluten-free formulations and uncertified free-from alternatives manifests in parallel supply chain architectures—dedicated allergen-free production lines command 40-60% capital premiums over shared facilities, while commodity-positioned suppliers absorb margin compression from volatile tapioca starch and rice protein concentrate inputs.
Pricing Analysis
Outcome-based pricing anchored to clinical dietary compliance and digestive tolerance outcomes stratifies the market across premium pharmacy-channel positioning and mass retail commodity tiers. Three-tier pricing structure across certified-clean-label, retailer-certified, and uncertified economy levels reflects differential investment in third-party audits and dedicated manufacturing infrastructure. Pricing pressure stems from enzymatic processing cost compression in lactose-free dairy, where immobilized reactor systems have halved conversion expenses. Health-conscious consumers in German supermarket channels exhibit lowest price sensitivity, while private-label buyers in discount retail demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Novozymes and DuPont Nutrition's captive positions in food-grade lactase and transglutaminase supply, creating input dependency for mid-tier processors lacking backward integration into enzyme manufacturing. Tapioca starch sourcing concentrates in Thailand, rice protein concentrate in India, and enzymatic processing equipment in Denmark and the Netherlands. Tariff exposure on specialty ingredient imports from Southeast Asian harvest cycles generates margin volatility for gluten-free bakery formulators. Distribution runs through supermarket retail channels in Germany and France, pharmacy networks in Italy and Spain, and direct-to-consumer subscription platforms capturing recurring revenue models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's 20 parts per million gluten-free labeling threshold and the EU's Food Information for Consumers Regulation construct a cost-of-compliance barrier that entrenches vertically integrated incumbents while forcing marginal private-label suppliers toward uncertified economy positioning.
For Market Incumbents: Acquire dedicated allergen-free manufacturing facilities to consolidate pharmacy-channel premium positioning against emerging contract manufacturers with retrofit capabilities. Nestlé S.A.'s dairy science heritage and Dr. Schär AG/SPA's gluten-free infrastructure demonstrate how captive production lines sustain pricing power under tightening EU precautionary allergen labeling mandates. Capacity addition in Bavaria's Munich-Stuttgart enzymatic processing corridor defends margin position against Dutch and Danish dairy processor expansion. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription channels paired with personalized intolerance testing kits to bypass retail slotting fees and capture lifetime value through automated replenishment. Brazilian retail modernization under ANVISA's evolving allergen framework represents the most penetrable geography, with expanding supermarket private-label programs creating first-mover advantages for certified exporters establishing local blending facilities. Ketogenic diet sugar-free formulations utilizing allulose and monk fruit blends offer the clearest white-space target in North American specialty retail. For Investors and Strategic Acquirers: Re-rating potential sits with dedicated allergen-free specialists possessing pharmacy-channel distribution networks and third-party certification infrastructure, given accelerating EU regulatory disclosure mandates and German retailer listing prerequisites. Long-term viability favors manufacturers with backward integration into enzymatic processing capabilities and multi-allergen-free product line breadth serving family purchasing decisions. The signal to watch is ANVISA's final allergen framework implementation in Brazil, which will determine capital deployment timelines for export-oriented blending facility investments.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy-Channel Distribution Expansion | Dr. Schär AG/SPA's Italian and Spanish networks demonstrate premium pricing power through clinical credibility. |
| Immobilized Enzyme Reactor Deployment | Dutch and Danish dairy processors cut lactose-free processing costs by half through continuous-flow automation. |
| Third-Party Certification Investment | German retailers now mandate gluten-free certification as a listing prerequisite, displacing uncertified competitors. |
| Direct-to-Consumer Subscription Launch | Personalized testing kits paired with curated product boxes bypass retail slotting fees and capture recurring revenue. |
| Brazilian Local Blending Facility Establishment | ANVISA's evolving allergen framework creates first-mover advantages for certified exporters in expanding retail channels. |
Research Approach
Multi-period observation of enzymatic processing cost curves, certification penetration rates, and pharmacy-channel pricing premiums anchored the trend analysis, supplemented by interviews with food intolerance product brand managers, supermarket category buyers, enzymatic processing equipment suppliers, regulatory affairs specialists at multinational dairy and bakery manufacturers, and pharmacy distribution network managers. Secondary validation drew from FDA gluten-free labeling guidance documents, EU Food Information for Consumers Regulation implementation reports, EFSA novel protein allergenicity assessments, ANVISA regulatory filings, and customs trade data on tapioca starch and rice protein concentrate flows. Bottom-up segment sizing triangulated against top-down market aggregation.
Segment-weighting across product type, end user archetype, delivery mode, and packaging format dimensions structured the analytical framework, with enzymatic processing technology adoption curves and clean-label certification penetration serving as industry-specific forecast inputs. CAGRs were derived from trajectory fitting across the projection horizon, with cross-validation against historical elasticity patterns in German and French retail channels. Volume and value outputs reflect iterative reconciliation between supply-side capacity assessments and demand-side consumption occasion modeling.
Regulatory threshold revisions, harvest cycle volatility in Thai and Indian specialty ingredient sourcing, and competitive entry by contract manufacturers with shared-facility retrofit capabilities are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on certification adoption timelines and pharmacy-channel margin sustainability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Lactose Free Products Market
Food Intolerance Products
Allergen Free Food Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market
Food Intolerance Products
Fermented Garlic and Onion Digestive Comfort Bases Market
Food Intolerance Products
Gluten Free Malt Extracts Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Lactose-Free Food Market
Food Intolerance Products
Dyspepsia Market
Food Intolerance Products
Food Allergy and Intolerance Products Market
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
Europe Gluten Free Foods and Beverages Market
Food Intolerance Products
Australia Gluten Free Food Market