
 Asia-Pacific Gluten-Free Breakfast Cereals Market | 2026-2036
Asia-Pacific Gluten-Free Breakfast Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Gluten-Free Breakfast Cereals Market Outlook
Australia's FSANZ gluten-free labeling standard is decoupling informal breakfast cereal trade from formal retail channels. General Mills Inc. leverages its supply chain infrastructure to distribute certified oats across Australian and Japanese supermarkets. Nestlé S.A. anchors its regional portfolio through specialized production lines that exclude cross-contamination protocols. Nature's Path Foods Inc. differentiates through organic ingredient sourcing that commands premium positioning in health food stores.
Asia-Pacific gluten-free breakfast cereals are processed grain formulations containing less than 20 parts per million gluten, manufactured through dedicated milling and extrusion equipment to prevent cross-contact with wheat, barley, or rye. These products serve celiac patients, health-conscious consumers, and fitness enthusiasts seeking digestible morning nutrition without triggering autoimmune responses. Oats dominates product type volumes due to established consumer familiarity and versatile formulation compatibility across hot and ready-to-eat applications. Online retail represents the fastest-expanding distribution channel as urban consumers in India and Southeast Asia bypass traditional supermarket infrastructure for direct-to-doorstep subscription models. Health-conscious consumers anchor end-user demand, though celiac patient segments sustain higher per-unit spending on certified medical-grade formulations.
Japan's Consumer Affairs Agency enforces strict allergen labeling that elevates compliance costs for imported cereal brands. China's SAMR and National Health Commission regulate gluten-free health claims through functional food registration pathways that delay market entry. India's FSSAI has proposed tighter gluten threshold definitions that would reshape domestic manufacturing standards and import certification requirements. Stakeholders must monitor regulatory divergence across these three frameworks when allocating product development and localization investments.
Market Dynamics
Australia's FSANZ gluten-free labeling standard is decoupling informal breakfast cereal trade from formal retail channels, forcing manufacturers to retool milling infrastructure and recertify supply chains to maintain shelf access in Australian and Japanese supermarkets.
Growth Catalysts
- FSANZ gluten-free labeling enforcement:Australia's strict ppm thresholds are compelling regional manufacturers to upgrade dedicated production lines, creating compliant product flows that unlock premium retail placement across Melbourne and Sydney.
- Metro corridor demand concentration:Health food stores and online retail channels in India's Delhi-Mumbai-Bangalore corridor are expanding shelf space for certified oats and quinoa formats, pulling volume through direct-to-doorstep subscription models.
- Extrusion equipment modernization:Dedicated milling infrastructure that eliminates cross-contact with wheat, barley, or rye is enabling consistent sub-20 ppm output that satisfies both celiac patients and fitness enthusiasts.
Market Restraints
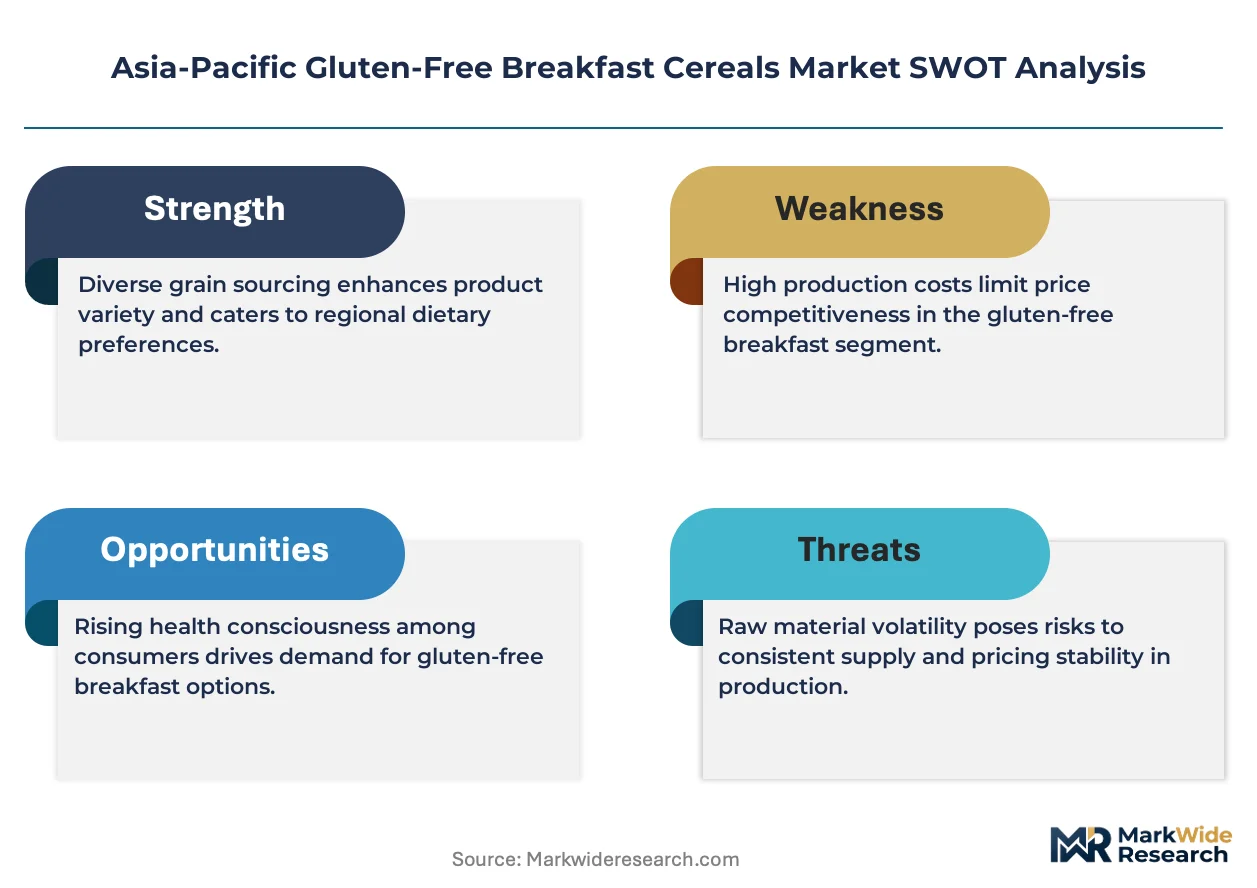
- Input cost volatility:Certified gluten-free oat premiums fluctuate with Australian and Canadian harvest yields, compressing margin structures for regional formulators dependent on imported grain.
- Regulatory friction:China's SAMR functional food registration pathways delay market entry by 18-24 months for brands seeking gluten-free health claims, freezing revenue recognition timelines.
- Technical limitation:Sensory profile gaps in sorghum and millet bases limit formulation flexibility compared to wheat analogs, constraining product range expansion in taste-sensitive segments.
Strategic Opportunities
- Underpenetrated Southeast Asian corridors:Indonesia and Vietnam health food retail remains nascent, offering first-mover positioning for certified organic lines ahead of local supply chain maturation.
- Regulatory tailwind:India's proposed FSSAI gluten threshold tightening would reshape domestic manufacturing standards, advantaging early compliance investments by imported and locally milled alternatives.
- Technology convergence:Near-infrared spectroscopy paired with blockchain traceability is automating real-time gluten detection and supply chain verification, reducing batch rejection rates.
Industry Challenges
- Certification timeline compression:Japan's Consumer Affairs Agency allergen labeling audits require 6-9 month validation cycles that stall product launches and tie up working capital.
- Skill gap in dedicated facility management:Shortage of technicians trained in HACCP protocols for gluten-free environments limits production scale-up across Australian contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Gluten-Free Breakfast Cereals Market |
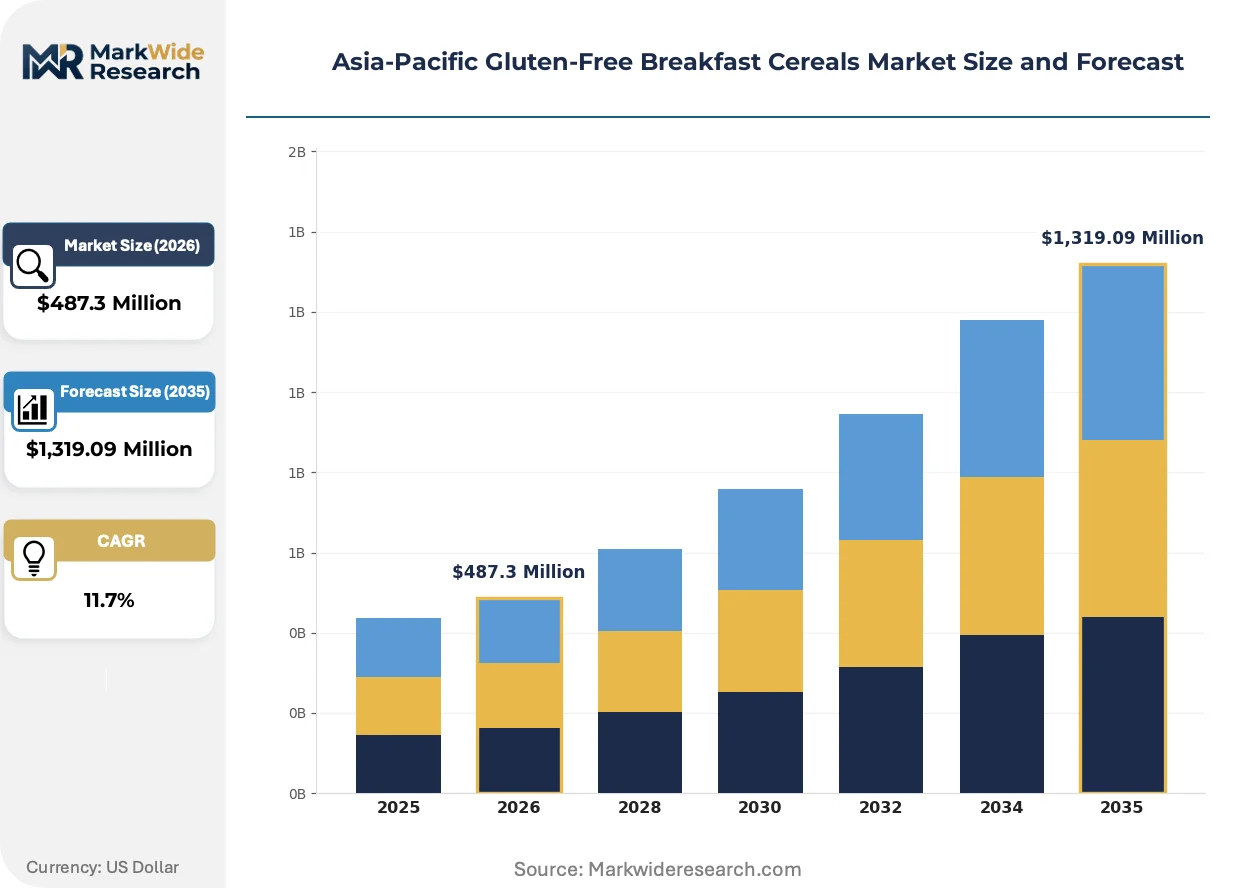
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oats, Cornflakes, Rice Flakes, Quinoa Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Convenience Stores End User: Health-Conscious Consumers, Celiac Patients, Fitness Enthusiasts, Families Ingredient Source: Organic, Non-GMO, Local Sourcing, Imported |
| Companies Covered | General Mills Inc., Kellogg Company, Nestlé S.A., PepsiCo Inc., Bob's Red Mill Natural Foods Inc., Post Holdings Inc., Mondelez International Inc., Nature’s Path Foods Inc., B&G Foods Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Gluten-Free Breakfast Cereals Market Strategic Shifts
Three interconnected shifts are restructuring how gluten-free breakfast cereals reach Asia-Pacific consumers: automation of quality assurance, regulatory divergence creating compliance complexity, and subscription commerce bypassing traditional retail infrastructure.
Near-infrared spectroscopy integrated into extrusion lines is automating real-time gluten contamination detection at sub-5 ppm sensitivity. Australian contract manufacturers are deploying these systems to satisfy FSANZ audit requirements without offline laboratory delays. This automation is compressing batch release timelines from 72 hours to 4 hours, enabling just-in-time replenishment for supermarket private label programs.
Japan's Consumer Affairs Agency is tightening cross-contamination disclosure rules for imported cereal products, elevating documentation burdens for brands sourcing from shared facilities. Manufacturers must now submit third-party audit certificates covering entire supply chains from farm to finished goods. Australian and New Zealand exporters face the steepest compliance cost escalation, forcing portfolio pruning toward dedicated-facility suppliers.
Subscription commerce is displacing supermarket impulse purchasing among urban Indian and Southeast Asian households. Direct-to-doorstep models bundle certified oats with nutritional consulting, capturing higher lifetime value than transactional retail. This shift concentrates demand intelligence with platform operators, eroding brand equity leverage for traditional manufacturers dependent on shelf visibility.
Asia-Pacific Gluten-Free Breakfast Cereals Market Segmentation
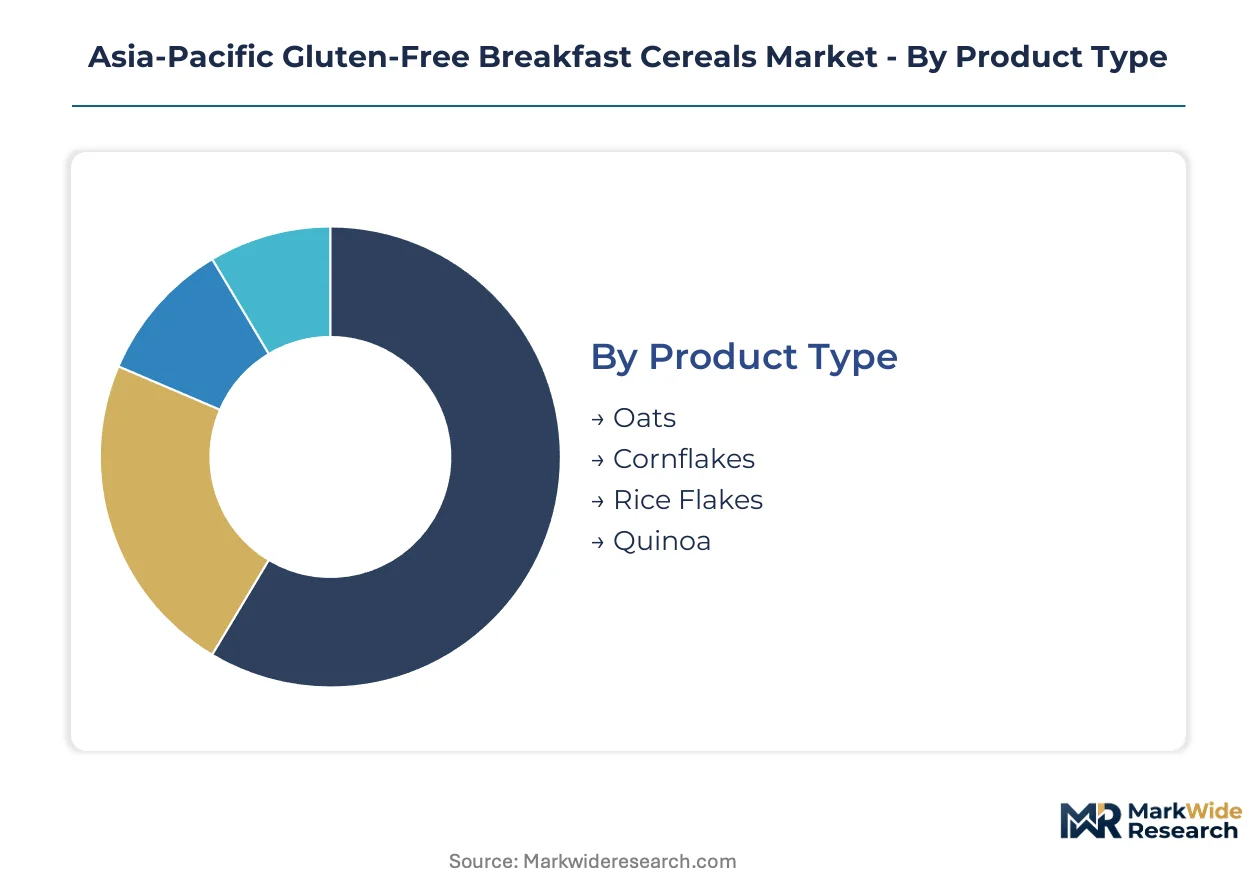
Product specifications and certification thresholds determine how gluten-free breakfast cereals reach distinct consumer groups across Asia-Pacific. Segmentation reveals where formulation investments align with regulatory compliance and channel access requirements.
Product Type:
Grain composition and processing tolerance define the technical hierarchy of certified formulations.
- Oats:Rolled and steel-cut varieties processed through dedicated milling equipment achieve sub-20 ppm certification. Australian and Japanese supermarkets anchor volume demand for hot and ready-to-eat oat formats. FSANZ labeling enforcement compels manufacturers to maintain segregated supply chains from Canadian and Australian growers.
- Quinoa:Pseudocereal base delivers complete protein profiles and low glycemic indices for fitness-oriented consumers. Health food stores in India's Delhi-Mumbai-Bangalore corridor pull imported quinoa flakes through direct sourcing relationships with Andean suppliers. Premium positioning sustains despite higher input costs versus oat alternatives.
- Cornflakes:Maize-based extrusion delivers familiar crunch texture at lower price points than specialty grains. Non-GMO certification variants concentrate in Southeast Asian health food retail.
- Rice Flakes:Paddy-derived formulations serve price-sensitive segments and traditional breakfast preferences in South Asian markets. Local milling infrastructure in India supports domestic supply.
Oats leads on scale; quinoa leads on momentum.
Distribution Channel:
Channel selection determines compliance burden and margin capture for certified product flows.
- Online Retail:Subscription models bypass traditional supermarket infrastructure and concentrate demand intelligence with platform operators. Urban Indian households drive steepest expansion trajectory through direct-to-doorstep certified oat deliveries bundled with nutritional consulting.
- Supermarkets:Melbourne and Sydney retail chains enforce FSANZ-compliant documentation for shelf placement. General Mills and Nestlé anchor presence through dedicated supply chain investments.
- Health Food Stores:Curated assortment of organic and imported lines serves celiac patients seeking medical-grade certification. Staff consultation drives higher per-unit spending than self-service retail.
- Convenience Stores:Single-serve packaging formats target commuter demand in Japanese urban corridors. Limited shelf space constrains certified product range.
Supermarkets dominate absolute volume; online retail climbs fastest.
End User:
Consumer health status and lifestyle orientation shape formulation priorities and price tolerance.
- Health-Conscious Consumers:Preventive wellness seekers prioritize organic sourcing and clean label attributes over strict gluten thresholds. This segment expands shelf space for premium-positioned lines in Australian and Japanese retail.
- Celiac Patients:Medically diagnosed consumers sustain highest per-unit spending on certified sub-20 ppm formulations with full supply chain documentation. FSANZ and Japan's Consumer Affairs Agency labeling requirements directly serve this group's safety needs.
- Fitness Enthusiasts:Macronutrient-focused buyers favor high-protein quinoa and oat combinations for post-workout consumption. Protein fortification drives product development priorities.
- Families:Multi-person households balance certified safety with palatability for children and cost efficiency for daily consumption. Value-oriented packaging sizes concentrate in supermarket channels.
Health-conscious consumers anchor volume expansion; celiac patients anchor margin extraction.
Ingredient Source:
Provenance claims differentiate positioning and determine regulatory pathway complexity.
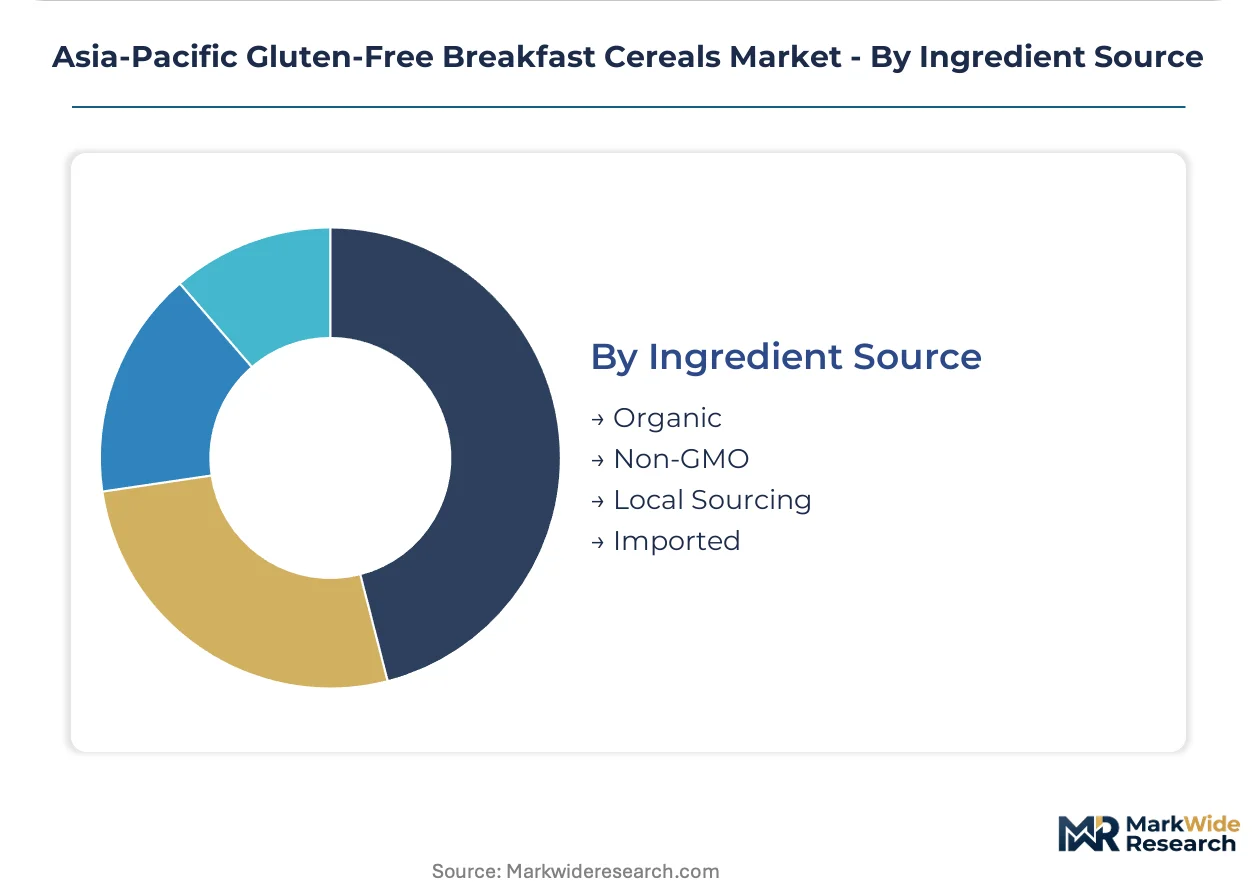
- Organic:Third-party certified cultivation excludes synthetic pesticides and GMO inputs. Nature's Path Foods and comparable specialists command premium shelf placement in health food stores across Australia and Japan.
- Non-GMO:Identity-preserved supply chains document absence of genetically modified organisms through testing protocols. This specification opens access to consumer segments skeptical of biotechnology in food systems.
- Local Sourcing:Domestic grain procurement reduces transport costs and satisfies emerging preferences for shorter supply chains. Indian and Australian manufacturers leverage this for cost-competitive positioning.
- Imported:Canadian oat and Andean quinoa inputs supply markets lacking sufficient domestic certified production. Import documentation requirements extend lead times and elevate compliance costs.
Organic leads on premium positioning; local sourcing leads on cost efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized food safety auditors and certified supply chain technicians concentrate in Australia's Melbourne-Sydney corridor and Japan's Kanto region, anchoring technical compliance capacity for gluten-free cereal manufacturing.
Australia
Urban households in Melbourne and Sydney drive retail uptake of certified gluten-free oats through supermarket chains enforcing strict documentation protocols. FSANZ gluten-free labeling standards compel manufacturers to maintain segregated milling infrastructure and third-party audit trails. The Melbourne-Sydney corridor concentrates dedicated production facilities serving both domestic demand and export flows to New Zealand and Southeast Asia.
Japan
Health-conscious consumers in Tokyo and Osaka sustain premium positioning for quinoa and organic oat formats through curated health food retail. The Consumer Affairs Agency enforces strict allergen labeling and cross-contamination disclosure rules that elevate compliance costs for imported brands. Kanto region distribution hubs handle documentation-intensive clearance for cereal products seeking shelf placement in metropolitan retail chains.
India
Metro corridor demand concentrates in Delhi, Mumbai, and Bangalore where health food stores and online retail channels expand shelf space for certified alternatives. FSSAI has proposed tighter gluten threshold definitions that would reshape domestic manufacturing standards and import certification requirements. The Delhi-Mumbai-Bangalore corridor pulls volume through direct-to-doorstep subscription models bypassing traditional supermarket infrastructure.
China
SAMR and the National Health Commission regulate gluten-free health claims through functional food registration pathways that delay market entry for international brands. Urban consumers in Shanghai and Beijing access imported certified products through cross-border e-commerce channels operating outside conventional retail compliance frameworks. The Yangtze River Delta concentrates import logistics and warehousing for specialty grain formulations awaiting regulatory approval.
South Korea
Fitness-oriented consumers in Seoul sustain demand for high-protein quinoa and oat combinations through health food retail and specialized online platforms. MFDS allergen labeling requirements align with Japan's stringent disclosure standards, creating compliance synergies for manufacturers serving both markets. The Seoul Capital Area anchors distribution networks for certified products targeting post-workout consumption segments.
Asia-Pacific Gluten-Free Breakfast Cereals Market Competitive Environment
Capital-heavy producers with dedicated milling infrastructure compete with asset-light brands outsourcing manufacturing to certified contract facilities. The market structure tiers between multinational packaged food conglomerates controlling supermarket shelf space and specialist organic operators commanding premium health food positioning. Three archetypes dominate: integrated grain-to-shelf manufacturers with captive supply chains, portfolio diversifiers leveraging existing cereal production assets, and organic specialists differentiating through ingredient provenance claims. Competitive moves concentrate on supply chain certification investments and subscription commerce platform partnerships.
Among North American packaged food conglomerates, General Mills Inc. and Kellogg Company occupy positions anchored by existing cereal manufacturing infrastructure and supermarket distribution relationships. Nestlé S.A. represents the European multinational archetype with specialized production lines excluding cross-contamination protocols. Nature's Path Foods Inc. exemplifies the organic specialist tier differentiating through certified ingredient sourcing that commands premium shelf placement in health food retail channels across Australia and Japan.
| Leading Market Players |
|---|
| General Mills Inc. |
| Kellogg Company |
| Nestlé S.A. |
| PepsiCo Inc. |
| Bob's Red Mill Natural Foods Inc. |
| Post Holdings Inc. |
| Mondelez International Inc. |
| Nature's Path Foods Inc. |
| B&G Foods Inc. |
| Others |
Value Chain & Pricing Dynamics
Subscription bundling in India's metro corridors is compressing per-unit margins while demanding just-in-time replenishment capabilities that only dedicated-milling suppliers can satisfy. This procurement preference shift forces manufacturers to absorb certification costs upfront and recover through lifetime value capture rather than transactional markup.
Pricing Analysis
Bundled subscription services versus unbundled supermarket transactions split the pricing architecture across Asia-Pacific. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and organic provenance. Price differentiation hinges on FSANZ compliance documentation and dedicated facility verification. Cost compression in economy tiers is intensifying because Indian and Southeast Asian consumers trade down during input cost spikes. Families exhibit highest price sensitivity; celiac patients show least.
Supply Chain Analysis
Dual-sourcing requirements from Australian and Japanese supermarket chains mandate multi-supplier qualification for certified oat inputs. Supply concentrates in Canada, Australia, and the Andean region for gluten-free grains. Raw material dependencies include certified seed stock, segregated transport containers, and third-party audit services. Single-source vulnerability persists where Canadian harvest failures disrupt global oat flows. Distribution runs through Melbourne-Sydney corridor hubs for Oceania and Kanto-region distribution centers for Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on automation-driven cost reduction in quality assurance and the shift toward premium-certified tiers that command documentation premiums.
For Market Incumbents: Cement dedicated milling infrastructure investments in the Melbourne-Sydney corridor to preempt FSANZ audit capacity constraints. Lock in multi-year supply agreements with Canadian oat growers before harvest volatility escalates. Channel control through subscription platform partnerships defends against direct-to-consumer disintermediation. For New Entrants and Emerging Players: India's proposed FSSAI gluten threshold tightening opens a window for early compliance investments that capture shelf space ahead of domestic manufacturer retooling. Target Indonesia and Vietnam health food retail through certified organic positioning before local supply chains mature. Go-to-market angle: partner with Australian contract manufacturers already holding FSANZ certification to bypass 18-24 month facility validation timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale organic specialists possessing captive Andean quinoa sourcing relationships and existing Japanese Consumer Affairs Agency audit clearances. Five-to-ten year viability favors brands that control identity-preserved supply chains rather than outsourced manufacturing. Watch India's FSSAI final rule publication as inflection indicator for compliance investment urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | FSANZ-compliant documentation unlocks premium supermarket placement in Australian and Japanese retail chains. |
| Subscription Platform Partnership | Direct-to-doorstep models in India concentrate demand intelligence and capture higher lifetime value than transactional retail. |
| Backward Integration into Seed Supply | Identity-preserved oat cultivation in Canada and Australia reduces input cost volatility and batch rejection risk. |
| Automation of Quality Assurance | Near-infrared spectroscopy deployment compresses batch release timelines from 72 hours to 4 hours for just-in-time replenishment. |
| Geographic Expansion | First-mover positioning in Indonesia and Vietnam health food retail ahead of local supply chain maturation secures shelf access. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary interviews captured perspectives from cereal manufacturing executives, FSANZ compliance officers, health food retail category buyers, and dedicated milling facility technicians. Secondary validation drew from customs trade records, FSANZ allergen labeling guidance documents, FSSAI consultation papers, and Consumer Affairs Agency disclosure requirements. Bottom-up volume estimates triangulated against top-down category spending assessments.
Comparable historical periods anchored the projection horizon to observed regulatory implementation lags and subscription commerce adoption curves. Segmentation dimensions modeled include grain composition, distribution channel, end-user health status, and ingredient provenance certification. CAGRs derived from trend extrapolation adjusted for threshold effects from pending regulatory changes. Industry-specific inputs incorporated oat harvest yield volatility patterns and extrusion equipment capacity utilization rates.
Revisions become necessary when India's FSSAI finalizes gluten threshold definitions or when Japan's Consumer Affairs Agency extends cross-contamination disclosure requirements. Deviation in Canadian oat harvest yields or Australian dollar exchange rate movements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market
Food Intolerance Products
United States Gluten Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
Allergen Free Food Market
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market
Food Intolerance Products
Argentina Gluten-Free Food and Beverage Market
Food Intolerance Products
Reduced Salt Food Products Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market
Food Intolerance Products
Low GI Food Market
Food Intolerance Products
Australia Gluten-Free Foods and Beverages Market
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Global Gluten Free Prepared Foods Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Food Intolerance Products Market
Food Intolerance Products
Global Lactose Intolerance Treatment Market
Food Intolerance Products
Food Allergy Market