
 Japan Gluten-Free Food and Beverages Market | 2026-2036
Japan Gluten-Free Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Gluten-Free Food and Beverages Market Foresight
Dietitian and food-scientist talent is bifurcating the competitive landscape as formulation complexity outpaces generalist capability. Nestle S.A. leverages its centralized R&D hub in Kobe to develop rice-based formulations tailored to Japanese palates. Kibun Foods Inc anchors domestic production with specialized tapioca processing lines that reduce import dependency. General Mills competes through brand recognition among expatriate and inbound tourist segments in major metropolitan areas.
Gluten-free food and beverages comprise products formulated without wheat, barley, rye, or their crossbred variants, typically substituting rice flour, tapioca starch, or corn-derived ingredients to achieve comparable texture and shelf stability. These formulations serve consumers with celiac disease, wheat allergy, or non-celiac gluten sensitivity across retail and foodservice channels. Rice-sourced ingredient lines lead volume due to cultural familiarity and domestic agricultural availability, while quinoa-based offerings represent the fastest-growing ingredient segment as health-conscious urban consumers associate it with higher protein content. Certified gluten-free labeling commands premium shelf positioning in supermarkets and health food stores, though organic and non-GMO dual certifications capture the strongest margin pools among specialty retailers.
Japan's Consumer Affairs Agency enforces strict allergen labeling under the Food Labeling Act, requiring wheat disclosure and creating compliance costs that favor established manufacturers with dedicated testing laboratories. METI promotes functional food innovation through regional cluster programs, indirectly supporting domestic gluten-free R&D investment. PMDA oversight of medical foods creates a parallel pathway for clinically positioned products targeting diagnosed celiac patients. Stakeholders must monitor how evolving JIS standards for gluten detection thresholds reshape import competitiveness and domestic formulation requirements.
Market Dynamics
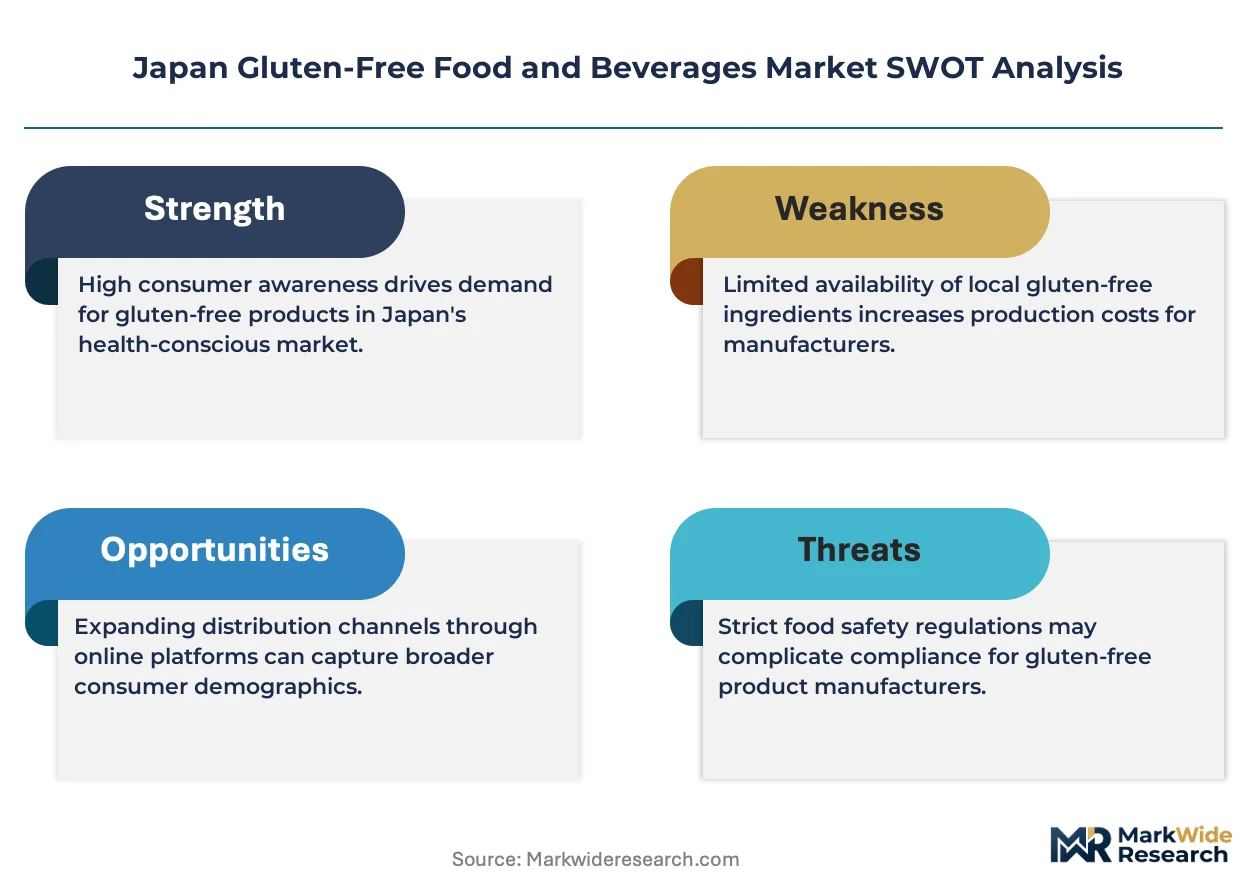
Japan's Consumer Affairs Agency is tightening allergen labeling enforcement, forcing manufacturers to rebuild supply chains and reformulate around verified gluten thresholds. This regulatory compression is reshaping competitive advantage toward players with captive laboratory testing capabilities.
Growth Catalysts
- Food Labeling Act amendments:Wheat disclosure mandates are accelerating certified product launches as retailers demand compliant SKUs to avoid liability exposure.
- Rice flour processing advances:Domestic milling technology improvements are reducing texture gaps versus wheat, expanding acceptable applications in traditional Japanese bakery formats.
- Tokyo-Osaka foodservice expansion:Premium restaurant chains are introducing dedicated gluten-free menus to capture inbound tourist and expatriate dining expenditure.
Market Restraints
- Tapioca starch import dependency:Supply concentration in Southeast Asian processing centers exposes margins to shipping cost volatility and currency fluctuation.
- JIS gluten detection threshold compliance:Testing infrastructure requirements create fixed cost barriers that disadvantage smaller regional manufacturers.
- Wheat-based convenience food substitution:Onigiri and rice noodle alternatives face entrenched consumer habit formation and lower relative price positioning.
Strategic Opportunities
- Hokkaido agricultural cluster development:METI regional innovation programs are funding quinoa cultivation trials to diversify domestic ingredient sourcing.
- Pharmacy channel medical food positioning:PMDA oversight pathways enable clinically branded products targeting diagnosed celiac patients with reimbursable positioning.
- Quinoa-protein convergence:Health-conscious urban consumers are migrating toward higher-protein ancient grain formulations in Kanto convenience retail.
Industry Challenges
- Food-scientist formulation expertise scarcity:Specialized talent capable of rice-tapioca blend optimization commands premium compensation that strains mid-tier manufacturer R&D budgets.
- Dual certification timeline compression:Simultaneous gluten-free and organic verification processes extend product launch cycles by four to six months versus conventional SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Gluten-Free Food and Beverages Market |
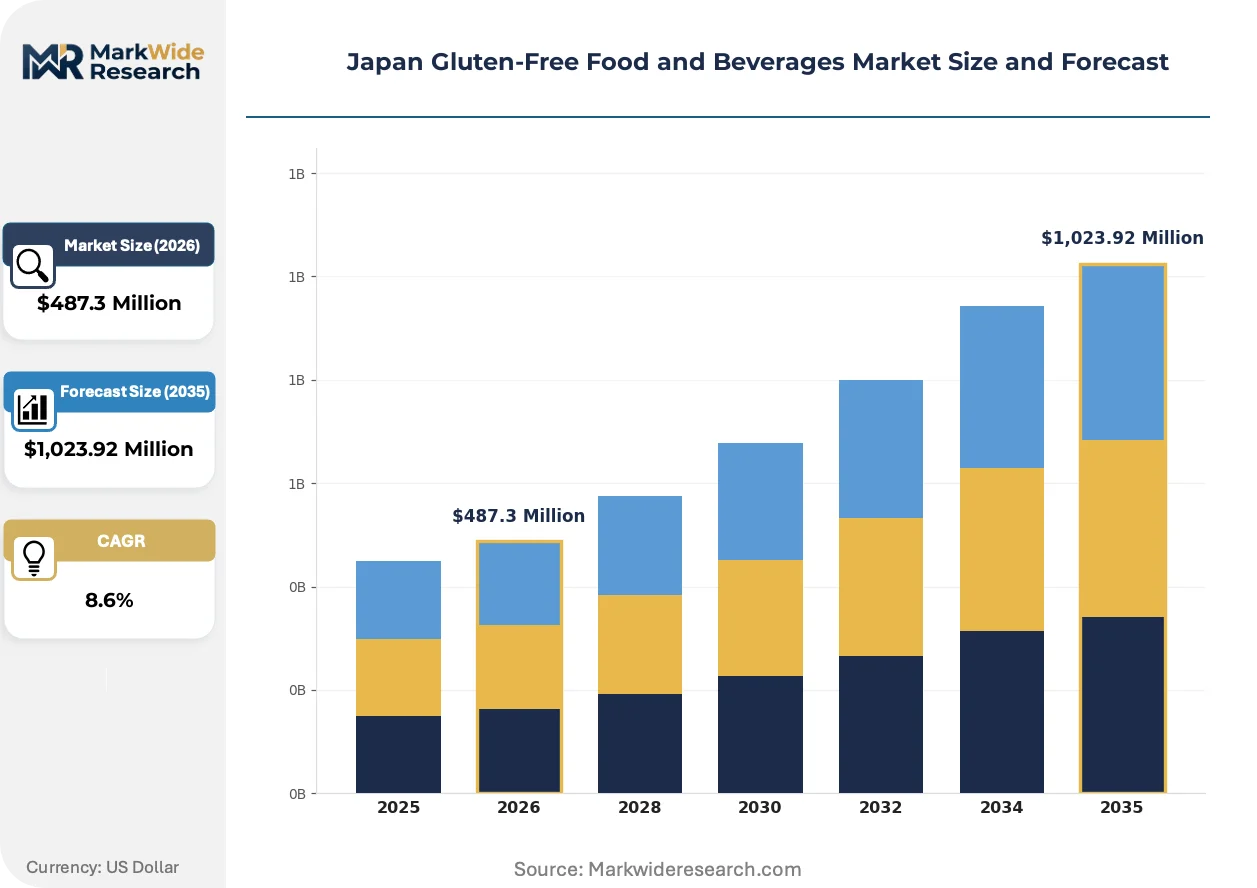
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Beverages, Baked Goods, Pasta Ingredient Source: Rice, Corn, Quinoa, Tapioca Certification Type: Gluten-Free Certified, Organic, Non-GMO, Allergen-Free Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Stores |
| Companies Covered | Hain Celestial Group, Mondelez International, Nestle S.A., Ener-G Foods, Inc., Kibun Foods Inc, The Kellogg Company, Groupe Danone, Enjoy Life Foods, General Mills, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Gluten-Free Food and Beverages Market Shifts & Advancements
Formulation science and distribution channel evolution are compressing traditional competitive moats. Japanese manufacturers are racing to integrate domestic ingredient sourcing with precision milling technology.
Enzymatic rice flour modification is displacing imported tapioca in premium bakery applications. Nagoya-based ingredient suppliers are deploying cellulase and amylase treatments to improve rice flour elasticity and browning characteristics. Major confectionery manufacturers are adopting these modified starches to reduce supply chain exposure while maintaining product consistency.
METI functional food cluster subsidies are redirecting R&D investment toward domestically sourced ancient grains. Regional processing facilities in northern Japan are receiving capital grants for quinoa and millet cleaning and milling infrastructure. Specialty retailers in Osaka and Fukuoka are responding with expanded shelf space for locally processed gluten-free flour blends.
Certification-driven purchasing is fragmenting traditional supermarket channel dominance. Health food stores and online subscription services are capturing urban consumer loyalty through verified gluten-free and additive-free dual positioning. Kanto region millennials demonstrate the strongest channel switching behavior, prioritizing third-party certified SKUs over conventional mass-market alternatives.
Japan Gluten-Free Food and Beverages Market Segmentation
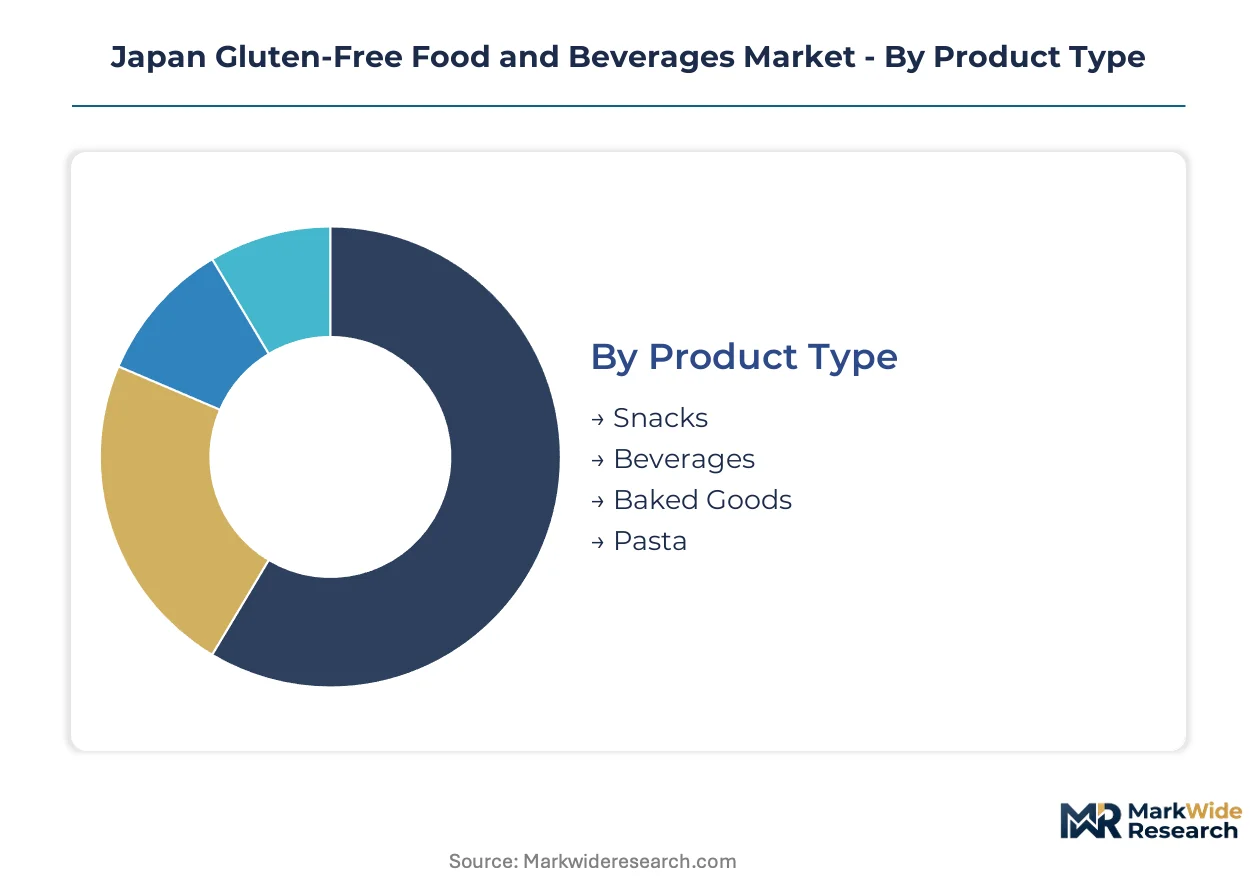
Segmentation in Japan's gluten-free market reveals how regulatory pressure and consumer sophistication are splitting demand across certification tiers and channel types. Manufacturers must align formulation investments with the specific margin structures each segment commands.
Product Type:
Premium positioning concentrates in formats requiring technical substitution complexity, where rice flour processing investments yield defendable price premiums.
- Beverages:Rice-based malt beverages and quinoa protein drinks dominate shelf-stable innovation. Tokyo convenience retail chains are expanding dedicated gluten-free cold vault sections as inbound tourist demand for Japanese-style functional beverages climbs.
- Baked Goods:Formulations combine enzymatically modified rice flour with tapioca starch to replicate mochi-like elasticity in bread applications. Osaka specialty bakeries are driving demand for certified products that satisfy both celiac patients and wheat-avoidant lifestyle consumers.
- Snacks:Senbei and arare variants using domestic rice flour anchor mass-market penetration.
- Pasta:Rice noodle alternatives face entrenched udon and soba substitution patterns in Kanto household purchasing.
The dominant share belongs to Beverages, while Baked Goods is closing the gap fastest.
Ingredient Source:
Domestic agricultural availability and import dependency create divergent cost structures across sourcing strategies.
- Rice:Koshihikari and Yumepirika varietals provide starch profiles optimized for gluten-free baking through regional milling partnerships. Niigata and Akita prefectures are expanding dedicated gluten-free rice flour processing capacity to reduce cross-contamination risk in shared facilities.
- Quinoa:Hokkaido cultivation trials under METI cluster funding are reducing Thai and Peruvian import reliance. Health-conscious Kanto millennials are migrating toward quinoa-protein formulations in convenience retail, associating the grain with higher amino acid completeness.
- Corn:Primarily sourced through US agricultural imports with price exposure to currency fluctuation.
- Tapioca:Southeast Asian processing concentration exposes margins to shipping cost volatility and supply interruption.
Rice maintains volume leadership, though Quinoa is expanding most quickly as domestic cultivation scales.
Certification Type:
Label density directly correlates with shelf positioning power and consumer willingness to pay premium multiples.
- Gluten-Free Certified:Third-party verification under JIS detection thresholds commands supermarket premium placement. Consumer Affairs Agency enforcement is accelerating retailer demand for certified SKUs to mitigate liability exposure.
- Organic:Dual certification with gluten-free status captures the strongest margin pools in specialty retail. Extended verification timelines compress product launch cycles by four to six months versus conventional SKUs.
- Non-GMO:Required for export-oriented production targeting North American and European markets.
- Allergen-Free:Broader exclusion labeling addresses multiple-sensitivity consumers in pharmacy and medical food channels.
Gluten-Free Certified holds the dominant position, while Organic dual-certification products are gaining share fastest in urban specialty retail.
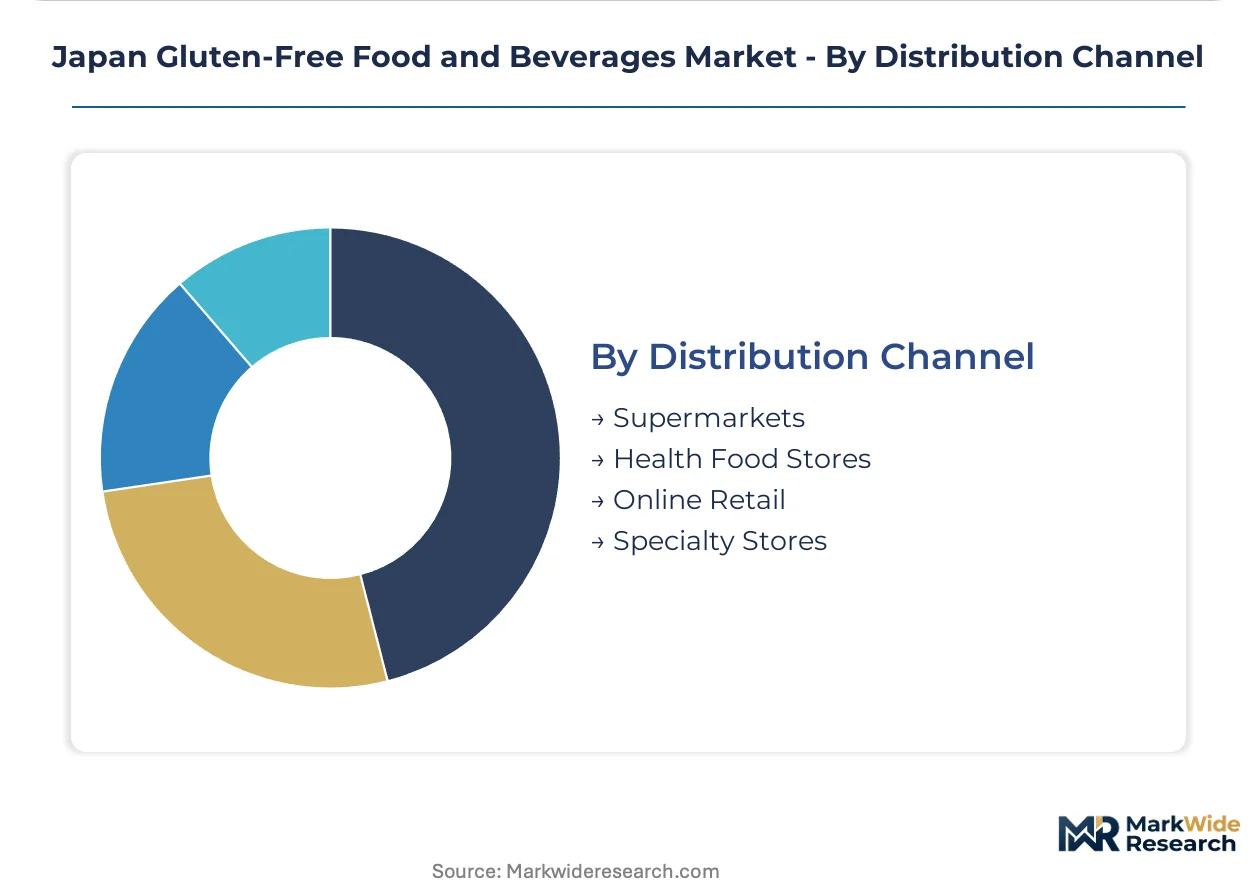
Distribution Channel:
Channel fragmentation is accelerating as verified purchasing behavior migrates away from traditional mass retail.
- Health Food Stores:Staff-trained environments enable education-heavy purchases for newly diagnosed celiac patients. Kanto region millennials demonstrate the strongest loyalty to third-party certified SKUs in this channel.
- Online Retail:Subscription services capture recurring purchasing through additive-free and certified gluten-free dual positioning. Osaka and Fukuoka specialty retailers are responding with expanded digital fulfillment infrastructure.
- Supermarkets:Mass-market penetration remains constrained by shelf-space competition with conventional wheat products.
- Specialty Stores:Pharmacy channel integration enables PMDA-aligned medical food positioning for diagnosed patients.
Health Food Stores anchor premium volume, while Online Retail is climbing the fastest as subscription models lock in recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Kanto while Kansai manufacturers compete on processing efficiency and domestic ingredient sourcing. Regional divergence reflects urban consumer sophistication gradients and METI cluster investment patterns across Japan's industrial geography.
Kanto/Tokyo
Tokyo's inbound tourist corridor and expatriate residential clusters generate concentrated demand for certified gluten-free restaurant dining and retail SKUs. The Consumer Affairs Agency headquarters proximity accelerates compliance timeline awareness among local manufacturers. Saitama and Chiba prefectures host dedicated rice flour milling facilities serving the capital's foodservice distributors.
Kansai/Osaka
Osaka's commercial bakery tradition translates into specialized gluten-free confectionery production targeting both domestic and export markets. METI Kansai regional innovation programs fund enzymatic processing equipment upgrades. Hyogo prefecture's Kobe manufacturing zone anchors centralized R&D operations for multinational food conglomerates.
Chubu/Nagoya
Nagoya's precision engineering heritage supports advanced rice flour modification technology development for texture optimization. Aichi prefecture food processors leverage automotive sector quality management systems for allergen control protocols. Local ingredient suppliers deploy cellulase treatments to improve domestic starch performance in traditional Japanese bakery formats.
Hokkaido
Hokkaido's agricultural land availability enables quinoa cultivation trials under METI functional food cluster subsidies. Sapporo-based processors receive capital grants for ancient grain cleaning and milling infrastructure development. Regional specialty retailers expand shelf space for locally processed gluten-free flour blends targeting health-conscious urban consumers.
Kyushu
Fukuoka's proximity to Southeast Asian shipping lanes positions the region for tapioca starch import processing and redistribution. Local manufacturers face margin pressure from currency fluctuation exposure in Southeast Asian supply contracts. Nagasaki and Saga prefectures develop rice flour blending operations to reduce import dependency in western Japan distribution networks.
Japan Gluten-Free Food and Beverages Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Japan's gluten-free food and beverages sector. Multinational conglomerates with centralized R&D infrastructure dominate formulation complexity, while domestic specialists capture efficiency advantages in regional ingredient processing. The competitive structure segments into three archetypes: global brand licensors, domestic agricultural processors, and clinical-positioning medical food specialists. Consolidation pressure operates through backward integration into rice flour milling capacity and strategic partnerships with METI-funded regional cluster programs.
Among global packaged food conglomerates, Nestle S.A., General Mills, and Mondelez International occupy positions defined by brand recognition and centralized formulation development. These entities exemplify the technology-leading archetype through captive laboratory testing capabilities and Kobe-based R&D hub investment. Domestic specialists including Kibun Foods Inc represent the cost-efficient processing tier with specialized tapioca handling infrastructure and reduced import dependency positioning.
| Leading Market Players |
|---|
| Hain Celestial Group |
| Mondelez International |
| Nestle S.A. |
| Ener-G Foods, Inc. |
| Kibun Foods Inc |
| The Kellogg Company |
| Groupe Danone |
| Enjoy Life Foods |
| General Mills |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for Thai and Vietnamese tapioca starch lock in supply access and price visibility for Japanese manufacturers, insulating against currency fluctuation while compressing margin flexibility when spot markets soften. Consumer Affairs Agency enforcement timelines drive buyers toward certified suppliers with captive laboratory infrastructure, embedding quality verification costs into contracted price floors.
Pricing Analysis
Customization-premium spreads separate enzymatically modified rice flour formulations from commodity tapioca-starch substitutes. Three-tier pricing structure across premium certified, standard compliant, and economy private-label levels reflects certification density and domestic sourcing ratios. Pricing pressure stems from JIS gluten detection threshold compliance costs that smaller regional manufacturers cannot absorb. Foodservice distributors in Tokyo demonstrate lowest price sensitivity, while mass-market supermarket buyers in Kyushu negotiate hardest on volume contracts.
Supply Chain Analysis
Malacca Strait transit underwrites Southeast Asian tapioca starch delivery schedules to Japanese ports, exposing just-in-time milling operations to piracy and congestion risks. Thailand, Vietnam, and Cambodia concentrate raw tapioca processing, while domestic Niigata and Akita prefectures anchor rice flour production. Supply chain risk centers on single-source vulnerability in modified starch enzyme suppliers based in Nagoya. Distribution runs through Tokyo-Osaka foodservice wholesalers and Kanto health food store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's gluten-free market represents a high-growth disruption as enzymatic rice flour modification displaces import-dependent tapioca formulations, with Consumer Affairs Agency labeling enforcement accelerating certified product adoption.
For Market Incumbents: Consolidate backward into dedicated rice flour milling capacity in Niigata and Akita prefectures to reduce cross-contamination risk and capture METI cluster subsidies. Lock in long-term offtake agreements with Hokkaido quinoa cultivation trials before domestic supply scales and commoditizes. Nestle S.A.'s Kobe R&D hub model demonstrates how centralized formulation infrastructure defends against smaller players lacking laboratory testing capabilities.
For New Entrants and Emerging Players: Differentiate on dual-certified organic-gluten-free positioning in Kanto health food store channels where millennial consumers pay premium multiples for verified additive-free SKUs. Target pharmacy channel medical food positioning under PMDA oversight, the least penetrated segment with reimbursable pricing potential. Pursue direct-to-subscription models bypassing supermarket shelf-space competition entirely.
For Investors and Strategic Acquirers: Domestic agricultural processors with METI-funded regional cluster partnerships offer the strongest acquisition profile, combining captive ingredient sourcing with government-subsidized infrastructure expansion. Long-term viability hinges on substitution cost parity with wheat-based alternatives across the analysis window. Watch Hokkaido quinoa yield trials as the inflection signal for domestic ancient grain supply scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rice Flour Milling | Captive supply of Koshihikari varietals reduces cross-contamination risk and METI compliance costs. |
| Dual Certification Investment | Organic-gluten-free verification commands strongest margin pools in Kanto specialty retail channels. |
| Pharmacy Channel Expansion | PMDA medical food positioning enables reimbursable pricing for diagnosed celiac patient segments. |
| Enzymatic Processing Partnership | Nagoya cellulase treatment alliances improve rice flour elasticity without tapioca import dependency. |
| Hokkaido Agricultural Cluster Engagement | METI quinoa cultivation subsidies diversify domestic ingredient sourcing and reduce currency exposure. |
Research Methodology
Operator-level perspectives from food-scientist formulators, health food store category buyers, Consumer Affairs Agency compliance officers, and METI regional cluster administrators anchored the qualitative base for this study. Primary interview insights triangulated against secondary sources including Food Labeling Act regulatory filings, JIS standard revision notices, Niigata and Akita prefectural agricultural statistics, and customs records for tapioca starch imports. Bottom-up SKU-level volume builds reconciled with top-down sector expenditure estimates across the projection horizon.
Sensitivity analysis tested forecast robustness against alternative gluten detection threshold adoption timelines and quinoa domestic cultivation scale scenarios. The analytical framework modeled segmentation across product type, ingredient source, certification tier, and distribution channel, with regional divergence patterns for Kanto, Kansai, Chubu, Hokkaido, and Kyushu. CAGRs derived from volume trajectory analysis incorporating rice flour processing capacity expansion schedules and inbound tourist foodservice demand recovery curves.
The analysis sits within stated boundaries; outcomes outside sustained Consumer Affairs Agency enforcement intensity or METI cluster funding continuity would require recalibration. Forecasts reflect assumptions regarding enzymatic modification technology diffusion and health food store channel expansion rates. Practitioners should keep alternative scenarios live as JIS standard revision timelines and Hokkaido agricultural yield data evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Asia-Pacific Gluten-Free Breakfast Cereals Market
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
Australia Gluten Free Food Market
Food Intolerance Products
South America Gluten Free Foods and Beverages Market
Food Intolerance Products
Lactose Free Products Market
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
North America Gluten-Free Food and Beverage Market
Food Intolerance Products
Gluten-Free Popcorn Products Market
Food Intolerance Products
Global Gluten-Free Ready Meals Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
Europe Gluten-Free Oats Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market