
 Gluten Free Products Market | 2026-2036
Gluten Free Products Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten Free Products Market Intelligence
Expanded production capacity in Italy and Spain for specialized gluten-free pastas and bakery goods is reshaping the European supply landscape, improving product quality. General Mills leverages its vast distribution network to mainstream gluten-free cereals and snacks into hypermarkets. The Hain Celestial Group differentiates through its portfolio of organic and natural gluten-free brands sold in specialty stores. European specialist Dr. Schär dominates the dedicated medical foods channel for coeliac disease patients, often distributed through pharmacies.
Gluten-free products are foods and beverages formulated without gluten, a protein composite found in wheat, barley, and rye. To qualify, these products must typically contain less than 20 parts per million of gluten, a standard set to protect consumer health. The bakery products segment, including bread and snacks, constitutes the largest market share due to staple food replacement. However, pasta and breakfast cereals represent the fastest-growing product categories, driven by innovation in alternative grain formulations.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) mandate strict labeling for gluten-free claims, defining the 20 ppm threshold. These rules, often aligned with the WHO's Codex Alimentarius standards, create market entry barriers for smaller producers but also build essential consumer confidence in product safety. Stakeholders must now decide whether to prioritize the high-margin medically necessary consumer segment or the larger, more price-sensitive lifestyle wellness market.
Market Dynamics
The gluten-free products market is defined by a fundamental demand split between the medically necessary segment, driven by coeliac disease, and the larger, more discretionary lifestyle wellness segment. This bifurcation influences every aspect of the value chain, from ingredient sourcing and price sensitivity to channel strategy and marketing communication.
Growth Catalysts
- Regulatory Harmonization:Increasingly strict food allergen labeling rules from the US FDA and EFSA, aligned with WHO Codex Alimentarius standards, build consumer trust and facilitate cross-border trade for compliant manufacturers.
- Food Service Expansion:The mainstreaming of gluten-free options on menus in restaurant chains, cafes, and institutional catering provides new, high-volume demand channels beyond traditional retail grocery.
- Product Innovation:Advances in formulating with alternative grains like quinoa, teff, and sorghum are improving the taste, texture, and nutritional profile of bakery products, attracting consumers beyond those with medical needs.
Market Restraints
- Input Cost Volatility:The price of alternative flours, such as almond or coconut flour, is significantly higher and more volatile than traditional wheat flour, creating margin pressure and pricing challenges for manufacturers.
- Technical Formulation Hurdles:Replicating the viscoelastic properties of gluten for bakery and pasta products remains a significant challenge, often resulting in products with inferior texture or shorter shelf life.
- Cross-Contamination Risk:Maintaining a certified gluten-free production environment requires dedicated facilities or stringent, costly cleaning protocols, which presents a substantial barrier to entry for smaller producers or those with mixed-use plants.
Strategic Opportunities
- Emerging Geographies:Markets in the Middle East and Latin America show nascent demand driven by rising health consciousness and disposable income, representing a significant white space for market entry.
- Functional Ingredients Integration:There is an opportunity to fortify gluten-free products with probiotics, prebiotics, and added fiber, appealing to a broader consumer base interested in gut health and functional foods.
- Plant-Based Synergy:Combining the gluten-free claim with the plant-based trend offers a powerful market position, targeting consumers who adhere to both dietary preferences for health or ethical reasons.
Industry Challenges
- Certification Complexity:Navigating the varying requirements and audit processes for different national and third-party gluten-free certifications adds significant administrative overhead and cost for producers operating in multiple markets.
- Formulation Expertise Scarcity:A limited talent pool of food scientists and R&D professionals with deep expertise in hydrocolloids and alternative grain chemistry constrains the pace of product development and innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten Free Products Market |
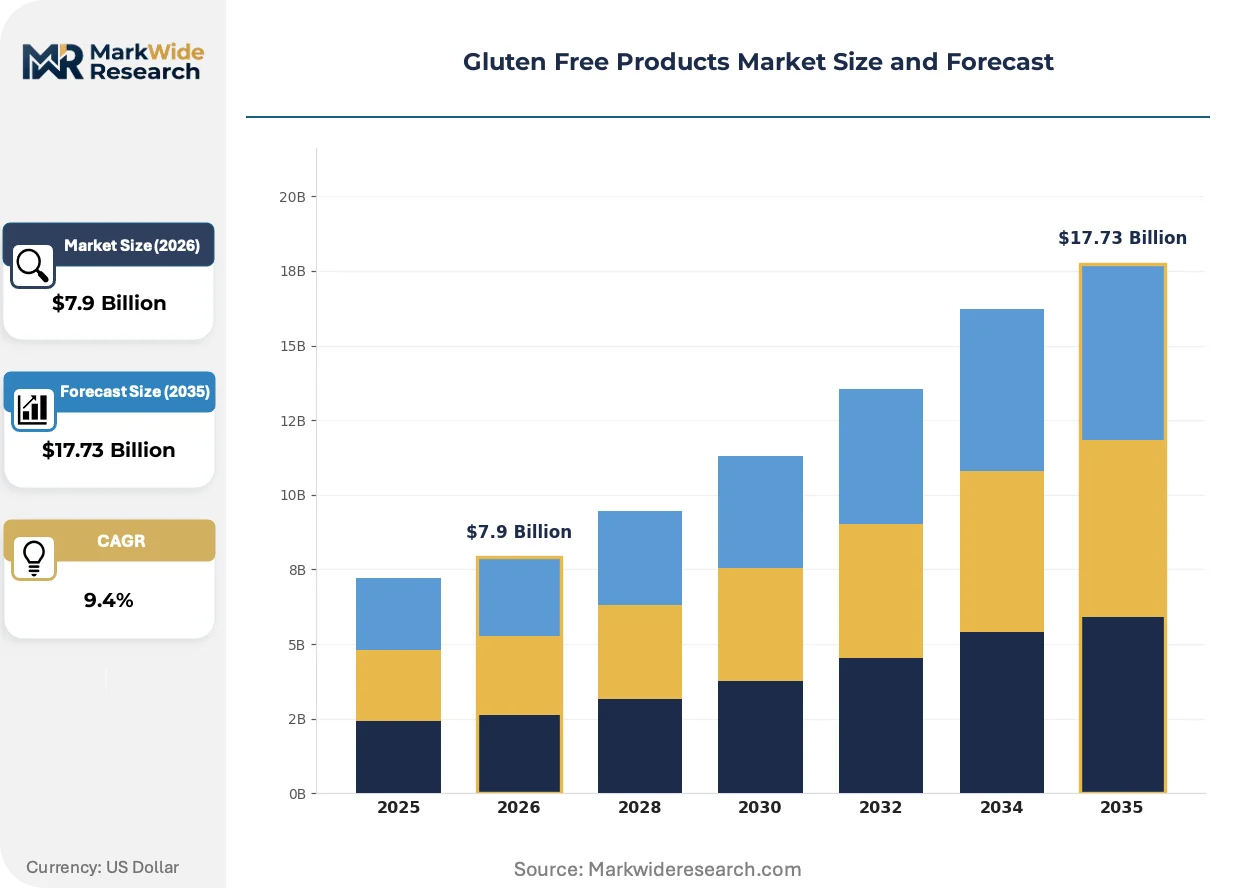
| Market Size in 2026 | $7.9 Billion |
| Market Size in 2035 | $17.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Pasta, Snacks, Breakfast Cereals, Bakery Mixes Application: Coeliac Disease Management, Wheat Allergy, Weight Management, Digestive Health End User: Retail Consumers, Food Service Providers, Institutional Buyers, Health Care Facilities Distribution Channel: Supermarkets & Hypermarkets, Specialty Stores, Online Retail, Pharmacies |
| Companies Covered | Nature’s Path Foods, Bob’s Red Mill Natural Foods, General Mills, The Hain Celestial Group, Conagra Brands, Kellogg Company, Dr. Schär, The Kraft Heinz Company, Bimbo Bakeries USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten Free Products Market Strategic Shifts & Innovations
The market's evolution is characterized by a shift from a purely medical necessity to a mainstream wellness category. This transition is powered by technological advancements in food science and a more sophisticated consumer understanding of ingredient benefits beyond simple gluten avoidance.
Digital twin technology for food formulation is virtualizing the trial-and-error process of product creation. Food scientists are the primary adopters of these platforms, which use predictive modeling to test interactions between alternative flours and binding agents. This innovation is virtualizing the physical test kitchen, significantly compressing R&D timelines and reducing raw material waste for new bakery and pasta formulations.
International regulatory alignment, guided by the WHO's Codex Alimentarius, standardizes the definition of "gluten-free" at a threshold of less than 20 parts per million. This harmonization between bodies like the US FDA and the European Food Safety Authority simplifies global trade for large manufacturers. However, it also increases compliance costs and analytical testing burdens, particularly affecting smaller, regional producers entering the market.
A notable consumption pattern shift sees consumers moving from simple avoidance to proactive inclusion of specific alternative grains. The focus is no longer just on what is absent (gluten) but on what is present, such as the protein in quinoa or the fiber in buckwheat. This trend is most visible in the breakfast cereal and savory snack categories in North America and Germany.
Gluten Free Products Market Segmentation
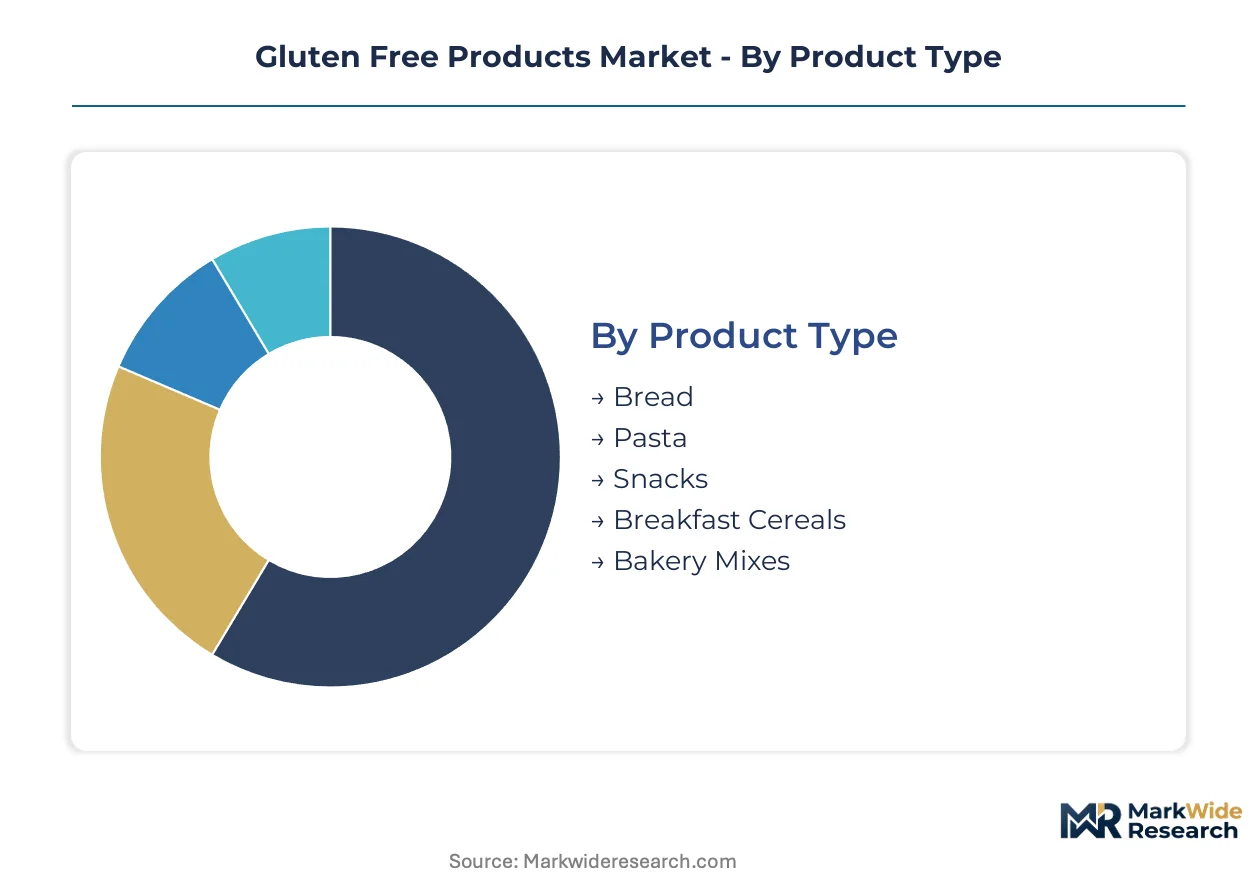
The gluten-free products market exhibits distinct consumer needs and purchasing behaviors across its various segments. Understanding these differentiations is crucial for manufacturers to tailor product development, marketing strategies, and distribution channels effectively. This segmentation analysis illuminates the diverse landscape.
Product Type:
Products like fresh bakery items typically have shorter consumption cycles, whereas shelf-stable pantry staples offer longer purchase intervals.
- Pasta:This segment includes a variety of gluten-free noodles, including those made from corn, rice, and legumes, providing a staple replacement. Demand concentrates in Europe, driven by innovation in texture and cooking performance that appeals to both medical and lifestyle consumers.
- Snacks:This category encompasses gluten-free chips, crackers, and bars, formulated with alternative flours and natural ingredients for convenience. North American consumers drive this segment, seeking portable, healthier options for on-the-go consumption.
- Bread:Gluten-free bread products replicate traditional loaves using ingredients like rice flour, potato starch, and tapioca, serving as a core dietary replacement.
- Breakfast Cereals:These cereals utilize grains such as corn, rice, and quinoa, offering gluten-free alternatives for morning meals.
- Bakery Mixes:This segment provides pre-blended gluten-free flours and mixes for home baking, allowing consumers to create their own baked goods.
Bread anchors the volume base while Pasta gains share at the steepest rate.
Application:
This category differentiates products based on the specific health concern or dietary preference of the consumer.
- Coeliac Disease Management:Products in this segment are specifically formulated to meet the strict dietary requirements of individuals diagnosed with coeliac disease, adhering to the 20 ppm gluten threshold. Demand is consistently high in Germany and the United States, where diagnosis rates are significant and regulatory enforcement is robust.
- Digestive Health:This application targets consumers seeking gluten-free options to alleviate digestive discomfort or improve gut health, often featuring added fibers or prebiotics. Consumers across Western Europe are increasingly adopting these products for their perceived wellness benefits beyond gluten avoidance.
- Wheat Allergy:These products cater to individuals with diagnosed wheat allergies, offering alternatives to wheat-containing foods.
- Weight Management:Consumers in this segment choose gluten-free products as part of broader weight loss or healthy eating regimens, often associating them with lower carbohydrate or calorie content.
The medically driven segments establish a foundational demand, with lifestyle-oriented applications demonstrating significant expansion.
End User:
The scale of purchase and consumption patterns vary significantly across different end-user groups.
- Retail Consumers:This segment includes individual shoppers purchasing gluten-free products for household consumption through various retail channels. This end-user group represents the largest volume, with diverse preferences influencing product innovation across all categories.
- Food Service Providers:Restaurants, cafes, and catering services constitute this segment, integrating gluten-free options into their menus to accommodate dietary needs. The expansion of gluten-free menus in commercial dining establishments in the US and UK drives demand.
- Institutional Buyers:This segment comprises schools, corporate cafeterias, and other large-scale organizations procuring gluten-free products for their patrons.
- Health Care Facilities:Hospitals, nursing homes, and clinics purchase gluten-free items to meet the dietary requirements of patients with specific medical conditions.
Retail Consumers command the largest purchasing volume, while Food Service Providers are increasingly influencing market growth.
Distribution Channel:
Each distribution channel offers unique pricing structures and margin opportunities for gluten-free product manufacturers.
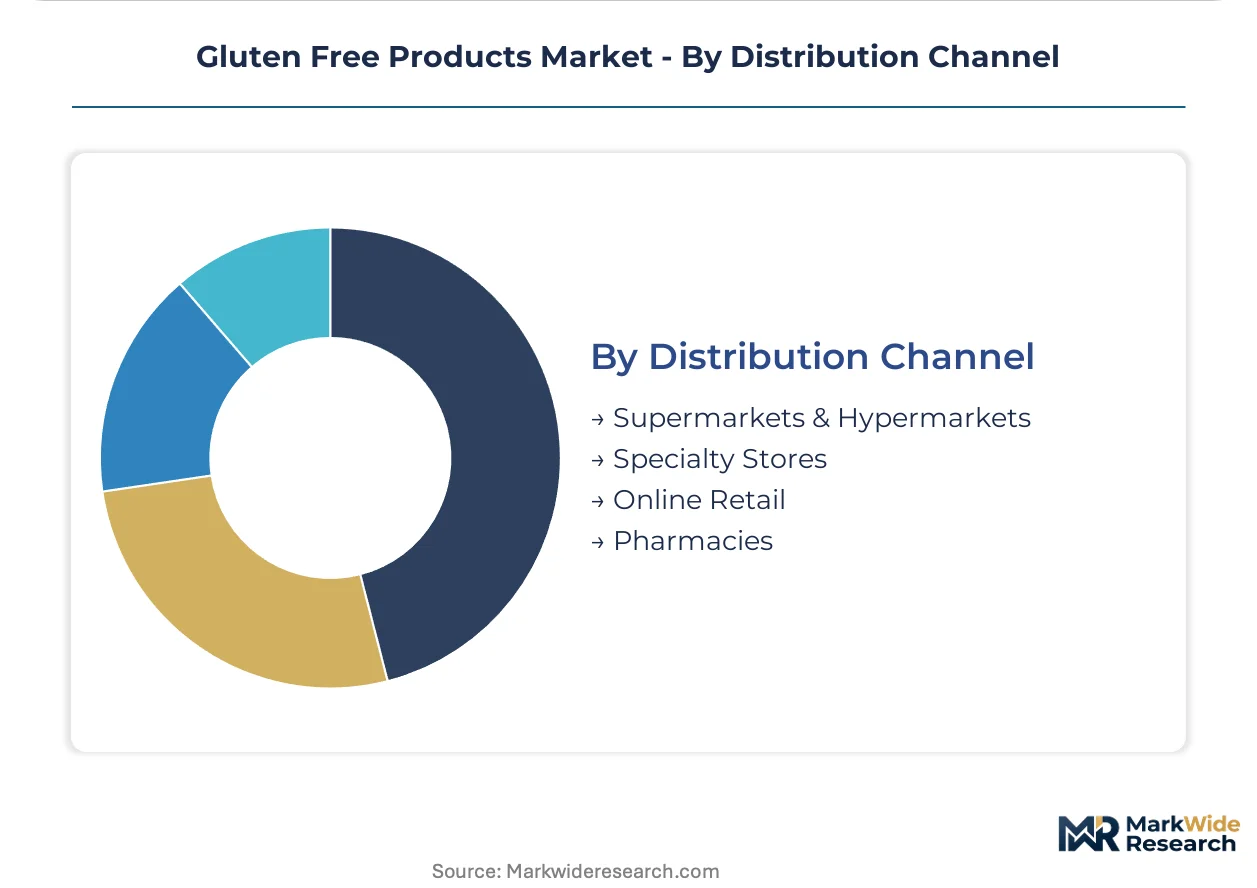
- Supermarkets & Hypermarkets:These large retail formats provide wide accessibility to a broad range of gluten-free products, often featuring dedicated aisles or sections. This channel offers mass market reach and convenience for everyday purchases, particularly in urban areas of the United States and Europe.
- Online Retail:E-commerce platforms and direct-to-consumer websites facilitate the purchase of gluten-free products, offering extensive product catalogs and home delivery. This channel provides increasing reach for niche brands and specialized items, appealing to consumers in remote areas or those seeking specific ingredients.
- Specialty Stores:Health food stores and organic markets focus on curated selections of gluten-free products, often emphasizing natural or organic attributes.
- Pharmacies:This channel distributes medically focused gluten-free products, particularly those designed for coeliac patients, often with professional advice available.
Supermarkets and Hypermarkets provide broad accessibility, while Online Retail is rapidly expanding its market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Food and Drug Administration (FDA) regulatory framework establishes a baseline for gluten-free product safety, influencing market dynamics across North America. This robust oversight fosters consumer confidence in the United States, driving significant demand. Demand for gluten-free products also shows high concentration in Germany and other European nations.
United States
United States demand for gluten-free products stems from both medical necessity for coeliac patients and a growing lifestyle wellness market. The US Food and Drug Administration (FDA) mandates strict labeling guidelines, reinforcing consumer trust in product claims. Major food manufacturers in states like California and Illinois are expanding production lines for gluten-free cereals and snacks.
Germany
Germany experiences strong demand, driven by a significant coeliac disease population and a broader consumer focus on digestive health. The European Food Safety Authority (EFSA) regulations, harmonized with WHO standards, ensure product integrity and safety. Specialist producers in regions like Bavaria and North Rhine-Westphalia focus on medical-grade gluten-free products for pharmacies.
Italy
Italy's market is expanding due to its traditional pasta-centric diet and increased production capacity for specialized gluten-free alternatives. Italian health authorities rigorously enforce EFSA guidelines, ensuring high standards for gluten-free product certification. Artisan and industrial producers in Lombardy and Emilia-Romagna are significantly improving the quality of gluten-free pasta offerings.
Spain
Spain sees rising demand for gluten-free products, propelled by growing health consciousness and food service sector expansion. Spanish regulatory bodies uphold the European Food Safety Authority's strict labeling requirements, building consumer trust. Food service providers in regions like Catalonia and Andalusia are actively integrating more gluten-free options into their menus.
United Kingdom
The United Kingdom market is influenced by a rising number of coeliac diagnoses and a clear consumer trend towards gut health foods. The UK's Food Standards Agency enforces stringent labeling standards, aligning with international gluten-free thresholds. Retail chains and specialty food stores in London and the Southeast are expanding their gluten-free product assortments significantly.
Gluten Free Products Market Key Industry Players
Capability concentration sits with specialist manufacturers focusing on complex gluten-free formulations, while scale advantage sits with large multinational food corporations leveraging existing distribution networks. The market exhibits a tiered structure, from dedicated medical food providers to mainstream consumer packaged goods companies. Strategic archetypes include organic-focused brands, mass-market generalists, and medical food specialists. Companies primarily pursue competitive moves through product innovation and geographic expansion.
Within the mass-market generalist tier, General Mills leverages its extensive distribution network to mainstream gluten-free cereals and snacks across hypermarkets. The Hain Celestial Group exemplifies the organic and natural brand archetype, often positioning its diverse portfolio for specialty retail channels. European specialist Dr. Schär anchors the dedicated medical foods segment, distributing products to coeliac disease patients, often through pharmacies. These entities collectively demonstrate the market's varied approaches to product development, ingredient sourcing, and channel strategy for distinct consumer groups.
| Leading Market Players |
|---|
| Nature’s Path Foods |
| Bob’s Red Mill Natural Foods |
| General Mills |
| The Hain Celestial Group |
| Conagra Brands |
| Kellogg Company |
| Dr. Schär |
| The Kraft Heinz Company |
| Bimbo Bakeries USA |
| Others |
Cost & Logistics Intelligence
Input cost volatility for alternative flours and specialized ingredients creates margin pressure for manufacturers, directly impacting downstream pricing power across retail and food service channels.
Pricing Analysis
Geographic price spreads reflect regional regulatory stringency and local ingredient availability. The dominant pricing model is per-unit transactional, with some contract-based long-term offtake for food service providers. Price differentiation stems from certification level, ensuring compliance with the 20 ppm gluten threshold, and brand premium associated with specialist manufacturers like Dr. Schär. Pricing pressure stems from the rising cost of alternative flours and ongoing R&D investment in formulation. Lifestyle wellness consumers exhibit the highest price sensitivity, while coeliac patients demonstrate lower price sensitivity for medically necessary products.
Supply Chain Analysis
Regulatory certification complexities and the need for dedicated production facilities restrict the cross-border flow of many gluten-free products. Supply concentration for specialized gluten-free pastas and bakery goods sits in Italy and Spain, while North America dominates gluten-free cereals and snacks. The supply chain draws from raw materials like almond, coconut, quinoa, and teff flours. A structural risk is the high input cost volatility for these alternative grains. Distribution runs through a hybrid model, combining mass retail accessibility in supermarkets and hypermarkets with specialized channels like pharmacies for medical foods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
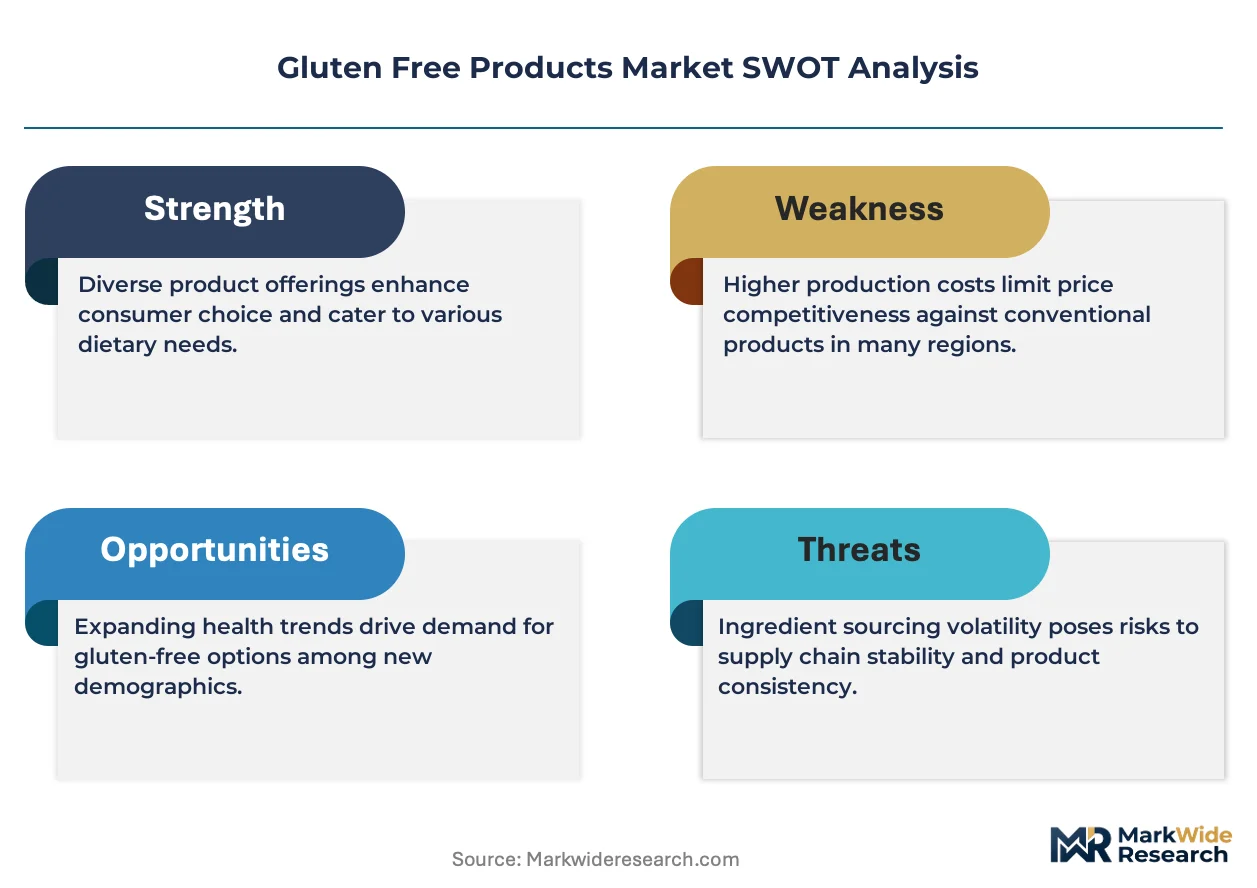
The gluten-free products market presents a defensive moat story, primarily due to the regulatory entrenchment created by strict FDA and EFSA labeling standards.
For Market Incumbents: Harden R&D investment in formulation expertise to overcome technical hurdles associated with gluten replacement. Expand production capacity in emerging geographies like the Middle East to capture nascent demand. Strengthen existing distribution networks within hypermarkets to maintain competitive positioning against smaller, niche brands. Prioritize investments in cross-contamination prevention technologies to reinforce consumer trust and regulatory compliance.
For New Entrants and Emerging Players: Emerging geographies in the Middle East and Latin America represent penetrable entry points for niche gluten-free brands. Target functional ingredient integration, combining gluten-free claims with probiotics or prebiotics to appeal to gut health-conscious consumers. Leverage online retail channels for direct-to-consumer reach, bypassing established brick-and-mortar distribution barriers. Focus on specific product categories like breakfast cereals or savory snacks with innovative alternative grain formulations.
For Investors and Strategic Acquirers: Capital is best deployed toward specialist manufacturers with strong R&D capabilities in alternative grain formulations and robust certification processes. These firms possess proprietary knowledge and established medical channels. Long-term viability rests on expanding product portfolios beyond basic replacements into functional and plant-based synergies. Watch for increased M&A activity consolidating formulation expertise and geographic reach, particularly among mid-sized European specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Alternative Grains | Improves taste and texture, attracting a broader consumer base. |
| Geographic Expansion (Emerging Markets) | Captures nascent demand in regions with rising health consciousness. |
| Functional Ingredient Integration | Differentiates products with added health benefits beyond gluten avoidance. |
| Supply Chain Certification Upgrade | Enhances consumer trust and facilitates cross-border trade compliance. |
| Food Service Channel Partnerships | Expands high-volume demand channels beyond traditional retail. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during the primary research phase, including food scientists, R&D directors, retail category managers, and food service procurement leads. This primary data was triangulated with extensive secondary validation from sources such as FDA and EFSA regulatory documents, WHO Codex Alimentarius standards, industry association reports, and financial filings of public companies. Bottom-up data collection was rigorously combined with top-down market sizing approaches.
Quantitative models were calibrated across the analysis window, integrating historical market trends and future growth projections. Segmentation dimensions modeled include product type, application, end-user, distribution channel, and regional regulatory stringency. Compound annual growth rates were derived from a multi-factor analysis considering consumer preference shifts and technological advancements. Input cost volatility for alternative flours and changing regulatory landscapes served as key forecast inputs.
Practitioners should monitor significant shifts in consumer dietary preferences or unexpected regulatory changes for early signals. Forecasts reflect assumptions regarding economic stability and ingredient availability. Material shifts in global trade policies or major agricultural disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Gluten-Free Popcorn Products Market
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
Global Lactose Intolerance Treatment Market
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
Italy Gluten-Free Foods and Beverages Market
Food Intolerance Products
France Gluten-Free Food and Beverage Market
Food Intolerance Products
Food Allergy and Intolerance Products Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market
Food Intolerance Products
Europe Gluten Free Foods and Beverages Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Low GI Food Market
Food Intolerance Products
Fermented Garlic and Onion Digestive Comfort Bases Market
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Celiac Disease Market