
 Asia-Pacific Gluten-Free Food and Beverages Market | 2026-2036
Asia-Pacific Gluten-Free Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Gluten-Free Food and Beverages Market Outlook
Coeliac Australia certification is collapsing as the baseline qualification for market entry across the region. Nestlé SA leverages its dairy alternatives portfolio to sustain shelf presence in Australian health food stores. General Mills Inc anchors its position through in-house production of gluten-free oat supply chains. Dr. Schär AG/SPA specializes in medical-grade bakery products that dominate pharmacy distribution channels.
Asia-Pacific gluten-free food and beverages encompass products formulated without wheat, barley, rye, or cross-contaminated oats, typically substituting rice flour, tapioca starch, or sorghum to achieve functional texture and shelf stability for consumer consumption. These formulations serve individuals with celiac disease, gluten sensitivity, and lifestyle-driven dietary exclusion across retail and foodservice channels. Bakery products command the widest margin pools due to ingredient complexity and premium positioning, while dairy alternatives represent the fastest-growing category as lactose-free and gluten-free claims converge on single labels. Online retail channels are displacing traditional supermarket dominance in India and Southeast Asia where direct-to-consumer subscription models reduce price transparency.
FSSAI gluten-free labeling standards in India and Australia's Food Standards Code collectively shape product formulation requirements and import clearance protocols across the region. BIS certification for processed food safety adds a secondary compliance layer for domestic manufacturers serving the Indian market. Stakeholders must monitor evolving allergen threshold definitions as regulators harmonize ppm limits for gluten content claims.
Market Dynamics
Certification fragmentation across Australia's Food Standards Code, India's FSSAI, and China's GB standards is forcing manufacturers to maintain parallel compliance systems rather than unified regional formulations.
Growth Catalysts
- Urban health-conscious consumption:Tier-one Chinese cities and metropolitan India are driving certified gluten-free snack purchases through pharmacy and specialty retail channels.
- FSSAI labeling harmonization:India's Food Safety and Standards Authority is clarifying gluten-free claim thresholds, reducing import clearance friction for compliant foreign manufacturers.
- Bakery product innovation:Rice flour and tapioca starch processing advances are improving texture parity with wheat-based alternatives in commercial foodservice applications.
Market Restraints
- Sorghum supply concentration:Australian and Indian domestic sorghum processors control critical gluten-free grain supply, creating input cost volatility during drought cycles.
- Cross-contamination infrastructure gaps:Shared milling facilities across Southeast Asia lack dedicated gluten-free production lines, forcing expensive facility segregation investments.
- Coeliac Australia certification erosion:The collapse of this baseline qualification is fragmenting trust signals, forcing retailers to verify multiple competing standards.
Strategic Opportunities
- Direct-to-consumer subscription models:Indian and Southeast Asian online retail channels are reducing price transparency and building recurring revenue streams outside supermarket dominance.
- Dairy alternatives convergence:Lactose-free and gluten-free dual claims on single labels are opening shelf space in Australian health food stores and Chinese premium retail.
- Medical-grade pharmacy distribution:Dr. Schär AG/SPA's pharmacy channel dominance demonstrates untapped potential for certified clinical nutrition positioning across Asia-Pacific markets.
Industry Challenges
- Multi-jurisdiction certification timelines:Australia's Food Standards Code updates, India's BIS processed food safety layer, and China's GB standards create overlapping compliance verification periods.
- Gluten-free oat supply chain integrity:In-house production requirements for uncontaminated oat sourcing demand capital-intensive vertical control over planting, harvesting, and processing stages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Gluten-Free Food and Beverages Market |
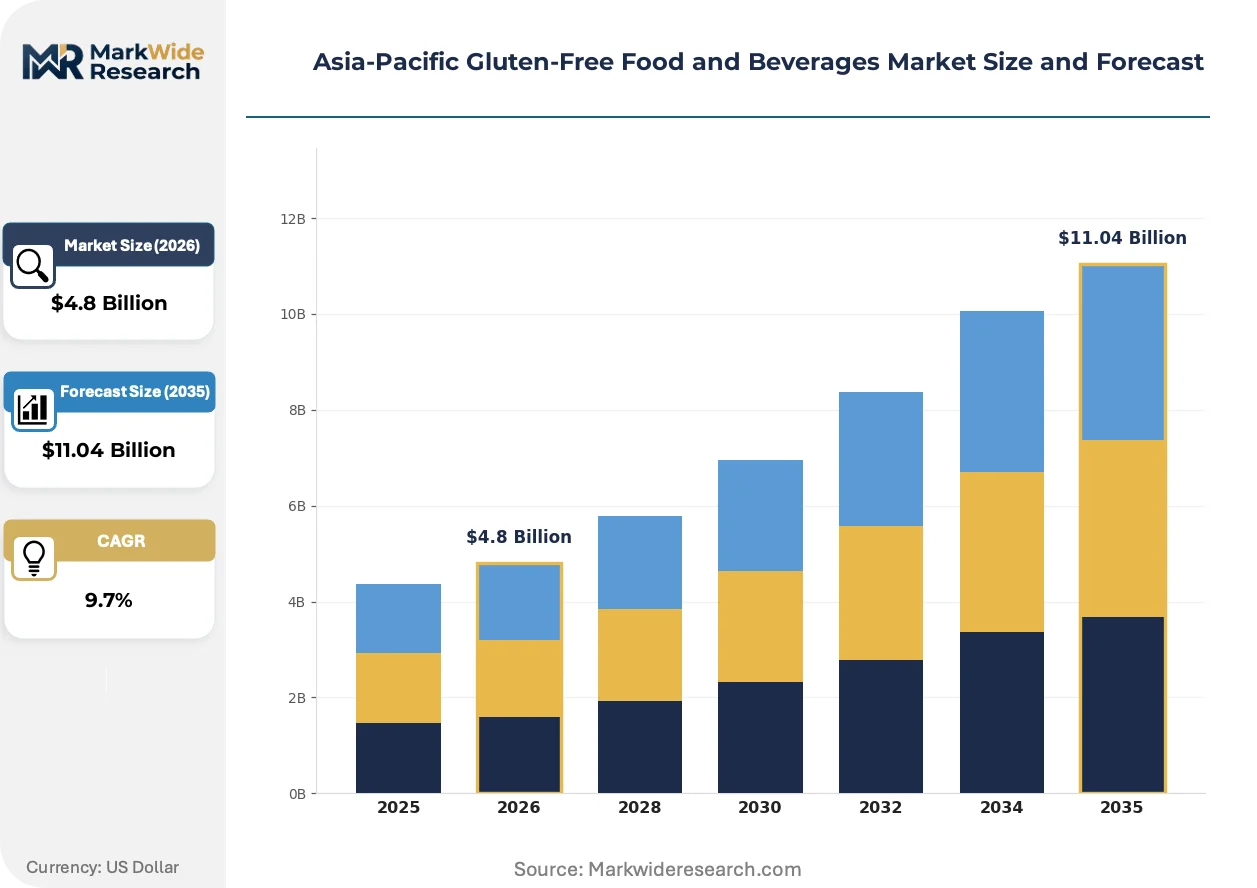
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Bakery Products, Dairy Alternatives, Beverages Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops End User: Individuals with Celiac Disease, Health-Conscious Consumers, Fitness Enthusiasts, Families Flavor Profile: Savory, Sweet, Spicy, Mild |
| Companies Covered | General Mills Inc, Conagra Brands Inc, Nestlé SA, The Kraft Heinz Company, Danone SA, Hain Celestial Group, PepsiCo Inc, The Kellogg Company, Dr. Schär AG/SPA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Gluten-Free Food and Beverages Market Strategic Shifts
Ingredient substitution science and distribution channel disintermediation are compressing traditional competitive advantages held by established bakery and dairy incumbents across the region.
Fermentation-based texture modification is displacing conventional hydrocolloid stabilization in gluten-free bakery formulations. Australian and Japanese manufacturers are adopting controlled fermentation of rice and pulse flours to achieve elastic dough structures without xanthan gum dependence. This biotechnology is displacing premium-priced imported hydrocolloids and enabling localized supply chain compression for mid-tier producers.
Australia's Food Standards Code gluten-free labeling updates are tightening ppm threshold definitions and cross-contact disclosure requirements. The regulation forces reformulation of imported products targeting the Australian market and accelerates domestic manufacturing investments to avoid compliance uncertainty. Bakery and snack segments with complex multi-ingredient supply chains face the steepest adaptation costs.
Urban Indian consumers are migrating from supermarket gluten-free aisles toward direct-to-consumer subscription platforms that bundle certified snacks with nutritional consultation. This channel shift is fragmenting traditional retail price discovery and enabling premium positioning through personalized dietary matching. Tier-one cities including Mumbai and Bangalore exhibit the highest subscription penetration rates.
Asia-Pacific Gluten-Free Food and Beverages Market Segmentation
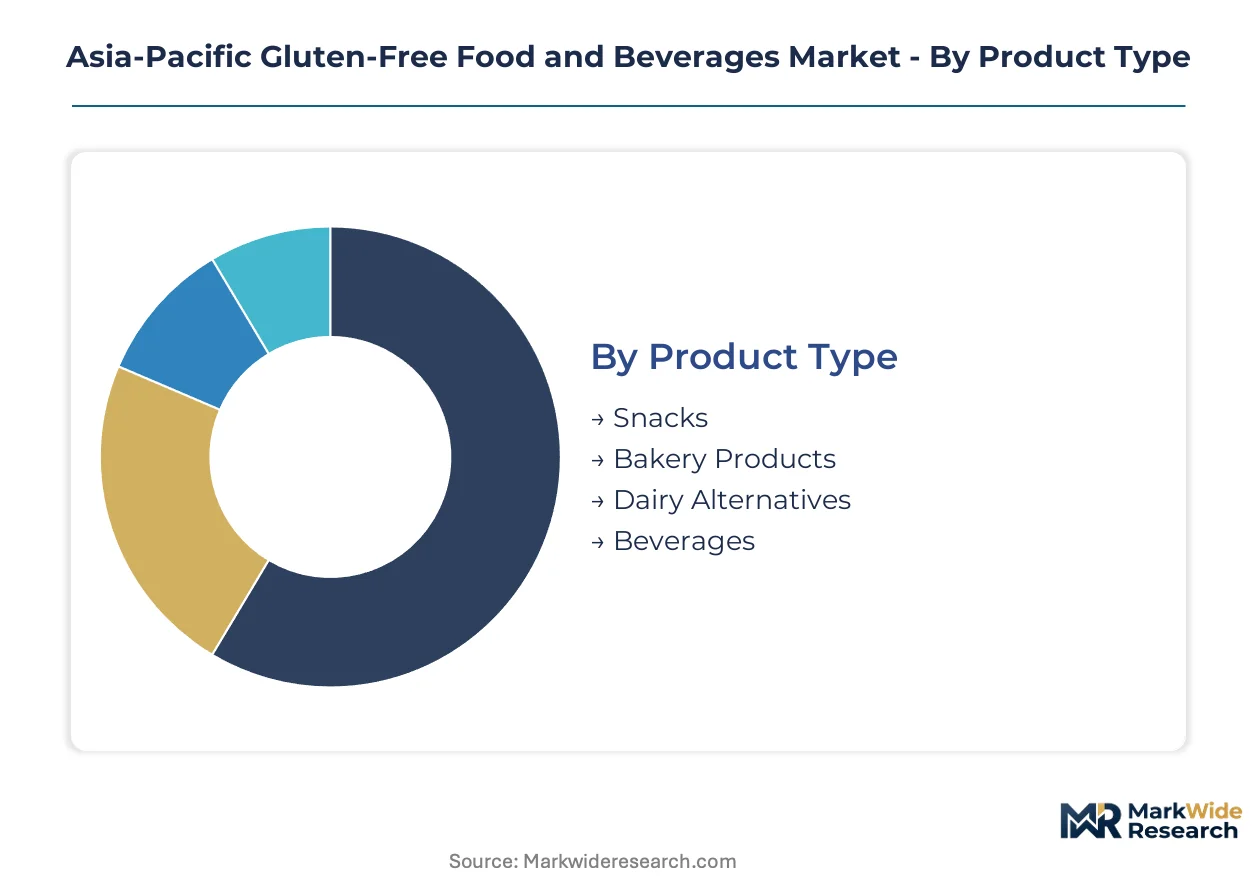
Segmentation in Asia-Pacific gluten-free markets determines channel access and certification requirements. Product type dictates margin structure, while distribution channel choice shapes consumer trust signals and price transparency.
Product Type:
Channel mix varies sharply across product categories, with pharmacy and specialty retail dominating medical-positioned segments while mass retail captures lifestyle-driven purchases.
- Bakery Products:Rice flour and tapioca starch formulations achieve functional texture parity with wheat-based alternatives. Demand concentrates in China's tier-one cities where commercial foodservice applications drive volume, constrained by Australia's Food Standards Code reformulation costs for imported goods.
- Dairy Alternatives:Lactose-free and gluten-free dual claims converge on single labels to capture shelf space. Expansion clusters in Australian health food stores and Chinese premium retail channels where Nestlé SA leverages existing distribution infrastructure.
- Snacks:Certified gluten-free snack purchases accelerate across urban India through pharmacy and specialty retail channels.
- Beverages:Gluten-free labeled drinks gain traction in Japanese and South Korean convenience store chains.
Bakery products dominate installed base. Dairy alternatives are where expansion concentrates.
Distribution Channel:
Cost tier stratification separates premium-positioned channels from volume-driven mass retail, with subscription models disrupting traditional price discovery.
- Online Retail:Direct-to-consumer subscription platforms fragment traditional retail price discovery in India and Southeast Asia. Mumbai and Bangalore exhibit highest subscription penetration for certified snack bundles with nutritional consultation.
- Supermarkets:Traditional aisle dominance erodes as urban Indian consumers migrate toward personalized dietary matching platforms.
- Health Food Stores:Australian channels sustain premium positioning through dairy alternatives convergence and pharmacy-adjacent trust signals.
- Specialty Shops:Dr. Schär AG/SPA's pharmacy channel strategy demonstrates clinical nutrition positioning potential across tier-one Chinese cities.
Supermarkets dominate installed base. Online retail is climbing the fastest.
End User:
Application severity determines certification stringency, with medical-grade requirements separating clinical nutrition from lifestyle exclusion segments.
- Individuals with Celiac Disease:Medical-grade bakery products require Coeliac Australia or equivalent certification for pharmacy distribution access.
- Health-Conscious Consumers:Urban health-conscious consumption drives certified gluten-free snack purchases through tier-one Chinese city channels.
- Fitness Enthusiasts:Protein-fortified gluten-free formulations gain traction in Australian and Japanese sports nutrition retail.
- Families:Multi-allergen-free claims target household pantry stocking in Indian metropolitan markets.
Health-conscious consumers dominate installed base. Individuals with celiac disease represent the steepest expansion trajectory.
Flavor Profile:
Geography determines preference clustering, with regional taste adaptation requiring localized formulation rather than standardized export recipes.
- Savory:Rice flour-based savory snacks align with Southeast Asian palates and dominate Indonesian and Vietnamese retail penetration.
- Sweet:Tapioca starch desserts capture Chinese and Japanese bakery innovation pipelines.
- Spicy:Chili-infused gluten-free formulations target Indian and Thai urban markets.
- Mild:Neutral flavor profiles serve pediatric and elderly clinical nutrition segments across Australian pharmacy channels.
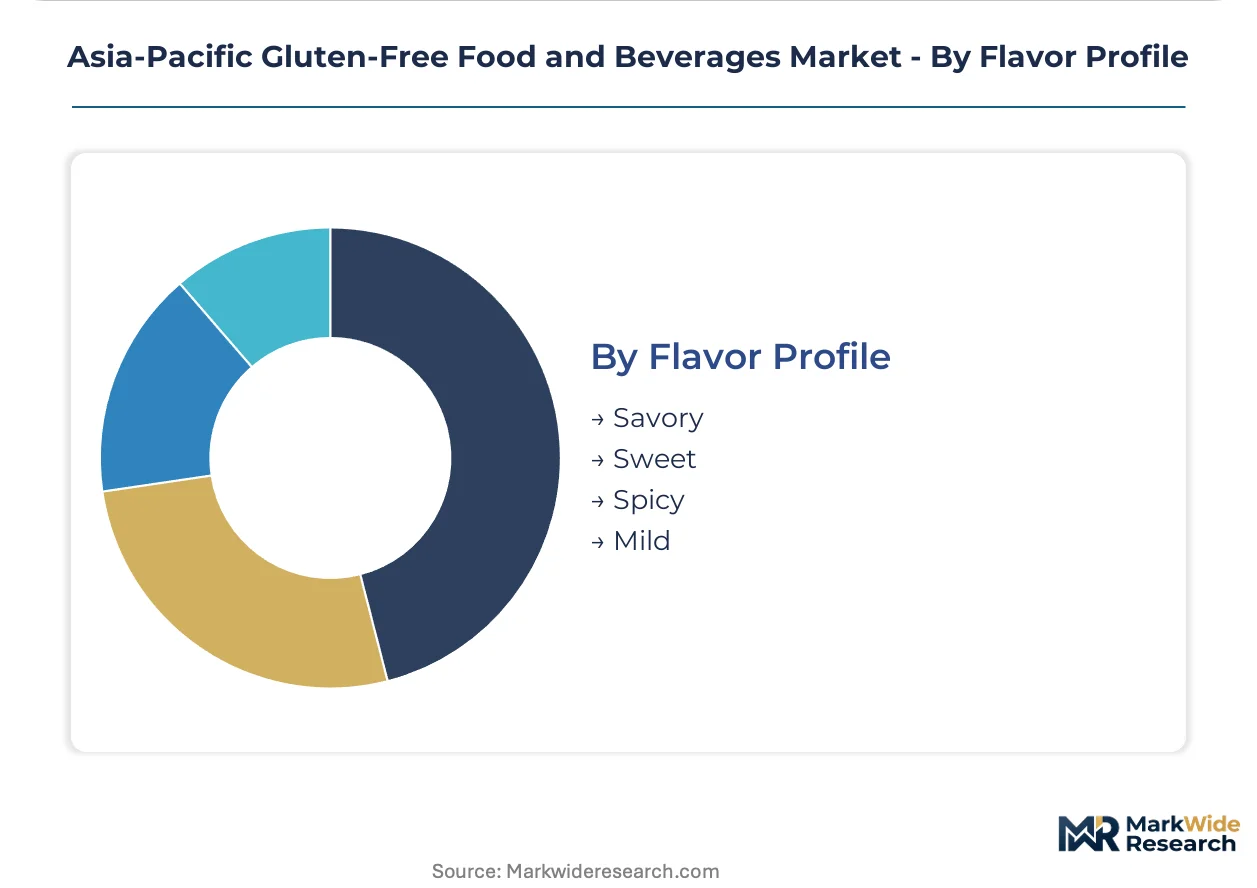
Savory dominates installed base. Sweet is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's refrigerated container throughput underwrites China's role as the regional import gateway for specialty food ingredients. Australian bulk grain terminals at Newcastle and Fremantle anchor sorghum and oat export flows to Southeast Asian processors. Singapore's cold chain logistics hub redistributes certified gluten-free formulations across ASEAN markets.
China
Shanghai and Beijing consumers drive bakery product innovation through commercial foodservice channels. GB standards on gluten-free labeling establish ppm thresholds for domestic manufacturing and import clearance. Yangtze River Delta food tech clusters accelerate rice flour processing advances for texture parity in wheat alternatives.
India
Mumbai and Bangalore health-conscious consumers expand certified snack purchases through pharmacy and subscription platforms. FSSAI gluten-free claim harmonization reduces import friction for compliant foreign manufacturers. Maharashtra's processed food corridor attracts domestic manufacturing investments to serve metropolitan demand.
Australia
Food Standards Code updates tighten cross-contact disclosure requirements for imported bakery goods. Sydney and Melbourne health food stores sustain premium positioning through dairy alternatives convergence. Domestic sorghum processors in Queensland control critical gluten-free grain supply during drought cycles.
Japan
Tokyo and Osaka convenience store chains expand gluten-free labeled beverage distribution. METI standards on functional food claims shape medical-grade product positioning. Kanto region fermentation technology clusters advance rice flour texture modification for elastic dough structures.
South Korea
Seoul Capital Area consumers drive protein-fortified gluten-free formulation demand through sports nutrition retail. MFDS allergen threshold definitions influence import compliance protocols. Busan-Ulsan logistics hubs facilitate ingredient redistribution to domestic bakery manufacturers.
Asia-Pacific Gluten-Free Food and Beverages Market Competitive Environment
Listed leaders compete with private specialists across certification and distribution channel dimensions. The vendor base separates into multinational packaged food conglomerates, dedicated gluten-free specialists, and regional private label manufacturers. Three archetypes dominate: scale-driven portfolio diversifiers, medical-grade clinical nutrition specialists, and direct-to-consumer subscription platforms. Competitive moves concentrate on M&A for oat supply chain control and strategic partnerships with pharmacy distribution networks.
Within the multinational conglomerate tier, Nestlé SA and General Mills Inc exemplify scale-driven portfolio diversification across dairy alternatives and in-house oat supply chains. Dr. Schär AG/SPA occupies the medical-grade specialist position, anchoring pharmacy channel strategies that demonstrate clinical nutrition positioning potential. These three entities represent divergent competitive vectors: Nestlé SA leverages existing distribution infrastructure, General Mills Inc pursues upstream supply chain control, and Dr. Schär AG/SPA concentrates on certification-intensive medical segments.
| Leading Market Players |
|---|
| General Mills Inc |
| Conagra Brands Inc |
| Nestlé SA |
| The Kraft Heinz Company |
| Danone SA |
| Hain Celestial Group |
| PepsiCo Inc |
| The Kellogg Company |
| Dr. Schär AG/SPA |
| Others |
Value Chain & Pricing Dynamics
Mill-scale efficiencies at Australian sorghum processors and Yangtze River Delta rice flour clusters compress unit economics for certified gluten-free formulations, concentrating pricing power among integrated operators while fragmenting margin capture across toll-milling dependent competitors.
Pricing Analysis
Volume-discount tiering structures stratify across premium pharmacy-grade, standard retail-certified, and economy private-label tiers. Price differentiation hinges on Coeliac Australia or FSSAI certification grade and geographic delivery cost to tier-one Chinese and Indian cities. Cost compression in the standard tier is intensifying as Yangtze River Delta capacity additions flood regional markets with rice flour alternatives. Health-conscious urban consumers in Mumbai and Bangalore exhibit lowest price sensitivity, while Southeast Asian mass retail buyers drive hardest bargain pressure.
Supply Chain Analysis
Strait of Malacca transit underwrites ingredient redistribution to ASEAN gluten-free processors, creating logistics chokepoint exposure for Australian sorghum and Indian tapioca starch flows. Geographic supply concentration centers on Queensland sorghum belts, Maharashtra processed food corridors, and Yangtze River Delta rice flour clusters. Raw material dependencies rest on uncontaminated oat sourcing, certified rice flour supply, and tapioca starch refining capacity. Single-source vulnerability concentrates in gluten-free oat supply chains where General Mills-style in-house production remains rare. Distribution runs through Singapore cold chain hubs for ASEAN markets, direct-to-consumer platforms for Indian metros, and pharmacy networks for Australian medical-grade segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification fragmentation across FSSAI, Australia's Food Standards Code, and GB standards fragments competitive positions, creating service-layer niches where unified compliance offerings capture premium positioning.
For Market Incumbents: Consolidate oat supply chain control through backward integration into Queensland or Victorian planting operations before drought cycles tighten grain availability. Lock pharmacy distribution exclusivity in tier-one Chinese cities before Dr. Schär AG/SPA replication accelerates. Certification investment in parallel FSSAI and Food Standards Code compliance systems defends against emerging Indian and Australian private-label threats. For New Entrants and Emerging Players: Nutritional consultation bundling gaps expose subscription platform opportunities where incumbents under-serve personalized dietary matching demand. White-space targets concentrate in direct-to-consumer certified snack bundles for Bangalore and Mumbai health-conscious segments, plus fermentation-based texture modification services for mid-tier Japanese and Australian bakery manufacturers. Go-to-market angle: clinical nutrition positioning through pharmacy channel partnerships in Chinese tier-one cities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription platforms with nutritional consultation bundling, offering superior cash-flow quality against transactional retail-dependent competitors. Long-term viability over the coming decade favors operators with captive gluten-free grain supply and multi-jurisdiction certification infrastructure. Acquisition target archetype: mid-tier rice flour processors with FSSAI compliance and Yangtze River Delta location. Signal to watch: Food Standards Code ppm threshold tightening accelerating domestic Australian manufacturing investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gluten-Free Oat Supply | Queensland and Victorian planting operations eliminate cross-contamination risk and drought-cycle price volatility. |
| Direct-to-Consumer Subscription Launch | Mumbai and Bangalore platforms capture health-conscious consumers migrating from supermarket aisles. |
| Multi-Jurisdiction Certification Investment | Parallel FSSAI and Food Standards Code compliance reduces import friction and accelerates market access. |
| Fermentation-Based Texture Modification Adoption | Japanese and Australian biotechnology clusters displace premium hydrocolloid imports for mid-tier bakery producers. |
| Pharmacy Distribution Channel Expansion | Tier-one Chinese city networks replicate Dr. Schär AG/SPA medical-grade positioning for clinical nutrition segments. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with gluten-free product development directors, FSSAI regulatory affairs leads, Australian health food store category buyers, and pharmacy procurement managers; and secondary validation through FSSAI labeling guidelines, Australia's Food Standards Code amendments, GB standards documentation, and customs trade flow records. Bottom-up triangulation against top-down macroeconomic drivers ensured segmentation integrity.
Across the analysis window, the forecasting framework modeled product type, distribution channel, end-user severity tier, and flavor profile dimensions. CAGRs derived from volume trajectory analysis incorporating urbanization rates, certification penetration curves, and channel shift elasticities. Industry-specific inputs included sorghum harvest variability indices and rice flour processing capacity utilization across Yangtze River Delta clusters.
Underlying assumptions cover sustained FSSAI harmonization progress and stable Australia-China grain trade flows, with deviation risk concentrated in drought-induced sorghum supply shocks and Food Standards Code threshold revisions. Practitioners should keep alternative scenarios live as regulatory harmonization timelines and climate volatility patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Allergen Free Food Products Market
Food Intolerance Products
Egg Allergy Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
United States Gluten Free Foods and Beverages Market
Food Intolerance Products
Italy Gluten-Free Foods and Beverages Market
Food Intolerance Products
Allergen Free Food Market
Food Intolerance Products
Global Gluten Free Prepared Foods Market
Food Intolerance Products
North America Gluten-Free Food and Beverage Market
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
Dyspepsia Market
Food Intolerance Products
Australia Gluten-Free Foods and Beverages Market
Food Intolerance Products
Global Lactose Intolerance Treatment Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
Low GI Food Market
Food Intolerance Products
Argentina Gluten-Free Food and Beverage Market