
 Hydrolyzed Formula Milk Powder Market | 2026-2036
Hydrolyzed Formula Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrolyzed Formula Milk Powder Market Insights
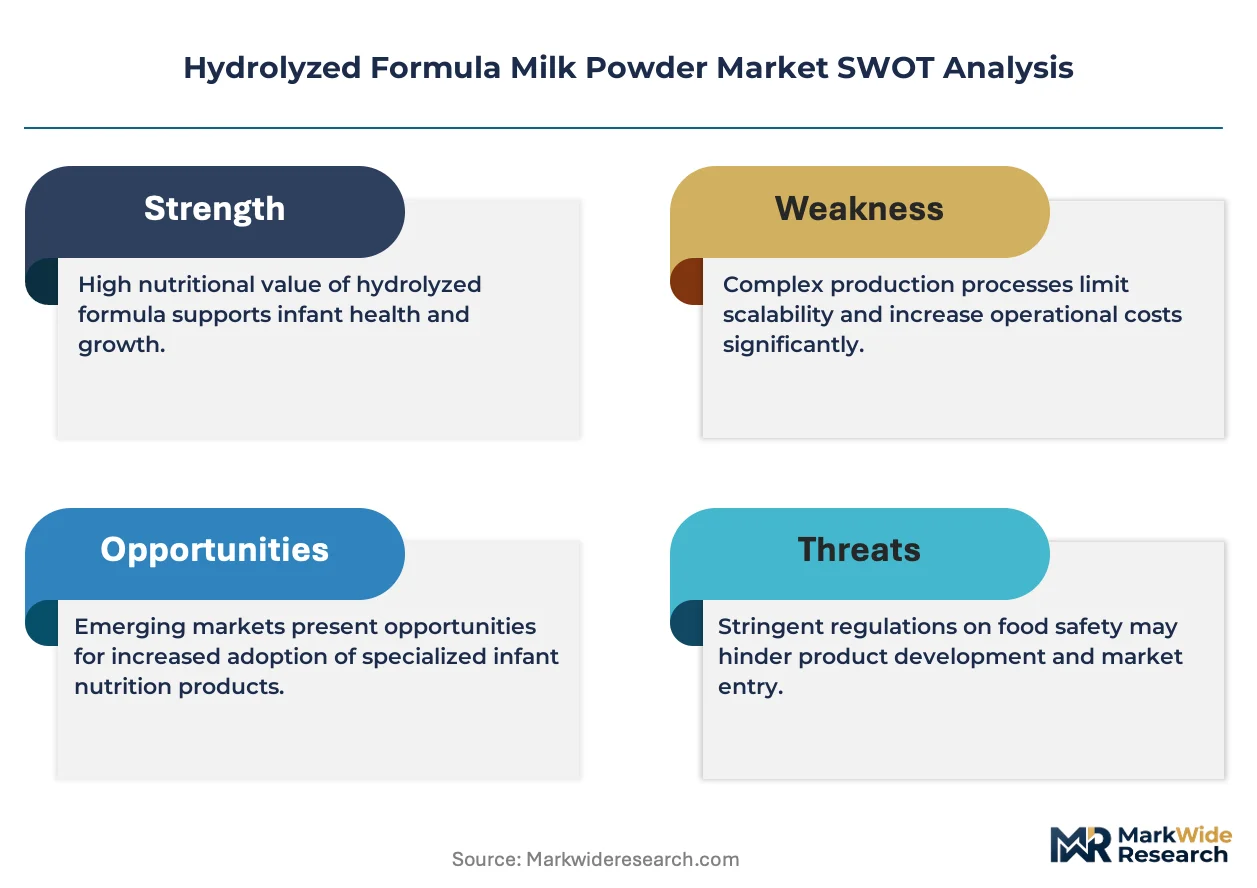
Consolidation among hospital group purchasing organizations is repositioning procurement leverage toward institutional buyers with specialized pediatric units. Nestlé S.A. leverages its clinical nutrition heritage to sustain long-term supply contracts with European hospital networks. Abbott Laboratories anchors its position through extensive extensively hydrolysate R&D pipelines. Danone S.A. competes via differentiated pharmacy-channel relationships that restrict competitor shelf access.
Hydrolyzed formula milk powder consists of cow milk proteins enzymatically broken into smaller peptides or free amino acids, typically achieving molecular weights below 3,000 daltons to reduce allergenic potential for immunocompromized consumers. The manufacturing process employs controlled proteolysis followed by ultrafiltration to standardize peptide distribution profiles for clinical tolerance. Extensively hydrolysate formulations command premium positioning due to stringent clinical validation requirements and narrow supplier bases. Infant end users dominate volume flows, though adult medical nutrition applications are expanding fastest through specialty pharmacy channels. Powder form maintains cost advantages in institutional purchasing, while ready-to-feed liquid variants capture margin pools in convenience-oriented retail segments.
FDA infant formula regulations govern nutritional adequacy claims and manufacturing facility inspections in the United States, while EFSA oversees hypoallergenic substantiation standards across European markets. China's NMPA and national food safety standards impose additional registration barriers for imported hydrolyzed formulations. Stakeholders must monitor evolving peptide-threshold definitions across jurisdictions, as regulatory divergence threatens to fragment product portfolios and complicate cross-border certification strategies.
Market Dynamics
Hospital neonatal unit procurement consolidation is compressing supplier margins while elevating clinical validation requirements as the decisive competitive filter. EFSA's tightening hypoallergenic substantiation protocols are forcing reformulation investments across European manufacturing footprints.
Growth Catalysts
- EFSA hypoallergenic labeling mandates:Stricter peptide-threshold definitions are accelerating clinical trial investments and filtering out undercapitalized competitors from European pharmacy shelves.
- Pediatric allergy management protocols:Hospital neonatal units are embedding hydrolyzed formulas into standardized immunocompromized infant care pathways, locking in institutional demand.
- Enzymatic proteolysis refinement:Advances in controlled hydrolysis are enabling more precise molecular weight targeting below 3,000 daltons, improving tolerance profiles for severely allergic infants.
Market Restraints
- Whey protein concentrate volatility:Dairy commodity input costs fluctuate with New Zealand and EU milk powder auction cycles, compressing gross margins unpredictably.
- Ultrafiltration equipment oligopoly:Membrane system supply concentrates among German and Danish engineering specialists, creating capex bottlenecks for new market entrants.
- Amino acid formula substitution:Elemental free-amino-acid alternatives capture severe allergy cases that hydrolyzed peptides cannot tolerate, capping addressable market ceiling.
Strategic Opportunities
- Adult medical nutrition expansion:Oncology and post-surgical recovery applications through specialty pharmacy channels represent underexploited volume pools beyond infant use.
- China NMPA registration pathways:Streamlined imported formula registration for clinically validated products is opening access to urban tier-one hospital networks.
- Ready-to-feed liquid formats:Convenience-positioned packaging is capturing premium margin pools in direct-to-consumer subscription channels underserved by powder-dominant incumbents.
Industry Challenges
- Peptide analytics talent scarcity:Specialized chromatography and mass spectrometry expertise for batch consistency verification is concentrated among a narrow pool of European contract laboratories.
- Cross-jurisdiction certification divergence:FDA nutritional adequacy inspections, EFSA hypoallergenic claims, and NMPA registration requirements create fragmented product portfolio complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrolyzed Formula Milk Powder Market |
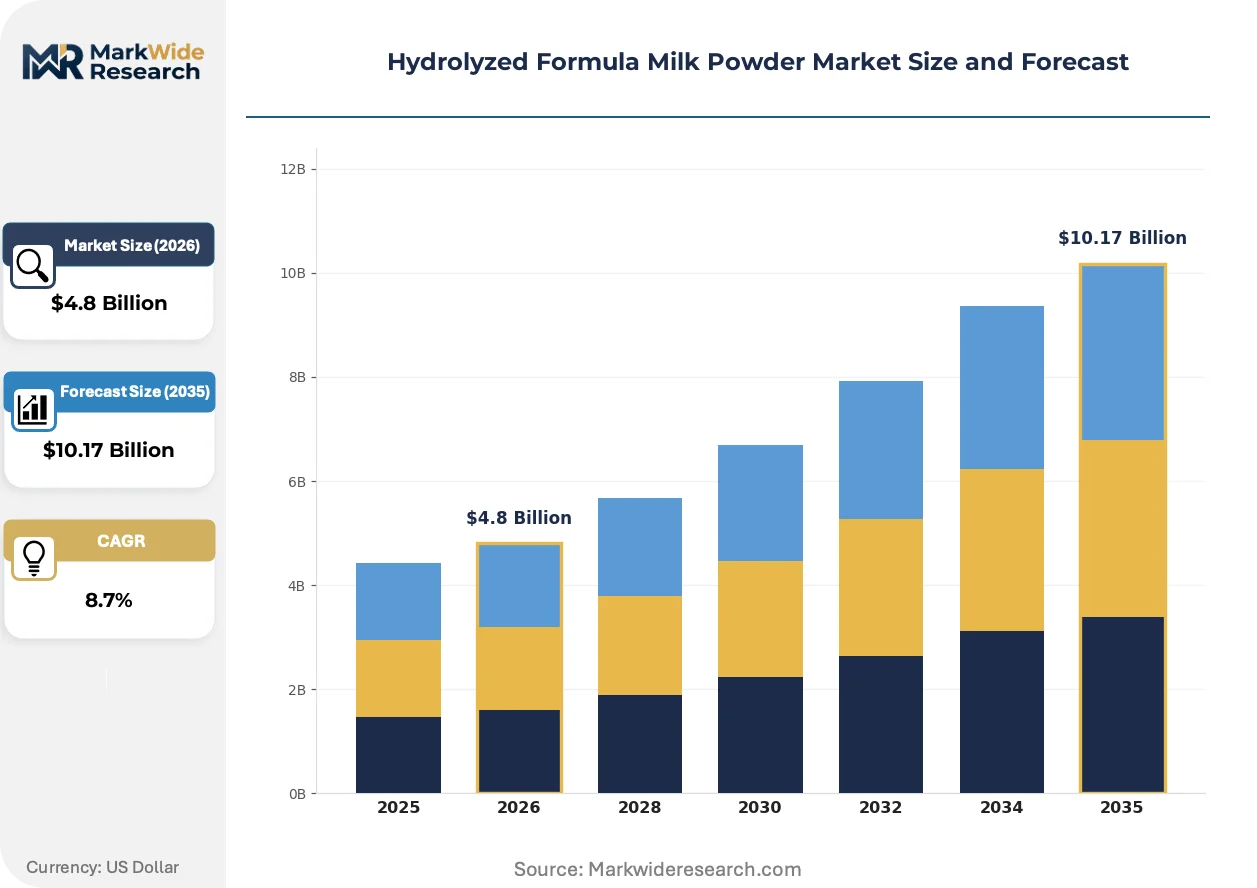
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Partial Hydrolysate, Extensively Hydrolysate, Free Amino Acid, Others End User: Infants, Children, Adults, Elderly Distribution Channel: Online Retailers, Hypermarkets, Specialty Stores, Pharmacies Form: Powder, Liquid, Ready-to-Feed, Concentrate |
| Companies Covered | Nestlé S.A., Abbott Laboratories, Danone S.A., Mead Johnson Nutrition, FrieslandCampina, Arla Foods, Nutricia, Meiji Group, Perrigo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrolyzed Formula Milk Powder Market Trends and Innovations
Precision enzymatic processing and regulatory data transparency are compressing product development cycles while elevating clinical evidence as the primary competitive differentiator. Manufacturing control systems are converging with real-time quality analytics.
Multi-enzyme cascade hydrolysis is unifying previously separate proteolysis and peptide fractionation steps into continuous manufacturing lines. German dairy engineering specialists are deploying these integrated systems at scale. The technology is unifying quality control and production scheduling, collapsing batch release timelines from weeks to days.
EFSA's 2023 updated guidance on hypoallergenic claims demands quantitative peptide mapping and clinical tolerance studies for label authorization. Manufacturers must submit standardized molecular weight distribution profiles alongside pediatric immunology data. Extensively hydrolysate formulations face the steepest compliance burden, advantaging incumbents with established clinical research infrastructure.
Hospital group purchasing organizations are consolidating formulary decisions across multi-hospital networks, compressing supplier rosters to three or fewer approved vendors per therapeutic category. Neonatal intensive care units in France and the Netherlands are piloting direct-manufacturer consignment models that bypass traditional pharmaceutical wholesalers. Germany's specialized infant nutrition retail channel remains the most concentrated geography for this procurement transformation.
Hydrolyzed Formula Milk Powder Market Segmentation
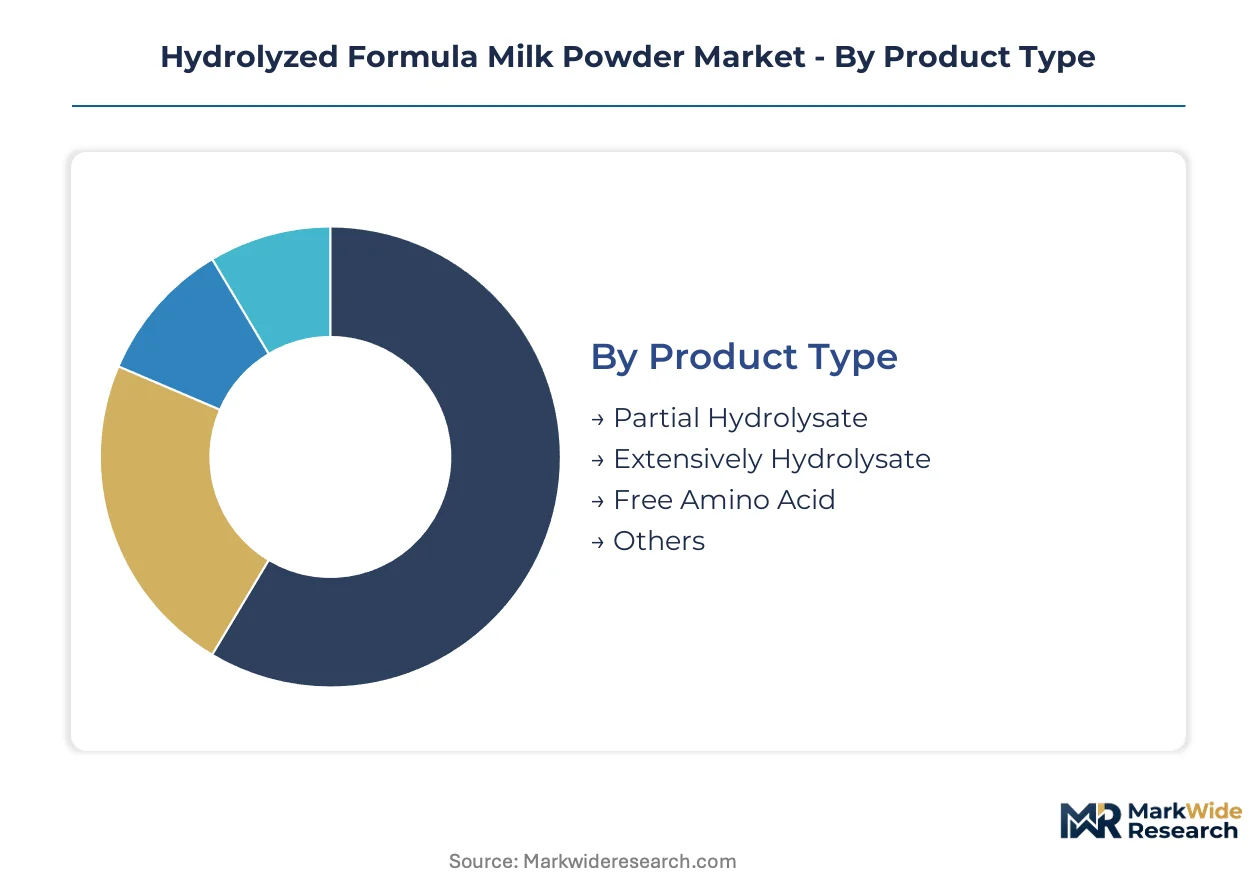
Segmentation in hydrolyzed formula milk powder reveals distinct clinical validation tiers and channel access barriers. Manufacturers must align peptide hydrolysis depth with end-user tolerance thresholds and procurement pathway requirements.
Product Type:
Integration depth varies sharply: extensively hydrolysate and free amino acid formulations demand embedded clinical infrastructure, while partial hydrolysate operates in standalone retail environments.
- Extensively Hydrolysate:Proteins broken to peptides below 3,000 daltons through controlled enzymatic proteolysis and ultrafiltration. Hospital neonatal units in Germany and the Netherlands concentrate procurement here, driven by EFSA hypoallergenic labeling mandates requiring quantitative peptide mapping and pediatric immunology data.
- Partial Hydrolysate:Moderate hydrolysis preserves some immunogenic epitopes, positioning for mild allergy prevention rather than treatment. Demand clusters in France's specialized infant nutrition retail channel, constrained by tighter margins and lower clinical validation barriers.
- Free Amino Acid:Elemental formulations bypass peptide structures entirely for severe allergy cases. Oncology and post-surgical recovery applications through specialty pharmacy channels are expanding fastest.
- Others:Emerging hybrid formulations and condition-specific blends targeting metabolic disorders.
Extensively hydrolysate leads volumes today; free amino acid is gaining share fastest.
End User:
Cost tier stratification separates institutional reimbursement pathways from out-of-pocket retail purchases.
- Infants:Neonatal intensive care units and allergy management protocols dominate volume. EMEA hospital group purchasing organizations consolidate formulary decisions across multi-hospital networks, compressing supplier rosters.
- Adults:Medical nutrition applications in oncology and post-surgical recovery represent the steepest expansion trajectory. Specialty pharmacy channels in urban tier-one hospital networks capture premium positioning.
- Children:Transitional formulations bridging infant and adult nutritional requirements.
- Elderly:Sarcopenia and dysphagia management applications with nasogastric feeding compatibility requirements.
Infant applications anchor revenue today; adult medical nutrition is climbing the fastest.
Distribution Channel:
Volume concentration follows procurement consolidation patterns, with institutional buyers extracting pricing leverage through direct-manufacturer relationships.
- Pharmacies:European pharmacy-channel relationships restrict competitor shelf access through exclusive distribution agreements. EFSA-compliant hypoallergenic claims require clinical validation documentation at point of sale.
- Online Retailers:Direct-to-consumer subscription channels for ready-to-feed liquid formats capture convenience premiums. China's NMPA registration pathways for imported formulations are streamlining cross-border access.
- Specialty Stores:Germany's concentrated infant nutrition retail channel maintains specialized staff training and clinical consultation services.
- Hypermarkets:Mass-market partial hydrolysate positioning with lower clinical validation requirements and compressed margins.
Pharmacies dominate value capture today; online retailers are expanding most quickly.
Form:
Margin structure inverts between institutional cost optimization and retail convenience premiums.
- Powder:Cost advantages in institutional purchasing through bulk packaging and extended shelf stability. Hospital neonatal units prioritize powder for inventory management efficiency.
- Ready-to-Feed:Convenience-oriented packaging captures premium margin pools in direct-to-consumer channels. Liquid sterilization and aseptic filling requirements concentrate manufacturing among established players.
- Liquid:Intermediate processing stage requiring refrigeration, limiting distribution radius.
- Concentrate:Dilution-required format for cost-sensitive institutional segments with on-site preparation capabilities.
Powder leads institutional volumes today; ready-to-feed is gaining share fastest in retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's specialized infant nutrition retail channel concentrates procurement leverage more sharply than the United States' fragmented hospital purchasing landscape. This divergence shapes how manufacturers allocate clinical validation investments across Atlantic markets.
United States
FDA infant formula regulations govern nutritional adequacy claims and manufacturing facility inspections, compressing supplier rosters through stringent compliance barriers. Hospital neonatal units embed hydrolyzed formulas into standardized immunocompromized infant care pathways. Greater Boston's pediatric research corridor anchors clinical trial infrastructure for peptide tolerance studies.
Germany
EFSA hypoallergenic labeling mandates demand quantitative peptide mapping and pediatric immunology data for market access. Pharmacy-channel relationships restrict competitor shelf access through exclusive distribution agreements. Bavaria's dairy engineering specialists deploy multi-enzyme cascade hydrolysis systems at commercial scale.
China
NMPA registration pathways for imported clinically validated products streamline access to urban tier-one hospital networks. National food safety standards impose additional barriers for foreign hydrolyzed formulations. Shanghai's specialty pharmacy channels capture premium positioning for adult medical nutrition applications.
Netherlands
Hospital group purchasing organizations consolidate formulary decisions across multi-hospital networks, compressing supplier rosters to three or fewer approved vendors. Neonatal intensive care units pilot direct-manufacturer consignment models bypassing traditional pharmaceutical wholesalers. Utrecht's clinical nutrition research cluster validates extensively hydrolysate tolerance profiles.
France
ANSM oversees pharmaceutical-grade infant formula manufacturing standards alongside EFSA hypoallergenic substantiation requirements. Specialized infant nutrition retail channels maintain trained staff for clinical consultation services. Paris-region hospital networks concentrate procurement leverage through centralized neonatal unit purchasing.
Hydrolyzed Formula Milk Powder Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered validation requirements. Extensively hydrolysate formulations concentrate among players with embedded clinical research infrastructure, while partial hydrolysate permits broader participation. Three archetypes dominate: multinational nutrition conglomerates with hospital network contracts, regional dairy processors with enzymatic processing capabilities, and pharmaceutical-grade specialists with peptide analytics expertise. Competitive moves center on M&A for clinical trial assets and strategic partnerships for membrane filtration technology access.
Among Swiss-based nutrition conglomerates, Nestlé S.A. occupies a position exemplifying clinical nutrition heritage leveraged toward long-term supply contracts. Abbott Laboratories represents the extensively hydrolysate R&D archetype through its anchored market presence. Danone S.A. sits within the pharmacy-channel relationship tier, restricting competitor shelf access through differentiated distribution positioning.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Abbott Laboratories |
| Danone S.A. |
| Mead Johnson Nutrition |
| FrieslandCampina |
| Arla Foods |
| Nutricia |
| Meiji Group |
| Perrigo |
| Others |
Pricing and Supply Chain Analysis
Captive upstream control over enzymatic processing and ultrafiltration infrastructure anchors both supply security and premium pricing power for extensively hydrolysate manufacturers. Hospital group purchasing organizations exploit this concentration to extract volume discounts while locking suppliers into long-term clinical validation commitments.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for extensively hydrolysate formulations as Bavarian dairy engineering specialists deploy multi-enzyme cascade systems at scale. Three-tier pricing structure across extensively hydrolysate, partial hydrolysate, and free amino acid levels stratifies by clinical validation depth and EFSA hypoallergenic certification tier. Pricing pressure stems from whey protein concentrate volatility tied to New Zealand and EU milk powder auction cycles. Hospital neonatal units demonstrate lowest price sensitivity due to reimbursement pathways, while mass-market hypermarket channels face acute margin compression.
Supply Chain Analysis
China's NMPA domestic-content mandates for imported formula registration are reshaping sourcing patterns as manufacturers establish localized peptide analytics capabilities. Raw material supply concentrates in New Zealand for whey protein concentrates, Germany for membrane filtration equipment, and Denmark for enzymatic processing systems. Ultrafiltration membrane production draws from a German-Danish engineering oligopoly, creating single-source vulnerability for new entrants. Distribution runs through hospital group purchasing organizations in Europe and specialty pharmacy channels in China's tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as pediatric allergy management protocols shift demand toward EFSA-validated extensively hydrolysate formulations with quantitative peptide mapping documentation.
For Market Incumbents: Anticipate amino acid formula substitution threats by deepening clinical trial infrastructure for severe allergy tolerance studies. Secure backward integration into enzymatic processing capabilities to insulate margins from whey protein concentrate volatility. Lock in exclusive pharmacy-channel relationships before NMPA registration pathways streamline competitor access to China's urban hospital networks. For New Entrants and Emerging Players: Enter via adult medical nutrition applications in oncology and post-surgical recovery, the least penetrated segment with specialty pharmacy channel access. Target China's tier-one hospital networks through streamlined NMPA registration for clinically validated products. Deploy ready-to-feed liquid formats through direct-to-consumer subscription channels to bypass powder-dominant incumbent shelf control. For Investors and Strategic Acquirers: Roll-up economics work for peptide analytics contract laboratories because EFSA's 2023 hypoallergenic guidance mandates quantitative mapping capabilities that concentrate among European specialists. Five-to-ten year viability hinges on clinical validation infrastructure rather than commodity manufacturing scale. Watch for NMPA registration approval velocity as the inflection signal for China market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Infrastructure Investment | EFSA peptide mapping requirements demand embedded mass spectrometry and pediatric immunology capabilities. |
| Multi-Enzyme Cascade Hydrolysis Deployment | German engineering specialists unify proteolysis and fractionation into continuous manufacturing lines. |
| Hospital GPO Direct Consignment Models | Netherlands neonatal intensive care units bypass pharmaceutical wholesalers for manufacturer-direct supply. |
| NMPA Registration Pathway Optimization | Streamlined imported formula access opens China's urban tier-one hospital procurement networks. |
| Specialty Pharmacy Channel Expansion | Adult medical nutrition applications in oncology capture premium positioning beyond infant segments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with neonatal nutrition directors, hospital procurement managers, pharmacy-channel category buyers, and enzymatic processing engineers with secondary validation from FDA infant formula regulations, EFSA hypoallergenic guidance documents, NMPA registration databases, and customs trade records. Bottom-up volume estimates by product type and end user triangulated against top-down market sizing across the analysis window.
Historical reference periods anchored the forecast window to pre- and post-EFSA 2023 guidance implementation phases, modeling extensively hydrolysate, partial hydrolysate, free amino acid, and hybrid formulation segments alongside infant, adult, child, and elderly end-user categories. CAGRs derived from regression analysis of peptide-threshold regulatory adoption curves and hospital procurement consolidation rates, with enzymatic processing capacity expansion and NMPA registration velocity as key forecast inputs.
Inputs from European hospital group purchasing organizations and Chinese specialty pharmacy channels were available through the study window; gaps in real-time whey protein concentrate auction pricing introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding EFSA enforcement consistency and NMPA streamlining trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
Canned Baby Food Market
Baby Food and Infant Formula
Baby Food Market
Baby Food and Infant Formula
Russia Pet Food Market
Baby Food and Infant Formula
Indonesia Infant Nutrition Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Infant Formula Ingredients Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
Organic Baby Food Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Wet Cat Food Market
Baby Food and Infant Formula
West Africa Baby Food Market
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
Baby Food Testing Market
Baby Food and Infant Formula
Parenteral Formula Market