
 Gluten-Free Popcorn Products Market | 2026-2036
Gluten-Free Popcorn Products Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten-Free Popcorn Products Market Analytics
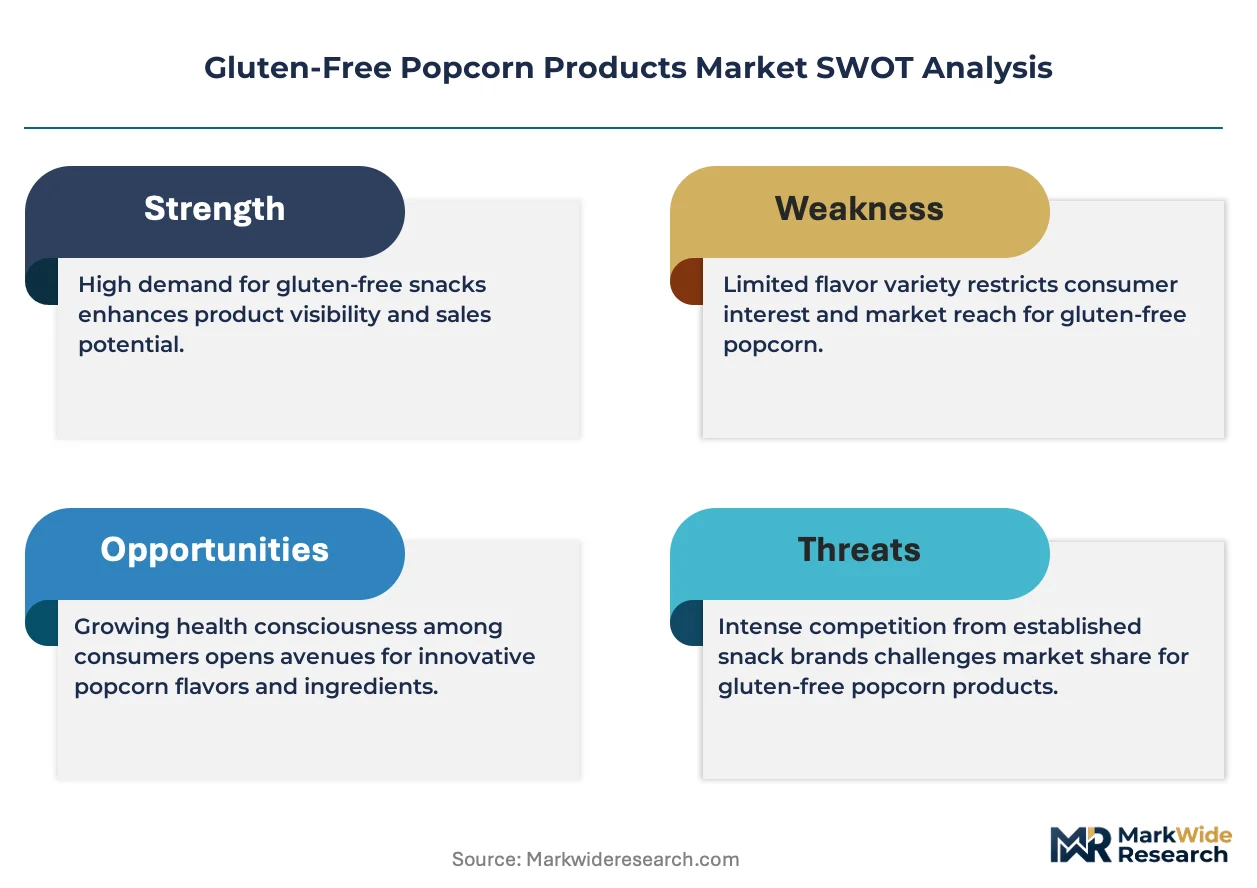
The capital-intensity gap between artisanal entrants and national manufacturers is collapsing as co-packing infrastructure scales across the Midwest. Conagra Brands leverages its frozen-to-shelf distribution network to secure mass retail placement. LesserEvil Snacks anchors its position through in-house oil sourcing and small-batch kettle production. Quinn Snacks differentiates via farm-to-bag transparency and paper packaging innovation.
Gluten-free popcorn products comprise maize kernels processed in facilities certified to prevent cross-contact with wheat, barley, or rye, typically achieving less than 20 parts per million gluten content through dedicated supply chains and validated cleaning protocols. The primary commercial purpose centers on delivering shelf-stable snacking options to celiac patients and gluten-avoidant households without sensory compromise. Air-popped formats command premium shelf space in health stores as calorie-conscious positioning offsets lower flavor intensity. E-commerce channels capture accelerating trial among subscription-oriented snack enthusiasts seeking variety packs unavailable in conventional supermarkets. Sweet flavor profiles dominate conventional retail while savory and spicy variants concentrate in specialty shops targeting adventurous palates.
FDA gluten-free labeling standards enforce facility segregation and testing documentation, elevating compliance costs for regional processors while advantaging scaled players with dedicated lines. USDA organic certification intersects with gluten-free claims in the organic product segment, creating dual-audit requirements that filter out marginal suppliers. Stakeholders must monitor evolving FERC-tracked energy costs affecting popping and packaging operations, as electricity-intensive expansion constrains margin recovery in contract manufacturing arrangements.
Market Dynamics
The gluten-free popcorn market pivots on FDA enforcement of facility segregation rules, which compresses margins for regional processors while locking in scaled manufacturers with validated supply chains and dedicated production lines.
Growth Catalysts
- Celiac disease diagnostics expansion:Rising detection rates across gastroenterology practices pull first-time buyers into certified gluten-free snacking categories.
- USDA organic certification overlap:Dual-audit requirements filter marginal suppliers and elevate shelf-stable products commanding retail premium placement.
- Air-popping technology diffusion:Lower-calorie positioning in health-specialty channels offsets flavor intensity trade-offs for weight-management households.
Market Restraints
- Maize input cost volatility:Midwest drought cycles and ethanol demand competition squeeze processor margins without contract hedging.
- Facility segregation capital requirements:Dedicated gluten-free lines demand $2-4 million per plant conversion, freezing out sub-scale regional entrants.
- Cross-contact testing documentation burden:FDA mandates ELISA kit verification at 20 ppm thresholds, adding $15,000-25,000 per production run compliance costs.
Strategic Opportunities
- E-commerce subscription velocity:Direct-to-consumer variety packs bypass conventional supermarket slotting fees and capture trial-oriented snack enthusiasts.
- Savory-spicy flavor white space:Specialty shops in urban clusters stock adventurous profiles underserved by mass-market sweet dominance.
- Clean-label packaging innovation:Paper-based compostable materials align with municipal organic waste mandates in California and New York jurisdictions.
Industry Challenges
- Co-packing capacity scarcity:Midwest contract manufacturing queues stretch 12-18 weeks, throttling brand expansion timelines.
- Supply chain reconfiguration friction:Validated cleaning protocols between allergen and gluten-free runs extend changeover downtime by 40 percent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten-Free Popcorn Products Market |
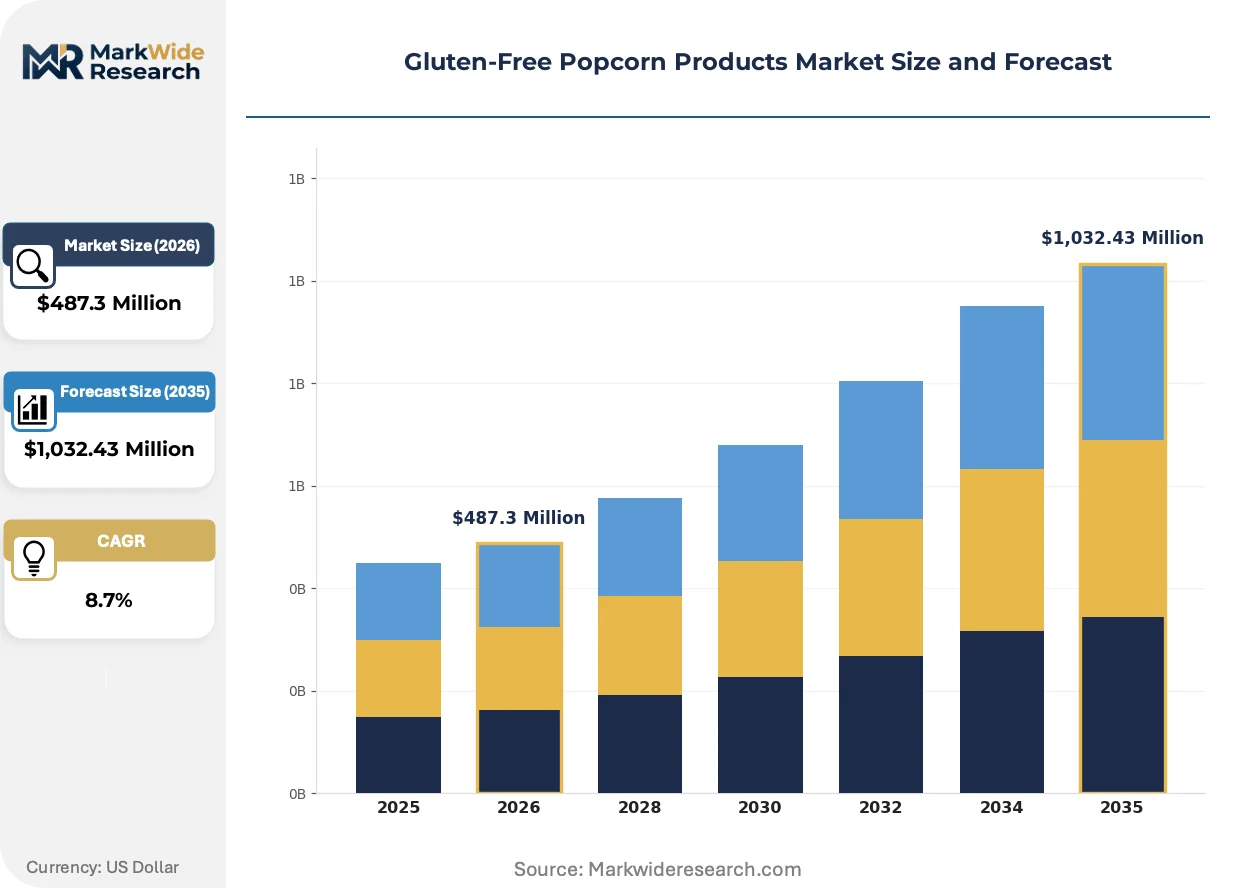
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Popped, Kettle Corn, Flavored, Organic Distribution Channel: Supermarkets, E-commerce, Health Stores, Specialty Shops End User: Health-Conscious Consumers, Kids, Athletes, Snack Enthusiasts Flavor Profile: Sweet, Savory, Spicy, Cheese |
| Companies Covered | Angie's Boomchickapop, Conagra Brands, Pop Secret, Orville Redenbacher, Skinnypop, LesserEvil Snacks, Quinn Snacks, Weaver Popcorn, American Pop Corn Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten-Free Popcorn Products Market Evolving Landscape
Active thermal processing and packaging material science are compressing production economics while regulatory stringency and channel fragmentation rewrite competitive rules for shelf access.
Infrared popping systems is displacing conventional oil-based kettle methods in mid-scale facilities. Health-conscious buyers in club retail channels accelerate adoption of these systems. The technology compresses oil input costs and enables cleaner-label claims that command shelf space.
FDA's 2023 updated gluten-free labeling guidance tightens facility segregation documentation requirements. Scaled manufacturers with captive laboratories absorb compliance costs more readily than contract-dependent brands. The rule most affects regional processors serving conventional grocery without dedicated lines.
Subscription box curation is fragmenting household purchase patterns away from single-flavor bulk buying. Variety-pack aggregators in coastal metropolitan markets displace conventional supermarket trial. California and New York households show highest concentration of this behavior.
Gluten-Free Popcorn Products Market Segmentation
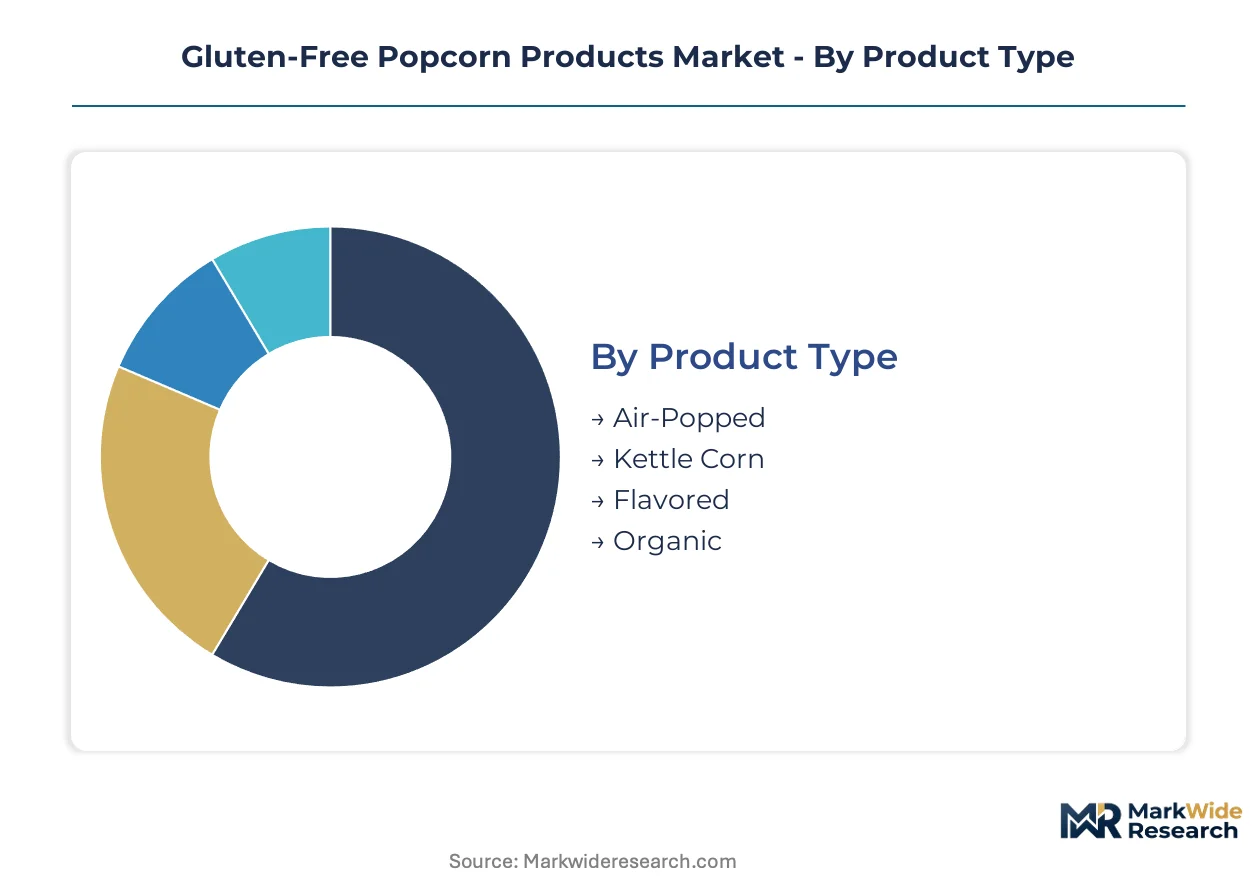
Segmentation in gluten-free popcorn reveals how processing technology, channel access, and consumer psychographics create distinct profit pools. Manufacturers configure supply chains differently for each slice, from dedicated organic lines to mass-retail air-popped formats.
Product Type:
Domestic consumption concentrates in air-popped and kettle formats, while organic variants increasingly serve export markets to Canada and European Union member states with dual gluten-free and organic certification requirements.
- Air-Popped:Kernels expand via hot air circulation without oil, yielding sub-100 calorie per cup profiles. Demand clusters in United States health-specialty retail and weight-management households where clean-label positioning offsets flavor intensity trade-offs.
- Kettle Corn:Traditional oil-popped preparation with light sugar coating delivers nostalgic taste profiles. Midwest contract manufacturers dominate supply, shipping to conventional grocery banners where sweet-salty balance commands repeat purchase.
- Flavored:Post-popping seasoning application spans white cheddar, caramel, and experimental profiles. Product development cycles accelerate through co-packer partnerships.
- Organic:USDA-certified maize supply chains with validated gluten-free segregation command dual-audit compliance. Export demand from Canadian and German retailers drives premium pricing.
Air-popped holds the largest share; momentum sits with organic.
Distribution Channel:
Channel selection determines margin structure, with direct-to-consumer formats capturing subscription velocity while brick-and-mortar placement demands slotting fee absorption.
- Supermarkets:Conventional grocery placement requires validated supply chains and dedicated gluten-free production lines to satisfy FDA labeling scrutiny. Mass retail volumes concentrate in United States Midwest and Southeast census regions.
- E-commerce:Direct-to-consumer variety packs bypass slotting fees and capture trial-oriented snack enthusiasts. Subscription velocity concentrates in California and New York metropolitan clusters.
- Health Stores:Natural products retail demands third-party gluten-free certification and non-GMO positioning. Regional chains in Pacific and Northeast corridors stock premium air-popped formats.
- Specialty Shops:Gourmet retailers and airport concessions stock adventurous flavor profiles. Urban coastal markets show highest per-square-foot velocity.
Supermarkets generate the highest absolute volume; e-commerce climbs the fastest.
End User:
User segmentation maps directly to formulation intensity, with medical necessity driving certification rigor versus lifestyle preference enabling broader ingredient flexibility.
- Health-Conscious Consumers:Calorie-aware households prioritize air-popped formats and clean-label ingredient decks. This cohort concentrates in United States suburban markets with above-median household income.
- Kids:Lunchbox-compatible single-serve packaging drives portion-controlled innovation. Parental purchase decisions favor recognizable flavor profiles and allergen-free facility claims.
- Athletes:Macronutrient-focused snacking demands protein-fortified and electrolyte-enhanced popcorn variants. Sports nutrition retail channels in Texas and Florida stock performance-positioned lines.
- Snack Enthusiasts:Variety-seeking trial behavior favors subscription boxes and limited-edition flavor drops. Social media engagement correlates with purchase frequency.
Health-conscious consumers anchor volume; athletes represent the steepest expansion trajectory.
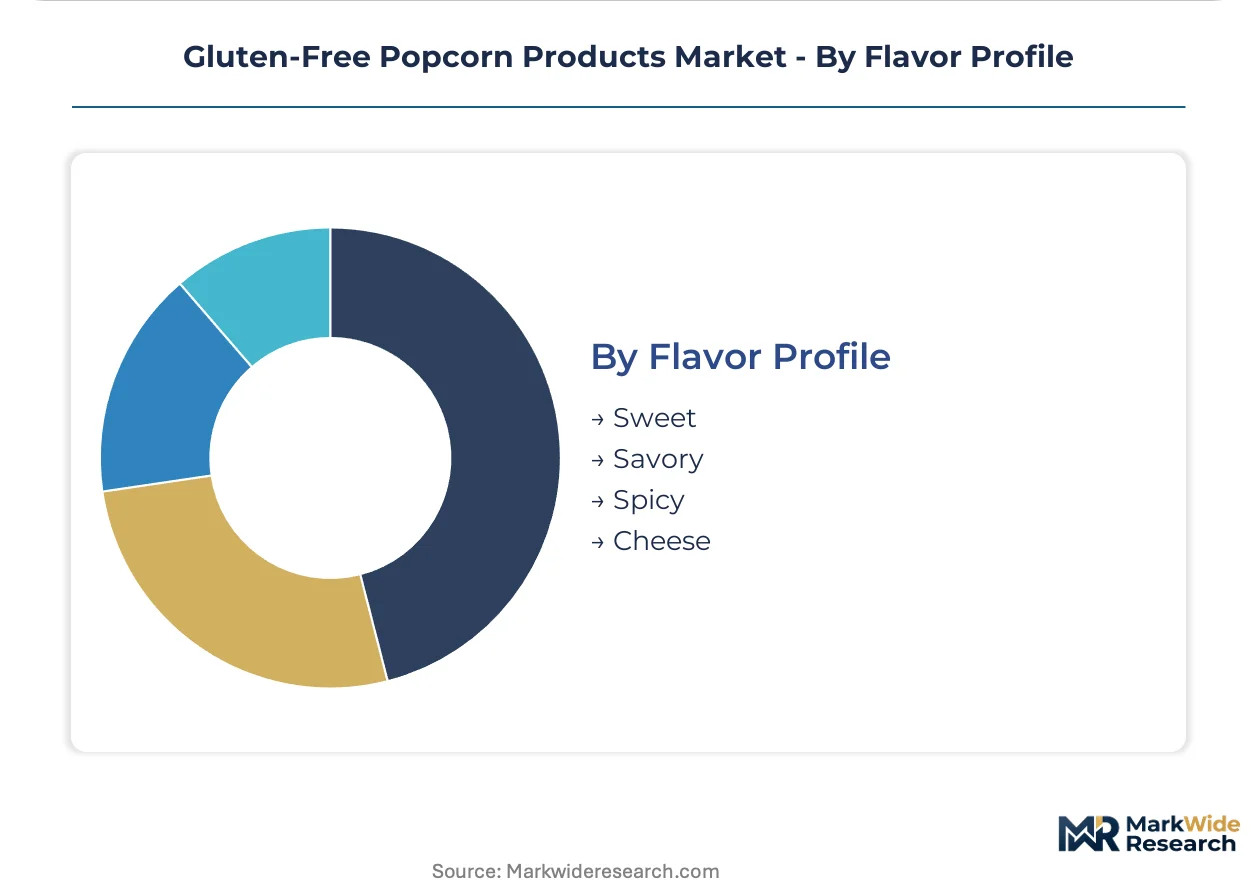
Flavor Profile:
Flavor segmentation reveals geographic taste divergence, with sweet dominance in heartland conventional retail and savory-spicy concentration in coastal specialty channels.
- Sweet:Caramel and kettle formulations dominate United States conventional grocery and club retail. Midwest and Southern households show highest per-capita consumption.
- Savory:Sea salt, rosemary, and truffle profiles command premium shelf space. Specialty shops in California and New York metropolitan areas stock these variants.
- Spicy:Chili-lime and sriracha formulations target adventurous palates. Urban clusters in Texas and Arizona show strongest velocity.
- Cheese:White cheddar and parmesan varieties balance mass appeal with premium positioning. Conventional grocery placement requires clean-label dairy sourcing.
Sweet profiles command the largest share; savory and spicy gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households consume gluten-free popcorn primarily through conventional grocery channels, while Canadian and German buyers concentrate demand in dual-certified organic formats that command export premiums.
United States
Health-specialty retail and weight-management households drive air-popped format adoption across suburban markets with above-median income. FDA gluten-free labeling standards enforce facility segregation and ELISA kit verification at 20 ppm thresholds. Chicago and Minneapolis industrial corridors host Midwest contract manufacturers with validated gluten-free lines serving mass retail banners.
Canada
Dual gluten-free and organic certification requirements pull USDA-certified maize supply chains across the border for premium retail placement. Health Canada maintains aligned gluten-free standards with FDA thresholds, reducing cross-border compliance friction. Toronto and Vancouver metropolitan clusters concentrate natural products retail demand for clean-label snacking formats.
Germany
EU organic regulations intersect with gluten-free claims to create stringent dual-audit demand from discounter and specialty channels alike. EFSA guidance on gluten thresholds aligns with Codex Alimentarius standards at 20 ppm. Hamburg and Berlin distribution hubs channel certified products into Scandinavian and Benelux export markets.
United Kingdom
Free-from aisle expansion in conventional grocery accelerates trial among non-celiac gluten-avoidant households seeking permissive snacking options. FSA enforcement of gluten-free labeling maintains post-Brexit alignment with EU standards. London and Southeast England retail clusters show highest per-capita velocity for premium savory and spicy flavor variants.
Australia
Coeliac Australia certification program drives third-party verified demand through health food chains and pharmacy retail channels. FSANZ standards mandate 20 ppm gluten thresholds with annual facility audit requirements. Sydney and Melbourne metropolitan areas concentrate subscription-oriented snack enthusiasts seeking direct-to-consumer variety pack formats.
Gluten-Free Popcorn Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in gluten-free popcorn manufacturing. National manufacturers leverage frozen-to-shelf distribution networks and captive laboratory testing to absorb FDA compliance costs. Specialist archetypes include farm-to-bag transparency advocates, small-batch kettle producers, and co-packer-dependent emerging brands. Dominant competitive moves center on co-packing infrastructure scaling and clean-label packaging material innovation.
Within the integrated leader tier, Conagra Brands exemplifies mass retail placement capability through established grocery distribution networks. LesserEvil Snacks and Quinn Snacks occupy positions within the specialist tier, representing archetypes of in-house production control and supply chain transparency positioning respectively. These three entities anchor the competitive spectrum from scale-driven conventional placement to premium-channel specialization.
| Leading Market Players |
|---|
| Angie's Boomchickapop |
| Conagra Brands |
| Pop Secret |
| Orville Redenbacher |
| Skinnypop |
| LesserEvil Snacks |
| Quinn Snacks |
| Weaver Popcorn |
| American Pop Corn Company |
| Others |
Value Network & Pricing Analysis
Twelve-to-eighteen-week co-packing queues in the Midwest industrial corridor concentrate pricing power with contract manufacturers holding validated gluten-free lines, while FDA facility segregation mandates compress margins for processors without captive capacity. This supply bottleneck feeds directly into premium pricing for air-popped and organic formats where dedicated production claims command retail shelf space.
Pricing Analysis
Long-term offtake agreements with organic maize suppliers anchor pricing stability for scaled manufacturers, while spot-market exposure punishes regional processors during drought cycles. Three-tier pricing structure across premium organic, standard certified, and economy private-label levels separates buyers by certification rigor and channel placement. Cost compression in the contract manufacturing tier is intensifying because co-packer scarcity extends lead times without corresponding rate increases. Private-label supermarket buyers exhibit highest price sensitivity; specialty health stores show lowest.
Supply Chain Analysis
Port congestion on Pacific trade lanes elevates inbound logistics costs for paper packaging materials sourced from Asian mills, compressing margins for brands prioritizing compostable claims. Maize supply concentrates in the United States Midwest and Argentina; organic certification sourcing extends to Canadian prairie provinces. Processing draws from dedicated gluten-free facilities in Illinois and Minnesota; flavoring inputs rely on dairy and seasoning suppliers in Wisconsin and California. Single-source vulnerability sits with co-packer concentration in the Chicago-Minneapolis corridor. Distribution runs through mass retail distribution centers serving conventional grocery banners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as subscription box curation fragments household purchase patterns, creating niches for specialized flavor innovators and regional organic processors outside mass retail concentration.
For Market Incumbents: Secure dedicated co-packing capacity through equity partnerships or captive facility investment before queue extensions freeze expansion timelines. Anchor shelf position by accelerating infrared popping technology deployment to capture health-specialty channel velocity. Threat from farm-to-bag transparency specialists demands supply chain documentation investment as a defensive lever. For New Entrants and Emerging Players: USDA organic certification fast-track through accredited Midwest auditors opens white-space penetration in Canadian export markets demanding dual-certified supply. Target savory-spicy flavor profiles underserved by mass-market sweet dominance in Texas and Arizona urban clusters. Launch through direct-to-consumer subscription velocity to bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across co-packing infrastructure as Midwest facility scaling spreads fixed compliance costs across brand portfolios. Five-to-ten-year viability favors acquisition targets with validated gluten-free lines and captive organic maize contracts. Watch co-packing queue length as inflection signal for pricing power transfer.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Packer Equity Partnership | Locks in validated gluten-free capacity ahead of FDA documentation tightening. |
| Infrared Popping Deployment | Enables clean-label claims that command premium shelf space in club retail. |
| Organic Maize Supply Contract | Satisfies dual-audit requirements for Canadian and German export premiums. |
| Subscription Box Distribution | Bypasses conventional supermarket slotting fees while capturing trial-oriented households. |
| Compostable Packaging Transition | Aligns with California and New York municipal organic waste mandates. |
Research Methodology
A spread of perspectives from brand managers at specialty snack companies, category buyers at conventional grocery banners, co-packing facility operators, and supply chain planners converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation against FDA gluten-free labeling guidance, USDA organic certification databases, Nielsen retail audit data, and FERC-tracked energy cost disclosures. Bottom-up volume builds across product type and channel segments triangulated against top-down market sizing.
Segmentation dimensions modeled include processing technology, distribution channel, flavor profile, and end-user psychographic across the projection horizon. CAGRs derived from growth driver elasticity analysis applied to baseline consumption patterns. Forecast inputs incorporated celiac disease diagnostic expansion rates and co-packing capacity utilization trends.
Decision-makers should treat outputs as directional under assumptions of sustained FDA enforcement stringency and stable organic certification demand; material deviation would warrant model refresh. Forecasts reflect these assumptions alongside maize input cost volatility and subscription channel penetration trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Gluten Free Malt Extracts Market
Food Intolerance Products
Europe Gluten Free Foods and Beverages Market
Food Intolerance Products
Global Gluten Free Prepared Foods Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Reduced Salt Food Products Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market
Food Intolerance Products
Lactose Free Products Market
Food Intolerance Products
Dyspepsia Market
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
Food Intolerance Products Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
United States Gluten Free Foods and Beverages Market
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market
Food Intolerance Products
Gluten-Free Soup Market