
 France Gluten-Free Food and Beverage Market | 2026-2036
France Gluten-Free Food and Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
France Gluten-Free Food and Beverage Market Foresight
France is reconfiguring its domestic gluten-free manufacturing footprint with expanded milling capacity near Brittany and the Loire Valley. Dr. Schär leverages its established European supply chain to dominate French pharmacy and specialty retail channels. Nestlé sustains brand recognition through reformulated mainstream product lines bearing clear gluten-free certification. Hain Celestial Group competes in the organic-aligned segment with clean-label positioning that resonates in French hypermarkets.
Gluten-free food and beverage encompasses products formulated without wheat, barley, rye, or cross-contaminated oats, typically substituting rice flour, corn starch, or pseudocereals like quinoa and buckwheat to achieve comparable texture and shelf stability. These formulations serve celiac patients, gluten-sensitive consumers, and health-focused buyers seeking digestive wellness or perceived nutritional benefits. Bakery commands the largest revenue pool due to bread's centrality in French dietary habits, though dairy alternatives capture accelerated growth as oat and almond-based drinks displace traditional breakfast offerings. Online retail channels expand fastest among distribution pathways, driven by subscription models and direct-to-consumer brands that bypass conventional retail markups.
ANSES maintains strict gluten threshold enforcement at 20 ppm for gluten-free claims, while EU Regulation 1169/2011 mandates allergen labeling that shapes manufacturer formulation decisions and consumer trust. The French DGCCRF conducts market surveillance to detect mislabeled products, creating compliance costs that favor established players with dedicated quality laboratories. Stakeholders must monitor evolving EU novel food approvals for emerging alternative proteins and fermented grain bases that could reshape competitive formulation standards.
Market Dynamics
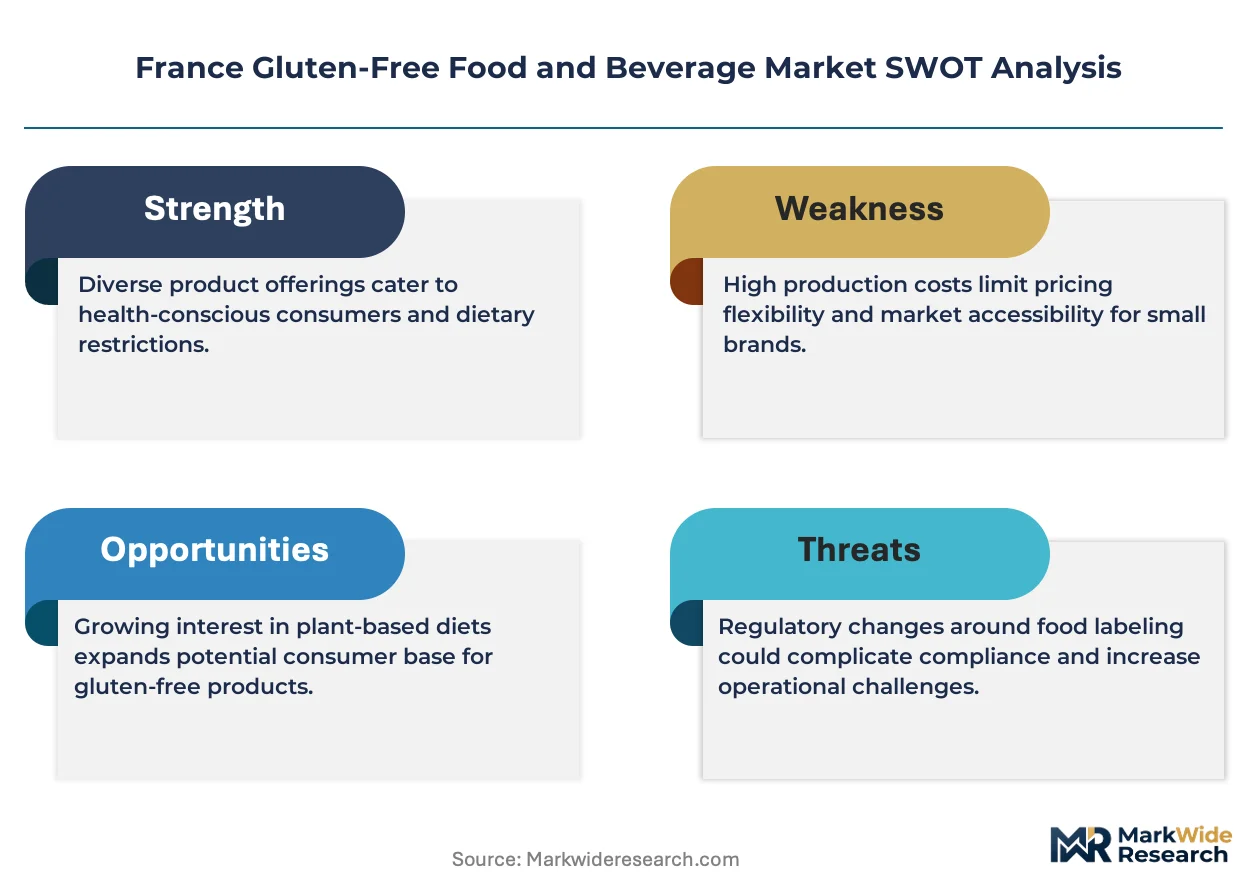
ANSES tightened gluten thresholds to 20 ppm for packaged food claims, forcing manufacturers to rebuild quality infrastructure and reformulate across bakery, pasta, and ready-meal categories. This regulatory compression is redistributing market access toward players with captive laboratory capacity.
Growth Catalysts
- Celiac Diagnosis Expansion:French gastroenterology screening protocols now capture latent cases faster, enlarging the addressable patient base requiring certified gluten-free products.
- EU Regulation 1169/2011:Mandatory allergen labeling harmonization builds consumer trust and reduces information asymmetry at retail shelf.
- Brittany Milling Cluster:Dedicated gluten-free grain processing infrastructure near Rennes and Nantes shortens supply chains for national distribution.
Market Restraints
- Input Cost Volatility:Quinoa and buckwheat prices swing with South American harvest cycles, compressing margins on premium-positioned bakery lines.
- Supply Concentration Risk:French retail pharmacy chains control 40% of specialty gluten-free distribution, creating gatekeeper power over new entrants.
- Technical Shelf-Life Limitation:Rice-flour formulations stale faster than wheat equivalents, constraining logistics radius and fresh bakery expansion.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur Underpenetration:Mediterranean coastal cities show lower specialty retail density than Paris or Lyon, offering whitespace for direct-to-consumer subscription models.
- Fermented Grain Bases:Novel sourdough fermentation techniques reduce additive dependence and unlock clean-label positioning in organic hypermarket aisles.
- Online Channel Innovation:Dedicated gluten-free subscription boxes bypass retail markups and capture recurring revenue from diagnosed households.
Industry Challenges
- Cross-Contamination Control:Shared milling equipment requires costly segregation protocols and third-party audit cycles that strain mid-tier producers.
- Formulation Talent Scarcity:Gluten-free bakery science demands hybrid food chemistry and sensory expertise that French technical institutes underproduce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Gluten-Free Food and Beverage Market |
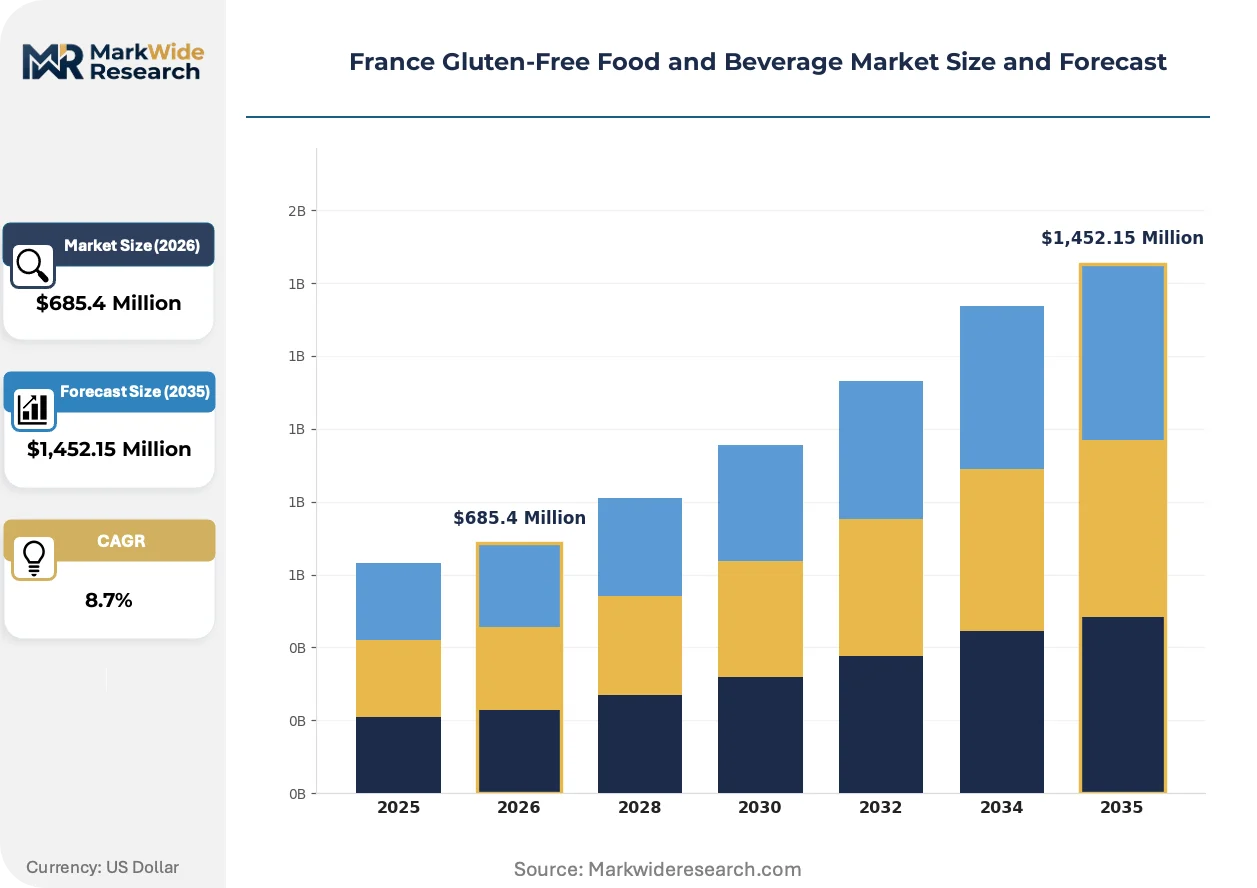
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bakery, Snacks, Dairy Alternatives, Beverages, Pasta, Meat Substitutes Application: Foodservice, Household Consumption, Cafés & Restaurants, Catering, Institutional Use Distribution Channel: Supermarkets & Hypermarkets, Specialty Stores, Online Retail, Convenience Stores, Pharmacies Customer Type: Celiac Patients, Health-Conscious Individuals, Athletes, Children, Elderly Consumers |
| Companies Covered | Raisio, Nestlé, Dr. Schär, Barilla, Amy's Kitchen, Hain Celestial Group, Unilever, Conagra Brands, PepsiCo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Gluten-Free Food and Beverage Market Shifts & Advancements
French manufacturers are racing to eliminate texture-compromise stigma through ingredient science and process engineering. Three converging developments are redefining competitive viability.
Enzymatic gluten degradation technology is collapsing the performance gap between wheat and alternative flours in industrial bakery applications. Large-scale producers in the Loire Valley are adopting transglutaminase and protease treatments to improve dough elasticity without chemical additives. This enzymatic shift is collapsing premium pricing power for legacy imported brands that relied on texture inferiority to justify markups.
ANSES maintains strict enforcement of its 20 ppm gluten threshold through randomized retail sampling and laboratory verification. The French DGCCRF complements this with unannounced facility inspections that detect trace contamination in shared production environments. Bakery and pasta manufacturers are responding by building dedicated gluten-free production lines rather than relying on sanitation protocols alone.
French households with celiac members are consolidating purchases through specialized e-commerce platforms that aggregate subscription boxes across multiple product categories. Direct-to-consumer brands are displacing conventional pharmacy and hypermarket channels for pantry-stocking behaviors. This channel migration concentrates most visibly in the Île-de-France and Auvergne-Rhône-Alpes regions where digital penetration and diagnosed prevalence overlap.
France Gluten-Free Food and Beverage Market Segmentation
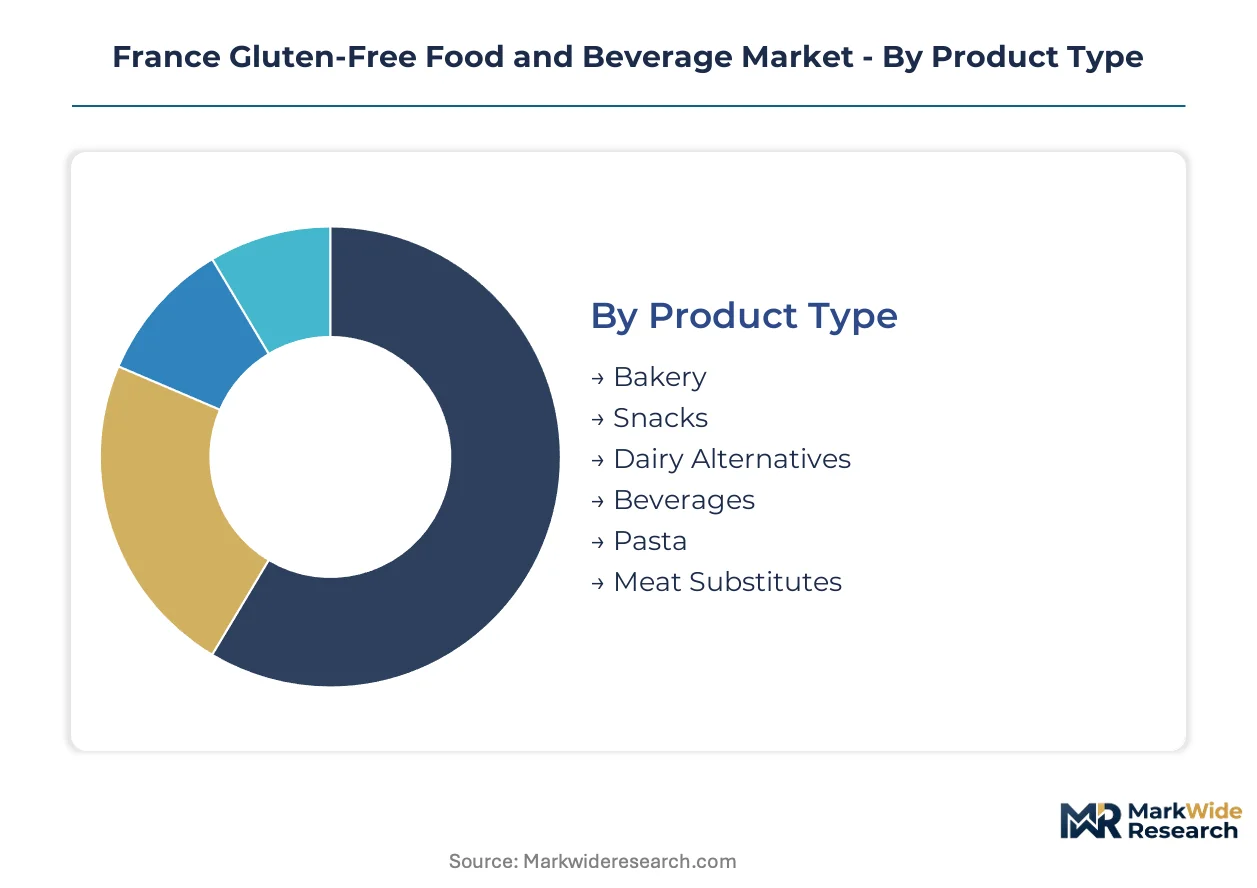
France's gluten-free market segments reflect divergent maturity levels across product categories, distribution channels, and consumer cohorts. Bakery and pasta formulations command established shelf space while fermented grain beverages and direct-to-consumer models accelerate from smaller bases. Understanding these segment trajectories enables manufacturers to calibrate R&D investment and channel strategy against regulatory thresholds and household purchasing patterns.
Product Type:
Mature segments anchor revenue while emerging categories reshape competitive entry points through novel formulation science.
- Bakery:Bread, pastries, and viennoiserie rely on rice flour, corn starch, and pseudocereal blends to replicate wheat gluten networks. Paris and Lyon households with diagnosed celiac members drive concentrated demand for certified baguettes and croissants that meet ANSES 20 ppm thresholds. Shelf-life limitations constrain logistics radius for fresh formats.
- Dairy Alternatives:Oat, almond, and rice-based drinks displace traditional breakfast offerings through enzymatic processing that achieves creamy mouthfeel without dairy proteins. Brittany milling clusters supply raw material for national brands targeting health-conscious consumers in hypermarket channels. Clean-label positioning accelerates adoption beyond the celiac core.
- Snacks:Crackers, bars, and savory formulations using buckwheat and quinoa bases serve portable consumption occasions.
- Beverages:Fermented grain drinks and functional waters address digestive wellness positioning.
- Pasta:Corn and rice extrusions replicate al dente texture for household preparation.
- Meat Substitutes:Seitan-free alternatives using legume and mushroom proteins serve flexitarian households avoiding gluten-containing wheat gluten.
Bakery retains volume leadership; dairy alternatives hold the steepest expansion curve.
Application:
Cost tier stratification separates premium foodservice specifications from mass-market household formats.
- Household Consumption:Pantry-stocking behaviors concentrate in diagnosed celiac households purchasing certified pasta, bread, and baking mixes through pharmacy and online subscription channels. ANSES labeling requirements build trust for repeat purchases. Île-de-France households show highest digital penetration for direct-to-consumer aggregation.
- Foodservice:Restaurants and cafés require segregated preparation protocols and supplier certification to prevent cross-contamination. Kitchen staff training costs and dedicated equipment investments favor chain operators over independent bistros. Parisian establishments lead adoption for tourist-facing gluten-free menu transparency.
- Cafés & Restaurants:Specialized brunch venues in Lyon and Marseille differentiate through certified gluten-free pastry offerings.
- Catering:Event and corporate dining segments demand bulk formats with traceable ingredient documentation.
- Institutional Use:Hospital and school cafeterias source compliant products through centralized procurement frameworks.
Household consumption dominates transaction volume; foodservice claims the premium pricing tier.
Distribution Channel:
Channel concentration varies sharply between pharmacy gatekeepers and emerging digital bypass routes.
- Pharmacies:French retail pharmacy chains control specialty gluten-free distribution through prescription-linked purchasing and dietitian counseling. Dr. Schär and established European brands maintain dominant shelf presence. Reimbursement pathways for diagnosed celiac patients reinforce channel stickiness.
- Online Retail:Subscription boxes and direct-to-consumer platforms aggregate multi-category purchases from diagnosed households, bypassing retail markups. Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur regions show fastest digital adoption where specialty retail density lags Paris.
- Supermarkets & Hypermarkets:Mass-market penetration for reformulated mainstream lines with clear certification.
- Specialty Stores:Dedicated gluten-free boutiques and organic retailers serve ingredient-seeking home bakers.
- Convenience Stores:Limited grab-and-go snack and beverage selection for immediate consumption.
Pharmacies retain the diagnosed patient channel; online retail expands most quickly among emerging channels.
Customer Type:
Medical necessity separates regulated purchasing from discretionary wellness-oriented trial.
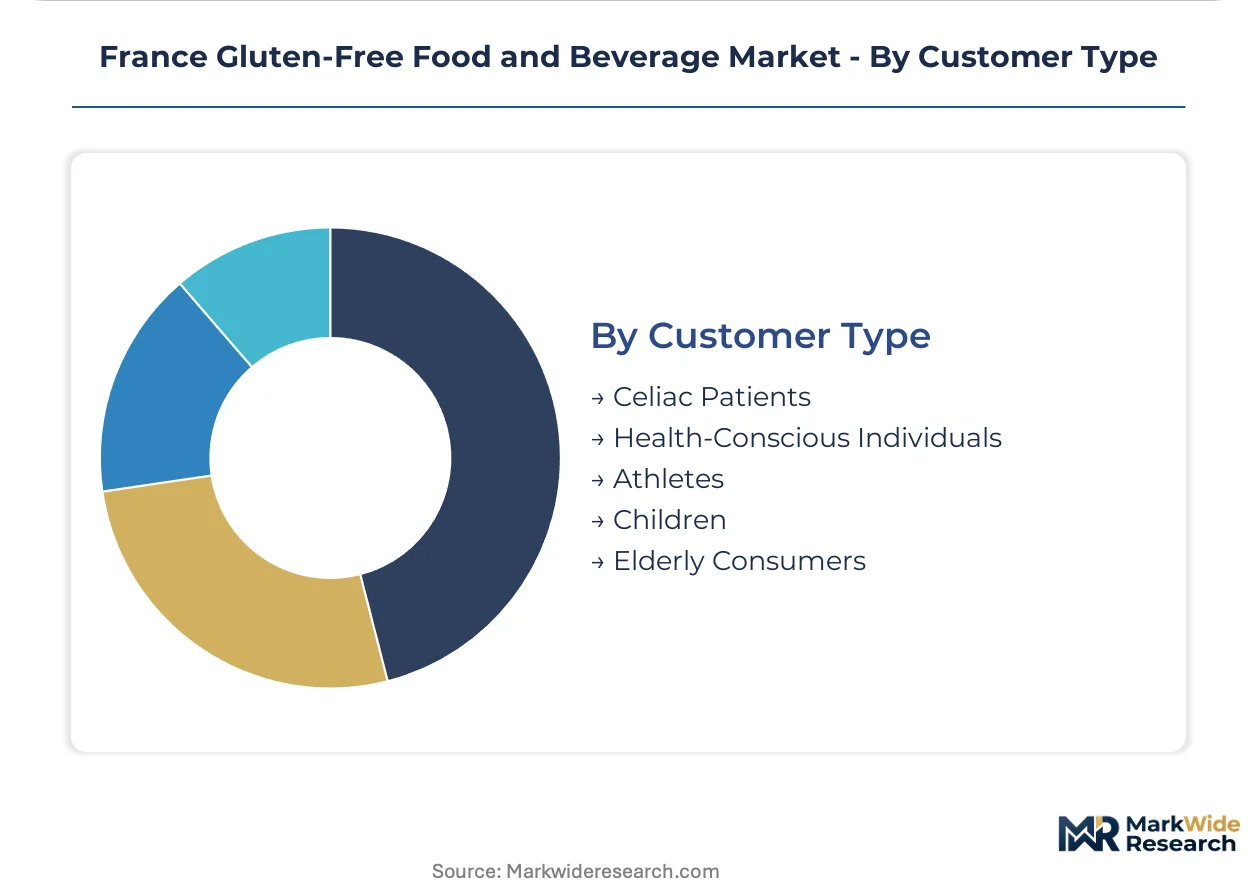
- Celiac Patients:Medically diagnosed individuals requiring strict gluten elimination constitute the regulated core with pharmacy reimbursement access and dietitian-guided purchasing. ANSES threshold enforcement and DGCCRF surveillance validate product safety for this cohort. Household consolidation behavior concentrates volume in subscription and bulk formats.
- Health-Conscious Individuals:Discretionary adopters seeking digestive wellness or perceived nutritional benefits drive category expansion beyond medical necessity. Clean-label and organic positioning in hypermarket channels captures this segment's willingness to pay premium prices for additive-free formulations.
- Athletes:Performance-oriented consumers targeting reduced inflammation through gluten elimination.
- Children:Parent-driven purchasing for diagnosed or suspected gluten sensitivity in school-age populations.
- Elderly Consumers:Digestive comfort positioning addresses age-related dietary modification preferences.
Celiac patients anchor volume concentration; health-conscious individuals generate the broadest category expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gluten-free manufacturing concentrates in northwestern France where Brittany's dedicated milling infrastructure shortens supply chains for national distribution. Regional demand patterns diverge sharply between Paris-Lyon corridor density and Mediterranean underpenetration.
Île-de-France
Paris households with diagnosed celiac members drive concentrated pharmacy and subscription channel purchasing. ANSES headquarters proximity accelerates regulatory compliance verification for manufacturers. The capital's foodservice sector leads certified gluten-free menu adoption for tourist-facing establishments.
Auvergne-Rhône-Alpes
Lyon's gastroenterology screening protocols capture latent celiac cases faster than national averages, enlarging the addressable patient base. EU Regulation 1169/2011 allergen labeling harmonization builds consumer trust in hypermarket channels. The region's digital penetration supports direct-to-consumer platform growth for diagnosed households.
Provence-Alpes-Côte d'Azur
Mediterranean coastal cities show lower specialty retail density than northern counterparts, creating whitespace for subscription models. DGCCRF unannounced facility inspections enforce cross-contamination protocols across imported product lines. Marseille and Nice concentrate emerging demand for certified gluten-free brunch venues.
Brittany
Dedicated gluten-free grain processing infrastructure near Rennes and Nantes anchors national supply chain efficiency. ANSES 20 ppm threshold enforcement validates product safety for distribution beyond regional boundaries. The Loire-Atlantique corridor hosts expanded milling capacity serving bakery and pasta manufacturers.
Hauts-de-France
Cross-border Belgian and Dutch supply chain integration shapes procurement patterns for industrial food processors. The country's national food safety surveillance detects mislabeled products entering through northern ports. Lille's retail pharmacy chains maintain gatekeeper control over specialty gluten-free distribution.
France Gluten-Free Food and Beverage Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient and milling segments. The French market exhibits tiered concentration where established European brands dominate pharmacy channels while domestic startups capture digital-native households. Three archetypes define competitive positioning: dedicated gluten-free pure-plays, reformulated mainstream portfolio holders, and organic-aligned clean-label specialists. Dominant competitive moves center on dedicated production line investments and direct-to-consumer channel bypass strategies.
Within the dedicated gluten-free tier, Dr. Schär and Barilla exemplify European supply chain leverage, while Nestlé occupies a position representing mainstream portfolio reformulation. Hain Celestial Group anchors the organic-aligned segment with clean-label positioning. These three players collectively represent divergent strategic responses to ANSES threshold enforcement and pharmacy channel gatekeeping.
| Leading Market Players |
|---|
| Raisio |
| Nestlé |
| Dr. Schär |
| Barilla |
| Amy's Kitchen |
| Hain Celestial Group |
| Unilever |
| Conagra Brands |
| PepsiCo |
| Others |
Supply & Pricing Matrix
Brittany's dedicated gluten-free milling cluster near Rennes and Nantes concentrates national supply capacity, translating infrastructure investment into downstream pricing power for bakery and pasta manufacturers serving ANSES-regulated markets.
Pricing Analysis
ANSES 20 ppm threshold enforcement dictates the pricing tier structure across French gluten-free segments. Three-tier pricing structure across premium certified pharmacy lines, standard hypermarket offerings, and economy private-label alternatives separates reimbursement-eligible products from discretionary wellness purchases. Cost compression in premium bakery tiers is intensifying because enzymatic processing technology collapses texture-performance premiums previously commanded by imported brands. Celiac patients with pharmacy reimbursement access show lowest price sensitivity; health-conscious discretionary buyers in hypermarket channels exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from French retail pharmacy chains strain working capital for mid-tier producers entering specialty distribution. Geographic supply concentration centers on France's Brittany cluster, with secondary sourcing from Italian and German dedicated gluten-free facilities. Raw material dependencies include South American quinoa, French buckwheat, and rice flour from Asian milling operations. Single-source vulnerability runs through South American pseudocereal harvest cycles that trigger input cost volatility. Distribution runs through pharmacy gatekeepers for diagnosed patients, with direct-to-consumer platforms emerging as bypass channels for subscription consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid formulation science combining enzymatic processing with clean-label positioning represents the critical capability gap separating viable competitors from margin-compressed commodity players in this market.
For Market Incumbents: Harden dedicated production line investments against cross-contamination liability by building captive laboratory capacity for ANSES compliance verification. Secure backward integration into Brittany milling infrastructure to reduce input cost exposure from South American quinoa volatility. Channel control through pharmacy chain partnership maintenance protects against direct-to-consumer subscription displacement. For New Entrants and Emerging Players: Pursue underpenetrated Mediterranean coastal markets in Provence-Alpes-Côte d'Azur where specialty retail density lags Paris-Lyon corridors. Target fermented grain beverage segments where novel sourdough techniques unlock clean-label differentiation without legacy texture stigma. Launch direct-to-consumer subscription aggregation as the primary go-to-market angle to bypass pharmacy gatekeeper control. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic processing specialists with laboratory-validated ANSES compliance infrastructure over commodity formulators. Long-term viability across the projection horizon rests on captive supply chain control and regulatory verification capability. Acquisition targets should demonstrate dedicated gluten-free production segregation rather than shared-equipment sanitation protocols. Watch DGCCRF enforcement intensity as the signal indicating regulatory barrier height for new capacity entry.| Strategic Initiative | Industry Significance |
|---|---|
| Dedicated Production Line Investment | ANSES 20 ppm compliance validates product safety for pharmacy reimbursement channels. |
| Backward Integration into Milling | Brittany cluster proximity reduces logistics radius and input cost volatility exposure. |
| Direct-to-Consumer Platform Launch | Subscription aggregation bypasses retail pharmacy markups for diagnosed household consolidation. |
| Enzymatic Processing Adoption | Transglutaminase treatments collapse premium pricing power of texture-inferior legacy imports. |
| Clean-Label Certification Pathway | Organic-aligned positioning captures health-conscious discretionary buyers in hypermarket channels. |
Research Methodology
A standing panel of food formulation scientists, pharmacy chain category managers, ANSES regulatory affairs specialists, and Brittany milling operations directors provided ongoing calibration for supply chain and pricing assumptions. Primary interviews with these stakeholders combined with secondary validation from EU Regulation 1169/2011 implementation documentation, DGCCRF surveillance reports, and customs data on pseudocereal import flows. Bottom-up segment sizing triangulated against top-down market aggregation across product type, distribution channel, and regional demand clusters.
Scenario-bracketing framed low, base, and high cases for celiac diagnosis expansion rates and pharmacy reimbursement policy continuity across the projection horizon. Segmentation dimensions modeled include product category maturity, channel concentration structure, and regional digital penetration patterns. CAGRs derived from fitted growth curves applied to diagnosed household formation and per-capita consumption intensity trajectories. Forecast inputs incorporated ANSES threshold enforcement trends and enzymatic processing technology diffusion rates.
Macroeconomic conditions sit as an overlay; deviation in eurozone consumer spending indices or South American agricultural commodity prices would shift the trajectory. Forecasts reflect documented assumptions on diagnosis protocol expansion and pharmacy channel stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
Global Lactose Intolerance Treatment Market
Food Intolerance Products
Gluten Free Malt Extracts Market
Food Intolerance Products
Dyspepsia Market
Food Intolerance Products
Australia Gluten-Free Foods and Beverages Market
Food Intolerance Products
Allergen Free Food Products Market
Food Intolerance Products
Sugar Free Food and Beverage Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market
Food Intolerance Products
Lactose Free Products Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Citrus-Derived Gastrointestinal Comfort Blends Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
Reduced Salt Food Products Market
Food Intolerance Products
Argentina Gluten-Free Food and Beverage Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Global Gluten Free Prepared Foods Market