
 Lactose Free Products Market | 2026-2036
Lactose Free Products Market Size, Share, and Industry Trends Forecast 2026-2036
Lactose Free Products Market Analysis
The gap between clinical-diagnosis-driven buyers and wellness-curious flexitarians is collapsing as the latter group accelerates lactose-free dairy purchases faster than traditional medical-need segments. Danone SA leverages its Activia and Alpro portfolios to dominate European refrigerated lactose-free yogurt shelves. Nestle SA anchors its position through extensive R&D in enzymatic lactose hydrolysis for infant nutrition and adult milk powders. Arla Foods AMBA competes with farmer-owned supply chain control across Nordic and British retail channels.
Lactose free products are dairy items treated with lactase enzyme to hydrolyze lactose into glucose and galactose, achieving less than 0.01 grams lactose per 100 milliliters in finished milk while preserving protein structure and calcium bioavailability. The enzymatic hydrolysis process operates at refrigerated temperatures between 4 and 8 degrees Celsius over 24-hour holding periods to prevent off-flavor development. Lactose free milk occupies the largest volume share among product types due to its substitution parity with conventional fluid milk in cooking and direct consumption. Lactose free yogurt captures expanding margin pools as probiotic positioning commands premium shelf placement in specialty stores. The powder form sustains institutional demand from food manufacturers reformulating baked goods and confectionery for lactose-intolerant populations.
FDA labeling requirements for lactose content claims and USDA organic certification standards shape product formulation and marketing compliance for manufacturers serving North American buyers. EFSA health claim evaluations and EU MDR framework influence how European producers position digestive comfort benefits on lactose-free packaging. Stakeholders must monitor evolving enzyme supplier consolidation and regional dairy quota politics that threaten input cost stability for hydrolyzed milk production.
Market Dynamics
Enzymatic lactose hydrolysis technology maturation is collapsing the cost premium between conventional and lactose-free dairy, eroding the historical medical-niche positioning and forcing volume-scale repositioning across retail channels.
Growth Catalysts
- Millennial and Gen Z flexitarian demand:Health-conscious younger cohorts in the United States purchase premium lactose-free yogurt and ice cream without clinical diagnosis, expanding addressable population beyond traditional intolerance sufferers.
- EFSA digestive comfort claim pathways:European producers leverage evolving health claim evaluations to position enzymatically treated dairy for wellness positioning, unlocking shelf space in specialty retail.
- Institutional food manufacturing reformulation:Powdered lactose-free milk solids enable baked goods and confectionery producers to serve intolerance-sensitive populations without recipe architecture changes.
Market Restraints
- Lactase enzyme supplier consolidation:Input cost volatility threatens hydrolyzed milk production economics as enzyme manufacturing concentrates among specialized biotechnology suppliers.
- EU dairy quota politics:Regional production limits constrain raw milk availability for hydrolysis processing in Nordic and British supply chains controlled by farmer-owned cooperatives.
- Plant-based dairy substitution:Oat and almond milk alternatives capture price-sensitive consumers seeking dairy avoidance without enzymatic processing premiums.
Strategic Opportunities
- Probiotic-positioned lactose-free yogurt:Premium shelf placement in specialty stores commands margin expansion as functional digestive health positioning differentiates from commodity fluid milk.
- USDA organic certification layering:Dual-certified organic lactose-free products access price-insensitive segments in United States natural grocery channels.
- Infant nutrition enzymatic hydrolysis:Specialized lactose-free infant formula applications address diagnosed intolerance in early childhood with prescription-access distribution models.
Industry Challenges
- 24-hour refrigerated holding protocol compliance:Off-flavor prevention requires precise temperature maintenance between 4 and 8 degrees Celsius across extended production cycles, straining cold chain infrastructure.
- FDA lactose content claim substantiation:Less than 0.01 grams per 100 milliliters threshold demands analytical validation protocols that extend product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactose Free Products Market |
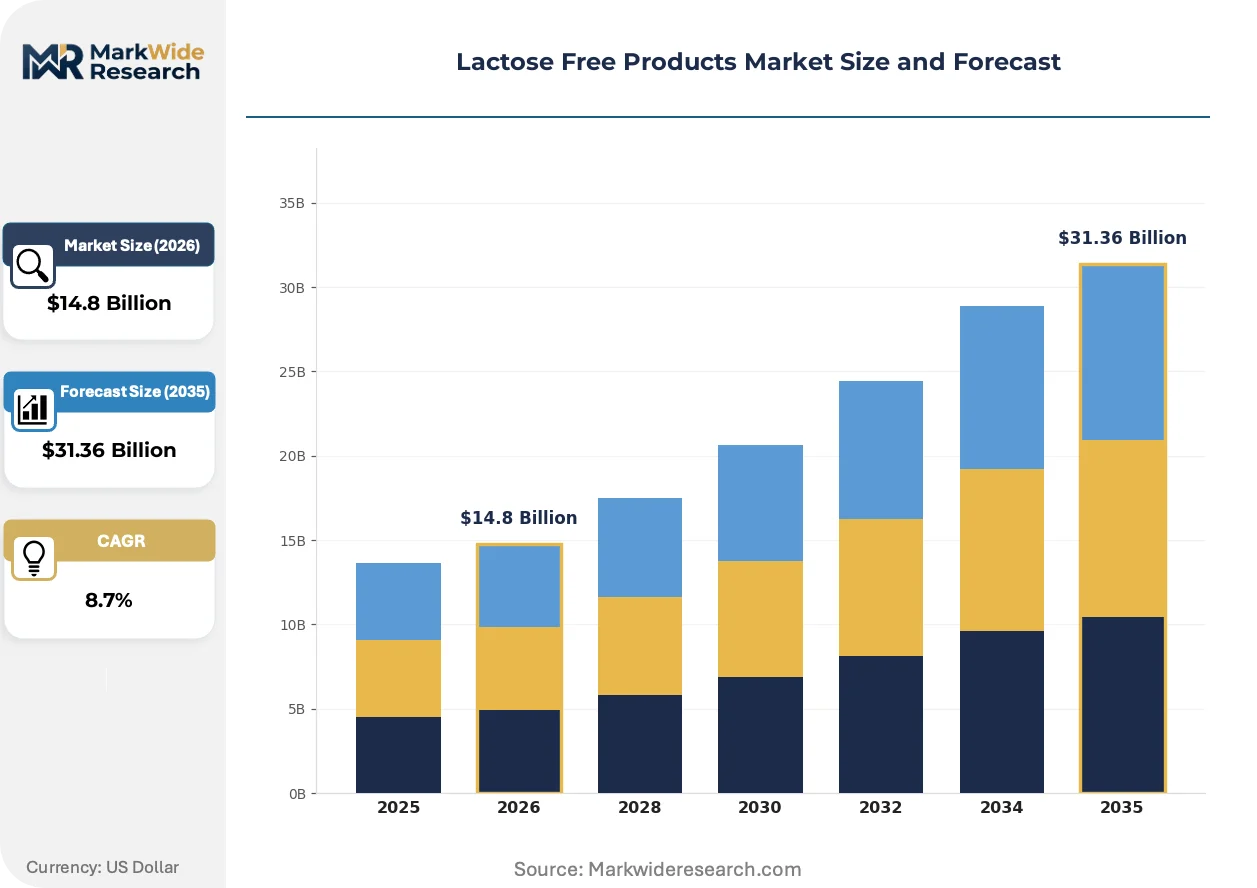
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactose Free Milk, Lactose Free Cheese, Lactose Free Yogurt, Lactose Free Ice Cream End User: Retail Consumers, Food Service, Healthcare Institutions, Food Manufacturers Distribution Channel: Supermarkets, Online Stores, Specialty Stores, Convenience Stores Form: Liquid, Powder, Frozen, Shelf-Stable |
| Companies Covered | Danone SA, Arla Foods AMBA, Nestle SA, Fonterra Cooperative Group, FrieslandCampina, Dairy Farmers of America Inc., Lactalis SA, Lifeway Foods Inc., Saputo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactose Free Products Market Emerging Trajectories
Continuous-flow enzymatic reactor systems are replacing batch hydrolysis tanks, compressing processing time from 24 hours to under 6 hours while preserving protein structure integrity.
Continuous-flow enzymatic reactor systems operate at controlled temperatures with immobilized lactase enzymes that maintain catalytic activity across multiple production cycles. Major dairy processors in the United States and Denmark adopt these systems to triple throughput without expanding physical plant footprint. This capital efficiency is supplanting traditional batch tank investments and enabling mid-scale regional dairies to enter the lactose-free segment.
EU MDR framework revisions tighten substantiation requirements for digestive comfort claims on lactose-free packaging, forcing reformulation documentation and clinical evidence standards. Manufacturers serving European markets must now maintain batch traceability records linking enzymatic treatment parameters to finished product lactose assay results. Adult milk powder and yogurt segments face the steepest compliance cost escalation as claim-dependent positioning dominates their marketing architecture.
Direct-to-consumer subscription models for lactose-free milk delivery bypass traditional grocery slotting fee structures, capturing household-level purchase data that informs flavor innovation pipelines. Urban millennials in United States coastal metropolitan areas drive this channel shift, prioritizing convenience over in-store selection breadth. This behavioral pivot pressures conventional retail buyers to negotiate exclusive SKUs or risk volume diversion to proprietary e-commerce platforms operated by dairy brands.
Lactose Free Products Market Segmentation
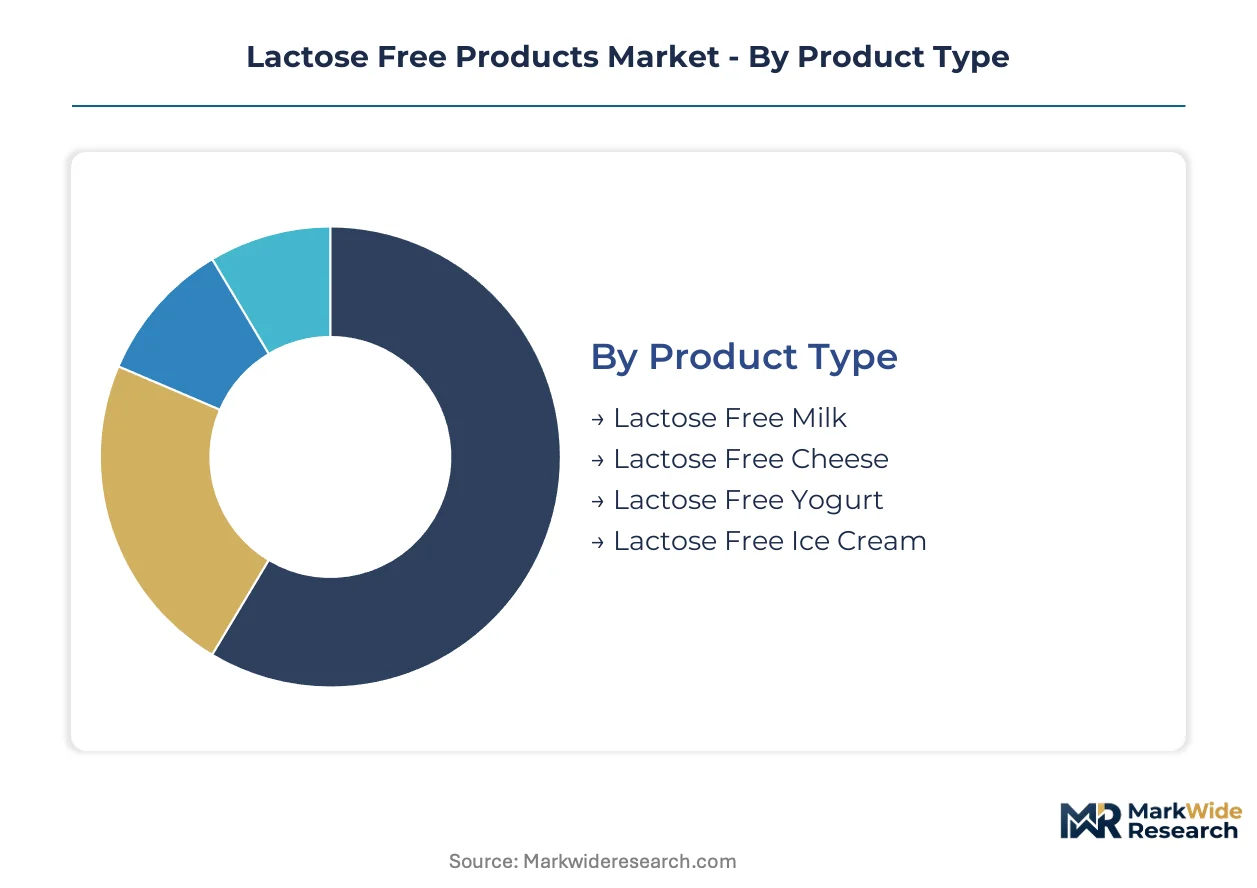
Segmentation in the lactose-free dairy market reflects divergent regulatory pathways, processing technologies, and channel economics. Each dimension carries distinct compliance burdens and margin structures that shape competitive positioning across enzymatic hydrolysis supply chains.
Product Type:
FDA's less than 0.01 grams per 100 milliliters lactose threshold applies uniformly across all categories, yet EFSA digestive comfort claim substantiation requirements vary by finished product format, forcing differentiated documentation strategies.
- Lactose Free Milk:Fluid milk undergoes refrigerated enzymatic hydrolysis at 4-8 degrees Celsius over 24-hour holding periods to preserve protein structure and calcium bioavailability. United States retail consumers purchase this as direct substitution for conventional milk in cooking and beverage applications, with continuous-flow reactor systems now compressing processing time to under 6 hours.
- Lactose Free Yogurt:Probiotic-positioned variants command premium shelf placement in specialty stores as functional digestive health claims differentiate from commodity fluid offerings. United States millennials and Generation Z flexitarians without clinical diagnosis accelerate purchases of premium skus, expanding margin pools beyond traditional medical-need segments.
- Lactose Free Cheese:Enzymatic treatment protocols for curd-based products require modified holding temperatures to prevent texture degradation during hydrolysis.
- Lactose Free Ice Cream:Frozen dessert applications leverage lactose-free positioning for premium pricing in United States coastal metropolitan markets.
Lactose free milk handles the majority of throughput; lactose free yogurt is expanding most quickly on share.
End User:
Cost tier differentiation separates institutional buyers seeking powder inputs for reformulation from premium-positioned retail channels.
- Retail Consumers:Health-conscious younger cohorts in the United States purchase lactose-free yogurt and ice cream without clinical diagnosis, collapsing the gap between medical-need and wellness-curious segments. Direct-to-consumer subscription models bypass traditional grocery slotting fees in coastal metropolitan areas.
- Food Service:Restaurant and hospitality operators require liquid and frozen formats with extended shelf stability for menu integration.
- Healthcare Institutions:Hospitals and long-term care facilities prioritize USDA organic certification for patient nutrition protocols.
- Food Manufacturers:Powdered lactose-free milk solids enable baked goods and confectionery producers to serve intolerance-sensitive populations without recipe architecture changes, sustaining institutional demand from reformulation-dependent categories.
Retail consumers dominate volume absorption; food manufacturers are gaining share fastest on reformulation demand.
Distribution Channel:
Channel selection determines compliance exposure to FDA labeling requirements versus state-level organic certification enforcement.
- Supermarkets:Conventional grocery slotting fees strain emerging brands as established dairy processors leverage existing refrigerated infrastructure. United States national chains demand exclusive SKUs to combat volume diversion to direct-to-consumer platforms.
- Online Stores:E-commerce platforms capture household-level purchase data that informs flavor innovation pipelines, with urban millennials prioritizing convenience over in-store selection breadth.
- Specialty Stores:Natural grocery channels access price-insensitive segments through dual-certified organic lactose-free positioning.
- Convenience Stores:Limited refrigerated space constrains lactose-free sku proliferation in this channel.
Supermarkets maintain the largest throughput position; online stores are climbing the fastest on subscription model adoption.
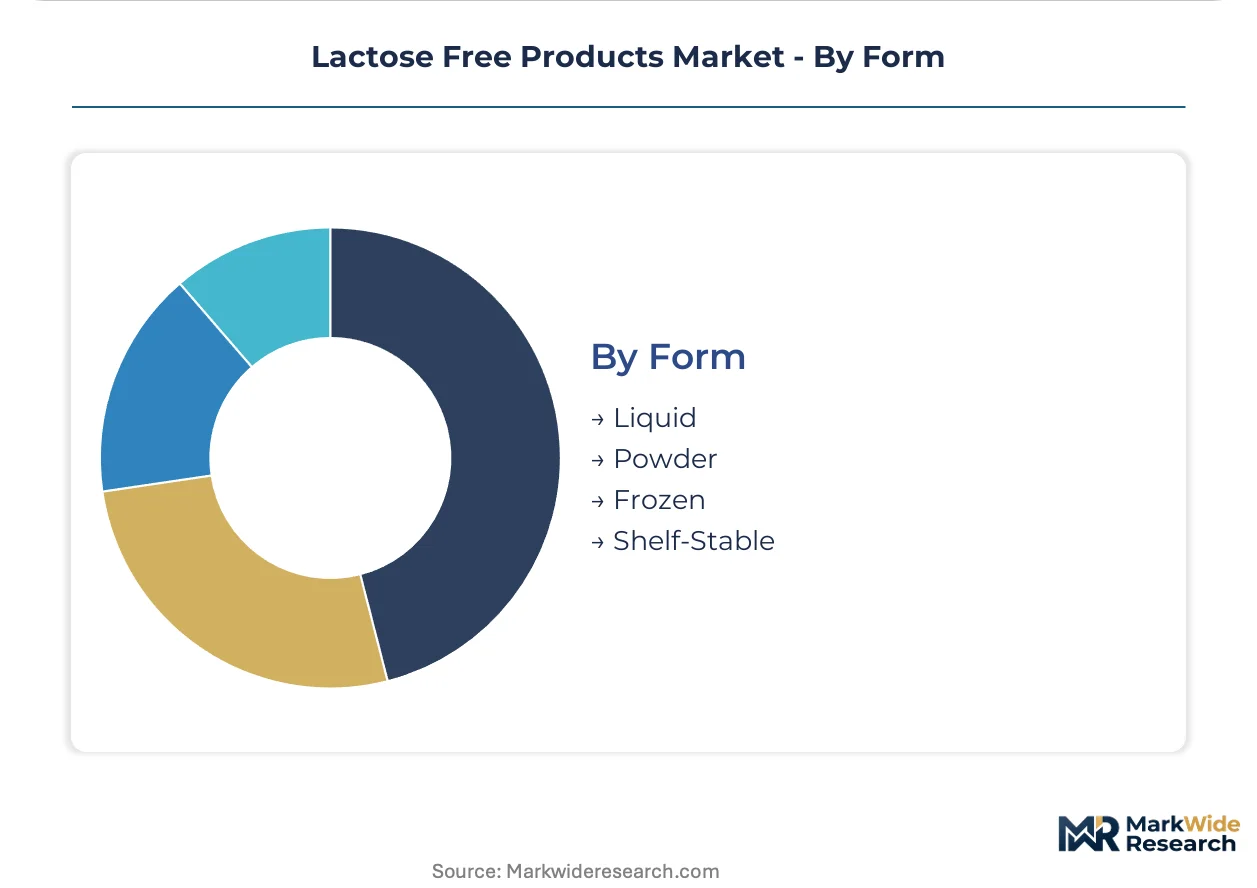
Form:
Processing maturity separates established liquid hydrolysis from emerging shelf-stable technologies requiring modified enzymatic protocols.
- Liquid:Standard refrigerated fluid milk dominates household consumption patterns and cooking substitution applications, with continuous-flow reactor adoption tripling throughput without physical plant expansion.
- Powder:Dehydrated lactose-free milk solids serve food manufacturing reformulation needs in baked goods and confectionery segments.
- Frozen:Ice cream and dessert applications target premium positioning in United States specialty retail.
- Shelf-Stable:Ultra-high temperature processing combined with enzymatic hydrolysis extends distribution reach for cold chain-constrained markets.
Liquid form commands the majority of volume; shelf-stable formats are expanding most quickly on distribution economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Generation Z flexitarians cluster in United States coastal metropolitan areas, collapsing the traditional boundary between clinical-diagnosis-driven buyers and wellness-curious consumers across developed markets.
United States
Health-conscious younger cohorts accelerate purchases of premium lactose-free yogurt and ice cream without clinical diagnosis. FDA labeling requirements for lactose content claims shape product formulation compliance for manufacturers. Direct-to-consumer subscription models in New York and Los Angeles metropolitan areas bypass traditional grocery slotting fees while capturing household-level purchase data.
Germany
EFSA digestive comfort claim evaluations enable wellness positioning for enzymatically treated dairy products. EU MDR framework revisions tighten substantiation requirements for packaging claims, forcing batch traceability documentation. Bavarian dairy processors adopt continuous-flow enzymatic reactor systems to compress processing cycles while maintaining protein structure integrity.
United Kingdom
Retail consumers expand purchases beyond dairy alternatives into functional lactose-free dairy across London and Southeast England. Farmer-owned cooperatives control supply chains through Arla Foods AMBA's vertically integrated operations. British refrigerated lactose-free yogurt shelves feature probiotic-positioned variants commanding premium placement in specialty stores.
France
Danone SA leverages Activia and Alpro portfolios to dominate European refrigerated lactose-free yogurt distribution. EFSA health claim pathways unlock shelf space in Parisian specialty retail channels. Île-de-France food manufacturers reformulate baked goods and confectionery using powdered lactose-free milk solids to serve intolerance-sensitive populations.
Denmark
Arla Foods AMBA competes through farmer-owned supply chain control across Nordic retail channels. EU dairy quota politics constrain raw milk availability for hydrolysis processing in cooperative-controlled supply chains. Copenhagen-based processors pioneer continuous-flow reactor adoption to triple throughput without physical plant expansion.
Lactose Free Products Market Vendor Landscape
Player mix skews toward multinational dairy conglomerates with enzymatic hydrolysis capabilities and farmer-owned cooperatives controlling raw milk supply. The competitive structure concentrates around scale-driven processors capable of absorbing FDA compliance costs and specialized enzyme technology investments. Two dominant archetypes emerge: vertically integrated dairy giants with global R&D operations and regional cooperatives leveraging captive milk supply. Competitive moves center on continuous-flow reactor technology licensing and exclusive retail SKU negotiations to combat direct-to-consumer volume diversion.
Among European dairy conglomerates, Danone SA and Nestle SA occupy positions representing the scale-driven multinational archetype, while Arla Foods AMBA exemplifies the farmer-owned cooperative model with supply chain control across Nordic and British channels. These three anchors demonstrate how enzymatic hydrolysis technology maturation forces divergent strategic responses: global players prioritize R&D in infant nutrition and adult milk powders, while cooperatives defend margin position through raw milk access advantages and regional retail relationships.
| Leading Market Players |
|---|
| Danone SA |
| Arla Foods AMBA |
| Nestle SA |
| Fonterra Cooperative Group |
| FrieslandCampina |
| Dairy Farmers of America Inc. |
| Lactalis SA |
| Lifeway Foods Inc. |
| Saputo Inc. |
| Others |
Supply Flow & Price Mechanics
USDA organic certification gates both supply qualification and price differentiation simultaneously, requiring dual-certified producers to maintain segregated cold chain infrastructure that commands shelf space premiums in natural grocery channels while excluding conventional hydrolysis operations from the highest-margin tier.
Pricing Analysis
Cost-plus contracts with lactase enzyme suppliers index to biotechnology input benchmarks, embedding volatility into hydrolyzed milk production economics. Three-tier pricing structure across premium probiotic yogurt, standard fluid milk, and economy powder formats separates functional positioning from commodity substitution. Pricing pressure stems from plant-based dairy alternatives capturing price-flexible consumers in United States coastal markets. Food manufacturers exhibit highest price sensitivity due to reformulation volume scale, while direct-to-consumer subscribers show lowest sensitivity on convenience premiums.
Supply Chain Analysis
Inventory lead times for specialized lactase enzymes extend production planning cycles beyond conventional dairy scheduling. Denmark, Germany, and the United States concentrate enzymatic hydrolysis capacity through continuous-flow reactor adoption. Raw material dependencies center on refrigerated fluid milk, immobilized lactase enzyme cartridges, and organic certification-compliant feedstock. Single-source vulnerability in consolidated enzyme manufacturing threatens input cost stability. Distribution runs through farmer-owned cooperative networks in Nordic and British retail channels alongside multinational dairy processor direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where subscription-based direct delivery and probiotic formulation services expand faster than commodity fluid milk hardware, embedding recurring revenue layers that decouple growth from per-unit volume constraints.
For Market Incumbents: Compound defensive positioning through backward integration into captive lactase enzyme supply and exclusive SKU negotiations with United States national supermarket chains to combat volume diversion to proprietary e-commerce platforms. Plant-based dairy substitution represents the primary substitution threat requiring R&D investment in taste-profile parity. Certification investment in dual organic-lactose-free positioning serves as the priority margin defense lever. For New Entrants and Emerging Players: Differentiate on shelf-stable ultra-high temperature processing formats targeting cold chain-constrained emerging markets where conventional refrigerated hydrolysis infrastructure remains underdeveloped. The most penetrable white space sits in institutional food manufacturing reformulation demand for powdered lactose-free milk solids. A direct-to-consumer subscription go-to-market angle bypasses grocery slotting fee barriers while capturing household-level purchase data for flavor innovation pipelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous-flow enzymatic reactor adoption, compressing physical plant requirements and enabling mid-scale regional dairy participation. Long-term viability across the next decade favors processors with technology licensing capabilities and captive organic milk supply. The acquisition target archetype centers on regional cooperatives with farmer-owned supply chain control and established retail relationships. The signal to watch as inflection indicator is FDA lactose content claim substantiation timeline extensions that favor incumbents with established analytical validation protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Reactor Licensing | Triples throughput without physical plant expansion for Danish and United States processors. |
| Direct-to-Consumer Subscription Launch | Bypasses grocery slotting fees while capturing urban millennial purchase data in coastal metros. |
| Dual Organic Certification Investment | Accesses price-insensitive segments in United States natural grocery channels. |
| Probiotic-Positioned Yogurt Extension | Commands premium shelf placement through functional digestive health differentiation. |
| Enzyme Supplier Backward Integration | Defends margin position against biotechnology supplier consolidation volatility. |
Methodological Framework
Operator-level perspectives from dairy processing plant managers, enzymatic technology R&D directors, retail category buyers, and food manufacturing procurement leads anchored the qualitative base. Secondary validation drew from FDA labeling guidance documents, EFSA health claim evaluation records, USDA organic certification databases, and dairy cooperative annual disclosures. Bottom-up volume modeling and top-down value triangulation reconciled across enzymatic hydrolysis throughput estimates and retail scanner data.
Sensitivity analysis framed volume and value outputs across product type, end user segment, distribution channel, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from segment-level growth trajectory weighting against enzyme technology adoption curves and flexitarian demographic expansion patterns. Forecast inputs incorporated continuous-flow reactor penetration rates and EU MDR framework compliance cost escalations.
The analysis sits within stated boundaries; outcomes outside sustained enzymatic technology cost compression and stable dairy quota politics would require recalibration. Forecasts reflect documented assumptions regarding flexitarian demand persistence and enzyme supplier market structure. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Europe Gluten-Free Oats Market
Food Intolerance Products
Food Allergy and Intolerance Products Market
Food Intolerance Products
Australia Gluten-Free Foods and Beverages Market
Food Intolerance Products
Italy Gluten-Free Foods and Beverages Market
Food Intolerance Products
Asia-Pacific Gluten-Free Breakfast Cereals Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Allergen Free Food Products Market
Food Intolerance Products
Australia Gluten Free Food Market
Food Intolerance Products
Nut-Free Cookies Market
Food Intolerance Products
Global Gluten Free Prepared Foods Market
Food Intolerance Products
Reduced Salt Food Products Market
Food Intolerance Products
Celiac Disease Market
Food Intolerance Products
Food Intolerance Products Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market