
 Dyspepsia Market | 2026-2036
Dyspepsia Market Size, Share, and Industry Trends Forecast 2026-2036
Dyspepsia Market Analysis
Hospital gastroenterology departments is restructuring how dyspepsia therapies reach patients, shifting volume toward ambulatory surgical centers and specialized clinics. Pfizer Inc. leverages its manufacturing scale to supply proton pump inhibitors across North American hospital networks. Takeda Pharmaceutical Company Ltd. anchors its position through R&D intensity in acid suppression technology. AstraZeneca plc differentiates via brand strength in the prescription gastrointestinal segment.
Dyspepsia encompasses upper gastrointestinal disorders characterized by epigastric pain, bloating, and postprandial fullness, typically managed through acid suppression therapies that modulate gastric pH below four for symptom relief. The condition serves both diagnostic and therapeutic purposes across primary care, gastroenterology, and emergency medicine settings. Proton pump inhibitors dominate value pools due to superior healing rates in erosive esophagitis and gastritis, while antacids occupy the over-the-counter channel with high volume but compressed margins. Functional dyspepsia applications are expanding fastest as Rome IV diagnostic criteria improve identification of patients without structural lesions.
FDA oversight governs new drug approvals and label expansions for dyspepsia indications, while EMA standards in Europe demand additional pharmacovigilance for long-term acid suppression risks. The EPA regulates pharmaceutical manufacturing emissions, raising compliance costs for active ingredient production. Stakeholders must monitor how regulatory divergence between FDA and EMA on potassium-competitive acid blocker pathways shapes competitive entry timelines and portfolio prioritization.
Market Dynamics
FDA accelerated approval pathways are compressing development timelines for novel acid suppression therapies, forcing established proton pump inhibitor manufacturers to defend their positions against potassium-competitive acid blockers while hospital formularies renegotiate procurement contracts.
Growth Catalysts
- Rome IV diagnostic criteria:Improved identification of functional dyspepsia patients without structural lesions expands the addressable patient pool across gastroenterology practices.
- United States aging demographics:Elevated diagnostic rates and sustained prescription volumes in outpatient and inpatient settings concentrate demand in this market.
- EMA pharmacovigilance frameworks:Enhanced safety monitoring for long-term acid suppression builds prescriber confidence in extended therapy protocols.
Market Restraints
- Active ingredient production costs:EPA pharmaceutical manufacturing emission regulations raise compliance expenditures for proton pump inhibitor synthesis.
- Supply concentration risk:API manufacturing clusters in specific coastal regions create vulnerability to environmental regulatory enforcement actions.
- Generic substitution pressure:Patent-expired omeprazole and esomeprazole formulations compress branded pricing power in retail pharmacy channels.
Strategic Opportunities
- Ambulatory surgical center expansion:Hospital-based gastropepsia protocols are shifting procedural volume to specialized outpatient facilities with lower overhead structures.
- Potassium-competitive acid blocker convergence:Novel mechanisms combining rapid onset with sustained pH control offer differentiation from conventional PPI therapy.
- CDSCO pathway alignment:India's pharmaceutical regulator is streamlining bioequivalence requirements for acid suppression generics, opening formulation export opportunities.
Industry Challenges
- Formulation scientist scarcity:Specialized expertise in enteric coating technologies for acid-labile compounds commands premium compensation and extended hiring timelines.
- Legacy EHR integration:Hospital system electronic health record platforms require custom dyspepsia diagnostic coding modules that delay protocol standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dyspepsia Market |
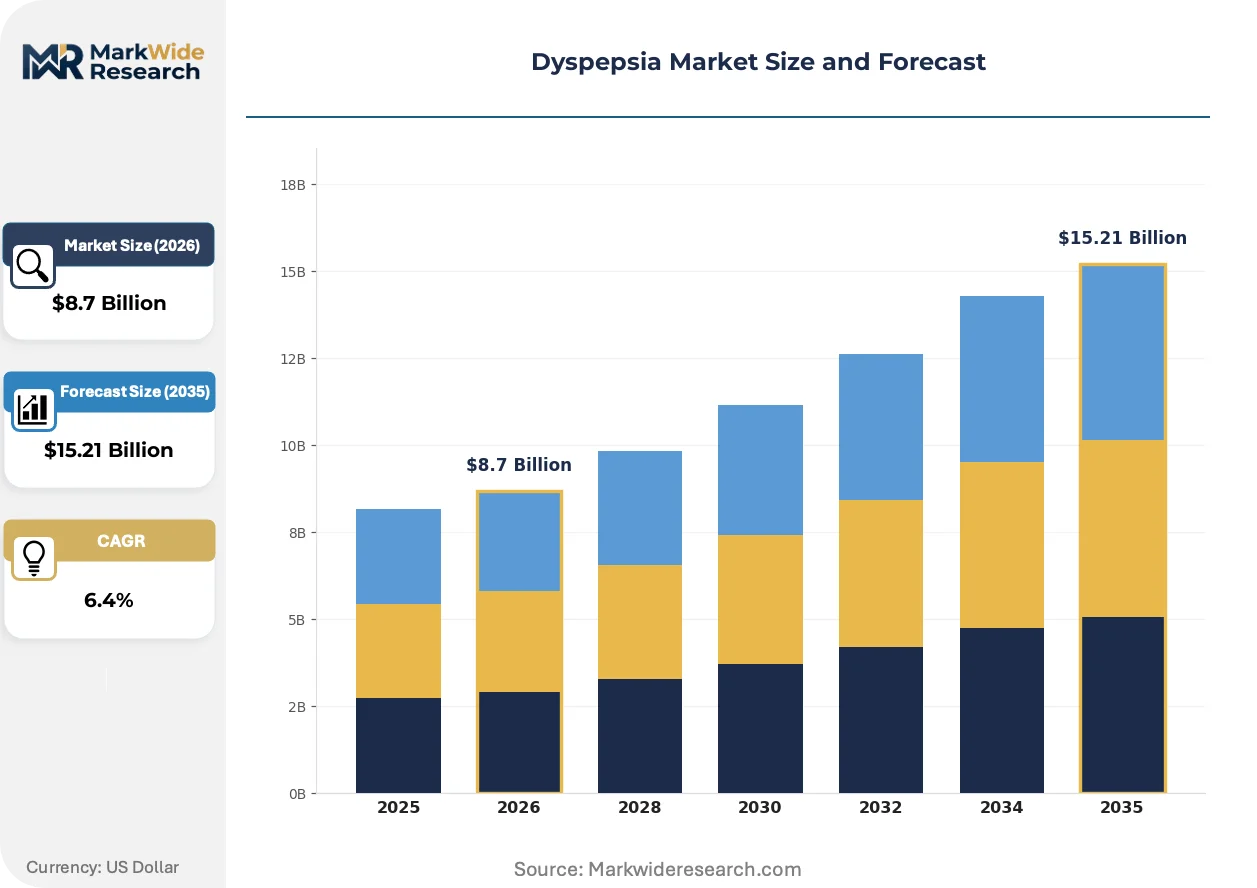
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Pump Inhibitors, Antacids, H2-Receptor Antagonists, Antibiotics End User: Clinics, Hospitals, Homecare, Ambulatory Surgical Centers Application: Acid Reflux, Gastritis, Functional Dyspepsia, Gastroesophageal Disease Delivery Mode: Oral, Injectable, Topical, Intravenous |
| Companies Covered | AstraZeneca plc, Pfizer Inc., GlaxoSmithKline plc, Sanofi, Takeda Pharmaceutical Company Ltd., Abbott Laboratories, Salix Pharmaceuticals, Johnson & Johnson Services, Inc., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dyspepsia Market Emerging Trajectories
Acid suppression therapy development is pivoting toward mechanism-based differentiation as potassium-competitive acid blockers challenge proton pump inhibitor dominance through faster onset kinetics and reversible binding profiles.
P-CAB compounds are absorbing clinical trial investment previously directed toward next-generation PPI formulations, with reversible proton pump antagonism enabling flexible dosing schedules that appeal to shift workers and irregular eaters. Gastroenterology departments in tertiary hospitals are piloting these agents for non-erosive reflux disease overlap populations. The technology is absorbing market share from delayed-release PPIs in Japan and South Korea where PMDA and MFDS approvals have preceded FDA timelines.
REACH authorization requirements for pharmaceutical intermediates are forcing reformulation of coating solvents used in enteric-protected acid suppression tablets, with ECHA substance restrictions affecting supply continuity for European manufacturers. Manufacturers are relocating solvent recovery operations to jurisdictions with less stringent volatile organic compound limits. The regulatory shift most impacts mid-scale generic producers lacking captive chemical synthesis capabilities.
Hospital procurement committees are consolidating dyspepsia therapy purchasing through centralized therapeutic class reviews that bundle acid suppressants with endoscopy services. Integrated delivery networks in the United States are replacing individual physician prescribing autonomy with formulary compliance incentives tied to quality metrics. This consolidation is most advanced in Medicare Advantage–dominated metropolitan markets where risk-bearing entities control specialist referral patterns.
Dyspepsia Market Segmentation
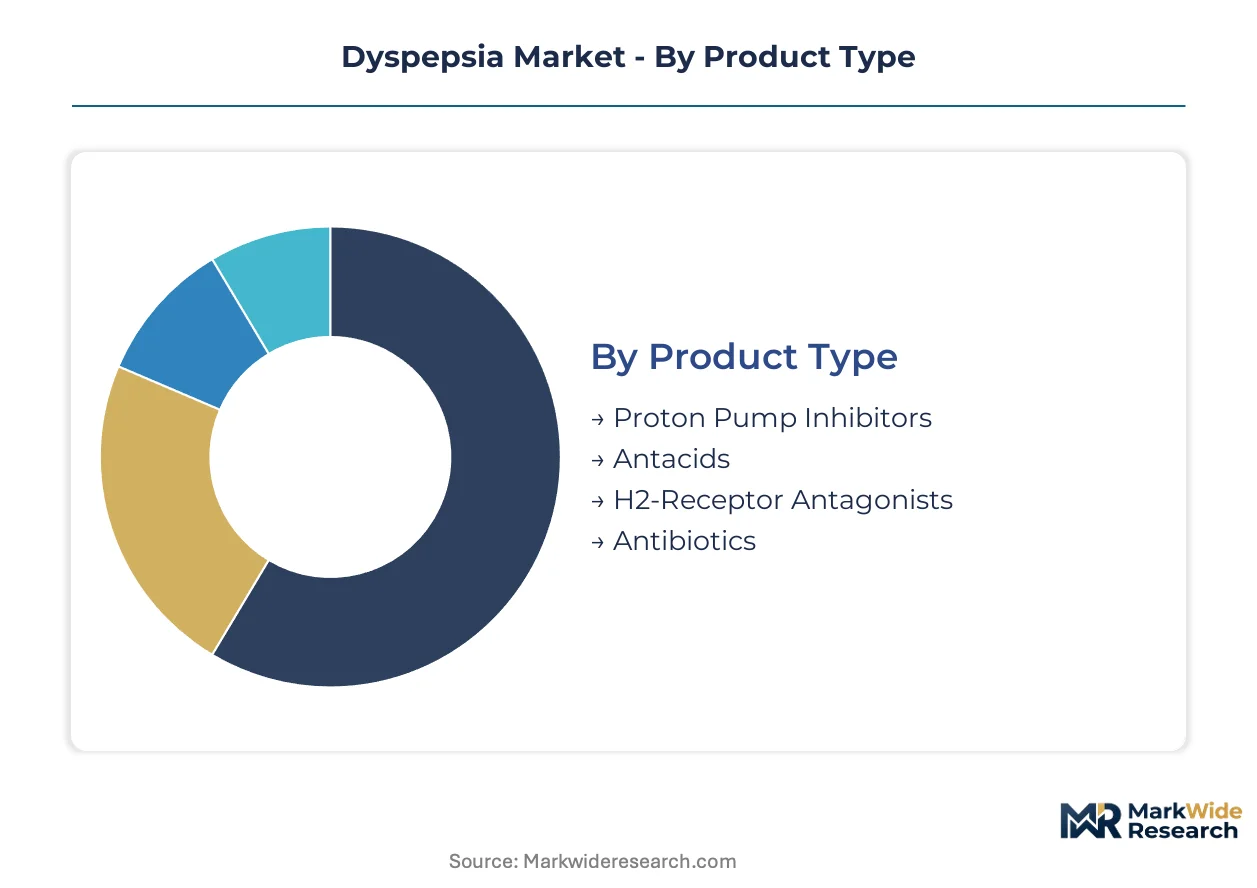
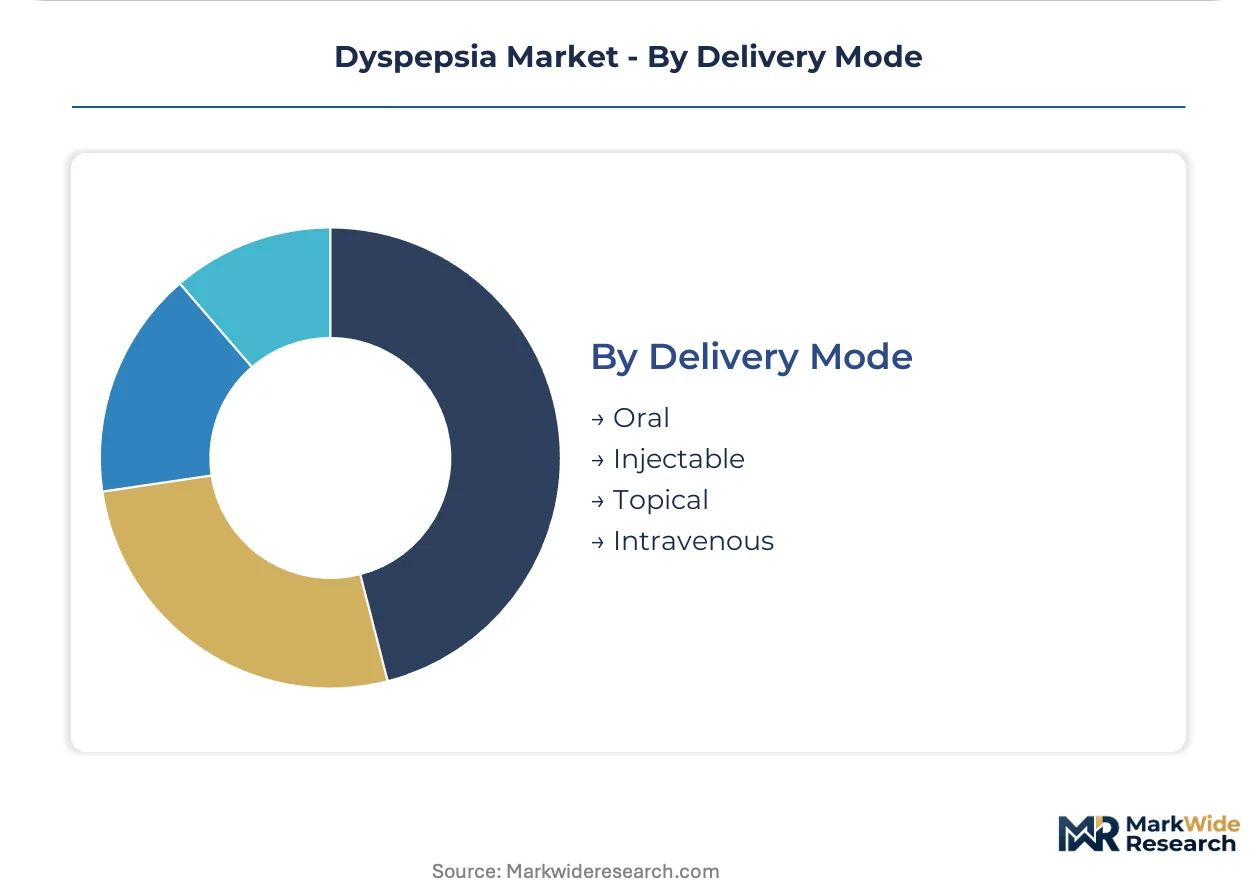
Dyspepsia therapy segmentation reveals divergent margin structures across prescription and over-the-counter channels. Product type and delivery mode combinations determine reimbursement pathways, while end-user concentration shapes procurement contract negotiations.
Product Type:
Prescription authority and acid suppression potency separate buyers across this category.
- Proton Pump Inhibitors:Irreversible proton pump binding delivers sustained gastric pH elevation below four. Hospital formularies in the United States concentrate demand here for erosive esophagitis protocols, though generic substitution compresses branded pricing.
- Antacids:Rapid neutralization chemistry targets episodic symptom relief without prescription barriers. Retail pharmacy volumes in India concentrate in this segment, where CDSCO streamlined bioequivalence pathways accelerate generic formulation entry.
- H2-Receptor Antagonists:Competitive histamine blockade offers intermediate duration acid suppression for milder presentations.
- Antibiotics:Helicobacter pylori eradication regimens combine with acid suppressants in triple-therapy protocols.
Volume sits with Proton Pump Inhibitors; growth tilts toward Antibiotics as H. pylori resistance patterns drive combination therapy innovation.
End User:
Capital intensity and procedural integration define purchasing behavior across care settings.
- Hospitals:Tertiary gastroenterology departments command centralized procurement for inpatient acid suppression protocols. Medicare Advantage concentration in United States metropolitan markets steers volume toward integrated delivery network formularies.
- Ambulatory Surgical Centers:Lower overhead structures attract pre-procedural PPI administration for endoscopy patients. EMA pharmacovigilance frameworks for extended therapy build prescriber confidence in outpatient protocols.
- Clinics:Primary care gatekeepers initiate dyspepsia workup before specialist referral.
- Homecare:Maintenance therapy dispensing follows hospital discharge for chronic gastritis patients.
Revenue concentrates in Hospitals; Ambulatory Surgical Centers are climbing the fastest as procedural volume shifts outpatient.
Application:
Structural lesion presence versus functional diagnosis determines diagnostic workup intensity and therapy duration.
- Functional Dyspepsia:Rome IV criteria identify patients without mucosal damage, expanding addressable pools where PPI response is partial. Gastroenterology practices in Japan apply PMDA-approved P-CAB compounds for this overlap population.
- Gastritis:Mucosal inflammation protocols demand extended acid suppression with healing verification endoscopy. EPA emission compliance costs for active ingredient synthesis constrain supply elasticity in this high-volume segment.
- Acid Reflux:Symptom-driven intermittent therapy dominates over-the-counter channels.
- Gastroesophageal Disease:Erosive presentations require maintenance dosing with surveillance protocols.
Patient volume clusters in Gastritis; Functional Dyspepsia exhibits the steepest expansion trajectory as diagnostic criteria improve case identification.
Delivery Mode:
Patient compliance capability and acute care necessity shape route selection.
- Oral:Enteric-coated delayed-release formulations protect acid-labile compounds through gastric transit. Formulation scientist scarcity for coating technologies extends development timelines across North American manufacturing networks.
- Intravenous:Peri-procedural and nil-per-os inpatient indications command premium pricing. MFDS approvals in South Korea for IV esomeprazole preceded FDA timelines, establishing regional supply precedents.
- Injectable:Subcutaneous depot formulations address compliance failures in chronic maintenance.
- Topical:Mucosal protective agents adjunctive to systemic acid suppression.
Dispensing volume favors Oral; Intravenous gains share fastest as same-day surgery protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in pharmaceutical manufacturing hubs concentrate active ingredient production for acid suppression therapies. Tax incentives in these zones lower compliance costs for EPA-regulated synthesis operations. Cluster effects in designated chemical processing districts accelerate formulation development timelines.
United States
Medicare Advantage penetration in metropolitan markets concentrates dyspepsia prescription volume through integrated delivery networks. FDA accelerated approval pathways compress development timelines for novel acid suppression mechanisms. The Research Triangle Park corridor anchors clinical trial infrastructure for gastrointestinal therapeutics.
Germany
EMA pharmacovigilance frameworks for long-term acid suppression build prescriber confidence in extended therapy protocols. REACH authorization requirements for pharmaceutical intermediates force reformulation of coating solvents in enteric-protected tablets. The Rhine-Main chemical cluster hosts specialized manufacturing for proton pump inhibitor active ingredients.
Japan
PMDA approvals for potassium-competitive acid blockers preceded FDA timelines, establishing regional supply precedents. METI industrial policy supports domestic pharmaceutical manufacturing through designated innovation zones. The Kansai region concentrates formulation expertise for acid-labile compound coating technologies.
India
CDSCO streamlined bioequivalence requirements accelerate generic acid suppression formulation entry. PLI scheme incentives for pharmaceutical manufacturing expand active ingredient production capacity. Gujarat's special economic zones concentrate contract manufacturing for export-oriented proton pump inhibitor synthesis.
South Korea
MFDS approvals for intravenous esomeprazole established regional supply precedents ahead of FDA timelines. National health insurance reimbursement policies sustain prescription volumes for branded acid suppression therapies. The Songdo biomedical cluster hosts specialized gastroenterology clinical research infrastructure.
Dyspepsia Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with prescription authority concentrating value pools while generic substitution compresses retail margins. The structure tilts toward consolidated procurement through hospital formularies and integrated delivery networks. Three archetypes dominate: multinational pharmaceutical conglomerates with manufacturing scale, regional generic specialists with bioequivalence expertise, and niche innovators pursuing mechanism-based differentiation through potassium-competitive acid blockers. Competitive moves center on formulary compliance incentives and strategic partnerships with ambulatory surgical center networks.
Within the multinational tier, AstraZeneca plc and Pfizer Inc. occupy positions shaped by brand strength and manufacturing scale respectively. Takeda Pharmaceutical Company Ltd. exemplifies the R&D-intensive archetype pursuing acid suppression technology advancement. These three entities anchor competitive dynamics across North American hospital networks and Japanese gastroenterology practices.
| Leading Market Players |
|---|
| AstraZeneca plc |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Sanofi |
| Takeda Pharmaceutical Company Ltd. |
| Abbott Laboratories |
| Salix Pharmaceuticals |
| Johnson & Johnson Services, Inc. |
| Bayer AG |
| Others |
Supply Flow & Price Mechanics
Active pharmaceutical ingredient synthesis costs for proton pump inhibitors cascade through three pricing tiers as EPA emission compliance expenditures accumulate from coastal manufacturing clusters to hospital formularies and retail pharmacy channels. Enteric coating solvent reformulations under REACH authorization requirements further stratify procurement costs between European manufacturers and export-oriented generic producers in India.
Pricing Analysis
Short lead-time premiums for intravenous esomeprazole concentrate pricing in peri-procedural settings, while spot inventory of patent-expired omeprazole formulations trades at compressed margins in retail channels. Three-tier pricing structure across premium branded, authorized generic, and economy pure-generic levels reflects FDA therapeutic equivalence ratings and bioequivalence certification tiers. Pricing pressure stems from Medicare Advantage formulary consolidation that bundles acid suppressants with endoscopy services, tightening margins for non-contracted suppliers. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement schedules, while tertiary hospital systems leverage volume scale for preferential contracting.
Supply Chain Analysis
Certification gating through FDA current good manufacturing practice inspections and EMA qualified person release requirements constrains active pharmaceutical ingredient supplier pools to validated manufacturing sites in India, China, and the United States. Proton pump inhibitor synthesis draws from specialized chemical intermediates including benzimidazole derivatives and pyridine-based moieties, with enteric coating polymers sourced from European specialty chemical producers. Single-source vulnerability concentrates in coastal Indian manufacturing zones subject to monsoon-related logistics disruptions. Distribution runs through hospital procurement committees and integrated delivery network formularies that consolidate therapeutic class purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA pharmaceutical manufacturing emission regulations and EMA pharmacovigilance frameworks erect substantial compliance cost barriers that protect incumbent positions while filtering sub-scale entrants from proton pump inhibitor and potassium-competitive acid blocker markets.
For Market Incumbents: To counter potassium-competitive acid blocker displacement of conventional proton pump inhibitor protocols, secure backward integration into enteric coating polymer supply and expand manufacturing capacity in Gujarat special economic zones to exploit PLI scheme incentives. Anchor hospital formulary positions through integrated endoscopy service bundling that locks out non-contracted competitors. For New Entrants and Emerging Players: Ambulatory surgical center networks represent the most penetrable buyer archetype for novel acid suppression mechanisms, given their procurement autonomy outside integrated delivery network consolidation. Target non-erosive reflux disease overlap populations in Japanese gastroenterology practices where PMDA approvals precede FDA timelines. Pursue CDSCO bioequivalence pathway alignment for generic formulation export into price-sensitive Indian retail channels. For Investors and Strategic Acquirers: MFDS approval of intravenous esomeprazole ahead of FDA timelines is the leading indicator that regional regulatory divergence creates acquisition value in specialized manufacturing capabilities. Position for five-to-ten year horizon consolidation around mechanism-based differentiation, with formulation expertise in acid-labile compound coating technologies as the priority target archetype. Monitor REACH authorization requirement expansions as the signal for solvent recovery operation relocation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Potassium-Competitive Acid Blocker Clinical Advancement | P-CAB pipeline progression through FDA accelerated approval pathways displaces conventional PPI dominance in hospital formularies. |
| Enteric Coating Technology Licensing | Specialized solvent recovery capabilities under REACH compliance constraints command premium valuations from European manufacturers. |
| Integrated Delivery Network Partnership | Medicare Advantage concentration in metropolitan markets bundles acid suppression procurement with endoscopy referral control. |
| CDSCO Bioequivalence Pathway Alignment | Streamlined Indian regulatory requirements accelerate generic proton pump inhibitor export into price-compressed retail channels. |
| Ambulatory Surgical Center Network Expansion | Lower overhead structures attract pre-procedural PPI administration volume shifting from inpatient hospital settings. |
Methodological Framework
Multi-period observation of FDA approval timelines, EMA pharmacovigilance framework expansions, and hospital formulary contract awards anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare prescription data. Bottom-up patient volume modeling and top-down therapeutic class expenditure analysis provided cross-verification.
Segment-weighting across product type, end user, application, and delivery mode dimensions structured the analytical framework over the projection horizon. CAGRs were derived from patient population growth trajectories, diagnostic criteria expansion effects, and therapy duration assumptions. Modeled inputs included Rome IV criteria adoption rates, potassium-competitive acid blocker clinical trial progression, and integrated delivery network consolidation patterns.
Revisions become necessary when FDA approval pathway divergence from EMA or PMDA timelines materializes, when EPA emission enforcement actions disrupt active pharmaceutical ingredient supply, or when Medicare Advantage formulary bundling accelerates beyond modeled rates. A model refresh is warranted upon material change in potassium-competitive acid blocker regulatory approval status or REACH authorization requirement scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Food Market
Food Intolerance Products
Europe Gluten Free Foods and Beverages Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market
Food Intolerance Products
Reduced Salt Food Products Market
Food Intolerance Products
Low GI Food Market
Food Intolerance Products
Global Gluten-Free Ready Meals Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market
Food Intolerance Products
Food Intolerance Products Market
Food Intolerance Products
Argentina Gluten-Free Food and Beverage Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Europe Gluten-Free Oats Market
Food Intolerance Products
Citrus-Derived Gastrointestinal Comfort Blends Market
Food Intolerance Products
Allergen Free Food Market
Food Intolerance Products
Sugar Free Food and Beverage Market
Food Intolerance Products
Italy Gluten-Free Foods and Beverages Market