
 United States Gluten Free Foods and Beverages Market | 2026-2036
United States Gluten Free Foods and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
United States Gluten Free Foods and Beverages Market Analytics
Multi-source ingredient procurement is recalibrating how domestic manufacturers secure certified gluten-free oats, rice, and alternative flours. General Mills Inc. leverages its vertically milled supply chain to maintain batch purity across cereal lines. Bob's Red Mill Natural Foods Inc. anchors its position through dedicated gluten-free milling facilities in Oregon. The Hain Celestial Group Inc. differentiates via organic-certified gluten-free portfolios that command shelf-space premiums.
Gluten free foods and beverages comprise products formulated without wheat, barley, rye, or cross-contaminated oats, typically substituting with rice flour, tapioca starch, or almond meal to achieve comparable texture and shelf stability. These formulations serve celiac disease patients, non-celiac gluten sensitivity consumers, and discretionary health seekers seeking reduced-inflammation diets. Snack foods and cereals lead volume contribution due to repeat-purchase frequency and portable consumption occasions. Beverages represent the fastest-expanding margin pool as functional hydration and fermented alternatives displace traditional soft drinks. Supermarkets and specialty stores still dominate distribution throughput, though online channels are capturing subscription-based replenishment demand.
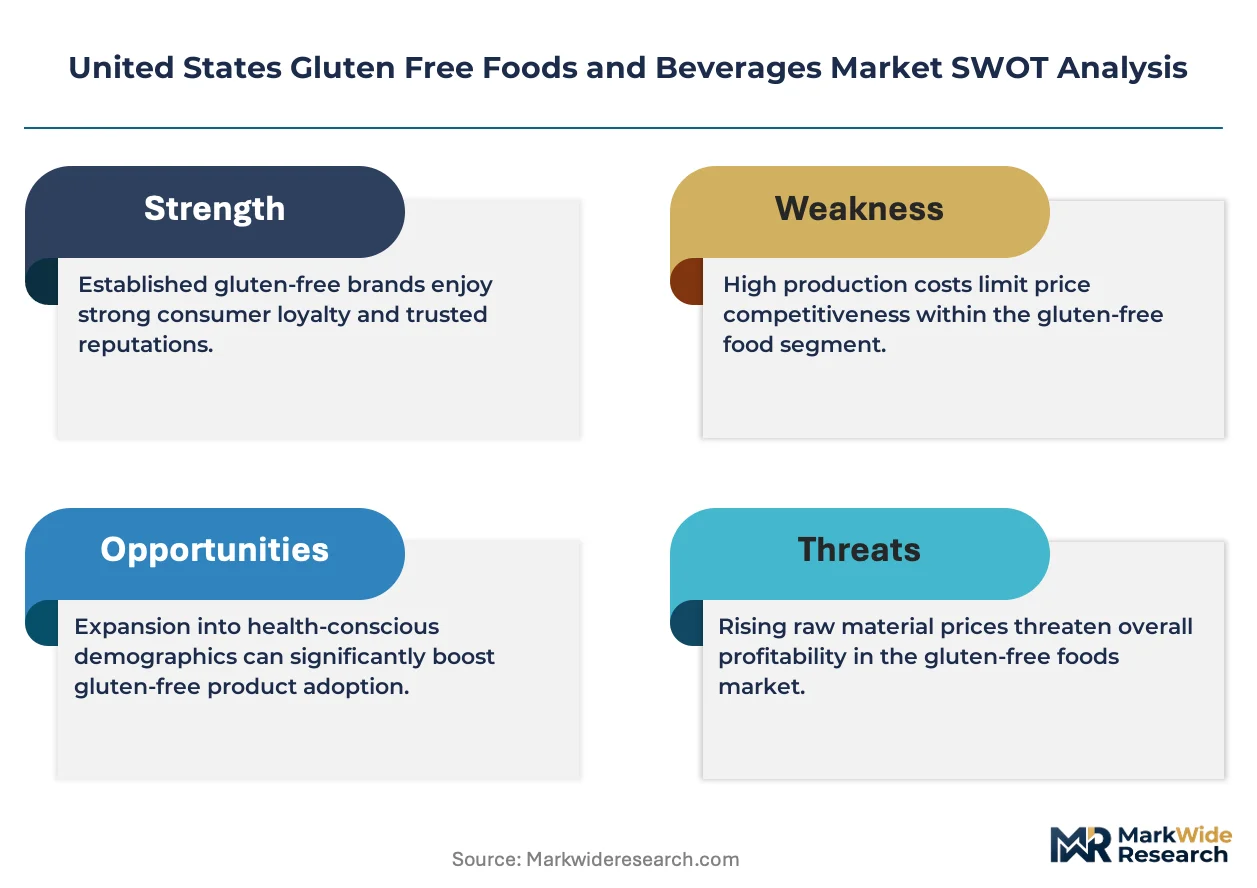
The FDA enforces the Gluten-Free Food Labeling Final Rule, mandating sub-20 ppm gluten thresholds and shaping manufacturer testing protocols and liability exposure. USDA organic certification intersects with gluten-free claims, creating dual-compliance costs that filter smaller producers from national retail placement. State-level health departments in California, Texas, and New York conduct supplemental marketplace sampling that amplifies enforcement variance. Stakeholders must monitor evolving FDA guidance on fermented and hydrolyzed gluten-free products, as analytical method disputes could redefine permissible ingredient lists and reformulation timelines.
Market Dynamics
FDA's sub-20 ppm gluten labeling threshold is compressing manufacturer margins while forcing batch-level testing investments that smaller mills cannot absorb. This regulatory pressure is reshaping competitive entry barriers across cereal, snack, and beverage formulations.
Growth Catalysts
- Urban Health-Conscious Concentration:California and Texas metropolitan clusters sustain premium pricing power for certified-organic gluten-free portfolios. Restaurant chains in these states now dedicate separate prep lines to capture celiac diner loyalty.
- FDA Gluten-Free Labeling Final Rule:Standardized thresholds reduce consumer confusion and accelerate retail shelf placement for compliant manufacturers. Third-party certification bodies gain authority as de facto market gatekeepers.
- Fermented Functional Beverages:Kombucha and probiotic drink lines are capturing discretionary health seekers seeking reduced-inflammation positioning beyond core celiac populations.
Market Restraints
- Certified Gluten-Free Oat Scarcity:Domestic oat supply concentrates in the Northern Plains, where cross-contamination risk limits eligible acreage. Purity-protocol premiums now exceed 40% above commodity oats.
- Dual-Compliance Cost Burden:USDA organic certification intersecting with FDA gluten-free mandates filters regional producers from national retail placement. Smaller Oregon and Colorado mills lack capital for parallel audit streams.
- Rice Flour Input Volatility:Arkansas and Louisiana rice belt weather variability disrupts alternative flour pricing predictability. Manufacturers face margin compression during drought cycles.
Strategic Opportunities
- Subscription Replenishment Channels:Direct-to-consumer platforms bypass slotting fee barriers that disadvantage emerging brands in conventional retail. Pacific Northwest and Northeast urban corridors show highest subscription retention rates.
- Fermented Product Regulatory Clarity:Pending FDA guidance on hydrolyzed gluten-free formulations will unlock new ingredient lists for sourdough and malt alternatives. First movers in analytical method validation capture reformulation timelines.
- Midwest Restaurant Chain Expansion:Underserved celiac populations in Ohio, Indiana, and Michigan present white-space demand for dedicated gluten-free menu sections. Regional chains can establish loyalty before national competitors arrive.
Industry Challenges
- Cross-Contamination Control Talent:Food safety managers with dedicated gluten-free facility experience command salary premiums that strain mid-cap manufacturer budgets. Technical training programs remain underdeveloped at land-grant universities.
- Batch Testing Infrastructure Capex:ELISA and PCR equipment for sub-20 ppm verification requires capital outlays that extend payback periods for single-product lines. Co-manufacturing relationships introduce liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Gluten Free Foods and Beverages Market |
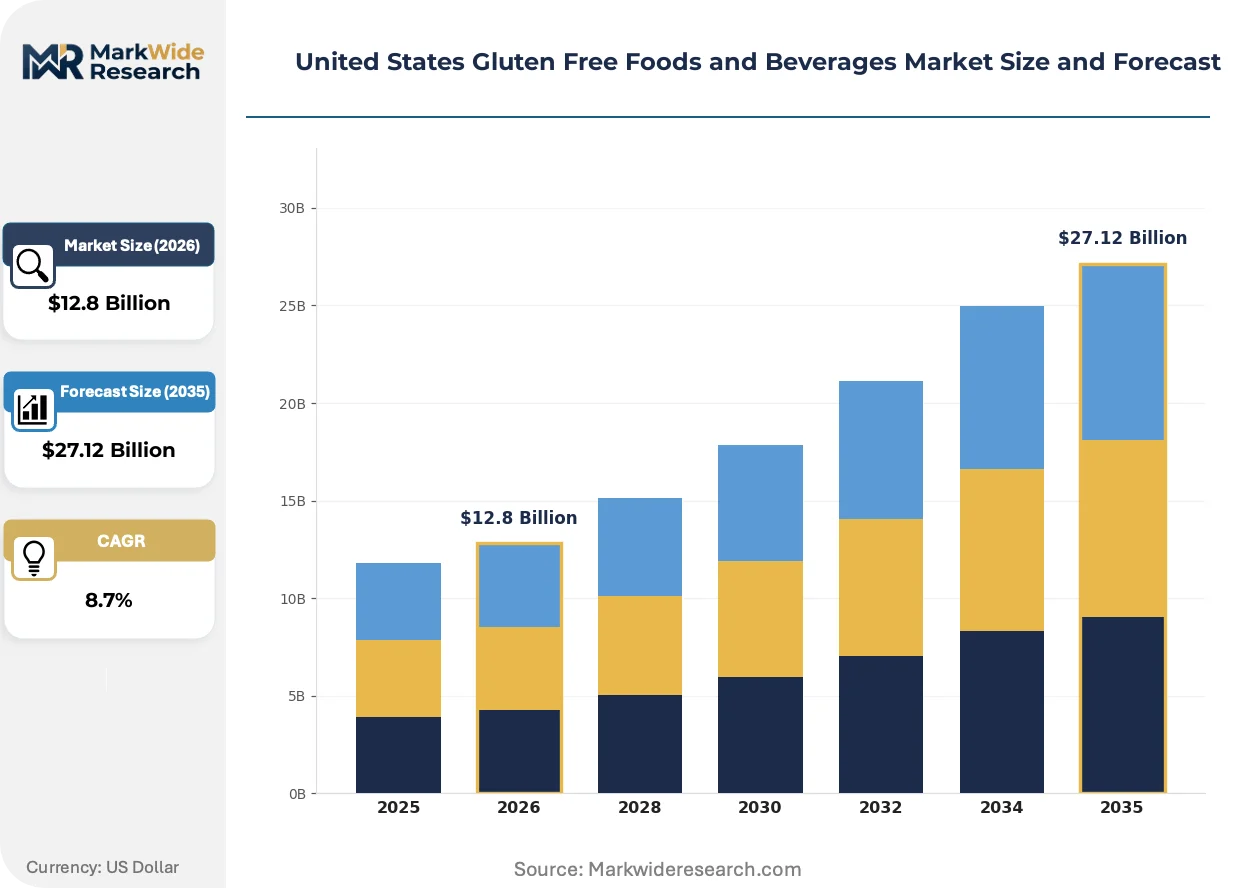
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snack Foods, Breads, Cereals, Beverages Distribution Channel: Online, Supermarkets, Specialty Stores, Convenience Stores End User: Individuals, Restaurants, Cafes, Food Service Providers Packaging Type: Bags, Boxes, Tetra Packs, Jars |
| Companies Covered | General Mills Inc., Conagra Brands Inc., The Hain Celestial Group Inc., Bob's Red Mill Natural Foods Inc., PepsiCo Inc., The Kraft Heinz Company, Kellanova, Amy's Kitchen Inc., Flowers Foods Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Gluten Free Foods and Beverages Market Evolving Landscape
Automation in milling and testing protocols is compressing quality assurance timelines while enabling smaller-batch production economics previously reserved for industrial-scale facilities.
Near-infrared spectroscopy paired with machine learning algorithms is automating real-time gluten detection across incoming grain shipments. Mid-sized Oregon and Minnesota mills are adopting these systems to reduce third-party lab dependency. The technology is automating batch release decisions that previously required 48-hour external verification cycles.
FDA enforcement discretion on fermented gluten-free products is tightening ahead of formal guidance publication. Manufacturers using traditional sourdough starters face reformulation pressure as analytical disputes over hydrolyzed protein detection methods persist. Beverage segments employing malt alternatives are most exposed to potential ingredient list revisions.
Health-conscious urban consumers in California and Texas are consolidating purchase decisions around dual-certified organic-gluten-free labels. Specialty retailers in Los Angeles, Austin, and Dallas are responding with dedicated aisle sections that displace conventional natural products. This certification-driven preference shift concentrates shelf-space premiums among portfolios with existing dual compliance infrastructure.
United States Gluten Free Foods and Beverages Market Segmentation
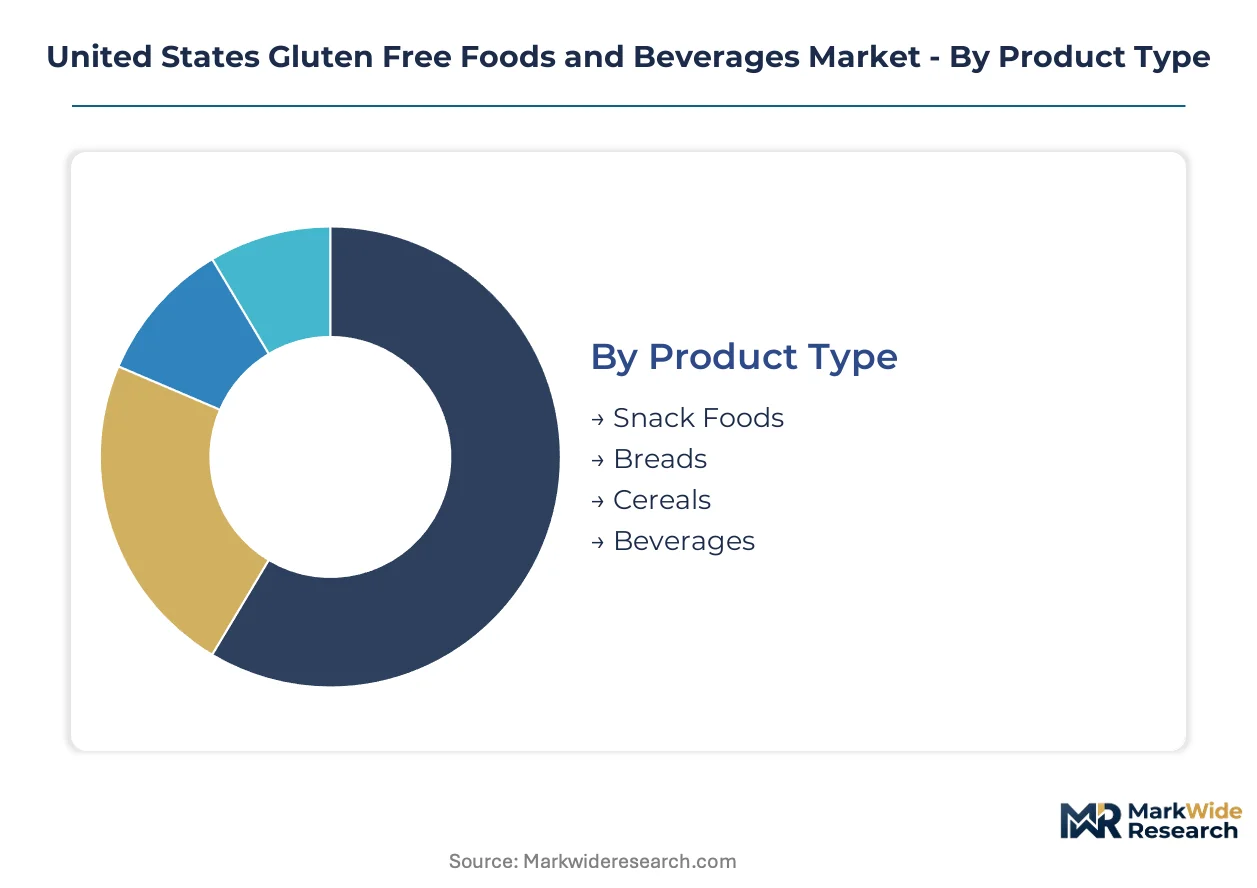
Segmentation in the United States gluten-free market reveals how FDA compliance costs and ingredient sourcing constraints concentrate profitability across specific product formats and channel configurations. Understanding these divides exposes where capital investments yield sustainable margin protection versus commodity exposure.
Product Type:
Supply concentration for certified gluten-free oats and alternative flours shapes competitive positioning across formulation categories, with milling infrastructure determining batch purity economics.
- Snack Foods:Formulations rely on rice flour, tapioca starch, and almond meal to achieve shelf-stable texture without wheat gluten. California and Texas urban clusters sustain premium pricing for portable, single-serve formats targeting commuter and office consumption occasions. Repeat-purchase frequency and impulse channel placement protect margin stability against input cost swings.
- Beverages:Kombucha, probiotic drinks, and functional hydration lines employ fermented bases with malt alternatives. Demand concentrates among discretionary health seekers in Austin, Los Angeles, and Dallas seeking reduced-inflammation positioning beyond core celiac populations. Pending FDA guidance on hydrolyzed gluten detection methods creates reformulation uncertainty for sourdough-derived ingredients.
- Breads:Dense, gum-dependent formulations using xanthan or guar substitutes for wheat gluten structure. Texas and California health-conscious households drive uptake of frozen and fresh-baked premium lines.
- Cereals:Puffed and extruded grains requiring dedicated gluten-free milling facilities to prevent cross-contamination. General Mills and Bob's Red Mill anchor supply through vertically controlled or dedicated Oregon facilities.
Snack Foods absorb the bulk of installed capacity; Beverages is expanding most quickly.
Distribution Channel:
Cost tier stratification across channel types filters which manufacturers achieve national placement versus regional concentration, with slotting fee structures favoring multi-product portfolios.
- Supermarkets:Dominant throughput channel commanding dedicated aisle sections in California and Texas urban stores. Dual-certified organic-gluten-free labels capture shelf-space premiums through certification-driven consumer consolidation.
- Online:Direct-to-consumer subscription platforms bypass conventional retail barriers, with Pacific Northwest and Northeast urban corridors showing highest retention rates for replenishment-based purchasing.
- Specialty Stores:Curated assortments in natural products retailers emphasizing local and artisanal gluten-free producers. Los Angeles, Austin, and Dallas locations respond with dedicated sections displacing conventional natural products.
- Convenience Stores:Limited gluten-free presence concentrated in grab-and-go snack formats. Shelf-stable, individually packaged items with extended dating predominate.
Supermarkets command the greatest volume throughput; Online is climbing the fastest as subscription models mature.
End User:
Application-specific requirements across consumer versus foodservice segments dictate formulation flexibility, with restaurant chains investing in separate prep lines to capture celiac diner loyalty.
- Individuals:Household purchasers seeking certified products for celiac disease management or discretionary health optimization. California and Texas metropolitan health-conscious populations drive premium uptake.
- Restaurants:Midwest and Southeast chains expanding dedicated gluten-free menu sections with segregated kitchen protocols. Ohio, Indiana, and Michigan present white-space demand before national competitor arrival.
- Cafes:Limited-service operations offering gluten-free baked goods and beverage pairings. Urban California and Texas locations lead in dedicated equipment investment.
- Food Service Providers:Institutional and contract feeding operations requiring bulk-certified ingredients with batch documentation. Compliance with FDA sub-20 ppm thresholds drives supplier qualification rigor.
Individuals represent the foundational demand base; Restaurants is gaining share fastest through chain expansion.
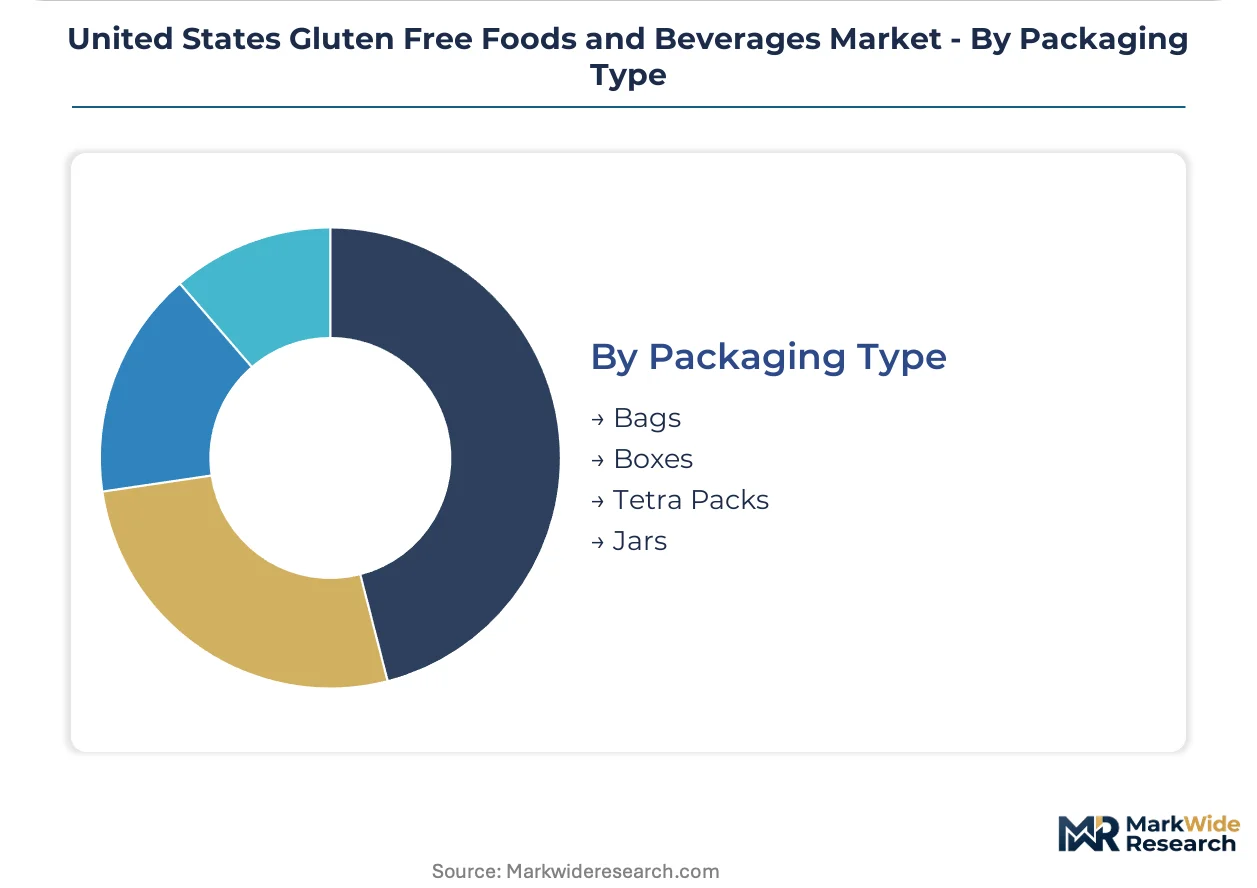
Packaging Type:
Volume and margin characteristics vary by packaging format, with barrier properties and shelf-life extension determining suitability for specific product moisture and oil content profiles.
- Bags:Flexible packaging for snacks and dry cereals employing multi-layer films with oxygen barriers. High-speed form-fill-seal economics favor large-scale production runs.
- Boxes:Secondary containment for cereals and crackers with inner bag structures. Retail shelf presence and stacking stability drive format selection.
- Tetra Packs:Aseptic cartons for beverages enabling ambient distribution without refrigeration. California and Texas retail environments favor ambient-stable functional drinks.
- Jars:Glass or rigid plastic containers for spreads, fermented products, and wet goods. Premium positioning supports higher price points in specialty retail.
Bags handle the greatest unit volume; Tetra Packs show the steepest expansion trajectory in beverage applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified gluten-free oat production anchors the Northern Plains, where purity-protocol acreage determines raw-material availability for domestic milling operations. This geographic concentration shapes manufacturer location decisions and compliance cost structures across the contiguous United States.
California
Los Angeles and San Francisco metropolitan clusters sustain premium pricing for dual-certified organic-gluten-free portfolios. The California Department of Public Health conducts supplemental marketplace sampling that amplifies FDA enforcement variance. Austin-inspired health-conscious retail formats in Los Angeles displace conventional natural products with dedicated gluten-free aisle sections.
Texas
Dallas and Austin urban corridors drive fastest-expanding demand for functional beverages and fermented alternatives. State health department sampling protocols exceed federal minimums for gluten-free label verification. Restaurant chains in Houston and San Antonio invest in segregated prep lines to capture celiac diner loyalty before national competitors establish presence.
Pacific Northwest
Oregon's dedicated gluten-free milling facilities anchor batch purity economics for cereal and flour production. The Oregon Department of Agriculture enforces parallel audit streams that intersect with FDA mandates. Portland and Seattle subscription replenishment platforms show highest retention rates for direct-to-consumer gluten-free portfolios.
Midwest
Ohio, Indiana, and Michigan present white-space demand for restaurant chain gluten-free menu expansion. State agricultural extension services in Illinois and Wisconsin support purity-protocol oat cultivation trials. Chicago and Detroit foodservice distributors qualify bulk-certified suppliers under FDA sub-20 ppm documentation requirements.
Southeast
Atlanta and Miami metropolitan areas concentrate health-conscious populations seeking reduced-inflammation positioning. Florida and Georgia state health departments coordinate regional sampling campaigns with federal thresholds. Restaurant chains in Charlotte and Nashville expand dedicated gluten-free sections with segregated kitchen protocols.
United States Gluten Free Foods and Beverages Market Competitive Landscape
Global majors compete with regional champions across certification infrastructure and milling capacity. The vendor base stratifies into three tiers: diversified food conglomerates with vertically controlled supply chains, mid-cap specialists operating dedicated gluten-free facilities, and emerging brands leveraging subscription channels to bypass retail slotting barriers. Dominant competitive moves include backward integration into certified oat sourcing and strategic partnerships with third-party certification bodies.
Within the diversified conglomerate tier, General Mills Inc., Conagra Brands Inc., and The Hain Celestial Group Inc. occupy positions defined by scale-driven batch purity economics and dual-compliance infrastructure. Bob's Red Mill Natural Foods Inc. exemplifies the mid-cap specialist archetype through Oregon-based dedicated milling operations. These four companies represent the competitive anchor points against which emerging brands benchmark certification investments and channel access strategies.
| Leading Market Players |
|---|
| General Mills Inc. |
| Conagra Brands Inc. |
| The Hain Celestial Group Inc. |
| Bob's Red Mill Natural Foods Inc. |
| PepsiCo Inc. |
| The Kraft Heinz Company |
| Kellanova |
| Amy's Kitchen Inc. |
| Flowers Foods Inc. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap milling operations in Oregon and Minnesota anchor supply-side discipline through generational capital commitment to dedicated gluten-free facilities, insulating pricing power against commodity oat volatility while forcing private-equity-rolled-up snack brands into margin-compressing slotting fee wars for supermarket placement.
Pricing Analysis
Warranty-style batch certification bundled with third-party lab verification commands shelf-space premiums in California and Texas retail environments, while unbundled commodity-grade products face price erosion from rice flour input volatility. Three-tier pricing structure across premium dual-certified organic-gluten-free, standard FDA-compliant, and economy private-label tiers separates buyers by risk tolerance, with foodservice providers exhibiting highest price sensitivity due to bulk documentation requirements and individual health-conscious consumers showing lowest sensitivity to certification-driven premiums.
Supply Chain Analysis
Freight cost premiums for purity-protocol oats sourced from the Northern Plains compress margins for coastal manufacturers lacking captive rail contracts or regional milling partnerships. Domestic supply draws from Montana, North Dakota, and Saskatchewan purity-protocol acreage, with rice flour inputs anchored in Arkansas and Louisiana. Single-source vulnerability concentrates in certified gluten-free oat supply, where eligible acreage limitations create chokepoint exposure. Distribution runs through supermarket direct-store-delivery networks in urban California and Texas, supplemented by Pacific Northwest subscription fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where FDA sub-20 ppm compliance costs and dual-certification audit burdens force sub-scale regional mills toward distressed exits or strategic absorption.
For Market Incumbents: Deploy backward integration into Northern Plains purity-protocol oat sourcing to lock in batch purity economics before acreage competition intensifies. General Mills and Bob's Red Mill should expand dedicated milling capacity in Oregon while acquiring third-party certification body partnerships to gatekeep retail placement against emerging subscription brands threatening channel control. For New Entrants and Emerging Players: FDA Gluten-Free Labeling Final Rule in the United States opens a window for analytical method validation services and hydrolyzed gluten detection consulting ahead of formal fermented product guidance publication. Target Midwest restaurant chain supply relationships in Ohio, Indiana, and Michigan through white-label bulk ingredient positioning, bypassing supermarket slotting fee barriers entirely. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap Oregon and Colorado milling specialists with existing dual-compliance infrastructure but strained parallel audit capital requirements. Long-term viability hinges on subscription channel retention rates and fermented beverage regulatory clarity; watch FDA guidance publication timing as inflection signal for sourdough-derived ingredient reformulation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Purity-Protocol Oats | Captive supply from Montana and North Dakota acreage locks in batch purity economics against 40% commodity premiums. |
| Third-Party Certification Body Partnership | Alliance with FDA-recognized auditors creates de facto gatekeeping authority over retail shelf placement decisions. |
| Subscription Replenishment Channel Launch | Direct-to-consumer platforms in Portland and Seattle bypass slotting fees while capturing highest-retention urban corridors. |
| Fermented Product Analytical Method Investment | Early validation of hydrolyzed gluten detection protocols positions brands ahead of FDA guidance reformulation requirements. |
| Midwest Restaurant Chain Supply Expansion | White-space demand in Ohio, Indiana, and Michigan allows regional loyalty capture before national competitors arrive. |
Research Methodology
Independent corroboration across FDA enforcement action databases, USDA organic certification registries, and state health department sampling records underwrites the qualitative findings. Primary interviews with food safety managers at dedicated gluten-free milling facilities, category buyers at California and Texas supermarket chains, and regulatory affairs leads at diversified food conglomerates combined with secondary validation from FDA guidance documents, USDA agricultural census data, and customs records for rice flour imports. Bottom-up capacity modeling and top-down consumption estimation triangulate volume outputs.
Comparable-period anchoring to historical FDA compliance cost trajectories and purity-protocol oat premium spreads shapes the forecast window across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end user, and packaging format alongside regional regulatory enforcement variance. CAGRs derive from ingredient input cost elasticity analysis and channel shift velocity parameters, with rice flour weather volatility and subscription retention rates serving as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for near-infrared spectroscopy paired with machine learning algorithms would alter the outlook by compressing third-party lab dependency timelines. Forecasts reflect assumptions about FDA guidance publication sequencing and Northern Plains acreage expansion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Europe Gluten-Free Oats Market
Food Intolerance Products
South America Gluten Free Foods and Beverages Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Lactose Free Products Market
Food Intolerance Products
Global Gluten-Free Ready Meals Market
Food Intolerance Products
Gluten-Free Popcorn Products Market
Food Intolerance Products
Allergen Free Food Market
Food Intolerance Products
Nut-Free Cookies Market
Food Intolerance Products
Italy Gluten-Free Foods and Beverages Market
Food Intolerance Products
Food Intolerance Products Market
Food Intolerance Products
Global Lactose Intolerance Treatment Market
Food Intolerance Products
Australia Gluten-Free Foods and Beverages Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Celiac Disease Market
Food Intolerance Products
Gluten Free Tortillas Market