
 Germany Gluten-Free Foods and Beverages Market | 2026-2036
Germany Gluten-Free Foods and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Gluten-Free Foods and Beverages Market Foresight
Health-conscious millennials is reorganizing demand in the Germany gluten-free sector, displacing the traditional celiac-patient-dominant buyer base. Dr Schar AG/S.p.A leverages its dedicated gluten-free manufacturing infrastructure to anchor premium shelf presence across German retail chains. Bauck GmbH specializes in organic-certified gluten-free grains, sustaining brand loyalty among clean-label seekers in the DACH region. Hanneforth food for you GmbH & Co. KG competes through direct-to-consumer channels, controlling last-mile distribution in underserved rural markets.
Germany gluten-free foods and beverages comprise formulated products containing less than 20 parts per million gluten, achieved through alternative grain sourcing, enzymatic degradation, or dedicated production line segregation to prevent cross-contamination. These products serve both medical dietary management for celiac disease and lifestyle positioning for consumers pursuing perceived digestive wellness or reduced inflammation. Breads and pasta occupy mature volume positions with established manufacturing know-how, while snacks capture accelerating growth as on-the-go consumption rises among working professionals. Breakfast cereals concentrate margin pools through premium positioning and fortification with vitamins and minerals. Distribution through supermarkets dominates absolute throughput, though e-commerce channels represent the fastest-expanding access point for repeat purchasers seeking subscription convenience.
German food law implements EU Regulation 1169/2011 on food information to consumers, requiring clear gluten-free labeling that builds purchase confidence and reduces trial barriers for new entrants. The Federal Office of Consumer Protection and Food Safety enforces compliance audits and traceability requirements that elevate production costs for smaller domestic manufacturers. Stakeholders must monitor evolving EU-wide allergen thresholds and potential harmonization with Codex Alimentarius standards that could reshape formulation requirements and competitive parity across the single market.
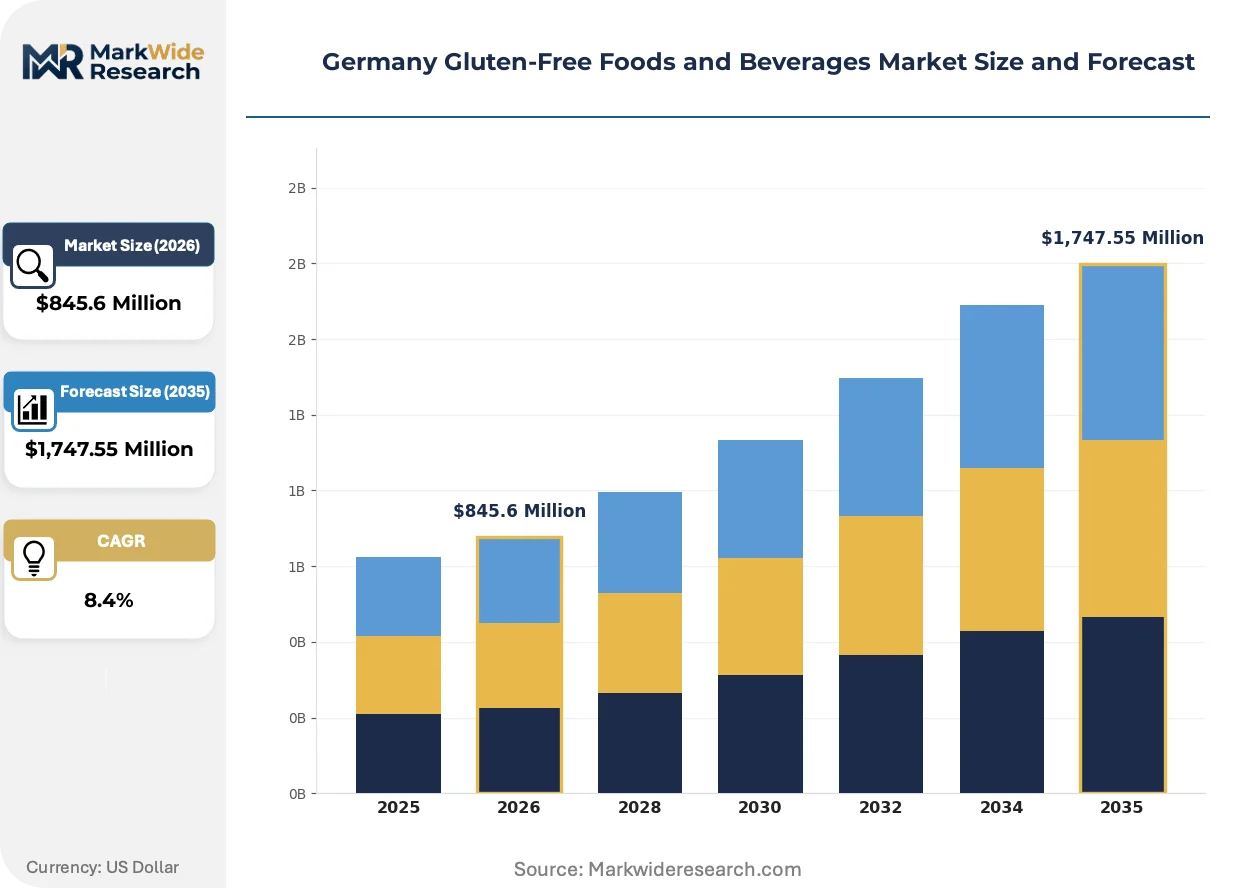
Market Dynamics
Millennial wellness adoption is fragmenting the traditional celiac-patient foundation of Germany's gluten-free sector, forcing manufacturers to pivot from medical positioning to lifestyle branding while navigating strict EU labeling thresholds.
Growth Catalysts
- EU Regulation 1169/2011:Mandatory gluten-free labeling thresholds build consumer trust and reduce trial barriers for new market entrants across German retail channels.
- Alternative grain enzymatic processing:Advanced enzymatic degradation technologies expand formulation flexibility beyond rice and corn bases into ancient grains.
- Bavaria and North Rhine-Westphalia:Concentrated specialty retail density in these states accelerates product accessibility and repeat purchase frequency.
Market Restraints
- Dedicated production line segregation:Capital-intensive facility requirements for cross-contamination prevention elevate fixed costs for domestic manufacturers.
- Alternative grain supply concentration:Dependence on imported quinoa, amaranth, and buckwheat exposes margins to currency volatility and harvest variability.
- 20 ppm gluten threshold rigidity:The Federal Office of Consumer Protection and Food Safety enforces strict compliance that limits formulation experimentation.
Strategic Opportunities
- E-commerce subscription channels:Direct-to-consumer platforms capture repeat purchasers seeking convenience beyond supermarket saturation.
- Fortified breakfast cereals:Vitamin and mineral enrichment creates premium positioning opportunities in an otherwise commoditized segment.
- Rural market underpenetration:Specialty retail gaps in eastern German states offer first-mover expansion potential for digital-native brands.
Industry Challenges
- Audited traceability systems:The Federal Office of Consumer Protection and Food Safety mandates documentation complexity that strains smaller domestic producers.
- Legacy manufacturing retrofitting:Conventional bakeries face prohibitive capex burdens converting to dedicated gluten-free lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Gluten-Free Foods and Beverages Market |
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,747.55 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Snacks, Pasta, Breakfast Cereals End User: Supermarkets, Health Food Stores, Online Retailers, Restaurants Packaging Type: Bags, Boxes, Tins, Pouches Distribution Channel: Direct Sales, Wholesalers, Distributors, E-commerce |
| Companies Covered | Dr Schar AG/S.p.A, Bahlsen GmbH & Co. KG, 3Pauly, Die Seitz glutenfrei GmbH, Bob’s Red Mill Natural Foods, Amy's Kitchen, Inc., Hanneforth food for you GmbH & Co. KG, Bauck GmbH, Hero AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Gluten-Free Foods and Beverages Market Shifts & Advancements
Three convergent forces are reconfiguring Germany's gluten-free landscape: enzymatic processing advances, evolving EU regulatory stringency, and the wellness-driven democratization of what began as a medical niche.
Enzymatic gluten degradation is fragmenting traditional reliance on naturally gluten-free grains by enabling wheat-based products with sub-20 ppm gluten content. Food technologists at German research institutes are refining transglutaminase and prolyl endopeptidase applications for industrial scale. Mid-market bakeries are adopting these systems to reclaim familiar wheat taste profiles without dedicated facility investments.
REACH chemical safety assessments are tightening scrutiny on processing aids and enzyme carriers used in gluten-free manufacturing. The European Chemicals Agency is reviewing cross-contact prevention coatings and sanitizing agents for food-grade compatibility. German manufacturers are preemptively reformulating with bio-based alternatives to avoid supply disruption.
Clean-label certification is compressing purchase decision cycles as German consumers prioritize organic and non-GMO credentials alongside gluten-free claims. Third-party verification from Bioland and Demeter is displacing unverified self-declarations in premium shelf positioning. Bavarian and Baden-Württemberg retailers are consolidating supplier lists around dual-certified portfolios.
Germany Gluten-Free Foods and Beverages Market Segmentation
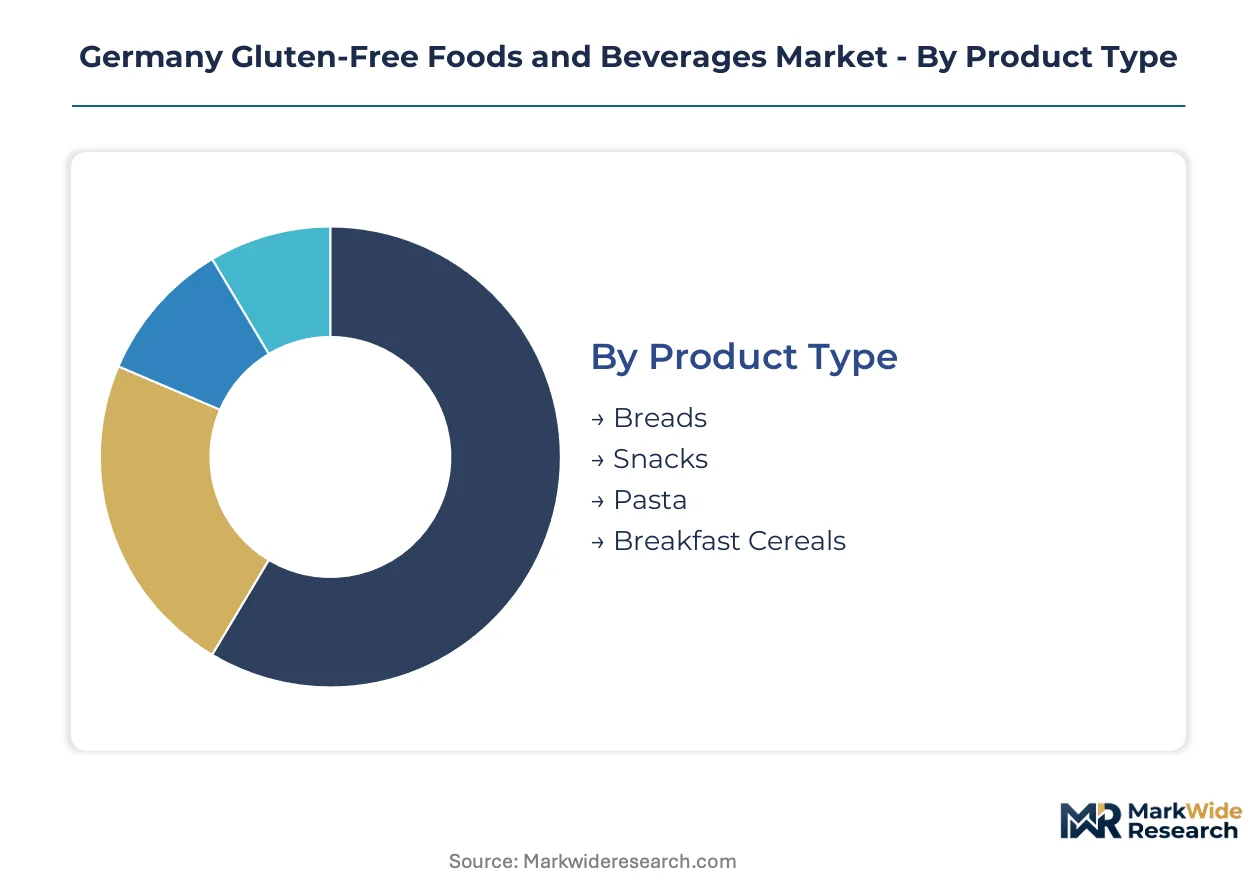
Segmentation in Germany's gluten-free sector reveals how medical necessity and lifestyle positioning create divergent margin profiles across product formats and channel structures. Manufacturers must align formulation investments with the specific compliance and accessibility requirements of each slice.
Product Type:
Margin pools concentrate in fortified categories where premium positioning offsets elevated input costs from alternative grain sourcing and dedicated production line segregation.
- Breads:Formulated with rice, corn, or enzymatically treated wheat bases to achieve sub-20 ppm gluten thresholds. Bavarian and North Rhine-Westphalian retail density supports established manufacturing know-how and repeat purchase loyalty among celiac patients.
- Snacks:On-the-go formats including crackers, bars, and savory bites capture accelerating demand from working professionals in urban centers. Clean-label certification from Bioland and Demeter compresses purchase decision cycles in premium positioning.
- Pasta:Alternative grain formulations using quinoa, amaranth, or legume bases serve both dietary management and protein-seeking wellness consumers.
- Breakfast Cereals:Vitamin and mineral fortification creates differentiation in an otherwise commoditized segment, with subscription e-commerce capturing repeat purchasers.
The dominant share belongs to Breads, while Snacks is closing the gap fastest through convenience-driven urban consumption.
End User:
Channel selection determines compliance burden and last-mile cost structure, with health food stores demanding stricter certification documentation than mass retail.
- Supermarkets:Absolute volume throughput channel where Dr Schar AG/S.p.A and Bauck GmbH anchor premium shelf presence across German retail chains. The Federal Office of Consumer Protection and Food Safety audits enforce traceability requirements that elevate supplier qualification barriers.
- Health Food Stores:Specialty retail concentration in Bavaria and Baden-Württemberg consolidates supplier lists around dual-certified organic and gluten-free portfolios. Third-party verification displaces unverified self-declarations.
- Online Retailers:Direct-to-consumer platforms including Hanneforth food for you GmbH & Co. KG control distribution in underserved rural eastern German states.
- Restaurants:Foodservice channels face cross-contamination prevention protocols that limit menu integration despite rising consumer inquiry.
Supermarkets command the volume base, though Online Retailers is expanding most quickly through subscription convenience and rural penetration.
Packaging Type:
Format selection balances shelf stability requirements against sustainability positioning pressures from REACH-compliant bio-based material transitions.
- Bags:Flexible packaging dominates bread and snack formats, with European Chemicals Agency scrutiny on coatings driving reformulation toward bio-based alternatives.
- Boxes:Rigid formats for breakfast cereals support fortification messaging and premium visual differentiation at point of sale.
- Tins:Metal packaging for ambient-stable pasta and prepared meals extends shelf life but elevates material cost exposure.
- Pouches:Resealable flexible formats capture on-the-go snack demand, with enzyme carrier compatibility under tightening REACH assessment.
Bags holds the installed base, while Pouches is gaining share fastest through portability alignment with working professional consumption patterns.
Distribution Channel:
Channel configuration directly determines working capital intensity and customer data access, with e-commerce subscription models capturing lifetime value beyond transactional wholesale relationships.
- Direct Sales:Manufacturer-controlled relationships with health food cooperatives and regional bakery chains bypass distributor margins but require dedicated sales force investment.
- Wholesalers:Consolidated procurement for supermarket chains concentrates volume leverage, pressuring supplier terms in mature product categories.
- Distributors:Third-party logistics providers manage temperature-controlled storage and allergen-segregated transport for multi-brand portfolios.
- E-commerce:Platform-based and proprietary direct-to-consumer channels represent the steepest expansion trajectory, with subscription convenience capturing repeat purchasers seeking automated replenishment.
Wholesalers retain the volume anchor, yet E-commerce is climbing the fastest as digital-native brands exploit rural underpenetration and subscription retention economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German gluten-free manufacturers export formulated products across the DACH region and into Benelux markets, with cross-border retail procurement concentrating volume flows through Netherlands distribution hubs serving northern European health food chains.
Bavaria
Specialty retail density in Munich and Nuremberg anchors premium product accessibility for health-conscious urban consumers. The Federal Office of Consumer Protection and Food Safety conducts compliance audits that elevate supplier qualification barriers for local manufacturers. Clean-label certification from Bioland and Demeter compresses purchase decision cycles across Bavarian health food cooperatives.
North Rhine-Westphalia
Industrial food processing clusters in Cologne-Düsseldorf corridor support dedicated gluten-free manufacturing infrastructure and enzymatic processing R&D. EU Regulation 1169/2011 enforcement through state-level food safety offices ensures traceability documentation for cross-border shipments. Duisburg logistics terminals manage temperature-controlled distribution for multi-brand portfolios serving Benelux retail chains.
Baden-Württemberg
Organic farming cooperatives in Stuttgart hinterland supply alternative grain inputs for regional gluten-free processors. REACH chemical safety assessments from the European Chemicals Agency drive reformulation of processing aids toward bio-based alternatives. Freiburg and Karlsruhe retail networks consolidate supplier lists around dual-certified organic and gluten-free portfolios.
Lower Saxony
Agricultural commodity trading in Hanover region exposes gluten-free manufacturers to currency volatility in quinoa and amaranth import sourcing. The Federal Office of Consumer Protection and Food Safety mandates audited traceability systems that strain smaller domestic producers in rural eastern districts. Wolfsburg and Braunschweig supermarket chains anchor volume throughput for mass-market gluten-free bread and pasta formats.
Berlin-Brandenburg
Digital-native direct-to-consumer brands exploit e-commerce subscription convenience among urban millennials seeking automated replenishment. EFSA guidance on allergen thresholds informs national interpretation that shapes formulation requirements for Berlin-based startups. Potsdam logistics parks support last-mile distribution infrastructure reaching underserved eastern German states.
Germany Gluten-Free Foods and Beverages Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with publicly traded food conglomerates leveraging scale economics while family-owned organic processors defend margin through dual-certification premiums. The vendor base arranges into three strategic archetypes: dedicated gluten-free pure-plays, diversified organic specialists, and international CPG entrants. Consolidation pressure concentrates among mid-cap domestic brands facing capex burdens for dedicated production line segregation. Competitive moves center on M&A capture of organic-certified supply chains and geographic expansion into rural eastern states through digital-native distribution.
Among DACH-region dedicated gluten-free specialists, Dr Schar AG/S.p.A represents the listed pure-play archetype with S.p.A corporate structure signaling Italian capital market access. Bauck GmbH exemplifies the family-owned organic processor model, with GmbH designation indicating German private limited liability and generational ownership continuity. Hanneforth food for you GmbH & Co. KG occupies the direct-to-consumer digital native position, with KG partnership structure enabling founder control alongside external capital participation. These three entities anchor distinct competitive vectors within the national market structure.
| Leading Market Players |
|---|
| Dr Schar AG/S.p.A |
| Bahlsen GmbH & Co. KG |
| 3Pauly |
| Die Seitz glutenfrei GmbH |
| Bob's Red Mill Natural Foods |
| Amy's Kitchen, Inc. |
| Hanneforth food for you GmbH & Co. KG |
| Bauck GmbH |
| Hero AG |
| Others |
Supply & Pricing Matrix
Dedicated gluten-free manufacturing infrastructure in Bavaria and North Rhine-Westphalia generates scale economies that compress unit costs for enzymatically processed wheat alternatives while establishing price floors for smaller domestic competitors lacking segregated production lines.
Pricing Analysis
Enzymatic processing technology divides pricing tiers between legacy rice-and-corn formulations, current-generation wheat-based enzymatic products, and next-generation ancient grain blends. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and organic credential intensity. Pricing pressure stems from imported quinoa and amaranth currency volatility squeezing mid-market margins. Health food stores exhibit lowest price sensitivity due to dual-certification premiums, while mass-market supermarkets drive cost compression through consolidated procurement leverage.
Supply Chain Analysis
Inventory lead times for alternative grains stretch 8-14 weeks from South American harvest cycles through Rotterdam port clearance into German processing facilities. Supply concentration centers on Bolivia and Peru for quinoa, China for buckwheat, and domestic Baden-Württemberg cooperatives for organic-certified regional grains. Tariff exposure on processed food imports from non-EU sources threatens margin stability for commodity-dependent formulators. Distribution runs through Netherlands-based health food wholesalers serving DACH-region retail chains with temperature-controlled, allergen-segregated logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's gluten-free sector constitutes a high-growth disruption as enzymatic gluten degradation technology collapses the taste-quality gap between medical-necessity products and mainstream indulgence, with EU Regulation 1169/2011 providing regulatory scaffolding that accelerates consumer trial.
For Market Incumbents: Fortify dedicated production line segregation through capacity expansion in North Rhine-Westphalia's industrial corridor, defending against mid-market bakeries adopting enzymatic systems without facility investment. Prioritize Bioland and Demeter certification lock-in to maintain premium shelf positioning as clean-label compression intensifies purchase decisions. For New Entrants and Emerging Players: Anchor in eastern German rural markets where specialty retail gaps and subscription e-commerce underpenetration create first-mover territory. Target Berlin-Brandenburg's millennial wellness demographic through direct-to-consumer platforms with automated replenishment, leveraging Potsdam logistics infrastructure for last-mile cost efficiency. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors family-owned organic processors with captive supply chains over asset-light digital brands dependent on third-party manufacturing. Acquisition targets should demonstrate dual-certification premiums and regional grain sourcing relationships. The signal to watch is REACH reformulation costs accelerating consolidation pressure among sub-scale domestic manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Scale-Up | Industrial adoption of transglutaminase systems by mid-market bakeries collapses taste-quality barriers without dedicated facility capex. |
| Dual-Certification Portfolio Expansion | Bioland and Demeter verification displaces unverified self-declarations in Bavarian health food cooperative supplier consolidation. |
| E-Commerce Subscription Launch | Direct-to-consumer platforms exploit rural eastern German underpenetration with automated replenishment capturing lifetime value. |
| Backward Integration into Organic Grain Supply | Baden-Württemberg cooperative partnerships secure alternative grain inputs against Bolivian and Peruvian currency volatility. |
| REACH-Compliant Reformulation Program | European Chemicals Agency scrutiny on enzyme carriers drives bio-based processing aid transitions avoiding supply disruption. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at gluten-free specialists, category buyers at German supermarket chains, supply planners at alternative grain importers, and regulatory affairs leads at enzymatic processing technology providers, then refined against secondary validation from EU Regulation 1169/2011 implementation guidance, Federal Office of Consumer Protection and Food Safety audit protocols, Bioland certification standards documentation, and Nielsen retail audit data for German health food channels, with bottom-up volume builds triangulated against top-down category spend estimates.
Variance decomposition across product type, end user channel, packaging format, and distribution method segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators incorporated enzymatic technology adoption curves and EU-wide allergen threshold harmonization scenarios as industry-specific forecast inputs.
Material uncertainties — South American harvest variability, REACH regulatory amendments, and millennial wellness trend persistence — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Low GI Food Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Europe Gluten Free Foods and Beverages Market
Food Intolerance Products
Nut-Free Cookies Market
Food Intolerance Products
Lactose Free Products Market
Food Intolerance Products
Gluten Free Malt Extracts Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
Sugar Free Food and Beverage Market
Food Intolerance Products
Allergen Free Food Products Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Global Gluten-Free Ready Meals Market
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
Citrus-Derived Gastrointestinal Comfort Blends Market
Food Intolerance Products
Lactose-Free Food Market
Food Intolerance Products
Asia-Pacific Gluten-Free Breakfast Cereals Market
Food Intolerance Products
United States Gluten Free Foods and Beverages Market