
 Clarified Rice Syrup Market | 2026-2036
Clarified Rice Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
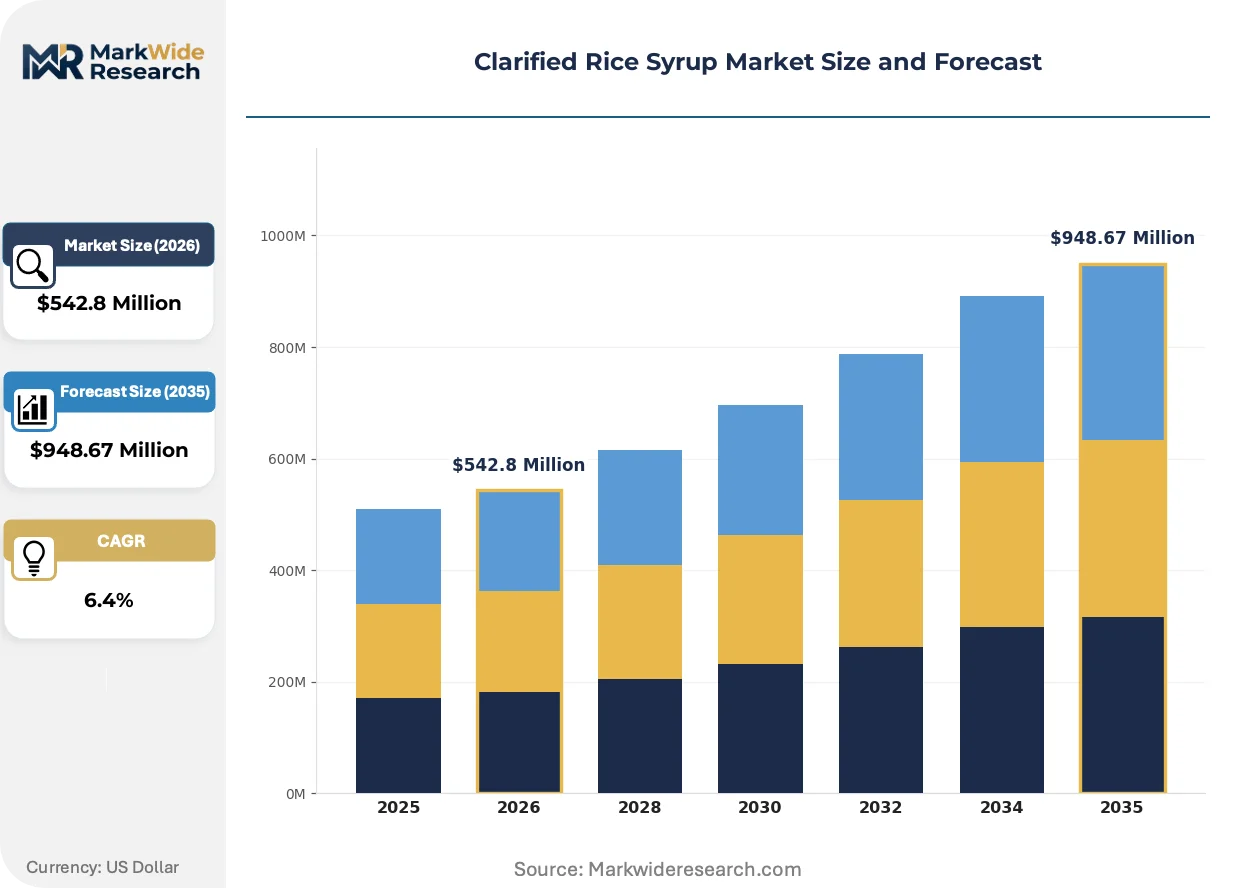
Clarified Rice Syrup Market Outlook
The capital-intensity divergence between integrated rice millers and tolling-dependent blenders is unwinding competitive stability across the clarified rice syrup landscape. Cargill leverages captive wet-milling infrastructure in North America to secure consistent dextrose equivalent specifications for industrial buyers. Gulshan Polyols Ltd. anchors South Asian supply through backward integration into rice starch hydrolysis, while Ciranda differentiates via certified organic and non-GMO product lines targeting premium food service channels.
Clarified rice syrup is a transparent, enzymatically hydrolyzed liquid sweetener derived from rice starch, typically standardized to dextrose equivalent values between 28 and 63 for viscosity and fermentability control in food manufacturing. The organic product type commands disproportionate margin pools as European and North American clean-label mandates tighten additive disclosure requirements. Food and beverages applications dominate volume absorption, though nutritional supplements represent the fastest-growing demand corridor as plant-based protein formulators substitute clarified rice syrup for honey and maltodextrin binders.
EU REACH and the F-Gas Regulation impose purity and processing chemical disclosure thresholds that filter non-compliant Asian exporters from premium European procurement lists. The US FDA and USDA National Organic Program maintain divergent labeling standards that force dual-certification investments for suppliers serving transatlantic accounts. Stakeholders must monitor enzymatic processing patent expirations and carbon intensity scoring methodologies that threaten to reclassify rice-derived sweeteners relative to regenerative-agriculture-certified alternatives.
Market Dynamics
Enzymatic hydrolysis patent cliffs and carbon accounting methodologies are restructuring supplier competitiveness in clarified rice syrup, forcing processors to recertify feedstock provenance or lose premium channel access.
Growth Catalysts
- EU REACH Purity Mandates:Disclosure thresholds for processing chemicals are filtering non-compliant Asian exporters from European procurement lists, creating procurement windows for certified suppliers.
- Clean-Label Confectionery:German manufacturers are expanding clarified rice syrup procurement as a maltose alternative in reduced-additive formulations.
- Plant-Based Protein Binders:Nutritional supplement formulators are substituting clarified rice syrup for honey and maltodextrin in vegan protein products.
Market Restraints
- Input Cost Volatility:Rice starch prices fluctuate with monsoon-dependent harvests in Thailand and India, compressing margin predictability for tolling-dependent blenders.
- Supply Concentration Risk:Integrated processing clusters in Thailand's Chachoengsao province control ASEAN export volumes, creating single-geography vulnerability.
- Substitution Threat:Regenerative-agriculture-certified sweeteners are gaining carbon-intensity preference in European retail channels.
Strategic Opportunities
- USDA Organic Certification:Dual-certification investments for transatlantic accounts open premium pricing tiers in North American natural food channels.
- Carbon Labeling Convergence:ISO 14067-compliant product carbon footprint declarations are creating differentiation vectors for early adopters in EU markets.
- Direct-to-Manufacturer Sourcing:Food service distributors are bypassing traditional ingredient brokers to secure volume commitments from integrated millers.
Industry Challenges
- Enzyme Patent Navigation:Expiring proprietary amylase licenses are triggering litigation risk around process-intellectual property in Asian production facilities.
- Dual-Certification Timelines:USDA National Organic Program and EU organic equivalence negotiations are extending compliance timelines for export-oriented processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clarified Rice Syrup Market |
| Market Size in 2026 | $542.8 Million |
| Market Size in 2035 | $948.67 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Non-GMO, Gluten-Free Application: Food & Beverages, Bakery Products, Nutritional Supplements, Confectionery End User: Manufacturers, Retailers, Food Service, Consumers Packaging Type: Bottles, Tetra Packs, Bulk Containers, Sachets |
| Companies Covered | Ciranda, Matco Foods, Wuhu Deli Foods Co., Ltd., Axiom Foods, California Natural Products, Cargill, Archer-Daniels-Midland Company, Gulshan Polyols Ltd., Suzanne’s Specialties, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clarified Rice Syrup Market Strategic Shifts
Continuous enzymatic processing and carbon accounting integration are redefining operational benchmarks, while procurement centralization among multinational food manufacturers compresses supplier margins.
Membrane filtration systems optimized for rice starch hydrolysis are displacing traditional acid-hydrolysis methods in new capacity installations. Mid-scale processors in Vietnam and Indonesia are adopting these systems to meet EU F-Gas Regulation solvent-recovery standards. The technology is displacing legacy equipment orders and reshaping capital allocation toward water-recovery integration.
F-Gas Regulation amendments tightening solvent disclosure for imported feedstocks are forcing Asian exporters to retrofit processing lines or exit premium European channels. Industrial buyers in Germany and France now require third-party verification of hydrolysis chemistry. Organic-certified suppliers are absorbing compliance costs faster than conventional competitors.
Consolidated procurement by multinational confectionery and beverage manufacturers is compressing supplier negotiation leverage. Direct sourcing contracts with integrated Thai millers are displacing spot-market purchases through Singapore trading houses. This pattern concentrates most visibly in North American clean-label brands seeking supply security.
Clarified Rice Syrup Market Segmentation
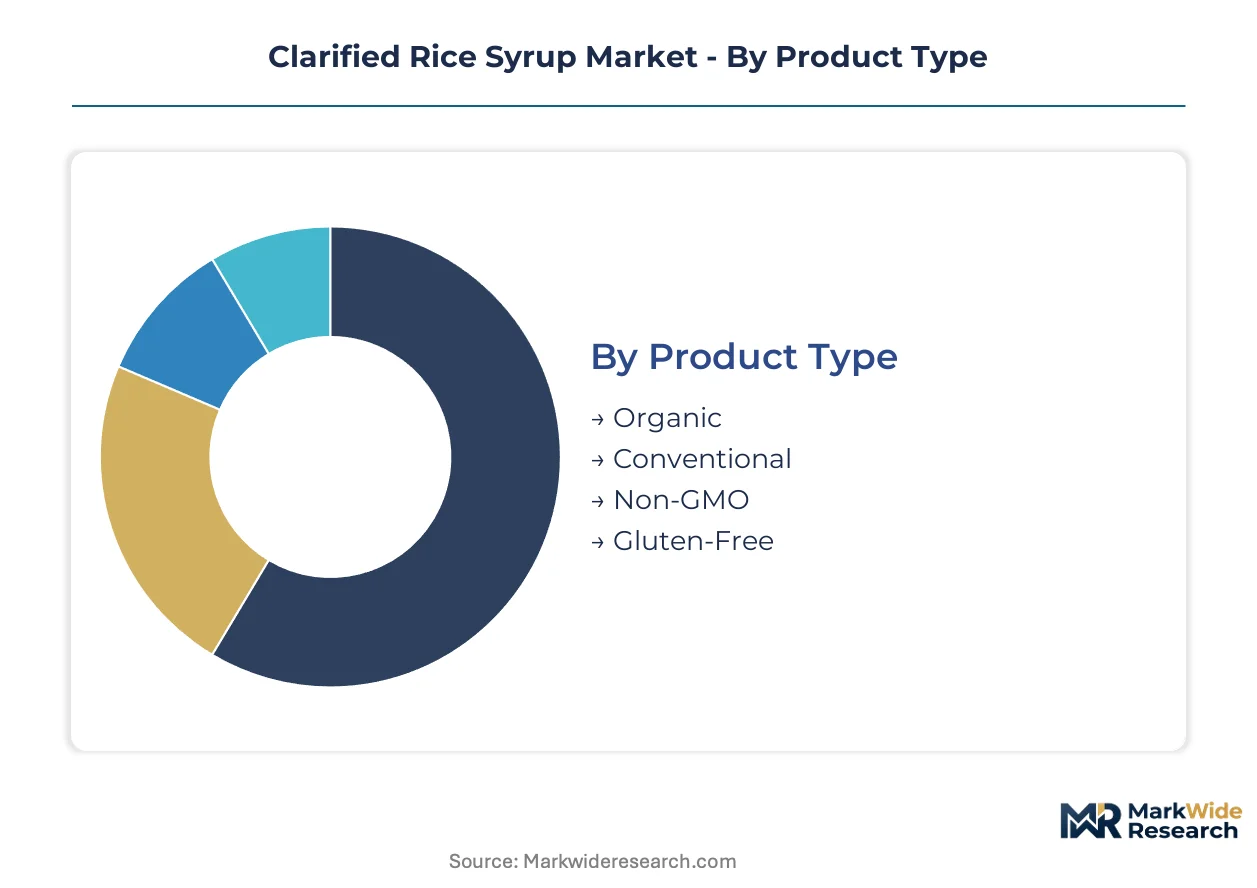
Segmentation in clarified rice syrup reveals how certification tiers and application specifications split procurement budgets across divergent supply chain configurations. Buyers in premium channels prioritize organic and non-GMO credentials that command sourcing premiums, while industrial formulators optimize around viscosity specifications and bulk delivery economics.
Product Type:
Organic and non-GMO variants draw disproportionate investment from export-oriented processors seeking EU and North American market access, while conventional grades dominate domestic Southeast Asian absorption.
- Organic:Certified under USDA National Organic Program and EU organic equivalence standards, commanding dual-certification investments from Thai and Vietnamese millers. German confectionery manufacturers and US natural food brands concentrate procurement here, driven by clean-label disclosure mandates that filter uncertified competitors from premium lists.
- Conventional:Standard enzymatic hydrolysis without organic feedstock provenance, serving price-sensitive industrial buyers in ASEAN domestic markets and bulk food service channels. Margin compression is acute as rice starch input costs fluctuate with monsoon-dependent harvests.
- Non-GMO:Identity-preserved rice starch sourcing with third-party verification, bridging conventional pricing and organic premiums. North American plant-based protein formulators favor this tier for vegan binder applications.
- Gluten-Free:Processed in dedicated facilities to eliminate cross-contamination, targeting celiac-safe confectionery and bakery niches in Australia and Canada.
Conventional clarified rice syrup commands the established base. The steepest expansion runs through organic certification tiers.
Application:
Volume concentration varies sharply by end-use sophistication, with nutritional supplements absorbing capacity at margin premiums while food and beverages anchor throughput scale.
- Food & Beverages:Standardized dextrose equivalent syrups for beverage formulation and sauce applications, with procurement centralizing among multinational manufacturers seeking direct miller contracts. Thai integrated processors in Chachoengsao province dominate supply security for this segment.
- Nutritional Supplements:Low-DE clarified rice syrup serves as vegan binder replacing honey and maltodextrin in plant-based protein powders. European and North American formulators are expanding procurement fastest, though absolute volumes remain below food and beverages.
- Bakery Products:Humectant and browning agent functions in clean-label bread and pastry applications, with German and French industrial bakeries driving specification tightening.
- Confectionery:Maltose alternative in reduced-additive candy and chocolate formulations, where EU REACH purity mandates filter non-compliant Asian exporters from procurement lists.
Food and beverages anchors volume absorption. Nutritional supplements are climbing the fastest as protein formulation demand accelerates.
End User:
Procurement leverage concentrates with manufacturers consolidating direct sourcing relationships, while food service and retail channels fragment across distributor tiers.
- Manufacturers:Industrial formulators with specification control over dextrose equivalent and viscosity parameters, bypassing brokers to secure volume commitments from integrated Thai millers.
- Food Service:Restaurant chains and catering operations purchasing standardized grades through regional distributors, with limited specification influence.
- Retailers:Private-label organic and non-GMO bottling for natural food channels, absorbing compliance costs faster than conventional competitors.
- Consumers:Direct-to-consumer sachet and small-format sales, marginal to industrial volumes but relevant for brand awareness in premium Asian markets.
Manufacturers hold pricing power through consolidated procurement. Food service is gaining share fastest as clean-label menu expansion accelerates.
Packaging Type:
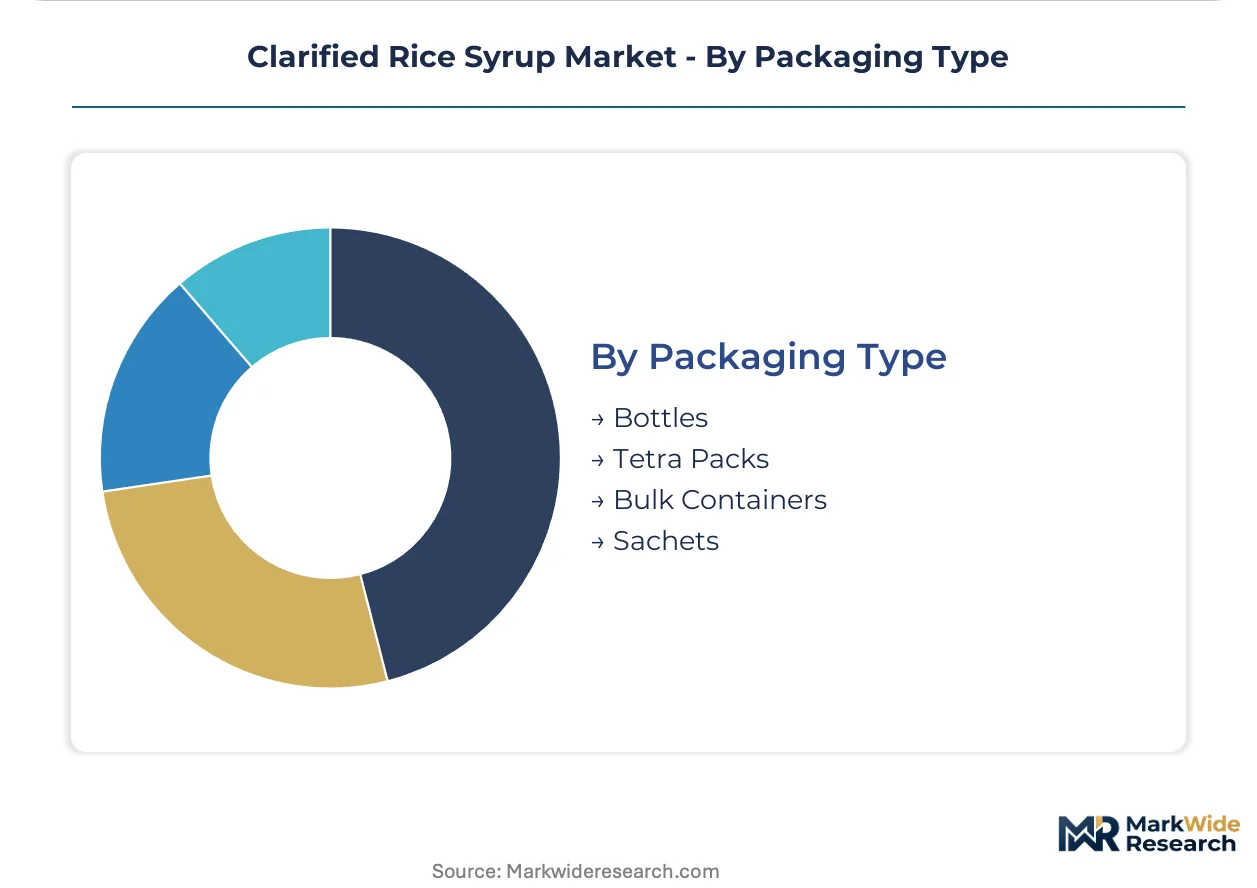
Format selection tracks supply chain distance and contamination risk, with bulk configurations dominating intercontinental trade and retail formats multiplying near consumption points.
- Bulk Containers:Intermediate bulk containers and tanker shipments for industrial manufacturers, minimizing unit logistics costs on Thailand-to-Europe and Vietnam-to-North America lanes.
- Bottles:Retail-ready packaging for natural food store distribution, with label real estate consumed by organic and non-GMO certification marks.
- Tetra Packs:Aseptic filling for extended shelf-life applications in food service and institutional channels.
- Sachets:Single-serve portions for hospitality and airline catering, plus emerging direct-to-consumer trial formats in Asian e-commerce.
Bulk containers dominate export economics. Bottles are expanding most quickly as retail clean-label penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Southeast Asia exhibit acute price sensitivity to rice starch input costs, while European and North American purchasers absorb certification premiums for organic and non-GMO grades with minimal demand elasticity.
Thailand
Integrated rice starch-to-syrup processing clusters in Chachoengsao province supply ASEAN export channels and European clean-label manufacturers. Thai processors navigate EU F-Gas Regulation amendments by retrofitting solvent-recovery systems. Bangkok-based millers dominate bulk procurement contracts with multinational confectionery accounts.
Germany
German confectionery manufacturers expand clarified rice syrup procurement as a maltose alternative in reduced-additive formulations. ECHA REACH compliance mandates filter non-compliant Asian exporters from premium procurement lists. Industrial buyers in Hamburg and Frankfurt now require third-party verification of hydrolysis chemistry for all imported feedstocks.
United States
USDA National Organic Program standards diverge from EU equivalence protocols, forcing dual-certification investments from export-oriented Thai and Vietnamese millers. California natural food brands and Midwest plant-based protein formulators drive specification tightening for low-DE vegan binders. Chicago and Los Angeles distribution hubs concentrate spot-market purchasing power.
Vietnam
Mid-scale processors adopt membrane filtration systems to meet EU solvent-recovery standards and displace legacy acid-hydrolysis capacity. Vietnam's rice belt millers face margin compression from monsoon-dependent harvest volatility. Ho Chi Minh City trading houses lose volume to direct sourcing contracts between integrated millers and North American clean-label brands.
India
Gulshan Polyols Ltd. anchors South Asian supply through backward integration into rice starch hydrolysis, insulating operations from tolling-dependent blender instability. FSSAI labeling requirements and DGFT export protocols shape certification investments for European market access. Maharashtra and Gujarat processing facilities serve domestic bakery and confectionery channels.
Clarified Rice Syrup Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated rice millers commanding feedstock security and tolling-dependent blenders competing on batch flexibility. The vendor base splits between multinational agribusiness conglomerates with captive wet-milling infrastructure and regional specialists with organic and non-GMO certification depth. Three archetypes dominate: integrated starch-to-syrup processors, certified organic specialists, and tolling-dependent blenders. Competitive moves concentrate on direct-to-manufacturer sourcing contracts and dual-certification investments for transatlantic market access.
Among North American agribusiness conglomerates, Cargill and Archer-Daniels-Midland Company occupy positions defined by captive wet-milling infrastructure and consistent dextrose equivalent specifications. Gulshan Polyols Ltd. represents the integrated regional processor archetype with backward control over rice starch supply. Ciranda exemplifies the certified organic specialist tier targeting premium food service channels through non-GMO and organic product lines.
| Leading Market Players |
|---|
| Ciranda |
| Matco Foods |
| Wuhu Deli Foods Co., Ltd. |
| Axiom Foods |
| California Natural Products |
| Cargill |
| Archer-Daniels-Midland Company |
| Gulshan Polyols Ltd. |
| Suzanne's Specialties |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Thai integrated millers and German confectionery manufacturers lock in supply access and price visibility, insulating procurement teams from monsoon-driven rice starch volatility while compressing spot-market liquidity for tolling-dependent blenders.
Pricing Analysis
Certification tier premiums drive lifetime value, with USDA Organic and EU equivalence dual-certification commanding substantial sourcing premiums from North American natural food brands. Three-tier pricing structure across organic, non-GMO, and conventional grades reflects compliance cost absorption rather than input differentials alone. Cost compression in conventional grades is intensifying because tolling-dependent Vietnamese processors face margin squeeze from Bangkok-based integrated competitors. Industrial manufacturers exhibit lowest price sensitivity, while ASEAN domestic food service channels absorb spot-market fluctuations with minimal specification leverage.
Supply Chain Analysis
Thailand and Vietnam anchor clarified rice syrup production, with Chachoengsao province clusters supplying ASEAN export channels and Ho Chi Minh City processors retrofitting membrane filtration for EU F-Gas compliance. Feedstock draws from monsoon-dependent rice starch harvests across Thailand's central plains and Vietnam's Mekong Delta. Single-geography concentration in Chachoengsao creates vulnerability to climate-induced harvest disruption. Distribution runs through direct miller-manufacturer contracts displacing Singapore trading houses, with bulk tanker shipments dominating Thailand-to-Europe lanes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation amendments and enzymatic hydrolysis patent cliffs are restructuring supplier competitiveness, creating acquisition windows for processors with certified carbon accounting and solvent-recovery infrastructure.
For Market Incumbents: Compound backward integration into rice starch supply to defend against regenerative-agriculture-certified sweetener substitution threatening premium European channels. Accelerate ISO 14067-compliant carbon footprint declarations to capture early-mover differentiation in German and French procurement lists. Prioritize dual-certification investments before USDA-EU organic equivalence negotiations conclude. For New Entrants and Emerging Players: USDA Organic certification fast-tracks access to California natural food brands and Midwest plant-based protein formulators seeking low-DE vegan binders. Target nutritional supplements as the fastest-growing demand corridor with minimal incumbent certification depth. Pursue direct-to-manufacturer sourcing contracts bypassing established Singapore trading houses. For Investors and Strategic Acquirers: Capital is best deployed toward integrated starch-to-syrup processors with captive wet-milling infrastructure and existing EU REACH compliance. Long-term viability favors archetypes with proven solvent-recovery retrofit execution and established relationships with multinational confectionery accounts. Monitor carbon intensity scoring methodology revisions as the critical inflection signal for rice-derived sweetener reclassification risk.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | USDA Organic and EU equivalence unlocks premium pricing tiers in transatlantic natural food channels. |
| Membrane Filtration Retrofit | F-Gas Regulation compliance preserves European market access for Thai and Vietnamese processors. |
| Direct Sourcing Contracts | Bypassing Singapore trading houses secures volume commitments from integrated Chachoengsao millers. |
| Carbon Footprint Certification | ISO 14067 declarations create differentiation vectors in German and French procurement specifications. |
| Backward Integration | Captive rice starch supply insulates margins from monsoon-dependent harvest volatility. |
Study Parameters
The analysis maps organic certification tiers, enzymatic processing technologies, and application-specific viscosity grades, each validated through procurement managers at multinational confectionery manufacturers, technical directors at Thai integrated millers, regulatory affairs leads at Vietnamese processors, and sustainability officers at North American natural food brands. Primary interview findings were cross-checked against ECHA REACH compliance databases, USDA National Organic Program certification registries, EU F-Gas Regulation amendment filings, and ASEAN customs trade statistics. Bottom-up capacity assessments and top-down demand absorption estimates were reconciled through iterative triangulation.
Consistency checks validated volume and value outputs against external benchmarks including industry association production surveys and regional agricultural harvest data. Segmentation modeling incorporated product type, application end-use, certification grade, and geographic production cluster dimensions across the projection horizon. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking specification tightening trajectories, with enzymatic processing patent expiration schedules and carbon accounting methodology adoption curves serving as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EU REACH enforcement and stable USDA-EU organic equivalence protocols; material deviation in regulatory alignment or climate-induced harvest disruption would warrant model refresh. Recalibration cycles align with material shifts in F-Gas Regulation amendments, carbon intensity scoring standardization, and patent cliff litigation outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
North America Low-Calorie Sweeteners Market
Sweeteners
Spain Food Sweetener Market
Sweeteners
Asia-Pacific Sugar Substitute Market
Sweeteners
Gluten-Free Sugar Syrup Market
Sweeteners
Asia-Pacific Cane Sugar Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
Europe Starch Sweetener Market
Sweeteners
Asia-Pacific Plant-Derived and Synthetic Sugar Market
Sweeteners
Sanding Sugar Market
Sweeteners
D-Mannose Market
Sweeteners
Methyl Glucose Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
North America Sugar Substitutes Market
Sweeteners
Polyphenol Sweetener Market
Sweeteners
D Psicose Market
Sweeteners
Sugar Beet Juice Extract Market