
 Global Joint Replacement Device Market | 2026-2036
Global Joint Replacement Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Joint Replacement Device Market Intelligence
The shift of procedures towards Ambulatory Surgery Centers is redrawing the competitive landscape for device manufacturers. Stryker Corporation leverages its extensive portfolio of robotic-assisted surgery systems to secure contracts with high-volume centers. Zimmer Biomet Holdings sustains its market position through strong relationships with orthopedic surgeons and investments in digital health platforms. Johnson & Johnson MedTech competes by offering a broad range of implants across different price points to cater to diverse hospital procurement strategies.
A joint replacement device is an implantable medical prosthesis designed to substitute a damaged or arthritic joint. These devices are fabricated from biocompatible materials such as cobalt chromium or titanium alloys, engineered for long-term durability. Their primary function is to restore joint mobility and alleviate pain. Knee implants constitute the largest product segment, driven by high osteoarthritis prevalence, while hip implants represent a mature category with continuous material innovation.
Regulatory pathways significantly influence market access, with the US FDA's 510(k) clearance and Europe's Medical Device Regulation (MDR) setting stringent requirements. These frameworks mandate extensive clinical data on biocompatibility and long-term performance, governing product commercialization. China's NMPA also presents a critical approval hurdle for market entry. Stakeholders must now focus on navigating evolving reimbursement models while adapting portfolios for cost-sensitive economies.
Market Dynamics
The primary force shaping the market is the dual pressure of advancing procedural technology, such as robotics and 3D printing, against intensified cost-containment initiatives from public and private payers globally.
Growth Catalysts
- Patient-Specific Instrumentation:The application of 3D printing to create custom surgical guides and trial implants improves surgical accuracy and reduces operating time, accelerating adoption by orthopedic surgeons.
- Aging Demographics:Expanding elderly populations and rising osteoarthritis prevalence in countries like Japan and China create a sustained, non-discretionary demand base for knee and hip replacement procedures.
- Outpatient Procedure Shift:The migration of joint replacement surgeries to Ambulatory Surgery Centers (ASCs) expands patient access and lowers overall healthcare system costs, particularly in the United States.
Market Restraints
- Biomaterial Cost Volatility:The high and fluctuating costs of medical-grade cobalt chromium and titanium alloys, essential for implant fabrication, exert persistent pressure on manufacturer gross margins.
- Stringent Regulatory Hurdles:Europe's Medical Device Regulation (MDR) imposes extensive clinical evidence requirements and longer review timelines, creating significant barriers to market entry for new devices.
- Non-Surgical Alternatives:Advances in regenerative medicine, viscosupplementation, and targeted physical therapy present a growing substitution threat for patients with early-stage joint degradation, delaying or preventing surgery.
Strategic Opportunities
- Emerging Market Penetration:Healthcare infrastructure development in Brazil and Mexico creates opportunities for market entry, though navigating regulatory bodies like ANVISA requires localized expertise.
- Smart Implant Integration:The convergence of sensor technology with implants offers a new frontier for post-operative monitoring, enabling remote data collection on patient mobility and implant stress.
- Digital Health Platforms:Developing proprietary software platforms for pre-surgical planning and post-operative patient engagement creates new revenue streams and strengthens relationships with hospital systems.
Industry Challenges
- Robotics Training Gap:A shortage of surgeons and operating room staff proficient in using robotic-assisted surgical systems limits the broader adoption of this capital-intensive technology.
- Data Interoperability:Integrating data from smart implants and digital health platforms with fragmented and often proprietary hospital Electronic Health Record (EHR) systems remains a significant technical hurdle.
- Reimbursement Model Complexity:Navigating disparate and evolving reimbursement policies for outpatient procedures across different geographies complicates financial planning and market access strategies for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Joint Replacement Device Market |
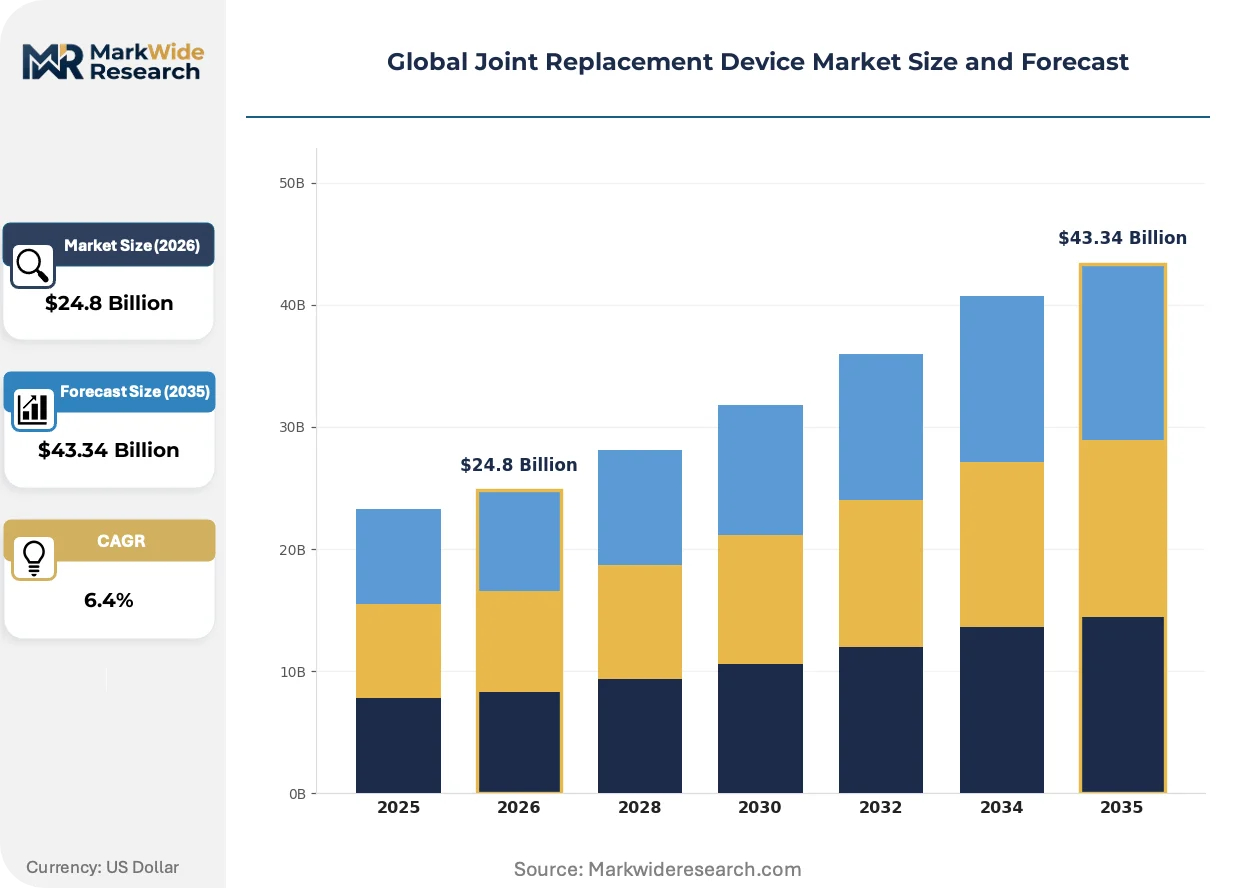
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knee Implants, Hip Implants, Shoulder Implants, Elbow Implants, Ankle Implants Material: Cobalt Chromium, Titanium Alloy, Stainless Steel, Polyethylene, Ceramic Application: Osteoarthritis, Rheumatoid Arthritis, Traumatic Injury, Avascular Necrosis, Bone Tumors End User: Orthopedic Clinics, Ambulatory Surgery Centers, Specialized Centers, Rehabilitation Facilities |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, Johnson & Johnson MedTech, Smith & Nephew, B. Braun, Medtronic, MicroPort Scientific Corporation, Arthrex, CONMED Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Joint Replacement Device Market Strategic Shifts & Innovations
The convergence of digital health technologies with traditional orthopedic implants is creating a new paradigm focused on data-driven surgical outcomes and personalized patient recovery pathways, moving beyond the device itself.
Sensor-enabled smart implants collect real-time data on joint articulation, load, and patient activity. High-volume academic medical centers are the primary early adopters for complex revision cases. The integration of microelectronics into prostheses is miniaturizing the feedback loop between patient recovery and clinical intervention, enabling proactive care.
China’s volume-based procurement (VBP) programs are altering the competitive dynamics for medical devices. These policies compel manufacturers to offer steep price reductions for guaranteed sales volume within public hospitals. The knee and hip implant categories are particularly affected, forcing a strategic pivot toward premium private markets or portfolio simplification.
A shift toward value analysis committees within hospitals is changing purchasing criteria for joint replacement devices. This model disrupts the traditional sales channel focused on surgeon preference, elevating administrators who prioritize total episode-of-care costs. The trend is most visible in large Integrated Delivery Networks (IDNs) across the United States.
Global Joint Replacement Device Market Segmentation
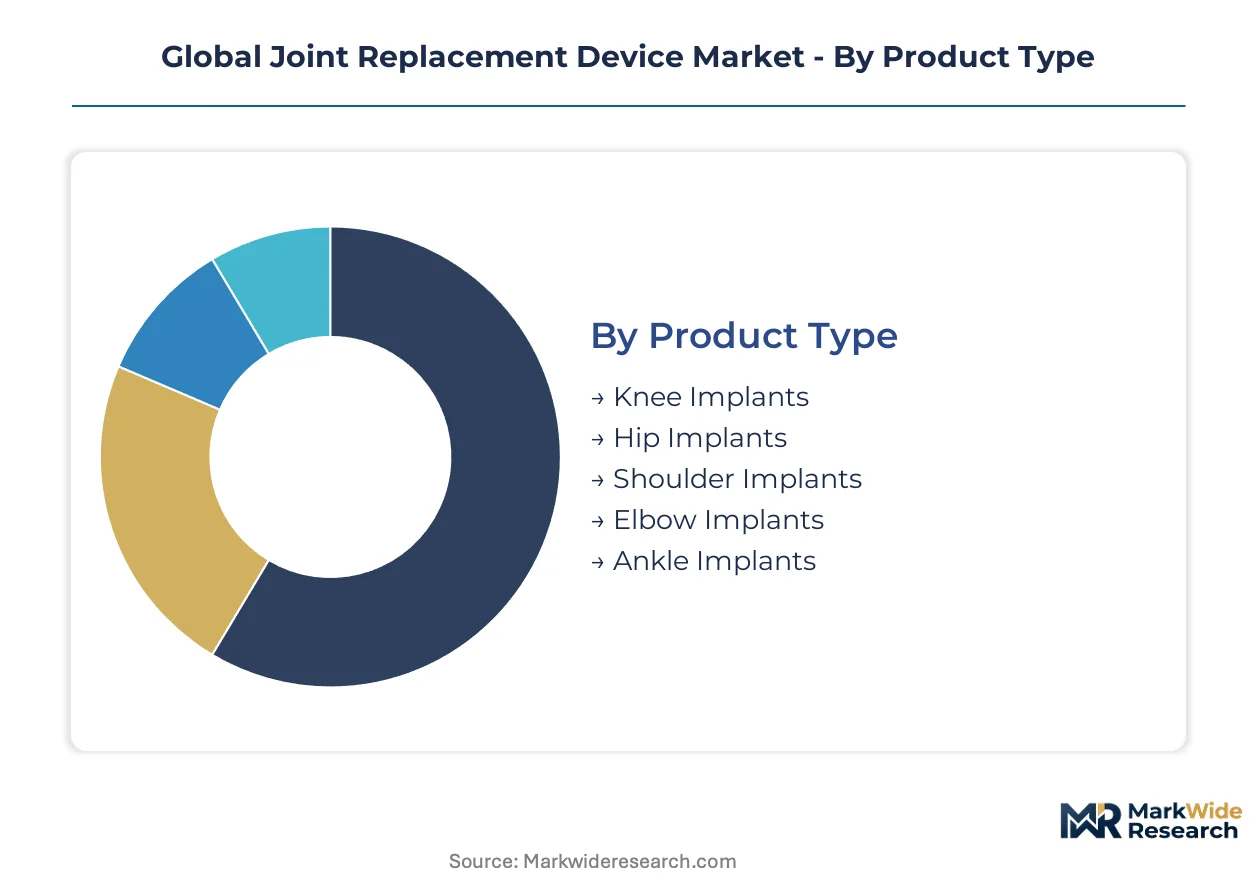
The Global Joint Replacement Device Market segmentation offers a detailed view of product evolution, material science advancements, and diverse end-user adoption patterns. This understanding is essential for manufacturers to tailor innovation, navigate regulatory landscapes, and optimize market entry strategies across different healthcare systems.
Product Type:
Regulatory bodies like the US FDA and Europe's MDR categorize joint replacement devices by anatomical application, influencing clinical trial requirements and post-market surveillance protocols.
- Knee Implants:These prostheses replace damaged knee joints, often due to osteoarthritis. Demand concentrates in countries with aging demographics like Japan and China, driven by high disease prevalence and expanding healthcare access.
- Hip Implants:Designed to restore hip joint function, these devices feature continuous material innovation for improved longevity. Their market presence is mature across developed economies, with significant adoption in the United States due to established practices.
- Shoulder Implants:These devices address severe shoulder arthritis or complex fractures, restoring mobility and reducing pain.
- Elbow Implants:Utilized for severe elbow arthritis or post-traumatic reconstruction, these implants improve joint articulation.
- Ankle Implants:These prostheses replace damaged ankle joints, offering an alternative to traditional fusion procedures.
Established volume favors Knee Implants; emerging adoption favors Ankle Implants.
Material:
Material selection for joint replacement devices impacts biocompatibility, durability, and manufacturing costs, directly influencing procurement strategies for hospital systems.
- Cobalt Chromium:This alloy provides excellent wear resistance and mechanical strength, common for articulating surfaces. Its high cost volatility, however, pressures manufacturer gross margins globally.
- Titanium Alloy:Known for superior biocompatibility and osseointegration, titanium alloy is widely used for implant stems and porous coatings. Demand is high in Europe, driven by stringent performance requirements.
- Stainless Steel:This material offers a cost-effective solution for certain components, particularly in less load-bearing applications.
- Polyethylene:Ultra-high molecular weight polyethylene (UHMWPE) serves as a bearing surface in many implants due to its low friction.
- Ceramic:Ceramic materials provide exceptional hardness and wear resistance, often employed in hip implant bearings to minimize particle generation.
The market prioritizes Cobalt Chromium for durability, while Polyethylene offers flexibility for specific applications.
Application:
The underlying medical condition necessitating joint replacement surgery dictates specific device requirements and influences patient demographics across global regions.
- Osteoarthritis:This degenerative joint disease is the primary indication for knee and hip replacement, driving sustained demand. Its prevalence is high among aging populations in countries like Germany and the United States.
- Traumatic Injury:Accidents and acute injuries often result in severe joint damage requiring surgical intervention. This critical application area sees consistent global demand due to unpredictable incidents.
- Rheumatoid Arthritis:This autoimmune inflammatory disease leads to joint destruction, necessitating replacement surgeries for pain relief.
- Avascular Necrosis:This condition, involving bone tissue death, often requires joint replacement, particularly in the hip.
- Bone Tumors:Resection of bone tumors can necessitate complex joint replacement to reconstruct the affected limb and restore function.
Demand for joint replacement devices is predominantly driven by Osteoarthritis, with Traumatic Injury representing a significant patient cohort.
End User:
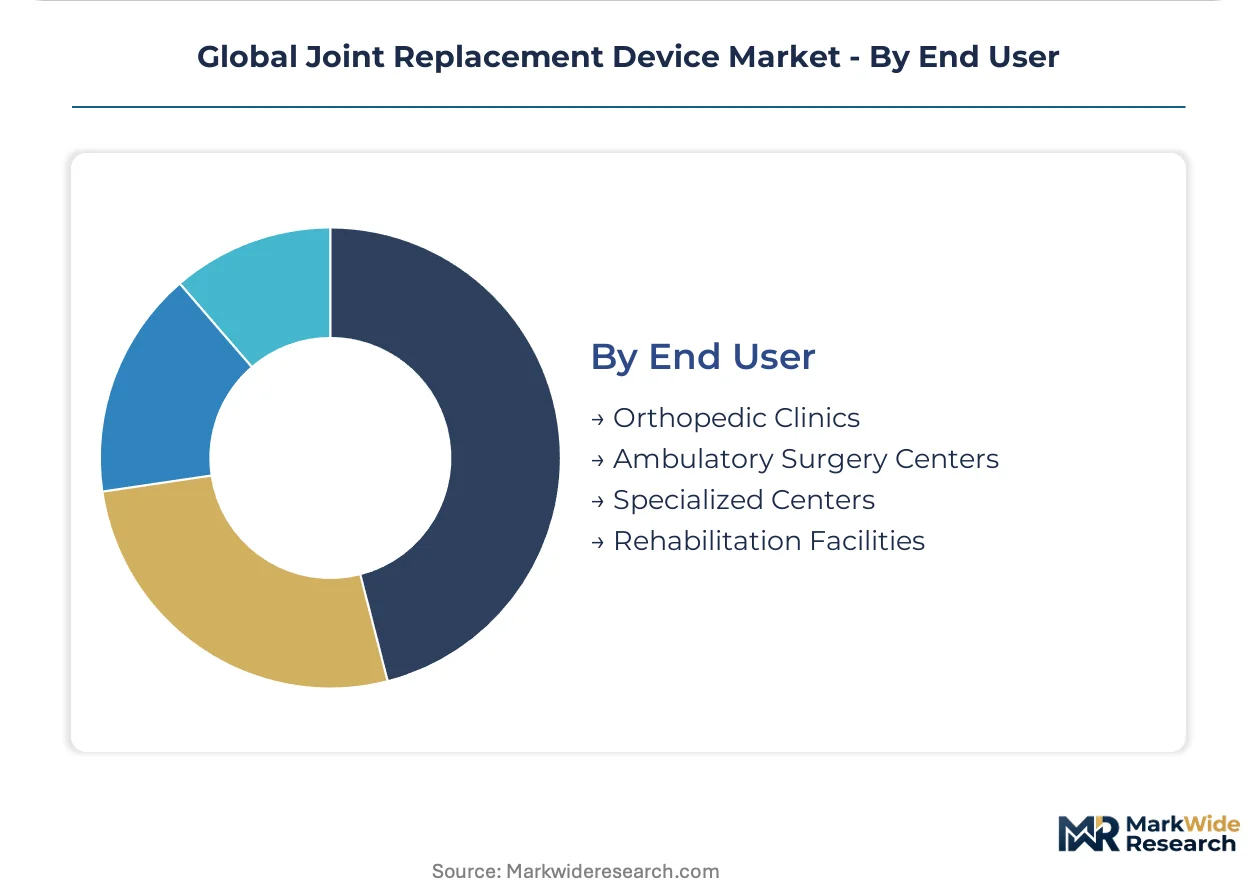
Evolving healthcare delivery models impact where joint replacement procedures are performed, influencing procurement channels and service offerings from device manufacturers.
- Orthopedic Clinics:These facilities serve as primary points of contact for diagnosis, pre-surgical planning, and post-operative follow-up. They maintain strong relationships with orthopedic surgeons.
- Ambulatory Surgery Centers:ASCs increasingly perform outpatient joint replacement procedures, driven by cost-containment and improved recovery. Their growing adoption in the United States reshapes device distribution.
- Specialized Centers:These facilities focus on complex revision surgeries or specific joint types, requiring specialized devices and expertise.
- Rehabilitation Facilities:Crucial for post-operative recovery, these centers influence patient outcomes and device performance perception.
Ambulatory Surgery Centers are gaining procedural volume, while Orthopedic Clinics maintain their foundational role in patient care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetype concentration is evident in regions with expanding elderly populations and developing healthcare infrastructure, driving consistent demand for joint replacement devices. Countries like China and Japan face significant osteoarthritis prevalence, requiring sustained surgical intervention. This demographic shift, combined with evolving healthcare delivery models, reshapes market dynamics across diverse economies.
United States
Demand for joint replacement procedures remains robust, driven by an aging population and high osteoarthritis rates. The US FDA's 510(k) clearance process governs market access for new devices, requiring extensive clinical data. Ambulatory Surgery Centers in major metropolitan areas like Dallas and Atlanta are increasingly performing outpatient joint replacements, altering traditional hospital procurement.
China
Expanding healthcare infrastructure and a rapidly aging demographic fuel significant demand for knee and hip implants. China's NMPA sets critical approval hurdles for market entry, ensuring product safety and efficacy. Volume-based procurement (VBP) programs in cities like Shanghai and Beijing are compelling manufacturers to reduce prices for guaranteed sales volumes.
Germany
High osteoarthritis prevalence among the elderly population sustains demand for joint replacement devices. Europe's Medical Device Regulation (MDR) imposes stringent clinical evidence requirements, influencing product commercialization. Specialized orthopedic centers in regions like Bavaria and North Rhine-Westphalia focus on complex revision surgeries and advanced implant technologies.
Japan
An exceptionally aging population and high rates of osteoarthritis create a non-discretionary demand base for joint replacement procedures. Japan's PMDA regulates medical device approvals, emphasizing long-term performance and patient safety. Academic medical centers in Tokyo and Osaka are primary early adopters for sensor-enabled smart implants and complex revision cases.
Brazil
Healthcare infrastructure development and a growing middle class are expanding access to joint replacement surgeries. ANVISA, Brazil's regulatory body, requires localized expertise for market entry and product registration. Orthopedic clinics in São Paulo and Rio de Janeiro are key points of contact for diagnosis and post-operative follow-up.
Global Joint Replacement Device Market Key Industry Players
Player mix skews toward large, diversified medical technology companies that leverage extensive product portfolios and established relationships. The market exhibits a tiered structure, with global leaders, specialized innovators, and regional players competing across different price points. Dominant competitive moves include strategic investments in digital health platforms and the acquisition of advanced robotic-assisted surgery technologies.
Within the diversified medical technology archetype, Stryker Corporation, Zimmer Biomet Holdings, and Johnson & Johnson MedTech exemplify market leadership. Stryker Corporation occupies a strong position through its extensive portfolio of robotic-assisted surgery systems. Zimmer Biomet Holdings sustains its market presence through robust relationships with orthopedic surgeons and investments in digital health. Johnson & Johnson MedTech anchors its competitive strategy by offering a broad range of implants across different price points.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings |
| Johnson & Johnson MedTech |
| Smith & Nephew |
| B. Braun |
| Medtronic |
| MicroPort Scientific Corporation |
| Arthrex |
| CONMED Corporation |
| Others |
Cost & Logistics Intelligence
Volume-based procurement (VBP) programs, particularly in China, lock in both supply access for public hospitals and predictable, albeit reduced, pricing for manufacturers. This contract structure significantly influences global pricing strategies and supply chain configurations for joint replacement devices, driving a strategic pivot towards premium segments or localized production.
Pricing Analysis
Cost-plus contracts, often indexed to raw material prices, govern a portion of device procurement, especially for specialized components. Pricing stratifies across premium, standard, and economy tiers based on implant material, surgical complexity, and brand reputation. Pricing pressure stems from global cost-containment initiatives and volume-based procurement programs in countries like China, impacting manufacturer gross margins. Public hospital systems in VBP regions exhibit the highest price sensitivity, while specialized orthopedic centers prioritize advanced technology and clinical outcomes.
Supply Chain Analysis
Access to medical-grade cobalt chromium and titanium alloys, primarily sourced from global mining and processing hubs, underpins implant fabrication. Key manufacturing concentrations for finished devices exist in the United States, Germany, and China. Raw material cost volatility and stringent regulatory compliance for biocompatible materials represent a significant structural risk for device manufacturers. Distribution runs through a hybrid model combining direct sales forces for large hospital systems and specialized distributors for smaller clinics and Ambulatory Surgery Centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a service-attach opportunity, with digital health platforms and post-operative monitoring solutions expanding faster than the underlying hardware sales.
For Market Incumbents:
Consolidate market share by leveraging extensive robotic-assisted surgery system portfolios and deepening relationships with high-volume Ambulatory Surgery Centers. Invest in advanced R&D for patient-specific instrumentation to counter the threat of non-surgical alternatives. Establish robust regulatory expertise to navigate evolving frameworks like Europe's MDR and China's NMPA, protecting market access. Expand digital health platform offerings to create recurring revenue streams and strengthen hospital system partnerships.
For New Entrants and Emerging Players:
Differentiate on specialized solutions for underserved anatomical segments like ankle implants, or focus on advanced material science for improved longevity. Penetrate emerging markets such as Brazil and Mexico by offering cost-effective solutions tailored to local healthcare infrastructure. Develop proprietary software for pre-surgical planning or post-operative patient engagement as a unique go-to-market angle. Target specialized centers seeking innovative smart implant technologies for complex revision cases.
For Investors and Strategic Acquirers:
Specialized innovators in smart implant technology and digital health platforms represent attractive acquisition targets for long-term growth. The market offers sustained demand due to aging demographics and persistent osteoarthritis prevalence, ensuring fundamental stability. Monitor the successful integration of digital health solutions with fragmented hospital Electronic Health Record systems as a key inflection indicator. Evaluate companies with strong intellectual property in patient-specific instrumentation or biomaterial advancements.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Robotic-Assisted Surgery Portfolio | Stryker Corporation strengthens its competitive position by offering advanced surgical precision and efficiency to high-volume centers. |
| Invest in Digital Health Platforms | Zimmer Biomet Holdings enhances surgeon relationships and generates new revenue streams through integrated patient care solutions. |
| Develop Patient-Specific Instrumentation | Improved surgical accuracy and reduced operating time accelerate adoption among orthopedic surgeons. |
| Strengthen Emerging Market Presence | Penetration into Brazil and Mexico addresses unmet demand and diversifies revenue away from mature economies. |
| Integrate Smart Implant Technology | Real-time data on patient mobility and implant stress enables proactive clinical intervention and personalized recovery pathways. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews to gather qualitative insights and validate quantitative findings. Interviews engaged orthopedic surgeons, hospital procurement managers, device manufacturers' R&D leads, and regulatory affairs specialists. Secondary validation drew from US FDA 510(k) filings, Europe MDR guidance documents, NMPA approval databases, and medical journal articles on osteoarthritis prevalence, triangulating data for accuracy.
The forecast framework applies a robust analytical approach across the projection horizon, modeling segmentation dimensions including product type, material, application, end user, and regional regulatory environments. Compound Annual Growth Rates (CAGRs) were derived from a synthesis of historical market trends and projected future dynamics. Key industry-specific forecast inputs included global osteoarthritis prevalence rates and evolving healthcare expenditure trends across different economies.
The analysis sits within stated boundaries; outcomes outside biomaterial cost stability or consistent reimbursement models would require recalibration. Forecasts reflect documented assumptions regarding technological advancements and regulatory pathways. Practitioners should keep alternative scenarios live as evolving reimbursement policies and geopolitical trade dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Smart Contact Lenses Market
Medical Devices
Robotics-Assisted Telesurgery Market
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
3D Surgical Microscope Systems Market
Medical Devices
Implantable Cardiac Rhythm Management Device Market
Medical Devices
Smart Pills Drug Delivery Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Enteral Feeding Devices Market
Medical Devices
Occlusion Balloon Catheter Market
Medical Devices
Interventional Spine Devices Market
Medical Devices
Global Neurovascular Guidewires Market
Medical Devices
Mandibular Advancement Devices Market
Medical Devices
Heated Humidifiers Market
Medical Devices
Global Vitreoretinal Surgery Devices Market
Medical Devices
Manometry System Market
Medical Devices
Arthroscopy Devices Market