
 Global Vitreoretinal Surgery Devices Market | 2026-2036
Global Vitreoretinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vitreoretinal Surgery Devices Market Foresight
Ambulatory surgical facilities are rotating toward higher-acuity vitreoretinal cases, displacing traditional hospital-only models for macular hole and epiretinal membrane repairs. Alcon leverages its integrated vitrectomy platform to dominate high-volume surgical centers across North America. Bausch & Lomb sustains competitive positioning through specialized fluid infusion systems that anchor its presence in European eye hospitals. Carl Zeiss Meditec differentiates via optical coherence tomography-linked surgical visualization, occupying the premium technology tier.
Vitreoretinal surgery devices comprise precision instruments for posterior segment intervention, including pneumatic cutters operating at 5,000–10,000 cuts per minute, endoilluminators delivering adjustable xenon or LED output, and wide-angle viewing systems enabling panoramic retinal visualization during membrane peeling or hemorrhage evacuation. Their primary purpose is to restore anatomical retinal attachment and preserve photoreceptor function in pathologies threatening central vision. Gauge size 25G technology leads procedural adoption due to reduced surgical trauma and faster patient recovery, while dual-port fluidics represents the fastest-growing innovation by enabling sustained intraocular pressure stability. Retinal laser devices command concentrated margin pools because of consumable fiber-optic dependencies and recurring calibration service contracts.
The FDA's 510(k) premarket notification framework governs device clearance in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements for vitrectomy systems marketed in Europe. Japan's PMDA enforces stringent biocompatibility testing protocols under JIS standards that extend approval timelines but elevate product reliability benchmarks. Stakeholders must monitor evolving MDR technical documentation demands and gauge-size miniaturization trajectories to align R&D allocation with regulatory compliance costs and surgeon workflow preferences.
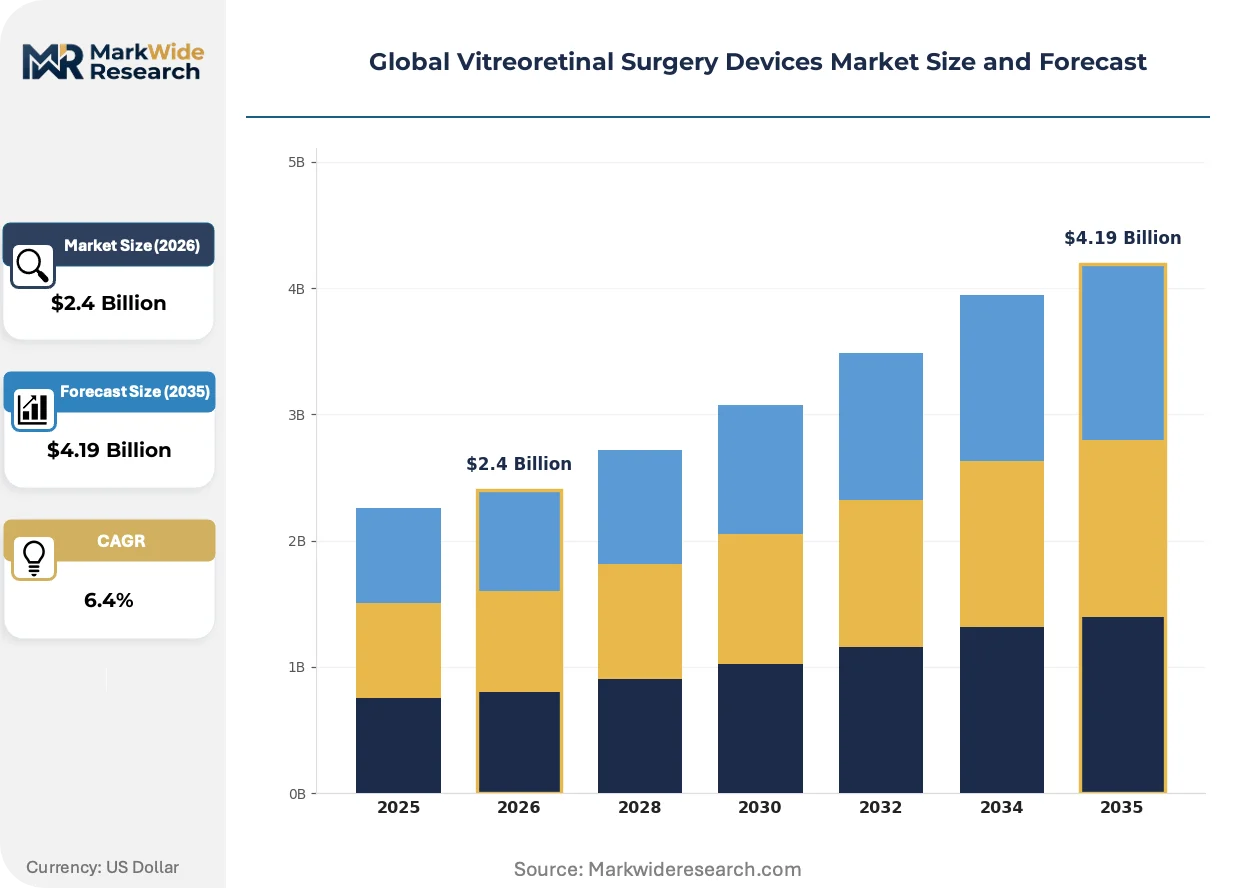
Market Dynamics
The migration of vitreoretinal procedures toward ambulatory surgical facilities is compressing capital equipment procurement cycles while elevating throughput requirements for integrated visualization platforms.
Growth Catalysts
- 25G Gauge Miniaturization:Smaller instrument profiles reduce surgical trauma and accelerate patient discharge protocols, aligning with ambulatory facility throughput targets.
- EU MDR Technical Documentation:Strengthened clinical evidence requirements for vitrectomy systems elevate product reliability benchmarks and create competitive moats for compliant manufacturers.
- Japan PMDA Biocompatibility Protocols:Stringent JIS testing standards extend approval timelines but enhance device durability credentials in premium surgical centers.
Market Restraints
- Xenon Illuminator Supply Concentration:Specialized gas-discharge lamp manufacturing concentrates in German and Japanese component suppliers, creating input vulnerability.
- FDA 510(k) Pathway Friction:Predicate device dependencies for vitrectomy system clearances constrain novel fluidics architecture introduction timelines.
- Pharmacologic Anti-VEGF Substitution:Intravitreal injection therapies for diabetic macular edema displace selected surgical indications in early-intervention protocols.
Strategic Opportunities
- India Tier-2 City Penetration:Underdeveloped vitreoretinal surgical infrastructure in secondary urban centers creates equipment installation white space as ophthalmology residency programs expand.
- OCT-Integrated Visualization Convergence:Real-time optical coherence tomography overlay during membrane peeling procedures commands premium positioning in academic medical centers.
- Direct-to-Facility Service Contracts:Unbundled maintenance and calibration agreements bypass traditional distributor intermediaries in North American surgical center networks.
Industry Challenges
- Vitreoretinal Surgeon Training Pipeline:Fellowship program capacity constraints limit qualified operator availability for advanced 27G instrument adoption.
- Dual-Port Fluidics Integration Complexity:Legacy vitrectomy platform retrofit requirements delay sustained intraocular pressure stability feature deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vitreoretinal Surgery Devices Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.19 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitrectomy Systems, Endoilluminators, Fluid Infusion Systems, Retinal Laser Devices, Wide-Angle Viewing Systems Technology: Gauge Size 23G, Gauge Size 25G, Gauge Size 27G, High-Speed Cutting, Dual-Port Fluidics Application: Diabetic Retinopathy, Retinal Detachment, Macular Hole, Epiretinal Membrane, Vitreous Hemorrhage End User: Ophthalmology Clinics, Surgical Centers, Eye Hospitals, Ambulatory Surgical Facilities |
| Companies Covered | Alcon, Bausch & Lomb, Carl Zeiss Meditec, Dutch Ophthalmic Research Center, Johnson & Johnson Vision, MedOne Surgical, BVI, Nidek, Topcon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vitreoretinal Surgery Devices Market Shifts & Advancements
Device architecture is pivoting toward seamless intraoperative imaging integration while regulatory frameworks harden evidence requirements across major jurisdictions.
Dual-port fluidics architecture is decomposing conventional single-infusion vitrectomy workflows by enabling dynamic pressure modulation during membrane peeling. Academic medical centers in Germany and the United States are adopting these systems for complex proliferative diabetic retinopathy cases. The technology is decomposing established market segmentation between high-volume ambulatory centers and referral-based academic hospitals.
Japan's PMDA has tightened biocompatibility validation protocols for silicone oil and perfluorocarbon liquid accessories under revised JIS standards. Device manufacturers must now submit extended cytotoxicity and sensitization data for intraocular tamponade agents. European suppliers are responding by establishing dedicated Tokyo-based regulatory affairs functions to navigate extended approval timelines.
Outcome-based equipment utilization agreements are displacing traditional capital purchase models in United States ambulatory surgical facility networks. Leasing structures tied to procedure volume thresholds transfer obsolescence risk from facility operators to device vendors. This shift is most pronounced in Florida and Texas multi-site ophthalmology platforms consolidating procurement decisions at corporate headquarters.
Global Vitreoretinal Surgery Devices Market Segmentation
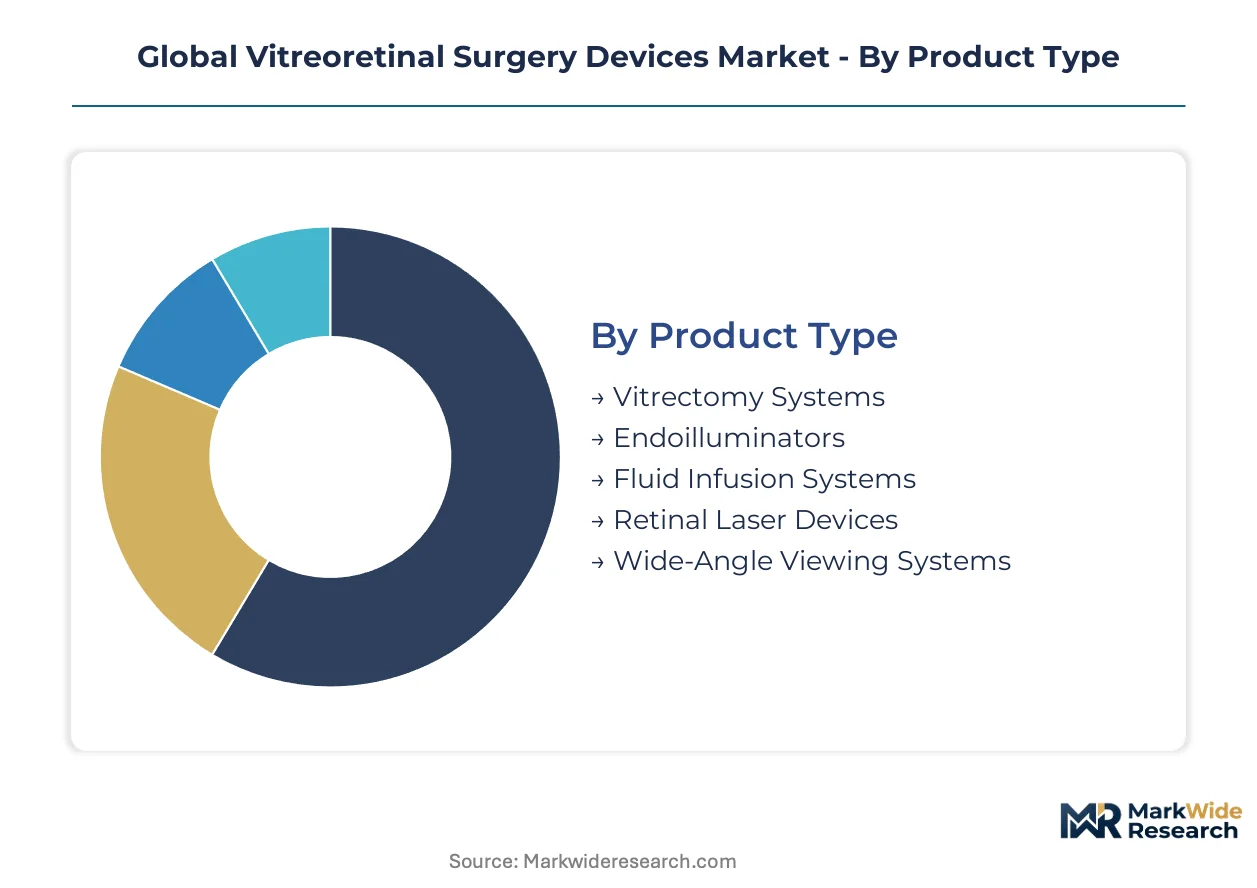
Vitreoretinal surgery devices segment along four critical dimensions that determine procurement priorities and technology adoption curves. Product type classifications reflect capital intensity and consumable attachment rates, while technology tiers capture the gauge miniaturization trajectory reshaping surgical workflows.
Product Type:
Anti-VEGF pharmacologic substitution exerts asymmetric pressure across device categories, with retinal laser systems facing the steepest displacement risk in diabetic macular edema protocols while vitrectomy platforms retain irreplaceable status for mechanical pathologies.
- Vitrectomy Systems:Integrated pneumatic cutter-illumination-fluidics platforms operating at 5,000–10,000 cuts per minute anchor capital expenditure budgets in United States ambulatory surgical networks. Demand concentrates in Florida and Texas multi-site ophthalmology platforms where outcome-based utilization agreements are displacing traditional purchase models.
- Retinal Laser Devices:Photocoagulation systems with consumable fiber-optic dependencies and recurring calibration service contracts command concentrated margin pools. German and Japanese component suppliers dominate xenon illuminator manufacturing, creating input vulnerability for European eye hospital procurement.
- Endoilluminators:Adjustable xenon or LED output devices deliver intraoperative visualization.
- Fluid Infusion Systems:Specialized platforms enable sustained intraocular pressure stability during posterior segment intervention.
- Wide-Angle Viewing Systems:Panoramic retinal visualization instruments support membrane peeling and hemorrhage evacuation procedures.
Vitrectomy systems retain volume leadership; dual-port fluidics-enabled configurations hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium integrated platforms from modular upgrade paths, with academic medical centers absorbing full-featured systems while ambulatory facilities prioritize gauge compatibility over advanced fluidics.
- Gauge Size 25G:Smaller instrument profiles reduce surgical trauma and accelerate patient discharge protocols. United States ambulatory surgical facilities are rotating toward higher-acuity cases using 25G technology, displacing traditional hospital-only models for macular hole and epiretinal membrane repairs.
- Dual-Port Fluidics:Dynamic pressure modulation architecture decomposes conventional single-infusion workflows during membrane peeling. Academic medical centers in Germany and the United States are adopting these systems for complex proliferative diabetic retinopathy cases.
- Gauge Size 23G:Established instrument standard with broader instrument availability.
- Gauge Size 27G:Ultra-miniaturized profiles constrained by fellowship program capacity limitations for qualified operator training.
- High-Speed Cutting:Elevated cut-rate technology for efficient vitreous base dissection.
Gauge Size 25G dominates installed base; dual-port fluidics is climbing the fastest among technology investments.
Application:
Procedure volume distribution correlates directly with diabetic population prevalence and aging demographics, concentrating device utilization in pathologies with mechanical rather than pharmacologic treatment pathways.
- Diabetic Retinopathy:Proliferative and non-proliferative variants drive substantial procedure volume in United States surgical networks, though early-intervention protocols increasingly substitute intravitreal anti-VEGF injections for selected surgical indications.
- Retinal Detachment:Rhegmatogenous and tractional detachments require irreplaceable mechanical intervention, insulating vitrectomy system demand from pharmacologic displacement pressures affecting other categories.
- Macular Hole:Full-thickness defects requiring precise membrane peeling with OCT-integrated visualization.
- Epiretinal Membrane:Fibrocellular proliferation on internal limiting membrane necessitating surgical peeling.
- Vitreous Hemorrhage:Blood accumulation in vitreous cavity requiring evacuation and underlying pathology management.
Retinal detachment retains volume leadership; macular hole repair holds the steepest expansion trajectory as OCT-integrated visualization penetrates academic centers.
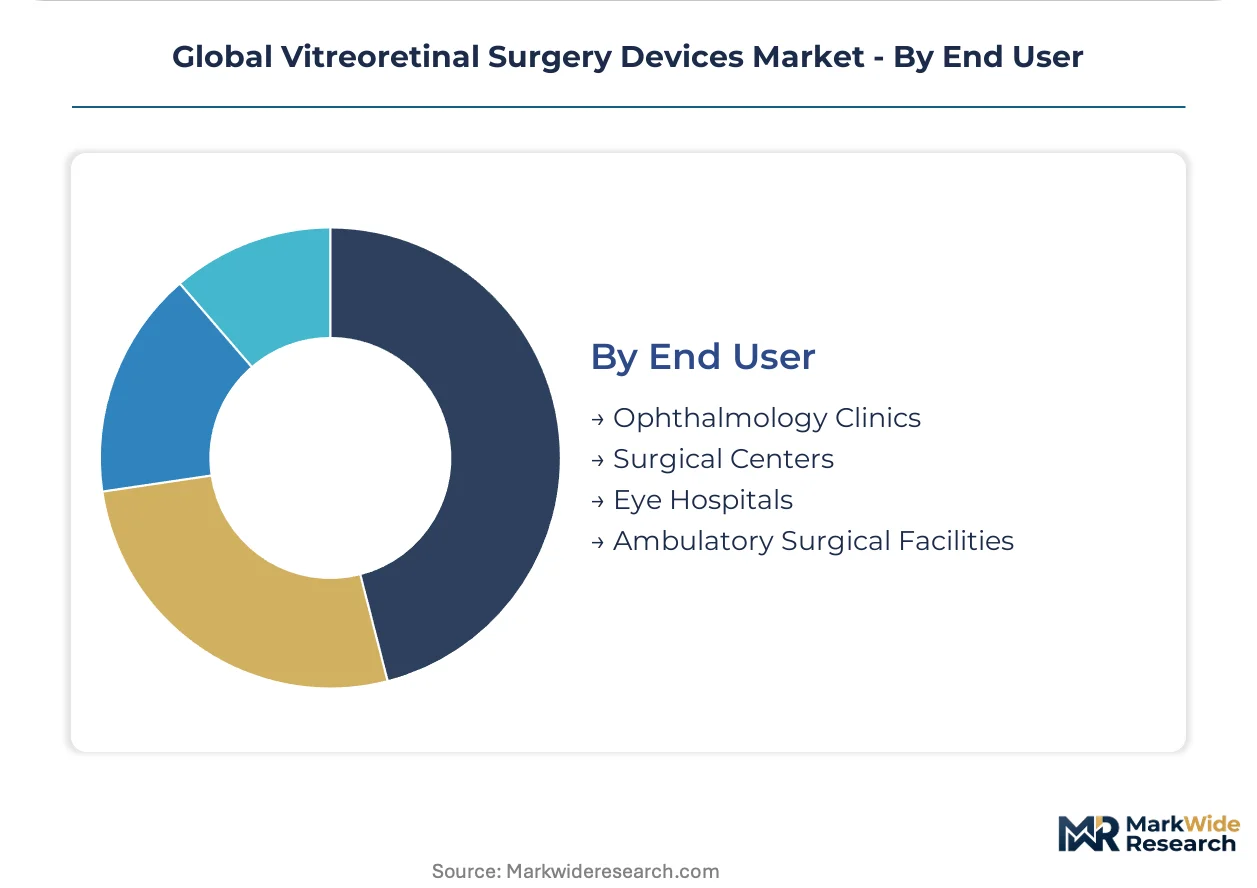
End User:
Customer type determines capital equipment procurement cycles, with consolidated corporate decision-making in multi-site platforms compressing vendor negotiation timelines compared to independent facility purchasing.
- Ambulatory Surgical Facilities:Outpatient-focused centers are accelerating demand as retinal procedures gain preference over hospital-based care. United States networks in Florida and Texas are consolidating procurement decisions at corporate headquarters, favoring vendors offering direct-to-facility service contracts that bypass traditional distributor intermediaries.
- Eye Hospitals:European specialty institutions sustain competitive positioning for fluid infusion systems through specialized requirements and established supplier relationships.
- Ophthalmology Clinics:Office-based settings with limited surgical capacity.
- Surgical Centers:Multi-specialty facilities with shared equipment utilization models.
Ambulatory surgical facilities retain volume leadership; eye hospitals hold the steepest expansion curve as European MDR compliance elevates reliability benchmarks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites Europe's distribution capacity for temperature-sensitive ophthalmic instruments, while Japan's Kansai International Airport cargo terminals anchor Asia-Pacific device transshipment.
United States
Florida and Texas multi-site ophthalmology platforms consolidate procurement decisions at corporate headquarters, accelerating outcome-based utilization agreements. FDA 510(k) premarket notification framework governs vitrectomy system clearances, constraining novel fluidics architecture introduction timelines. The Southeast surgical corridor between Miami and Tampa concentrates ambulatory facility expansion for retinal detachment repair volume.
Germany
Academic medical centers in Bavaria and Baden-Württemberg adopt dual-port fluidics systems for complex proliferative diabetic retinopathy cases. EU Medical Device Regulation imposes strengthened clinical evidence requirements for vitrectomy systems marketed in Europe. The Mannheim-Heidelberg ophthalmology cluster drives adoption of OCT-integrated visualization platforms for membrane peeling procedures.
Japan
PMDA enforces stringent biocompatibility testing protocols under JIS standards that extend approval timelines but elevate product reliability benchmarks. Tokyo-based regulatory affairs functions established by European suppliers navigate extended clearance pathways for silicone oil accessories. The Nagoya medical device manufacturing corridor concentrates xenon illuminator component fabrication.
India
Tier-2 city penetration creates equipment installation white space as ophthalmology residency programs expand in secondary urban centers. CDSCO medical device regulations govern import licensing for vitrectomy platforms while domestic production incentives accelerate local assembly partnerships. The Hyderabad-Bangalore corridor concentrates surgical training infrastructure for 25G gauge adoption.
Global Vitreoretinal Surgery Devices Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity tiers, producing a bifurcated structure where integrated platform vendors face modular component challengers. The vendor base separates into three strategic archetypes: diversified ophthalmology conglomerates with full surgical suites, specialized vitreoretinal instrument pure-plays, and optical technology crossovers leveraging imaging expertise. Competitive moves concentrate on M&A for gauge miniaturization IP and direct-to-facility service contract unbundling that bypasses distributor intermediaries.
Within the diversified ophthalmology tier, Alcon and Bausch & Lomb exemplify integrated platform strategies, while Carl Zeiss Meditec occupies a position bridging optical coherence tomography technology with surgical visualization. These three companies anchor the premium technology segment through distinct capability emphases: Alcon through vitrectomy platform integration, Bausch & Lomb through fluid infusion specialization, and Carl Zeiss Meditec through imaging-surgery convergence. Their collective presence shapes procurement standards across United States ambulatory networks and European eye hospital systems.
| Leading Market Players |
|---|
| Alcon |
| Bausch & Lomb |
| Carl Zeiss Meditec |
| Dutch Ophthalmic Research Center |
| Johnson & Johnson Vision |
| MedOne Surgical |
| BVI |
| Nidek |
| Topcon Corporation |
| Others |
Supply & Pricing Matrix
Outcome-based utilization agreements lock in multi-year equipment access and service bundling for United States ambulatory surgical networks, compressing capital expenditure visibility into predictable per-procedure metrics. This contract structure concentrates pricing power with integrated platform vendors while forcing modular component suppliers into distributor-dependent margin pools.
Pricing Analysis
Volume-discount tiering structures separate high-throughput multi-site ophthalmology platforms from independent surgical centers, with Florida and Texas corporate procurement offices extracting steeper concessions than standalone facilities. Pricing stratifies across premium integrated platforms, standard modular configurations, and economy-tier legacy gauge systems, with certification grade under EU MDR and FDA 510(k) clearance status serving as the primary differentiation drivers. Cost compression in standard-tier vitrectomy systems is intensifying as anti-VEGF pharmacologic substitution erodes retinal laser device utilization. Multi-site platforms exhibit lowest price sensitivity due to consolidated bargaining power, while independent eye hospitals face acute margin pressure from MDR compliance cost pass-through.
Supply Chain Analysis
Germany and Japan anchor xenon illuminator component fabrication, with the Nagoya medical device manufacturing corridor and specialized Bavarian suppliers feeding global vitrectomy platform assembly. German and Japanese gas-discharge lamp production draws from rare earth phosphor deposits and precision glassblowing craft clusters, while silicone oil accessories rest on petrochemical feedstock pathways through Rotterdam and Singapore. Single-source vulnerability concentrates in specialized xenon lamp manufacturing, where dual-qualified suppliers remain scarce. Distribution runs through Port of Rotterdam cold chain infrastructure for European eye hospital networks, with direct-to-facility service contracts bypassing traditional distributor intermediaries in North American ambulatory surgical center consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers are expanding faster than hardware sales as calibration contracts and fiber-optic consumables deepen recurring revenue per installed vitrectomy platform. Preventive maintenance agreements and real-time remote monitoring subscriptions now capture margin pools that capital equipment transactions alone cannot access.
For Market Incumbents: Secure exclusive gauge miniaturization IP through targeted acquisition of 27G instrument specialists before fellowship training capacity constraints ease. Lock in direct-to-facility service contract penetration across Florida and Texas multi-site platforms to neutralize distributor-dependent challengers. Vertical integration into xenon illuminator component fabrication mitigates supply concentration risk from German and Japanese suppliers. For New Entrants and Emerging Players: CDSCO fast-track pathways for 25G vitrectomy platforms offer regulatory arbitrage into Indian Tier-2 cities where ophthalmology residency expansion outpaces equipment installation. Target Hyderabad and Bangalore surgical training corridors with modular upgrade-compatible systems that avoid full-platform capital displacement. Unbundled fluid infusion system sales to European eye hospitals exploit Bausch & Lomb's integrated platform bundling gaps. For Investors and Strategic Acquirers: OCT-integrated visualization pure-plays with academic medical center validation represent the highest-conviction acquisition archetype as imaging-surgery convergence accelerates membrane peeling procedure premiumization. Long-term viability hinges on sustained R&D allocation to dual-port fluidics architecture and real-time intraoperative overlay capabilities. Watch for FDA 510(k) clearance acceleration for novel fluidics architectures as the inflection signal indicating regulatory pathway friction easing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Novel fluidics architectures gain faster market entry as predicate device dependencies loosen under FDA review modernization. |
| CE Marking Pathway Investment | EU MDR technical documentation capabilities create competitive moats for compliant manufacturers against delayed entrants. |
| Hospital System Partnership | Academic medical center adoption of OCT-integrated platforms validates premium positioning for membrane peeling procedures. |
| Software Companion Development | Real-time intraoperative pressure monitoring applications extend platform utility beyond hardware transaction margins. |
| Reimbursement Strategy | Outcome-based contracting alignment with Medicare ASC payment reforms secures ambulatory facility procurement preference. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with vitreoretinal surgeons, biomedical engineers, ambulatory surgical center procurement directors, and GPO contracts managers; and secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract registries, and Japanese PMDA approval records. Bottom-up triangulation across equipment installation counts and top-down reconciliation against manufacturer revenue disclosures anchored market sizing integrity.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, gauge size technology tier, application pathology, and end-user facility category. CAGRs were derived from procedure volume elasticity to diabetic population prevalence and aging demographic shifts, with specific inputs including ophthalmology fellowship program capacity constraints and anti-VEGF substitution rates in early-intervention protocols.
Decision-makers should treat outputs as directional under assumptions of stable FDA 510(k) predicate device availability and sustained EU MDR enforcement intensity; material deviation in regulatory pathway timelines or biocompatibility testing stringency would warrant model refresh. Recalibration cycles align with material shifts in reimbursement policy, gauge miniaturization adoption curves, and ambulatory surgical facility consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Male Artificial Urinary Sphincter Market
Medical Devices
Cervical Implants Market
Medical Devices
Hemodialysis Catheters Market
Medical Devices
Global Dermatoscope Market
Medical Devices
Veterinary Radiography Flat Panel Detectors Market
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Directed Energy Based Surgical Systems Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
Pressure Mapping Systems in Healthcare Market
Medical Devices
Support Surfaces Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Urodynamic Devices Market
Medical Devices
Wearable Blood Pressure Monitor Market
Medical Devices
Global Nebuliser Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Global Bone Tumor Ablation Devices Market