
 Manometry System Market | 2026-2036
Manometry System Market Size, Share, and Industry Trends Forecast 2026-2036
Manometry System Market Foresight
Germany is reconfiguring its diagnostic device manufacturing footprint through targeted investments in precision sensor fabrication. Medtronic leverages its integrated supply chain to sustain leadership in high-resolution manometry catheter production. Laborie Medical Technologies anchors its competitive position through specialized gastrointestinal motility diagnostics. Boston Scientific differentiates via concentrated R&D spending on wireless pressure monitoring platforms.
Manometry systems measure pressure variations within hollow organs using catheter-mounted pressure transducers, typically resolving differences of less than one millimeter of mercury to assess peristaltic function and sphincter coordination. These systems serve primarily to diagnose esophageal motility disorders, anorectal dysfunction, and urodynamic abnormalities in clinical settings. Computer-assisted systems command the dominant share of product type revenue due to their software-integrated waveform analysis capabilities. Fiber optic technology represents the fastest-expanding segment as hospitals seek electromagnetic interference immunity during concurrent imaging procedures. Portable units occupy an emerging niche in ambulatory diagnostic clinics seeking flexible deployment models.
FDA 510(k) premarket notification requirements govern device clearance in the United States, while the EU Medical Device Regulation mandates notified body conformity assessment for European market access. ISO 13485 quality management standards shape supplier qualification criteria across manufacturing ecosystems. Stakeholders must monitor evolving cybersecurity guidance from regulators as wireless monitoring architectures proliferate in hospital networks.
Market Dynamics
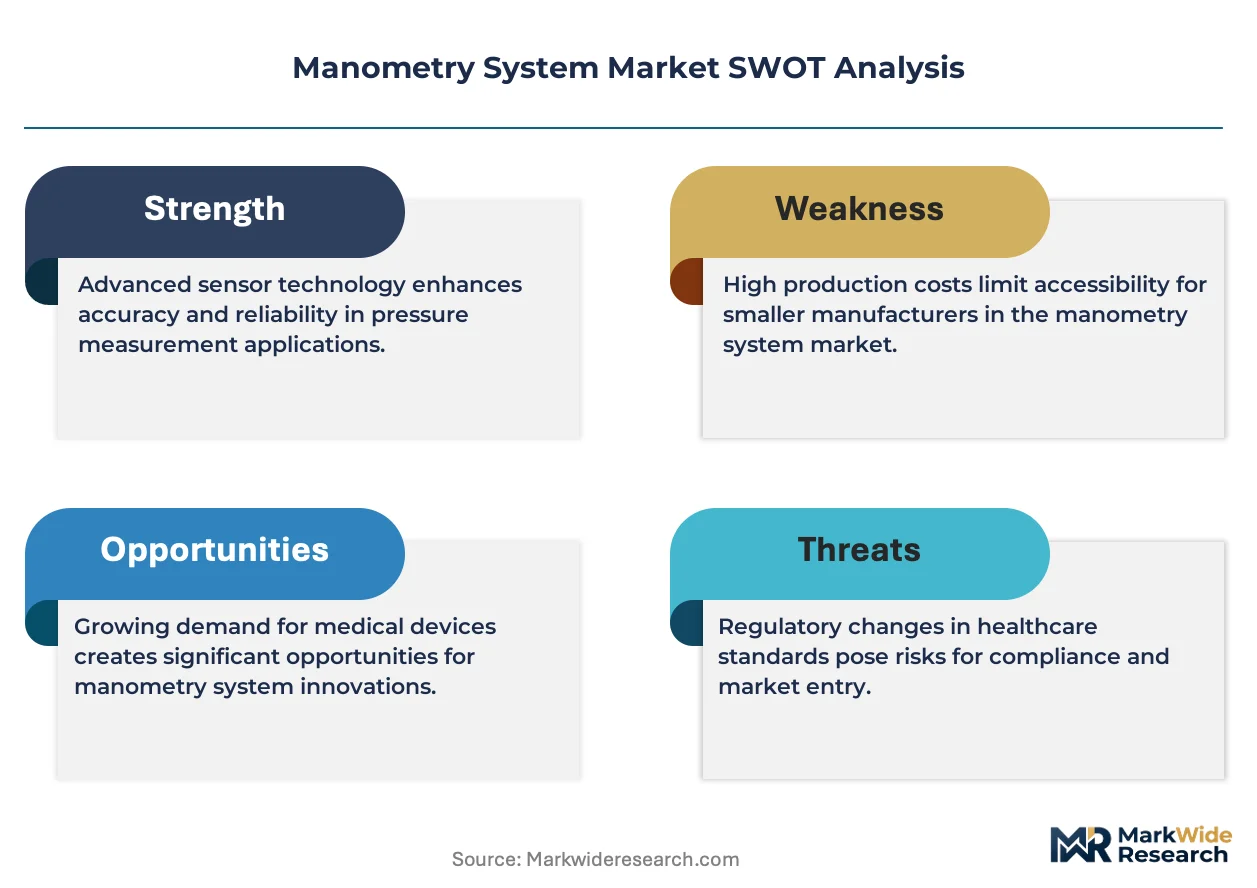
High-resolution manometry catheter manufacturing is concentrating among vertically integrated suppliers with captive sensor fabrication capabilities, compressing procurement options for independent diagnostic device assemblers and reshaping competitive positioning across the value chain.
Growth Catalysts
- FDA 510(k) pathway efficiency:Streamlined premarket notification for Class II devices accelerates commercialization timelines for computer-assisted manometry platforms in the United States.
- Gastroenterology department expansion:Hospital systems are scaling motility diagnostic infrastructure to address rising esophageal disorder prevalence and anorectal dysfunction screening protocols.
- Fiber optic immunity:Electromagnetic interference-resistant pressure transducers enable concurrent manometry and MRI procedures, opening hybrid diagnostic workflows in tertiary care centers.
Market Restraints
- Precision sensor supply concentration:Germany and Japan dominate high-fidelity pressure transducer fabrication, creating geographic vulnerability for catheter manufacturers without backward integration.
- EU MDR conformity costs:Notified body assessment requirements for European market access extend certification timelines and elevate compliance expenditure for mid-tier device developers.
- Wireless capsule substitution:Ambulatory pH monitoring capsules are capturing functional reflux diagnostics, pressuring stationary manometry system utilization in select esophageal indications.
Strategic Opportunities
- Ambulatory clinic channel development:Portable manometry units address flexible deployment demand from independent diagnostic centers seeking capital-efficient motility testing capacity.
- Urodynamics application expansion:Pelvic floor dysfunction protocols are incorporating high-resolution manometry for integrated sphincter coordination assessment beyond traditional gastrointestinal use cases.
- ISO 13485 supplier qualification:Quality management certification is becoming a procurement gatekeeper, creating differentiation leverage for contract manufacturers with established compliance infrastructure.
Industry Challenges
- Catheter reprocessing validation:Reusable high-resolution assemblies require rigorous sterilization documentation under FDA infection control guidance, complicating service operations.
- Legacy system software integration:Hospital IT departments face interoperability friction when connecting new manometry platforms to existing electronic health record architectures and waveform databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manometry System Market |
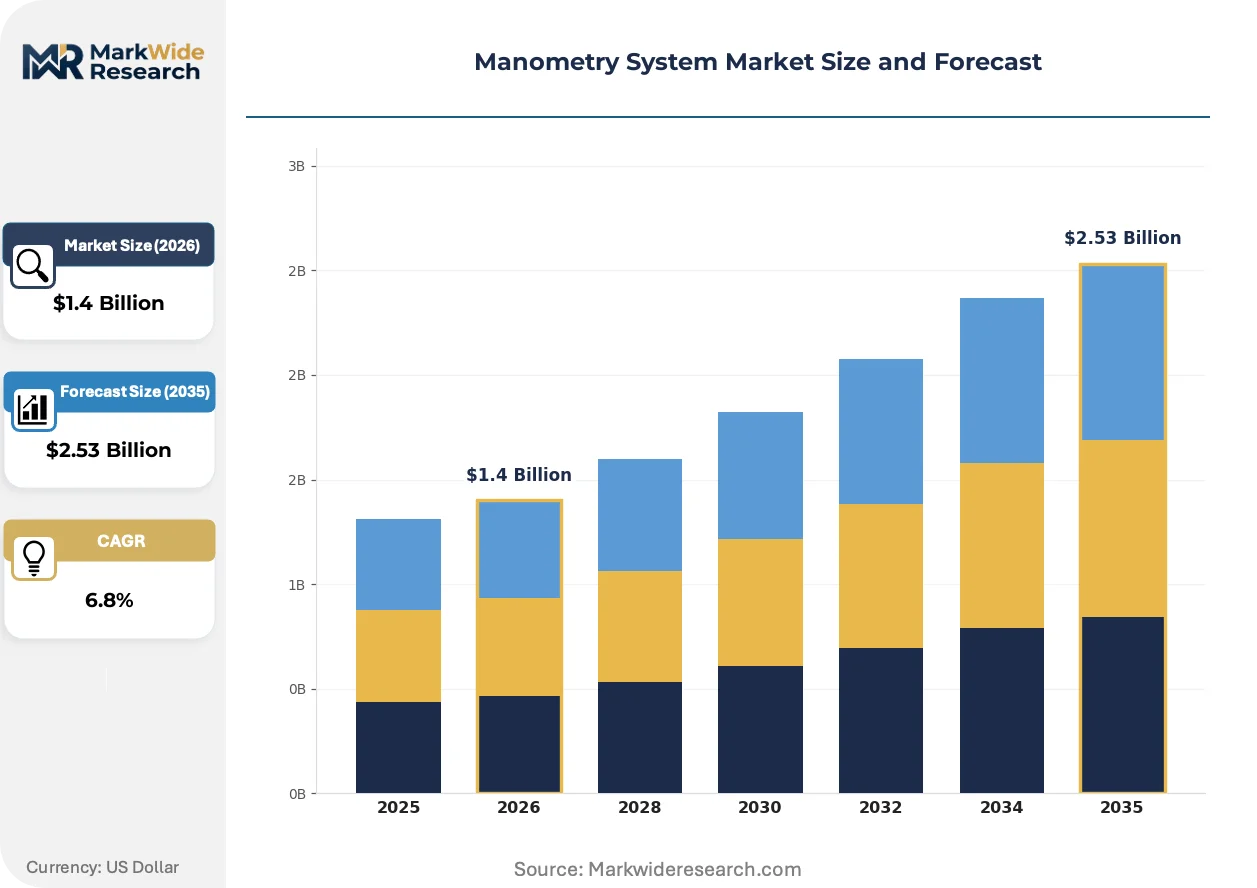
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Monitors, Computer-Assisted Systems, Stationary Devices, Portable Units End User: Diagnostic Clinics, Hospitals, Research Institutions, Academic Facilities Technology: Fiber Optic, Electronic Sensors, Wireless Monitoring, Pressure Measurement Application: Gastroenterology, Urology, Pulmonology, Neurology |
| Companies Covered | Medica S.p.A., Alacer Biomedica, Medtronic, Creo Medical, Mui Scientific, Laborie Medical Technologies, EB Neuro, Boston Scientific, Diversatek Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manometry System Market Shifts & Advancements
Software-integrated waveform analysis is virtualizing diagnostic interpretation workflows, compressing the traditional specialist-technician hierarchy and enabling remote clinical decision support across distributed care networks.
Cloud-native manometry platforms are virtualizing data storage and computational analysis, allowing community hospitals to access algorithmic diagnostic assistance without on-premise server infrastructure. Gastroenterology groups in the United States and Germany are piloting these architectures to extend subspecialist expertise into underserved markets. The technology is virtualizing the traditional capital-intensity barrier that concentrated advanced manometry within academic medical centers.
The EU Medical Device Regulation is mandating unique device identification and post-market surveillance systems, elevating traceability requirements for catheter manufacturers serving European hospitals. Compliance investments are diverting R&D resources toward regulatory infrastructure rather than core sensor innovation. High-resolution esophageal platforms face the steepest adaptation burden due to their classification as Class IIa devices with sustained patient contact.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, forcing manufacturers to compete on discrete maintenance and software update pricing. This disintermediation is compressing vendor margins while creating openings for third-party technical service specialists. The pattern is most pronounced in German hospital systems undergoing consolidated purchasing reforms.
Manometry System Market Segmentation
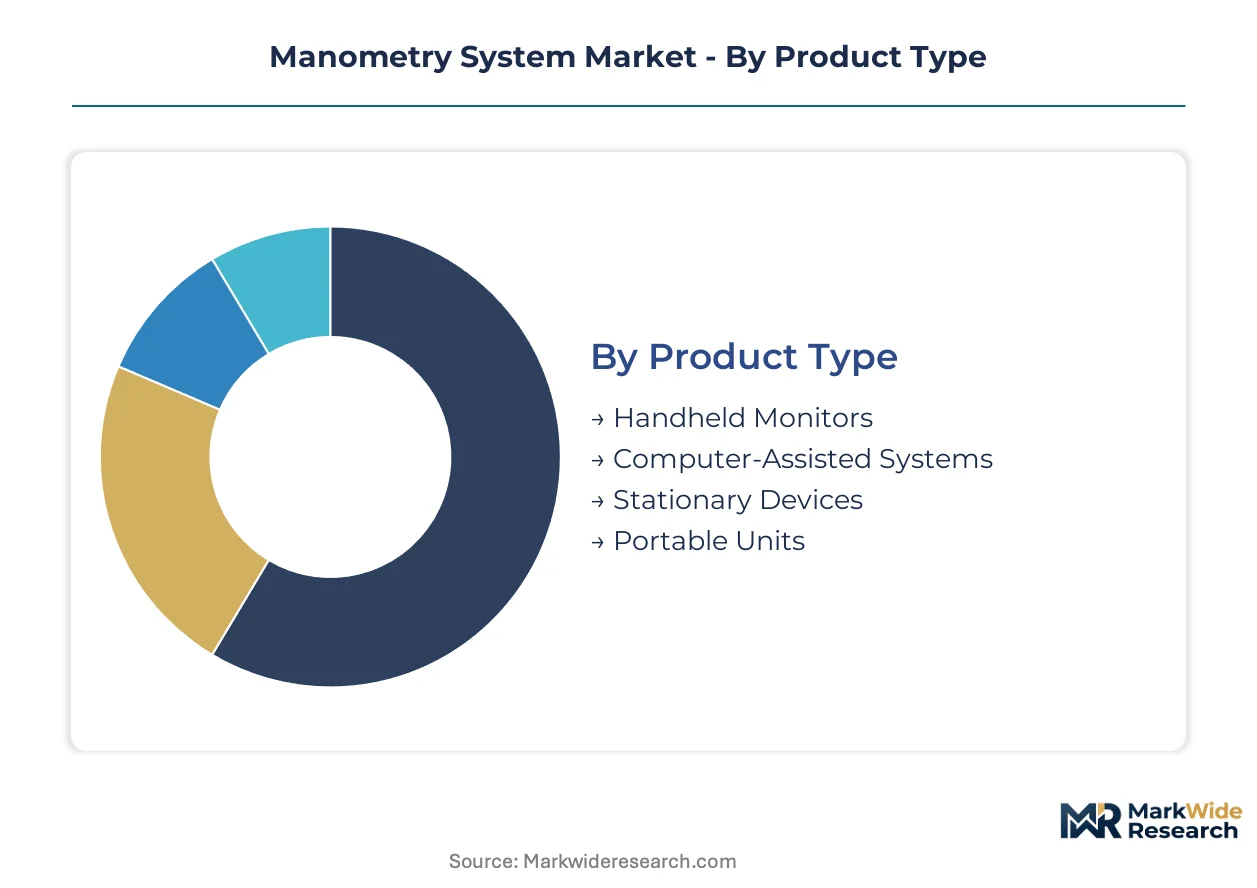
Manometry system segmentation reveals distinct service intensity profiles across product tiers, with computer-assisted platforms demanding complex software maintenance contracts while portable units shift toward discrete component replacement models. Hospital procurement committees exploit these structural differences to unbundle capital and service expenditures.
Product Type:
After-sales service intensity varies sharply across product tiers, with software-integrated systems requiring continuous calibration support and handheld monitors depending on consumable catheter replenishment.
- Computer-Assisted Systems:Software-integrated platforms with algorithmic waveform analysis capabilities anchor revenue concentration in tertiary care centers. Demand clusters at academic medical centers in Germany and the United States seeking remote diagnostic assistance infrastructure. Service contracts typically span multi-year software licensing and computational hardware maintenance.
- Portable Units:Battery-powered devices with modular catheter interfaces address ambulatory clinic demand for flexible deployment. Independent diagnostic centers in underserved U.S. markets and German regional hospitals prioritize these for capital-efficient motility testing capacity. Lower service attachment rates shift margin capture toward disposable component sales.
- Stationary Devices:Fixed-installation platforms with integrated pressure transducer arrays dominate high-throughput hospital motility laboratories.
- Handheld Monitors:Compact single-channel devices serve point-of-care screening applications with minimal technical support requirements.
By volume, handheld monitors lead. By growth pace, portable units are ahead.
End User:
Customer procurement sophistication determines pricing realization, with consolidated hospital systems extracting steeper discounts than fragmented diagnostic clinic networks.
- Hospitals:Integrated health systems with dedicated gastroenterology departments drive replacement cycles for high-resolution esophageal platforms. German hospital networks undergoing consolidated purchasing reforms unbundle service contracts to compress vendor margins. These institutions demand ISO 13485-certified suppliers with established cybersecurity documentation.
- Diagnostic Clinics:Independent ambulatory centers prioritize portable manometry units for flexible capital deployment. U.S. specialty clinics in secondary markets access cloud-native platforms to virtualize subspecialist expertise without on-premise infrastructure. Procurement committees favor discrete maintenance pricing over bundled service agreements.
- Academic Facilities:University-affiliated medical centers pilot wireless monitoring architectures and hybrid diagnostic workflows.
- Research Institutions:Clinical trial sites utilize high-fidelity pressure transducers for protocol-specific motility assessment.
By installed base, hospitals dominate. By expansion velocity, diagnostic clinics are climbing the fastest.
Technology:
Sensor fabrication geography constrains supply security, with German and Japanese suppliers controlling high-fidelity pressure transducer production.
- Fiber Optic:Electromagnetic interference-immune pressure transducers enable concurrent manometry and MRI procedures. Tertiary care centers in the United States and Germany deploy these for hybrid diagnostic workflows. The technology commands premium positioning due to precision sensor supply concentration.
- Wireless Monitoring:Capsule-based pressure architectures reduce catheter-related patient discomfort in ambulatory settings. U.S. gastroenterology groups pilot these platforms to extend testing beyond traditional laboratory environments. FDA cybersecurity guidance for wireless hospital network integration elevates compliance burdens.
- Electronic Sensors:Solid-state transducer arrays deliver sub-millimeter mercury resolution for standard clinical applications.
- Pressure Measurement:Conventional strain-gauge technologies serve cost-sensitive installations with established reprocessing protocols.
By current deployment, electronic sensors lead. By technology transition momentum, fiber optic is gaining share fastest.
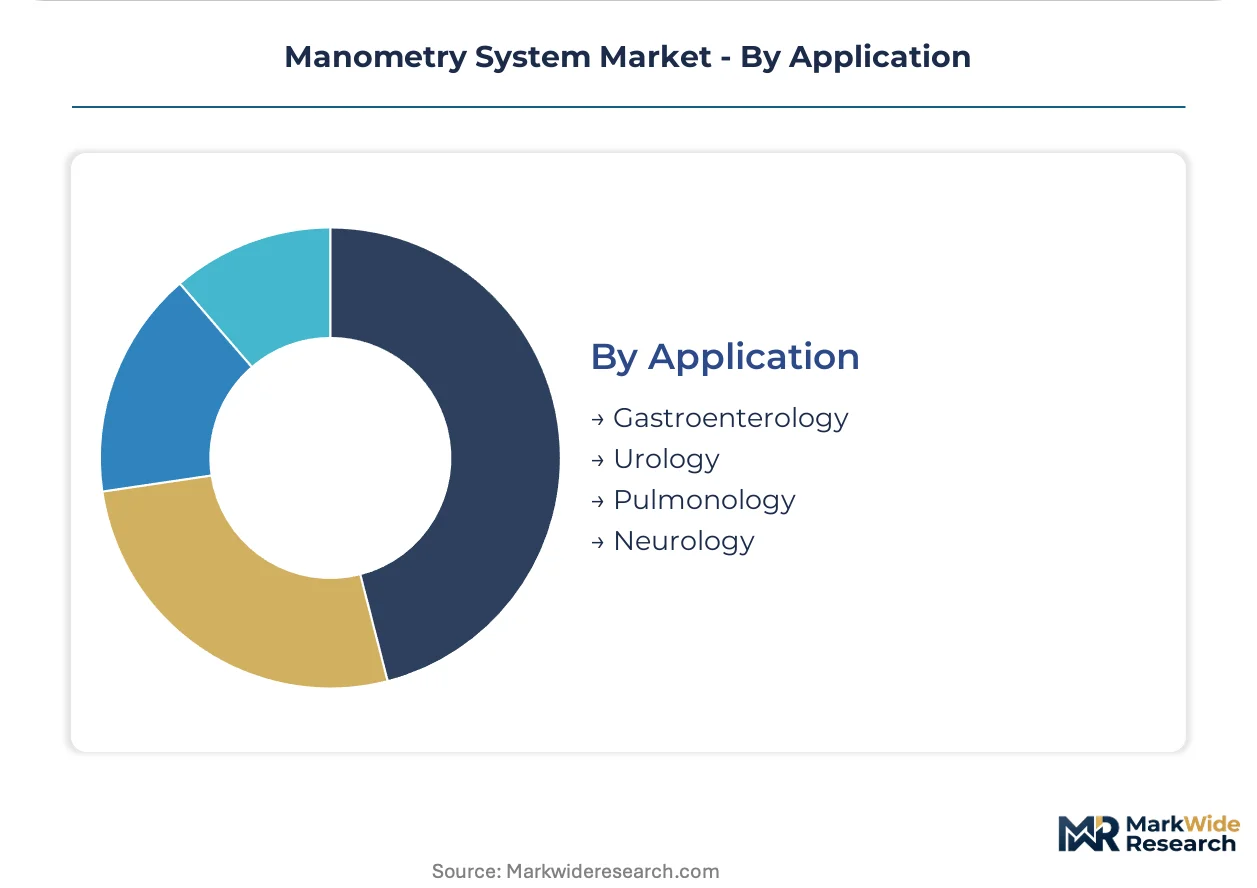
Application:
Clinical protocol expansion beyond traditional gastrointestinal indications reshapes segment prioritization for catheter manufacturers.
- Gastroenterology:Esophageal motility disorder diagnosis and anorectal dysfunction screening constitute the core revenue base. Hospital systems in Germany and the United States scale dedicated motility laboratories to address rising disorder prevalence. High-resolution esophageal platforms face steepest EU MDR adaptation burden due to Class IIa classification.
- Urology:Pelvic floor dysfunction protocols incorporate high-resolution manometry for integrated sphincter coordination assessment. U.S. urogynecology practices and German specialized clinics drive adoption beyond traditional gastrointestinal use cases. Catheter design modifications accommodate anatomical specificity.
- Pulmonology:Esophageal pressure monitoring supports respiratory mechanics assessment in critical care settings.
- Neurology:Neurogenic bowel dysfunction evaluation utilizes anorectal manometry for sphincter control assessment.
By procedure volume, gastroenterology dominates. By protocol expansion rate, urology is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's 510(k) clearance pathway anchors the United States as the dominant geography for manometry system commercialization, while Germany and Japan concentrate precision sensor fabrication capabilities that constrain global catheter supply security.
United States
Hospital systems in Texas and Florida are expanding dedicated gastroenterology motility laboratories to address rising esophageal disorder prevalence. FDA's streamlined premarket notification for Class II devices accelerates commercialization timelines for computer-assisted platforms. The Greater Boston medical technology cluster anchors wireless monitoring architecture development for ambulatory diagnostic applications.
Germany
Specialized motility clinics in Bavaria and North Rhine-Westphalia drive replacement cycles for high-resolution esophageal manometry platforms. EU Medical Device Regulation mandates notified body conformity assessment, extending certification timelines for catheter manufacturers. The Baden-Württemberg precision engineering corridor concentrates high-fidelity pressure transducer fabrication for backward-integrated suppliers.
Japan
Tertiary care centers in Tokyo and Osaka deploy fiber optic manometry systems for concurrent MRI procedures in hybrid diagnostic workflows. PMDA's quality management standards shape supplier qualification criteria for domestic device assemblers. The Nagoya medical device manufacturing belt specializes in electromagnetic interference-immune pressure transducer production.
United Kingdom
NHS trusts in London and the Midlands are consolidating procurement for gastrointestinal diagnostic equipment under framework agreements. MHRA's post-Brexit regulatory alignment with EU MDR requirements elevates compliance documentation burdens for catheter suppliers. The Cambridge life sciences cluster supports algorithmic waveform analysis software development for cloud-native platforms.
India
Corporate hospital chains in Maharashtra and Karnataka are importing high-resolution manometry systems to establish motility diagnostic capacity in tier-1 cities. CDSCO's medical device registration requirements are tightening quality management expectations for foreign manufacturers. The Hyderabad medical technology park is attracting contract manufacturers seeking ISO 13485-certified production infrastructure.
Manometry System Market Competitive Landscape
Vertically integrated multinationals and specialized gastrointestinal diagnostics firms split the market into distinct capability tiers. The structure concentrates around suppliers with captive sensor fabrication and those dependent on external procurement. Three archetypes dominate: precision sensor fabricators with backward integration, software-integrated platform developers, and regional contract manufacturers. Competitive moves center on supply chain consolidation and cloud-native architecture licensing.
Within the integrated tier, Medtronic and Boston Scientific exemplify archetypes combining sensor production with platform development, while Laborie Medical Technologies occupies a position as a specialized gastrointestinal diagnostics firm. Medtronic's Irish incorporation and Boston Scientific's US structure reflect geographic anchoring strategies, with Laborie's positioning demonstrating how focused portfolio concentration competes against diversified health technology conglomerates.
| Leading Market Players |
|---|
| Medica S.p.A. |
| Alacer Biomedica |
| Medtronic |
| Creo Medical |
| Mui Scientific |
| Laborie Medical Technologies |
| EB Neuro |
| Boston Scientific |
| Diversatek Healthcare |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and Japanese precision sensor fabricators determines both pricing tier spreads and supply chain shape, compressing procurement options for catheter assemblers without backward integration while elevating premium positioning for vertically integrated multinationals.
Pricing Analysis
Trans-Atlantic price spreads of 15-25 percent separate U.S. hospital system contracts from German regional hospital procurements, reflecting differential service bundling and regulatory compliance overhead. Three-tier pricing structure across premium, standard, and economy levels stratifies by catheter resolution capability and ISO 13485 certification tier. Cost compression in mid-tier electronic sensor systems is intensifying because independent diagnostic clinics are unbundling after-sales contracts. Independent ambulatory centers exhibit acute price sensitivity, while academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for catheter manufacturers sourcing from Baden-Württemberg precision engineering suppliers, straining working capital for non-integrated assemblers. High-fidelity pressure transducer production centers on Germany, Japan, and select U.S. medical device clusters, with electromagnetic interference-immune fiber optic components drawing from Nagoya manufacturing belts. Single-source vulnerability in specialty sensor substrates creates exposure to export control adjustments. Distribution runs through hospital procurement committees and GPO frameworks in the United States, direct tender processes in Germany, and import-dependent dealer networks in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: FDA 510(k) clearance timelines and EU MDR conformity assessments create structural barriers that protect incumbents with established quality management infrastructure.
For Market Incumbents: Insulate market position by deepening captive sensor fabrication capabilities in Baden-Württemberg or Nagoya corridors to neutralize supply concentration risk. Prioritize cybersecurity documentation investment for wireless monitoring architectures ahead of FDA guidance finalization, as hospital IT committees are elevating network integration requirements to procurement gatekeeper status.
For New Entrants and Emerging Players: Establish a beachhead in portable manometry units for U.S. ambulatory diagnostic clinics, where capital-efficient deployment models and unbundled service pricing create lower barriers than tertiary care computer-assisted platforms. Target cloud-native platform licensing to community hospitals seeking subspecialist expertise virtualization without on-premise infrastructure investment.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision sensor fabricators with ISO 13485-certified production infrastructure and established notified body relationships. Long-term viability over the next decade rests on regulatory compliance scalability rather than pure R&D intensity. Watch for EU MDR implementation friction as an inflection signal: catheter manufacturers facing steep adaptation burdens for Class IIa high-resolution esophageal platforms may become distressed acquisition targets.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Streamlined premarket notification accelerates U.S. commercialization timelines for computer-assisted platforms. |
| CE Marking Conformity Assessment | Notified body certification under EU MDR extends European market access for high-resolution catheter systems. |
| Hospital System Partnership | Integrated health network alliances secure replacement cycle visibility for esophageal motility platforms. |
| Software Companion Development | Algorithmic waveform analysis integration enables remote diagnostic assistance across distributed care networks. |
| Reimbursement Strategy | Coding alignment with CMS and German DRG frameworks determines procedure volume economics for motility testing. |
Research Methodology
A standing panel of gastroenterology department heads, hospital procurement committee chairs, biomedical engineering directors, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR notified body registries, hospital equipment procurement databases, and CMS Medicare reimbursement schedules. Bottom-up demand modeling across catheter replacement cycles and top-down market sizing through manufacturer revenue triangulation anchored volume estimates.
Scenario-bracketing across regulatory implementation timelines, sensor supply disruption events, and wireless technology adoption curves shaped the analytical framework. Segmentation dimensions modeled encompassed product type tiers, end-user facility categories, technology platform generations, and application-specific procedural volumes throughout the forecast period. CAGRs derived from fitted growth curves against historical replacement cycle data and hospital capital expenditure patterns, with fiber optic technology transition rates and ambulatory clinic expansion velocity as key industry-specific inputs.
Stress conditions across EU MDR conformity cost inflation, precision sensor export restriction scenarios, and wireless cybersecurity compliance burden were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory trajectory and hospital procurement reform momentum. Macroeconomic contraction affecting hospital capital budgets, unanticipated regulatory guidance revision, or disruptive wireless capsule substitution acceleration would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
China Artificial Organs and Bionic Implants Market
Medical Devices
Microwave Ablation Devices Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
EEG and EMG Equipment Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
Canada Anesthesia Devices Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Repetitive Transcranial Magnetic Stimulation Market
Medical Devices
Medical Device Validation and Verification Market
Medical Devices
Trocars Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Gastric Electrical Stimulators Market
Medical Devices
Peripheral Embolization Device Market
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
PPG Biosensors Market
Medical Devices
Blood Collection Devices Market