
 Global Heart Valve Devices Market | 2026-2036
Global Heart Valve Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Heart Valve Devices Market Foresight
Polymer leaflets replacing traditional bovine and porcine pericardium is realigning valve durability economics and biocompatibility profiles across the industry. Edwards Lifesciences Corporation leverages its transcatheter platform depth to sustain leadership in minimally invasive aortic procedures. Medtronic plc anchors its position through integrated structural heart portfolios spanning surgical and catheter-based modalities. Abbott Laboratories differentiates via its clip-based mitral repair technology, competing directly against replacement paradigms in select patient cohorts.
Heart valve devices are implantable prostheses engineered from biocompatible materials including pyrolytic carbon, bovine pericardium, porcine aortic roots, or advanced polymers, designed to restore unidirectional blood flow across diseased cardiac valves through mechanical fixation or catheter delivery. Transcatheter valves command accelerating investment as minimally invasive procedures expand treatable patient populations beyond surgical candidates, while mechanical valves retain entrenched positions in younger demographics where longevity outweighs anticoagulation burden. Tissue valves capture margin concentration in elderly patients seeking bioprosthetic solutions that eliminate lifelong warfarin dependency. Application segmentation reveals aortic valve replacement as the procedural volume leader, with mitral valve repair emerging as the fastest-growing addressable segment amid expanding transcatheter mitral technologies.
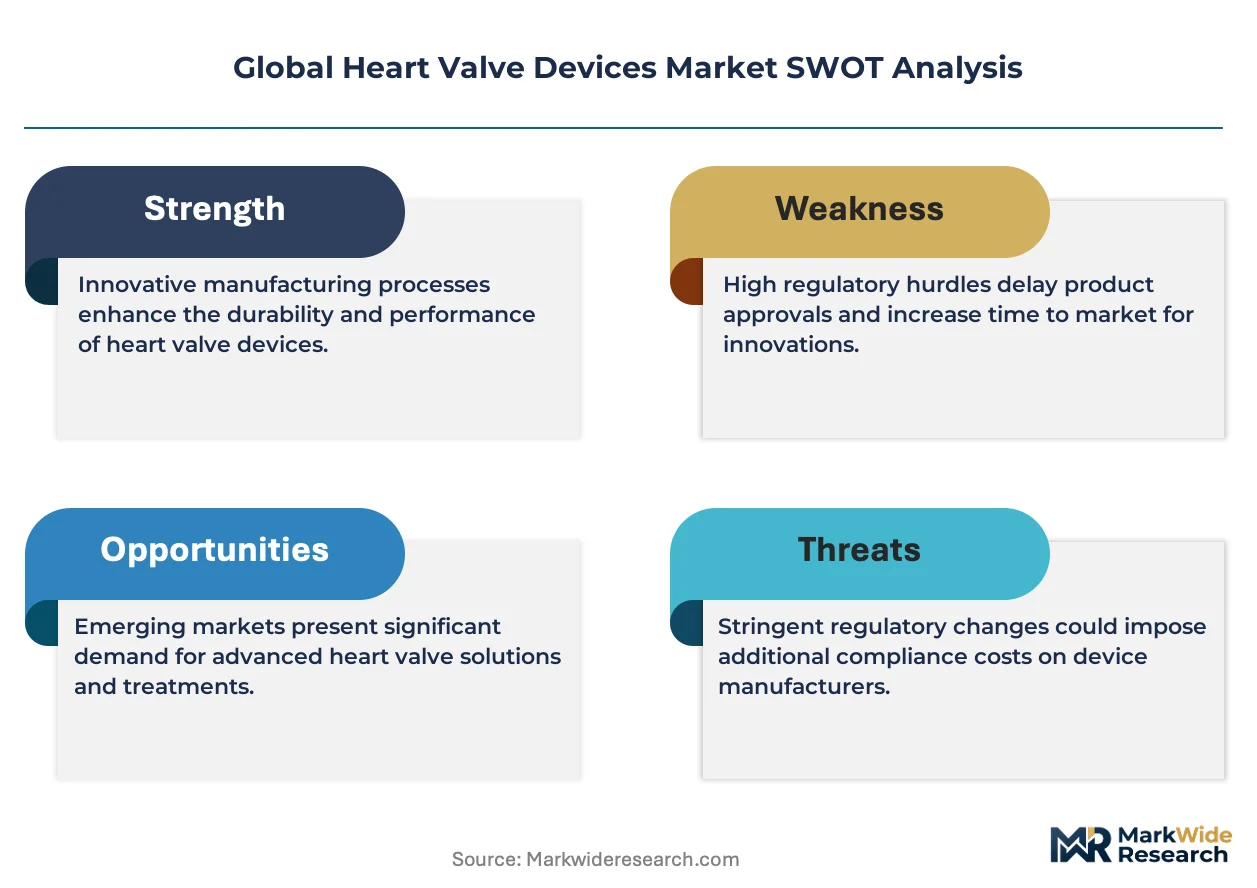
FDA premarket approval pathways and the EU Medical Device Regulation impose escalating clinical evidence and post-market surveillance demands that filter market access toward well-capitalized manufacturers with robust quality management systems. Japan's PMDA adds distinct reimbursement-linked approval requirements that shape product launch sequencing across Asia-Pacific. ISO 5840 standards for cardiovascular implants further define fatigue resistance and hydrodynamic performance benchmarks that manufacturers must satisfy prior to commercialization. Stakeholders should monitor evolving transcatheter durability data and shifting regulatory evidentiary thresholds as these forces determine competitive viability across procedural categories.
Market Dynamics
Polymer leaflet technology is compressing valve replacement intervals and forcing incumbents to recalibrate durability claims against emerging biocompatibility benchmarks. This materials transition is redistributing value capture from tissue processors to polymer synthesis specialists.
Growth Catalysts
- EU Medical Device Regulation:Stricter post-market surveillance requirements favor established manufacturers with robust quality systems, accelerating consolidation around compliant product portfolios.
- Transcatheter delivery platforms:Minimally invasive procedures expand treatable populations beyond surgical candidates, particularly among elderly patients with comorbidities in Japan and Germany.
- Aging demographics:The United States, Germany, and Japan exhibit concentrated demand for bioprosthetic solutions as life expectancy extends valve replacement windows.
Market Restraints
- Bovine pericardium supply concentration:Tissue sourcing depends on limited abattoir networks in Australia and New Zealand, creating raw material vulnerability for biological valve manufacturers.
- Anticoagulation burden:Mechanical valve recipients require lifelong warfarin management, restricting adoption among patients with bleeding risks or lifestyle constraints.
- FDA premarket approval timelines:Extended clinical evidence requirements for novel materials delay commercialization of polymer-based alternatives by 18-36 months versus predicate devices.
Strategic Opportunities
- Transcatheter mitral repair:Clip-based technologies address underpenetrated structural heart segments where surgical intervention carries prohibitive risk profiles.
- Japan's PMDA reimbursement-linked pathways:Premium pricing for breakthrough devices incentivizes manufacturers to prioritize Japanese launch sequencing ahead of broader Asia-Pacific expansion.
- Polymer-tissue hybrid leaflets:Convergence of synthetic durability with biological hemodynamics opens intermediate durability categories between mechanical and bioprosthetic paradigms.
Industry Challenges
- Structural heart imaging expertise:Transcatheter procedures require specialized echocardiography skills that outpace training pipeline capacity in community hospital settings.
- ISO 5840 fatigue validation:Accelerated wear testing protocols demand substantial capital investment in pulsatile flow simulators and extended verification timelines.
- Legacy surgical infrastructure:Hybrid operating suite conversion costs impede catheter-based procedure adoption in smaller cardiac centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Heart Valve Devices Market |
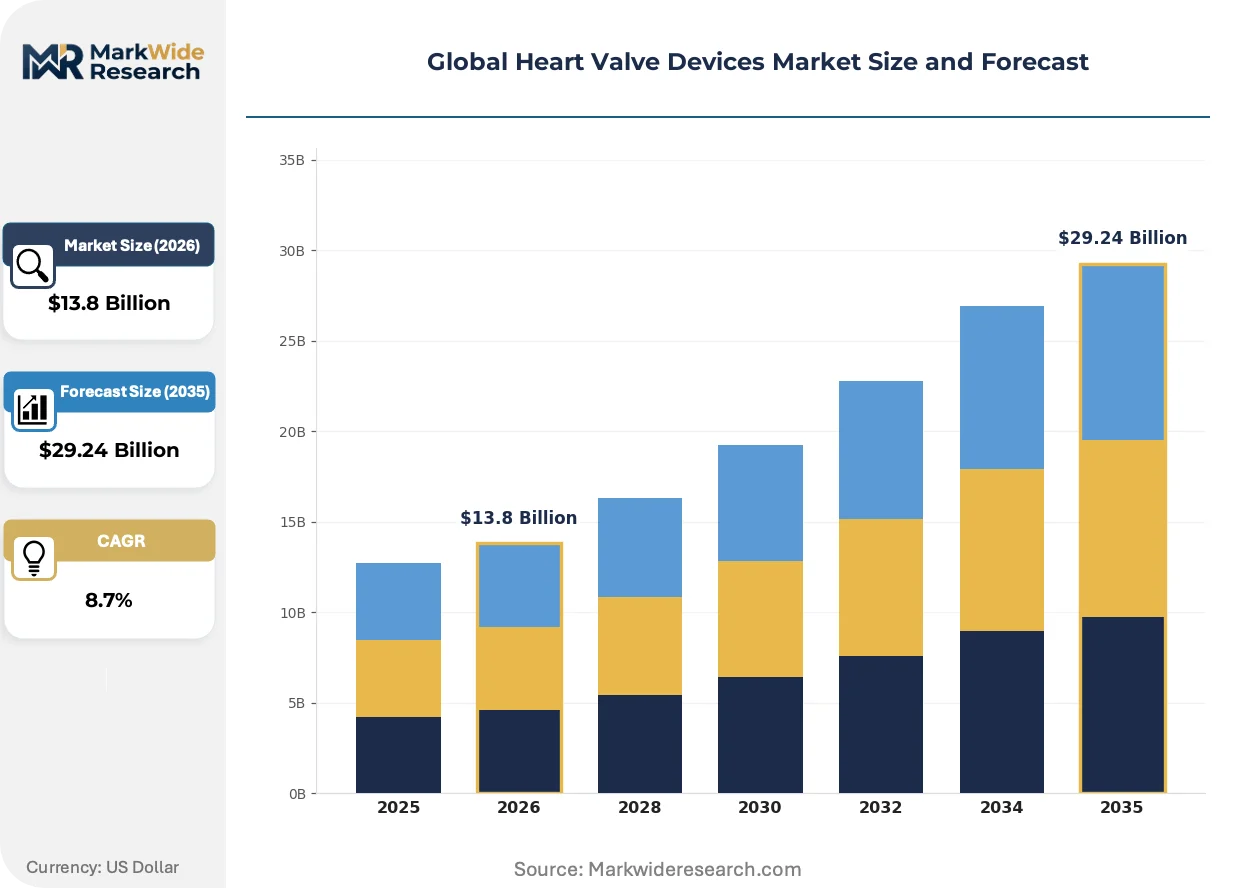
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $29.24 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Valves, Tissue Valves, Transcatheter Valves, Homograft Valves Application: Aortic Valve Replacement, Mitral Valve Repair, Pulmonary Valve Replacement, Tricuspid Valve Repair End User: Cardiac Surgery Centers, Specialized Clinics, Ambulatory Cardiovascular Units, Research Institutes Installation Method: Open Heart Surgery, Minimally Invasive Surgery, Transcatheter Procedure, Robotic Assisted Surgery |
| Companies Covered | Boston Scientific Corporation, JenaValve Technology, Inc., Edwards Lifesciences Corporation, MicroPort Scientific Corporation, Meril Life Sciences Pvt. Ltd., Medtronic plc, LivaNova PLC, Lepu Medical Technology, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Heart Valve Devices Market Shifts & Advancements
Computational modeling and advanced materials science are compressing product development cycles while regulatory frameworks force earlier evidence generation. These forces are reconfiguring competitive advantage around simulation capabilities rather than empirical iteration alone.
Polymer leaflet systems incorporating polyhedral oligomeric silsesquioxane (POSS) nanocomposites are automating durability prediction through finite element analysis prior to physical prototyping. Cardiac surgery centers in Germany and the United States are piloting these valves for intermediate-age patients seeking anticoagulation-free alternatives. The technology is automating the shift from empirical wear testing to in-silico validation, collapsing traditional 5-year preclinical timelines.
The EU Medical Device Regulation's stricter clinical evidence requirements are extending approval timelines for novel valve materials while grandfathering predicate devices. Manufacturers must now generate real-world performance data through post-market clinical follow-up studies spanning minimum two-year intervals. Tissue valve segments face disproportionate impact as biological material variability complicates equivalence demonstrations against established benchmarks.
Hospital procurement committees are consolidating valve purchasing around outcome guarantees and total cost-of-ownership frameworks rather than device-centric pricing. Integrated delivery networks in the United States are negotiating bundled contracts spanning implant, procedure, and 30-day readmission liability. This behavioral shift concentrates purchasing power among systems with sufficient case volume to absorb financial risk, disadvantaging smaller cardiac centers.
Global Heart Valve Devices Market Segmentation
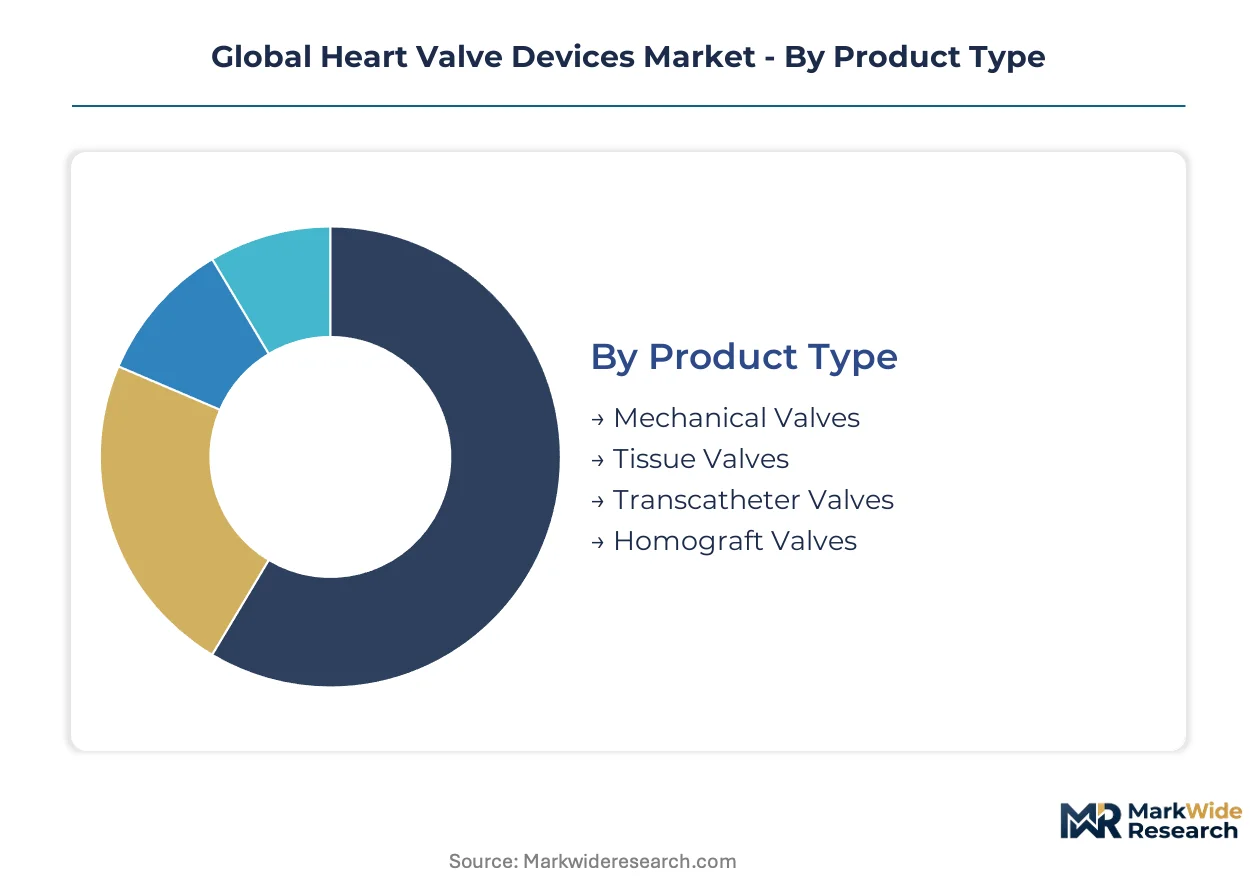
Heart valve device segmentation reveals how material science, procedural access, and care delivery economics fragment commercial opportunity. Manufacturers must align portfolio depth with specific installation capabilities and patient risk profiles across heterogeneous healthcare systems.
Product Type:
Supply concentration in pyrolytic carbon foundries and pericardium processing facilities dictates which valve categories manufacturers can scale profitably.
- Mechanical Valves:Pyrolytic carbon discs and metal cages deliver indefinite structural durability. Younger patients in Germany and Japan select these devices despite lifelong warfarin requirements, prioritizing longevity over anticoagulation burden.
- Tissue Valves:Bovine pericardium and porcine aortic roots provide biocompatibility without anticoagulation. Elderly populations in the United States drive demand as life expectancy extends replacement windows and bleeding risk tolerance drops.
- Transcatheter Valves:Nitinol frames with biological leaflets deploy via catheter. Intermediate-risk surgical candidates in cardiac surgery centers adopt these for reduced recovery timelines.
- Homograft Valves:Cryopreserved human donor tissue eliminates xenogenic immune response. Pediatric and infective endocarditis cases in specialized clinics utilize these for anatomical flexibility.
Tissue valves absorb the bulk of installed capacity; transcatheter valves are expanding most quickly.
Application:
Procedure volume distribution across valve positions reflects anatomical complexity and regulatory approval sequencing for transcatheter alternatives.
- Aortic Valve Replacement:The procedural volume leader with established transcatheter pathways. Centers in the United States and Germany perform these interventions on expanded patient cohorts previously excluded from surgery.
- Mitral Valve Repair:Clip-based technologies and transcatheter replacements address undertreated regurgitation. Japan's PMDA reimbursement pathways accelerate adoption among high-risk surgical candidates.
- Pulmonary Valve Replacement:Congenital heart defect corrections dominate this segment. Pediatric cardiac surgery centers in specialized academic medical centers concentrate expertise.
- Tricuspid Valve Repair:Emerging transcatheter solutions target isolated tricuspid regurgitation. Research institutes pilot devices for this historically neglected valve position.
Aortic valve replacement absorbs the bulk of installed capacity; mitral valve repair is climbing the fastest.
End User:
Capital intensity and technical expertise requirements stratify valve deployment across facility types.
- Cardiac Surgery Centers:Hybrid operating suites and full surgical backup enable all valve modalities. These facilities command premium pricing for complex combined procedures.
- Specialized Clinics:Focused structural heart programs deliver high transcatheter volumes with streamlined workflows. Outcome data transparency drives patient referral patterns.
- Ambulatory Cardiovascular Units:Same-day discharge capabilities for select transcatheter patients. Regulatory frameworks in select geographies constrain expansion.
- Research Institutes:First-in-human trials and extended follow-up protocols for novel materials. FDA and EMA breakthrough designations channel investigational devices here.
Cardiac surgery centers absorb the bulk of installed capacity; specialized clinics are gaining share fastest.
Installation Method:
Facility infrastructure investment determines which procedural modalities hospitals can offer.
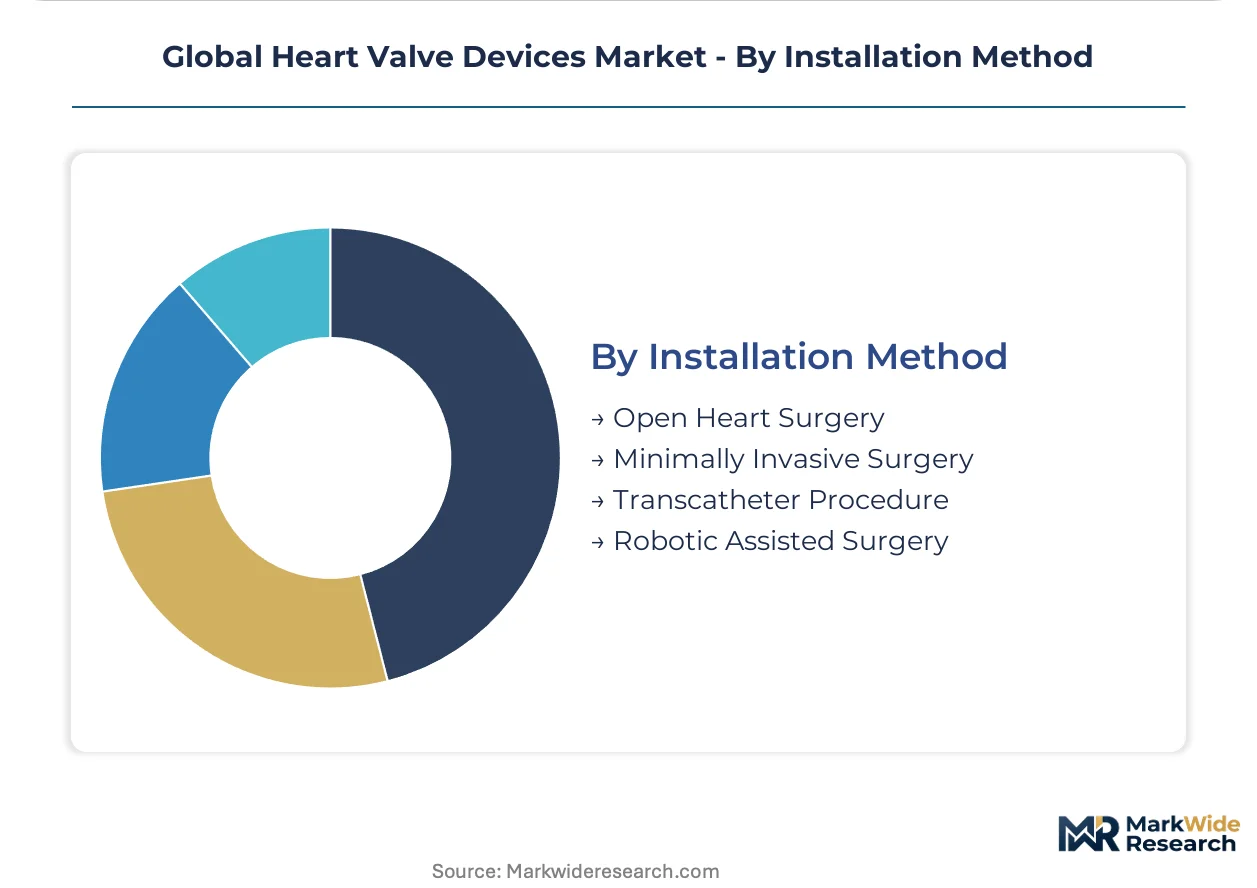
- Open Heart Surgery:Sternotomy with cardiopulmonary bypass remains the durability benchmark. Younger patients and complex multi-valve procedures require this approach.
- Minimally Invasive Surgery:Partial sternotomy or thoracotomy reduces recovery without catheter technology. Specialized training programs in Germany propagate these techniques.
- Transcatheter Procedure:Femoral or apical access eliminates sternotomy. Aging demographics and comorbidity burden in Japan and the United States propel volume expansion.
- Robotic Assisted Surgery:Da Vinci systems enable precise valve repair with smaller incisions. Capital cost limits deployment to flagship cardiac centers.
Open heart surgery absorbs the bulk of installed capacity; transcatheter procedures are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac surgery centers in the United States, Germany, and Japan concentrate the bulk of procedural volume and premium valve deployment. Reimbursement clarity and aging demographics in these markets sustain demand for bioprosthetic and transcatheter alternatives.
United States
Medicare coverage determinations and bundled payment pilots accelerate transcatheter valve adoption among elderly patients with comorbidities. FDA breakthrough device pathways compress timelines for novel polymer leaflet technologies. The Cleveland Clinic and Mayo Clinic anchor multi-center trials that generate real-world durability data for regulatory submissions.
Germany
Statutory health insurance funds reimburse transcatheter procedures at rates that sustain hospital investment in hybrid operating suites. EU Medical Device Regulation post-market surveillance requirements filter market access toward manufacturers with established quality management systems. The Heidelberg and Munich cardiac surgery clusters concentrate expertise in minimally invasive mitral repair techniques.
Japan
PMDA reimbursement-linked approval pathways incentivize manufacturers to prioritize Japanese launch sequencing for premium devices. Aging demographics expand the addressable patient population beyond surgical candidates. Tokyo and Osaka academic medical centers pilot transcatheter mitral technologies ahead of broader Asia-Pacific expansion.
China
NMPA regulatory reforms accelerate review timelines for imported valve devices while domestic manufacturers scale production capacity. Provincial medical insurance catalogs increasingly cover transcatheter procedures in tier-one cities. The Shanghai and Beijing hospital networks concentrate structural heart programs that train interventional cardiologists for catheter-based modalities.
India
CDSCO regulatory pathways and price controls on imported devices create openings for domestic tissue valve manufacturers. Private hospital chains in Mumbai and Delhi expand cardiac surgery capacity to capture medical tourism flows. Government health insurance schemes extend coverage for surgical valve replacement to lower-income patient segments.
Global Heart Valve Devices Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers integrate surgical and catheter-based modalities under single corporate structures. The vendor base concentrates around three tiers: integrated multinational conglomerates with full structural heart portfolios, mid-cap specialists focused on single valve positions or delivery technologies, and regional fabricators serving price-sensitive emerging markets. Strategic archetypes include transcatheter platform builders, tissue processing specialists, and polymer synthesis innovators. M&A activity and technology licensing agreements represent the primary competitive moves reshaping market boundaries.
Within the integrated multinational tier, Edwards Lifesciences Corporation, Medtronic plc, and Abbott Laboratories exemplify distinct strategic positioning. Edwards Lifesciences Corporation anchors transcatheter platform depth through its California-based corporate structure. Medtronic plc occupies a position spanning surgical and catheter-based modalities through its Irish-domiciled, operationally global configuration. Abbott Laboratories represents clip-based mitral repair specialization competing against replacement paradigms, with its Illinois-based corporate heritage supporting diversified healthcare exposure.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| JenaValve Technology, Inc. |
| Edwards Lifesciences Corporation |
| MicroPort Scientific Corporation |
| Meril Life Sciences Pvt. Ltd. |
| Medtronic plc |
| LivaNova PLC |
| Lepu Medical Technology |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Premium-transcatheter versus standard-surgical valve bifurcation concentrates margin capture among manufacturers with catheter platform depth while compressing tissue valve pricing power through procurement consolidation. This tier divergence manifests in divergent supply chain configurations: polymer synthesis specialists command forward integration into leaflet production, whereas pericardium processors face backward price pressure from abattoir network concentration.
Pricing Analysis
Volume-margin splits favor transcatheter platforms where procedure expansion sustains premium capture despite higher per-unit manufacturing costs. Three-tier pricing structure across premium transcatheter, standard surgical tissue, and economy mechanical valves reflects ISO 5840 fatigue validation tiers and anticoagulation burden trade-offs. Pricing pressure stems from US bundled payment pilots that shift financial risk to hospitals, intensifying GPO negotiation leverage. Price sensitivity concentrates among ambulatory cardiovascular units seeking same-day discharge economics, while cardiac surgery centers absorb premium positioning for complex combined procedures.
Supply Chain Analysis
Freight cost sensitivity elevates for cryopreserved homograft valves requiring cold-chain logistics from specialized tissue banks in the United States and Germany. Pyrolytic carbon foundries in the United States and Japan anchor mechanical valve production, while bovine pericardium processing draws from abattoir networks in Australia and New Zealand. Single-source vulnerability concentrates in nitinol frame suppliers tethered to superelastic alloy production. Distribution runs through integrated delivery networks consolidating purchasing around outcome guarantees rather than device-centric procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer leaflet systems are displacing biological tissue as the dominant durability paradigm, compressing replacement intervals and recalibrating manufacturer R&D allocation toward synthetic materials science.
For Market Incumbents: Cement transcatheter platform leadership through captive polymer synthesis capacity that insulates against raw material volatility in biological tissue supply. Deepen hospital system partnerships around outcome-based contracting to defend margin position against procurement consolidation. Prioritize ISO 5840 fatigue validation investment as regulatory evidentiary thresholds escalate under EU MDR post-market surveillance requirements. For New Entrants and Emerging Players: Direct-to-clinic digital education platforms enable white-space penetration in tricuspid valve repair, where surgical expertise scarcity and undertreated patient populations create addressable gaps. Target specialized structural heart clinics in Japan's reimbursement-linked PMDA pathway, where premium pricing for breakthrough devices accelerates commercial traction ahead of broader Asia-Pacific expansion. Deploy software companion development for procedural imaging guidance to differentiate against incumbent hardware-centric offerings. For Investors and Strategic Acquirers: Re-rating potential sits with polymer-tissue hybrid leaflet specialists given FDA breakthrough device pathway acceleration for anticoagulation-free alternatives in intermediate-age demographics. Long-term viability over the projection horizon favors manufacturers with vertically integrated materials science capabilities spanning synthesis through finished device production. Monitor transcatheter durability data publication cadence as the inflection signal for competitive repositioning across tissue versus mechanical valve paradigms.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Leaflet Development | POSS nanocomposite integration collapses preclinical timelines through in-silico validation prior to physical prototyping. |
| CE Marking Pathway | EU MDR post-market clinical follow-up requirements filter market access toward manufacturers with robust quality management systems. |
| Hospital System Partnership | Bundled contracts spanning implant, procedure, and readmission liability concentrate purchasing power among high-volume cardiac centers. |
| Software Companion Development | Specialized echocardiography guidance addresses training pipeline capacity constraints in community hospital settings. |
| Reimbursement Strategy | PMDA premium pricing for breakthrough devices incentivizes Japanese launch sequencing ahead of broader Asia-Pacific expansion. |
Research Methodology
Document review covered FDA premarket approval filings, EU MDR technical documentation, and ISO 5840 cardiovascular implant standards, complemented by interviews with cardiac surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, hospital procurement databases, and regulatory submission records. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market size estimation.
Cross-referencing historical procedural adoption curves against expert panel input on transcatheter expansion trajectories shaped the analytical framework across the analysis window. Segmentation dimensions modeled include valve position, material composition, delivery modality, and regional regulatory cluster. CAGRs derived from logistic diffusion curves calibrated to demographic aging patterns and reimbursement policy shifts. Industry-specific inputs incorporated polymer fatigue testing protocols and cardiac surgery center capacity expansion pipelines.
The model holds under stable reimbursement policy environments; deviation in FDA evidentiary requirement escalation or EU MDR enforcement intensity would shift competitive viability thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Antimicrobial Coated Medical Devices Market
Medical Devices
Medical Device and Accessories Market
Medical Devices
Global Radial Artery Compression Devices Market
Medical Devices
South America Ultrasound Devices Market
Medical Devices
Diode Laser Hair Removal Equipment Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
Lyophilized Injectable Market
Medical Devices
Knee Walkers Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Global 3D Printed Surgical Models Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
Wrist Fixator Procedure Kit Market
Medical Devices
Infant Radiant Warmer Market
Medical Devices
Implantable Defibrillators Market
Medical Devices
Wireless Neurofeedback Device Market