
 Equine Operating Tables Market | 2026-2036
Equine Operating Tables Market Size, Share, and Industry Trends Forecast 2026-2036
Equine Operating Tables Market Foresight
Germany is reshaping European supply dynamics through precision engineering clusters serving veterinary equipment makers. Haico leverages its domestic manufacturing base to sustain export competitiveness across Western Europe. Midmark Corporation anchors North American distribution through extensive dealer networks. Jørgen Kruuse A/S specializes in Scandinavian markets with region-specific product configurations.
Equine operating tables are surgical platforms engineered to support horses weighing up to 1,200 kilograms, incorporating hydraulic lift mechanisms and radiolucent tabletops for intraoperative imaging. Their primary purpose centers on positioning large animals safely during orthopedic, abdominal, and dental procedures while protecting both surgical staff and patient. Hydraulic tables dominate installed bases due to proven reliability under heavy loads, while electric variants capture fastest-growing interest where clinic budgets permit automation upgrades. Stainless steel construction leads material selection for sterilization compatibility, though aluminum gains traction in mobile clinic configurations where weight reduction determines transport feasibility.
The FDA Center for Veterinary Medicine oversees device safety claims in the United States, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance for tables sold in Europe. ISO 10993 biocompatibility standards further constrain surface material choices, pushing manufacturers toward certified coatings and documented supply chains. Stakeholders must monitor how evolving MDR conformity assessment timelines affect European product registration costs and competitive entry barriers.
Market Dynamics
The EU Medical Device Regulation is compressing product registration timelines and forcing manufacturers to revalidate legacy hydraulic systems against stricter biocompatibility benchmarks. This regulatory pressure is reshaping competitive positioning across Western Europe as domestic engineering clusters absorb compliance costs that offshore competitors struggle to match.
Growth Catalysts
- MDR compliance mandates:The EU Medical Device Regulation requires updated clinical evidence for legacy tables, creating replacement demand across German and French veterinary networks.
- Orthopedic specialization:Large-animal referral hospitals in the United States are outfitting dedicated surgical suites with radiolucent tabletops for intraoperative imaging.
- Hydraulic reliability:Proven load-bearing performance under 1,200-kilogram horses sustains installed-base loyalty where electric automation remains cost-prohibitive.
Market Restraints
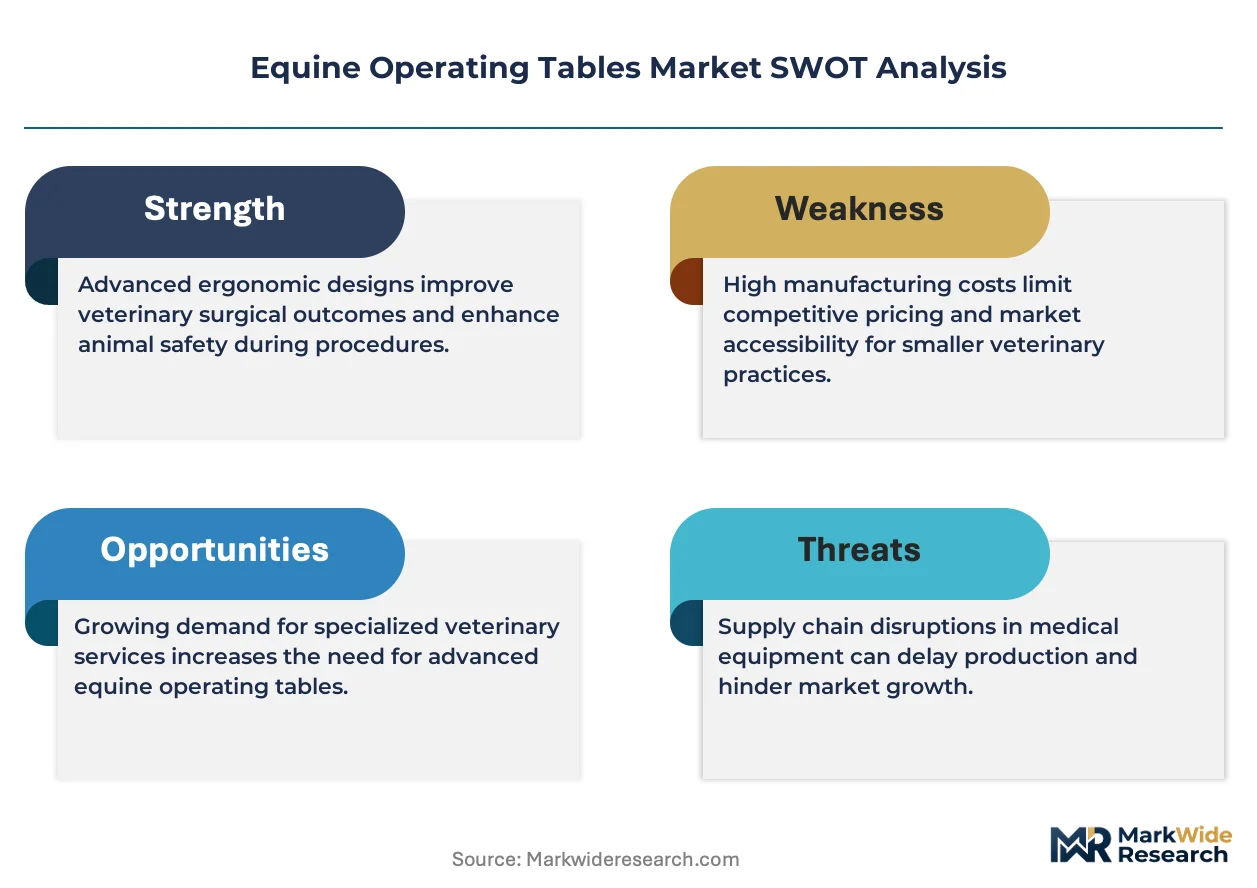
- Stainless steel price volatility:Input cost swings for surgical-grade alloys squeeze margin structures for mid-tier manufacturers.
- German supply concentration:Precision engineering clusters in Baden-Württemberg dominate high-specification component sourcing, creating geographic vulnerability.
- ISO 10993 certification friction:Surface coating biocompatibility testing extends product development cycles by 8-14 months.
Strategic Opportunities
- Mobile clinic expansion:Aluminum-frame configurations address transport-weight constraints for ambulatory equine services in rural Texas and Kentucky.
- Scandinavian welfare standards:Jørgen Kruuse A/S leverages region-specific ergonomic configurations to capture premium positioning in Denmark and Norway.
- Service unbundling:Aftermarket maintenance contracts separate from capital sales, creating recurring revenue streams independent of replacement cycles.
Industry Challenges
- Veterinary surgical technician scarcity:Specialized training for large-animal table operation limits clinic throughput regardless of equipment availability.
- Legacy system integration:Electric table retrofits require incompatible electrical infrastructure in facilities built before 2015.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equine Operating Tables Market |
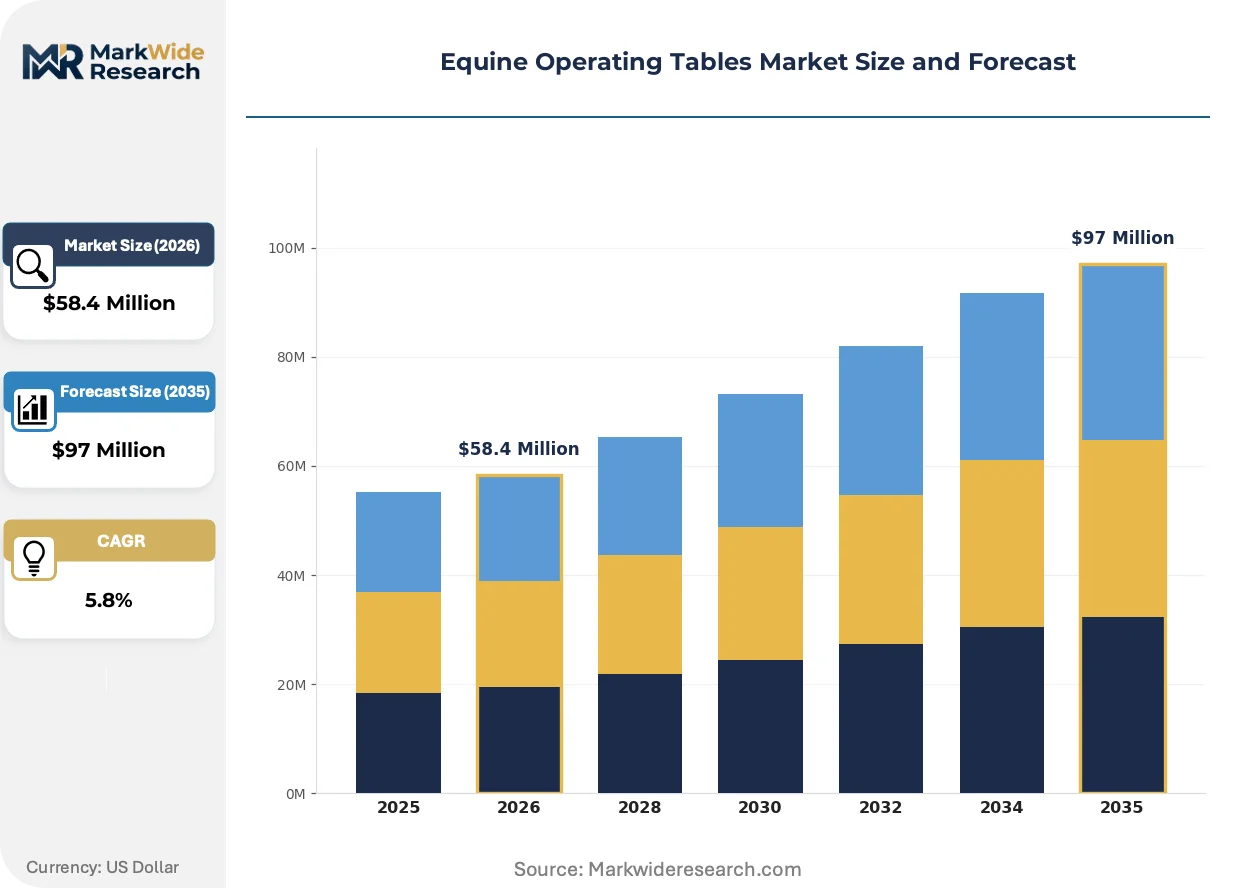
| Market Size in 2026 | $58.4 Million |
| Market Size in 2035 | $97 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Tables, Portable Tables, Hydraulic Tables, Electric Tables End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Mobile Clinics Material: Stainless Steel, Aluminum, Plastic, Composite Materials Feature: Height Adjustable, Foldable, X-Ray Compatible, Accessories Included |
| Companies Covered | Haico, Shank’s Veterinary Equipment, Autoquip Corporation, Jørgen Kruuse A/S, Midmark Corporation, DRE Veterinary, Pedigo, Suburban Surgical, Jorgensen Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equine Operating Tables Market Shifts & Advancements
Radiolucent tabletop materials and automated positioning systems are collapsing traditional trade-offs between imaging compatibility and load-bearing capacity. Veterinary equipment procurement is accelerating toward modular platforms that accommodate both hydraulic reliability and electric precision.
Carbon-fiber composite tabletops are collapsing the weight-to-strength ratio that previously forced clinics to choose between imaging clarity and mechanical durability. University veterinary centers in the United States are adopting these platforms fastest, compressing the upgrade cycle from 12-year replacement intervals to 7-year technology refresh schedules.
REACH substance restrictions are tightening surface coating formulations across European supply chains. Manufacturers serving Germany and France must reformulate anti-corrosion treatments to eliminate candidate list substances, forcing reformulation investments that smaller competitors cannot absorb.
Consolidated buying groups now dominate capital equipment acquisition for multi-site veterinary networks. Independent clinics in the United States are losing negotiating leverage as purchasing cooperatives standardize on approved vendor lists, compressing price differentiation and forcing manufacturers toward volume rebate structures.
Equine Operating Tables Market Segmentation
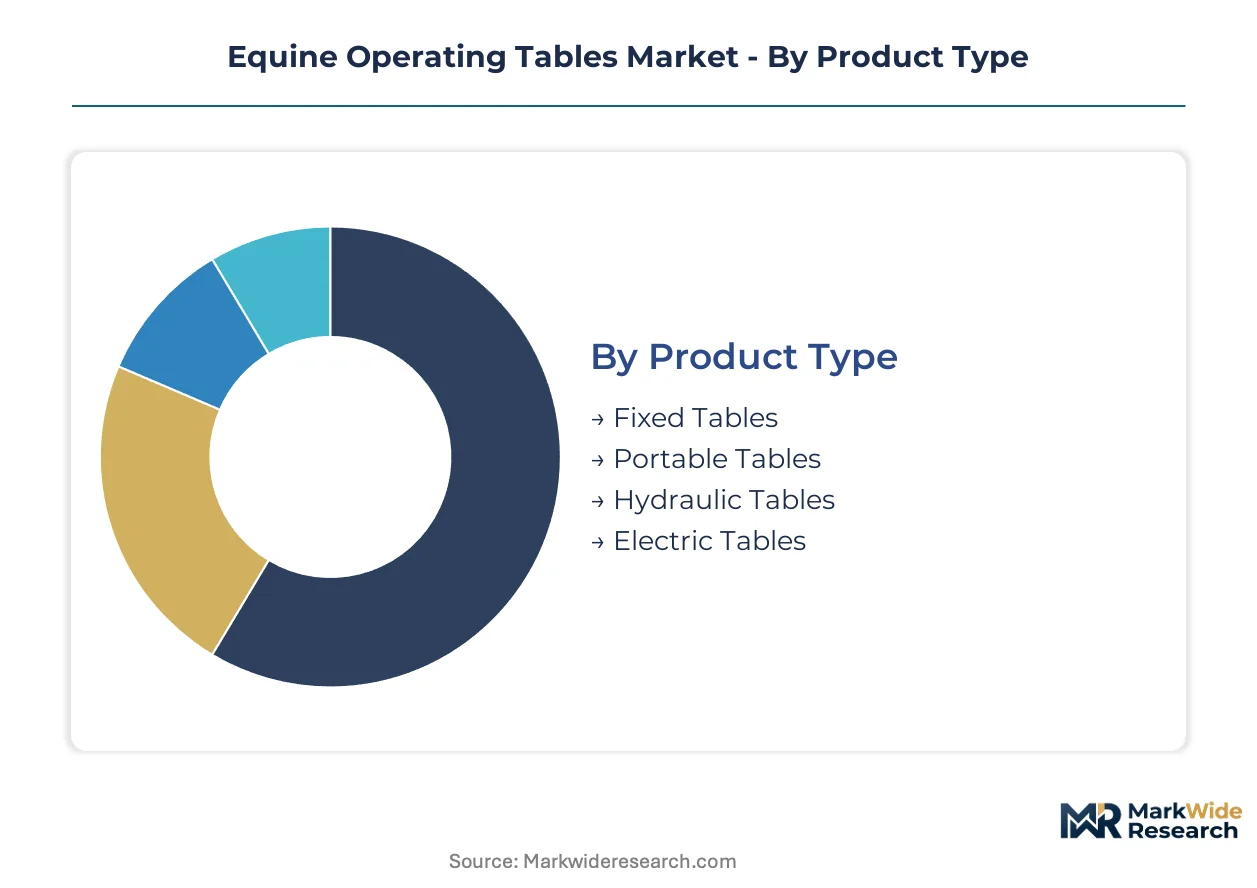
Equine operating tables serve divergent clinical workflows spanning stationary surgical suites and ambulatory field services. Understanding how product configurations, user settings, material choices, and feature sets intersect reveals where capital investment concentrates and where technology substitution accelerates.
Product Type:
Use cases span permanent installations in referral hospitals to transportable platforms for on-site emergency procedures.
- Hydraulic Tables:Lift mechanisms using fluid pressure systems sustain 1,200-kilogram loads with proven field reliability. Large-animal referral hospitals in Texas and Kentucky favor these for orthopedic suites where uninterrupted power during lengthy procedures is non-negotiable.
- Electric Tables:Servo-motor positioning enables millimeter-precise adjustments and programmable height memory. Academic veterinary centers absorb premium pricing to integrate these with digital surgical workflow systems.
- Fixed Tables:Stationary platforms with manual adjustment dominate budget-constrained municipal clinics.
- Portable Tables:Collapsible aluminum-frame designs address mobile veterinary services in rural Australia.
Established volume favors hydraulic tables; emerging adoption favors electric tables.
End User:
Capital intensity and procedure throughput determine equipment specifications across facility types.
- Animal Hospitals:Multi-specialty institutions perform 200+ equine surgeries annually, justifying radiolucent tabletops and integrated anesthesia delivery systems. These facilities drive replacement demand as imaging compatibility requirements tighten.
- Mobile Clinics:Ambulatory services in Kentucky's Thoroughbred breeding regions require sub-150-kilogram transport weight and rapid setup capability. Aluminum construction and battery-independent hydraulics address field power constraints.
- Veterinary Clinics:Single-practitioner operations prioritize cost containment over feature depth.
- Research Institutions:University laboratories demand ISO 10993-certified surfaces for longitudinal studies.
Replacement cycles concentrate in animal hospitals; steepest expansion trajectory belongs to mobile clinics.
Material:
Weight, sterilization compatibility, and corrosion resistance drive material selection trade-offs.
- Stainless Steel:Surgical-grade 316L alloys dominate installed bases for autoclave tolerance and structural longevity. German manufacturers leverage Baden-Württemberg precision engineering clusters to maintain supply continuity.
- Composite Materials:Carbon-fiber tabletops collapse weight-to-strength ratios for intraoperative imaging without sacrificing load capacity. University centers in the United States are adopting these fastest for orthopedic specialization.
- Aluminum:Mobile clinic configurations favor this for transport weight reduction.
- Plastic:Limited to disposable surface overlays and non-structural components.
Stainless steel anchors current procurement; composite materials gain share fastest in premium segments.
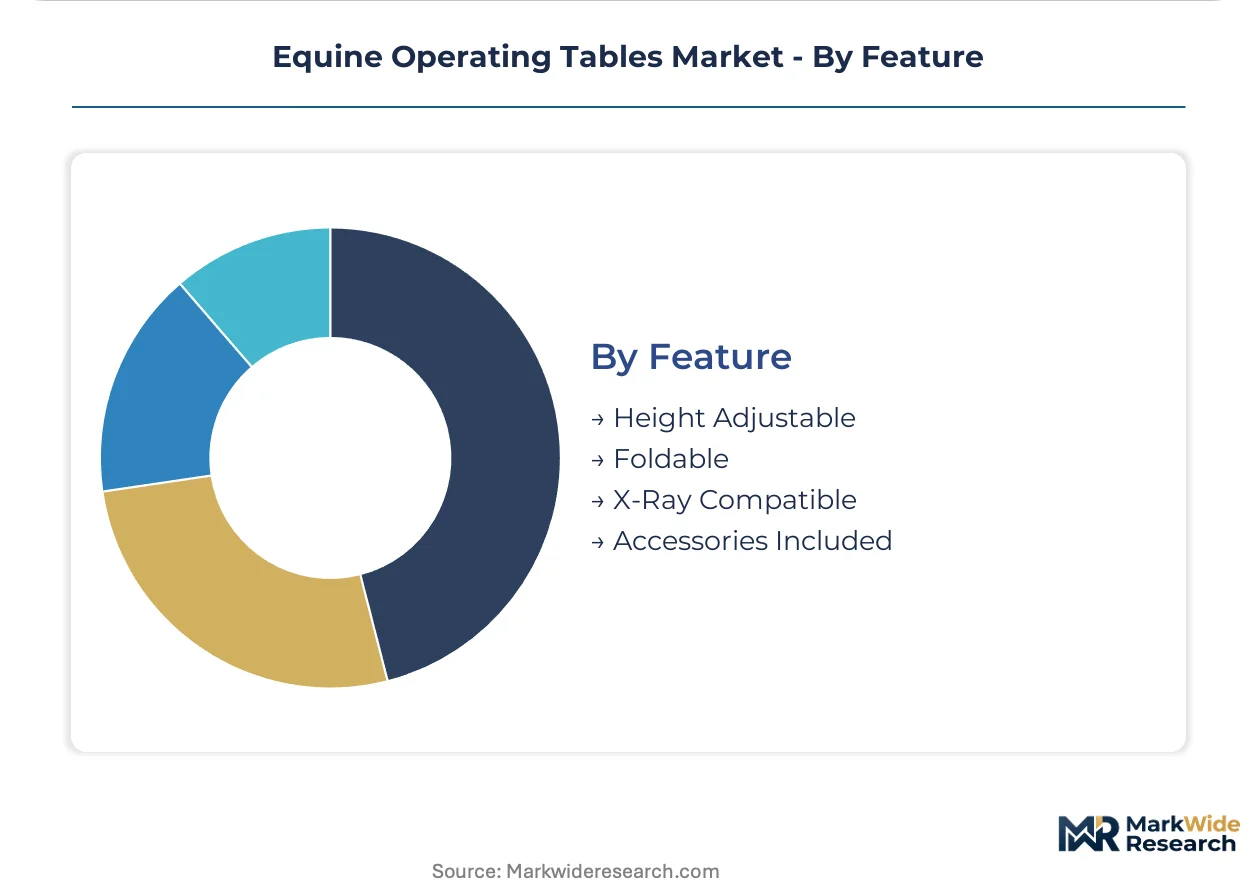
Feature:
Functional specifications separate baseline utility from premium positioning capability.
- X-Ray Compatible:Radiolucent tabletops enable fluoroscopy and digital radiography without patient repositioning. Large-animal hospitals in the United States outfit dedicated surgical suites with these for fracture repair and implant placement.
- Height Adjustable:Electric or hydraulic vertical travel protects surgical staff from musculoskeletal injury during 1,200-kilogram patient positioning. EU ergonomic directives are accelerating mandatory adoption in Germany and France.
- Accessories Included:Integrated anesthesia arms and traction apparatus bundle operational readiness.
- Foldable:Collapsible designs address storage constraints in multi-purpose treatment rooms.
Height adjustability approaches universal expectation; X-ray compatibility separates premium procurement tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine guidelines shape procurement standards in the United States, while EU Medical Device Regulation compliance costs are redistributing competitive advantage toward domestic European engineering clusters.
United States
Large-animal referral hospitals in Texas and Kentucky drive replacement demand for radiolucent orthopedic suites. The FDA Center for Veterinary Medicine mandates device safety documentation for intraoperative imaging compatibility. Lexington's Thoroughbred medical corridor concentrates procurement authority for multi-site equine networks.
Germany
Baden-Württemberg precision engineering clusters supply surgical-grade hydraulic components to Western European veterinary networks. EU Medical Device Regulation clinical evidence requirements compress registration timelines for legacy table upgrades. Stuttgart-area fabricators absorb biocompatibility testing investments that offshore competitors cannot match.
France
ANSM oversight of veterinary device conformity assessment adds national certification layers beyond EU baseline requirements. REACH substance restrictions force reformulation of anti-corrosion surface coatings used in surgical table construction. Lyon veterinary teaching hospitals anchor demand for ISO 10993-certified research platforms.
United Kingdom
Post-Brexit divergence from EU Medical Device Regulation creates parallel registration pathways for tables sold across Northern Ireland and Great Britain. The Veterinary Medicines Directorate maintains distinct device oversight frameworks. Newmarket's equine racing medical infrastructure sustains specialized surgical equipment procurement.
Australia
TGA therapeutic goods classification governs import approval for radiolucent tabletops used in university veterinary centers. Mobile clinic expansion in Queensland and New South Wales drives aluminum-frame demand for ambulatory field services. Sydney's large-animal referral networks standardize on carbon-fiber composite configurations for imaging-intensive procedures.
Equine Operating Tables Market Competitive Landscape
Capability concentration sits with precision engineering specialists; scale advantage sits with diversified veterinary equipment conglomerates. The market structures around three tiers: domestic European fabricators with MDR compliance integration, North American distributors with extensive dealer networks, and mobile-specialist manufacturers with weight-optimized aluminum platforms. Consolidation pressure favors M&A activity among mid-tier hydraulic component suppliers, while portfolio diversification into aftermarket service contracts separates recurring revenue models from pure capital sales.
Among European precision fabricators, Haico leverages its domestic manufacturing base to sustain export positioning across Western Europe. Jørgen Kruuse A/S occupies a specialist tier serving Scandinavian welfare-standard configurations. Midmark Corporation represents the scale-driven North American distribution archetype, anchoring procurement relationships through multi-site veterinary network contracts.
| Leading Market Players |
|---|
| Haico |
| Shank's Veterinary Equipment |
| Autoquip Corporation |
| Jørgen Kruuse A/S |
| Midmark Corporation |
| DRE Veterinary |
| Pedigo |
| Suburban Surgical |
| Jorgensen Laboratories |
| Others |
Supply & Pricing Matrix
Baden-Württemberg precision engineering clusters supply surgical-grade hydraulic components to Western European veterinary equipment fabricators, anchoring margin capture with domestic manufacturers who absorb EU Medical Device Regulation compliance costs that offshore competitors cannot match. This upstream concentration funnels pricing power toward German and French producers while compressing margins for mid-tier assemblers dependent on imported subsystems.
Pricing Analysis
North American electric tables command 40-60% premiums over hydraulic equivalents sold in municipal clinics, with three-tier pricing structure across premium, standard, and economy levels separating academic medical centers from budget-constrained single-practitioner operations. Price differentiation hinges on ISO 10993 certification grade and after-sales service bundling, with stainless steel input cost volatility intensifying cost compression in mid-tier segments. Large-animal referral hospitals in Texas and Kentucky exhibit lowest price sensitivity due to orthopedic specialization requirements, while mobile clinics in rural Australia face acute budget constraints.
Supply Chain Analysis
Contract manufacturing for precision hydraulic cylinders concentrates with Baden-Württemberg metalworking specialists and Scandinavian fabrication houses serving Jørgen Kruuse A/S, while aluminum frame production draws from Chinese and Turkish extrusion facilities. Raw material dependencies center on surgical-grade 316L stainless steel from German mills, carbon-fiber prepregs from Japanese suppliers, and certified coating formulations subject to REACH substance restrictions. Single-source vulnerability in hydraulic component sourcing creates geographic concentration risk. Distribution runs through specialized veterinary equipment dealers in North America and direct manufacturer relationships in European hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary surgical equipment fabrication demands rare combinations of large-animal biomechanical engineering expertise and medical device regulatory navigation, creating capability gaps that constrain competitive entry and sustain incumbent advantage.
For Market Incumbents: Harden supply chain resilience by securing captive capacity at Baden-Württemberg precision engineering clusters before MDR compliance timelines compress further, and deepen backward integration into surgical-grade stainless steel processing to defend margin structures against alloy price volatility. Carbon-fiber tabletop substitution from Asian suppliers threatens premium positioning; counter through exclusive university hospital partnerships that lock in technology refresh cycles. For New Entrants and Emerging Players: Build out aluminum-frame portable configurations for Kentucky and Queensland mobile clinics where incumbent coverage remains thin, exploiting transport-weight requirements that established hydraulic specialists have underinvested in. Target ambulatory equine services with battery-independent hydraulic systems and rapid-setup designs. Go-to-market should route through regional veterinary purchasing cooperatives rather than direct hospital sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier hydraulic component suppliers serving German veterinary OEMs, where MDR-driven consolidation pressure creates roll-up opportunities. Five-to-ten year viability rests on aftermarket service contract penetration rather than capital sales cyclicality. Monitor carbon-fiber composite adoption rates at US university centers as inflection indicator for technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Integration | CE marking pathways for legacy hydraulic systems open German and French procurement channels. |
| Carbon-Fiber Platform Development | Radiolucent tabletops capture orthopedic specialization demand at US academic centers. |
| Aftermarket Service Unbundling | Maintenance contracts separate recurring revenue from capital replacement cycles. |
| Mobile Clinic Configuration | Aluminum-frame designs address transport constraints in Kentucky Thoroughbred regions. |
| University Hospital Partnership | Technology refresh schedules compress from twelve-year to seven-year intervals. |
Research Methodology
Cross-validation between primary interviews with equine surgical specialists, veterinary equipment procurement managers, and biomedical engineers and secondary validation through FDA Center for Veterinary Medicine device registrations, EU MDR conformity assessment databases, and hospital capital expenditure records anchors the qualitative findings. Bottom-up triangulation from installed base estimates and top-down calibration against veterinary clinic census data ensures coverage integrity.
Calibration against historical replacement cycles and technology diffusion patterns across the projection horizon informs the analytical framework. Segmentation dimensions span product type, end-user facility tier, material specification, and feature configuration, with CAGRs derived from regression against veterinary procedure volume trends and capital equipment spending patterns. ISO 10993 certification timelines and MDR registration friction serve as industry-specific forecast inputs.
Stress conditions across stainless steel price volatility, MDR implementation delays, and veterinary surgical technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory enforcement intensity. Quarterly review of university center procurement announcements and REACH substance list updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical CO2 Carboxytherapy Machine Market
Medical Equipment
Next Generation Centrifuge Market
Medical Equipment
Cell Washer Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Operating Light Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Global Oxygen Flow Meters Market
Medical Equipment
Global Optometry Equipment Market
Medical Equipment
Medical Oxygen Systems Market
Medical Equipment
Global Countertop Platelet Incubator Market
Medical Equipment
CO2 Medical Laser Systems Market
Medical Equipment
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
Global Plasma Sterilizers Market
Medical Equipment
Medical Ultrasonic Cleaners Market