
 Global Heart Rate Monitor Market | 2026-2036
Global Heart Rate Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Heart Rate Monitor Market Foresight
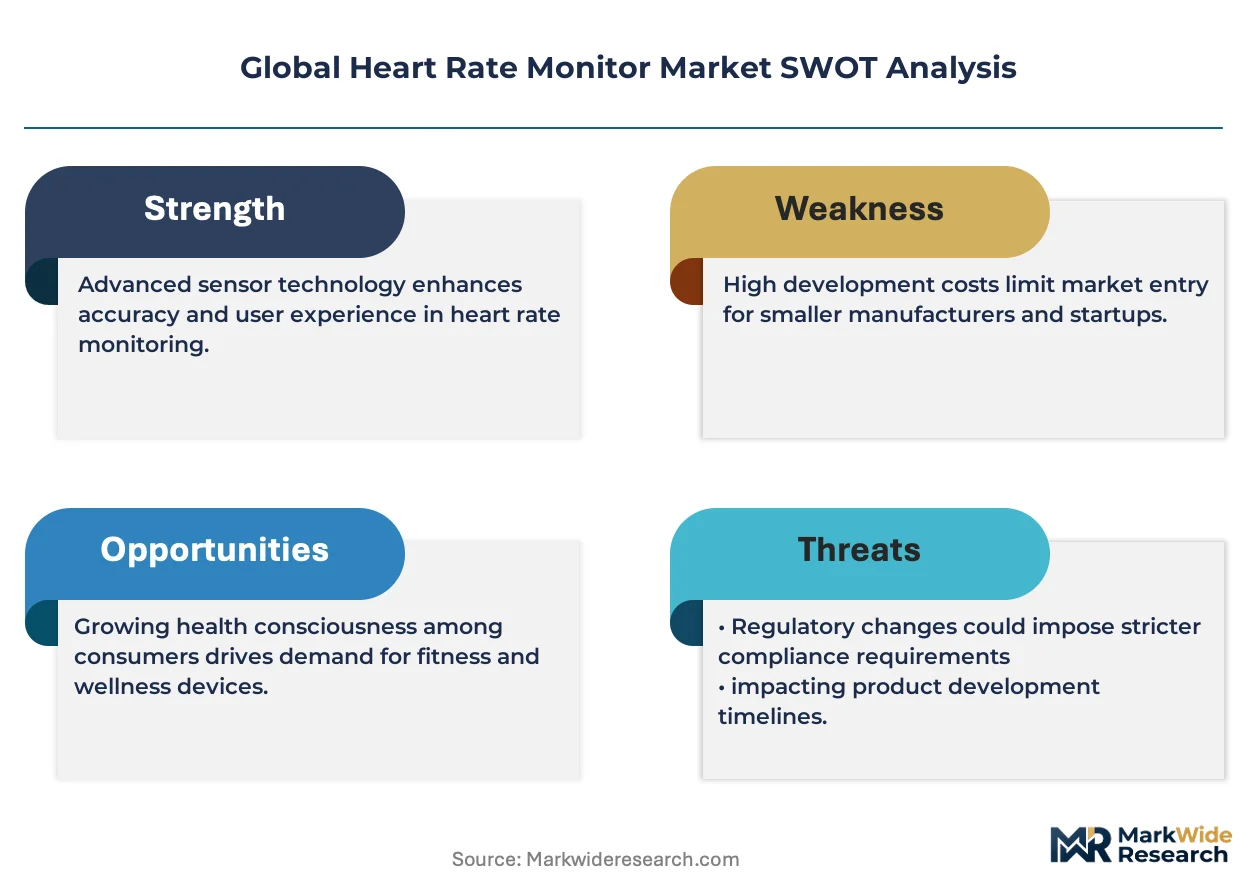
China's manufacturing corridor for consumer wearables is rewriting cost structures across the heart rate monitor supply chain. Apple leverages its silicon design to sustain premium positioning in wrist-worn optical devices. Garmin anchors the sports performance segment with specialized chest strap and multi-sensor ecosystems. Samsung competes through combined sensor integration across its smartwatch portfolio.
A heart rate monitor is a photoplethysmography or electrocardiography-based device that detects pulse intervals through LED-optical or electrical conductive methods, typically achieving accuracy within one to five beats per minute under controlled motion states. Its primary commercial purpose spans fitness optimization, cardiac rehabilitation oversight, and longitudinal wellness data collection for insurers and employers. Wrist-worn products now dominate volume shipments while chest strap configurations retain superior accuracy for elite sports performance applications. Optical sensor technology leads unit economics due to miniaturization, though combined sensor architectures command premium positioning in clinical research settings where signal fidelity requirements are stringent.
The FDA regulates heart rate monitors as Class II medical devices when marketed for diagnostic purposes, while the EU MDR requires notified body intervention for clinical claim substantiation. China's NMPA has accelerated review pathways for wearable health devices under revised digital therapeutics guidelines. Japan's PMDA maintains stricter electrical safety standards that filter non-compliant imports. Stakeholders must monitor evolving regulatory divergence between wellness and medical classifications to avoid market access delays.
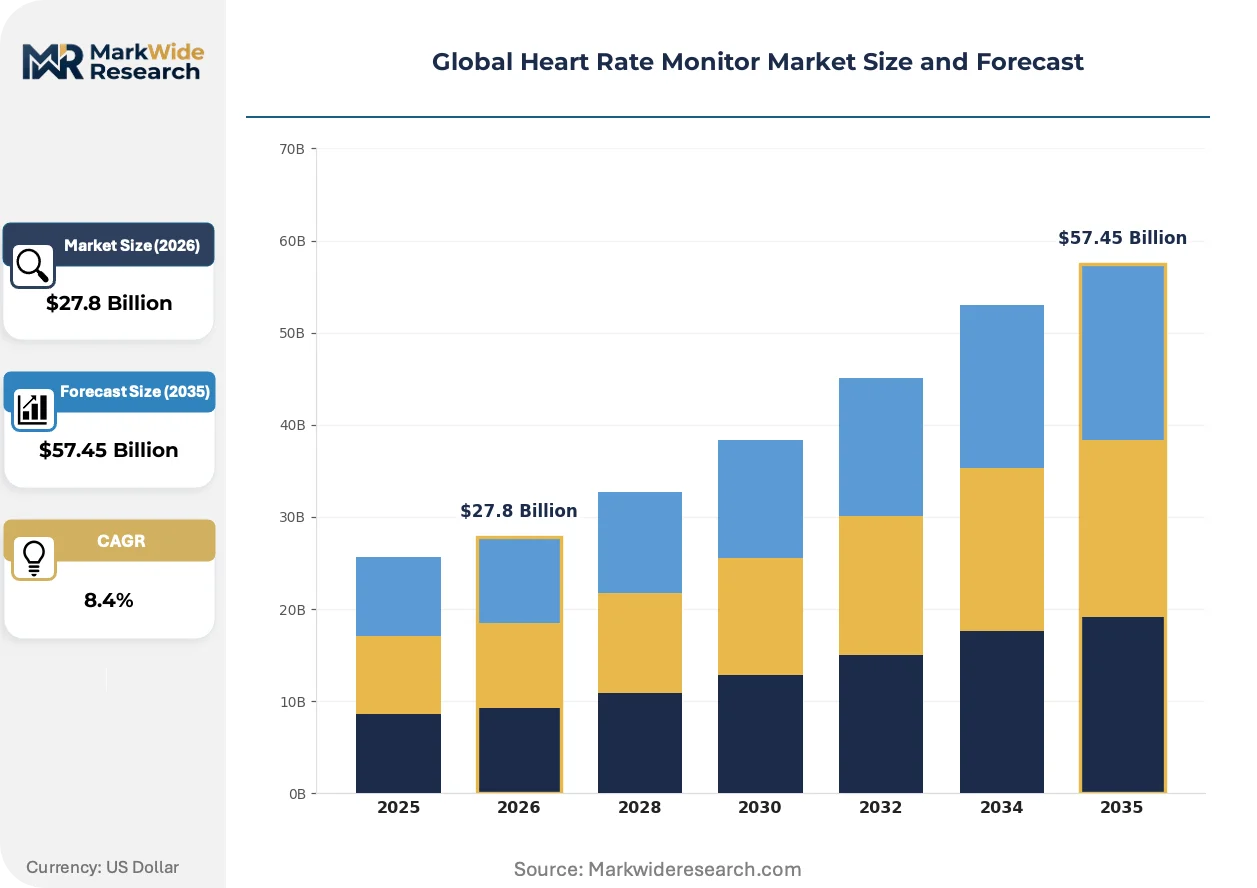
Market Dynamics
Optical photoplethysmography (PPG) sensors are compressing unit economics while regulatory frameworks in the US and EU bifurcate wellness from medical-grade claims, forcing manufacturers to choose between consumer volume and clinical validation pathways.
Growth Catalysts
- Fitness tracker proliferation:Wrist-worn devices with multi-wavelength LED arrays are capturing recreational athlete segments previously served by chest straps. The EU MDR's digital health fast-track provisions are accelerating notified body reviews for validated optical systems.
- Insurer wellness programs:Employer-sponsored longitudinal health monitoring is creating institutional procurement channels. India's PLI scheme for wearable electronics manufacturing is attracting component suppliers to Gujarat and Tamil Nadu corridors.
- Cardiac rehabilitation outsourcing:Post-acute care facilities are adopting remote patient monitoring to reduce readmission penalties. China's NMPA has streamlined Class II registrations for home-use heart rate devices under revised digital therapeutics guidelines.
Market Restraints
- Optical accuracy degradation:PPG signal fidelity collapses under high-motion states and melanin-rich skin tones, limiting addressable populations for single-sensor architectures without ECG corroboration.
- Component supply concentration:High-precision accelerometers and specialized optical emitters depend on Taiwanese and South Korean foundry capacity, exposing lead time volatility during semiconductor allocation cycles.
- FDA diagnostic classification friction:Devices marketed for arrhythmia detection trigger Class II medical device requirements, imposing 510(k) submission costs and clinical trial burdens that exclude smaller hardware startups.
Strategic Opportunities
- Rural India penetration:Sub-$20 optical wristbands distributed through pharmacy networks and telecom retail partnerships can capture first-time wearable users outside metropolitan centers.
- Multi-modal sensor fusion:Combining PPG with bioimpedance and temperature sensing enables sleep apnea screening and stress load quantification for corporate wellness contracts.
- Japan's PMDA electrical safety harmonization:Compliance with JIS T 0601-1 standards opens premium positioning for clinical-grade wearables in aging population home care markets.
Industry Challenges
- Biomedical signal processing talent scarcity:Algorithm development for motion artifact rejection requires rare cross-training in electrical engineering and physiology, constraining R&D velocity at mid-tier manufacturers.
- EU MDR notified body queue congestion:Clinical claim substantiation now faces 12-18 month review timelines, delaying product launches and compressing effective patent life for validated devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Heart Rate Monitor Market |
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $57.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wrist-worn, Chest strap, Ear clip, Finger sensor Technology: Optical sensor, Electrical sensor, Combined sensor, Radio frequency sensor Application: Fitness tracking, Wellness monitoring, Clinical research, Sports performance End User: Athletes, Research institutions, Gyms & fitness centers, Personal users |
| Companies Covered | Apple, Garmin, Polar Electro, Fitbit, Samsung, Withings, Omron, Suunto, Wahoo Fitness, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Heart Rate Monitor Market Shifts & Advancements
Sensor architecture decisions are becoming strategic differentiators as manufacturers balance cost, accuracy, and regulatory burden across diverging wellness and clinical market segments.
Multi-wavelength PPG arrays with green and infrared LED combinations are migrating from flagship smartwatches into mid-tier fitness bands. Sports performance clinics and occupational health departments are adopting these configurations for 24-hour autonomic monitoring. The technology is migrating from premium positioning toward standard equipment in corporate wellness procurement, compressing margins for single-sensor competitors.
The EU MDR's Article 117 software classification rules are redefining boundary conditions for algorithm-driven health claims. Devices with arrhythmia detection capabilities now require notified body intervention regardless of hardware simplicity. Cardiac rehabilitation service providers in Germany and the Netherlands are restructuring supplier contracts to exclude non-MDR-certified devices from reimbursement pathways.
Direct-to-employer contracting is displacing traditional retail and distributor channels for enterprise wellness deployments. Benefits administrators at Fortune 500 manufacturers are negotiating multi-year sensor provisioning agreements with outcome-based fee structures. This pattern is most visible in US automotive and logistics sectors where DOT medical certification requirements intersect with fleet safety programs.
Global Heart Rate Monitor Market Segmentation
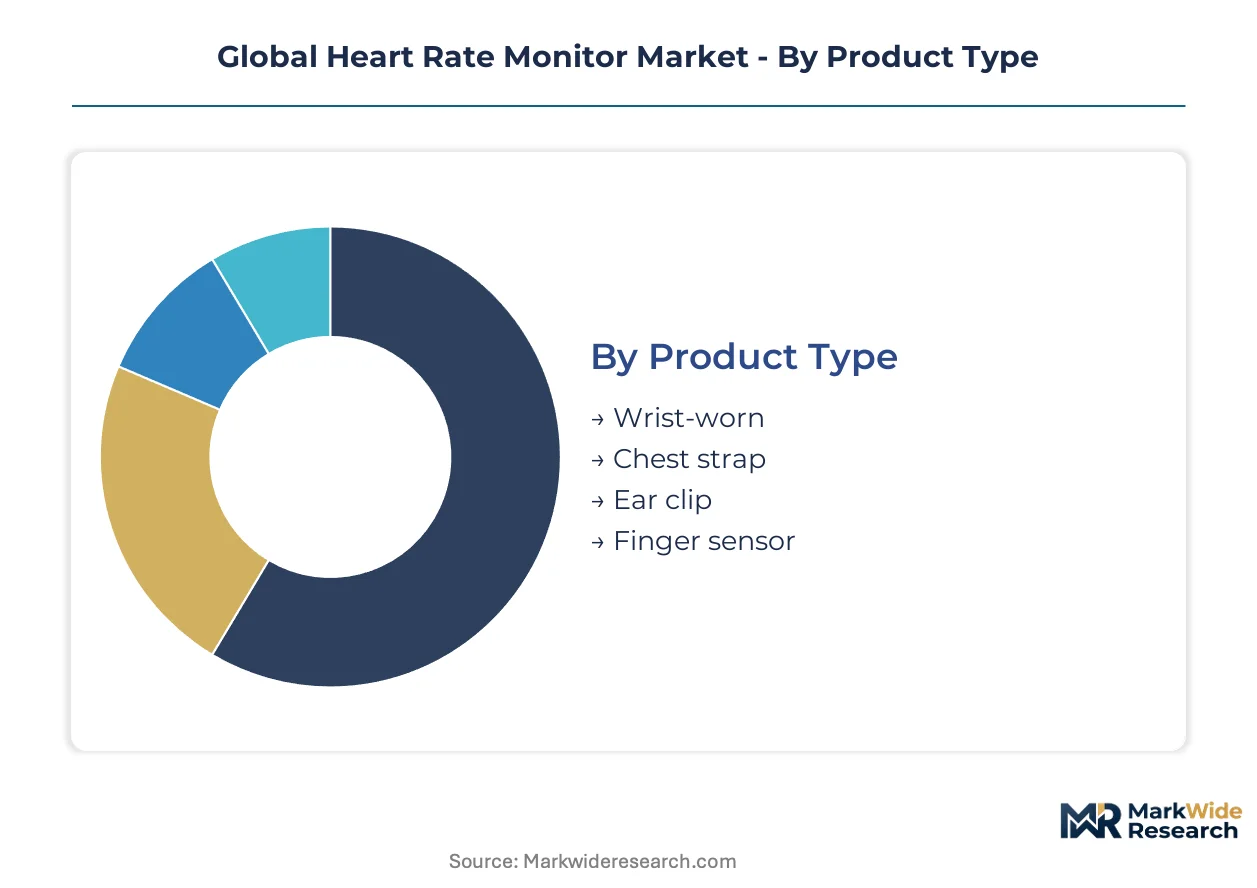
Heart rate monitor segmentation reflects a market bifurcating between wellness convenience and clinical precision. Manufacturers optimize sensor architectures, form factors, and validation pathways to serve diverging end-use requirements across consumer fitness and medical monitoring domains.
Product Type:
Mature wrist-worn configurations dominate unit economics while emerging ear clip designs test miniaturization boundaries.
- Wrist-worn:Multi-wavelength LED arrays integrated into watch-style housings capture recreational athlete demand through all-day comfort and smartphone connectivity. China's manufacturing corridor in Shenzhen and Dongguan compresses bill-of-materials costs for sub-$50 retail positioning.
- Chest strap:Electrode-based conductive sensors deliver ECG-grade accuracy within one beat per minute for elite training protocols. Garmin and Polar anchor professional sports team procurement through validated signal fidelity under maximal exertion states.
- Ear clip:Photoplethysmography modules positioned at the earlobe exploit vascular density for improved perfusion signal quality during high-motion activities.
- Finger sensor:Pulse oximetry-derived architectures serve spot-check clinical applications and home-based cardiac rehabilitation monitoring.
Wrist-worn handles the majority of throughput; ear clip is the fastest mover on share.
Technology:
Cost tier stratification separates validated clinical systems from consumer-grade optical implementations.
- Optical sensor:Green and infrared LED photoplethysmography enables sub-$30 retail price points through semiconductor miniaturization. Melanin-related signal attenuation and motion artifact degradation constrain accuracy claims for darker skin tones and high-impact activities.
- Electrical sensor:Dry electrode chest strap configurations retain gold-standard status for arrhythmia detection and HRV analysis in cardiac rehabilitation settings. FDA Class II diagnostic classification requirements limit commercialization to established medical device manufacturers.
- Combined sensor:Fusion architectures integrating PPG, bioimpedance, and accelerometer inputs command premium positioning for sleep apnea screening and autonomic nervous system assessment.
- Radio frequency sensor:Radar-based contactless heart rate detection eliminates wearability constraints for infant monitoring and driver fatigue applications.
Optical sensor handles the majority of throughput; combined sensor is climbing the fastest on share.
Application:
Volume concentration in fitness tracking contrasts with margin concentration in clinical research deployments.
- Fitness tracking:Caloric expenditure estimation and zone-based training guidance drive consumer wearable procurement through employer wellness subsidies and insurer incentive programs.
- Wellness monitoring:Longitudinal stress load quantification and recovery metrics serve corporate human capital management contracts in US automotive and logistics sectors.
- Clinical research:FDA 21 CFR Part 11-compliant data logging and GCP validation support pharmaceutical trials and digital therapeutic efficacy studies.
- Sports performance:Real-time lactate threshold estimation and training load optimization anchor professional team and Olympic federation procurement.
Fitness tracking handles the majority of throughput; clinical research is gaining share fastest.
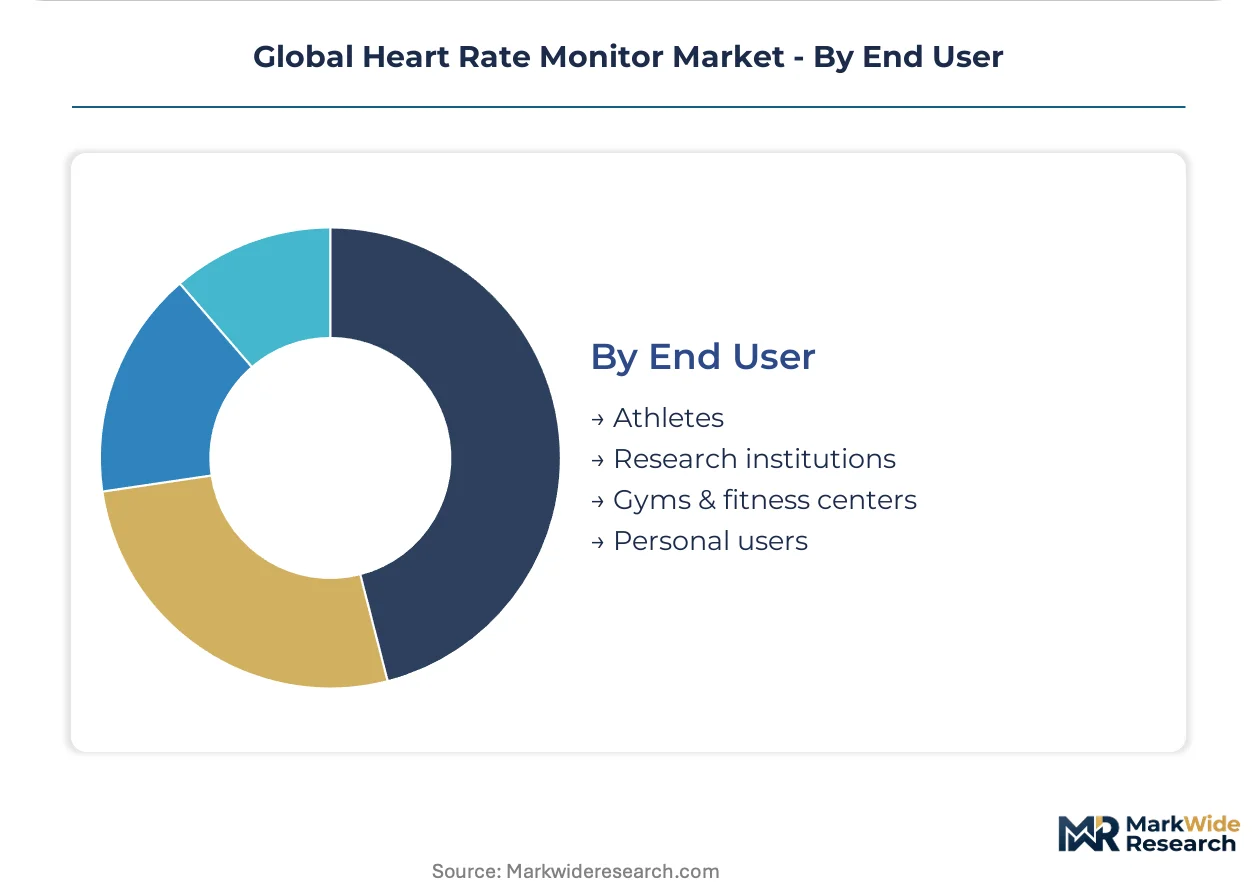
End User:
Customer type fragmentation spans institutional procurement discipline and individual purchase spontaneity.
- Personal users:Direct-to-consumer retail and e-commerce channels dominate, with India's pharmacy network distribution and telecom bundling emerging as novel penetration vectors for first-time wearable adoption.
- Athletes:Amateur to professional competitive segments demand validated accuracy for training periodization, with sports performance clinics in Germany and Australia specifying multi-sensor ecosystems.
- Research institutions:Academic medical centers and contract research organizations require ISO 14155-compliant devices with audit trail capabilities for regulatory submission support.
- Gyms & fitness centers:Commercial equipment integration and member subscription bundling create B2B procurement channels distinct from individual device retail.
Personal users handle the majority of throughput; research institutions are expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component foundries in Taiwan and South Korea concentrate precision sensor supply, while final assembly clusters in China's Pearl River Delta and India's Tamil Nadu corridor reshape finished device economics.
United States
Employer wellness subsidies and insurer incentive programs drive enterprise procurement volumes. FDA Class II diagnostic classification requirements constrain arrhythmia detection claims to validated manufacturers. The Greater Boston corridor hosts cardiac rehabilitation technology developers integrating remote patient monitoring platforms.
China
First-time wearable adoption through pharmacy networks and telecom retail bundling accelerates penetration outside tier-one cities. NMPA streamlined Class II registrations for home-use devices under revised digital therapeutics guidelines. Shenzhen and Dongguan manufacturing clusters compress bill-of-materials costs for sub-$50 retail positioning.
Germany
Cardiac rehabilitation service providers restructure supplier contracts to exclude non-MDR-certified devices from reimbursement pathways. EU MDR notified body intervention now applies to algorithm-driven arrhythmia detection regardless of hardware simplicity. Munich and Stuttgart anchor sports performance clinic procurement for multi-sensor ecosystems.
India
PLI scheme incentives for wearable electronics manufacturing attract component suppliers to Gujarat and Tamil Nadu corridors. Sub-$20 optical wristbands distributed through pharmacy networks capture first-time users outside metropolitan centers. Bangalore hosts algorithm development operations for motion artifact rejection signal processing.
Japan
Aging population home care markets create demand for clinical-grade wearables compliant with JIS T 0601-1 electrical safety standards. PMDA maintains stricter filtering of non-compliant imports than regional counterparts. Tokyo and Osaka metropolitan areas concentrate rehabilitation facility procurement for longitudinal monitoring contracts.
Global Heart Rate Monitor Market Competitive Landscape
Silicon-integrated platform developers and specialized sports performance equipment manufacturers split the market between consumer volume and professional accuracy segments. The competitive structure consolidates around three archetypes: consumer technology conglomerates with captive semiconductor design, dedicated fitness wearable specialists with validated sensor ecosystems, and medical device incumbents with diagnostic regulatory clearance. Dominant competitive moves include strategic component supply partnerships with Taiwanese foundries and portfolio diversification into multi-modal biometric sensing.
Within the consumer technology tier, Apple and Samsung exemplify silicon-integrated positioning through proprietary optical sensor architectures. Garmin anchors the specialized sports performance archetype with chest strap and multi-sensor ecosystem offerings. Polar Electro occupies a position between professional and consumer segments with validated accuracy claims for training applications.
| Leading Market Players |
|---|
| Apple |
| Garmin |
| Polar Electro |
| Fitbit |
| Samsung |
| Withings |
| Omron |
| Suunto |
| Wahoo Fitness |
| Others |
Supply & Pricing Matrix
Taiwanese and South Korean foundry capacity for high-precision accelerometers and specialized optical emitters anchors margin capture at the component tier, while downstream pricing power fragments across wellness and clinical validation pathways. Optical sensor miniaturization compresses bill-of-materials costs for wrist-worn configurations, yet FDA Class II diagnostic requirements impose premium pricing tiers for arrhythmia-capable devices.
Pricing Analysis
FDA and EU MDR classification frameworks dictate the pricing tier structure across consumer wellness and clinical-grade segments. Three-tier pricing structure across premium, standard, and economy levels separates validated multi-sensor ecosystems from single-LED fitness bands and sub-$20 pharmacy-distributed units. Price differentiation hinges on certification grade and signal fidelity validation, with clinical research procurement showing lowest price sensitivity and rural Indian first-time buyers exhibiting highest elasticity. Cost compression in mid-tier optical bands is intensifying because Shenzhen manufacturing clusters are absorbing LED array cost declines into retail positioning.
Supply Chain Analysis
Specialized optical emitters and MEMS accelerometers draw from Taiwanese foundry capacity and South Korean semiconductor fabrication, with final assembly concentrating in China's Pearl River Delta and India's Tamil Nadu corridor. Bill-of-materials dependencies center on multi-wavelength LED arrays, bioimpedance electrodes, and precision motion sensors. Single-source vulnerability in Taiwanese accelerometer supply exposes lead time volatility during semiconductor allocation cycles. Distribution runs through direct-to-employer contracting for enterprise wellness deployments, pharmacy network partnerships in India, and traditional retail channels for consumer fitness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical photoplethysmography disruption is accelerating market bifurcation between wellness volume and clinical validation, with EU MDR Article 117 software classification rules compressing effective commercialization windows for algorithm-driven health claims.
For Market Incumbents: Insulate core positioning through captive semiconductor design partnerships with Taiwanese foundries and accelerated MDR certification investment for multi-modal sensor architectures. Chest strap accuracy leadership faces substitution threat from multi-wavelength PPG migration into mid-tier bands, requiring defensive portfolio diversification into combined sensor ecosystems for sleep apnea and autonomic monitoring applications. For New Entrants and Emerging Players: Establish a beachhead in rural Indian pharmacy network distribution for sub-$20 optical wristbands targeting first-time wearable adoption outside metropolitan centers. White-space concentration in corporate wellness direct-to-employer contracting offers procurement channel bypass of saturated retail, with outcome-based fee structures aligning vendor economics with employer health cost reduction objectives. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed sports performance equipment specialists holding validated sensor ecosystems but lacking consumer scale infrastructure. Long-term viability over the projection horizon favors platforms with regulatory clearance moats and algorithm development capabilities in motion artifact rejection. Signal to monitor: EU MDR notified body queue congestion duration as indicator of competitive entry barrier height.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Modal Sensor Fusion Development | Combining PPG with bioimpedance enables sleep apnea screening for corporate wellness contracts. |
| EU MDR Notified Body Certification | Article 117 compliance secures reimbursement pathway access in German cardiac rehabilitation markets. |
| Pharmacy Network Distribution Partnership | India's sub-$20 wristband channel captures first-time users outside tier-one metropolitan centers. |
| Direct-to-Employer Contracting Model | Outcome-based fee structures align vendor economics with Fortune 500 health cost reduction programs. |
| Silicon-Integrated Optical Architecture | Proprietary LED array design sustains premium positioning against Shenzhen cost compression. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wearable device engineering leads, cardiac rehabilitation clinic procurement managers, employer benefits administrators, and biomedical signal processing specialists. Secondary validation drew from FDA 510(k) filings, EU MDR notified body registration databases, NMPA digital therapeutics guideline revisions, and customs trade data for optical sensor component flows. Bottom-up shipment estimates triangulated against top-down healthcare expenditure allocation models.
Calibration against historical regulatory approval timelines and sensor technology adoption curves anchored growth trajectory assumptions across the modeling period. Segmentation dimensions modeled include product form factor, sensor technology architecture, application endpoint, and end-user procurement channel. CAGRs were derived from slope-intercept fitting to validated baseline volumes and scenario-weighted regulatory pathway assumptions. Forecast inputs incorporated PLI scheme incentive absorption rates and employer wellness subsidy expansion patterns.
Sensitivities concentrate around EU MDR notified body queue duration, Taiwanese foundry capacity allocation volatility, and melanin-related PPG accuracy litigation risk. Cross-checking against hospital procurement database benchmarks and GPO contract award patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
Neurology Patient Monitoring Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Europe Cardiac Holter Monitor Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Global Multi-Parameter Patient Monitoring Equipment Market
Patient Monitoring
Middle East and Africa Cardiac Monitoring Market
Patient Monitoring
Wireless Healthcare Market
Patient Monitoring
Brain Tissue Oxygen Monitoring Systems Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
South America Remote Patient Monitoring Systems Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Central Patient Monitoring System Market
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
North America Respiratory Monitoring Market
Patient Monitoring
Wearable Patient Monitor Market