
 Enteral Feeding Devices Market | 2026-2036
Enteral Feeding Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Enteral Feeding Devices Market Analysis
Home care is expanding as the fastest-rising end-use vertical for enteral feeding devices, displacing traditional hospital-centric procurement patterns. Fresenius Kabi anchors European manufacturing scale for pump systems and disposable sets. Cardinal Health controls North American distribution channels for home care supplies. Abbott Laboratories differentiates through nutrition-device integration across its metabolic product portfolio.
Enteral feeding devices comprise pumps, administration sets, and patient access tubes designed to deliver liquid nutrition directly into the gastrointestinal tract, typically operating at flow rates between 1 and 400 mL per hour with occlusion pressure alarms and anti-free-flow safety mechanisms. Pumps command the dominant product type position due to programmable accuracy requirements in critical care settings. Home care represents the fastest-growing end user segment as payors shift reimbursement toward outpatient management. Oncology applications generate concentrated demand for long-term jejunal access devices in patients undergoing head and neck radiation protocols.
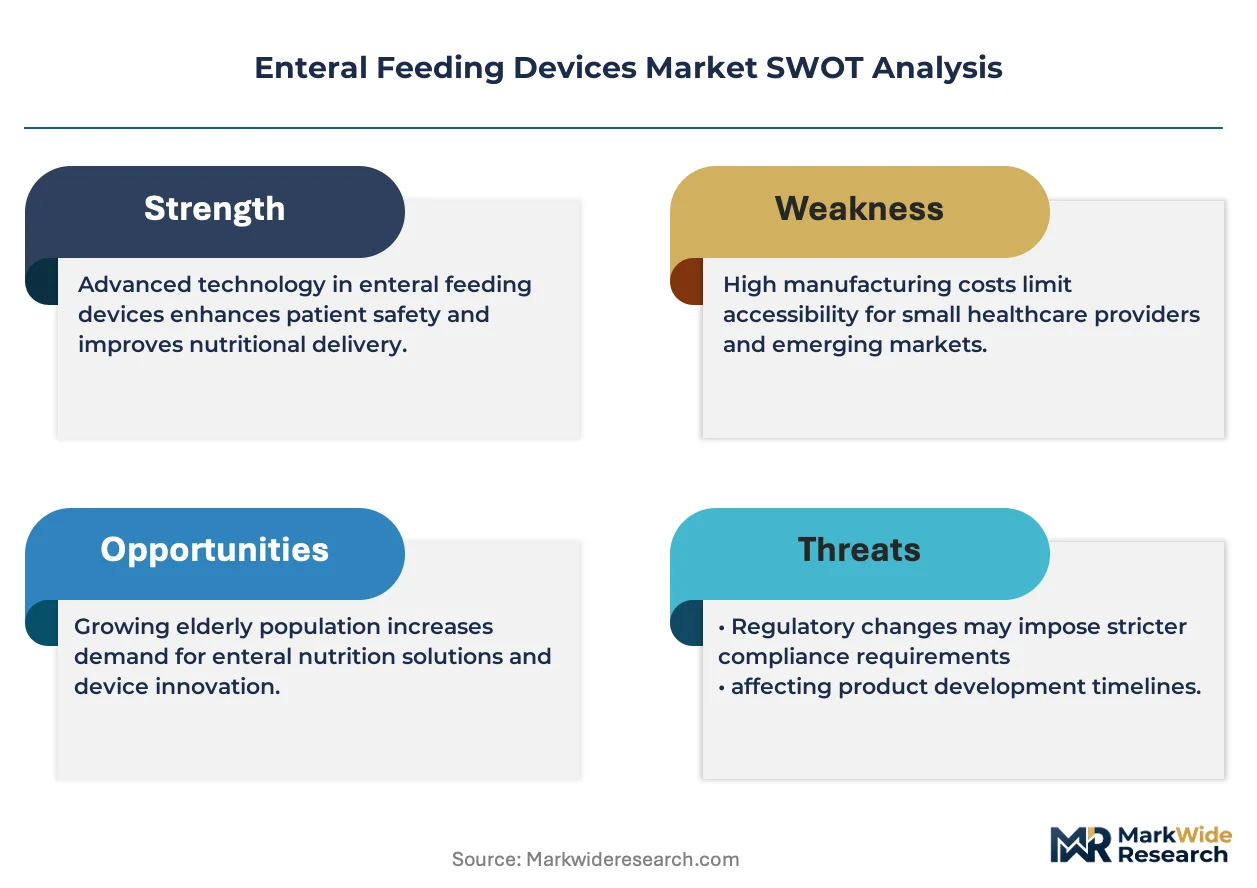
The FDA enforces ISO 80369-3 enteral connector standards to prevent lethal misconnections with intravenous or neuraxial systems, while the EMA's Medical Device Regulation imposes enhanced clinical evidence requirements for class IIa and above devices. The EPA and OSHA jointly influence material selection through biocompatibility and workplace exposure standards for silicone and polyurethane manufacturing. Stakeholders must monitor evolving reimbursement codes for home enteral nutrition across Medicare and private payors to align portfolio investments with coverage expansion trajectories.
Market Dynamics
The migration of enteral feeding from acute care to home settings is compressing equipment procurement cycles and forcing manufacturers to redesign pumps for non-clinical operators rather than ICU nurses.
Growth Catalysts
- Medicare home enteral nutrition coverage expansion:CMS reimbursement codes now cover pump rental and formula costs for ambulatory patients, accelerating discharge planning and durable medical equipment orders.
- ISO 80369-3 connector harmonization:The FDA-enforced enteral-specific Luer alternative eliminates lethal misconnection risks with IV systems, mandating fleet replacement across US hospital networks.
- Silicone elastomer biocompatibility advances:New platinum-cured formulations reduce tube-induced esophageal granulation tissue, extending indwell time for head and neck oncology patients.
Market Restraints
- Polyurethane raw material concentration:Medical-grade aromatic polyether supply chains cluster in German and Chinese chemical manufacturing zones, exposing device makers to input volatility.
- EMA MDR clinical evidence thresholds:Class IIa pump re-certification now requires post-market surveillance data that smaller EU manufacturers cannot fund without portfolio consolidation.
- Oral nutrition supplement substitution:High-protein medical foods capture borderline malnutrition cases that previously warranted nasogastric intervention, capping addressable patient populations.
Strategic Opportunities
- Japan's super-aged prefectures:Tochigi and Aomori demonstrate 35%+ population over 65 with minimal home infusion infrastructure, creating first-mover terrain for remote monitoring-integrated pump systems.
- Smartphone-connected bolus programming:Bluetooth-enabled dose calculators allow pediatric caregivers to adjust feeds without clinical visits, opening subscription revenue streams.
- India PLI scheme for medical devices:Domestic manufacturing incentives reduce import duty exposure for multinational tubing and pump assembly operations targeting South Asian price points.
Industry Challenges
- Biomedical technician scarcity:Home care agencies cannot hire personnel trained on enteral-specific occlusion alarm troubleshooting, forcing manufacturers to build predictive diagnostic firmware.
- Legacy hospital fleet interoperability:New ISO 80369-3 connectors fail to mate with existing administration sets in inventory, requiring costly dual-SKU bridging strategies during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enteral Feeding Devices Market |
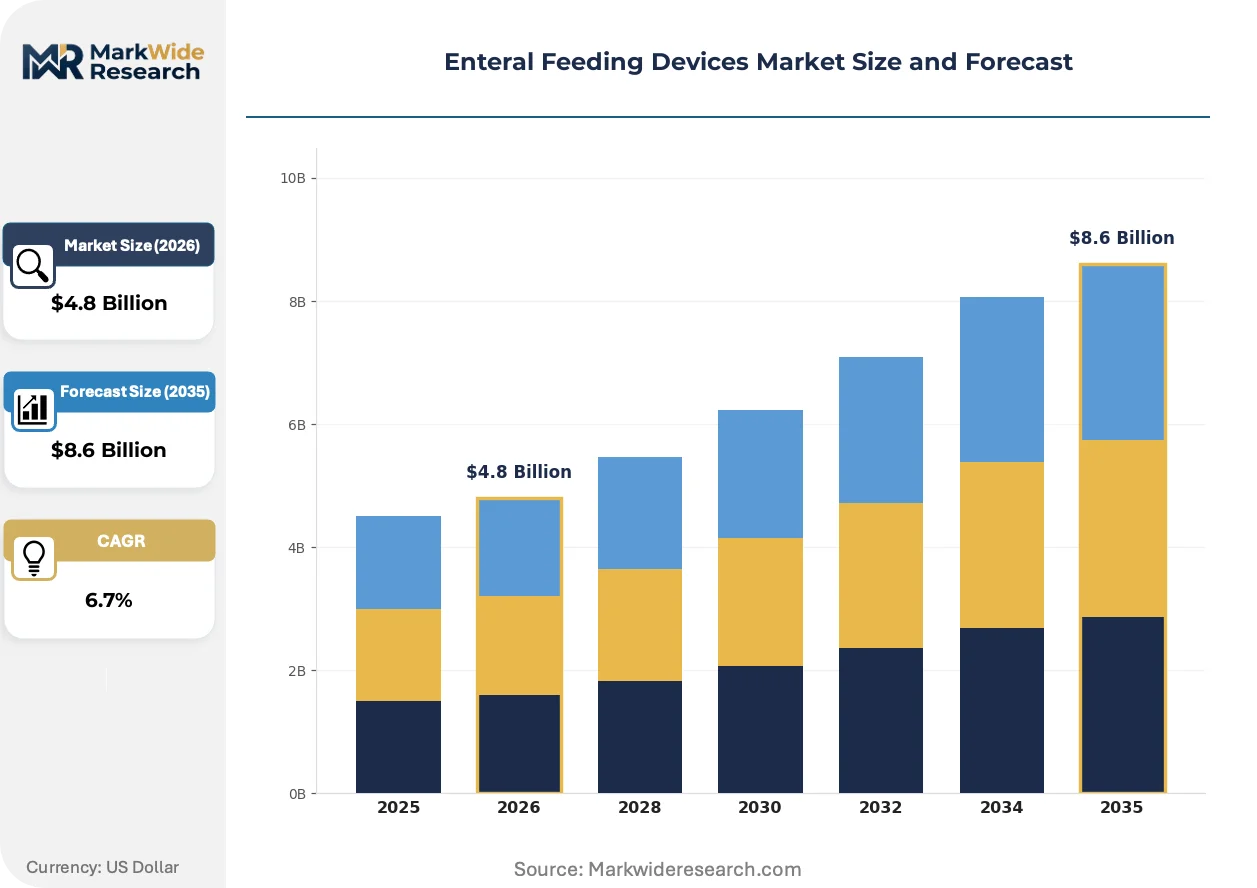
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Feeding Bags, Tubing, Accessories End User: Hospitals, Long-term Care Facilities, Home Care, Rehabilitation Centers Application: Oncology, Neurology, Gastroenterology, Critical Care Technology: Enteral Pumps, Gravity Feed Systems, Safety Features, Enhanced Nutrition Delivery |
| Companies Covered | Fresenius Kabi, Cardinal Health, Abbott Laboratories, Avanos Medical, Boston Scientific Corporation, Becton, Dickinson and Company, B. Braun Melsungen, Danone, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enteral Feeding Devices Market Emerging Trajectories
Connectivity architectures and material science are converging to transform enteral feeding from a bedside utility into a remotely managed chronic care modality with embedded compliance verification.
Wireless pump telemetry is decentralizing clinical oversight by transmitting flow rate deviations and battery status to cloud dashboards accessible by home health nurses. Medicare Advantage plans in Florida and Arizona now require such connectivity for prior authorization of extended home coverage. The technology is decentralizing traditional home visit economics by enabling one nurse to monitor fifty patients rather than ten.
REACH Annex XVII phthalate restrictions are compelling European manufacturers to abandon DEHP plasticizers in PVC tubing for DEHT or bio-based alternatives. Compounders in the Netherlands and Belgium have scaled citrate ester production to meet MDR-compliant device submissions. Pediatric and neonatal segments face the steepest reformulation timelines due to heightened developmental toxicity scrutiny.
Hospital purchasing consortia are consolidating enteral device procurement under single-source agreements that bundle pumps, sets, and nutrition formulas. Group Purchasing Organizations now dominate acute care acquisition in the US Midwest and Southeast, squeezing independent distributors. The behavioral shift is most pronounced in IDN-affiliated community hospitals where standardization reduces nurse training burden across rotating staff.
Enteral Feeding Devices Market Segmentation
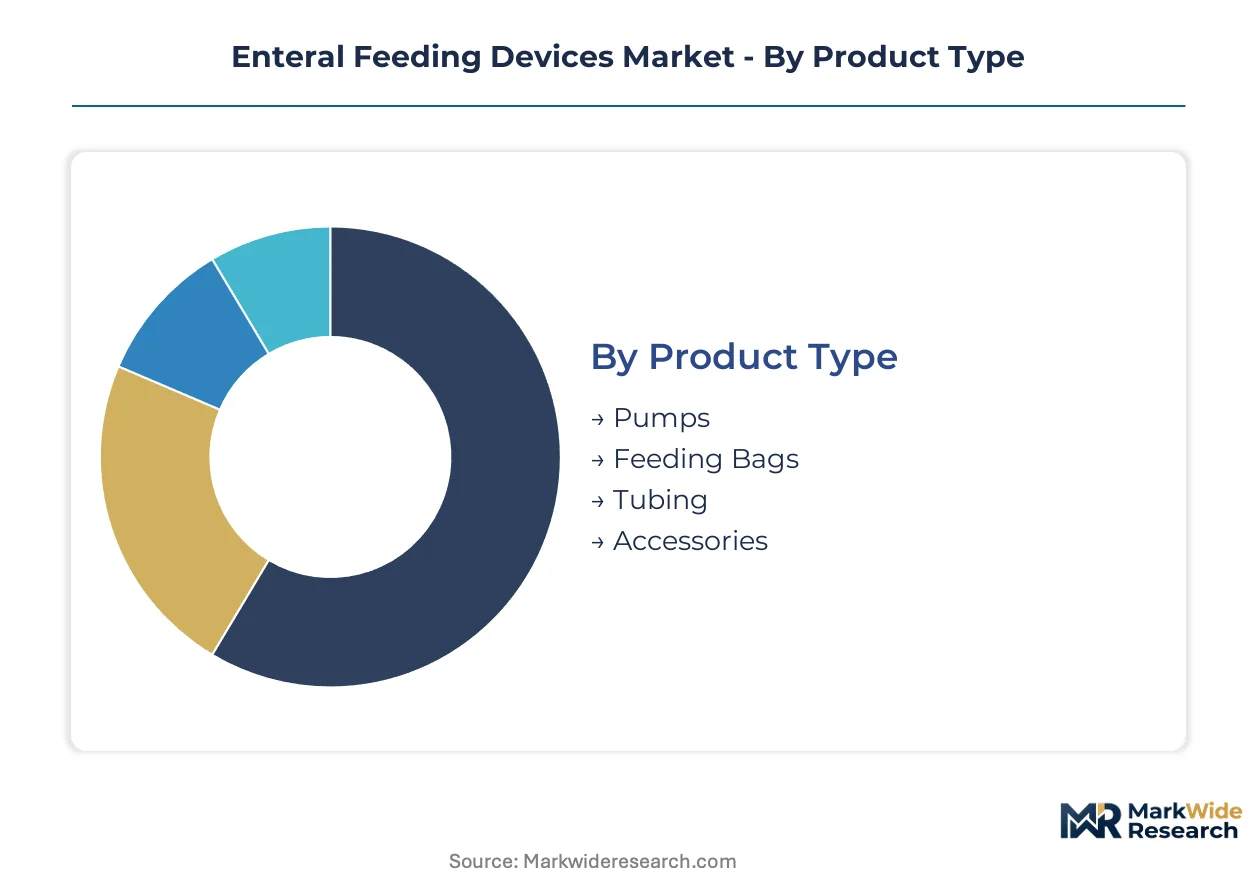
Enteral feeding devices segment across multiple functional dimensions that determine procurement patterns, reimbursement pathways, and regulatory scrutiny intensity. Manufacturers must align product architectures with the specific clinical environment and patient acuity level where deployment occurs.
Product Type:
Pumps operate as standalone capital equipment requiring programmed accuracy, while bags and tubing function as embedded consumables within integrated delivery systems.
- Pumps:Electromechanical devices deliver formula at programmable rates between 1 and 400 mL per hour with occlusion pressure alarms and anti-free-flow safety mechanisms. Demand concentrates in United States hospital networks undergoing ISO 80369-3 connector fleet replacement mandated by FDA enforcement.
- Feeding Bags:Flexible reservoirs constructed from PVC or non-DEHP alternatives hold 500 to 1,500 mL of enteral formula with graduated volume markings and tamper-evident ports. Oncology wards in Germany and France drive premium bag specifications requiring extended hang-time stability for nocturnal feeding protocols.
- Tubing:Silicone or polyurethane administration sets connect reservoir to patient access with enteral-specific connectors preventing lethal misconnections.
- Accessories:Syringes, extension sets, and fixation devices complete delivery configurations for specific anatomical access routes.
Pumps lead volumes today; accessories are gaining share fastest as home care agencies stock comprehensive supply kits.
End User:
Cost tiers separate capital-intensive acute settings from reimbursement-dependent ambulatory channels where device durability and ease-of-use dominate purchasing criteria.
- Hospitals:Intensive care units and step-down wards deploy programmable pumps with centralized fleet management and biomedical engineering support. United States health systems prioritize connectivity-enabled devices that integrate with electronic medical record platforms for automated documentation.
- Home Care:Patients or family caregivers operate simplified pump interfaces with remote monitoring capabilities and battery-powered portability. Medicare Advantage plans in Florida and Arizona now mandate wireless telemetry for prior authorization of extended coverage periods.
- Long-term Care Facilities:Nursing homes balance device sophistication against staff training limitations and infection control protocols.
- Rehabilitation Centers:Transitional care settings bridge acute and home environments with equipment rental models supporting temporary recovery periods.
Hospitals dominate absolute spending; home care is expanding most quickly as payor reimbursement shifts toward outpatient management.
Application:
Clinical indication determines access route selection, indwell duration requirements, and complication risk profiles that shape device specification.
- Oncology:Head and neck radiation patients require long-term jejunal access devices bypassing esophageal inflammation. Platinum-cured silicone formulations reduce granulation tissue formation, extending tube indwell time in United States cancer centers.
- Neurology:Stroke and neurodegenerative disease patients with dysphagia depend on percutaneous endoscopic gastrostomy tubes for chronic nutritional support. Japan's super-aged prefectures demonstrate concentrated demand for remote monitoring-integrated systems serving dispersed rural populations.
- Gastroenterology:Malabsorption syndromes and inflammatory bowel disease drive nasogastric and post-pyloric feeding configurations.
- Critical Care:Mechanically ventilated patients receive early enteral nutrition through gastric access with motility-assisting pump algorithms.
Neurology leads procedure volumes today; oncology shows steepest expansion trajectory as radiation protocols intensify.
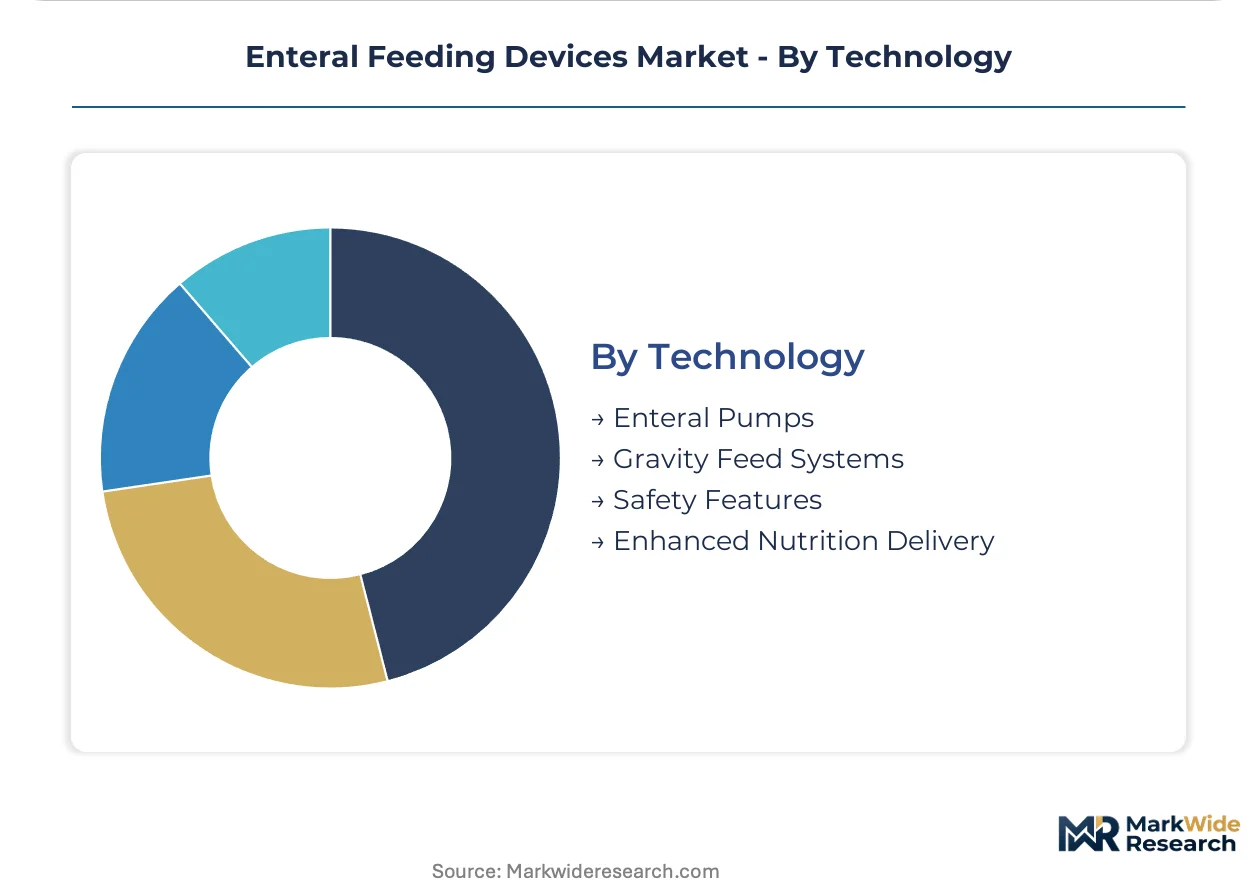
Technology:
Technology maturity separates established gravity-dependent systems from digitally enhanced platforms with embedded compliance verification.
- Enteral Pumps:Microprocessor-controlled peristaltic or rotary mechanisms achieve delivery accuracy within 5% with programmable bolus and continuous modes. Bluetooth-enabled dose calculators allow pediatric caregivers in United States metropolitan areas to adjust feeds without clinical visits.
- Safety Features:ISO 80369-3 enteral-specific connectors, free-flow protection valves, and occlusion alarm systems prevent adverse events. EMA MDR compliance requires enhanced clinical evidence for class IIa devices with integrated safety electronics.
- Gravity Feed Systems:Passive delivery without electromechanical components serves resource-limited settings and short-term interventions.
- Enhanced Nutrition Delivery:Dual-lumen tubes permitting simultaneous feeding and gastric decompression address complex motility disorders.
Enteral pumps dominate installed base today; safety features are climbing the fastest as regulatory mandates accelerate fleet replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redirecting enteral feeding device manufacturing toward jurisdictions with streamlined clinical evidence pathways and favorable reimbursement frameworks. Manufacturers now optimize regional footprints based on cost-of-compliance differentials between FDA, EMA, and national Asian regulators rather than pure labor arbitrage.
United States
Medicare home enteral nutrition coverage expansion and hospital-to-home transition programs drive device procurement across Florida and Arizona Medicare Advantage networks. The FDA enforces ISO 80369-3 connector standards mandating fleet replacement across acute care networks. Minneapolis and San Diego anchor North American pump manufacturing clusters serving domestic home care distribution channels.
Germany
EMA MDR clinical evidence thresholds for class IIa pump re-certification are consolidating the European vendor base around well-capitalized manufacturers. REACH Annex XVII phthalate restrictions compel DEHP-free tubing reformulation across pediatric device portfolios. The Baden-Württemberg chemical corridor supplies medical-grade aromatic polyether for polyurethane tube production serving EU hospital networks.
Japan
Super-aged prefectures including Tochigi and Aomori demonstrate concentrated demand for remote monitoring-integrated pump systems serving dispersed rural populations with dysphagia. METI medical device reimbursement codes favor connectivity-enabled home care equipment. The Kansai region hosts specialized silicone elastomer compounders supplying platinum-cured formulations for extended indwell oncology tubes.
India
The PLI scheme for medical devices reduces import duty exposure for multinational tubing and pump assembly operations targeting South Asian price points. CDSCO streamlined registration pathways for class B and C devices accelerate market entry for home care pump manufacturers. Gujarat and Karnataka industrial corridors concentrate domestic manufacturing capacity for gravity feed systems serving resource-limited clinical settings.
China
NMPA medical device innovation fast-track programs prioritize smart pump connectivity features for domestic hospital procurement. Dual carbon goals drive bio-based plasticizer adoption in PVC tubing manufacturing. The Yangtze River Delta cluster integrates enteral device production with regional nutrition formula supply chains for bundled acute care offerings.
Enteral Feeding Devices Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers scale silicone and polyurethane component production to meet ISO 80369-3 fleet replacement cycles. The vendor base stratifies across three tiers: diversified medical technology conglomerates with integrated nutrition portfolios, specialized infusion device manufacturers with pump-centric expertise, and regional disposable set suppliers serving price-sensitive procurement channels. Strategic archetypes include full-stack nutrition-device integrators, pure-play pump specialists, and tubing-focused component suppliers. M&A activity concentrates on connectivity technology acquisitions and European MDR compliance capability builds.
Within the diversified medical technology tier, Fresenius Kabi, Cardinal Health, and Abbott Laboratories exemplify contrasting geographic and portfolio strategies. Fresenius Kabi anchors European manufacturing scale for electromechanical pump systems and disposable administration sets. Cardinal Health occupies a position controlling North American distribution channels for home care supply logistics. Abbott Laboratories represents the nutrition-device integration archetype, leveraging metabolic product portfolio breadth across enteral feeding workflows. These three entities collectively illustrate how scale, distribution control, and vertical portfolio scope define competitive positioning in an environment of regulatory-driven product refresh cycles.
| Leading Market Players |
|---|
| Fresenius Kabi |
| Cardinal Health |
| Abbott Laboratories |
| Avanos Medical |
| Boston Scientific Corporation |
| Becton, Dickinson and Company |
| B. Braun Melsungen |
| Danone |
| Nestlé |
| Others |
Supply Flow & Price Mechanics
Medical-grade aromatic polyether flows from Baden-Württemberg chemical corridors through German and Chinese compounding facilities into pump and tubing assemblies, with platinum-cured silicone formulations commanding premium tiers against standard PVC alternatives in oncology-specific procurement channels.
Pricing Analysis
Distributor margins for home care supply chains absorb the steepest compression as Group Purchasing Organizations consolidate acute care procurement under single-source enteral device agreements. Three-tier pricing structure across premium, standard, and economy levels separates connectivity-enabled pumps with Bluetooth telemetry from gravity feed systems and basic peristaltic mechanisms. Pricing pressure stems from Medicare Advantage prior authorization requirements mandating wireless fleet upgrades. Home care agencies exhibit highest price sensitivity due to fixed reimbursement rates, while United States cancer centers prioritize platinum-cured silicone specifications regardless of cost.
Supply Chain Analysis
Regional distribution centers in Minneapolis and San Diego anchor North American pump fulfillment networks serving Medicare home enteral nutrition channels. Manufacturing gravity centers on Germany for polyurethane tube production, China for PVC compounding, and Japan for platinum-cured silicone elastomer formulations. Raw material dependencies rest on medical-grade aromatic polyether, DEHP-free plasticizers, and precision pump motors. Single-source vulnerability concentrates in German chemical manufacturing zones for medical-grade polyurethane precursors. Distribution runs through Cardinal Health-controlled logistics networks for home care supply aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enteral feeding device manufacturing arbitrage favors India and China against European MDR compliance cost structures, with the PLI scheme reducing import duty exposure by two-thirds relative to EU clinical evidence thresholds.
For Market Incumbents: Anchor manufacturing scale in Gujarat and Karnataka industrial corridors to exploit PLI scheme benefits while consolidating European operations around MDR-compliant Class IIa pump re-certification capabilities. Capacity addition in Indian domestic assembly insulates against EMA post-market surveillance cost inflation. Channel control through GPO contract renewal locks out emerging connectivity specialists.
For New Entrants and Emerging Players: Begin with smartphone-connected bolus programming subscriptions targeting pediatric caregiver segments in United States metropolitan areas where clinical visit avoidance commands premium pricing. Japan's super-aged prefectures present the most penetrable geography for remote monitoring-integrated systems given minimal existing home infusion infrastructure. Hospital system partnership with IDN-affiliated community hospitals offers fastest credentialing pathway.
For Investors and Strategic Acquirers: Consolidation pressure builds where EMA MDR clinical evidence thresholds exceed smaller EU manufacturers' post-market surveillance funding capacity. Long-term viability favors diversified medical technology conglomerates with integrated nutrition portfolios over pure-play pump specialists facing connectivity R&D cost escalation. Acquisition target archetype: European disposable set suppliers with established ISO 80369-3 connector tooling. Signal to watch: Medicare Advantage connectivity mandates spreading beyond Florida and Arizona into Midwest networks.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 80369-3 Connector Fleet Replacement | FDA enforcement mandates lethal misconnection prevention across United States hospital networks. |
| PLI Scheme Manufacturing Localization | Indian domestic assembly reduces import duty exposure for South Asian price point targeting. |
| Bluetooth-Enabled Dose Calculator Development | Pediatric caregiver subscription revenue streams open in United States metropolitan markets. |
| REACH Annex XVII DEHP Reformulation | European pediatric and neonatal segments face accelerated citrate ester adoption timelines. |
| Medicare Reimbursement Strategy Alignment | CMS home enteral nutrition coverage expansion accelerates durable medical equipment procurement cycles. |
Methodological Framework
Bottom-up home care modeling reconciled against top-down pump manufacturing tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and home health agency directors combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EMA MDR submission trackers. Triangulation across stakeholder inputs and regulatory documentation ensures segment-level accuracy.
Input-output matrices map enteral pump unit shipments against formula consumption volumes across product type, end user, application, and technology segmentation dimensions. CAGRs derive from installed base replacement cycles, reimbursement code expansion trajectories, and connectivity adoption curves. Forecast inputs include ISO 80369-3 connector fleet replacement schedules and Medicare Advantage prior authorization requirement diffusion patterns.
Several conditions sit outside the modeled scope, including raw material price volatility in medical-grade polyurethane supply chains and unannounced regulatory shifts in Asian medical device registration pathways. Forecasts reflect assumptions about reimbursement stability and connectivity technology cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Obstetrics Devices Market
Medical Devices
Global Orthopedic Surgical Robots Market
Medical Devices
Anti-Fatigue Lenses Market
Medical Devices
Radial Compression Devices Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Minimally Invasive Neurosurgical Devices Market
Medical Devices
Global Veress Needle Market
Medical Devices
Latin America Insulin Syringes Market
Medical Devices
Sleeve Gastrectomy Devices Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
Ehealth Devices Market
Medical Devices
Canada Minimally Invasive Surgery Devices Market
Medical Devices
Wearable Atrial Fibrillation Detection Devices Market
Medical Devices
Global Uterine Manipulation Devices Market
Medical Devices
Retinal Surgery Devices Market