
 3D Surgical Microscope Systems Market | 2026-2036
3D Surgical Microscope Systems Market Size, Share, and Industry Trends Forecast 2026-2036
3D Surgical Microscope Systems Market Outlook
High-definition stereoscopic digital visualization is reconfiguring surgical workflows across microsurgical disciplines. Carl Zeiss Meditec leverages its century-long optics heritage to anchor premium positioning in neuro-ophthalmic suites. Leica Microsystems competes through deep integration of fluorescence imaging modules into its surgical microscope platforms. Olympus Corporation specializes in multi-disciplinary deployment, extending its endoscopy-installed base into complementary 3D visualization workflows.
3D surgical microscope systems combine precision-engineered stereoscopic optical paths with digital image sensors, beam splitters, and real-time video processing to deliver depth-perceptive visualization of anatomical structures at sub-millimeter scales during operative procedures. These systems typically achieve resolutions exceeding full high-definition standards while maintaining ergonomic maneuverability through motorized multi-axis positioning. Integrated systems currently dominate hospital capital budgets due to their seamless compatibility with surgical navigation and intraoperative imaging architectures. Digital imaging technology represents the fastest-expanding segment as facilities replace purely optical platforms with sensor-based architectures that support recording, streaming, and augmented reality overlay capabilities. Neurosurgery commands the largest application share given the absolute requirement for stereoscopic depth judgment during vascular and tumor resection procedures.
The FDA regulates these devices under Class II medical device pathways with 510(k) premarket notification requirements, while the EU Medical Device Regulation mandates notified body conformity assessment and CE marking for market access. Japan's PMDA enforces Pharmaceutical and Medical Device Act standards that govern optical performance validation and biocompatibility of patient-contact components. Stakeholders must monitor evolving cybersecurity guidance from these regulators as network-connected surgical visualization platforms become standard operating room infrastructure.
Market Dynamics
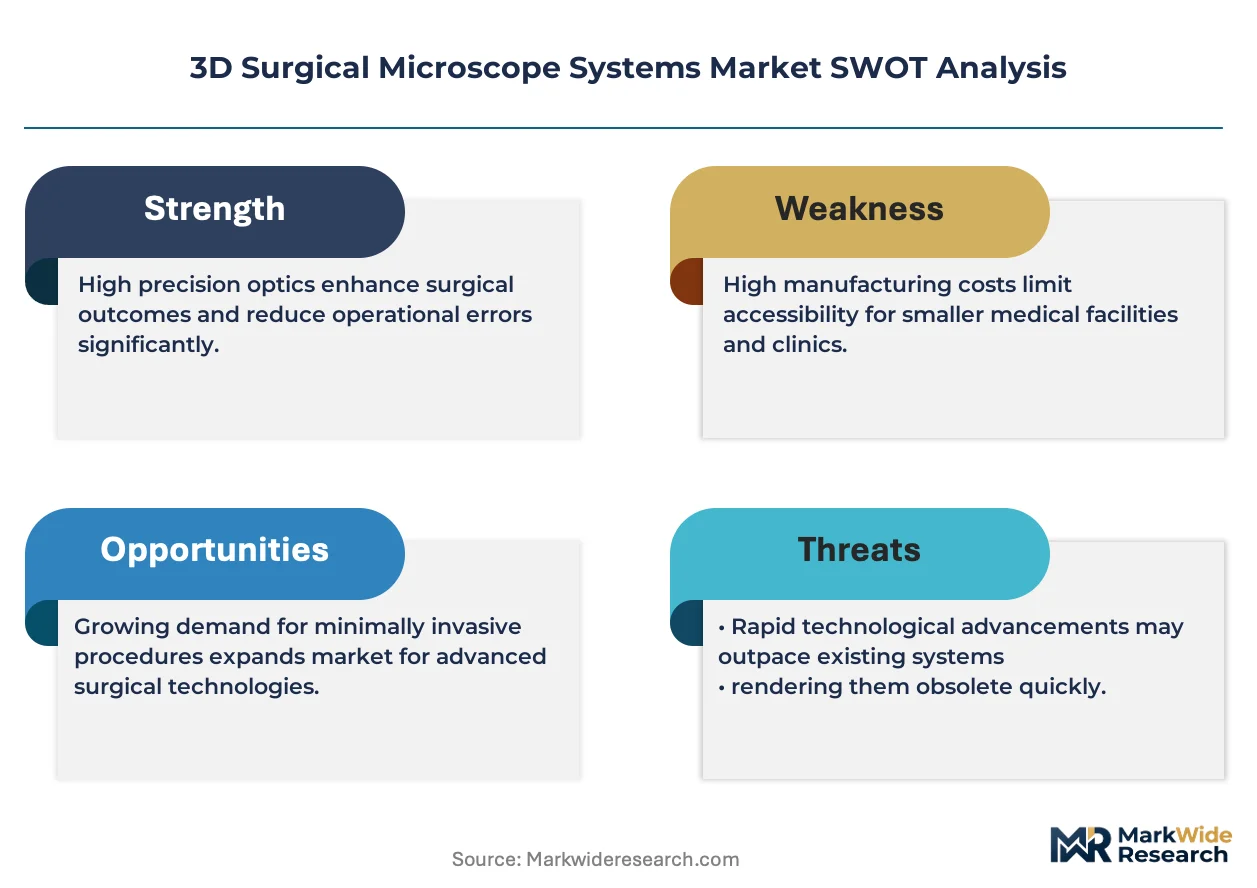
Hybrid operating room construction across tertiary hospitals is compressing procurement cycles for integrated 3D visualization platforms, as surgical departments demand seamless interoperability with navigation systems and intraoperative imaging suites.
Growth Catalysts
- Class II 510(k) pathway refinement:FDA streamlining of digital surgical visualization clearances accelerates product-to-market timelines for sensor-based microscope architectures.
- Neurosurgical workflow digitization:Tertiary hospitals in the United States, Germany, and Japan are mandating stereoscopic recording capabilities for vascular and tumor resection procedures.
- Fluorescence imaging convergence:Integration of indocyanine green and near-infrared modules into 3D optical paths expands addressable procedural volumes beyond traditional microscopy.
Market Restraints
- Precision optics supply concentration:German and Japanese optical component suppliers control critical lens grinding and coating capabilities, creating single-source vulnerabilities.
- Capital equipment budget compression:Hospital capital committees prioritize robotic surgery platforms, diverting funds from standalone microscope upgrades.
- EU MDR conformity costs:Enhanced notified body requirements for CE marking of Class IIa surgical devices extend validation timelines and inflate regulatory expenditure.
Strategic Opportunities
- Ambulatory surgery center penetration:United States outpatient spine and ophthalmic facilities remain underpenetrated for 3D microscopy despite procedure volume growth.
- Augmented reality overlay demand:Convergence of surgical navigation data with real-time stereoscopic video creates new software and service revenue streams.
- Japan PMDA fast-track incentives:Breakthrough device designation for intraoperative visualization innovations offers expedited review for novel optical architectures.
Industry Challenges
- Biomedical engineer scarcity:Specialized expertise in surgical optics-electronics integration remains concentrated among legacy microscope manufacturers.
- Legacy OR integration complexity:Retrofitting 3D platforms into existing surgical suites requires custom mounting solutions and HVAC modifications.
- Cybersecurity validation burden:Network-connected visualization systems must demonstrate compliance with evolving FDA guidance on medical device software security.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Surgical Microscope Systems Market |
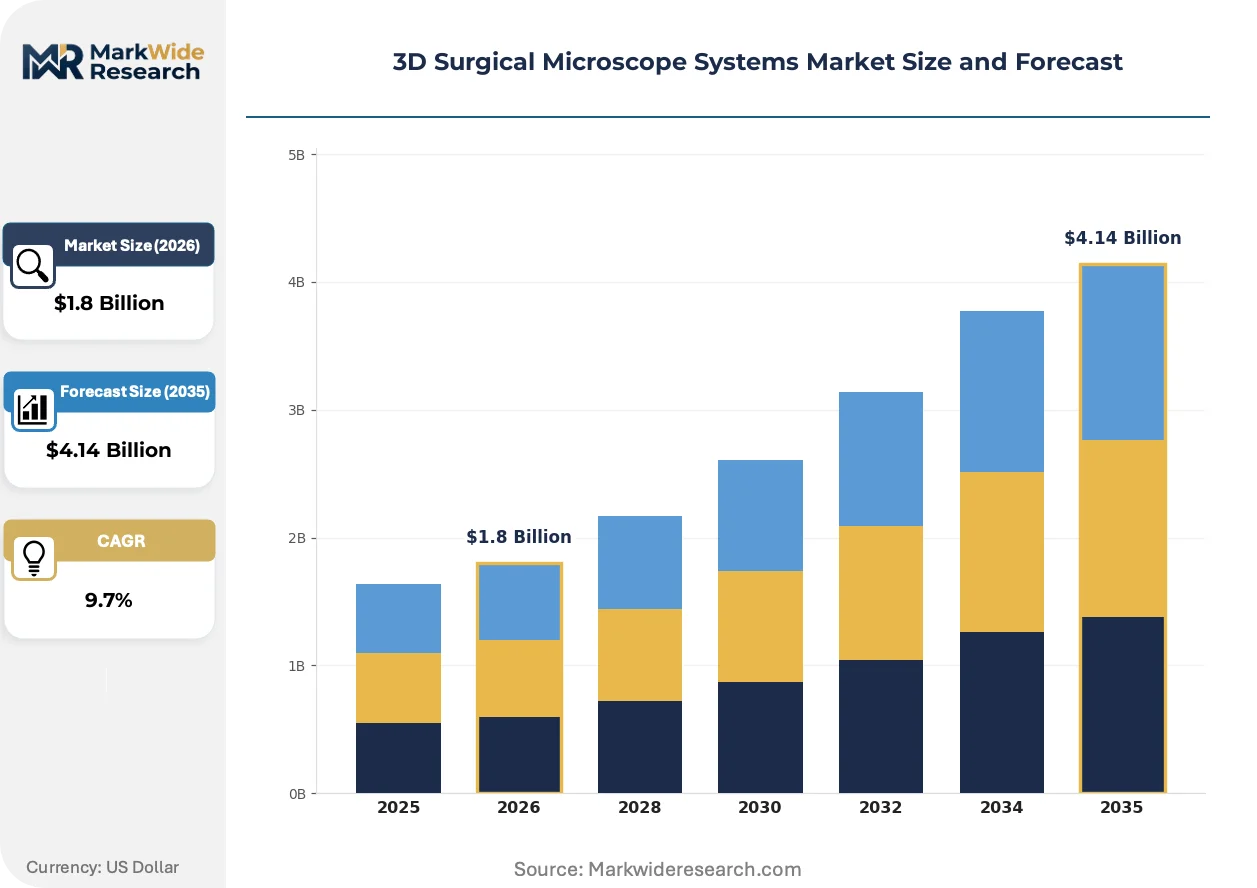
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Systems, Standalone Systems, Portable Systems, Robotic Systems End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: Optical Imaging, Digital Imaging, Video Conferencing, Augmented Reality Application: Neurosurgery, Ophthalmology, Oncology, Dental Surgery |
| Companies Covered | Leica Microsystems, Olympus Corporation, TrueVision 3D Surgical, Carl Zeiss Meditec, Alcon, Synaptive Medical, Topcon Corporation, HAAG-STREIT Surgical, Takagi Seiko, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Surgical Microscope Systems Market Strategic Shifts
Digital sensor architectures are supplanting purely optical light paths across microsurgical disciplines, compressing the distinction between intraoperative visualization and postoperative review workflows.
CMOS-based stereoscopic sensors with sub-micron resolution are rendering obsolete traditional binocular eyepiece-dependent observation in neurosurgical suites. Academic medical centers in the United States and Germany are completing fleet-wide conversions within eighteen-month procurement windows. This transition is compressing vendor maintenance revenue from optical component replacement toward software subscription and data management services.
EU MDR Article 10 technical documentation requirements now mandate clinical evidence for surgical microscope software updates, treating algorithm modifications as significant design changes. Notified bodies in Germany and the Netherlands are applying enhanced scrutiny to fluorescence imaging validation protocols. Digital pathology integration modules face extended conformity assessment timelines, delaying combined CE-MDR and FDA 510(k) dual submissions.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, negotiating third-party maintenance for electromechanical components while retaining manufacturer software support. United States health system GPOs are driving this disintermediation through multi-hospital volume aggregation. Tertiary neurosurgical departments respond by internalizing biomedical engineering capabilities for optical alignment and positioning system calibration.
3D Surgical Microscope Systems Market Segmentation
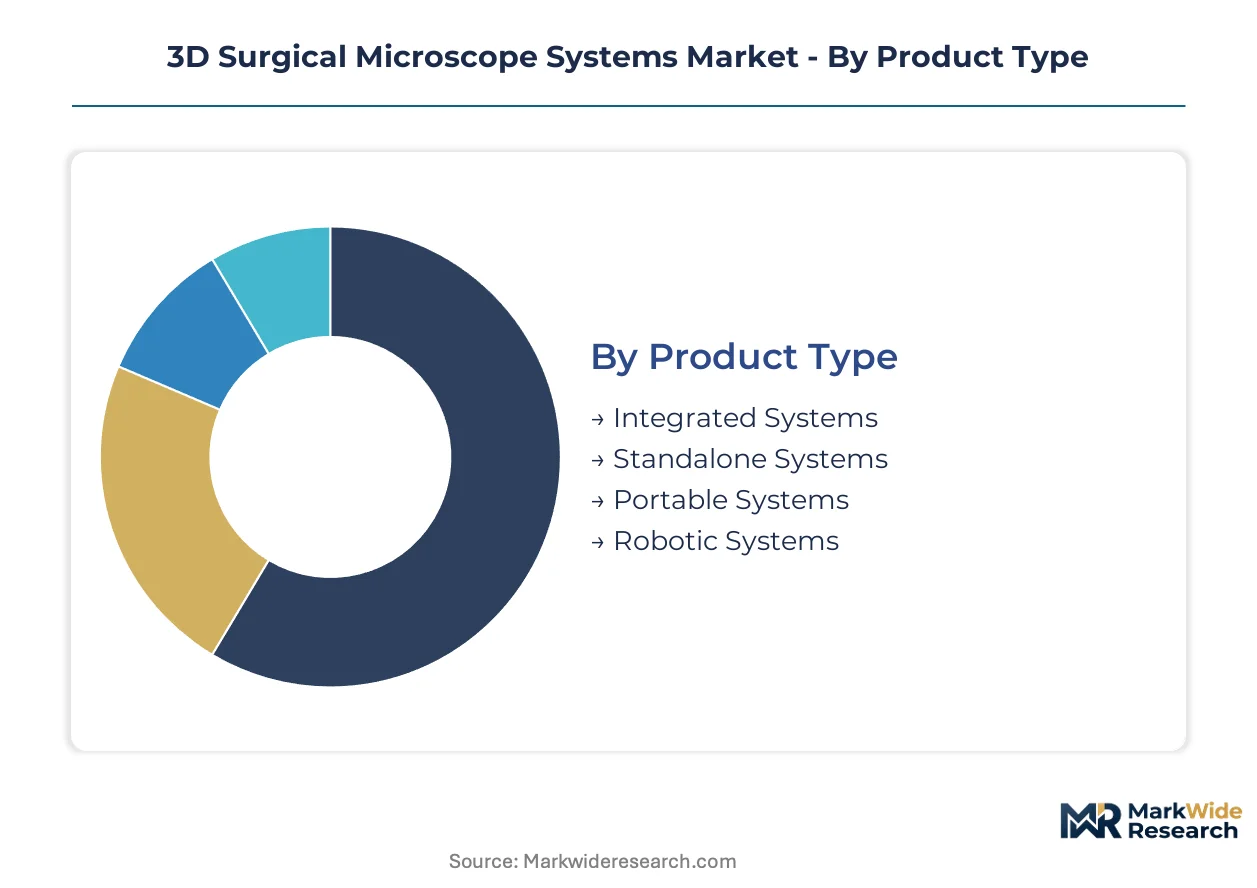
Segmentation in 3D surgical microscope systems reveals distinct procurement rhythms and technology refresh cycles across product architectures and clinical settings. Understanding these patterns enables vendors to align R&D investment with replacement demand and emerging application requirements.
Product Type:
Integrated systems command the longest replacement cycles at seven to ten years due to capital intensity and OR infrastructure lock-in, while portable platforms turn over fastest as battery and sensor technologies advance.
- Integrated Systems:These platforms embed stereoscopic optical paths with surgical navigation, intraoperative imaging, and fluorescence modules within fixed ceiling or floor-mounted configurations. Demand concentrates in tertiary hospital hybrid operating rooms across the United States, Germany, and Japan where neurosurgical departments require seamless interoperability with C-arm and MRI suites.
- Standalone Systems:Modular microscope architectures that operate independently of navigation infrastructure while maintaining motorized positioning and high-definition video output. Ambulatory surgery centers in the United States are expanding procurement of these units for outpatient spine and ophthalmic procedures where capital budgets preclude full integration.
- Portable Systems:Compact battery-powered units with CMOS-based stereoscopic sensors designed for field deployment and temporary OR setups. Military medical units and humanitarian surgical missions represent primary demand nodes.
- Robotic Systems:Motorized positioning platforms with programmable motion paths and haptic feedback integration. Academic medical centers in Germany are piloting these architectures for microvascular anastomosis procedures.
Integrated systems anchor the volume base while portable platforms gain share at the steepest rate.
End User:
Procurement authority and reimbursement pathways create divergent pricing tolerances across institutional categories, with hospitals absorbing premium integrated platforms and specialty clinics optimizing for procedure-specific configurations.
- Hospitals:Tertiary academic centers and community hospital systems with dedicated neurosurgical, ophthalmic, and oncological service lines. These institutions in the United States, Germany, and Japan are mandating stereoscopic recording capabilities for vascular and tumor resection procedures under quality accreditation standards.
- Ambulatory Surgical Centers:Outpatient facilities performing spine, ophthalmic, and dental microsurgical procedures with compressed procedure throughput requirements. United States ASCs remain underpenetrated for 3D microscopy despite procedure volume expansion.
- Specialty Clinics:Dedicated ophthalmology and dental surgery practices with focused procedural scopes. These settings prioritize ergonomic maneuverability and compact footprints over navigation integration.
- Research Institutions:Academic laboratories and preclinical facilities utilizing 3D microscopy for surgical training, technique development, and device validation. Funding cycles from NIH and DFG govern procurement timing.
Hospitals absorb the majority of capital expenditure while ambulatory surgical centers present the most rapid expansion trajectory for standalone and portable configurations.
Technology:
Sensor-based architectures are displacing purely optical platforms at differential rates across clinical applications, with digital imaging achieving near-complete penetration in neurosurgical suites while optical paths persist in cost-sensitive settings.
- Optical Imaging:Traditional binocular eyepiece-dependent light paths with precision-engineered lens systems and manual focus mechanisms. These systems retain presence in developing market clinical settings and training environments where capital constraints predominate.
- Digital Imaging:CMOS-based stereoscopic sensors with sub-micron resolution, real-time video processing, and recording capabilities. Academic medical centers in the United States and Germany are completing fleet-wide conversions within compressed procurement windows.
- Video Conferencing:Integrated streaming architectures enabling remote proctoring, surgical education, and multidisciplinary consultation. Pandemic-accelerated deployment has normalized these capabilities in teaching hospital networks.
- Augmented Reality:Overlay systems projecting surgical navigation data, preoperative imaging, and fluorescence signals onto stereoscopic video feeds. Early adoption concentrates in vascular neurosurgery departments at Johns Hopkins, Charité Berlin, and Tokyo University Hospital.
Digital imaging dominates current procurement while augmented reality exhibits the most aggressive adoption curve among emerging technology categories.
Application:
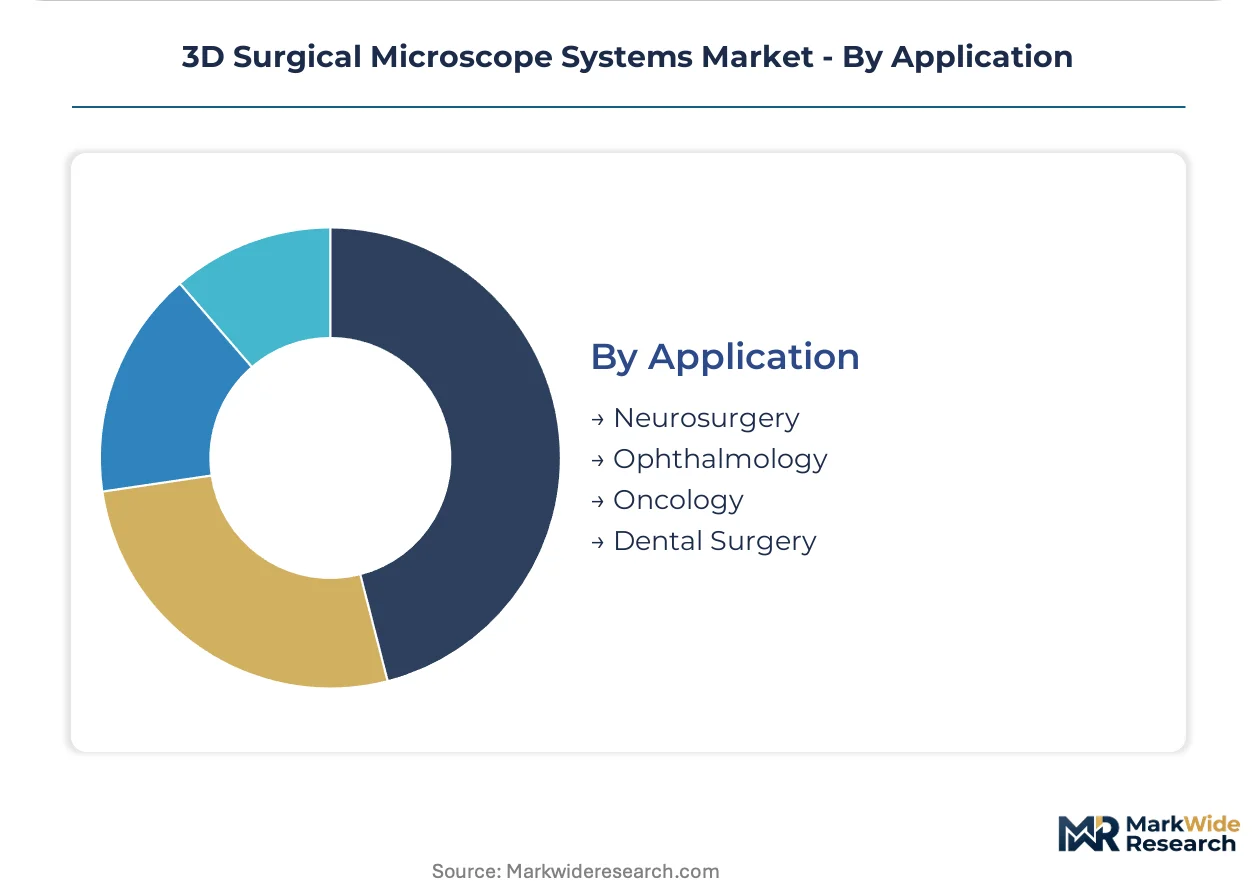
Procedural complexity and reimbursement levels determine technology specification requirements, with neurosurgery demanding the most sophisticated depth-perceptive capabilities and dental surgery accepting streamlined optical configurations.
- Neurosurgery:Vascular and tumor resection procedures requiring absolute stereoscopic depth judgment at sub-millimeter scales. Tertiary hospitals in the United States, Germany, and Japan are expanding hybrid OR construction specifically to accommodate integrated 3D visualization platforms.
- Ophthalmology:Retinal microsurgery and corneal transplantation procedures utilizing 3D visualization for posterior segment access. Vitreoretinal specialists are driving adoption of digital sensor architectures for recording and educational purposes.
- Oncology:Breast reconstruction microsurgery and sentinel lymph node mapping with fluorescence guidance. These procedures are expanding addressable volumes for ICG-integrated 3D platforms.
- Dental Surgery:Endodontic microsurgery and implant placement utilizing compact 3D microscopy for magnification and illumination. Specialty dental clinics in Japan represent concentrated demand for portable configurations.
Neurosurgery commands the largest installed base while oncology applications are climbing the fastest as fluorescence convergence expands procedural applicability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of precision optical components from Germany and Japan dominate upstream supply chains, while the United States absorbs the largest share of finished system imports. Demand concentration in tertiary hospital networks across these three markets is compressing procurement cycles for integrated hybrid OR platforms.
United States
Hybrid operating room construction at Johns Hopkins, Mayo Clinic, and Cleveland Clinic is accelerating integrated 3D microscope procurement. FDA Class II 510(k) pathway refinements for digital surgical visualization are compressing clearance timelines for sensor-based architectures. The Boston-Cambridge corridor anchors neurosurgical innovation clusters where academic medical centers pilot augmented reality overlay systems.
Germany
Charité Berlin and Heidelberg University Hospital are mandating stereoscopic recording capabilities for vascular resection procedures under quality accreditation standards. EU MDR notified body requirements for Class IIa surgical devices extend validation timelines but reinforce premium positioning for compliant manufacturers. The Baden-Württemberg optical engineering cluster around Oberkochen supplies precision lens grinding capabilities to global microscope assemblers.
Japan
Tokyo University Hospital and Osaka University Medical Center are expanding hybrid OR infrastructure specifically for neurosurgical 3D visualization platforms. PMDA breakthrough device designation for intraoperative visualization innovations offers expedited review pathways for novel optical architectures. The Kanto region concentrates domestic demand as METI funding supports surgical robotics and visualization R&D consortia.
United Kingdom
NHS England capital budgets for tertiary neurosurgical centers at Great Ormond Street and National Hospital for Neurology are prioritizing digital imaging conversions. MHRA alignment with EU MDR technical documentation requirements maintains regulatory continuity for CE-marked device access. London's biomedical engineering research corridor is piloting fluorescence-integrated 3D platforms for oncological microsurgery.
Switzerland
University Hospital Zurich and Geneva University Hospitals are procuring portable 3D microscopy configurations for humanitarian surgical mission deployment. Swissmedic conformity assessment for Class IIa surgical devices maintains stringent optical performance validation standards. The Basel pharmaceutical-medtech cluster is driving convergence between surgical visualization and intraoperative molecular imaging modalities.
3D Surgical Microscope Systems Market Competitive Environment
On the supply side, the industry is consolidating around three distinct capability tiers: legacy optics conglomerates with century-long heritage, diversified medical technology multinationals leveraging endoscopy-installed bases, and emergent digital sensor specialists. Strategic archetypes include precision optics heritage players, endoscopy-to-microscopy extenders, and software-augmented visualization disruptors. Dominant competitive moves encompass fluorescence imaging module integration partnerships and augmented reality overlay capability acquisitions.
Within the heritage optics tier, Carl Zeiss Meditec AG and Leica Microsystems GmbH exemplify premium positioning through precision-engineered stereoscopic optical paths. Olympus Corporation occupies a diversification archetype, extending endoscopy expertise into complementary 3D visualization workflows. These three entities anchor the competitive structure while digital-native entrants challenge through sensor-based architectures and software-centric service models.
| Leading Market Players |
|---|
| Leica Microsystems |
| Olympus Corporation |
| TrueVision 3D Surgical |
| Carl Zeiss Meditec |
| Alcon |
| Synaptive Medical |
| Topcon Corporation |
| HAAG-STREIT Surgical |
| Takagi Seiko |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in precision optical grinding facilities across Germany and Japan is tightening component availability while elevating pricing power for integrated system manufacturers serving tertiary hospital networks. This utilization squeeze propagates through procurement cycles as buyers face extended lead times for hybrid operating room installations.
Pricing Analysis
Hospital capital committees anchor pricing negotiations through multi-year service bundling demands that compress upfront equipment margins. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, fluorescence module integration depth, and navigation interoperability certification. Cost compression in standalone configurations is intensifying because ambulatory surgery centers are aggregating purchasing volume through United States health system GPOs. Specialty clinics exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers absorb premium positioning for augmented reality-enabled platforms.
Supply Chain Analysis
Contract manufacturing for electromechanical positioning assemblies concentrates with German and Japanese precision engineering specialists, while CMOS sensor fabrication draws from Taiwanese and South Korean foundry capacity. Critical dependencies include precision-ground optical glass from Schott AG and specialized coating chemistries from Japanese suppliers. Single-source vulnerability in fluorescence filter arrays creates exposure to export licensing delays. Distribution runs through direct hospital sales forces for integrated platforms and specialized medical device distributors for portable configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA 510(k) clearance histories and CE-MDR technical documentation libraries creates substantial switching costs for hospital customers.
For Market Incumbents: Harden installed base retention by internalizing optical component production through backward integration into German lens grinding capabilities, countering emerging sensor-native entrants. Deepen software subscription attach rates to offset hardware margin compression from GPO-aggregated purchasing. Prioritize fluorescence imaging patent portfolios as defensive barriers against modular competitors. For New Entrants and Emerging Players: United States ambulatory surgery centers present underpenetrated white space for portable and standalone configurations with compressed capital cycles. Target oncology microsurgery applications where fluorescence convergence is expanding procedural volumes beyond incumbent strongholds. Pursue hospital system partnership models that unbundle after-sales service from capital acquisition to bypass entrenched maintenance relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because FDA and EU MDR conformity assessment timelines create asymmetric barriers favoring incumbents with established technical documentation libraries. Acquisition targets should display software-augmented visualization capabilities and breakthrough device designation progress with PMDA. Monitor Japan METI funding disbursements for surgical robotics consortia as inflection signal for regional demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Dual Submission Acceleration | Streamlined conformity assessment with German notified bodies reduces time-to-market for fluorescence-integrated platforms. |
| Hospital System Partnership Development | Direct relationships with Johns Hopkins and Charité Berlin procurement committees bypass distributor margin extraction. |
| Software Companion Development | Augmented reality overlay modules create recurring revenue streams independent of capital equipment cycles. |
| Optical Component Backward Integration | In-house lens grinding capabilities in Baden-Württemberg cluster mitigate single-source supply vulnerabilities. |
| PMDA Breakthrough Device Pursuit | Expedited review pathways for novel optical architectures unlock priority access to Tokyo University Hospital networks. |
Study Parameters
Desk research of FDA 510(k) clearance databases, EU MDR notified body technical documentation, and hospital procurement contract disclosures preceded structured interviews with biomedical engineering directors, GPO contracts managers, neurosurgical department heads, and fluorescence imaging specialists. Secondary validation drew from PMDA breakthrough device designations, METI R&D consortium filings, and tertiary hospital capital expenditure records. Bottom-up unit demand estimates triangulated against top-down addressable procedure volume projections.
Fixed assumptions across the modeling period include continued FDA Class II pathway refinement for digital surgical visualization, sustained METI funding for Japanese surgical robotics development, and stable EU MDR notified body capacity for Class IIa device assessment. Segmentation dimensions encompassed product architecture, end-user institution type, sensor technology generation, and procedural application. CAGRs derived from logistic diffusion modeling of digital imaging adoption curves and replacement cycle compression in academic medical centers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by sensor-native entrants or regulatory pathway disruptions would shift outcomes. Quarterly review of FDA 510(k) submission volumes, EU MDR notified body queue lengths, and Japan PMDA breakthrough device grants is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Telehealth Device Market
Medical Devices
Peripheral Interventions Market
Medical Devices
Urine Flow Meters Market
Medical Devices
Global Gynecology Devices Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
Medical Device Tester Market
Medical Devices
Non-Invasive Intracranial Pressure Monitoring Device Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Radial Access Catheter Market
Medical Devices
Mobile Healthcare Devices Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
Global Cardiopulmonary Resuscitation Device Market
Medical Devices
Heating Pads Market
Medical Devices
Antibiotic-Loaded Bone Cement Market